
 Professional Hair Care Products Market | 2026-2036
Professional Hair Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Hair Care Products Market Outlook
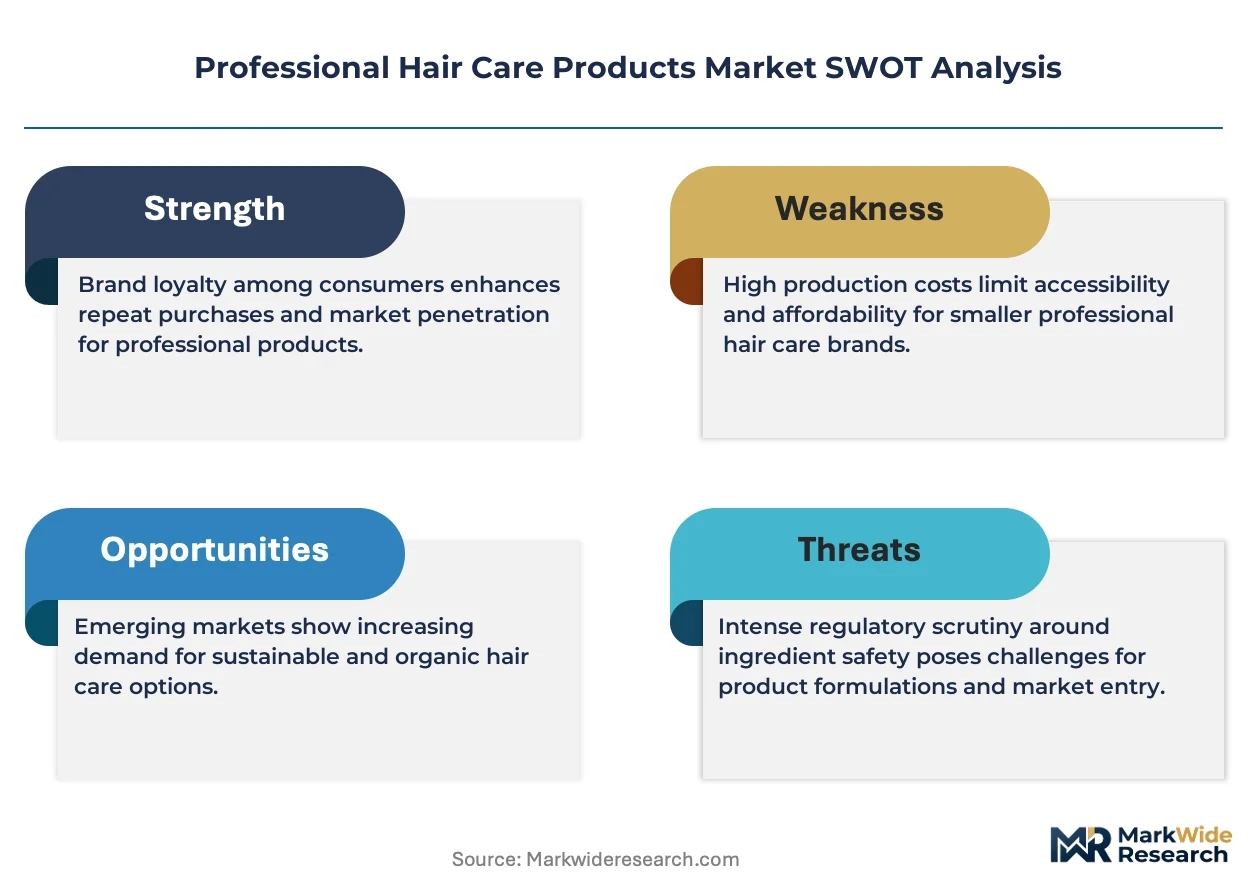
Salon professionals are expanding use of bond-building treatment systems, while barbershop demand for texture-focused styling products is realigning procurement patterns across distributor networks. L'Oréal S.A. dominates professional color care through captive salon education programs. Olaplex Holdings, Inc. differentiates via patented bis-aminopropyl diglycol dimaleate chemistry. Davines S.p.A. anchors Mediterranean craft positioning with B Corp-certified manufacturing.
Professional hair care products comprise salon-grade formulations with higher active ingredient concentrations than retail equivalents, typically requiring pH balancing between 3.5 and 5.5 and heat-activated delivery systems for cuticle penetration. These products serve licensed stylists performing chemical services, protective treatments, and finished styling on client hair. Treatment products command the strongest margin pools due to service-based attachment rates and repeat purchase cycles. Styling products compete on humidity resistance and thermal protection claims. Shampoo and conditioner segments remain volume leaders but face private-label encroachment in mid-tier salon distributors.
REACH in Europe and FDA cosmetic labeling rules in the US govern ingredient disclosure, safety substantiation, and prohibited substance lists, directly shaping R&D allocation toward clean-label reformulations. ISO 16128 standards for natural and organic cosmetics claims create additional compliance layers for brands targeting green-certified salon channels. Stakeholders must monitor evolving state-level ingredient bans in California and New York, as these precedents cascade into national distributor qualification requirements.
Market Dynamics
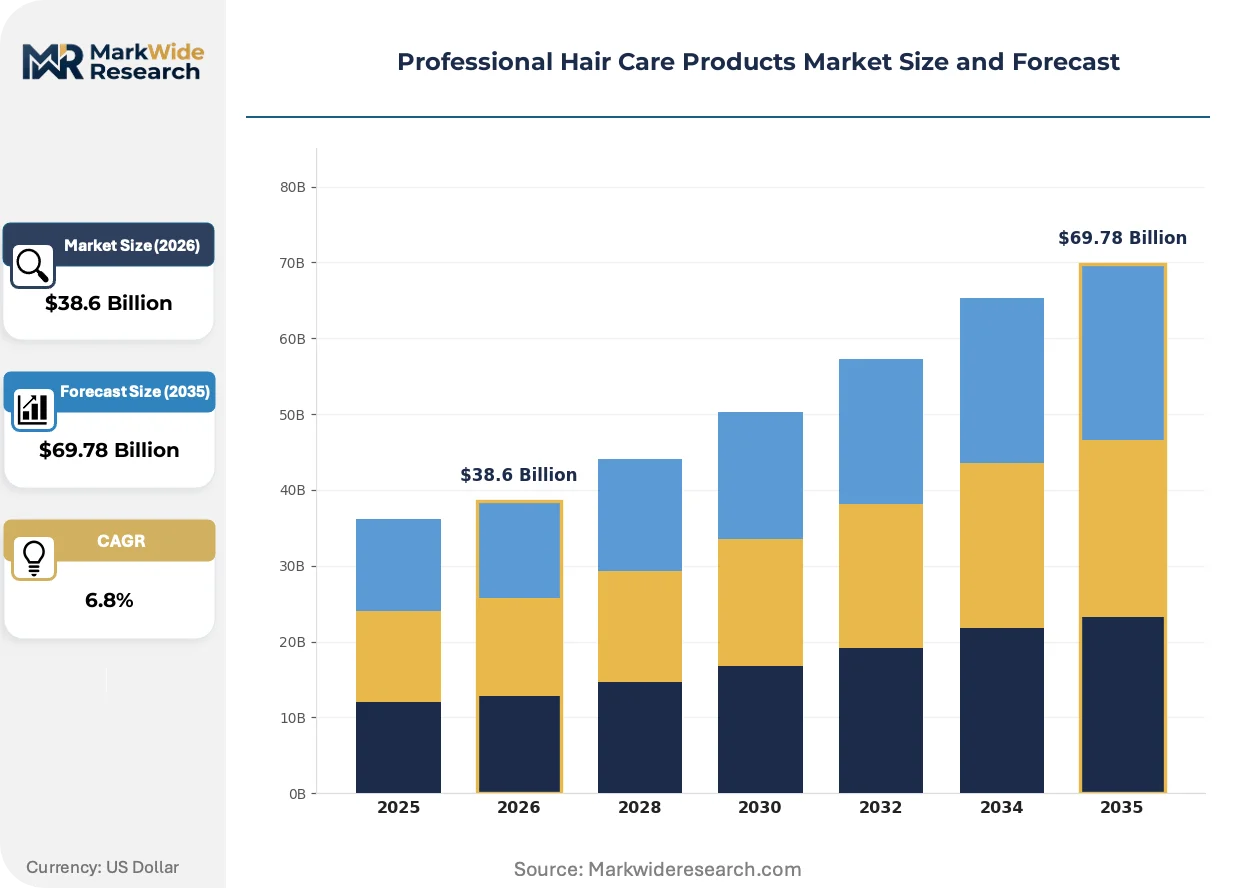
Bond-building chemistry patents and REACH ingredient disclosure mandates are compressing formulation cycles while redistributing margin pools toward treatment systems and clean-label certifications.
Growth Catalysts
- REACH compliance deadlines:ECHA disclosure requirements are accelerating clean-label reformulation investments across European salon distributors, creating first-mover advantages for brands with pre-certified ingredient portfolios.
- Licensed stylist channel expansion:Salon professionals in Brazil and Japan are attaching bond-building treatments to 60% of chemical service bookings, driving repeat purchase velocity.
- pH-balanced delivery systems:Heat-activated penetration technologies are extending service intervals and justifying premium positioning in professional-only SKUs.
Market Restraints
- Active ingredient cost volatility:Bis-aminopropyl diglycol dimaleate and ceramide complexes face supply concentration among three German specialty chemical suppliers, squeezing mid-tier brand margins.
- FDA labeling friction:Cosmetic ingredient disclosure rules require reformulation documentation cycles that extend product development timelines by 8-14 months for US market entry.
- Private-label encroachment:Distributor-owned shampoo and conditioner lines are capturing 35% of mid-tier salon volume in North American beauty supply chains.
Strategic Opportunities
- ISO 16128 certification gap:Only 12% of professional brands hold valid natural and organic cosmetics claims, opening positioning space for B Corp-certified manufacturing entrants.
- Barbershop texture specialization:Coil and curl-focused styling products remain underdeveloped in male grooming channels across Germany and Brazil.
- California ingredient ban cascade:State-level prohibitions on formaldehyde-releasing preservatives are creating national distributor qualification requirements that favor preemptive reformulators.
Industry Challenges
- Trichology certification scarcity:Licensed stylists require 40+ hours of supplemental training to recommend pH-specific treatment protocols, slowing attachment rate growth.
- Legacy distributor integration:ERP system incompatibility between salon software platforms and brand inventory management is fragmenting reorder automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Hair Care Products Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Treatment, Styling Products End User: Salons, Barbershops, Spas, At-home Users Application: Color Care, Moisture, Texture, Damage Repair Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | L'Oréal S.A., Procter & Gamble, Henkel AG & Co. KGaA, Unilever, Kao Corporation, Wella Company, Olaplex Holdings, Inc., The Estée Lauder Companies Inc., Davines S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Hair Care Products Market Strategic Shifts
Formulation science and procurement digitization are compressing the gap between laboratory innovation and salon floor application, with regulatory compliance now serving as a competitive moat rather than mere cost center.
Spectroscopic hair analysis devices are automating personalized treatment recommendations in premium salons. Stylists in Tokyo and São Paulo are adopting handheld scanners that assess cuticle damage and moisture retention, feeding data directly into product dispensing systems. This automation is compressing consultation times while lifting average service tickets through precision-matched SKU recommendations.
REACH authorization requirements for salon-grade silicones and conditioning polymers are forcing ingredient substitutions ahead of 2027 sunset dates. Manufacturers are pivoting toward bio-fermented alternatives and plant-derived quaternary compounds. Color care lines face the steepest reformulation costs, with German and French brands absorbing 15-20% R&D budget reallocations to maintain ECHA compliance.
Licensed stylists are consolidating supplier relationships around distributors offering education-credit bundling and same-day replenishment. Independent salons in Japan and Brazil are abandoning multi-brand cabinets for single-source partnerships that include virtual color-matching support and waste-reduction incentives. This concentration is squeezing regional distributor margins while elevating national players with integrated logistics networks.
Professional Hair Care Products Market Segmentation
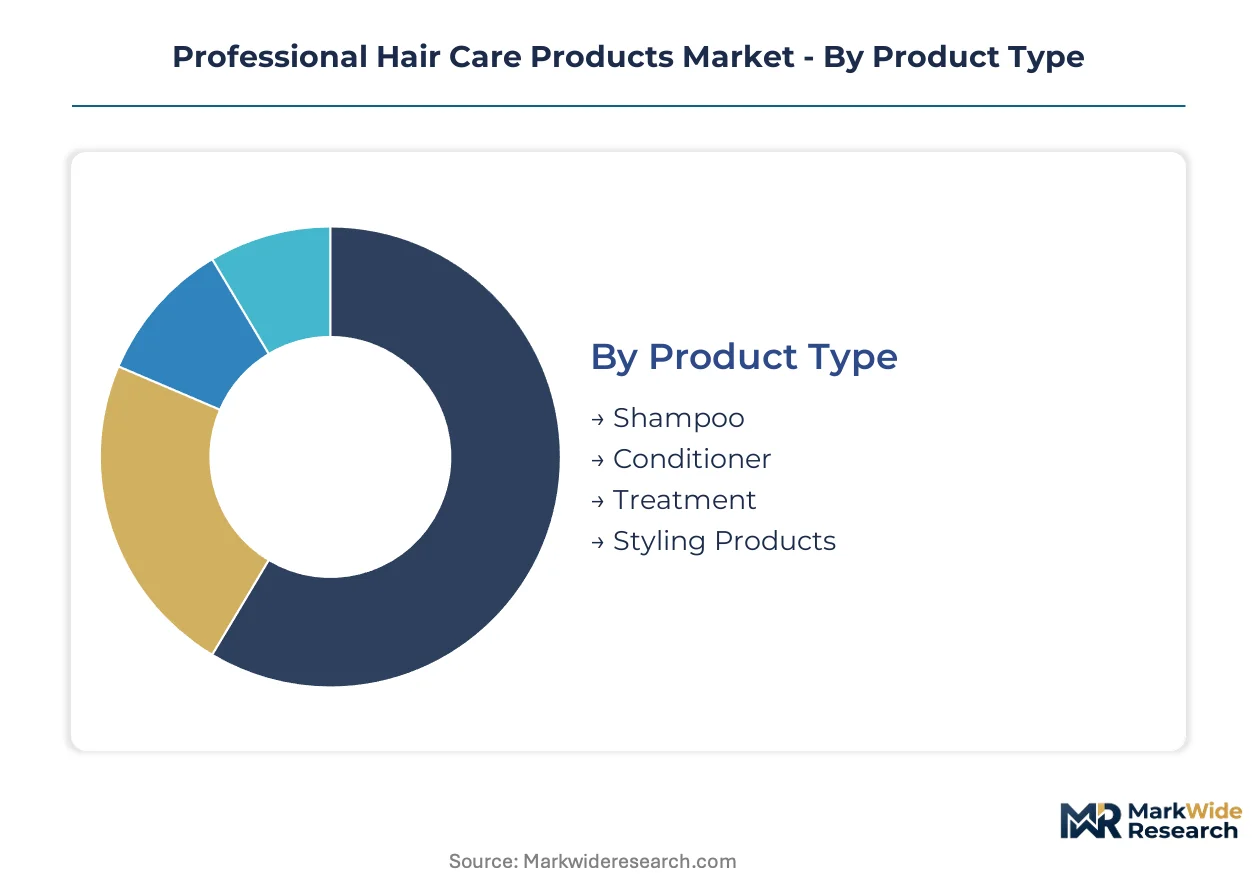
Professional hair care markets fragment across technical specifications, service contexts, and procurement channels. Each segmentation axis carries distinct margin profiles, regulatory exposure, and distributor qualification requirements that reshape competitive positioning.
Product Type:
pH specification and active ingredient concentration differentiate professional-grade formulations from retail equivalents, with heat-activated delivery systems commanding premium positioning.
- Shampoo:Salon-grade formulations maintain pH 4.5-5.5 for cuticle closure, with sulfate-free variants capturing preference in Japanese and German premium channels. Volume leadership masks margin compression from distributor private-label substitution in North American mid-tier supply chains.
- Treatment:Bond-building systems utilizing bis-aminopropyl diglycol dimaleate chemistry attach to 60% of chemical service bookings in Brazil and Japan. Heat-activated penetration technologies extend service intervals while justifying professional-only SKU premiums.
- Conditioner:Ceramide and protein complexes target cortex reinforcement, with silicone-free variants gaining traction under REACH authorization pressures.
- Styling Products:Humidity resistance and thermal protection claims differentiate offerings, with texture-focused lines for coil and curl patterns underdeveloped in male grooming channels.
Mature deployment sits with Shampoo. Newer deployment is concentrated in Treatment systems.
End User:
Licensed professional status determines product access, education requirements, and service-based attachment economics.
- Salons:Full-service chemical service providers in São Paulo and Tokyo are consolidating supplier relationships around education-credit bundling and same-day replenishment. Spectroscopic hair analysis devices automate personalized treatment recommendations, compressing consultation times while lifting average service tickets.
- Barbershops:Texture-specialized styling demand is realigning procurement patterns across distributor networks, with coil and curl-focused products remaining underdeveloped in Germany and Brazil.
- Spas:Wellness-positioned treatments integrate aromatherapy and scalp therapy protocols, with B Corp-certified manufacturing entrants capturing positioning space.
- At-home Users:Professional-grade product diversion through e-commerce channels challenges channel integrity, with salon-exclusive SKU strategies facing enforcement difficulties.
Channel concentration favors Salons for premium treatment attachment. Barbershops represent the steepest expansion trajectory for texture-specialized formulations.
Application:
Service intent drives active ingredient selection, processing time requirements, and repeat purchase velocity.
- Damage Repair:Bond-building chemistry patents are compressing formulation cycles, with German specialty chemical suppliers concentrating supply of key active ingredients.
- Color Care:Lines face steepest REACH reformulation costs, with German and French brands absorbing substantial R&D budget reallocations to maintain ECHA compliance ahead of silicone sunset dates.
- Moisture:Hyaluronic acid and panthenol formulations target cortex hydration, with bio-fermented alternatives gaining share under clean-label certification requirements.
- Texture:Coil and curl pattern specificity remains underserved in professional channels outside dedicated ethnic hair specialists.
Established demand centers on Color Care. Emerging formulation investment targets Damage Repair protocols.
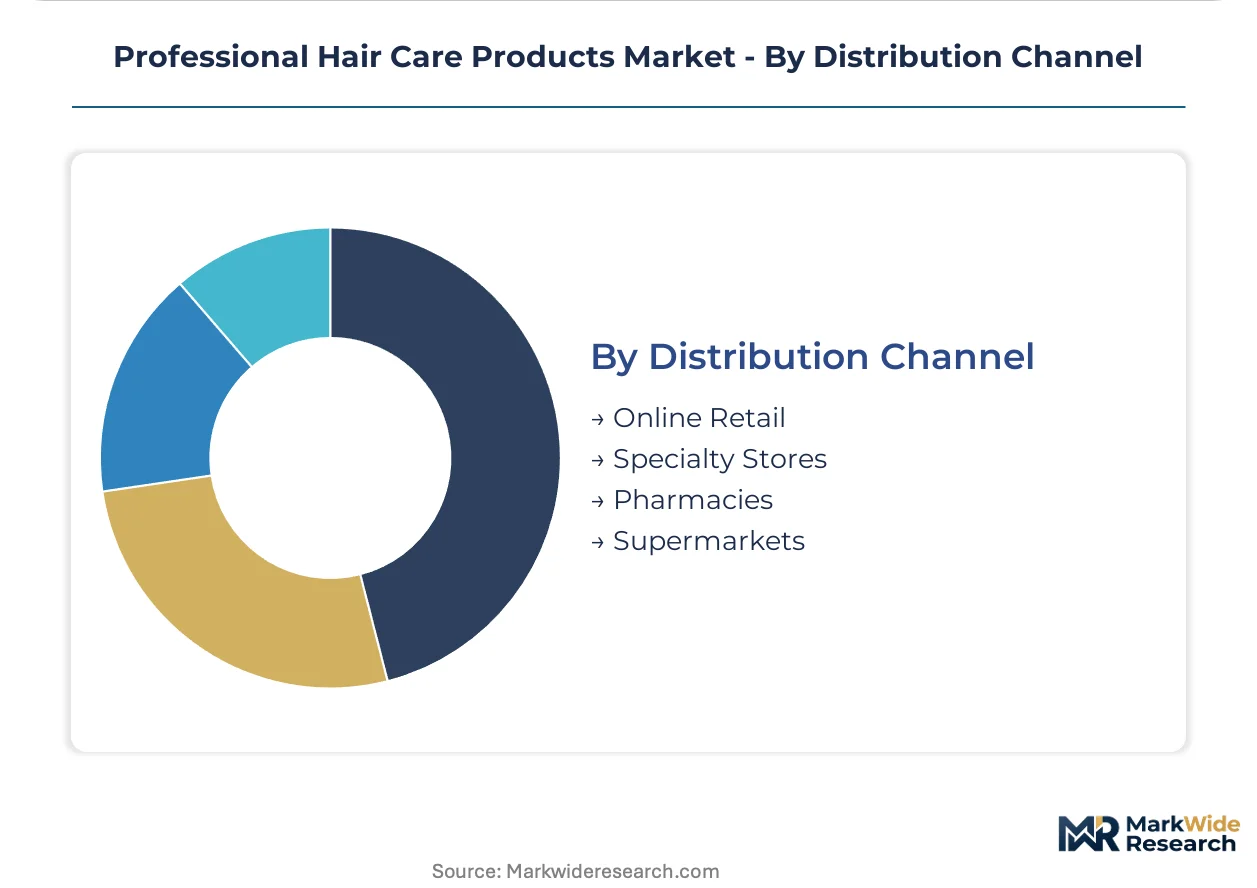
Distribution Channel:
Channel selection determines inventory velocity, education support availability, and regulatory documentation requirements.
- Specialty Stores:Salon-focused distributors in Japan and Brazil are integrating virtual color-matching support and waste-reduction incentives, squeezing regional players while elevating national operators with integrated logistics networks.
- Online Retail:Same-day replenishment capabilities and education-credit bundling are consolidating independent salon supplier relationships around single-source partnerships.
- Pharmacies:Professional-grade placement remains limited, with trichology certification requirements creating friction for recommendation-based sales.
- Supermarkets:Mass-market positioning conflicts with professional-grade concentration and pH balancing requirements, relegating offerings to diluted or licensed retail variants.
Dominant volume flows through Specialty Stores. Online Retail is gaining share fastest through replenishment automation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of active ingredients concentrates among German specialty chemical suppliers, while consumption gravity shifts toward high-service salon cultures in Brazil and Japan. Regulatory divergence between ECHA's REACH framework and FDA cosmetic labeling rules fragments compliance investment across export-oriented manufacturers.
United States
Licensed stylists attach bond-building treatments to a majority of chemical service bookings, driving repeat purchase velocity in premium salon channels. FDA cosmetic labeling rules extend product development timelines by 8-14 months for reformulation documentation cycles. Los Angeles and New York Metro anchor distributor consolidation around education-credit bundling and same-day replenishment capabilities.
Germany
REACH authorization deadlines for salon-grade silicones accelerate clean-label reformulation investments across European salon distributors. ECHA disclosure requirements create first-mover advantages for brands with pre-certified ingredient portfolios. The Rhine-Ruhr industrial corridor hosts three specialty chemical suppliers concentrating supply of bis-aminopropyl diglycol dimaleate and ceramide complexes.
Brazil
São Paulo salons drive 60% attachment rates for bond-building treatments to chemical service bookings, compressing consultation times through spectroscopic hair analysis adoption. ANVISA alignment with international cosmetic safety standards shapes import qualification requirements for professional-grade formulations. Southeast distributor networks realign procurement patterns around texture-focused styling demand from expanding barbershop channels.
Japan
Tokyo stylists adopt handheld scanners that assess cuticle damage and moisture retention, feeding data directly into product dispensing systems. METI standards for cosmetic manufacturing quality integrate with ISO 16128 natural and organic claims certification. Independent salons consolidate supplier relationships around single-source partnerships with virtual color-matching support.
France
Color care lines absorb substantial R&D budget reallocations to maintain ECHA compliance ahead of silicone sunset dates. ANSM oversight of cosmetic ingredient safety substantiates clean-label positioning for export-oriented professional brands. Parisian premium salons automate personalized treatment recommendations through spectroscopic analysis devices.
Professional Hair Care Products Market Competitive Environment
Top-tier vendors anchor professional color care and bond-building chemistry, while mid-tier specialists compete on ISO 16128 certification and B Corp manufacturing credentials. The vendor base stratifies across captive salon education programs, patented active ingredient portfolios, and Mediterranean craft positioning. Three archetypes dominate: multinational beauty conglomerates with integrated distributor networks, patent-holding treatment specialists, and certified clean-label craft manufacturers. Competitive moves concentrate on strategic partnerships for education-credit bundling and preemptive reformulation ahead of state-level ingredient bans.
Within the patent-holding specialist tier, Olaplex Holdings, Inc. exemplifies chemistry-driven differentiation, while Davines S.p.A. anchors B Corp-certified manufacturing credentials among Italian craft-positioned entrants. L'Oréal S.A. represents the integrated multinational archetype with captive salon education infrastructure. These three occupy positions across the premium treatment, clean-label certification, and scale-driven education vectors respectively.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Procter & Gamble |
| Henkel AG & Co. KGaA |
| Unilever |
| Kao Corporation |
| Wella Company |
| Olaplex Holdings, Inc. |
| The Estée Lauder Companies Inc. |
| Davines S.p.A. |
| Others |
Value Chain & Pricing Dynamics
REACH authorization deadlines for salon-grade silicones gate qualified supply access and premium-tier pricing power, forcing brands to absorb reformulation costs or surrender professional channel positioning. ECHA compliance investments stratify the vendor base between certified premium suppliers and excluded mid-tier competitors.
Pricing Analysis
Margin tightening in mid-tier shampoo and conditioner lines reflects private-label substitution capturing distributor volume. Three-tier pricing structure across professional-only, salon-exclusive, and diverted retail channels differentiates by certification grade and education bundling. Cost compression accelerates in standard-tier segments as Brazilian and Japanese salons consolidate single-source partnerships. Price sensitivity concentrates among independent stylists in North American beauty supply chains, while premium treatment buyers in Tokyo and São Paulo accept sustained premiums for bond-building chemistry.
Supply Chain Analysis
Specialized chemist workforce availability in the Rhine-Ruhr corridor, Osaka-Kobe manufacturing zones, and São Paulo industrial districts anchors active ingredient production. Bis-aminopropyl diglycol dimaleate and ceramide complexes draw from concentrated German specialty chemical suppliers, creating single-source vulnerability for mid-tier brands. Distribution runs through integrated national distributors offering same-day replenishment and education-credit bundling, squeezing regional players without logistics scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH authorization requirements create a barrier-to-entry moat favoring preemptive reformulators with certified ingredient portfolios.
For Market Incumbents: Hedge against private-label encroachment by deepening captive salon education infrastructure and securing backward integration into bio-fermented active ingredient production. Preemptive ISO 16128 certification investment locks out mid-tier competitors before state-level ingredient bans cascade into national distributor qualification requirements. For New Entrants and Emerging Players: Begin with barbershop texture-specialized styling demand in Germany and Brazil, the most penetrable white-space segment outside saturated salon treatment channels. Coil and curl-focused formulations for male grooming channels offer low competitive density and education-credit bundling partnerships with regional distributors. For Investors and Strategic Acquirers: California formaldehyde-releasing preservative prohibition enforcement is the leading indicator that national distributor qualification requirements are tightening, signaling acquisition timing for preemptive reformulators with clean-label portfolios. Target B Corp-certified manufacturing specialists with Mediterranean craft positioning and validated ECHA compliance pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Preemptive REACH Reformulation | ECHA compliance ahead of silicone sunset dates secures professional channel access against excluded competitors. |
| Captive Salon Education Expansion | L'Oréal-style education-credit bundling locks in stylist loyalty and repeat purchase velocity. |
| Spectroscopic Device Integration | Handheld cuticle analysis automation in Tokyo and São Paulo lifts service tickets through precision SKU matching. |
| Single-Source Distributor Consolidation | Same-day replenishment partnerships squeeze regional players lacking integrated logistics networks. |
| Barbershop Texture Line Launch | Coil and curl specialization captures underdeveloped male grooming demand in Germany and Brazil. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across salon owners, distributor procurement managers, licensed stylists, and specialty chemical R&D directors. ECHA authorization databases, FDA cosmetic labeling submissions, ANVISA import qualification records, and METI manufacturing quality filings provided compliance tracking. Bottom-up SKU-level volume estimates triangulated against top-down channel revenue assessments.
Data-stream reconciliation across product type, end user, application, and distribution channel dimensions shaped projections over the analysis window. CAGRs derived from segment-level growth rate distributions weighted by regional salon service booking trends and spectroscopic device adoption curves. Bond-building treatment attachment rates and private-label substitution velocity informed treatment and shampoo segment trajectories respectively.
Regulatory enforcement delays, raw material supply disruptions, and distributor consolidation failures are the dominant revision risks to modeled outcomes. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Sweden Hair Care Market
Hair Care
France Haircare Market
Hair Care
Hair and Scalp Care Market
Hair Care
Global Hair Color Market
Hair Care
Hair Tonic Market
Hair Care
Australia Hair Care Market
Hair Care
Japan Hair Care Market
Hair Care
South Korea Hair Care Market
Hair Care
Hair Edge Tamer Market
Hair Care
Hair Care Market
Hair Care
Hair Bond Multiplier Market
Hair Care
Brazil Hair Care Market
Hair Care
Global Professional Hair Care Market
Hair Care
Hair Texturizer Products Market
Hair Care
Organic Hair Care Market