
 Global Professional Hair Care Market | 2026-2036
Global Professional Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Professional Hair Care Market Outlook
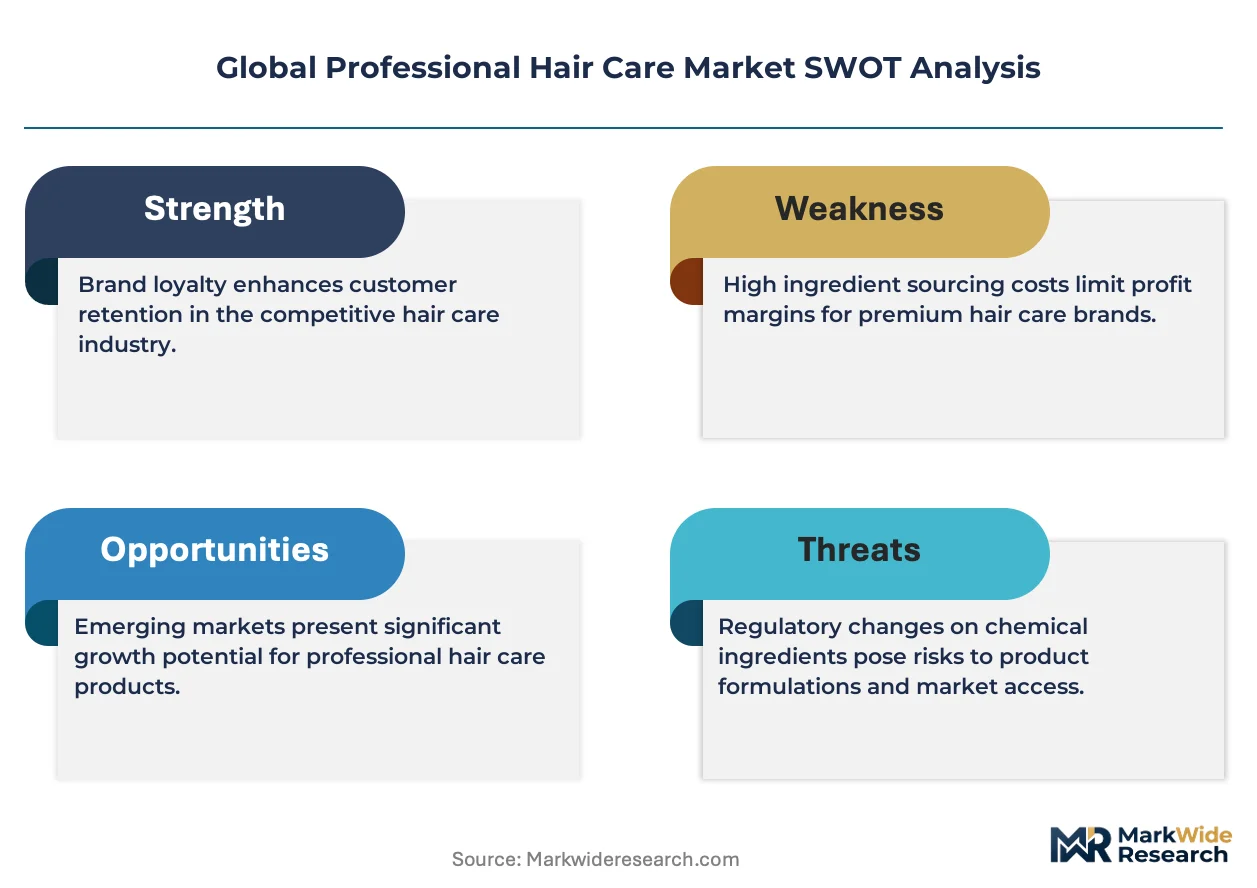
Salon-grade formulation standards is collapsing the gap between professional-only and retail-accessible performance tiers. L'Oréal Groupe leverages its Redken and Kérastase professional divisions to sustain channel exclusivity through licensed salon distribution. Henkel AG & Co. KGaA anchors its Schwarzkopf Professional line with ammonia-free colorant technology that dominates European salon procurement. Olaplex Holdings, Inc. differentiates through patented bond-building chemistry that extends repair service pricing power in premium salons.
Professional hair care encompasses products manufactured to higher active-concentration specifications than mass-market equivalents, typically requiring stylist training for proper application and often incorporating pH-balanced or bond-repair chemistries designed for repeated chemical processing environments. Hair colorants and hair treatments command the deepest margin pools due to service-attach rates and repeat visit dependency, while scalp care represents the fastest-expanding application as trichology certification spreads among stylists. Distribution through salon channels controls the majority of value capture, though online retailers are fragmenting replenishment purchasing among independent professionals.
REACH in Europe, FDA cosmetic labeling requirements in the United States, and China's GB standards for imported cosmetics collectively reshape permissible ingredient palettes and compliance documentation burdens for cross-border formulation portfolios. The EU AI Act introduces emerging scrutiny on algorithmic shade-matching tools deployed in salon color consultation systems. Stakeholders must monitor regulatory divergence between jurisdictions while building flexible formulation platforms that accommodate tightening chemical restrictions without degrading stylist-perceived performance thresholds.
Market Dynamics
Professional hair care is experiencing a fundamental channel compression as salon-exclusive formulations leak into direct-to-consumer channels, forcing incumbent suppliers to rebuild credentialing systems around stylist certification rather than physical distribution control.
Growth Catalysts
- EU Green Deal chemical phase-outs:REACH-mandated ingredient restrictions are accelerating reformulation cycles that favor professional-grade suppliers with dedicated R&D infrastructure over mass-market competitors.
- Trichology certification expansion:Scalp health specialization among licensed stylists in Germany and the United States is creating service-attach revenue streams for diagnostic equipment and targeted treatment protocols.
- China's GB standards liberalization:Streamlined import cosmetics registration for professional-use products is opening salon channel entry for European and North American formulation houses previously blocked by documentation burdens.
Market Restraints
- Isopropyl alcohol and silicone volatility:Feedstock cost swings tied to crude oil derivatives compress margin predictability for treatment and styling product lines.
- Professional colorant precursor concentration:Technical ceilings on oxidative dye penetration depth limit damage-free lightening performance, capping service pricing power for high-lift applications.
- REACH documentation reciprocity gaps:Divergent hazard classification between EU member states creates compliance friction for cross-border salon chain procurement.
Strategic Opportunities
- India's salon franchise consolidation:Organized retail penetration in tier-two cities creates demand for standardized professional product portfolios with training infrastructure.
- AI-assisted shade matching:Convergence of spectrophotometry and tablet-based consultation tools enables premium service tiering in color departments.
- Waterless formulation protocols:Concentrated anhydrous treatments address drought-region salon operating constraints in California and Australia while reducing shipping weights.
Industry Challenges
- Red Seal and cosmetology board reciprocity:Inconsistent state-level licensing requirements in the United States fragment training standardization for product-specific application certification.
- Legacy salon software integration:Inventory management systems from the 2010s lack API connectivity with modern brand portals, forcing manual reorder workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Professional Hair Care Market |
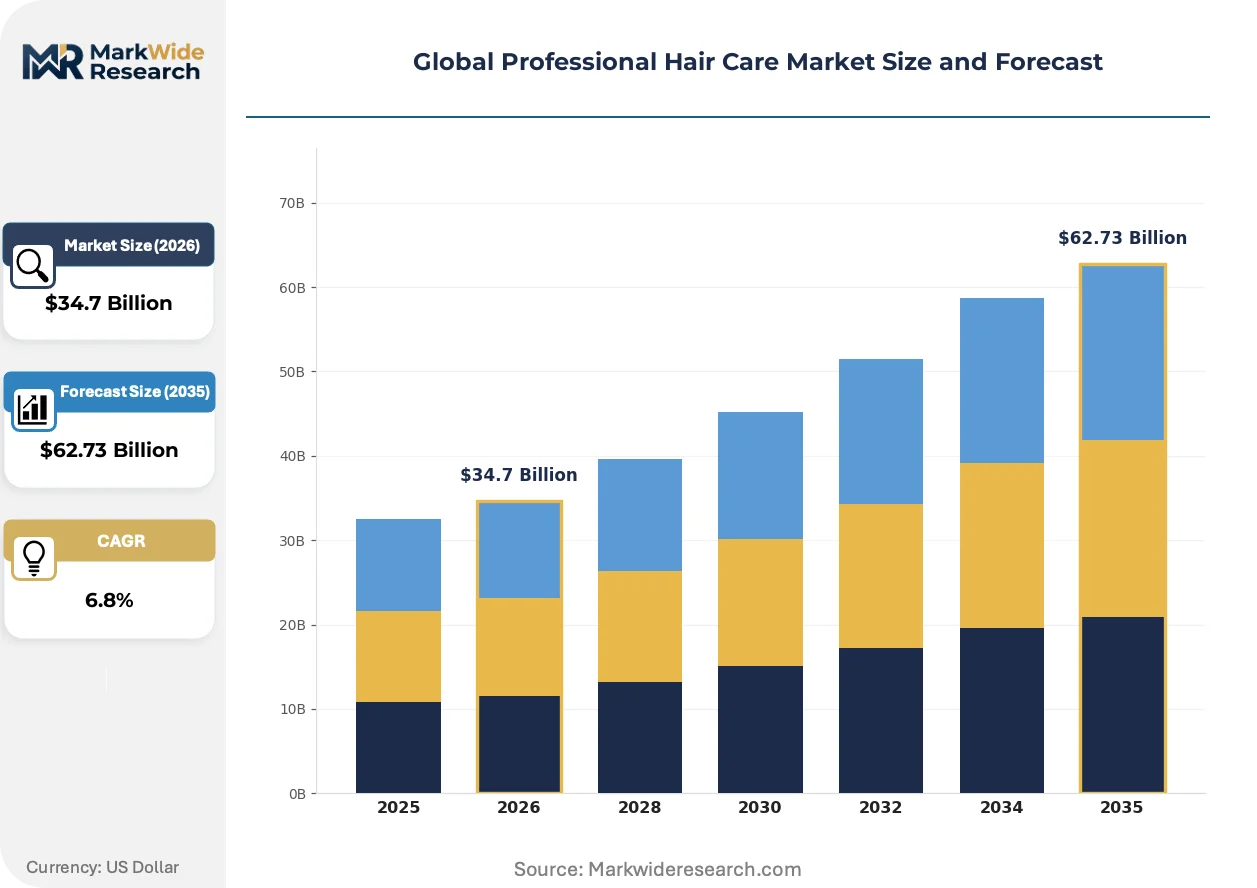
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Colorants, Hair Styling Products, Hair Treatments, Scalp Care Application: Hair Coloring, Hair Styling, Hair Repair, Scalp Treatment, Hair Cleansing, Hair Conditioning Distribution Channel: Salon Channels, Specialty Stores, Online Retailers, Beauty Parlors, Department Stores, Direct Sales Customer Type: Professional Stylists, Salons, Beauty Experts, Hairdressers, Cosmetologists, Barbers |
| Companies Covered | L'Oréal Groupe, Henkel AG & Co. KGaA, Kao Corporation, Wella Company, Olaplex Holdings, Inc., Estée Lauder Companies, Coty Inc., Davines Group, Kevin Murphy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Professional Hair Care Market Strategic Shifts
Bond-building chemistry and algorithmic color consultation are redrawing competitive boundaries between formulation suppliers and technology vendors, collapsing the traditional separation between product and service innovation.
Bis-aminopropyl diglycol dimaleate and similar bond-multiplier molecules now function as service-pricing anchors in premium color departments. Stylists in Los Angeles, London, and Shanghai have adopted these additives as standard protocol for bleach-and-tone services. This chemistry is decomposing the historical trade-off between lift level and hair integrity, enabling salons to charge premium rates for previously high-risk transformations.
REACH Annex XVII restrictions on sensitizing fragrance compounds and the EU AI Act's emerging scrutiny of algorithmic consultation tools are forcing dual compliance investments. Formulators must now document both chemical safety and decision-system transparency for shade-matching software deployed in salon environments. German and French regulators are piloting inspection protocols that treat AI-assisted color recommendation as a medical-adjacent service requiring audit trails.
Independent stylists operating suite rentals and mobile services now bypass distributor intermediaries for replenishment purchasing. This channel fragmentation concentrates in the United States and Australia where booth-rental licensing dominates salon employment structures. Brand loyalty is shifting from distributor sales representatives toward peer-reviewed social proof and direct manufacturer education content.
Global Professional Hair Care Market Segmentation
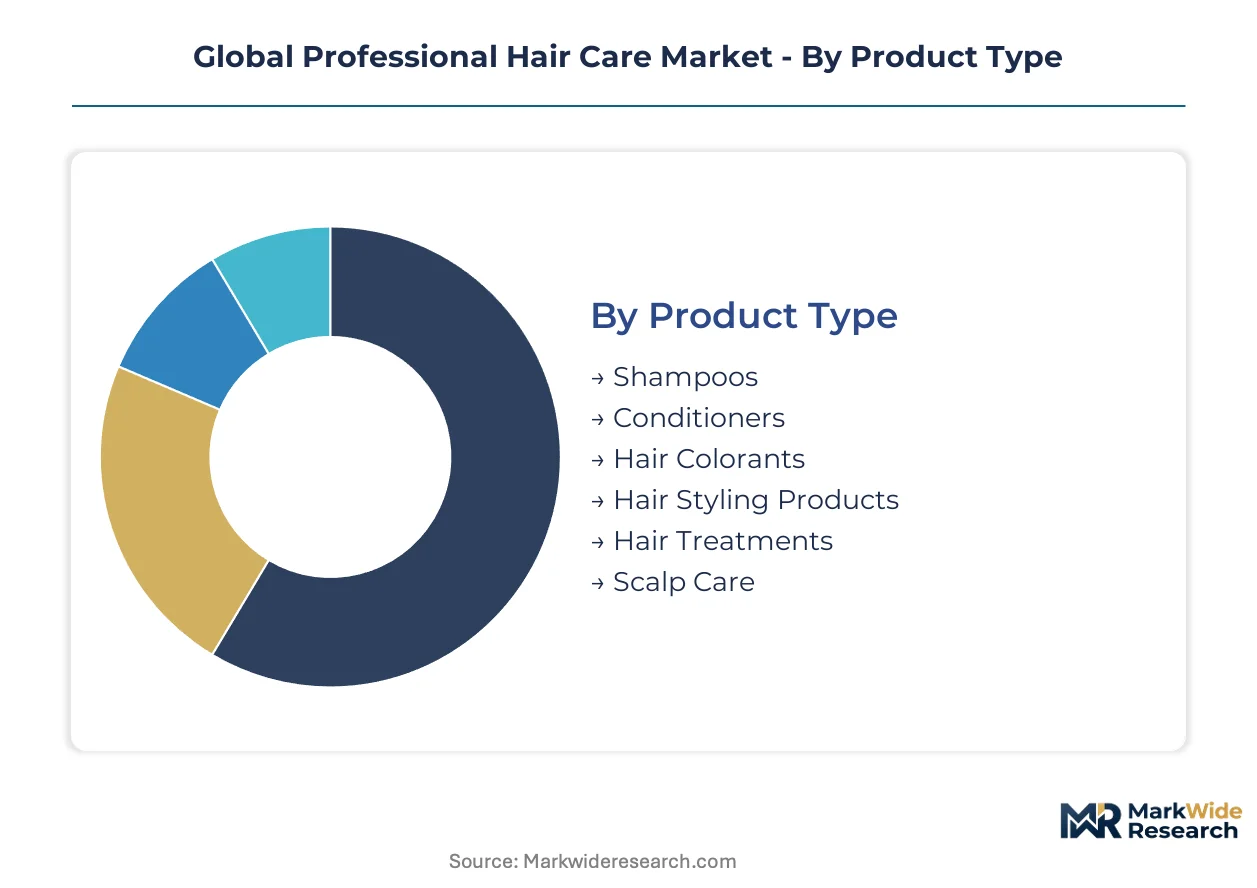
Professional hair care segmentation reflects the market's dual identity as both service-enabling chemistry and retail-accessible expertise. Channel control determines margin capture, with salon-exclusive formulations commanding premium positioning against mass-market alternatives.
Product Type:
Salon channels concentrate demand for high-concentration actives requiring stylist training, while specialty stores and online retailers fragment replenishment purchasing for maintenance products.
- Shampoos:pH-balanced formulations with chelating agents dominate pre-color service protocols. German and Japanese salon chains standardize on sulfate-free bases that extend color longevity between appointments.
- Conditioners:Cationic surfactant systems with hydrolyzed protein fractions support chemical service recovery. California drought regulations are accelerating concentrated rinse-off formats that reduce water consumption per treatment.
- Hair Colorants:Oxidative dye precursors with controlled ammonia or MEA alkalizers form the core revenue pool. Professional-only oxidative systems resist retail channel leakage through developer-concentration calibration.
- Hair Styling Products:Film-forming polymers and volatile silicone carriers enable finish customization. Demand concentrates in metropolitan salon districts where editorial and entertainment clientele drive texture-specific formulation requests.
- Hair Treatments:Bond-building molecules and lipid-replenishment emulsions anchor premium service pricing. Los Angeles, London, and Shanghai stylists have adopted bis-aminopropyl diglycol dimaleate additives as standard bleach protocol.
- Scalp Care:Trichology-certified diagnostic protocols are expanding this category fastest among German and United States stylists. FDA-registered active ingredients for seborrheic conditions require professional dispensing oversight.
By volume, Shampoos and Conditioners lead as baseline service prerequisites. By growth pace, Scalp Care is expanding most quickly on trichology certification penetration.
Application:
Margin concentration varies sharply by service attach rate, with color-dependent applications sustaining repeat visit economics against one-time repair interventions.
- Hair Coloring:Oxidative permanent, demi-permanent, and direct dye systems generate the deepest margin pools through chemical service dependency. REACH-compliant PPD alternatives are reformulating European salon procurement specifications.
- Hair Styling:Finish and hold products support event-service pricing tiers. Thermal protection formulations with heat-activated polymers dominate blow-dry bar service menus in United States metropolitan markets.
- Hair Repair:Bond-multiplier and protein-reconstruction protocols enable premium pricing for compromised hair transformations. Olaplex's patent-protected chemistry established this application as a standalone service category.
- Scalp Treatment:Diagnostic-led protocols with instrumentation attachments create equipment-plus-consumable revenue streams. Trichoscopy certification requirements in Germany limit product dispensing to certified practitioners.
- Hair Cleansing:Clarifying and chelating pre-treatments prepare hair for chemical services. Hard water regions in Texas and Arizona drive chelating shampoo demand for mineral deposit removal.
- Hair Conditioning:Deep conditioning masks and leave-in treatments support retail attachment at service conclusion. China's GB standards for imported professional conditioners streamlined registration documentation.
Hair Coloring generates the highest absolute revenue per service. Scalp Treatment shows the steepest expansion trajectory on certification infrastructure investment.
Distribution Channel:
Physical channel control is eroding as independent professionals bypass intermediaries for direct manufacturer replenishment.
- Salon Channels:Licensed distributor networks with education-field sales representatives retain core colorant and treatment volume. L'Oréal's Redken and Kérastase divisions enforce exclusivity through salon credentialing systems.
- Specialty Stores:Professional-only SKUs with higher active concentrations than mass equivalents serve independent stylists. United States beauty supply stores in Texas and Florida cluster near cosmetology school concentrations.
- Online Retailers:Direct-to-stylist replenishment is fragmenting loyalty from distributor sales representatives. Australian booth-rental stylists concentrate purchasing through manufacturer-direct portals.
- Beauty Parlors:Tier-two city franchise networks in India standardize procurement through organized retail. Henkel's Schwarzkopf Professional targets this channel with ammonia-free colorant portfolios.
- Department Stores:Premium treatment lines with consultation counters bridge professional and retail positioning. Selective distribution agreements limit SKU overlap with salon channels.
- Direct Sales:Education-embedded selling through academy and show formats sustains brand loyalty. Manufacturer field educators in France and Italy drive adoption through hands-on certification workshops.
Salon Channels retain the largest value share. Online Retailers are gaining share fastest on independent professional purchasing migration.
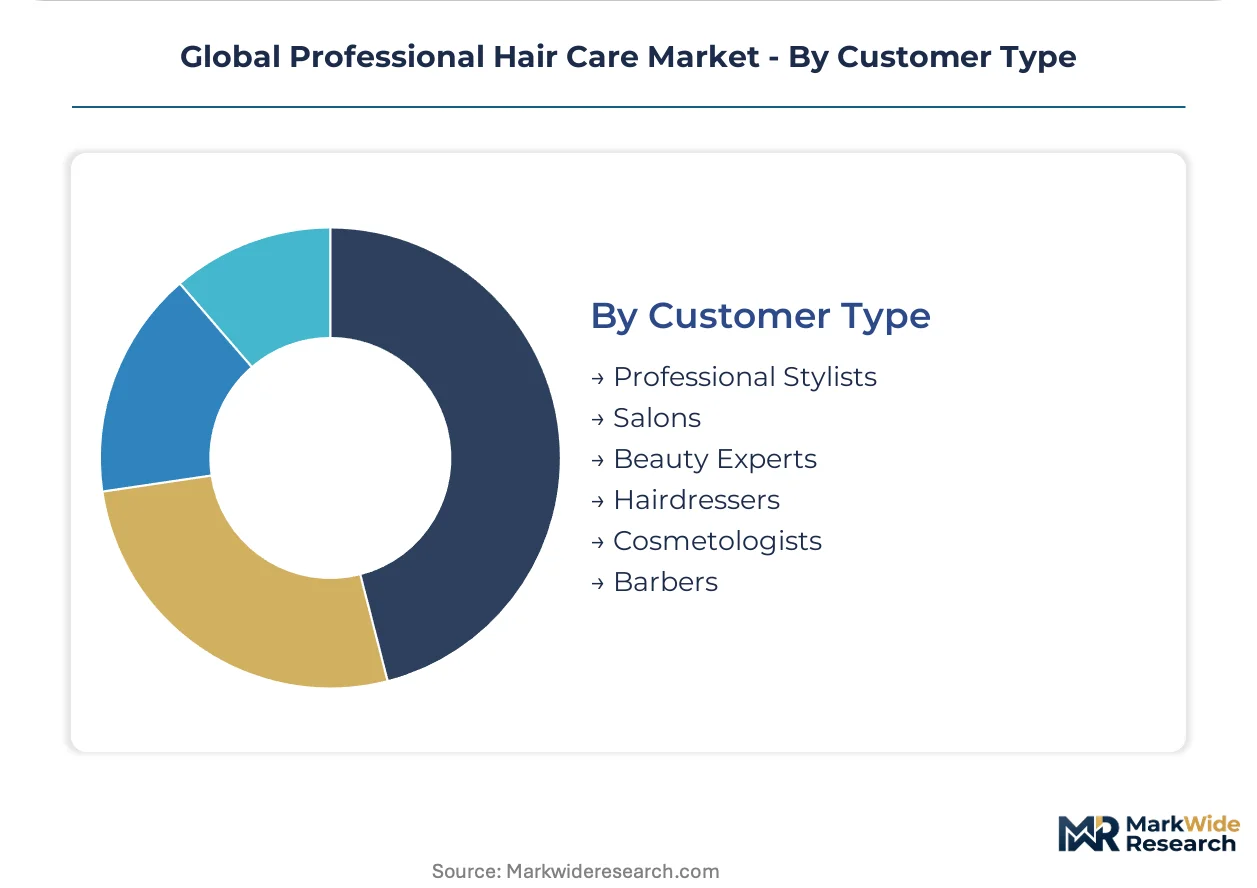
Customer Type:
Employment structure—booth rental versus commission—determines procurement autonomy and brand switching flexibility.
- Professional Stylists:Independent practitioners with suite rentals or mobile services drive direct purchasing fragmentation. Social proof and peer-reviewed content are displacing distributor sales representative relationships.
- Salons:Multi-staff establishments with inventory centralization sustain distributor relationships and volume commitments. Franchise networks in India's tier-two cities demand standardized training-infrastructure bundles.
- Beauty Experts:Editorial and celebrity specialists command formulation customization for high-visibility applications. Los Angeles and New York concentration supports premium service tier development.
- Hairdressers:Licensed practitioners in European apprenticeship systems follow manufacturer education curricula. German chamber of commerce certification requirements structure product-specific training pathways.
- Cosmetologists:State-board licensed professionals in the United States face fragmented reciprocity requirements. Red Seal certification gaps between California, Texas, and New York complicate standardized training deployment.
- Barbers:Male-grooming specialization is expanding scalp treatment and beard-care protocol adoption. United Kingdom barbering certification now incorporates trichology fundamentals.
Professional Stylists represent the largest addressable base by headcount. Salons concentrate the highest per-account revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in professional hair care tilt toward formulation houses in Germany, France, and the United States supplying salon chains across Asia-Pacific and Latin America. Trade documentation burdens under divergent chemical disclosure regimes create compliance friction that favors suppliers with dedicated regulatory affairs infrastructure.
United States
Salon franchise consolidation in Texas and Florida drives standardized procurement of ammonia-free colorant portfolios. FDA cosmetic labeling requirements mandate ingredient disclosure thresholds that exceed mass-market equivalents. Los Angeles stylists pioneered bond-building service protocols that now anchor premium pricing tiers nationwide.
Germany
Trichology certification expansion among chamber-of-commerce-licensed hairdressers creates equipment-plus-consumable revenue streams for scalp diagnostic protocols. REACH Annex XVII restrictions on sensitizing fragrance compounds accelerate reformulation cycles. Berlin-Brandenburg salon chains standardize on sulfate-free pre-color bases that extend oxidative dye longevity.
China
Streamlined GB standards registration for professional-use imports opens salon channel entry for European formulation houses previously blocked by documentation burdens. Shanghai and Beijing salon districts concentrate demand for high-lift oxidative systems with controlled alkalizers. NMPA alignment with international cosmetic safety standards reduces cross-border compliance duplication.
India
Organized retail penetration in tier-two cities creates demand for standardized professional portfolios with embedded training infrastructure. Maharashtra and Gujarat salon franchise networks procure ammonia-free colorants through centralized distributor agreements. BIS certification requirements for imported cosmetics structure procurement around documented safety dossiers.
Australia
Booth-rental employment structures concentrate independent stylist purchasing through manufacturer-direct portals, fragmenting traditional distributor loyalty. TGA cosmetic ingredient restrictions align closely with REACH standards, easing European supplier market entry. Sydney and Melbourne metropolitan salons drive concentrated demand for waterless anhydrous treatment formats addressing drought-region operating constraints.
Global Professional Hair Care Market Competitive Environment
Listed leaders compete with private specialists across channel control and formulation exclusivity. The market structure concentrates around multinational beauty conglomerates with dedicated professional divisions, mid-scale private specialists with certification-embedded distribution, and technology-focused innovators with patented chemistries. Three archetypes dominate: conglomerate professional divisions enforcing salon exclusivity through licensing systems, regional specialists leveraging ammonia-free or bond-building formulations, and direct-to-stylist challengers bypassing distributor intermediaries. Competitive moves center on stylist certification platform investments and direct e-commerce portal development for independent practitioner replenishment.
Within the conglomerate tier, L'Oréal Groupe and Henkel AG & Co. KGaA exemplify channel control through salon credentialing infrastructure. Olaplex Holdings, Inc. occupies a position representing patented chemistry specialists that transformed repair services into standalone premium categories. These three entities collectively illustrate the competitive tension between physical distribution control and direct digital engagement with independent stylists.
| Leading Market Players |
|---|
| L'Oréal Groupe |
| Henkel AG & Co. KGaA |
| Kao Corporation |
| Wella Company |
| Olaplex Holdings, Inc. |
| Estée Lauder Companies |
| Coty Inc. |
| Davines Group |
| Kevin Murphy |
| Others |
Value Chain & Pricing Dynamics
Long-term distributor contracts with take-or-pay minimums lock in supply access for salon-exclusive colorant portfolios while anchoring price visibility against feedstock volatility in European and North American procurement corridors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in professional hair care procurement. Price differentiation hinges on stylist certification grade and volume scale commitments, with premium tiers commanding exclusivity through bonded salon education infrastructure. Pricing pressure stems from isopropyl alcohol and silicone feedstock volatility tied to crude oil derivative markets. Independent booth-rental stylists exhibit highest price sensitivity as direct-to-manufacturer purchasing erodes distributor-negotiated volume discounts.
Supply Chain Analysis
Just-in-time inventory preferences dominate salon channel replenishment, though strategic stockpiling of REACH-compliant precursor chemicals buffers against regulatory phase-out disruptions in European manufacturing nodes. Raw material concentration centers on Germany, France, and the United States for oxidative dye intermediates, with China supplying film-forming polymer feedstocks. Supply chain risk rests on single-source vulnerability for patented bond-building molecules held by specialized chemistry houses. Distribution runs through licensed distributor networks with embedded field education representatives sustaining brand loyalty against direct e-commerce fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional hair care is approaching a platform-economics inflection as AI-assisted shade-matching tools and certification-embedded software ecosystems redraw the boundary between product supplier and service infrastructure provider.
For Market Incumbents: Shield salon-exclusive colorant margins by deepening stylist certification platform investments that embed switching costs beyond physical distribution control. Counter direct-to-stylist e-commerce challengers through API-integrated inventory management partnerships with legacy salon software providers. Vertical integration into bond-building chemistry R&D secures pricing power against patent-expiry pressure from generic additive suppliers.
For New Entrants and Emerging Players: Anchor in India's tier-two city salon franchise consolidation, where standardized training infrastructure demand outpaces incumbent supplier localization speed. Target scalp care diagnostic equipment as the fastest-expanding application segment, leveraging trichology certification gaps in United States state-level licensing reciprocity. Deploy education-embedded direct sales through academy partnerships rather than distributor intermediaries to bypass entrenched channel relationships.
For Investors and Strategic Acquirers: Patented chemistry specialists with FDA-registered active ingredient portfolios offer defensive moats against REACH-mandated reformulation cycles compressing generic formulation margins. Long-term viability favors suppliers with dual-use professional-retail SKU architectures that capture replenishment purchasing as salon channel control erodes. Watch for EU AI Act inspection protocol finalization as the signal triggering compliance investment requirements for algorithmic consultation tool vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Stylist Certification Platform Investment | Embedding L'Oréal and Henkel education curricula creates switching costs that resist direct e-commerce defection. |
| Direct-to-Stylist E-Commerce Portal Launch | Bypassing distributor intermediaries captures Australian and United States booth-rental purchasing migration. |
| REACH-Compliant Reformulation Acceleration | Ammonia-free colorant R&D responds to EU Green Deal chemical phase-outs favoring professional-grade suppliers. |
| AI-Assisted Shade Matching Integration | Spectrophotometry and tablet-based tools enable premium service tiering in German and French color departments. |
| Waterless Anhydrous Treatment Development | Concentrated formats address California and Australia drought-region salon operating constraints while reducing shipping weights. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with salon owners, distributor procurement managers, trichology certification program directors, and professional brand field educators; and secondary validation against customs/trade data, SEC 10-K filings from listed beauty conglomerates, REACH Annex XVII regulatory filings, and salon industry association membership records. Bottom-up triangulation across product-level volume estimates and top-down cross-checks against channel revenue flows anchored forecast integrity.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type concentration tiers, application service-attach rates, distribution channel control levels, and customer employment structure archetypes. CAGRs were derived from regression-weighted historical trajectory analysis adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated trichology certification penetration curves and REACH chemical phase-out implementation timelines.
Material uncertainties — regulatory divergence between EU member states, feedstock cost volatility in silicone and isopropyl alcohol markets, and algorithmic consultation tool compliance thresholds under emerging AI Act scrutiny — sit outside the modeled envelope. Forecasts reflect assumptions regarding salon franchise consolidation pace and direct e-commerce adoption curves among independent stylists. Revision becomes warranted when booth-rental licensing share in key state markets crosses thresholds that fundamentally alter distributor channel economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
South Korea Hair Care Market
Hair Care
Hair Mask Market
Hair Care
Brazil Hair Care Market
Hair Care
Hair Oil Market
Hair Care
Hair Texturizer Products Market
Hair Care
Hair Care Market
Hair Care
Hair Relaxer Market
Hair Care
Chile Hair Care Market
Hair Care
Hair Dye Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Russia Salon Hair Care Market
Hair Care
Latin America Hair Care Market
Hair Care
Hair Serum Market
Hair Care
Sweden Hair Care Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Hair Care Appliances Market