
 Asia Pacific Hair Styling Products Market | 2026-2036
Asia Pacific Hair Styling Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Hair Styling Products Market Outlook
ISO 16128 natural and organic cosmetics standards is reorganizing competitive access across the Asia Pacific hair styling products sector. Amorepacific Corp. leverages its integrated R&D campuses in South Korea to fast-track clean-label certifications. Kao Corp. anchors volume through mass-market aerosol manufacturing networks spanning Japan and Thailand. Shiseido Co. Ltd. differentiates via salon-exclusive professional lines that command premium positioning in Tokyo and Osaka.
Asia Pacific hair styling products encompass creams, liquids, aerosols, and gels formulated with film-forming polymers, solvents, and conditioning agents to shape, fix, or texturize hair for consumer and professional use. Hair spray formulations rely on vinyl acetate copolymers and hydrocarbon propellants to deliver humidity-resistant hold factors between eight and seventy-two hours. Hair wax segments capture concentrated margin pools in Japan and South Korea where matte-finish pomades target male grooming routines. Mousse applications remain the fastest-expanding category among professional salons across Indonesia and Vietnam due to lightweight volumizing properties suited to humid climates.
Japan's Ministry of Health, Labour and Welfare and South Korea's MFDS enforce ingredient disclosure and safety testing protocols that elevate compliance costs for new market entrants. China's SAMR and GB standards for cosmetics labeling create additional registration barriers for aerosol-based products containing volatile organic compounds. Brands must monitor regulatory divergence between Japan's quasi-drug classification for anti-hair-loss styling claims and South Korea's functional cosmetics approval pathway.
Market Dynamics
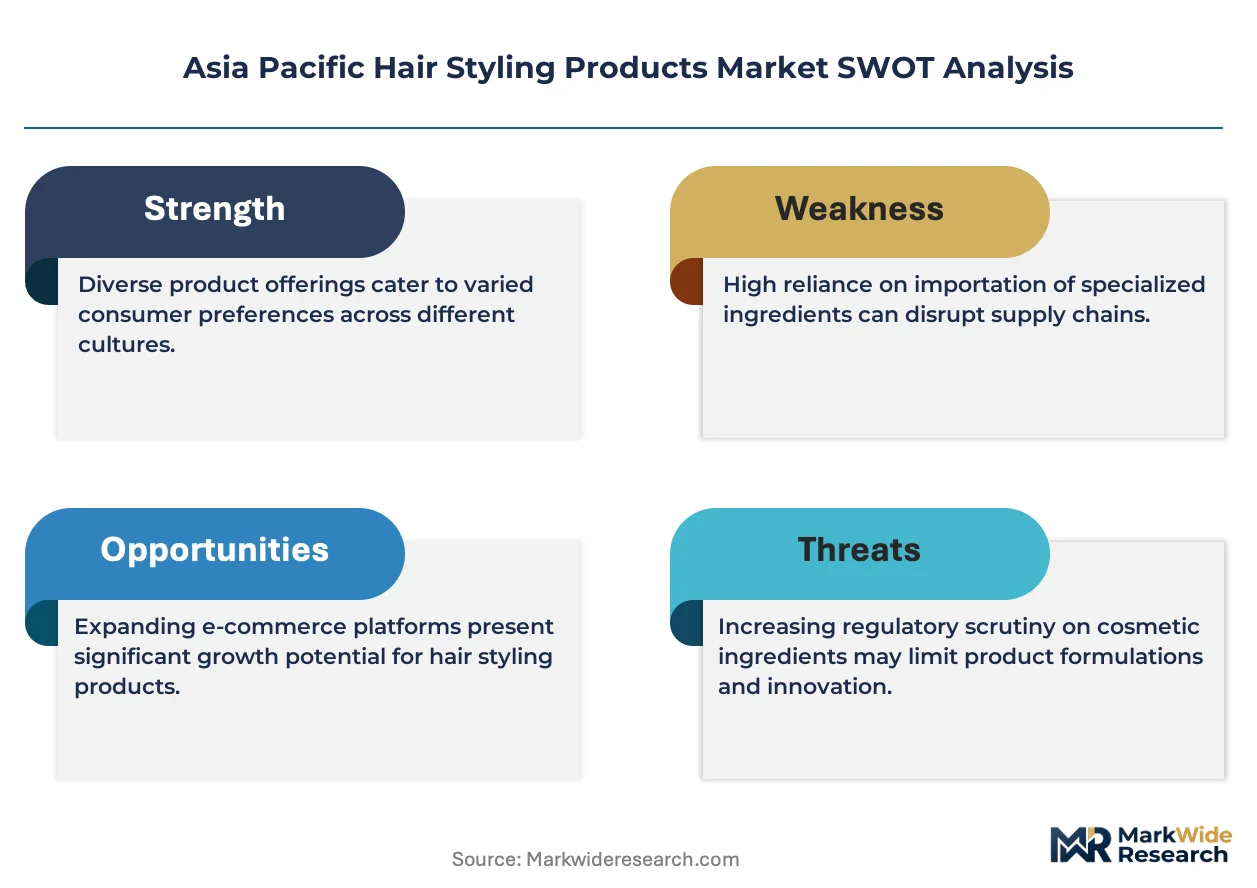
ISO 16128 natural and organic cosmetics standards are reorganizing competitive access across the Asia Pacific hair styling products sector, forcing reformulation investments and clean-label certifications that favor integrated R&D operators over import-reliant distributors.
Growth Catalysts
- Clean-label certification mandates:Japan's Ministry of Health, Labour and Welfare ingredient disclosure rules push brands toward transparent polymer sourcing and solvent replacement, accelerating adoption of plant-derived film-formers in professional salon lines.
- Seoul metropolitan corridor demand density:K-beauty trend velocity drives frequent product turnover and salon visit frequency, creating concentrated margin pools for styling wax and pomade formats targeting male grooming routines.
- Aerosol manufacturing network expansion:Mass-market production hubs spanning Japan and Thailand enable hydrocarbon propellant supply security for humidity-resistant hair spray formulations serving Southeast Asian climates.
Market Restraints
- Vinyl acetate copolymer input volatility:Petrochemical feedstock price swings compress margin stability for hold-factor formulations targeting 8-72 hour performance claims.
- China SAMR registration barriers:GB standards for cosmetics labeling and volatile organic compound restrictions create extended approval timelines for aerosol-based entrants.
- Water-based formulation substitution:Mousse and cream alternatives threaten traditional aerosol volume in Indonesia and Vietnam professional salon channels.
Strategic Opportunities
- Vietnam salon channel underpenetration:Lightweight volumizing mousse applications remain underdistributed in Ho Chi Minh City professional networks despite humid climate suitability.
- South Korea functional cosmetics pathway:MFDS approval frameworks for anti-hair-loss styling claims enable premium positioning for quasi-drug positioned treatments.
- E-commerce direct-to-stylist platforms:Professional-only digital procurement bypasses traditional distributor markups in Tokyo and Osaka metropolitan clusters.
Industry Challenges
- Formulation chemist scarcity:Clean-label polymer expertise concentrates in South Korean R&D campuses, creating talent acquisition friction for regional expansion.
- Dual regulatory divergence:Japan's quasi-drug classification conflicts with South Korea's functional cosmetics pathway, forcing parallel compliance investments for cross-border brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Hair Styling Products Market |
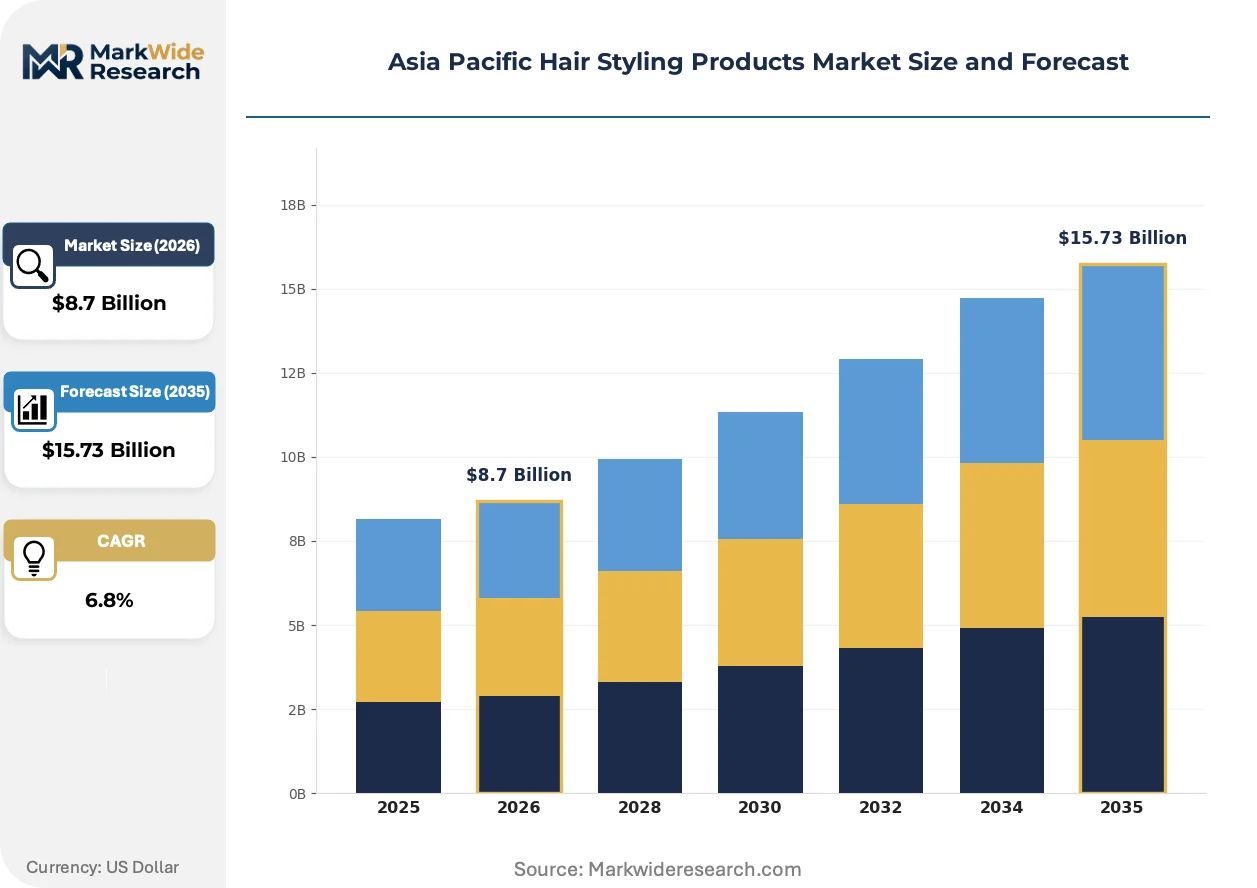
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Gel, Hair Spray, Hair Wax, Mousse End User: Professional Salons, Individual Consumers, Retail Chains, Cosmetology Schools Application: Styling, Fixing, Conditioning, Texturizing Formulation: Cream, Liquid, Aerosol, Gel |
| Companies Covered | Mandom Corp., Arimino Co. Ltd., Amorepacific Corp., Beiersdorf AG, Nature Republic, Kao Corp., Kose Corp., Henkel AG and Co. KGaA, Shiseido Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Hair Styling Products Market Strategic Shifts
Biodegradable film-forming polymers and water-soluble styling bases are actively displacing conventional petrochemical hold agents across Asia Pacific professional and consumer channels, with regulatory pressure and salon sustainability mandates accelerating adoption curves.
Plant-derived chitosan and pullulan-based fixatives are displacing vinyl acetate copolymers in premium salon-exclusive lines. Tokyo and Osaka professional stylists are adopting these reformulations at pace, with hold-factor performance now matching synthetic benchmarks. This displacement is compressing traditional polymer supplier margins while opening formulation partnerships between Korean biotech feedstock producers and Japanese finished goods manufacturers.
Japan's Ministry of Health, Labour and Welfare expanded quasi-drug classification requirements for anti-hair-loss styling claims, forcing ingredient-level safety documentation and clinical substantiation. Industrial consequence includes 12-18 month registration extensions for functional styling treatments. Professional salon segments in Tokyo metropolitan corridors absorb these delays through pre-launch education investments, while mass-market entrants retreat to basic hold-and-shine positioning.
Salon procurement patterns are fragmenting toward brand-direct digital platforms that bypass traditional beauty distributor networks. Independent stylists in Seoul and Bangkok metropolitan areas now source professional wax and pomade formats through manufacturer apps with 48-hour fulfillment. This channel disintermediation concentrates most visibly in South Korea's K-beauty corridor, where salon visit frequency and product turnover velocity reward inventory-light, data-rich restocking models over quarterly distributor orders.
Asia Pacific Hair Styling Products Market Segmentation
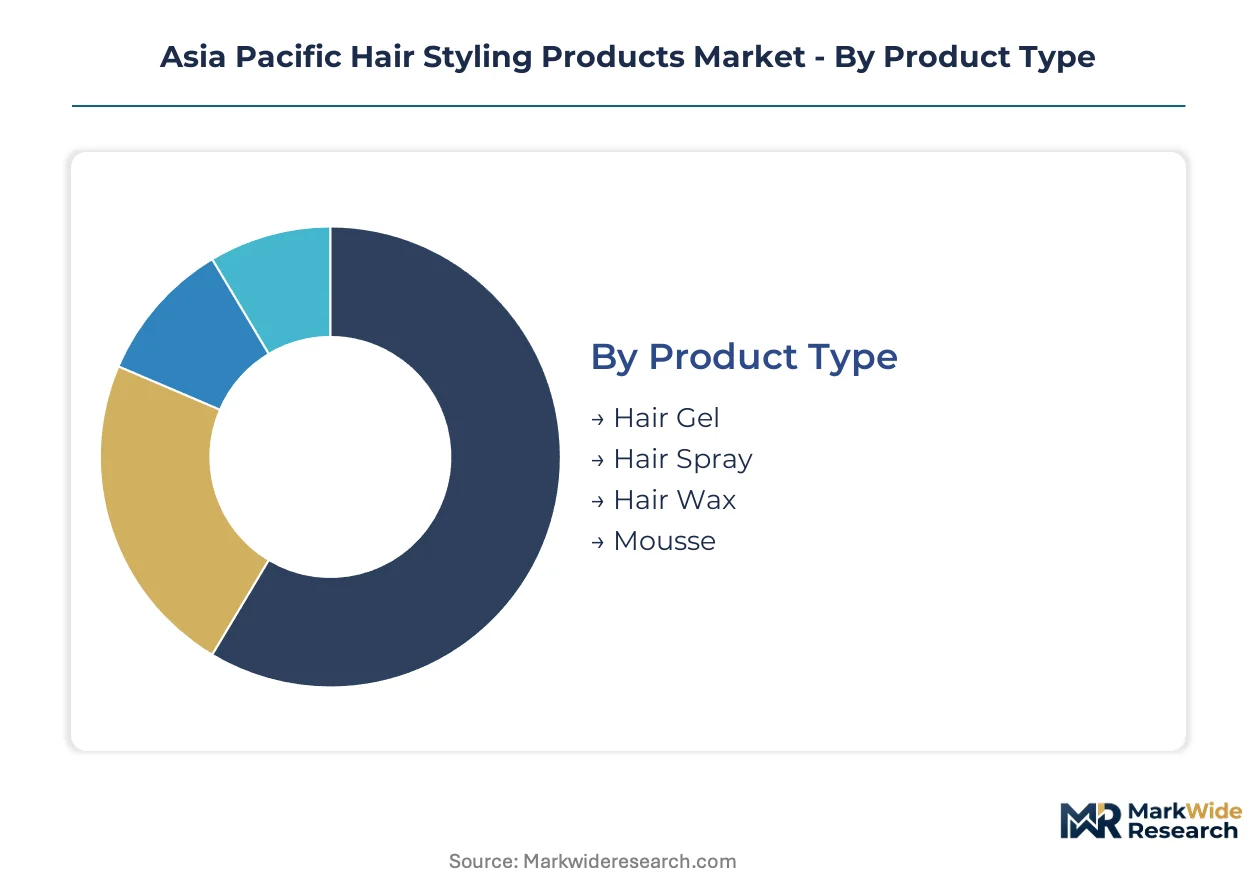
Segmentation in the Asia Pacific hair styling products market reveals distinct channel preferences and formulation requirements that shape procurement patterns across professional and consumer tiers. Understanding these divides enables targeted positioning for humidity-resistant hold factors and clean-label certifications.
Product Type:
Channel flow varies sharply by format, with professional salons favoring high-margin waxes and pomades while mass retail channels push aerosol volumes through automated replenishment systems.
- Hair Gel:Water-soluble polymer bases deliver medium-hold styling with flake-free drying characteristics. Demand clusters in South Korea's Seoul metropolitan corridor where K-beauty routines drive frequent application cycles and premium pricing tolerance.
- Hair Spray:Vinyl acetate copolymer formulations with hydrocarbon propellants achieve 8-72 hour humidity resistance. Professional salons across Tokyo and Osaka absorb premium positioning for salon-exclusive lines with extended hold factors.
- Hair Wax:Matte-finish pomades target male grooming segments in Japan and South Korea with concentrated margin pools.
- Mousse:Lightweight volumizing properties suit humid Southeast Asian climates, expanding most quickly through Indonesian and Vietnamese professional channels.
Hair spray dominates installed base through mass-market aerosol manufacturing networks. Mousse is where expansion concentrates as water-based alternatives displace traditional propellant formats.
End User:
Cost tier differentiation separates premium professional lines from economy retail positioning, with procurement authority fragmenting toward direct digital platforms in metropolitan clusters.
- Professional Salons:Salon-exclusive product lines command premium hold-factor claims and extended performance warranties. Stylists in Bangkok and Ho Chi Minh City metropolitan areas source through manufacturer-direct apps with 48-hour fulfillment cycles.
- Individual Consumers:Mass-market aerosol and gel formats dominate household purchasing through convenience retail and e-commerce platforms. Price sensitivity concentrates in tier-two Chinese cities where GB standards compliance elevates base cost structures.
- Retail Chains:Automated replenishment systems drive volume throughput for standardized hold-and-shine formulations.
- Cosmetology Schools:Training-volume contracts favor mid-tier conditioning and texturizing products with educational support materials.
Individual consumers represent the deepest installed base through retail chain penetration. Professional salons are where margin expansion concentrates as digital procurement disintermediates traditional distributors.
Application:
Functional specialization aligns with regulatory classification complexity, where anti-hair-loss claims trigger quasi-drug pathways in Japan versus functional cosmetics routes in South Korea.
- Styling:Primary hold-and-shape functions utilize film-forming polymers with variable drying speeds. Seoul's K-beauty corridor drives rapid product turnover for styling innovations with visual finish differentiation.
- Fixing:Extended hold factors from 24-72 hours require humidity-resistant polymer selection. Professional demand concentrates in Osaka and Tokyo where salon visit frequency supports premium positioning.
- Conditioning:Dual-function formulations merge styling control with hair health claims.
- Texturizing:Volume and separation effects target matte-finish male grooming routines.
Styling commands the broadest installed base across consumer and professional tiers. Fixing applications are where premium pricing concentrates as hold-factor performance claims justify formulation investment.
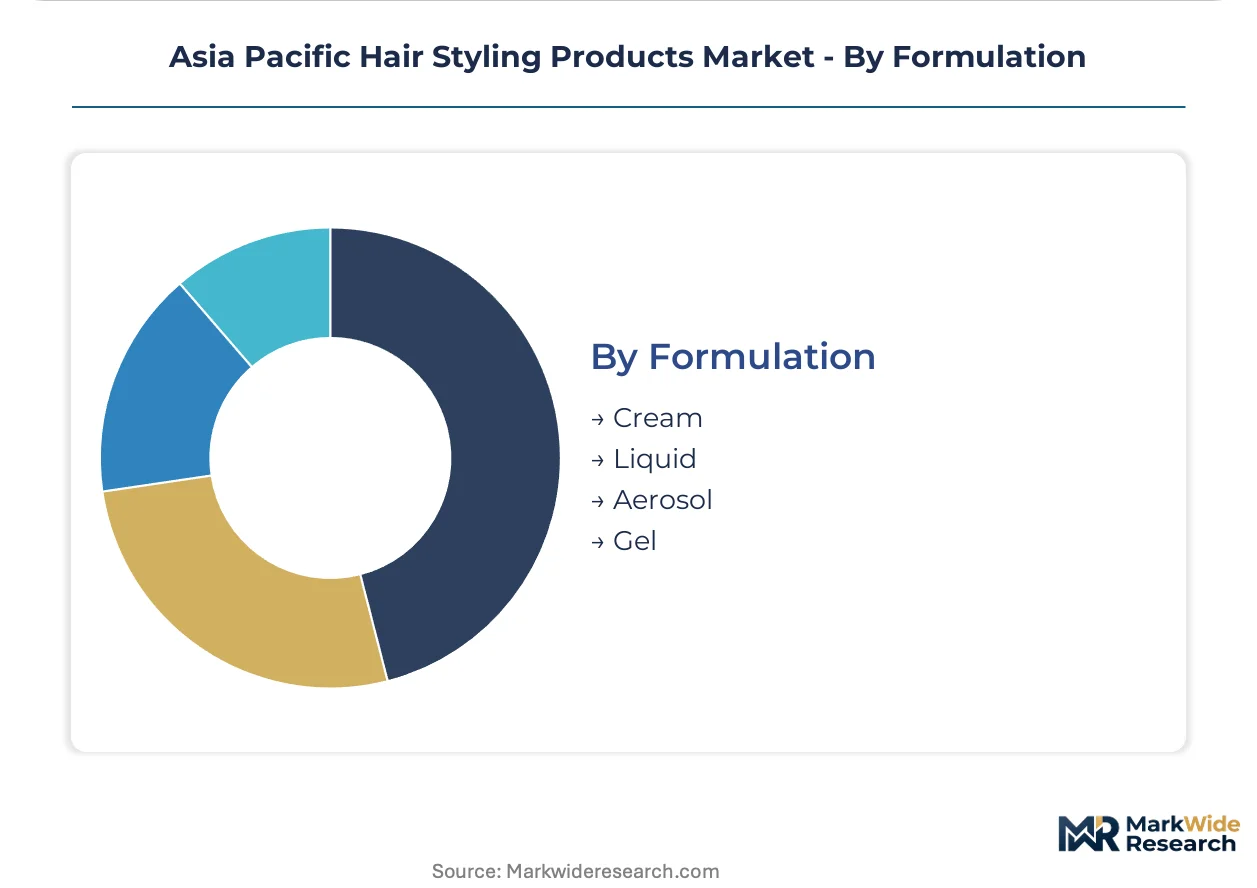
Formulation:
Supply concentration for biodegradable alternatives is reorganizing competitive access, with plant-derived chitosan and pullulan feedstocks favoring integrated R&D operators over import-reliant distributors.
- Cream:Emulsion-based delivery systems provide conditioning-styling hybrids with controlled spreadability. Japanese professional salons absorb reformulation costs for ISO 16128 clean-label certifications.
- Liquid:Water-soluble bases enable spray application with fast-drying characteristics. Southeast Asian humidity drives demand for lightweight liquid alternatives to heavy cream formats.
- Aerosol:Hydrocarbon propellant systems face volatile organic compound restrictions under China's SAMR registration barriers.
- Gel:Thickened aqueous bases deliver precise application control with alcohol-free drying.
Aerosol retains the largest installed base through established manufacturing infrastructure. Cream formulations are where clean-label substitution concentrates as biodegradable polymers displace petrochemical hold agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Ministry of Health, Labour and Welfare maintains strict ingredient disclosure rules that push brands toward cleaner formulations. South Korea's MFDS enforces functional cosmetics approval pathways. China's SAMR creates registration barriers for aerosol-based products containing volatile organic compounds.
Japan
Professional salons across Tokyo and Osaka metropolitan corridors absorb premium positioning for salon-exclusive styling lines. The Ministry of Health, Labour and Welfare expanded quasi-drug classification requirements for anti-hair-loss claims, forcing 12-18 month registration extensions. Kao Corp. anchors volume through mass-market aerosol manufacturing networks spanning Japan and Thailand.
South Korea
Seoul metropolitan corridor demand concentrates where K-beauty trends drive frequent product turnover and salon visits. MFDS approval frameworks for anti-hair-loss styling claims enable premium positioning for quasi-drug positioned treatments. Amorepacific Corp. leverages integrated R&D campuses to fast-track clean-label certifications.
China
GB standards for cosmetics labeling and volatile organic compound restrictions create extended approval timelines for aerosol-based entrants. SAMR registration barriers compress margin stability for hold-factor formulations. Tier-two cities exhibit price sensitivity where compliance elevates base cost structures.
Indonesia
Lightweight volumizing mousse applications expand most quickly through professional salon channels. Humid climate suitability drives water-based formulation substitution away from traditional propellant formats. Jakarta and Surabaya metropolitan stylists source through manufacturer-direct apps with 48-hour fulfillment cycles.
Vietnam
Ho Chi Minh City professional networks remain underdistributed for mousse applications despite humid climate suitability. Lightweight volumizing properties suit Southeast Asian conditions. Salon procurement patterns fragment toward brand-direct digital platforms that bypass traditional beauty distributor networks.
Asia Pacific Hair Styling Products Market Competitive Environment
Player mix skews toward integrated R&D operators with captive manufacturing infrastructure and clean-label certification capabilities. Mid-tier import-reliant distributors face margin compression from reformulation investments. Three archetypes dominate: multinational conglomerates with salon-exclusive professional lines, mass-market aerosol manufacturers with regional production hubs, and K-beauty specialists with rapid trend-to-shelf velocity. Competitive moves concentrate on strategic partnerships with biotech feedstock producers and direct-to-stylist digital procurement platforms.
Within the integrated R&D tier, Amorepacific Corp. and Kao Corp. exemplify divergent scale strategies. Amorepacific occupies a position anchored in Seoul metropolitan corridor demand density, representing the K-beauty velocity archetype with fast-track certification capabilities. Kao Corp. sits within the mass-market manufacturing archetype, exemplifying hydrocarbon propellant supply security across Japan-Thailand production networks. Shiseido Co. Ltd. represents the salon-exclusive premium positioning archetype, anchoring professional line differentiation in Tokyo and Osaka metropolitan clusters.
| Leading Market Players |
|---|
| Mandom Corp. |
| Arimino Co. Ltd. |
| Amorepacific Corp. |
| Beiersdorf AG |
| Nature Republic |
| Kao Corp. |
| Kose Corp. |
| Henkel AG and Co. KGaA |
| Shiseido Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Forty-eight-hour fulfillment cycles for salon-direct digital procurement concentrate pricing power with integrated manufacturers in Tokyo and Osaka metropolitan corridors, compressing distributor margins while elevating brand-direct premium capture across the Asia Pacific hair styling products sector.
Pricing Analysis
Cost-plus contracts indexed to vinyl acetate copolymer feedstock bands dominate procurement between Japanese aerosol manufacturers and Southeast Asian salon distributors. Three-tier pricing structure across premium, standard, and economy levels separates ISO 16128-certified salon-exclusive lines from mass-market hold-and-shine formulations. Pricing pressure stems from water-based mousse substitution in Indonesian and Vietnamese professional channels. Individual consumers in China's tier-two cities exhibit highest price sensitivity where SAMR compliance elevates base cost structures, while Tokyo stylists absorb premium positioning for extended hold-factor claims.
Supply Chain Analysis
Japan and South Korea anchor film-forming polymer production, with Thai manufacturing hubs handling hydrocarbon propellant filling operations for Southeast Asian distribution. Supply draws from petrochemical feedstocks and plant-derived chitosan feedstocks in parallel certification tiers. Single-source vulnerability concentrates in South Korean R&D campuses where clean-label polymer expertise pools. Distribution runs through manufacturer-direct digital platforms disintermediating traditional beauty distributor networks in Seoul and Bangkok metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment, where Japan's quasi-drug classification and South Korea's functional cosmetics pathway create twelve-to-eighteen-month approval barriers that protect incumbent positioning.
For Market Incumbents: Fortify salon-exclusive line differentiation through captive R&D campus expansion in South Korea, neutralizing formulation chemist scarcity that constrains regional competitor scaling. Deepen backward integration into plant-derived chitosan feedstock partnerships with Korean biotech producers, securing clean-label polymer supply security against vinyl acetate copolymer input volatility. Lock in 48-hour fulfillment infrastructure across Tokyo and Osaka metropolitan corridors to preempt digital procurement fragmentation. For New Entrants and Emerging Players: ISO 16128 fast-track certification pathways in South Korea offer the most penetrable entry vector for clean-label positioning against import-reliant distributors. Target Ho Chi Minh City professional salon networks where mousse applications remain underdistributed despite humid climate suitability. Deploy direct-to-stylist digital procurement platforms bypassing traditional beauty distributor markups, mirroring Seoul corridor inventory-light restocking models. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates divesting non-core mass-market aerosol portfolios amid water-based formulation substitution pressures. Five-to-ten-year viability hinges on clean-label certification capabilities and integrated R&D infrastructure rather than brand equity alone. Monitor MFDS approval velocity for anti-hair-loss functional cosmetics as inflection indicator for premium positioning sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Fast-Track | MFDS and ISO 16128 pathways in South Korea compress competitor entry timelines against import-reliant distributors. |
| Backward Integration into Biotech Feedstocks | Chitosan and pullulan partnerships with Korean producers secure biodegradable polymer supply against petrochemical volatility. |
| Direct-to-Stylist Digital Platform Launch | Manufacturer-direct apps with 48-hour fulfillment disintermediate traditional distributor networks in Bangkok and Ho Chi Minh City. |
| Salon-Exclusive Professional Line Extension | Quasi-drug positioning in Tokyo and Osaka metropolitan corridors captures premium hold-factor pricing. |
| Mousse Format Manufacturing Scale-Up | Water-based volumizing production in Indonesia and Vietnam addresses humid climate substitution away from aerosol formats. |
Study Parameters
Initial hypotheses were tested against primary input from formulation chemists at integrated R&D campuses, procurement managers at professional salon chains, regulatory affairs specialists navigating MFDS and SAMR pathways, and distribution channel partners across Southeast Asian beauty networks, then refined through secondary validation against customs records, cosmetics registration databases, and industry association technical reports, with bottom-up volume modeling triangulated against top-down market sizing.
Variance decomposition across the projection horizon isolates segment-level growth contributions from product format shifts, regulatory approval timelines, and channel migration patterns. Segmentation dimensions span formulation type, end-user tier, application function, and regional regulatory cluster. CAGRs derive from installed base erosion rates for aerosol formats and adoption curves for water-based alternatives, with humidity-indexed demand density and salon visit frequency serving as industry-specific forecast inputs.
Underlying assumptions cover regulatory pathway stability, feedstock price band persistence, and digital procurement adoption velocity, with deviation risk concentrated in SAMR registration timeline extensions and vinyl acetate copolymer supply disruptions. Recalibration cycles align with material shifts in clean-label certification mandates and quasi-drug classification expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Asia-Pacific Shampoo Market
Hair Care
China Hair Care Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Hair Mask Market
Hair Care
Argentina Hair Care Market
Hair Care
Brazil Hair Care Market
Hair Care
Russia Hair Care Market
Hair Care
Asia Pacific Hair Care Market
Hair Care
Global Shampoo Market
Hair Care
Europe Hair Care Market
Hair Care
Hair Tonic Market
Hair Care
South Korea Hair Care Market
Hair Care
Italy Hair Care Market
Hair Care
Hair Spray Market
Hair Care
Canada Hair Care Market
Hair Care
France Haircare Market