
 Hair Relaxer Market | 2026-2036
Hair Relaxer Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Relaxer Market Outlook
Licensed cosmetologist availability in North America is collapsing, forcing manufacturers to reformulate toward at-home application protocols. L'Oréal SA dominates professional-grade chemical relaxer distribution through salon-exclusive channels. Procter & Gamble Co competes in mass retail with simplified no-lye systems designed for consumer self-application. Croda International Plc anchors ingredient supply for formaldehyde-free alternatives across multiple brand portfolios.
A hair relaxer is a cosmetic treatment product that chemically or physically alters the disulfide bonds within keratin structures to reduce curl pattern, typically formulated with alkaline agents such as sodium hydroxide, guanidine hydroxide, or ammonium thioglycolate at pH levels between 10 and 14. Cream formulations sustain the largest revenue share due to controlled application precision and reduced scalp irritation risk versus liquid alternatives. Chemical technology leads absolute volume despite regulatory pressure, while herbal and natural segments represent the fastest-growing margin pools as clean-label positioning commands premium shelf placement. Thermal technology occupies a narrow niche concentrated in professional salon environments where equipment-assisted straightening protocols justify higher service pricing.
The FDA monitors adverse event reporting for chemical hair relaxers, particularly regarding formaldehyde-releasing preservatives, while the EPA governs manufacturing facility emissions for volatile organic compounds. REACH compliance in Europe has eliminated several long-chain parabens and formaldehyde donors from import-eligible formulations, compressing the approved ingredient universe. California's Proposition 65 labeling requirements for reproductive toxicants now extend to retail hair relaxer packaging, creating state-specific compliance layers. Stakeholders must monitor evolving class-action litigation linking chronic relaxer exposure to endocrine disruption, as judicial outcomes could force wholesale reformulation investments or channel restrictions regardless of regulatory timelines.
Market Dynamics
Licensed cosmetologist availability in North America is collapsing, forcing manufacturers to abandon salon-dependent distribution and reformulate toward at-home application protocols with simplified no-lye systems.
Growth Catalysts
- REACH chemical restrictions:ECHA's elimination of formaldehyde donors and long-chain parabens from import-eligible formulations is accelerating clean-label innovation across European supply chains.
- Brazilian middle-income cohorts:Textured hair care spending has intensified among this demographic, creating concentrated demand pull for premium formaldehyde-free alternatives.
- Professional salon channel:Formaldehyde-free formulations are expanding fastest through this end-use segment in the United States as service providers seek liability protection.
Market Restraints
- Sodium hydroxide supply volatility:Caustic soda price swings and energy-intensive production constraints in China compress margins for lye-based relaxer manufacturers.
- Ingredient universe compression:California Proposition 65 labeling mandates for reproductive toxicants create state-specific compliance layers that fragment national distribution.
- Natural substitute threat:Thermal straightening devices and keratin treatment systems are capturing professional salon service revenue previously locked to chemical relaxers.
Strategic Opportunities
- At-home application protocols:Licensed cosmetologist shortages create white space for simplified no-lye systems with consumer-directed instructions and reduced scalp irritation risk.
- Herbal segment premiumization:Clean-label positioning commands preferred shelf placement as retailers respond to FDA adverse event monitoring pressure on formaldehyde-releasing preservatives.
- EPA manufacturing compliance services:Volatile organic compound emission governance creates ancillary revenue streams for formulation houses assisting brands with facility-level regulatory adherence.
Industry Challenges
- Licensed practitioner scarcity:Professional salon application protocols require trained cosmetologists, and workforce attrition is forcing channel migration before at-home infrastructure matures.
- Class-action litigation exposure:Judicial proceedings linking chronic relaxer exposure to endocrine disruption threaten wholesale reformulation investments regardless of regulatory timelines.
- Multi-jurisdiction certification burden:Separate FDA, EPA, REACH, and state-level compliance pathways extend product launch timelines and concentrate development resources on regulatory navigation rather than innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Relaxer Market |
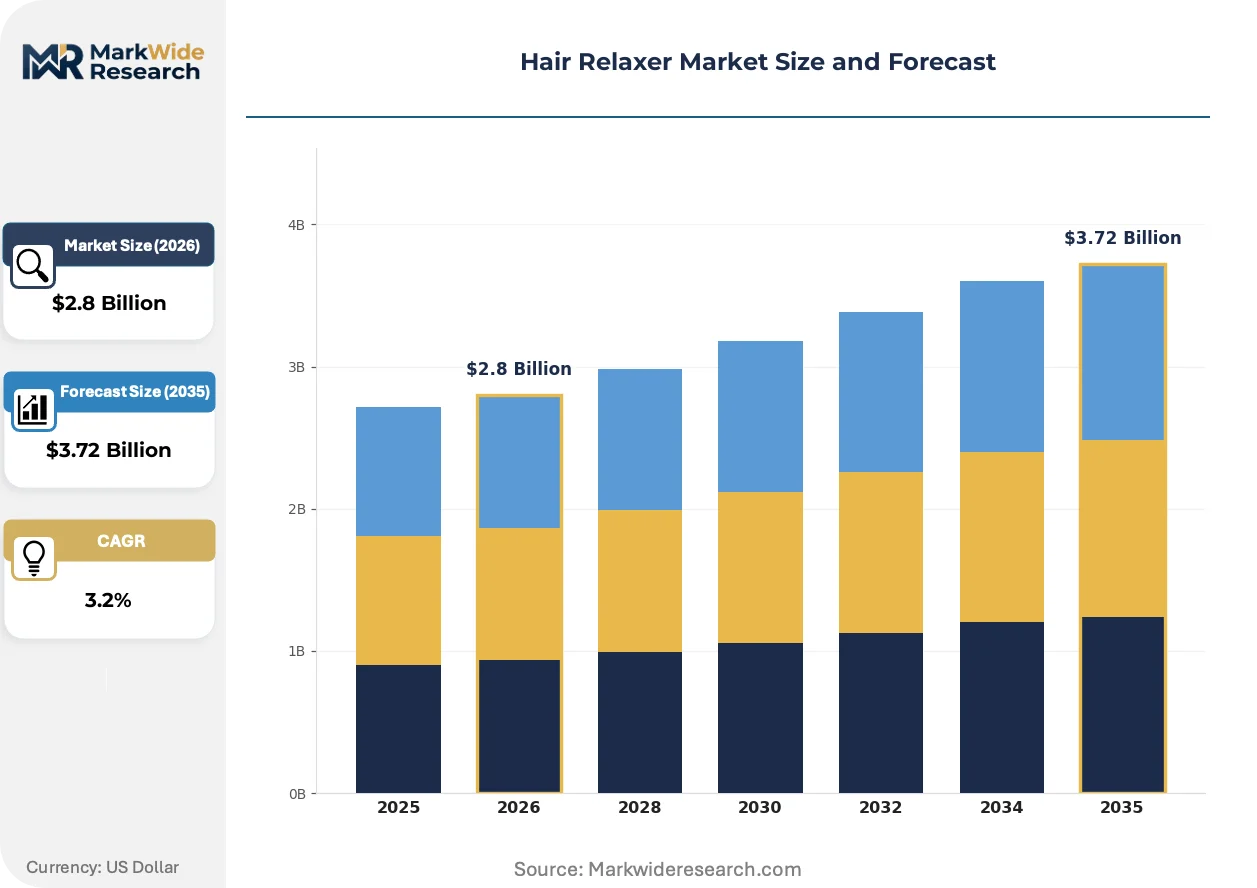
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Lotion, Spray, Gel Technology: Chemical, Herbal, Natural, Thermal End User: Salons, Beauty Professionals, Individual Consumers, Retail Chains Application: Hair Smoothing, Frizz Control, Curl Relaxing, Straightening |
| Companies Covered | Henkel AG & Co. KGaA, Croda International Plc, L'Oréal SA, MacAndrews & Forbes Incorporated, Epitomi Inc, Procter & Gamble Co, Avlon Industries Inc., Jotoco Corp, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Relaxer Market Strategic Shifts
Formulation chemistry is diverging sharply between professional-grade alkaline systems and consumer-directed no-lye alternatives, with regulatory pressure and workforce constraints driving parallel development tracks.
Ammonium thioglycolate-based formulations are fragmenting the traditional sodium hydroxide market by offering reduced scalp irritation and simplified neutralization protocols. Mass retail buyers are adopting these systems rapidly as shelf-space allocation shifts toward self-application products. The technology is fragmenting manufacturer R&D budgets between maintaining professional salon relationships and building direct-to-consumer infrastructure.
REACH restrictions on hazardous chemicals continue compressing permissible ingredient lists across all import-eligible formulations. ECHA's elimination of formaldehyde donors and specific paraben classes forces reformulation investments that favor larger manufacturers with dedicated regulatory affairs capacity. European import compliance now requires extensive substance safety dossiers that smaller regional formulators struggle to assemble.
Buyer concentration in mass retail channels is consolidating procurement leverage around clean-label certification requirements. Walmart and Target-tier buyers now mandate formaldehyde-free positioning as a condition of shelf access, displacing traditional chemical formulations regardless of performance metrics. This pattern is most visible in United States distribution, where retailer sustainability scorecards increasingly govern category management decisions.
Hair Relaxer Market Segmentation
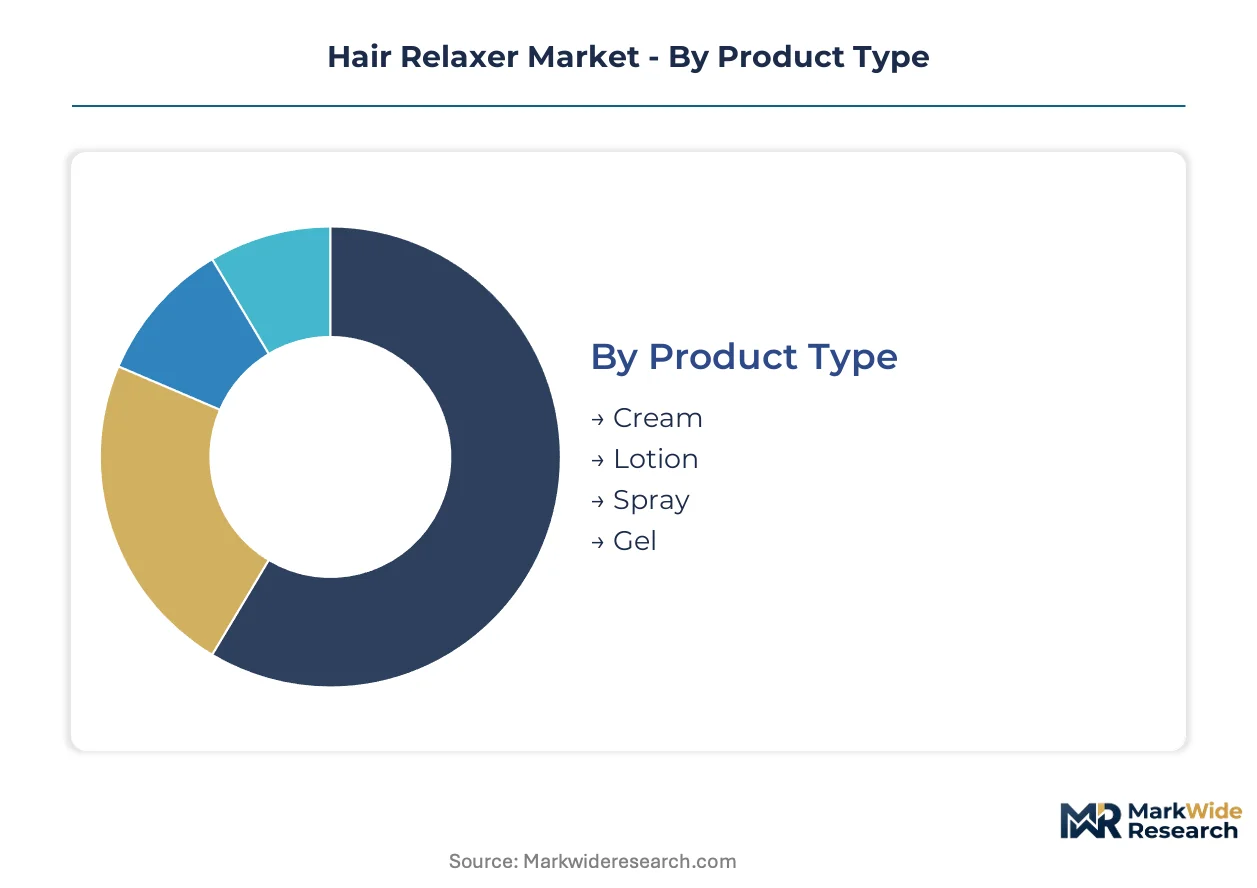
Hair relaxer segmentation reveals divergent supply chains across professional and consumer channels. Product form and technology choices determine whether formulations serve salon-dependent protocols or at-home self-application markets.
Product Type:
Cream and lotion formulations anchor domestic manufacturing capacity, while spray and gel variants increasingly serve export-oriented production lines seeking lighter freight economics.
- Cream:Viscous emulsion systems with controlled spreadability enable precise scalp sectioning during professional application. Demand concentrates in United States salon channels where service providers prioritize drip-free handling and reduced peripheral skin contact.
- Lotion:Lower viscosity enables pump-dispense packaging suited to consumer bathroom environments. Brazilian retail chains are expanding shelf allocation for lotion formats as middle-income households shift from salon dependency toward self-directed maintenance protocols.
- Spray:Aerosolized delivery systems target root-touchup applications between full treatments.
- Gel:Thixotropic formulations cling to coarse hair textures common in African-descended consumer populations.
Cream commands the established base. The steepest expansion runs through lotion formats.
Technology:
Cost tier stratification separates premium-positioned thermal and herbal systems from commodity chemical formulations, with margin structure determining R&D allocation across manufacturer portfolios.
- Chemical:Sodium hydroxide and guanidine hydroxide systems operate at pH 10-14 to cleave disulfide bonds within keratin structures. Volume concentrates in mass retail channels where Procter & Gamble and L'Oréal maintain brand equity through heritage alkaline formulations despite regulatory pressure.
- Herbal:Plant-derived active systems incorporating cassia, henna, or botanical extracts command premium shelf placement. European import demand is climbing fastest as ECHA REACH restrictions eliminate formaldehyde donors from competing chemical alternatives.
- Natural:Minimal-processing formulations with certified organic inputs target clean-label buyers.
- Thermal:Equipment-assisted straightening protocols require salon infrastructure and trained practitioner presence.
Chemical technology retains volume leadership. Herbal segments are gaining share fastest.
End User:
Customer type fragmentation mirrors workforce availability constraints, with licensed practitioner scarcity forcing channel migration before at-home infrastructure fully matures.
- Salons:Full-service establishments with licensed cosmetologist staff perform complete application and neutralization sequences. United States metropolitan markets concentrate demand here as liability concerns drive formaldehyde-free formulation adoption.
- Beauty Professionals:Independent contractors and mobile service providers require portable kit formats. Brazil's expanding middle-class neighborhoods are generating concentrated demand pull for professional-grade products distributed through beauty supply wholesalers.
- Individual Consumers:Self-directed buyers purchasing through drugstore and e-commerce channels.
- Retail Chains:Walmart and Target-tier buyers mandating clean-label certification as condition of shelf access.
Salon channels command the established base. The steepest expansion runs through individual consumers.
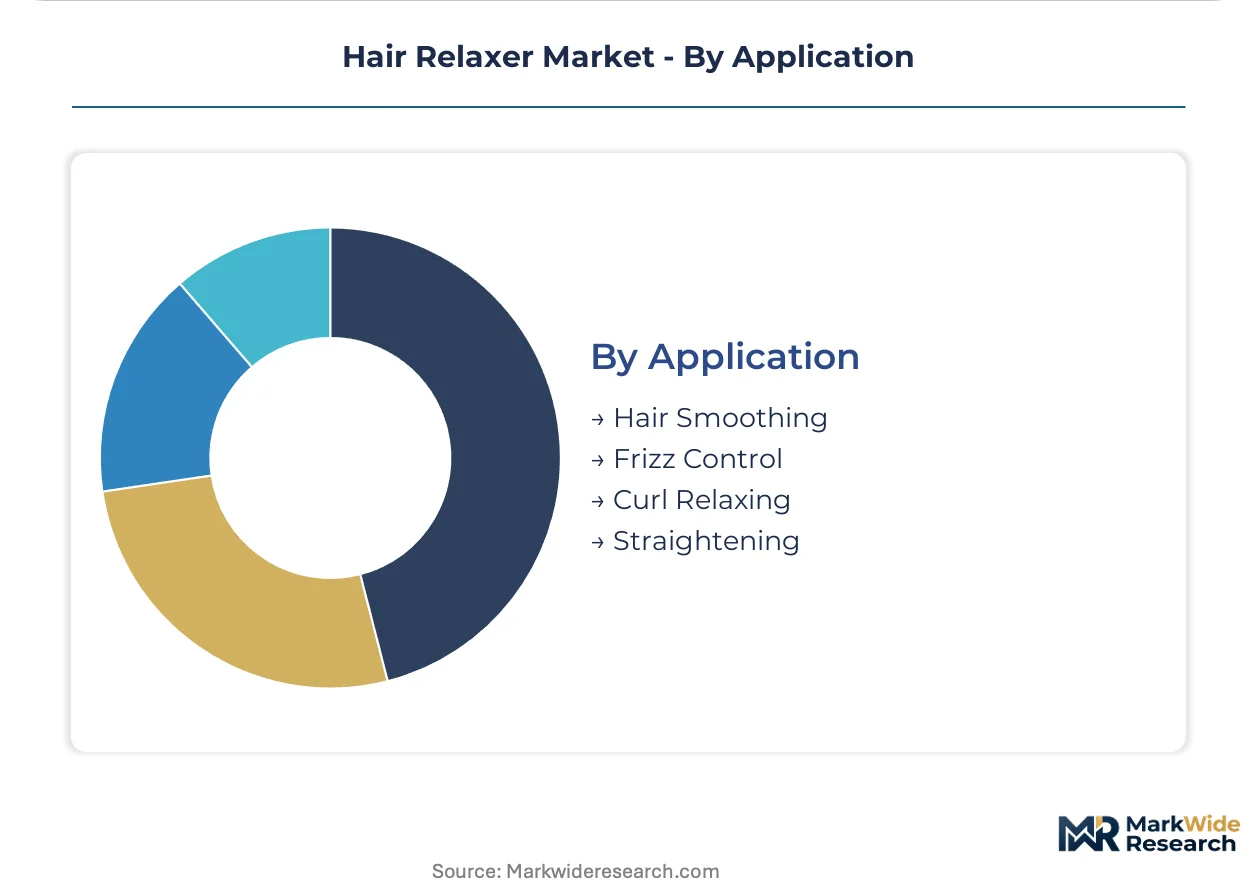
Application:
Application purpose determines formulation chemistry intensity, with straightening protocols requiring maximum bond disruption while smoothing treatments permit milder intervention.
- Straightening:Maximum curl reduction demands high-pH alkaline systems or ammonium thioglycolate at concentrations sufficient for complete disulfide bond reconfiguration. Professional salon channels in the United States concentrate demand for straightening outcomes.
- Hair Smoothing:Partial cuticle alignment without full bond cleavage suits consumers seeking texture management rather than elimination. Brazilian retail expansion is driving fastest volume growth for smoothing-focused formulations with reduced processing time.
- Frizz Control:Surface-level conditioning treatments with temporary effect duration.
- Curl Relaxing:Moderate bond reduction preserving some wave pattern.
Straightening applications command the established base. The steepest expansion runs through hair smoothing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with professional salon dependency collapsing in North America while at-home protocols surge, and Brazil's middle-income households driving premium formaldehyde-free demand through retail channels.
United States
Licensed cosmetologist shortages force rapid channel migration toward consumer self-application, with metropolitan salon clusters in Atlanta and Houston pivoting to formaldehyde-free formulations for liability protection. FDA adverse event monitoring on chemical preservatives tightens ingredient scrutiny. California's Proposition 65 labeling mandates for reproductive toxicants create state-specific compliance layers that fragment national distribution strategies.
Brazil
Middle-income consumer cohorts in São Paulo and Rio de Janeiro intensify textured hair care spending, pulling premium formaldehyde-free alternatives through beauty supply wholesalers. ANVISA maintains stricter cosmetic ingredient surveillance than regional peers, accelerating clean-label positioning. São Paulo's expanding suburban retail chains are reallocating shelf space toward lotion-format products suited to self-directed maintenance protocols.
Germany
Professional salon channels concentrate demand for ammonium thioglycolate systems as REACH compliance eliminates formaldehyde donors from import-eligible formulations. ECHA substance safety dossier requirements favor manufacturers with dedicated regulatory affairs capacity. The Rhine-Ruhr industrial corridor hosts formulation houses assisting brands with EPA-aligned volatile organic compound emission governance for export manufacturing.
South Africa
Beauty supply distributors in Johannesburg and Cape Town serve dual professional and retail channels as salon infrastructure remains uneven across income tiers. The country's national pharmaceutical regulator maintains cosmetic safety surveillance without REACH-equivalent chemical restrictions. Gauteng province's wholesale networks are expanding formaldehyde-free portfolio breadth to capture migrating demand from traditional lye-based systems.
United Kingdom
Post-BREXIT regulatory divergence complicates dual EU-UK compliance for manufacturers serving both markets through shared supply chains. The Medicines and Healthcare products Regulatory Agency enforces cosmetic safety standards with heightened attention to endocrine-disrupting chemical classes. Greater London's independent beauty professionals drive portable kit format demand as mobile service provision expands beyond fixed salon locations.
Hair Relaxer Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational consumer goods conglomerates controlling mass retail distribution while regional formulators capture professional salon loyalty. The upper tier commands shelf-space allocation through heritage brand equity and regulatory compliance infrastructure. Two strategic archetypes dominate: scale-driven mass-market suppliers with simplified no-lye systems, and premium-positioned professional-grade specialists with salon-exclusive channels. Competitive moves concentrate on portfolio diversification toward formaldehyde-free alternatives and backward integration into captive ingredient supply.
Within the integrated multinational tier, L'Oréal SA and Procter & Gamble Co exemplify divergent channel strategies, with the former anchoring professional salon distribution and the latter dominating mass retail self-application markets. Croda International Plc occupies a distinct position as an ingredient supplier archetype, enabling formaldehyde-free formulation transitions across multiple brand portfolios through specialized chemical supply relationships.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Croda International Plc |
| L'Oréal SA |
| MacAndrews & Forbes Incorporated |
| Epitomi Inc |
| Procter & Gamble Co |
| Avlon Industries Inc. |
| Jotoco Corp |
| Unilever PLC |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles for sodium hydroxide and guanidine hydroxide precursors concentrate cost volatility exposure among lye-based relaxer manufacturers, compressing margin buffers when caustic soda prices spike and amplifying pricing power for formaldehyde-free formulators with captive ingredient supply.
Pricing Analysis
Contract-based long-term offtake agreements dominate professional salon channel procurement, while mass retail buyers operate on spot-market terms with quarterly renegotiation. Price differentiation hinges on REACH certification tier and brand heritage equity, with European import-eligible formulations commanding premium shelf placement. Pricing pressure stems from sodium hydroxide supply volatility in China, eroding margins for commodity alkaline systems. Individual consumers exhibit highest price sensitivity, whereas United States metropolitan salons prioritize liability protection over unit cost.
Supply Chain Analysis
Caustic soda production concentration in China's Shandong and Jiangsu provinces creates single-source vulnerability for lye-based relaxer manufacturers dependent on energy-intensive chlor-alkali output. Raw material dependencies center on sodium hydroxide, guanidine carbonate, and ammonium thioglycolate intermediates. Supply chain risk manifests in tariff exposure on Chinese chemical imports and logistics chokepoints through Shanghai-Ningbo port clusters. Distribution runs through beauty supply wholesalers serving professional channels and mass retail buyers controlling shelf access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical restrictions and licensed cosmetologist scarcity are forcing simultaneous channel migration and formulation reinvention, creating compressed windows for competitive repositioning before at-home infrastructure matures.
For Market Incumbents: Consolidate regulatory affairs capacity to navigate multi-jurisdiction certification burdens, securing ECHA dossier completion ahead of smaller competitors. Deepen backward integration into formaldehyde-free active ingredient supply through captive relationships with Croda International Plc-tier suppliers. Channel control through salon-exclusive distribution must adapt to workforce attrition by building direct-to-consumer fulfillment infrastructure.
For New Entrants and Emerging Players: Mobile service provision for independent beauty professionals represents an under-served layer where incumbents maintain weak coverage, particularly in Brazil's expanding suburban retail corridors. Target lotion-format self-application products through Brazilian beauty supply wholesalers as the most penetrable geography-application combination. Go-to-market execution should emphasize ANVISA-compliant clean-label certification to differentiate from heritage alkaline formulations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across herbal and natural formulation segments as clean-label R&D and organic input sourcing require sustained investment. Long-term viability favors manufacturers with dual professional-consumer channel capability and dedicated regulatory affairs infrastructure. Acquisition targets should demonstrate EPA manufacturing compliance services revenue or REACH-aligned formulation portfolios. The signal to watch is class-action litigation progression linking chronic relaxer exposure to endocrine disruption, which could force wholesale channel restrictions regardless of regulatory timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Formaldehyde-Free Formulation Transition | ECHA REACH restrictions eliminate competing chemical alternatives from European import eligibility. |
| At-Home Application Protocol Development | Licensed cosmetologist shortages in North America force channel migration toward consumer self-application. |
| Backward Integration into Ingredient Supply | Croda International Plc anchors formaldehyde-free active supply for multiple brand portfolios. |
| Beauty Supply Wholesaler Partnership Expansion | Brazilian middle-income cohorts intensify textured hair care spending through retail channels. |
| Multi-Jurisdiction Regulatory Certification Investment | California Proposition 65 labeling mandates create state-specific compliance layers fragmenting national distribution. |
Study Parameters
A standing panel of formulation chemists, beauty supply distribution managers, licensed cosmetologists, and ANVISA regulatory consultants provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA adverse event reporting databases, ECHA substance safety dossiers, customs records tracking sodium hydroxide import flows, and SEC 10-K disclosures from L'Oréal SA and Procter & Gamble Co. Bottom-up volume modeling triangulated against top-down category spend estimates from Nielsen retail audit data.
Consistency checks validated volume and value outputs against external benchmarks including historical CAGRs and cross-segment elasticity patterns. The analytical framework segmented by product form, technology type, end-user channel, and application purpose across the projection horizon. CAGRs were derived from regression analysis of historical consumption trends and forward-looking regulatory impact assessments. Industry-specific forecast inputs included caustic soda price indices and licensed practitioner workforce statistics from state cosmetology boards.
Underlying assumptions cover REACH compliance timelines and sodium hydroxide supply stability, with deviation risk concentrated in class-action litigation outcomes and ANVISA regulatory tightening. Practitioners should keep alternative scenarios live as ECHA substance restrictions and California labeling mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Dye Market
Hair Care
Israel Hair Care Market
Hair Care
Global Premium Hair Care Market
Hair Care
Asia Pacific Hair Styling Products Market
Hair Care
Asia Pacific Hair Care Market
Hair Care
Anti-Pollution Hair Care Market
Hair Care
Australia Hair Care Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
Chile Hair Care Market
Hair Care
Argentina Hair Care Market
Hair Care
Hair Care Products Market
Hair Care
Germany Hair Care Market
Hair Care
Global Hair Color Market
Hair Care
Italy Hair Care Market
Hair Care
South Africa Hair Care Market
Hair Care
Hair Serum Market