
 Hair Bond Multiplier Market | 2026-2036
Hair Bond Multiplier Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Bond Multiplier Market Analysis
Cysteine-based actives are repositioning bond-multiplier formulations away from formaldehyde-releasing chemistries. Olaplex Holdings Inc. leverages its patent estate on bis-aminopropyl diglycol dimaleate to sustain premium pricing across professional channels. L'Oréal SA anchors mass-market penetration through salon-exclusive distribution under its Redken and Schwarzkopf Professional banners. Croda International Plc competes as a specialty-ingredient supplier, extending its reach into hybrid natural-synthetic bond builders for third-party brands.
Hair bond multipliers are topical cosmetic treatments containing reactive molecules that seek out and reform disulfide bonds in keratin fibers, typically applied at concentrations between 5-15% active during or after chemical processing to prevent structural degradation. These products function by penetrating the cortex and cross-linking broken cysteine residues, restoring tensile strength and elasticity to chemically stressed hair. Liquid formulations dominate professional salon application due to rapid absorption and precise dosing control, while cream-based retail products are gaining traction in home-use segments as consumers seek maintenance between salon visits. Ingredient-source segmentation shows hybrid natural-synthetic compositions leading margin pools, combining bio-fermented actives with lab-stabilized bond-repair molecules to satisfy both efficacy and clean-beauty positioning.
Cosmetic ingredient oversight from the FDA in the United States and the EU's REACH framework jointly shape product safety substantiation requirements, with both jurisdictions tightening scrutiny on novel synthetic actives entering topical applications. The EU's MDR-adjacent cosmetic regulation and state-level clean-beauty legislation in California are forcing reformulation timelines for brands reliant on legacy preservative systems. Stakeholders must monitor evolving perfluorinated-compound restrictions and biotech-fermentation certification standards as these will determine which bond-repair chemistries retain market access.
Market Dynamics
The Hair Bond Multiplier Market pivots on a single structural force: the collision between professional salon demand for damage-prevention protocols and tightening EU REACH disclosure requirements on synthetic actives, forcing simultaneous innovation in clean-label bond chemistries and supply-chain transparency.
Growth Catalysts
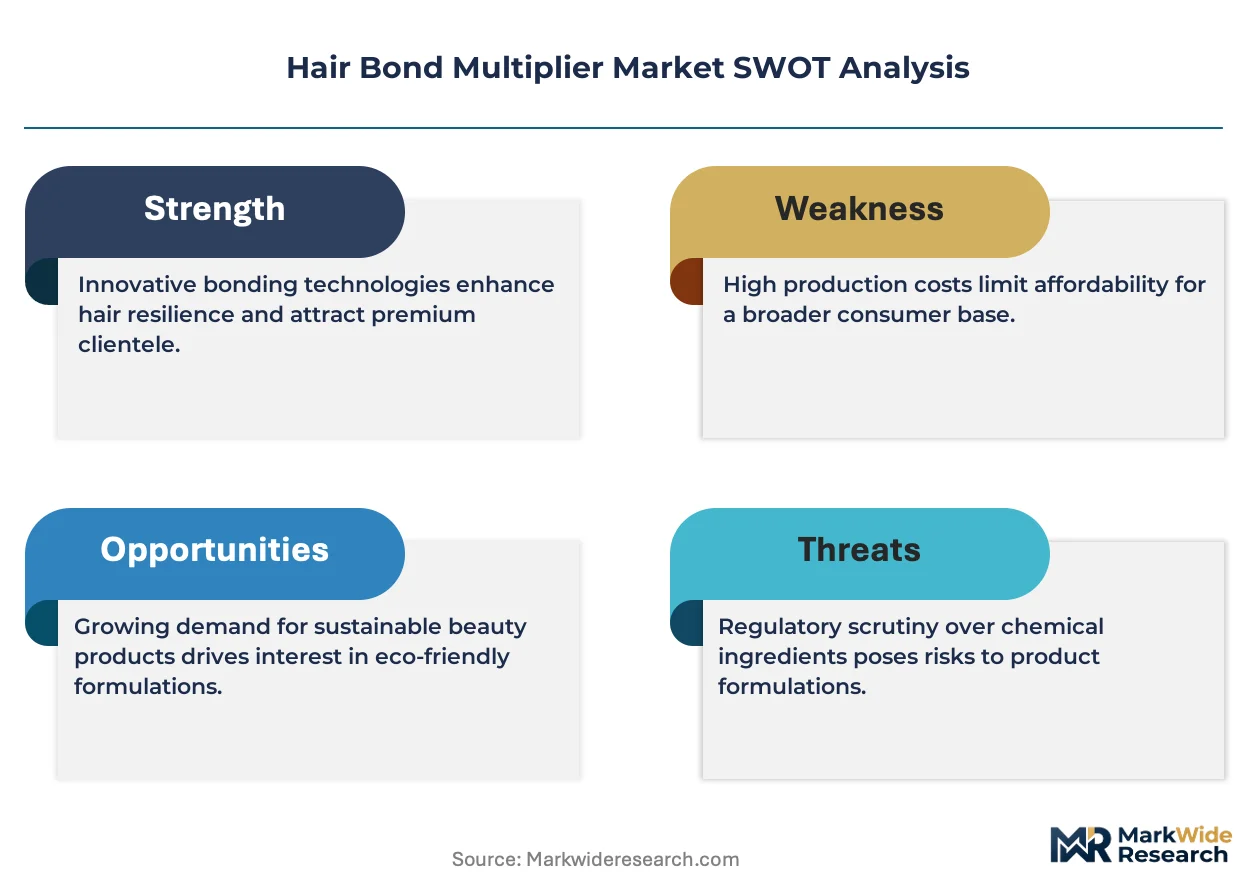
- Professional salon channel expansion:Stylists in the United States and Germany are standardizing bond-building treatments as mandatory pre- and post-coloring protocols, embedding these products into service workflows rather than optional add-ons.
- REACH compliance innovation:The EU's tightening cosmetic ingredient safety framework is accelerating reformulation investment toward cysteine-derived and bio-fermented actives that satisfy disclosure mandates while maintaining efficacy.
- Hybrid natural-synthetic chemistry:Advances in lab-stabilized bond-repair molecules combined with fermentation-derived inputs are opening premium positioning opportunities that command higher per-unit economics.
Market Restraints
- Specialty active ingredient concentration:Supply of pharmaceutical-grade bis-aminopropyl diglycol dimaleate and comparable bond-repair molecules concentrates among a handful of European and North American specialty chemical producers, creating procurement vulnerability.
- California clean-beauty legislative friction:State-level disclosure requirements under California's Safer Consumer Products regulations extend reformulation timelines and compliance costs for brands maintaining national distribution.
- Technical performance ceiling:Current bond-multiplier chemistries demonstrate diminished efficacy on severely compromised hair below 30% of original tensile strength, limiting addressable damage severity.
Strategic Opportunities
- At-home maintenance segment:Cream-based retail formulations for consumer self-application between salon visits represent underdeveloped white space, particularly in suburban United States markets where salon visit frequency lags urban centers.
- Biotech-fermentation certification standards:Early alignment with emerging ISO frameworks for bio-processed cosmetic actives creates first-mover positioning as clean-beauty preferences harden into purchasing requirements.
- Men's grooming channel integration:Barbershops and male-focused grooming chains present untapped distribution infrastructure for bond-repair treatments targeting chemical straightening and beard coloring services.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise spanning both keratin biochemistry and regulatory compliance is concentrating among senior specialists, constraining R&D velocity for mid-tier brands.
- Perfluorinated compound supply chain reconfiguration:Pending restrictions on PFAS in cosmetic applications force expedited supplier audits and raw material substitutions with compressed validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Bond Multiplier Market |
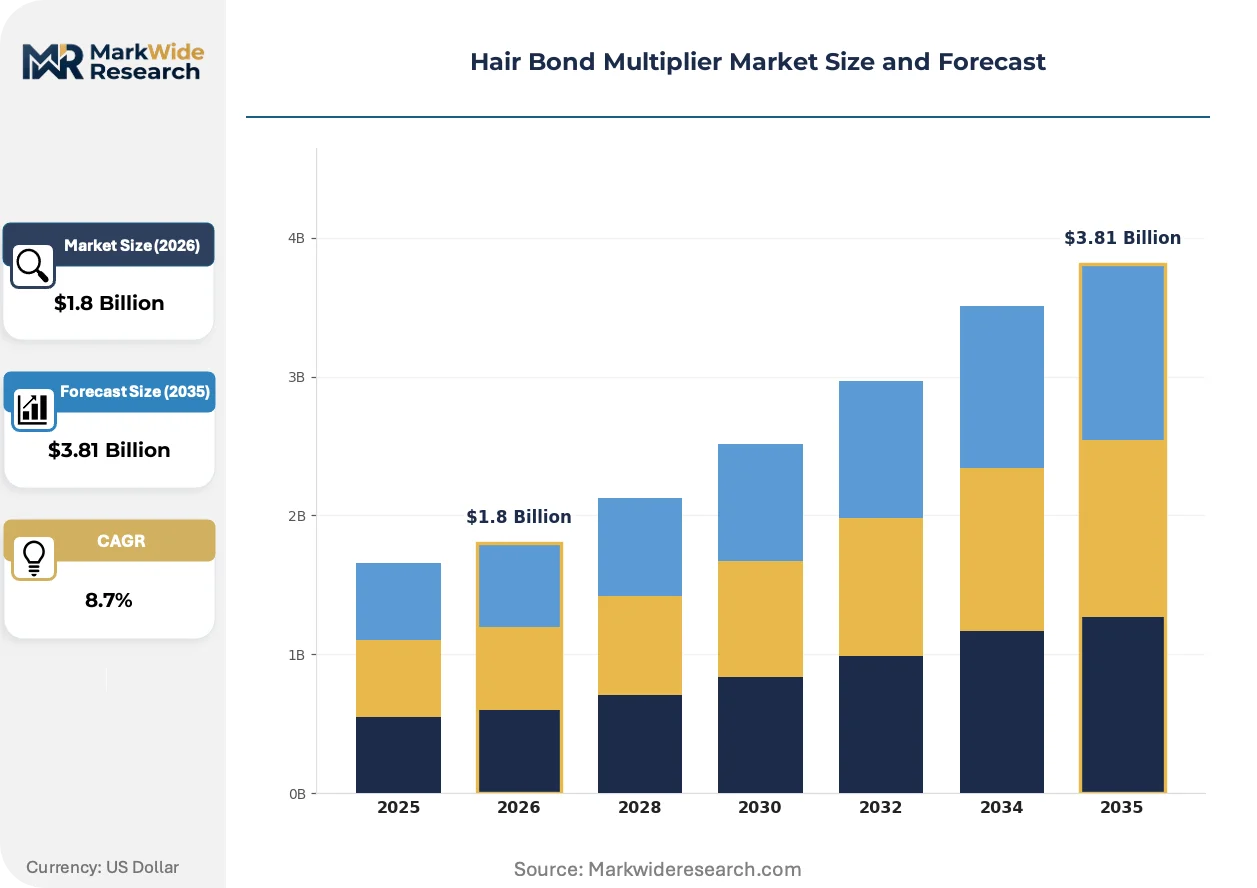
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Cream, Powder, Gel Application: Salon Use, Home Use, Professional Treatments, Retail Products Ingredient Source: Natural, Synthetic, Organic, Hybrid Target Hair Type: Curly, Straight, Wavy, Coarse |
| Companies Covered | Croda International Plc, Keune Haircosmetics, Olaplex Holdings Inc., Schwarzkopf Professional, Redken, LOréal SA, K18hair, ALTERNA, Henkel AG and Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Bond Multiplier Market Emerging Trajectories
Bio-fermented actives are displacing petroleum-derived bond-repair molecules as the dominant innovation vector, with regulatory pressure and consumer preference converging to reward transparency in ingredient sourcing and manufacturing processes.
Peptide-infused bond multipliers are expanding into professional salon protocols as stylists seek measurable tensile-strength recovery data to justify premium service pricing. High-frequency color clients in Los Angeles and New York metro markets are adopting these treatments at twice the rate of general salon populations. The technology is expanding into adjacent haircare categories, with bond-repair conditioners and leave-in treatments capturing shelf space previously occupied by silicone-heavy smoothing products.
REACH's 2023 extension of disclosure requirements for synthetic cosmetic actives is forcing ingredient suppliers to document full supply-chain provenance for bond-repair molecules. German and French formulators face the steepest compliance burdens, with dossier preparation costs filtering downstream to brand partners. Professional-only product lines are responding fastest, leveraging direct stylist education channels to communicate reformulation rationale without mass-market label confusion.
Subscription-based replenishment models are disrupting traditional retail purchasing for at-home bond-maintenance products. Direct-to-consumer brands are displacing salon-exclusive resale arrangements in secondary United States cities where stylist recommendation influence weakens. This behavioral shift concentrates most visibly among 25-34 year-old consumers in Texas and Florida markets, where digital-native purchasing patterns override professional-channel loyalty.
Hair Bond Multiplier Market Segmentation
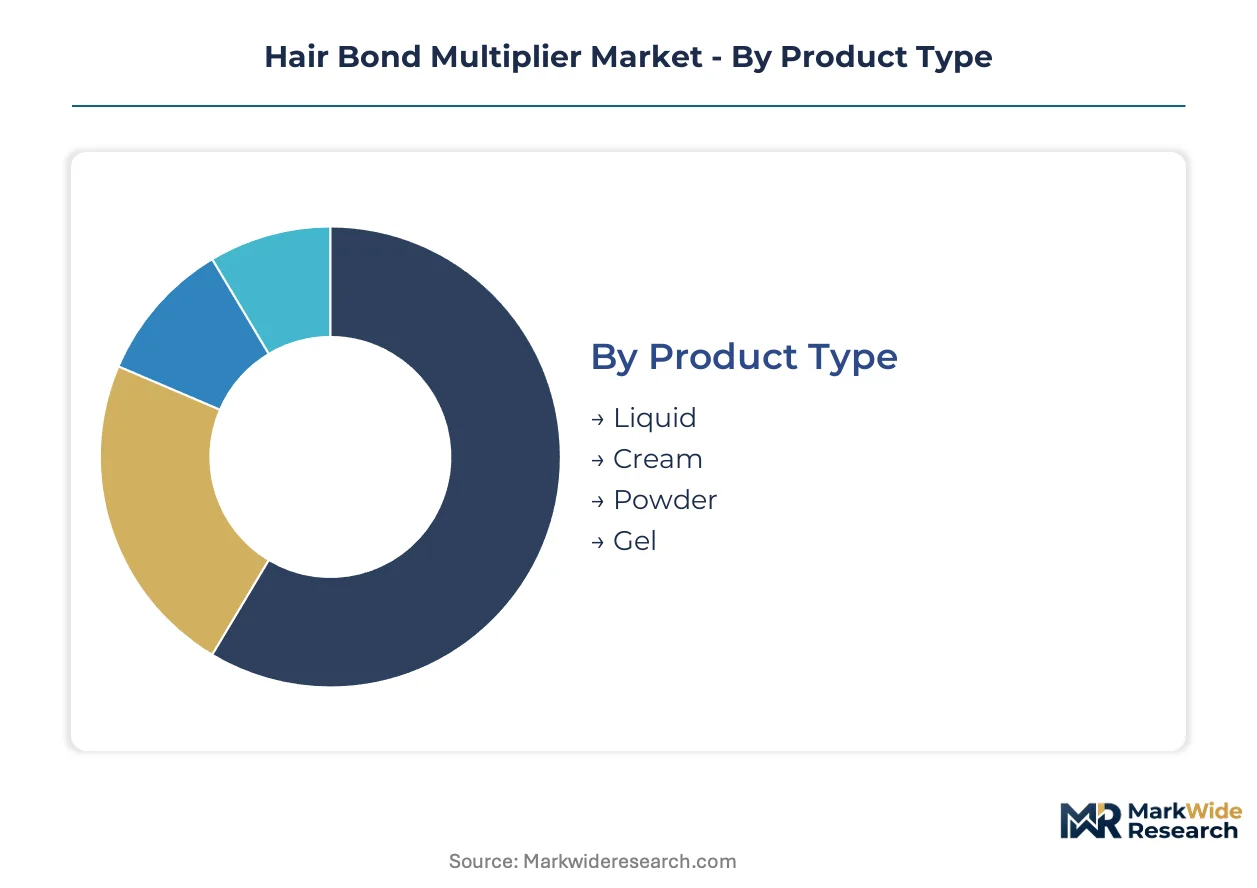
Hair bond multipliers fragment across formulation physics, application context, and ingredient provenance. Each axis shapes manufacturing investment, regulatory pathway, and channel economics differently. Understanding these divides reveals where margin pools concentrate and where new entrants face structural barriers.
Product Type:
Viscosity and delivery mechanism determine professional adoption velocity and consumer self-application feasibility.
- Liquid:Low-viscosity aqueous or alcoholic solutions penetrate the hair cortex rapidly, enabling precise dosing control during chemical processing. Demand concentrates in German and United States professional salons where stylists integrate bond-building as mandatory pre-color protocols. FDA cosmetic labeling requirements for volatile organic content shape formulation constraints for interstate distribution.
- Cream:Emulsion-based systems with higher substantivity to damaged cuticles support extended contact time for severely compromised hair. Growth concentrates in suburban United States retail channels where consumers seek maintenance between infrequent salon visits. California Safer Consumer Products disclosure mandates extend development timelines for preservative system selection.
- Powder:Anhydrous concentrates requiring reconstitution prior to application, favored for shipping economy and shelf stability in professional backbar inventories.
- Gel:Thickened aqueous bases enabling targeted application to specific hair sections, common in precision highlighting services.
Liquid leads on scale; cream leads on momentum.
Application:
Service setting determines price realization, formulation sophistication, and regulatory scrutiny intensity.
- Salon Use:Professional-only formulations applied by licensed stylists during chemical services command premium per-treatment economics through service bundling. Stylists in Los Angeles and New York metro markets adopt peptide-infused variants at twice the rate of general salon populations. State cosmetology board regulations govern permissible active concentrations in licensed facility use.
- Professional Treatments:Intensive in-salon protocols combining multiple bond-repair steps with heat activation, positioned as standalone damage-recovery services rather than color add-ons. Demand clusters in high-frequency color client bases where measurable tensile-strength recovery justifies premium service pricing.
- Home Use:Consumer self-application products sold through retail and direct-to-consumer channels, typically at lower active concentrations for safety margin.
- Retail Products:Mass-market and prestige shelf placements including bond-repair shampoos, conditioners, and leave-in treatments extending the category into daily maintenance routines.
Salon use leads on scale; professional treatments lead on momentum.
Ingredient Source:
Provenance positioning intersects with REACH disclosure mandates and clean-beauty purchasing preferences to reshape competitive advantage.
- Hybrid:Compositions combining bio-fermented cysteine derivatives with lab-stabilized synthetic bond-repair molecules capture premium positioning while satisfying transparency demands. German and French formulators face steepest ECHA dossier preparation costs, filtering downstream to brand partners. ISO frameworks for bio-processed cosmetic actives create first-mover certification advantages.
- Synthetic:Petroleum-derived bis-aminopropyl diglycol dimaleate and comparable molecules deliver consistent batch performance and established efficacy documentation. Supply concentrates among European and North American specialty chemical producers, creating procurement vulnerability for mid-tier brands.
- Natural:Plant-derived cysteine precursors and botanical extracts positioned for clean-beauty preference alignment, though with variable bond-repair kinetics.
- Organic:Certified organic inputs meeting USDA or EU organic cosmetic standards, commanding niche premium in sustainability-focused channels.
Hybrid leads on scale; natural leads on momentum.
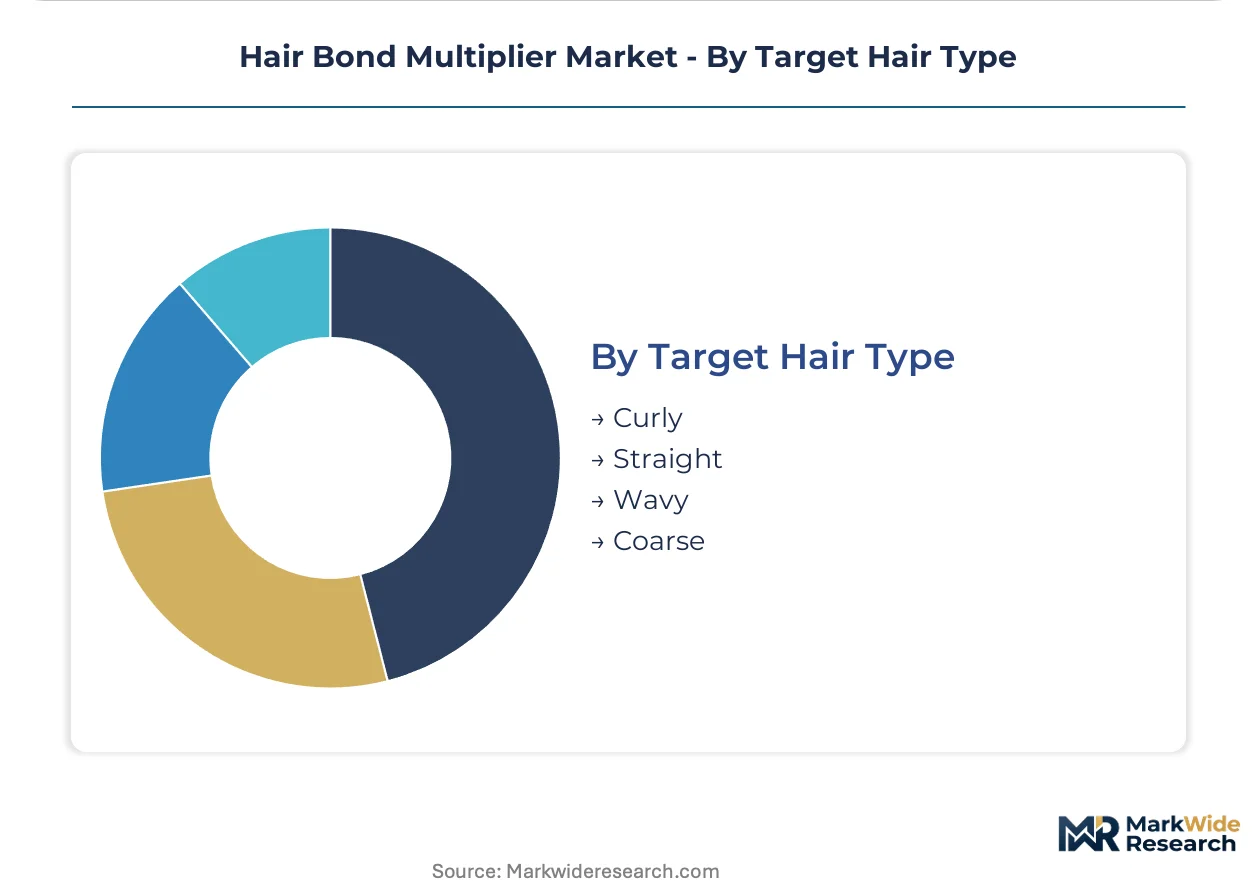
Target Hair Type:
Fiber morphology and damage susceptibility drive formulation customization and channel targeting.
- Curly:Tightly coiled keratin structures with elevated disulfide bond density require specialized penetration enhancers and higher active concentrations. Stylists serving textured hair clients in Atlanta and Houston markets standardize bond-building as mandatory for chemical straightening services.
- Coarse:Thick-diameter fibers with compact cuticle layers resist active penetration, demanding extended processing times or mechanical assistance for efficacy.
- Straight:Relatively uniform fiber architecture enables predictable active distribution, supporting streamlined formulation platforms.
- Wavy:Intermediate curl pattern with moderate damage susceptibility, representing volume concentration in general salon populations.
Straight leads on scale; curly leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors professional salon demand for peptide-infused bond multipliers, with stylists in this cluster adopting damage-prevention protocols at twice the rate of general salon populations. The United States concentrates premium haircare spending, while EU REACH disclosure mandates reshape formulation strategies across Germany and France.
United States
High-frequency color clients in New York and Los Angeles metro markets drive professional treatment adoption, with stylists embedding bond-building as mandatory pre-coloring protocols. FDA cosmetic labeling requirements for volatile organic content constrain interstate formulation distribution. Texas and Florida suburban markets show fastest direct-to-consumer subscription growth for at-home maintenance products.
Germany
Professional salons in Hamburg and Munich standardize cysteine-derived bond multipliers as mandatory damage-prevention workflows during bleaching services. ECHA dossier preparation costs for REACH-compliant synthetic actives filter downstream to brand partners. Frankfurt-based specialty chemical producers concentrate supply of pharmaceutical-grade bond-repair molecules.
France
Parisian formulators face steep compliance burdens under REACH's extended disclosure requirements for cosmetic actives. ANSM oversight on topical product safety substantiation extends development timelines for preservative system selection. Lyon and Marseille salon chains accelerate adoption of bio-fermented hybrid formulations to satisfy clean-beauty positioning demands.
United Kingdom
London professional salons integrate bond-repair treatments into premium coloring services, with measurable tensile-strength recovery justifying higher service pricing. Post-Brexit regulatory divergence from EU REACH creates parallel compliance pathways for brands maintaining European distribution. Manchester and Birmingham retail channels show momentum for cream-based consumer maintenance products.
Canada
Toronto and Vancouver salon markets adopt bond-building protocols for chemical straightening services targeting curly and textured hair clients. Health Canada cosmetic ingredient oversight aligns with FDA frameworks, streamlining North American formulation strategies. Montreal formulators specialize in hybrid natural-synthetic compositions for cross-border brand supply.
Hair Bond Multiplier Market Vendor Landscape
Patent litigation and licensing enforcement dominate the current landscape as incumbent players defend intellectual property positions around bis-aminopropyl diglycol dimaleate chemistries. The vendor base stratifies across three tiers: multinational beauty conglomerates with salon-exclusive distribution, specialty ingredient suppliers serving third-party formulators, and direct-to-consumer challengers disrupting traditional retail channels. Two strategic archetypes prevail—vertically integrated beauty houses controlling end-to-end supply chains, and ingredient-focused innovators monetizing through B2B licensing. Competitive intensity concentrates on M&A targeting biotech-fermentation capabilities and strategic partnerships bridging professional and at-home application segments.
Within the multinational beauty conglomerate tier, L'Oréal SA and Henkel AG and Co. KGaA occupy positions anchoring mass-market penetration through salon-exclusive distribution under professional banners. Among specialty ingredient suppliers, Croda International Plc exemplifies the B2B licensing archetype, extending reach into hybrid natural-synthetic bond builders for third-party brand partners. Olaplex Holdings Inc. represents the patent-defended premium positioning model, leveraging intellectual property estates to sustain pricing power across professional channels.
| Leading Market Players |
|---|
| Croda International Plc |
| Keune Haircosmetics |
| Olaplex Holdings Inc. |
| Schwarzkopf Professional |
| Redken |
| LOréal SA |
| K18hair |
| ALTERNA |
| Henkel AG and Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Specialized cosmetic chemist talent concentrated in Frankfurt and Paris drives labor-cost differentials that widen pricing-tier spreads between premium salon-exclusive formulations and mass-market retail variants. REACH dossier preparation expenses and cysteine-derivative sourcing premiums compound these spreads, embedding workforce geography directly into final product economics.
Pricing Analysis
Input-cost pass-through from pharmaceutical-grade bis-aminopropyl diglycol dimaleate and bio-fermented cysteine derivatives sustains premium-mid-economy pricing differentiation across professional and retail channels. Price differentiation hinges on certification grade under REACH disclosure tiers and brand premium anchored by patent-protected molecular platforms. Pricing pressure stems from California Safer Consumer Products compliance costs compressing margins in national distribution tiers. Home-use consumers demonstrate highest price sensitivity, while licensed salon professionals absorb premium markups through service-bundled economics.
Supply Chain Analysis
Direct-to-salon distribution handles professional-channel demand, while retail and subscription platforms serve consumer self-application segments. Pharmaceutical-grade bond-repair molecule production concentrates in Germany, France, and the United States. Raw material dependencies include cysteine precursors, fermentation-derived actives, and lab-stabilized synthetic cross-linkers. Supply chain risk centers on single-source vulnerability for bis-aminopropyl diglycol dimaleate among European specialty chemical producers. Distribution runs through professional beauty distributors, direct-to-consumer platforms, and prestige retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where professional salon demand has shifted toward peptide-infused formulations with measurable tensile-strength documentation justifying premium service pricing.
For Market Incumbents: Acquire biotech-fermentation certification capabilities to preempt ISO framework alignment and defend margin position against clean-beauty challengers. Consolidate backward integration into cysteine-derivative supply to offset procurement vulnerability from European specialty chemical concentration. Channel control through exclusive stylist education platforms remains essential as direct-to-consumer subscription models erode salon resale arrangements. For New Entrants and Emerging Players: Fermentation-derived hybrid actives offer a technology-first wedge into the underdeveloped at-home maintenance segment, particularly in suburban United States markets where salon visit frequency lags urban centers. Target cream-based retail formulations for consumer self-application between professional visits, leveraging digital-native purchasing patterns among younger demographics. Go-to-market execution should prioritize subscription replenishment models over traditional retail shelf placement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier brands lacking REACH dossier preparation capabilities but possessing established distribution relationships. Long-term viability over the coming decade rests on regulatory compliance infrastructure and biotech-fermentation access rather than brand equity alone. Watch for ECHA disclosure deadline enforcement as the inflection signal separating compliant from stranded asset positions.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech-Fermentation Certification Investment | Early ISO framework alignment creates first-mover positioning as clean-beauty preferences harden into purchasing requirements. |
| Backward Integration into Cysteine Supply | Captive sourcing of bio-fermented actives reduces dependency on Frankfurt-based specialty chemical producers. |
| Subscription-Based Replenishment Launch | Direct-to-consumer platforms capture younger demographics in Texas and Florida where stylist recommendation influence weakens. |
| Professional-Only Product Line Extension | Salon-exclusive peptide-infused variants command premium economics through measurable tensile-strength recovery data. |
| Men's Grooming Channel Integration | Barbershop distribution infrastructure targets chemical straightening and beard coloring services in underserved segments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic chemists, salon chain procurement directors, regulatory affairs specialists at ingredient suppliers, and brand managers at professional beauty houses with secondary validation. Sources included ECHA REACH dossier databases, FDA cosmetic ingredient filings, customs trade records for cysteine derivatives, and professional salon industry association reports. Bottom-up volume modeling across formulation types and application contexts triangulated against top-down market sizing.
Segment-weighting approaches distributed value and volume across liquid, cream, powder, and gel formulations; salon use, professional treatments, home use, and retail product applications; and hybrid, synthetic, natural, and organic ingredient sources. CAGRs derived from regression analysis of historical procurement patterns and projected stylist adoption curves. Industry-specific inputs incorporated REACH compliance timeline assumptions and bio-fermentation capacity buildout trajectories across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA enforcement intensity, perfluorinated compound restriction timing, and biotech-fermentation certification standard finalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
France Haircare Market
Hair Care
Canada Hair Care Market
Hair Care
Latin America Hair Care Market
Hair Care
Europe Hair Care Market
Hair Care
Hair Serum Market
Hair Care
Mexico Hair Care Market
Hair Care
Hair Texturizer Products Market
Hair Care
Sweden Hair Care Market
Hair Care
Global Premium Hair Care Market
Hair Care
Hair and Scalp Care Market
Hair Care
Hair Care Appliances Market
Hair Care
Brazil Hair Care Market
Hair Care
Hair Care Products Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Hair Mask Market
Hair Care
Australia Hair Removal Market