
 Oleophilic Materials Market | 2026-2036
Oleophilic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Oleophilic Materials Market Analytics
EPA discharge standards under the Clean Water Act is hardening compliance costs for water treatment infrastructure across upstream oil and gas operations. 3M Company leverages its deep materials science portfolio to sustain membrane performance advantages in produced water applications. Elastec anchors its position through specialized oil recovery vessels and containment systems deployed across North American coastal zones. Brady Corporation competes via channel control over industrial absorption product distribution to manufacturing and environmental services accounts.
Oleophilic materials exhibit selective affinity for hydrocarbon molecules, typically engineered from polypropylene, polyurethane, or cellulose substrates with surface energies below 30 mN/m to ensure preferential oil wetting over aqueous phases. These materials enable phase separation, contaminant recovery, and spill containment across process industries where oil-water emulsions challenge conventional treatment economics. Membranes and filters capture the dominant share of product value, driven by repeat replacement cycles in continuous water treatment trains, while coatings gain traction in subsea pipeline protection where fouling resistance extends asset life. Granules remain a mature, price-competitive format for emergency spill response, though margin pools are thinning amid commoditization of polypropylene loose-fill absorbents.
EPA enforcement of Clean Water Act effluent limitations shapes product certification requirements and procurement specifications for offshore and onshore operators. OSHA workplace exposure standards and Coast Guard spill response regulations further constrain material selection, favoring flame-retardant and low-toxicity formulations in marine deployment scenarios. ASTM and ISO test protocols for oil sorption capacity and retention under dynamic flow conditions increasingly determine vendor qualification status in public-sector and supermajor tenders. Stakeholders must monitor regulatory harmonization pressures between EPA state-delegated programs and emerging MEE water quality benchmarks in Chinese import markets, as divergence in certification burdens threatens to fragment supplier compliance strategies.
Market Dynamics
EPA discharge standards under the Clean Water Act are hardening compliance costs for water treatment infrastructure across upstream oil and gas operations, concentrating procurement authority among supermajors with capital to absorb membrane replacement cycles and certification burdens.
Growth Catalysts
- Offshore produced water volumes:Deepwater drilling in the Gulf of Mexico generates continuous demand for oleophilic membrane replacement in separation trains.
- REACH substance restrictions:European chemical safety frameworks are phasing out legacy surfactant-based treatments, opening substitution windows for bio-based oleophilic absorbents.
- Cellulose substrate engineering:Modified agricultural fiber technologies are achieving polypropylene-equivalent sorption capacity at lower unit environmental footprint.
Market Restraints
- Propylene feedstock volatility:Polypropylene production costs swing with naphtha and propane pricing, compressing margin stability for membrane manufacturers.
- Single-source ceramic substrate dependence:High-performance membrane coatings rely on concentrated alumina supply from specific mining jurisdictions.
- Subsea coating adhesion limits:Current polyurethane formulations degrade under high-pressure CO2 environments beyond 1,500 meter depths.
Strategic Opportunities
- Brazilian pre-salt development:ANVISA environmental licensing for ultra-deepwater fields creates demand for certified spill response materials.
- Electrospun nanofiber convergence:Hybrid manufacturing combining melt-blowing with electrospinning is enabling sub-micron filtration efficiency in single-layer membranes.
- Industrial distributor bypass:Direct procurement platforms are emerging for mid-size refinery operators seeking to consolidate absorbent purchasing.
Industry Challenges
- ASTM F726 certification timelines:Oil sorption capacity testing protocols require 90-120 day validation cycles, delaying new product commercialization.
- Legacy skimmer integration:New membrane materials face mechanical incompatibility with existing offshore vessel recovery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oleophilic Materials Market |
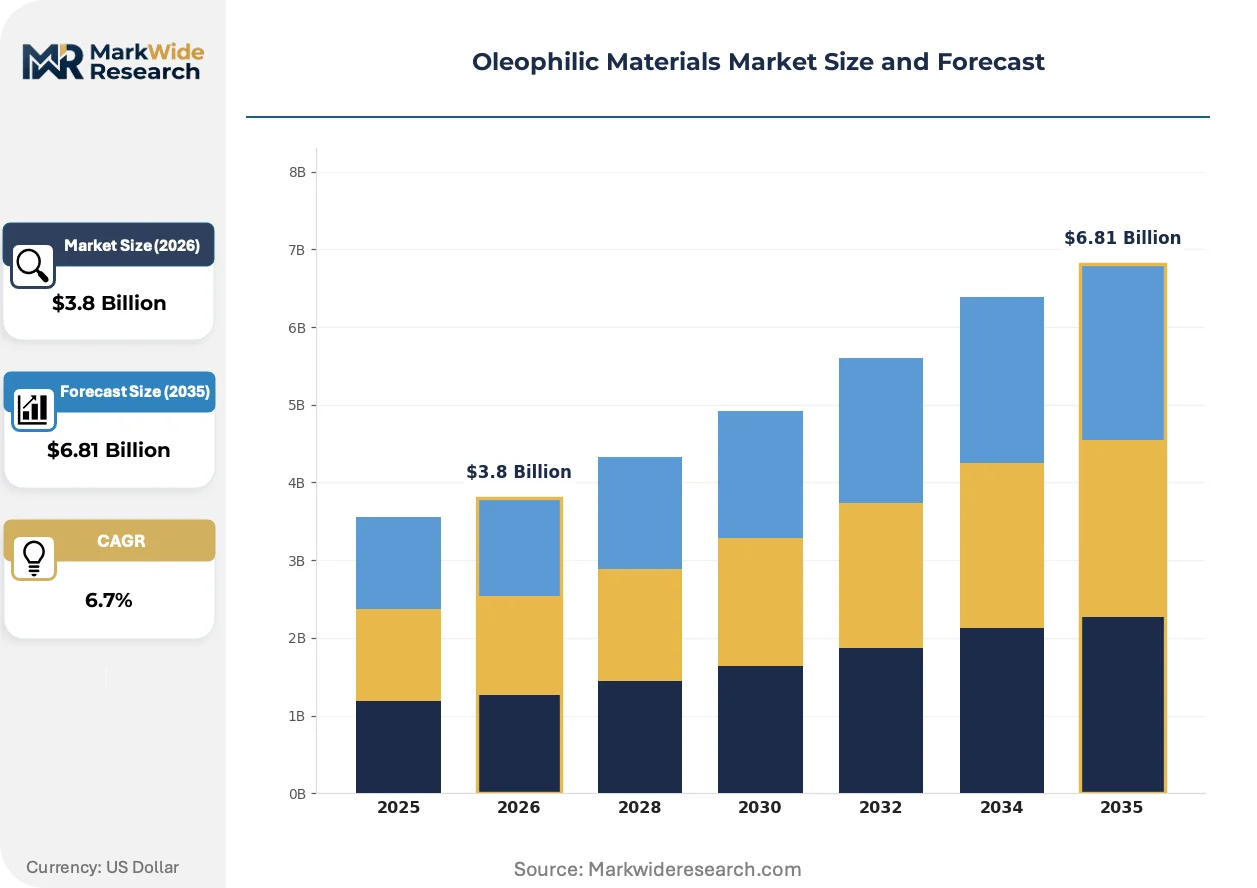
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membranes, Coatings, Filters, Granules Application: Water Treatment, Oil Recovery, Industrial Absorption, Spill Cleanup End Use Industry: Manufacturing, Environmental Services, Oil & Gas, Pharmaceuticals Distribution Channel: Direct Sales, E-commerce, Distributors, Retail |
| Companies Covered | 3M Company, Elastec, Brady Corporation, New Pig Corporation, Miller Environmental Group, Seashell Technology LLC, Saint-Gobain ADFORS, Chemtex, Parker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oleophilic Materials Market Evolving Landscape
Surface energy engineering and manufacturing process control are converging to expand the performance envelope of oleophilic materials beyond traditional polypropylene dominance, with regulatory chemistry restrictions accelerating substrate diversification.
Electrospun nanofiber membranes are automating quality consistency in high-throughput production lines. Offshore platform operators in the Gulf of Mexico are specifying these materials for produced water polishing stages. The technology is automating labor-intensive manual filter replacement schedules while reducing downstream emulsion breakthrough incidents.
EPA effluent limitation guidelines for the oil and gas extraction category are tightening total dissolved solids and oil and grease discharge thresholds. Upstream operators face capital allocation decisions between upgrading existing gravity separation vessels or installing secondary membrane treatment trains. Texas and Louisiana coastal facilities are prioritizing compact skid-mounted systems to minimize offshore platform footprint penalties.
Refinery procurement departments are consolidating absorbent purchasing through integrated supply contracts that bundle spill response inventory with routine maintenance materials. Industrial distributors serving the petrochemical corridor are losing share to manufacturer-direct channels offering volume-tiered pricing and technical field support. This concentration is most visible among integrated supermajors operating multiple downstream sites along the Texas Gulf Coast.
Oleophilic Materials Market Segmentation
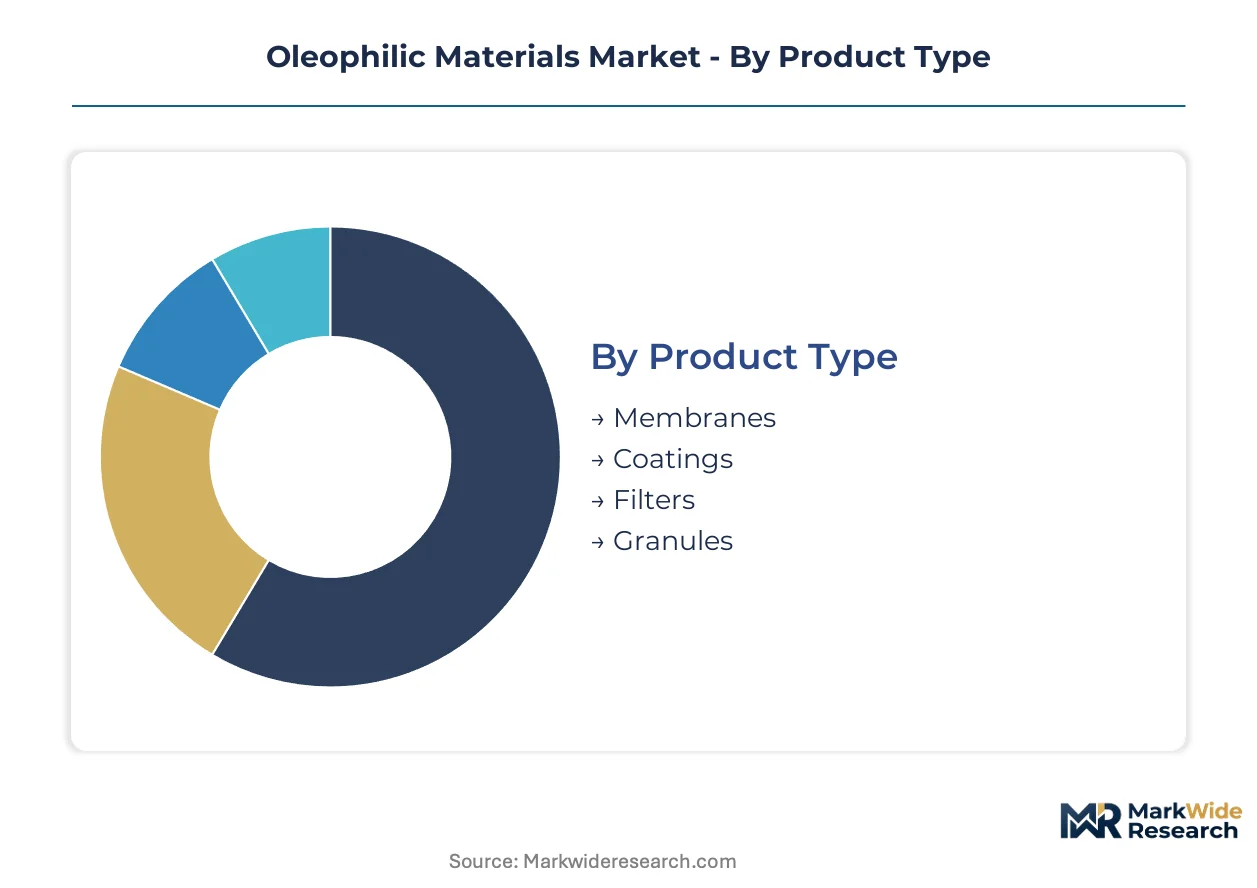
Oleophilic materials serve divergent buyer priorities across product formats, from membrane replacement cycles in continuous water treatment to emergency spill response inventory. Segmentation reveals how procurement authority concentrates among supermajors with capital for certified infrastructure versus mid-size operators seeking consolidated purchasing channels.
Product Type:
Buyers differentiate primarily by replacement frequency and capital intensity, with continuous-process operators prioritizing membrane performance guarantees and emergency responders weighing unit cost against sorption capacity.
- Membranes:Polypropylene and cellulose substrates engineered below 30 mN/m surface energy deliver selective oil wetting in produced water separation trains. Gulf of Mexico offshore platforms specify these for polishing stages where EPA discharge standards mandate sub-15 ppm oil and grease effluent.
- Filters:Pleated and depth configurations capture suspended hydrocarbons in upstream water handling systems, with repeat replacement cycles driving recurring revenue concentration among integrated operators in Texas and Louisiana refinery clusters.
- Coatings:Polyurethane formulations protect subsea pipelines from fouling, though high-pressure CO2 degradation beyond 1,500 meters limits ultra-deepwater deployment.
- Granules:Loose-fill polypropylene absorbents dominate emergency spill response procurement, with margin compression from commoditized Chinese imports reshaping distributor economics.
Membranes lead volumes today; coatings are gaining share fastest as subsea asset life extension priorities intensify.
Application:
Regulatory enforcement intensity and operational criticality separate buyers, with continuous discharge compliance commanding premium pricing against episodic spill response procurement.
- Water Treatment:Produced water separation in upstream oil and gas operations consumes oleophilic membranes and filters in continuous replacement cycles, with EPA Clean Water Act enforcement hardening specification requirements for offshore Gulf of Mexico facilities.
- Oil Recovery:Skimmer-mounted oleophilic belts and drum systems capture floating hydrocarbons from vessel-deployed containment operations, concentrating demand among Coast Guard-certified response contractors along coastal Louisiana.
- Industrial Absorption:Manufacturing facilities deploy pads and rolls for routine maintenance leakage, with procurement consolidating through integrated supply contracts bundling spill inventory with MRO materials.
- Spill Cleanup:Emergency response organizations stockpile granules and booms for rapid deployment, with ANVISA environmental licensing in Brazil creating certified material demand for pre-salt field development.
Water treatment anchors current revenue; oil recovery applications are expanding most quickly as offshore production volumes rise.
End Use Industry:
Capital availability and regulatory exposure divide buyers, with oil and gas supermajors absorbing certification burdens that exclude smaller environmental services competitors from premium membrane tenders.
- Oil & Gas:Upstream operators in the Gulf of Mexico and downstream refineries along the Texas Gulf Coast generate concentrated demand for membranes, filters, and spill response materials, with EPA effluent limitations driving secondary treatment train installations.
- Environmental Services:Spill response contractors and remediation specialists procure granules and absorption products for emergency deployment, facing margin pressure from manufacturer-direct channels bypassing traditional distribution.
- Manufacturing:Petrochemical and heavy industrial facilities specify industrial absorption products for workplace OSHA compliance, with channel control determining vendor selection among safety distributors.
- Pharmaceuticals:Aseptic processing and solvent recovery applications require specialized oleophilic filtration, though validation timelines and FDA quality system requirements extend procurement cycles.
Oil and gas dominates current procurement; environmental services is climbing the fastest as outsourcing of remediation operations accelerates.
Distribution Channel:
Scale and technical support requirements fragment buyer pathways, with integrated supermajors leveraging direct procurement platforms while mid-size operators remain dependent on distributor relationships.
- Direct Sales:Membrane manufacturers deploy technical field support teams for supermajor accounts, offering volume-tiered pricing and performance guarantees that consolidate procurement authority among multi-site refinery operators.
- Distributors:Industrial safety and environmental products distributors serve mid-size manufacturing and environmental services accounts, though share erosion to manufacturer-direct channels is visible across the Texas petrochemical corridor.
- E-commerce:Digital procurement platforms emerge for standardized absorbent products, enabling consolidated purchasing for mid-size refinery operators seeking to bypass traditional channel markups.
- Retail:Limited to small-scale spill response inventory and consumer-grade absorption products, with minimal relevance to industrial oleophilic material procurement.
Direct sales captures the largest volume today; e-commerce channels are expanding most quickly as procurement digitization penetrates mid-market accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical engineering talent clusters along the US Gulf Coast anchor oleophilic materials deployment, with regulatory enforcement intensity and offshore production economics shaping geographic demand concentration.
United States
Deepwater drilling operators in the Gulf of Mexico sustain membrane replacement cycles for produced water polishing stages. EPA effluent limitation guidelines under the Clean Water Act mandate sub-15 ppm oil and grease discharge thresholds, hardening procurement specifications. Texas and Louisiana coastal facilities concentrate demand, with refinery clusters in Houston and Lake Charles driving integrated supply contract consolidation.
Brazil
Pre-salt field development in the Santos Basin generates certified spill response material demand for ultra-deepwater operations. ANVISA environmental licensing frameworks shape product certification requirements for offshore contractors. Rio de Janeiro serves as the procurement coordination hub, with local distributors managing inventory for Petrobras-operated platforms.
China
MEE water quality benchmarks for industrial discharge are tightening oil content thresholds in coastal refining zones. Domestic membrane manufacturers compete with imported polypropylene substrates in Bohai Bay oilfield water treatment. The Yangtze River Delta petrochemical corridor concentrates procurement authority among state-owned refinery operators.
Germany
REACH substance restrictions are phasing out legacy surfactant-based treatments in chemical manufacturing effluent streams. ECHA authorization processes favor bio-based oleophilic absorbents with lower environmental footprint profiles. The Ruhr industrial region and Ludwigshafen chemical complex anchor demand for cellulose substrate alternatives to polypropylene.
United Arab Emirates
Offshore production expansion in the Arabian Gulf drives specification of flame-retardant oleophilic materials for high-temperature deployment scenarios. MOHAP environmental safety frameworks influence material selection for marine spill response inventory. Abu Dhabi and Dubai serve as regional procurement hubs for supermajor operators across Middle Eastern production zones.
Oleophilic Materials Market Competitive Landscape
The competitive structure tilts toward diversified materials science conglomerates with captive polymer substrate supply. Market concentration is moderate, with membrane performance certification requirements creating barriers that favor established players with capital for ASTM validation cycles. Two strategic archetypes dominate: integrated conglomerates leveraging backward polymer integration, and specialized environmental equipment fabricators with Coast Guard certification relationships. Competitive moves center on direct procurement platform development and electrospun nanofiber manufacturing scale-up.
Among US-based diversified manufacturers, 3M Company and Brady Corporation exemplify the conglomerate archetype, with the former representing deep materials science portfolios and the latter occupying a position in industrial safety distribution channels. Elastec anchors the specialized equipment tier, with its corporate name signaling environmental containment focus. These three companies sit within distinct competitive vectors—materials innovation, channel control, and application-specific engineering—rather than direct product overlap.
| Leading Market Players |
|---|
| 3M Company |
| Elastec |
| Brady Corporation |
| New Pig Corporation |
| Miller Environmental Group |
| Seashell Technology LLC |
| Saint-Gobain ADFORS |
| Chemtex |
| Parker |
| Others |
Value Network & Pricing Analysis
Backward integration into polypropylene substrate production anchors pricing power for membrane manufacturers serving Gulf of Mexico offshore operators. Captive polymer supply insulates integrated conglomerates from naphtha and propane feedstock volatility that compresses margins for non-integrated competitors.
Pricing Analysis
The bundled-versus-unbundled service split separates procurement economics across buyer tiers. Contract-based long-term offtake dominates supermajor accounts, where volume scale and certification grade drive price differentiation. Cost compression in loose-fill absorbent granules is intensifying because Chinese imports flood emergency response channels. Mid-size refinery operators exhibit highest price sensitivity, while EPA-mandated membrane specifications render supermajors relatively inelastic to unit cost swings.
Supply Chain Analysis
Dual-sourcing requirements from Petrobras and Gulf of Mexico supermajors mandate multi-supplier qualification for ceramic membrane substrates. Geographic supply concentrates in Germany for alumina precursors, China for polypropylene resin, and the United States for cellulose fiber engineering. Raw material dependencies rest on propylene feedstocks, agricultural fiber supply, and specialty mining outputs from concentrated jurisdictions. Single-source vulnerability in high-purity alumina extraction threatens coating adhesion performance for ultra-deepwater deployment. Distribution runs through manufacturer-direct technical sales teams for membrane replacement cycles and industrial safety distributors for standardized absorbent products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
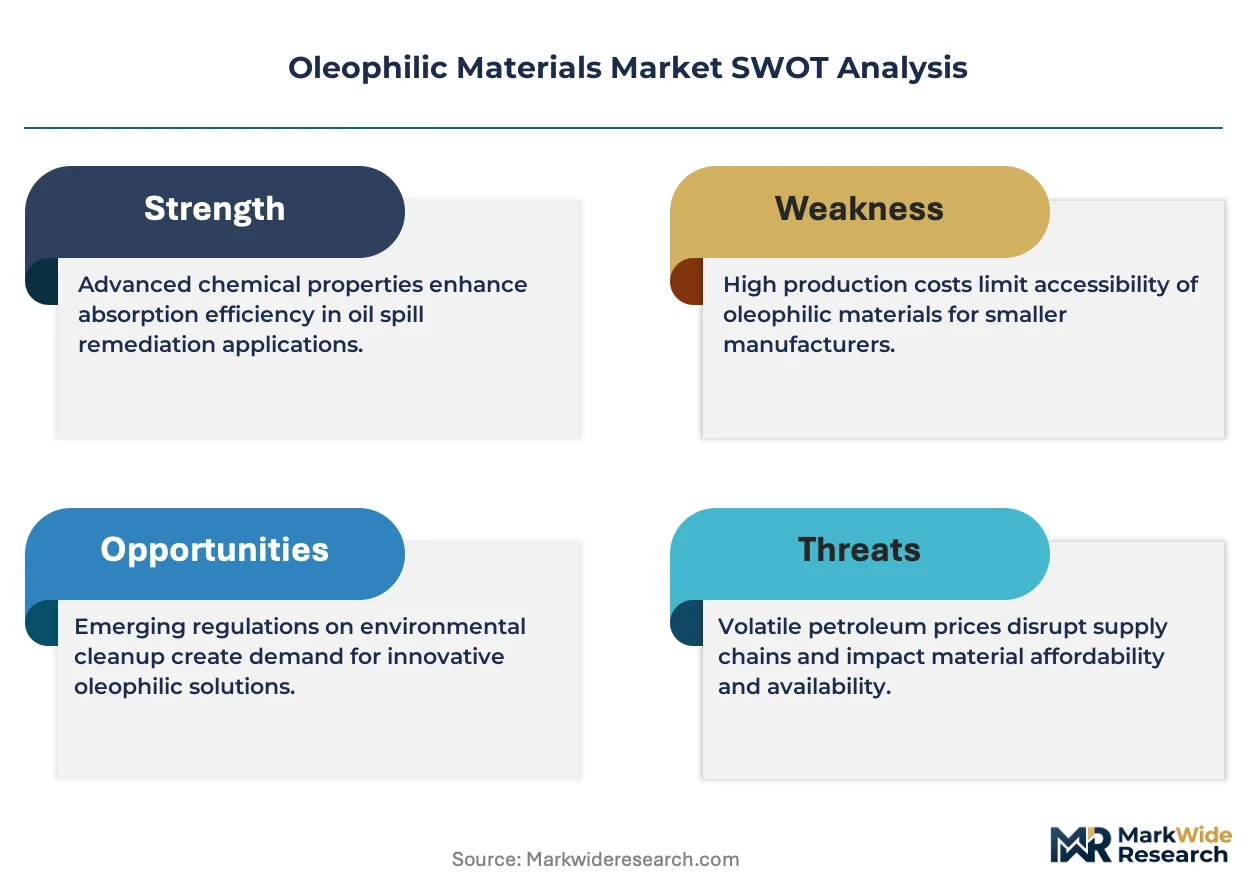
This market reads as a late-cycle quality story. EPA effluent limitation guidelines under the Clean Water Act are forcing upgrades toward premium membrane specifications that command performance guarantees over commodity alternatives.
For Market Incumbents: Anchor membrane performance advantages through ASTM F726 certification investment and electrospun nanofiber manufacturing scale-up. Consolidate procurement relationships with supermajor accounts by embedding technical field support teams at Texas and Louisiana refinery clusters. Defend against cellulose substrate substitution by quantifying lifecycle cost advantages in continuous water treatment trains. For New Entrants and Emerging Players: The price-point gap between premium electrospun membranes and economy-grade polypropylene absorbents creates entry space for hybrid manufacturing approaches. Target Brazilian pre-salt development for ANVISA-certified spill response materials where incumbent presence remains thin. Pursue direct procurement platform partnerships with mid-size refinery operators seeking to bypass traditional distributor markups. For Investors and Strategic Acquirers: Roll-up economics work for specialized environmental equipment fabricators because Coast Guard certification relationships constitute non-replicable intangible assets. Long-term viability centers on membrane replacement cycle recurrence rather than one-time spill response inventory. Watch electrospun nanofiber yield consistency as the inflection signal separating scalable manufacturers from pilot-scale operators.| Strategic Initiative | Industry Significance |
|---|---|
| Electrospun Nanofiber Scale-Up | Automated quality control enables sub-micron filtration efficiency for Gulf of Mexico polishing stages. |
| Direct Procurement Platform Development | Manufacturer-direct channels capture mid-size refinery accounts from industrial safety distributors. |
| Cellulose Substrate Engineering Investment | Modified agricultural fibers achieve polypropylene-equivalent sorption with lower environmental footprint. |
| Coast Guard Certification Relationship Expansion | ANVISA licensing in Brazil and EPA compliance in US create dual-jurisdiction qualification barriers. |
| Backward Integration into Polypropylene Supply | Captive resin production insulates margin stability from naphtha and propane price volatility. |
Research Methodology
Coverage spans the United States Gulf Coast, Brazil's Santos Basin, and China's Bohai Bay oilfields, with primary inputs from each regional cluster. The analysis combines interviews with offshore platform operations managers, refinery procurement leads, membrane R&D directors, and environmental services contractors with secondary validation from EPA effluent limitation guidelines, ANVISA licensing databases, and SEC filings from diversified materials science conglomerates. Bottom-up and top-down triangulation reconciles replacement cycle frequency data with aggregate membrane consumption estimates.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. The analytical framework models segmentation across product format, application criticality, end-use industry capital availability, and procurement channel structure. CAGRs derive from replacement cycle elasticity to regulatory enforcement intensity and offshore production volume trajectories. Forecast inputs incorporate electrospun nanofiber adoption curves and cellulose substrate substitution rates in produced water treatment.
The model assumes a particular technology adoption path; alternative pathways for electrospun manufacturing automation would alter the outlook. Forecasts reflect assumptions about EPA enforcement continuity, propylene feedstock price bands, and ceramic substrate supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Glycerol Esters Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Lipid Rich Powder Market
Oleochemicals
Global Specialty Oleochemicals Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Europe Wax Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Global Palm Wax Market