
 Critical Infrastructure Monitoring Market | 2026-2036
Critical Infrastructure Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Infrastructure Monitoring Market Outlook
North American sensor manufacturers is recalibrating production schedules to meet utility procurement timelines. Cisco Systems leverages its networking heritage to dominate edge connectivity layers for power substations. IBM anchors its position through AI-driven predictive analytics platforms tailored to water treatment facilities. Siemens Mobility competes aggressively in transportation infrastructure monitoring across European rail corridors.
Critical infrastructure monitoring encompasses the continuous acquisition, transmission, and analysis of operational data from physical assets using networked sensor arrays, telemetry systems, and centralized analytics platforms to prevent failures and optimize performance. These systems typically integrate vibration sensors, thermal imagers, and SCADA interfaces operating at sub-second refresh rates to detect anomalies before service disruption occurs. IoT Solutions leads deployment volume due to mature hardware cost curves and standardized communication protocols. AI Analytics represents the fastest-expanding segment as operators demand automated pattern recognition for asset degradation forecasting. Cloud Computing occupies the margin-rich tier where subscription-based platform economics generate recurring revenue streams from multi-site operators.
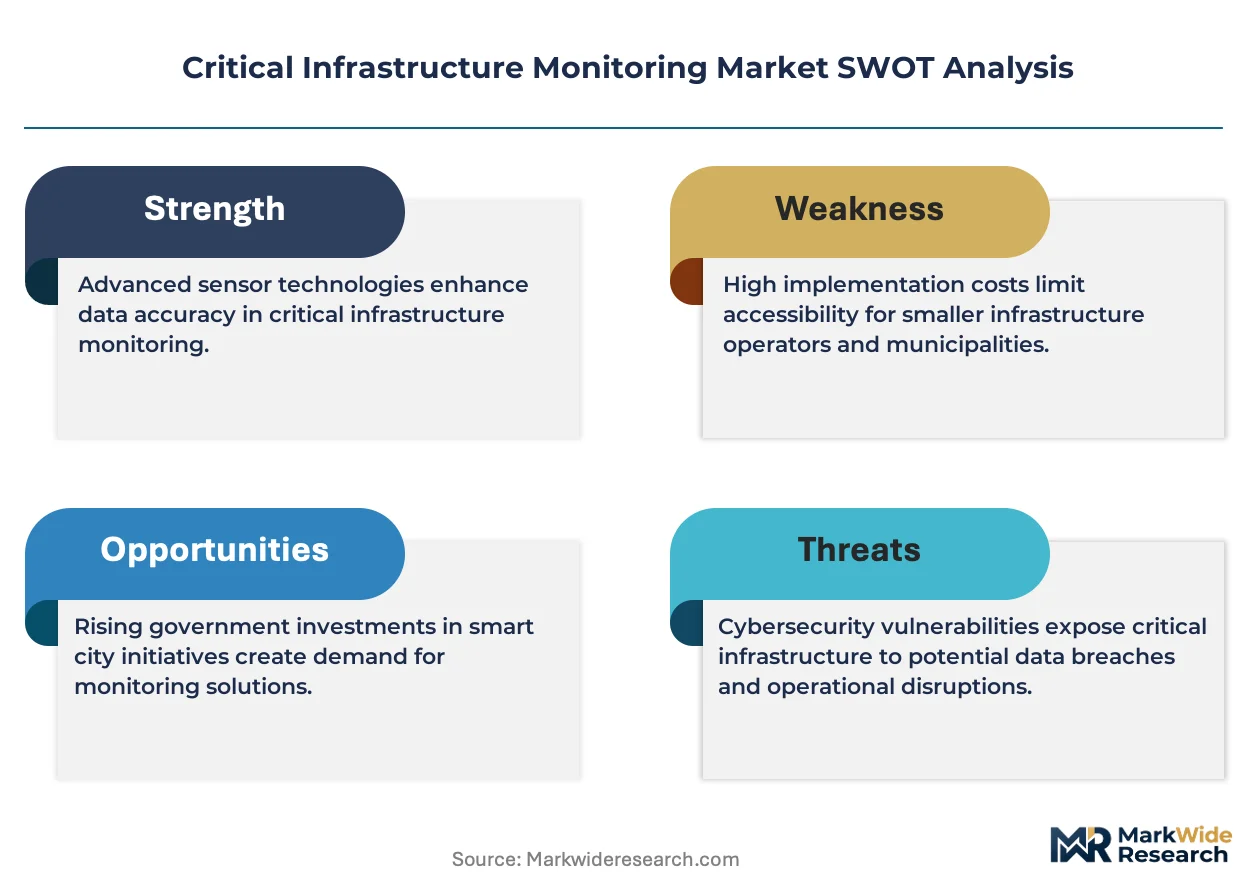
The Federal Energy Regulatory Commission enforces mandatory reliability standards that compel electric utilities to maintain continuous monitoring coverage across bulk power systems. The Environmental Protection Agency drives water infrastructure investment through lead service line replacement mandates requiring real-time quality tracking. The Cybersecurity and Infrastructure Security Agency publishes binding operational directives that shape procurement specifications for critical facility operators. Stakeholders must weigh the capital intensity of on-premises deployments against the operational flexibility of hybrid architectures as regulatory compliance windows tighten.
Market Dynamics
NERC CIP reliability standards in the United States are compelling utilities to maintain continuous asset visibility across bulk power systems, creating structural pull for sensor networks and predictive analytics platforms that prevent service disruption before it occurs.
Growth Catalysts
- NERC CIP mandates:The Federal Energy Regulatory Commission enforces mandatory reliability standards that compel electric utilities to deploy continuous monitoring coverage across transmission and distribution networks.
- Water quality tracking:The Environmental Protection Agency drives infrastructure investment through lead service line replacement mandates requiring real-time contaminant detection systems.
- Predictive maintenance platforms:Industrial facility operators in Germany prioritize vibration analysis and thermal imaging systems to optimize asset performance and prevent unplanned outages.
Market Restraints
- Semiconductor supply concentration:Sensor manufacturers face input cost volatility from concentrated fabrication capacity in East Asia, constraining production scaling for utility procurement timelines.
- Legacy system integration friction:SCADA interfaces operating at sub-second refresh rates create technical limitations when interfacing with decades-old control architectures in established facilities.
- Capex intensity of on-premises deployments:Full-stack hardware installations require substantial upfront investment compared with hybrid architectures, slowing adoption among smaller municipal operators.
Strategic Opportunities
- Transportation infrastructure monitoring:European rail corridors present underpenetrated demand for track condition sensors and signaling system analytics as operators modernize aging networks.
- AI-driven pattern recognition:Automated asset degradation forecasting converges machine learning with IoT sensor arrays, creating white space for platform providers serving multi-site water treatment facilities.
- CISA procurement specifications:The Cybersecurity and Infrastructure Security Agency publishes binding operational directives that shape vendor qualification standards, favoring suppliers with certified security architectures.
Industry Challenges
- OT-IT convergence expertise:Operators struggle to recruit personnel fluent in both operational technology protocols and enterprise cybersecurity frameworks, creating talent bottlenecks for deployment teams.
- Multi-vendor integration complexity:Telemetry systems from disparate suppliers require extensive custom engineering to achieve unified analytics, extending project timelines and inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Infrastructure Monitoring Market |
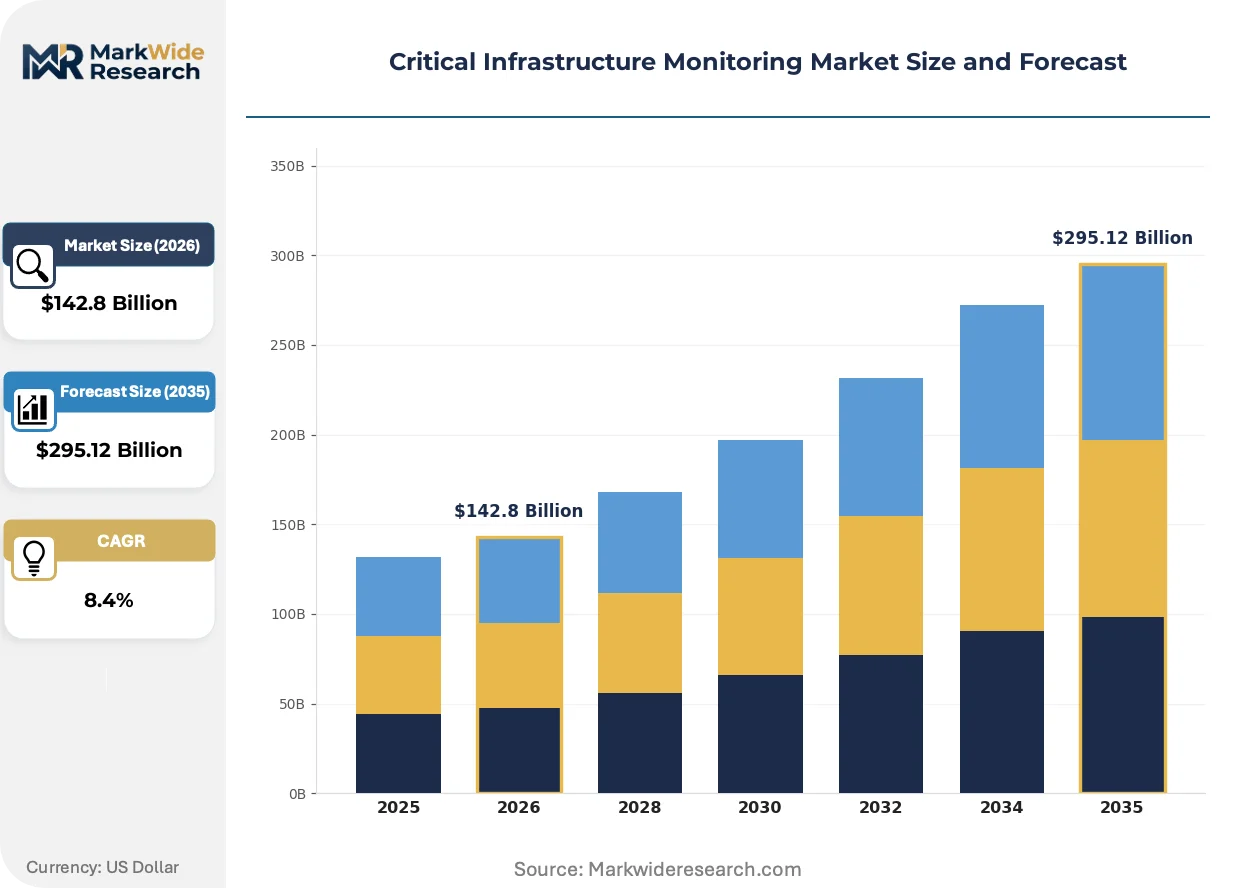
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $295.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, AI Analytics, Cloud Computing, Edge Computing Application: Energy Management, Water Supply Monitoring, Transportation Systems, Security Surveillance End User: Utilities, Government Agencies, Manufacturing, Public Safety Organizations Deployment: On-Premises, Cloud-Based, Hybrid, Remote |
| Companies Covered | Broadcom, New Relic, Cisco Systems, Bentley Systems, Datadog, IBM, BMC Software, Siemens Mobility, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Infrastructure Monitoring Market Strategic Shifts
Edge computing architectures are actively reshaping how sensor data is processed, with intelligence migrating from centralized platforms toward substations and treatment facilities where millisecond response times matter.
Edge analytics hardware is decentralizing data processing for power substations by embedding inference engines directly within sensor gateways. Mid-sized utilities across the Midwest and Southeast are accelerating deployment of these distributed nodes to reduce bandwidth costs and enable autonomous fault isolation. This architecture is decentralizing the competitive landscape by lowering barriers for regional system integrators to compete against centralized platform providers.
The EU AI Act imposes risk-based compliance requirements on automated decision systems deployed in critical infrastructure contexts. Water treatment operators must now document algorithmic transparency and human oversight protocols for predictive maintenance platforms. European facility managers are responding by demanding explainable AI modules from vendors, reshaping procurement specifications across Germany, France, and the Netherlands.
Subscription-based platform economics are displacing perpetual licensing for multi-site infrastructure operators. Cloud-native monitoring suites with usage-based pricing are capturing preference among municipal utilities managing dispersed generation and distribution assets. This transition is most visible in California and Texas, where deregulated market structures accelerate technology refresh cycles and favor operational expenditure models over capital-intensive on-premises deployments.
Critical Infrastructure Monitoring Market Segmentation
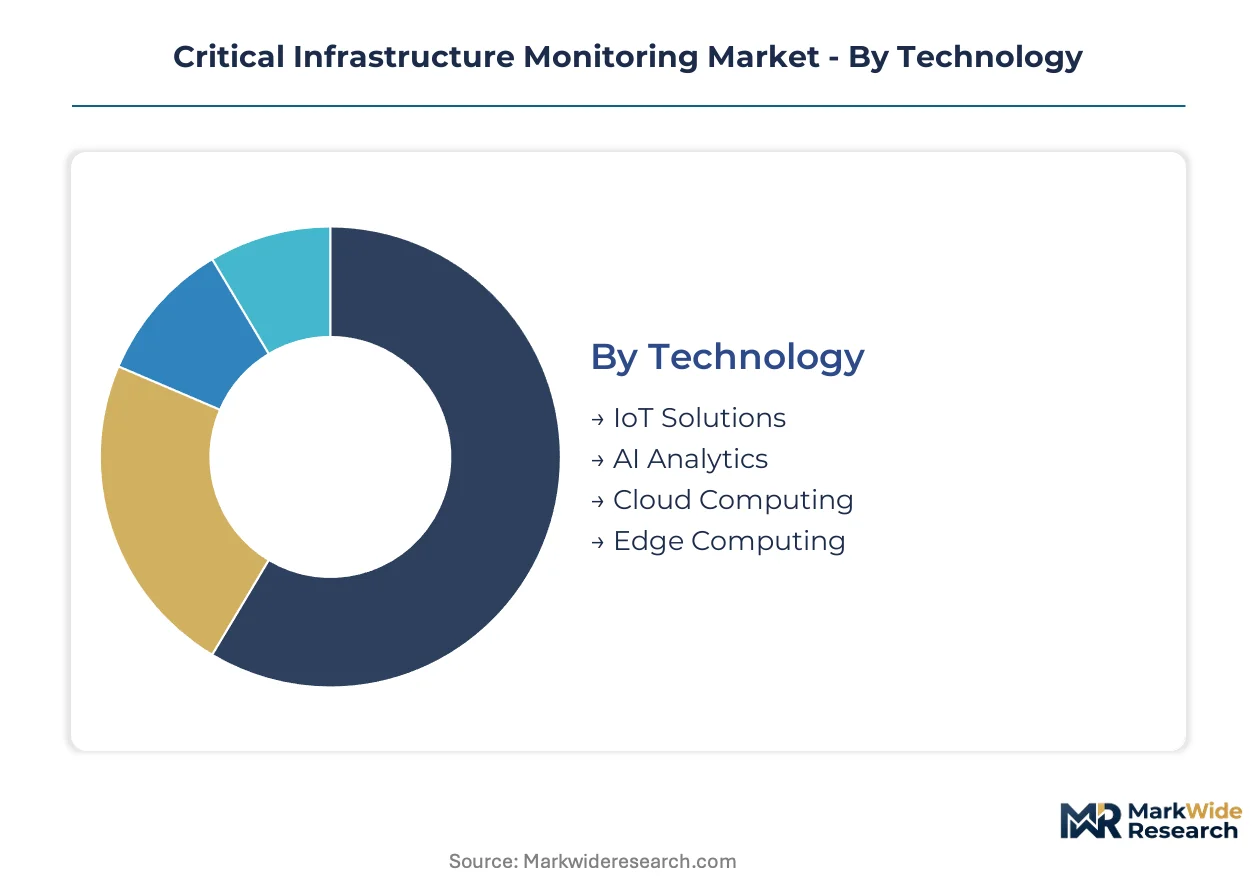
Segmentation reveals how capital allocation priorities diverge across technology layers and operational contexts in critical infrastructure monitoring. Procurement patterns cluster around deployment complexity, with upfront hardware intensity shaping vendor selection criteria and financing structures differently for municipal utilities versus industrial operators.
Technology:
Capital intensity peaks in edge computing deployments requiring localized inference hardware, while cloud computing shifts expenditure toward recurring operational outlays.
- IoT Solutions:Sensor arrays and telemetry hardware operating on standardized protocols deliver sub-second data acquisition from grid and pipeline assets. Demand concentrates in Midwestern US utilities modernizing distribution networks under NERC CIP compliance deadlines. Mature cost curves accelerate procurement velocity for municipal operators with constrained capital budgets.
- AI Analytics:Machine learning platforms automate pattern recognition for asset degradation forecasting across multi-site water treatment operations. German industrial facility operators prioritize these systems to optimize maintenance scheduling and prevent unplanned outages. The EU AI Act's risk-based compliance requirements are reshaping procurement specifications toward explainable algorithmic modules.
- Cloud Computing:Subscription-based platform economics generate recurring revenue from dispersed generation and distribution assets.
- Edge Computing:Embedded inference engines within sensor gateways enable autonomous fault isolation at substations.
Most installed capacity flows through IoT Solutions. Expansion is steepest in AI Analytics.
Application:
Application segmentation tracks where regulatory mandates create non-discretionary procurement obligations versus discretionary performance optimization.
- Energy Management:Continuous monitoring of transmission and distribution networks under FERC-enforced reliability standards. US electric utilities deploy sensor networks across bulk power systems to maintain NERC CIP compliance. Real-time visibility requirements prevent service disruption through predictive intervention.
- Water Supply Monitoring:Real-time quality tracking systems for lead service line replacement mandates. EPA regulatory pressure drives investment in contaminant detection infrastructure. California and Texas municipal utilities favor cloud-native suites with usage-based pricing under deregulated market structures.
- Transportation Systems:Track condition sensors and signaling analytics for European rail corridor modernization.
- Security Surveillance:CISA binding operational directives shape procurement specifications for critical facility perimeter protection.
Regulatory compliance obligations concentrate procurement in Energy Management. Technology refresh cycles accelerate fastest in Water Supply Monitoring.
End User:
End user segmentation distinguishes between rate-regulated entities with predictable capital recovery mechanisms and budget-constrained operators with fragmented decision authority.
- Utilities:Rate-regulated electric and water operators with established capital recovery mechanisms through rate base treatment. Deployment concentrates in transmission and distribution infrastructure where reliability standards mandate continuous coverage. Hybrid architecture preferences are emerging as compliance windows tighten.
- Government Agencies:Federal and state entities managing dispersed critical facilities under CISA security directives. Procurement specifications favor certified security architectures with binding operational compliance.
- Manufacturing:Industrial facility operators in Germany deploying vibration analysis and thermal imaging for predictive maintenance.
- Public Safety Organizations:Emergency response entities requiring real-time infrastructure status for coordinated incident management.
Procurement volume concentrates with Utilities. Technology sophistication requirements climb fastest among Government Agencies.
Deployment:
Deployment segmentation captures the structural trade-off between control retention and operational flexibility that shapes multi-year technology roadmaps.
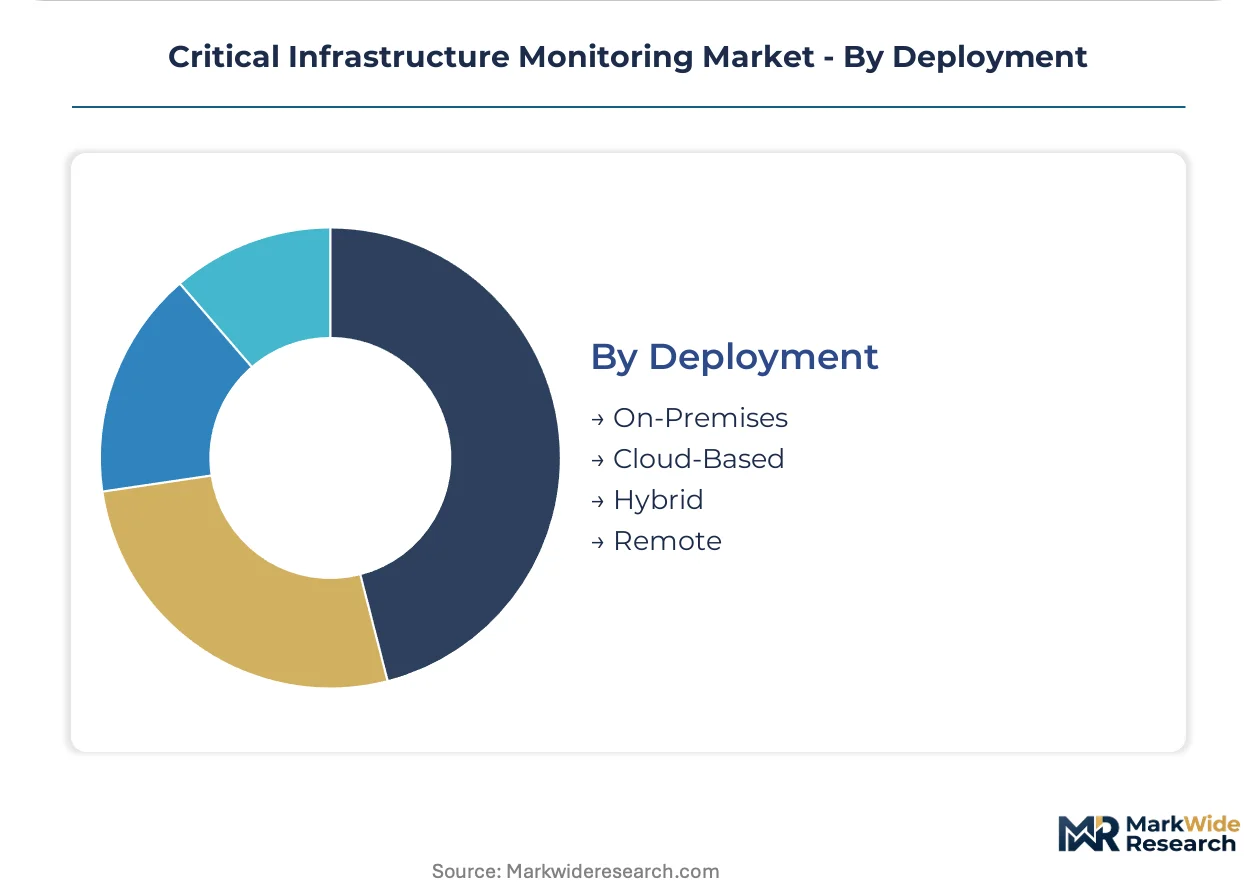
- On-Premises:Full-stack hardware installations with substantial upfront capital requirements and complete data sovereignty. Smaller municipal operators face adoption constraints from concentrated initial outlays compared with hybrid alternatives.
- Cloud-Based:Usage-priced suites eliminating capital intensity in favor of operational expenditure classification. Preference captures municipal utilities in deregulated markets accelerating refresh cycles.
- Hybrid:Architectures balancing control retention with flexibility as regulatory compliance windows tighten.
- Remote:Centralized monitoring configurations for geographically dispersed assets with limited on-site technical personnel.
Legacy infrastructure retains substantial On-Premises deployment. Cloud-Based adoption is gaining share fastest among new procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor location decisions as compliance cost differentials widen between jurisdictions with binding infrastructure mandates and those with advisory frameworks.
United States
FERC-enforced NERC CIP standards compel electric utilities to deploy continuous sensor coverage across transmission networks. The Cybersecurity and Infrastructure Security Agency issues binding operational directives that shape procurement specifications for critical facility operators. Midwestern utilities in Illinois and Ohio are accelerating distribution network modernization under compliance deadlines.
Germany
Industrial facility operators prioritize vibration analysis and thermal imaging systems for predictive maintenance optimization. The EU AI Act imposes risk-based compliance requirements on automated decision systems in critical infrastructure contexts. Manufacturing clusters in Bavaria and Baden-Württemberg are demanding explainable AI modules from platform vendors.
United Kingdom
Water treatment operators are migrating toward cloud-native monitoring suites with usage-based pricing models. The Environment Agency drives investment in real-time quality tracking for aging pipe infrastructure. Municipal utilities in Greater London and the Southeast are favoring operational expenditure models over capital-intensive deployments.
Japan
Transportation infrastructure operators are deploying track condition sensors and signaling analytics for rail corridor modernization. METI guidelines encourage edge computing architectures with embedded inference engines at substations. Industrial corridors in Kanto and Kansai regions are integrating AI-driven pattern recognition for asset degradation forecasting.
India
Central Electricity Authority mandates are accelerating smart grid sensor deployment across state transmission utilities. The Bureau of Indian Standards issues technical specifications for SCADA interface compatibility in critical infrastructure contexts. Manufacturing hubs in Maharashtra and Gujarat are piloting predictive maintenance platforms for industrial facility optimization.
Critical Infrastructure Monitoring Market Competitive Environment
United States-based technology conglomerates anchor one tier; European engineering specialists hold differentiated positions in transportation and industrial verticals. The vendor landscape exhibits moderate concentration with network infrastructure incumbents leveraging installed base advantages against cloud-native challengers. Three archetypes dominate: networking heritage players with edge connectivity dominance, AI-platform specialists with predictive analytics capabilities, and industrial automation incumbents with OT-IT convergence expertise. Competitive intensity manifests through strategic partnerships between sensor manufacturers and cloud platform providers, alongside vertical integration into specialized analytics software.
Within the networking heritage tier, Cisco Systems exemplifies edge connectivity dominance through power substation deployments. Cloud-native monitoring specialists include Datadog and New Relic, which occupy positions emphasizing subscription-based platform economics for multi-site operators. These three companies represent distinct competitive vectors: infrastructure incumbency, cloud-native agility, and observability specialization.
| Leading Market Players |
|---|
| Broadcom |
| New Relic |
| Cisco Systems |
| Bentley Systems |
| Datadog |
| IBM |
| BMC Software |
| Siemens Mobility |
| Hewlett Packard Enterprise |
| Others |
Value Chain & Pricing Dynamics
Edge computing hardware migration to substations and treatment facilities compresses sensor gateway production costs while concentrating semiconductor procurement leverage among East Asian foundries. This technology shift simultaneously reduces bandwidth expenditure for Midwestern utilities and amplifies input cost volatility for regional system integrators competing against centralized platform providers.
Pricing Analysis
Direct-to-utility channel discounts dominate sensor and telemetry hardware transactions, while subscription-based platform economics capture recurring revenue through cloud-native monitoring suites. Three-tier pricing structure across premium AI analytics, standard IoT connectivity, and economy SCADA retrofit modules differentiates procurement tiers. Pricing pressure stems from semiconductor supply concentration constraining production scaling for compliance-driven procurement timelines. Municipal operators in deregulated markets exhibit highest price sensitivity, favoring operational expenditure models over capital-intensive on-premises deployments.
Supply Chain Analysis
Semiconductor fabrication for sensor processors rests on concentrated capacity in Taiwan, South Korea, and mainland China. Critical inputs include MEMS vibration sensors, thermal imaging arrays, and edge inference accelerators. Single-source vulnerability in advanced node chip production exposes manufacturers to geopolitical disruption and input cost volatility. Distribution runs through specialized industrial automation distributors serving utility procurement departments and systems integrators deploying multi-vendor telemetry networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Critical Infrastructure Monitoring Market functions as a stable compounder anchored by non-discretionary regulatory compliance obligations that mandate continuous asset visibility across bulk power systems and water treatment networks.
For Market Incumbents: Cement edge connectivity dominance through backward integration into sensor gateway manufacturing, reducing exposure to East Asian semiconductor supply volatility. Deepen certification investment in CISA-compliant security architectures to defend against cloud-native challengers targeting municipal utilities with hybrid deployment models. For New Entrants and Emerging Players: Launch via usage-based pricing platforms targeting water supply monitoring in deregulated US markets where technology refresh cycles accelerate operational expenditure preferences. Penetrate European rail corridor transportation infrastructure where legacy network modernization demands track condition sensors and signaling analytics with limited incumbent saturation. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with OT-IT convergence expertise and established utility relationships. Long-term viability centers on acquisition targets possessing certified security architectures and explainable AI capabilities aligned with EU AI Act risk-based compliance requirements. Monitor CISA binding operational directive expansion as inflection signal for procurement specification shifts favoring qualified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies SCADA interfaces with cloud-native analytics for NERC CIP-compliant utilities. |
| Backward Integration | Captures sensor gateway manufacturing to mitigate East Asian semiconductor supply concentration. |
| Strategic Partnership | Combines Cisco's edge connectivity with IBM's AI analytics for water treatment facilities. |
| Acquisition of Specialist Firm | Absorbs explainable AI modules required by EU AI Act risk-based compliance mandates. |
| Geographic Expansion | Targets German industrial clusters prioritizing vibration analysis and thermal imaging systems. |
Study Parameters
Direct dialogue with utility planning officers, OT-IT integration specialists, CISA compliance consultants, and industrial automation procurement directors grounded qualitative findings. Secondary validation drew from FERC reliability standard filings, EPA lead service line replacement mandates, NERC CIP enforcement documentation, and EIA grid modernization expenditure data. Bottom-up sensor deployment estimates triangulated against top-down infrastructure investment projections across the analysis window.
Segmentation outputs reflect technology layer differentiation across IoT Solutions, AI Analytics, Cloud Computing, and Edge Computing, crossed with application context in Energy Management, Water Supply Monitoring, Transportation Systems, and Security Surveillance. End-user archetypes modeled rate-regulated utilities, government agencies, manufacturing operators, and public safety organizations. Deployment mode segmentation captured on-premises, cloud-based, hybrid, and remote configurations. CAGRs derived from regulatory compliance deadline clustering and technology refresh cycle velocity across deregulated versus rate-regulated markets.
Several conditions sit outside the modeled scope, including unforeseen cybersecurity incidents triggering emergency procurement suspensions, abrupt shifts in FERC enforcement posture, and supply chain disruptions exceeding historical semiconductor volatility patterns. Forecasts embed assumptions regarding NERC CIP compliance timeline adherence and EU AI Act implementation sequencing. A small set of named triggers warrants ongoing watch: CISA directive expansion scope, East Asian foundry capacity allocation shifts, and municipal utility bankruptcy filings affecting technology refresh funding.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Global Threat Intelligence Platform Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Middle East and Africa Explosion-Proof Equipment Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Asia Pacific Tank Protection Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market