
 Spain Fox Nuts Market | 2026-2036
Spain Fox Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Fox Nuts Market Insights
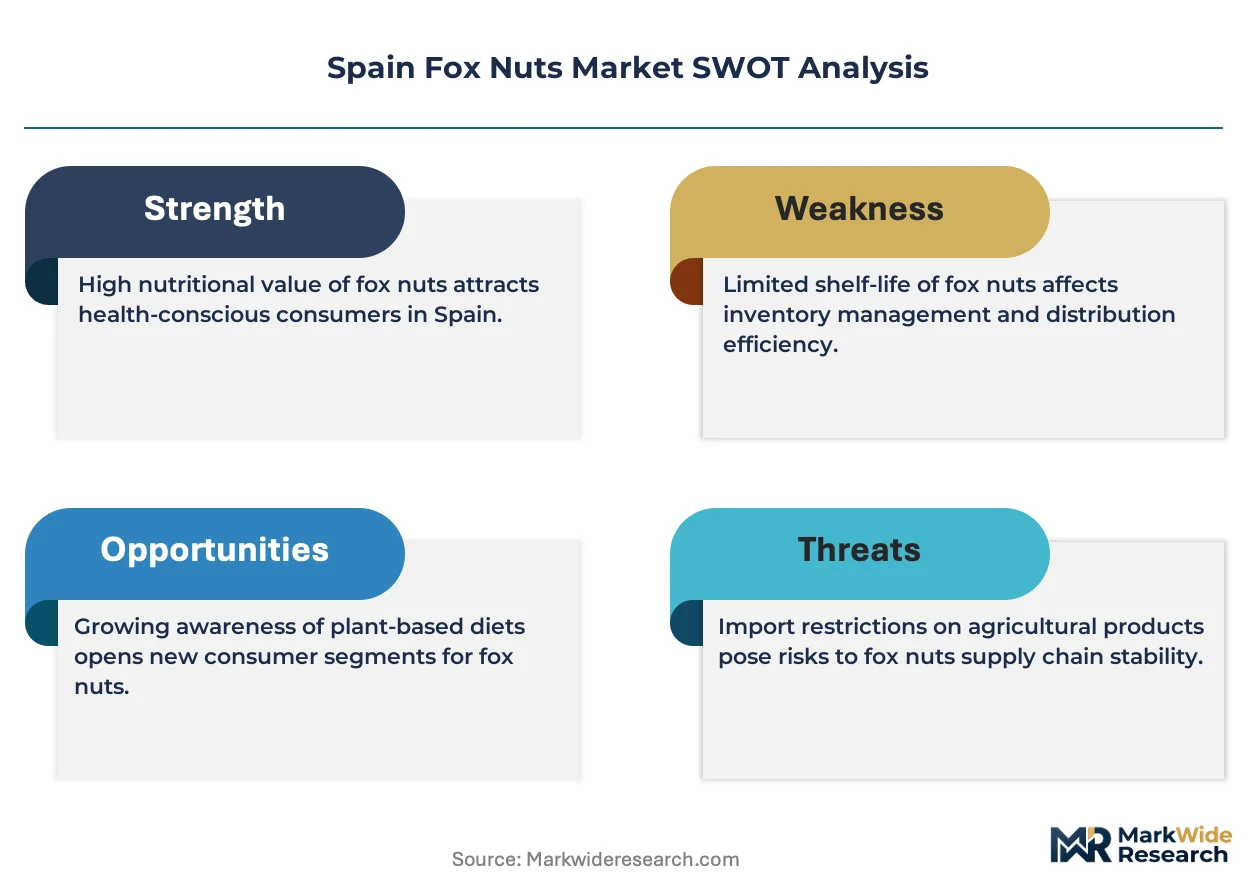
Single-serve pouch configurations is broadening buyer choice across convenience and premium tiers. Sattviko leverages its roasted product specialization to occupy shelf space in Spanish health food channels. Madhubani Makhana Private Limited anchors supply reliability through backward integration into Bihar's cultivation belt. Caryopses Pvt. Ltd. differentiates via organic certification pipelines that navigate EU import compliance.
Fox nuts, or Euryale ferox seeds, comprise starch-rich kernels harvested from aquatic plants and processed through sun-drying, roasting, or puffing to achieve a crunchy texture; they serve as gluten-free snack ingredients and ayurvedic functional foods. Roasted variants lead volume due to familiar flavor profiles, while organic SKUs capture expanding margin pools as Spanish retailers prioritize clean-label assortment. Specialty stores sustain premium pricing power for flavored lines, though online channels register the fastest route-to-market expansion.
Spain's national food safety regulator enforces EU-wide maximum residue limits on mycotoxins in dried nuts and seeds, compelling importers to maintain laboratory documentation at port of entry. BIS-equivalent standards from origin countries plus EU organic certification under ECO-EU regulation shape product eligibility for Spanish shelves. Stakeholders must monitor evolving novel food classification rulings that could reclassify fox nut extracts beyond conventional snack use.
Market Dynamics
Spain's fox nuts market operates under intense regulatory scrutiny from the country's national food safety authority, which enforces EU-wide aflatoxin thresholds that reshape import documentation requirements and laboratory testing protocols at Spanish ports.
Growth Catalysts
- EU Organic Certification (ECO-EU):Clean-label mandates from Spanish retailers accelerate shelf access for certified organic fox nut SKUs, widening margin capture for compliant importers.
- Functional Snack Demand:Madrid and Barcelona's premium retail corridors channel millennial purchasing power toward roasted and puffed variants positioned as gluten-free alternatives.
- Single-Serve Pouch Formats:Packaging innovation across convenience and premium tiers broadens consumption occasions from on-the-go snacking to gourmet gifting.
Market Restraints
- Input Cost Volatility:Sun-drying and roasting energy requirements expose processors to natural gas price swings across Spain's industrial zones.
- Supply Concentration Risk:Dependence on Bihar's cultivation belt for raw Euryale ferox seeds creates geographic single-point vulnerability for Spanish importers.
- Aflatoxin Testing Burden:EFSA-mandated maximum residue limits impose recurring laboratory costs that compress margins for small-scale distributors.
Strategic Opportunities
- Andalusia Expansion:Underpenetrated southern Spanish provinces present white-space potential for specialty store penetration beyond Madrid-Barcelona axis.
- Ayurvedic Positioning:Functional food classification under novel food rulings could unlock pharmacy and wellness channel placement for fox nut extracts.
- Direct-to-Consumer Channels:E-commerce fulfillment models bypass traditional retail slotting fees while capturing consumer preference data.
Industry Challenges
- Certification Timeline Compression:ECO-EU organic audits and BIS-equivalent origin documentation create 90-120 day port clearance delays.
- Skill Gap in Mycotoxin Analysis:Laboratory technicians trained in EU-compliant aflatoxin detection remain scarce across Spain's import inspection infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Fox Nuts Market |
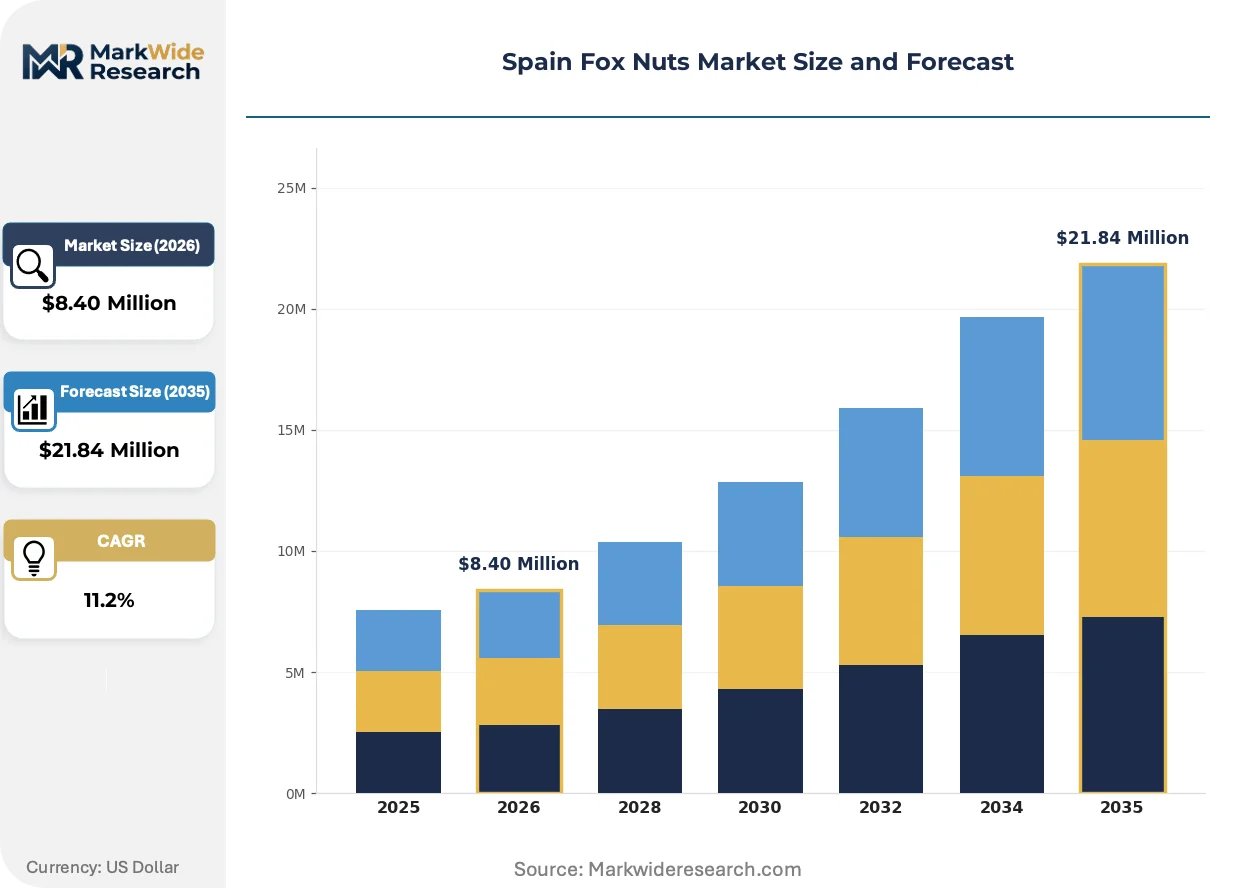
| Market Size in 2026 | $8.40 Million |
| Market Size in 2035 | $21.84 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roasted, Salted, Organic, Flavored End User: Food Manufacturers, Retailers, Food Service, Health Stores Sales Channel: Online, Supermarkets, Health Food Stores, Specialty Stores Packaging Type: Bags, Pouches, Tins, Bulk |
| Companies Covered | Manju Makhana, Caryopses Pvt. Ltd., Shaktisudha Makhana, Makhana Amrit Mantra Pte. Ltd., Hindustan Foreign Traders Group, K.K. Products, Sattviko, Madhubani Makhana Private Limited, Maruti Makhana, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Fox Nuts Market Trends and Innovations
Product format diversification and regulatory compliance automation are actively reshaping competitive positioning in Spain's fox nuts landscape. Spanish stakeholders now prioritize traceability infrastructure and clean-label certification pipelines.
Advanced roasting control systems is expanding into mid-scale processing facilities, enabling precise temperature modulation that preserves starch integrity while eliminating moisture variability. Madrid-based health food distributors adopt these systems to meet EFSA documentation standards. The technology is expanding into quality assurance protocols that reduce batch rejection rates at Spanish customs.
Spain's national food safety authority alignment with EFSA mycotoxin surveillance programs tightens inspection frequency for dried aquatic seeds. Industrial consequence includes mandatory pre-shipment laboratory certificates from origin-country facilities. Organic importers respond by embedding third-party auditors into Bihar supply chains before container loading.
Spanish millennial buyers now prioritize subscription-based replenishment models over conventional retail purchasing for functional snacks. Specialty e-commerce platforms displace traditional gourmet store distribution in Barcelona's metropolitan area. This behavioral pivot concentrates most visible demand rotation within Catalonia's urban consumer base.
Spain Fox Nuts Market Segmentation
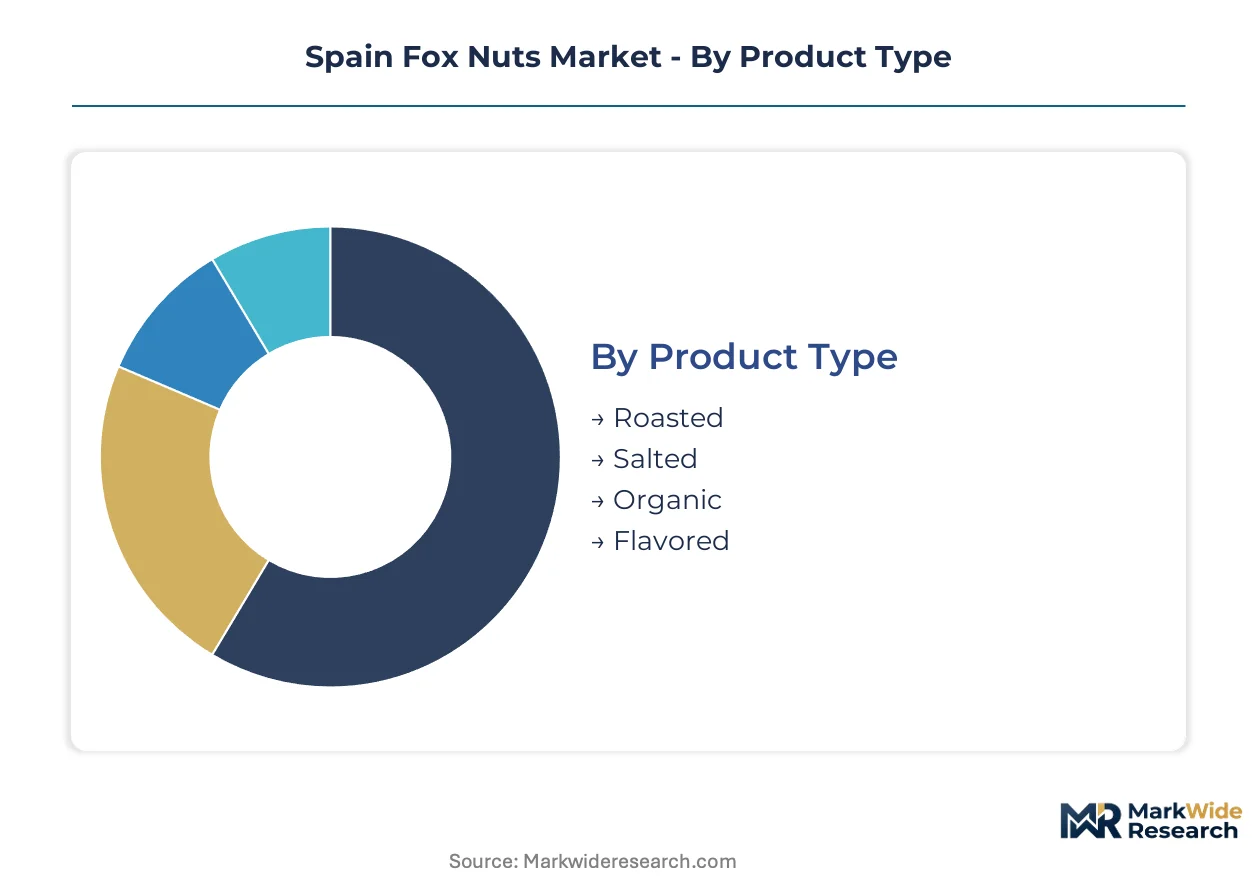
Segmentation in Spain's fox nuts market reveals how supply chain configuration, regulatory compliance burdens, and channel-specific margin structures fragment commercial opportunity. Distinct buyer requirements across product formats, end-use applications, and distribution pathways force importers to maintain parallel certification pipelines and inventory positions.
Product Type:
Supply concentration in Bihar's cultivation belt funnels raw Euryale ferox seeds through divergent processing pathways that determine final product positioning and margin capture.
- Roasted:Thermal processing at controlled temperatures preserves starch integrity while developing familiar flavor profiles that dominate Madrid and Barcelona retail corridors. Madrid-based health food distributors deploy advanced roasting control systems to meet EFSA documentation standards and reduce batch rejection rates at Spanish customs.
- Organic:ECO-EU certification mandates shape product eligibility for Spanish shelves, with clean-label priorities from retailers widening margin capture for compliant importers. Spanish stakeholders embed third-party auditors into Bihar supply chains before container loading to compress certification timelines.
- Salted:Sodium-enhanced variants occupy mid-tier convenience positioning with simpler regulatory pathways than organic alternatives.
- Flavored:Specialty formulations targeting gourmet gifting occasions sustain premium pricing power in Barcelona's metropolitan specialty stores.
Roasted variants absorb the bulk of installed capacity; organic SKUs are expanding most quickly.
End User:
Cost tier differentiation separates volume-driven commodity buyers from premium channel operators willing to absorb higher per-unit input costs for certification compliance.
- Retailers:Supermarket and specialty store buyers prioritize single-serve pouch configurations and ECO-EU certification to satisfy clean-label mandates. Barcelona's premium retail corridors channel millennial purchasing power toward compliant product lines.
- Health Stores:Madrid-based health food distributors demand laboratory documentation at port of entry and advanced roasting control systems that preserve functional food characteristics. These buyers capture expanding margin pools as Spanish retailers prioritize clean-label assortment.
- Food Manufacturers:Industrial buyers source bulk formats for ingredient applications in gluten-free snack formulations.
- Food Service:Hospitality channels favor roasted variants for familiar flavor integration into existing menu architectures.
Retailers absorb the bulk of installed capacity; health stores are climbing the fastest.
Sales Channel:
Volume concentration in established retail infrastructure contrasts with rapid expansion in direct-to-consumer fulfillment models that bypass traditional slotting fees.
- Online:Subscription-based replenishment models concentrate demand rotation within Catalonia's urban consumer base, with specialty e-commerce platforms displacing traditional gourmet store distribution. These channels capture consumer preference data while circumventing Madrid-Barcelona retail corridor concentration.
- Specialty Stores:Barcelona's metropolitan area sustains premium pricing power for flavored lines and gourmet gifting formats. Physical inspection capabilities reduce aflatoxin-related rejection risks compared to bulk import channels.
- Supermarkets:Mass retail slotting fees compress margins for small-scale distributors navigating EFSA-mandated testing burdens.
- Health Food Stores:Madrid-based distributors in this channel prioritize ECO-EU certification and traceability infrastructure.
Specialty stores absorb the bulk of installed capacity; online channels are gaining share fastest.
Packaging Type:
Customer type segmentation separates convenience-oriented single-serve buyers from institutional purchasers managing inventory turnover and moisture control requirements.
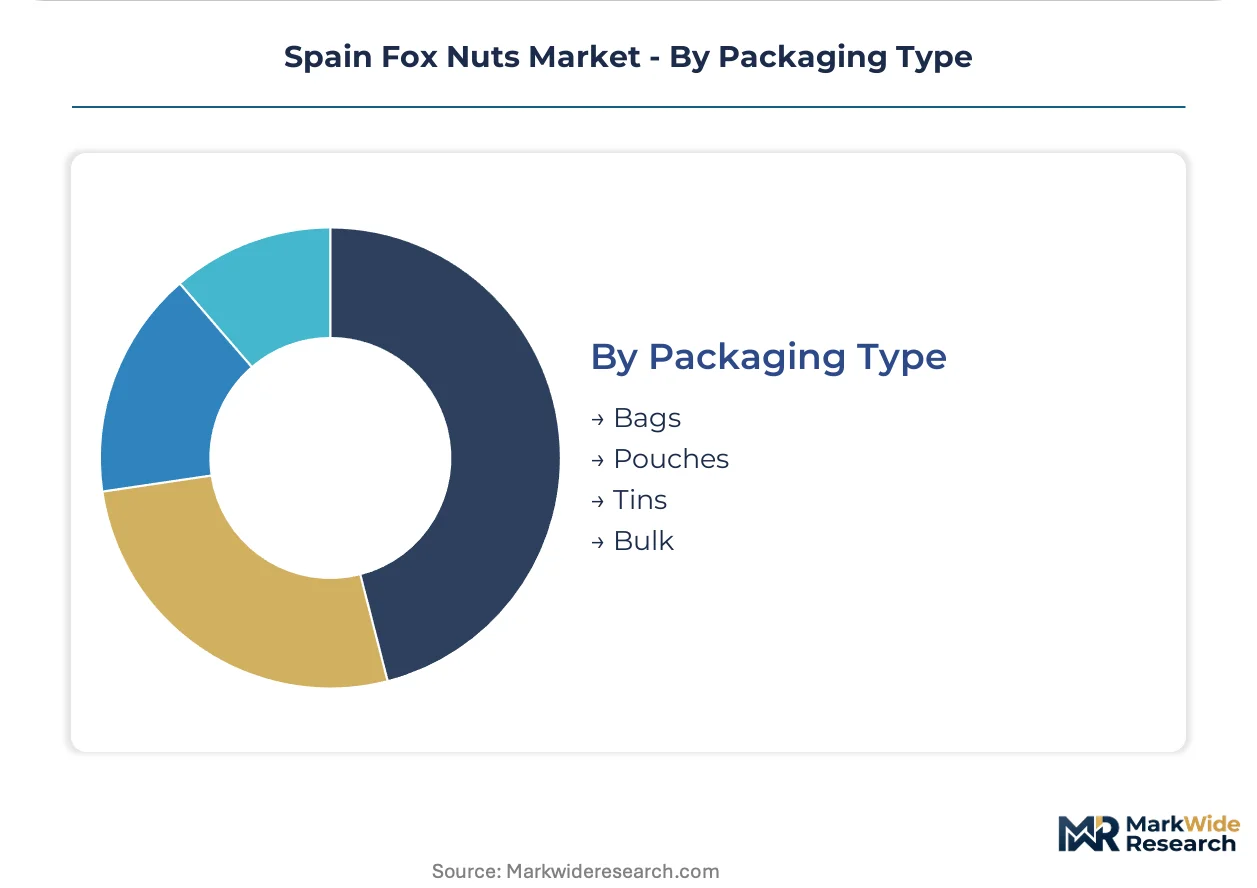
- Pouches:Single-serve configurations broaden consumption occasions from on-the-go snacking to gourmet gifting across convenience and premium tiers. Flexible packaging formats accommodate the moisture variability challenges inherent in sun-dried Euryale ferox processing.
- Bulk:Industrial and food service buyers prioritize cost efficiency and custom roasting specifications over retail-ready presentation. These formats face elevated aflatoxin surveillance frequency under EFSA alignment with Spain's national food safety authority.
- Bags:Mid-tier retail packaging balances shelf visibility with material cost constraints.
- Tins:Premium gifting formats command position in specialty store assortments targeting Barcelona's metropolitan consumer base.
Pouches absorb the bulk of installed capacity; bulk formats are expanding most quickly in food service penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain produces negligible quantities of Euryale ferox seeds, forcing the market to rely entirely on Indian imports from Bihar's cultivation belt. This structural dependency shapes regional demand patterns across Spanish sub-markets.
Madrid
Health-conscious millennials drive roasted fox nut consumption through premium retail corridors and health food distributors. EFSA-mandated aflatoxin documentation requirements create port clearance bottlenecks at Madrid's logistics hubs. Advanced roasting control systems preserve starch integrity for functional food positioning.
Catalonia
Barcelona's metropolitan area channels subscription-based replenishment models through specialty e-commerce platforms displacing traditional gourmet stores. Catalonia's urban consumer base prioritizes single-serve pouch configurations for on-the-go snacking. Local distributors embed third-party auditors into Bihar supply chains before container loading.
Basque Country
Industrial food manufacturers in Bilbao-San Sebastián corridor source bulk formats for gluten-free snack ingredient applications. ECO-EU organic certification pipelines face compressed timelines due to 90-120 day audit requirements. Mid-scale processors deploy precision temperature modulation to reduce batch rejection rates.
Andalusia
Underpenetrated southern provinces present white-space expansion potential beyond the Madrid-Barcelona axis. Seville and Málaga retail infrastructure remains nascent for specialty store penetration. Regional distributors navigate Spain's national food safety authority alignment with EFSA mycotoxin surveillance programs.
Valencia
Levante region's hospitality channels favor roasted variants for menu integration into existing culinary architectures. Food service buyers prioritize cost efficiency over retail-ready presentation. Valencia's import inspection infrastructure exhibits skill gaps in EU-compliant aflatoxin detection protocols.
Spain Fox Nuts Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's fox nuts landscape. The vendor base fragments between Indian-origin suppliers controlling raw material access and European distributors managing compliance navigation. Three archetypes dominate: backward-integrated cultivator-processors, certification-specialized exporters, and channel-focused brand builders. Competitive moves concentrate on organic certification pipeline construction and direct-to-consumer channel development.
Among Indian-origin suppliers, Madhubani Makhana Private Limited and Caryopses Pvt. Ltd. exemplify divergent strategic positioning. Madhubani Makhana anchors supply reliability through captive cultivation control in Bihar's production belt. Caryopses occupies the compliance-specialist tier, navigating ECO-EU organic certification requirements for Spanish shelf access. Sattviko represents the brand-builder archetype, leveraging roasted product specialization to secure health food channel placement.
| Leading Market Players |
|---|
| Manju Makhana |
| Caryopses Pvt. Ltd. |
| Shaktisudha Makhana |
| Makhana Amrit Mantra Pte. Ltd. |
| Hindustan Foreign Traders Group |
| K.K. Products |
| Sattviko |
| Madhubani Makhana Private Limited |
| Maruti Makhana |
| Others |
Pricing and Supply Chain Analysis
ECO-EU certification tiers create a three-tier pricing structure across premium, standard, and economy levels that both reflects and reinforces supply chain control patterns. Premium organic SKUs command shelf access through Bihar-embedded audit infrastructure, while commodity roasted variants compete on port clearance speed and energy cost absorption at Spanish processing nodes.
Pricing Analysis
Margin tightening in organic tiers reflects EFSA-mandated laboratory documentation burdens and 90-120 day certification timelines. Price differentiation separates ECO-EU certified SKUs from conventional alternatives through clean-label retailer mandates. Cost-down pressure on bulk formats accelerates because natural gas price volatility across Spain's industrial zones compresses roasting margins. Health food distributors in Madrid exhibit lowest price sensitivity; convenience channel buyers in mass retail show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Bihar's cultivation belt, where Euryale ferox seed production feeds entirely into Spanish import demand. Raw material flows draw from captive farming networks, third-party aggregator channels, and spot market procurement. Tariff exposure emerges from EU-India trade agreement renegotiation risks. Distribution runs through Madrid-Barcelona logistics corridors before radiating to Andalusian white-space territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EFSA mycotoxin surveillance programs and certification timeline compression force sub-scale distributors toward exit or acquisition. Regulatory compliance automation investments separate viable competitors from margin-compressed laggards.
For Market Incumbents: Hedge against supply disruption by embedding third-party auditors into Bihar cultivation networks before container loading. Secure roasting capacity in Madrid industrial zones to preserve starch integrity documentation for health food channel retention. Backward integration into sun-drying cooperatives reduces batch rejection exposure at Spanish customs. For New Entrants and Emerging Players: Launch via subscription-based e-commerce platforms targeting Catalonia's urban consumer base for fastest route-to-market validation. Prioritize Andalusian specialty store penetration where Madrid-Barcelona corridor concentration remains weakest. Lead with single-serve pouch configurations to bypass mass retail slotting fee barriers. For Investors and Strategic Acquirers: Re-rating potential sits with compliance-specialist exporters given ECO-EU organic certification pipeline scarcity. Five-to-ten year viability hinges on traceability infrastructure ownership rather than commodity trading margins. Watch for novel food classification rulings on fox nut extracts as pharmacy channel placement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ECO-EU Certification Pipeline Buildout | Clean-label mandates from El Corte Inglés and Carrefour España accelerate shelf access for compliant importers. |
| Direct-to-Consumer Channel Launch | Subscription models bypass traditional retail slotting fees while capturing millennial preference data in Barcelona. |
| Andalusian Distribution Expansion | Seville and Málaga retail infrastructure gaps present first-mover advantage for specialty store penetration. |
| Advanced Roasting Control System Deployment | Madrid-based processors reduce EFSA batch rejection rates through precise temperature modulation technology. |
| Third-Party Supply Chain Audit Integration | Pre-shipment Bihar verification compresses 90-120 day port clearance timelines for organic SKUs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Spanish health food distributors, Madrid-based import compliance officers, and Bihar cultivation cooperative managers combined with EFSA surveillance reports, ECO-EU certification databases, and Indian agricultural export statistics. Bottom-up volume modeling and top-down value reconciliation triangulated market size estimates.
Data-stream reconciliation across product type, end user category, sales channel, and packaging format dimensions generated segment-level projections over the analysis window. CAGRs derived from historical import velocity analysis and forward-looking retailer assortment expansion plans. Roasted variant penetration rates and organic SKU margin expansion served as industry-specific forecast inputs.
EFSA regulatory reinterpretation, Bihar crop yield volatility, and EU-India trade policy shifts are the dominant revision risks for these projections. Deviation in ECO-EU audit timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
Cashew Nut Butter Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
Walnut Market
Nuts and Seeds
North America Moringa Products Market
Nuts and Seeds
Pistachios Market