
 United States Facility Management Market | 2026-2036
United States Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
United States Facility Management Market Analytics
Skilled trades shortages across HVAC, electrical, and building automation is reorganizing how facility services are procured and delivered across the United States. CBRE Group leverages its national property management footprint to bundle maintenance with lease administration. Emcor Group Inc. sustains market presence through in-house technical staffing and vertical capabilities in mechanical and electrical systems. Sodexo Inc. differentiates via integrated food and facilities service contracts anchored in healthcare and education campuses.
Facility management encompasses the operational oversight of buildings and infrastructure, integrating maintenance scheduling, energy systems management, security protocols, and space utilization analytics to ensure safe, efficient, and compliant environments for occupants. The discipline relies on computerized maintenance management systems (CMMS), IoT sensor networks, and automated building controls to monitor equipment health and optimize resource consumption across portfolios. The outsourced delivery model leads in revenue contribution as corporations shed fixed labor costs, while managed services and hybrid arrangements are gaining fastest among mid-market enterprises seeking flexibility without full capital commitment. Janitorial and maintenance services occupy the mature core of the service type mix, though energy management and security segments attract higher-margin technology-enabled contracts.
OSHA mandates drive systematic safety audits and training investments, while EPA energy standards push building owners toward retrofitting and smart system upgrades that expand addressable demand for technical facility services. State-level codes in California and New York layer additional efficiency and emissions requirements that filter into procurement specifications. Stakeholders must weigh in-house capability depth against outsourced flexibility as compliance complexity and technology integration requirements intensify.
Market Dynamics
Workforce scarcity across skilled trades is compressing service delivery timelines and forcing facility operators toward technology-augmented staffing models and predictive maintenance platforms that reduce labor dependency.
Growth Catalysts
- Healthcare Outsourcing Wave:Hospital systems are consolidating non-clinical operations into bundled facilities contracts that combine maintenance, food service, and environmental management under single-vendor accountability.
- EPA Energy Mandates:Building performance standards in California and New York are mandating retrofits that expand demand for energy management services and smart building integration expertise.
- IoT Sensor Networks:Real-time equipment monitoring is reducing unplanned downtime and enabling condition-based maintenance schedules that optimize technician deployment across dispersed portfolios.
Market Restraints
- Labor Cost Escalation:Wage compression in HVAC and electrical trades is eroding margin structures for service providers operating on fixed-price maintenance agreements.
- Supply Chain Concentration:Building automation hardware depends heavily on semiconductor components sourced through concentrated Asian manufacturing corridors vulnerable to disruption.
- Technical Debt Burden:Legacy pneumatic controls and proprietary BAS protocols in older commercial stock impede seamless integration with cloud-based analytics platforms.
Strategic Opportunities
- Mid-Market Hybrid Models:Enterprises with 500,000 to 2 million square feet of space are adopting managed service arrangements that blend outsourced expertise with retained in-house oversight capabilities.
- IRA Tax Incentives:Federal energy-efficiency credits are accelerating building electrification projects that require specialized commissioning and ongoing optimization services.
- Convergence of CMMS and IWMS:Integration between computerized maintenance management and integrated workplace management systems is creating unified data layers for space and asset optimization.
Industry Challenges
- Certification Pipeline Collapse:Apprenticeship completion rates in stationary engineering and building trades are failing to replace retiring journeyman technicians.
- System Integration Friction:Disparate data protocols between security, HVAC, and lighting controls require costly middleware development for unified dashboard visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Facility Management Market |
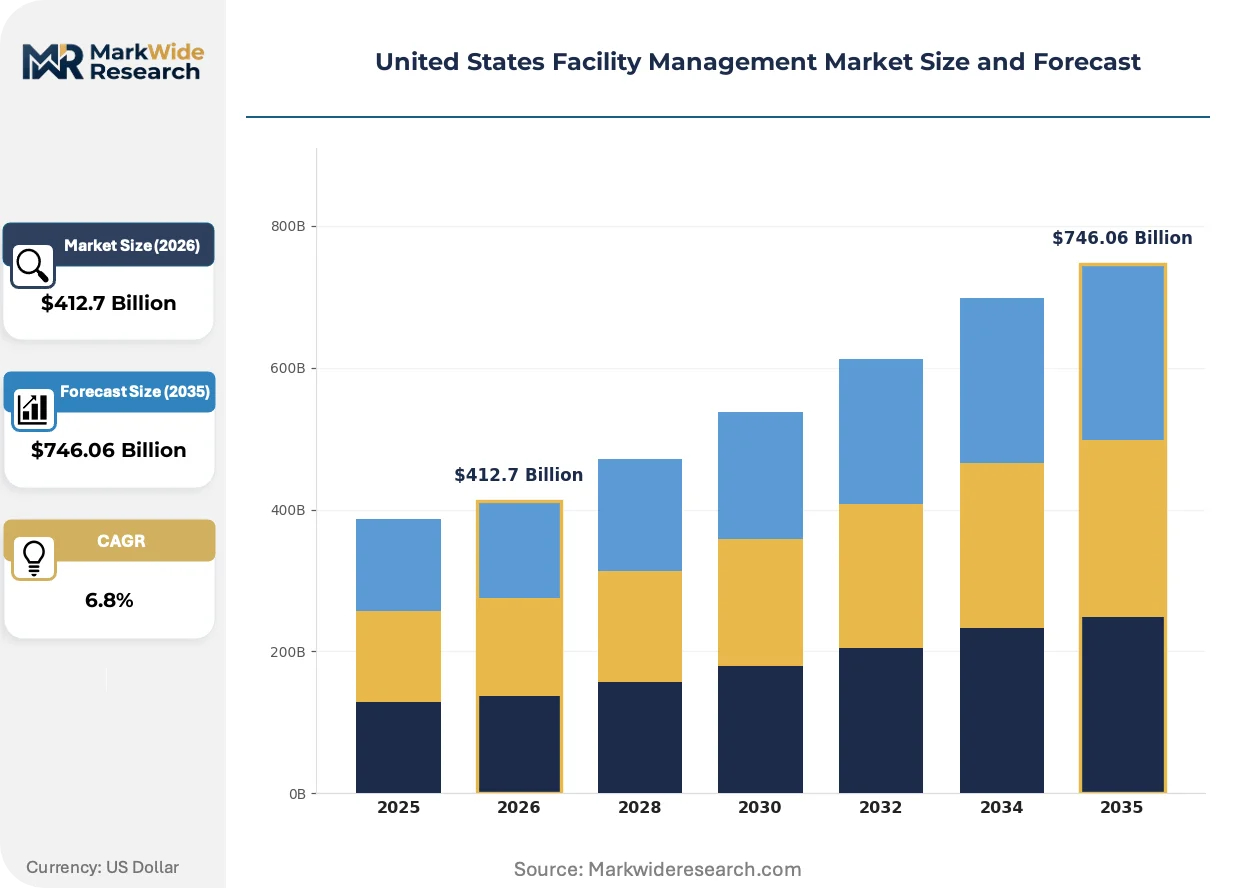
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $746.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Janitorial, Maintenance, Security, Landscaping End User: Commercial, Education, Healthcare, Government Delivery Model: In-House, Outsourced, Hybrid, Managed Services Technology: IoT Solutions, CMMS, Energy Management, Automation |
| Companies Covered | Emcor Group Inc., ISS Facility Services Inc., CBRE Group, Kellermeyer Bergensons Services, Sodexo Inc., Jones Lang LaSalle Incorporated, Cushman & Wakefield plc, MaintenX, ABM Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Facility Management Market Evolving Landscape
Digital twin technology and edge computing architectures are redefining how facility data is collected, processed, and actioned across distributed building portfolios. These shifts are compressing response times and enabling autonomous building operations.
Edge-based analytics hardware is miniaturizing to enable localized processing of sensor data without cloud dependency, reducing latency for critical equipment alerts. Large commercial portfolios in Texas and Florida are deploying these units at scale to monitor chiller plants and electrical distribution. The technology is miniaturizing the physical footprint of building automation controllers while expanding computational capacity for predictive algorithms.
OSHA's updated workplace safety enforcement protocols are mandating documented hazard assessments and corrective action tracking across all covered facilities. Building owners are responding by embedding safety compliance modules into CMMS workflows. Healthcare campuses and industrial warehouses face the steepest compliance burden and are prioritizing vendors with certified safety management systems.
Corporate real estate teams are unbundling bundled service contracts to purchase janitorial, maintenance, and energy management through separate specialist providers. This disaggregation allows granular performance benchmarking and competitive rebidding of individual service lines. Technology and financial services tenants in urban cores are driving this pattern most aggressively as they seek transparent unit-cost visibility.
United States Facility Management Market Segmentation
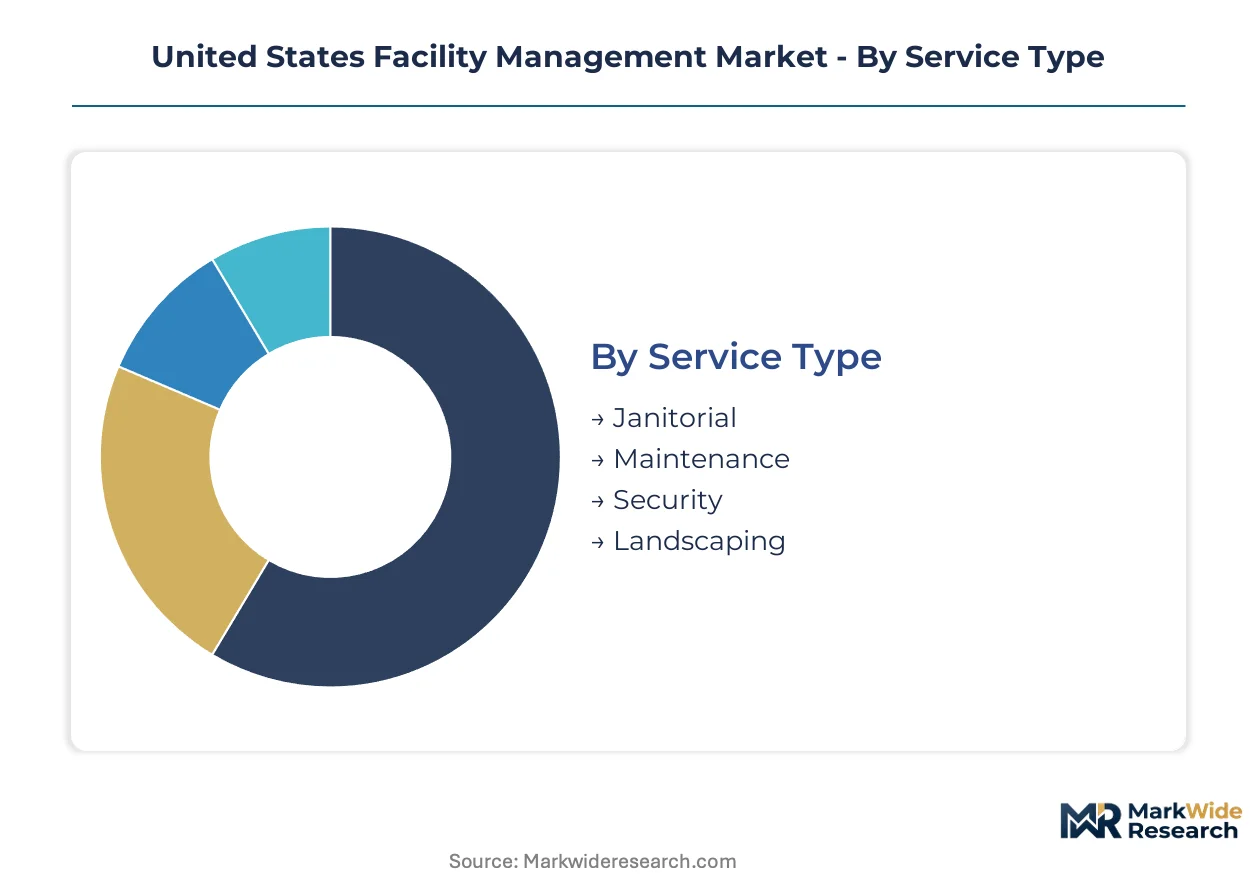
Facility management procurement in the United States fragments across service lines, end-use sectors, delivery structures, and technology stacks. Each segmentation axis reveals distinct margin profiles and competitive dynamics that shape vendor positioning and contract economics.
Service Type:
Margin concentration sits in technology-enabled services where specialized expertise commands pricing power over commoditized labor pools.
- Janitorial:Labor-intensive cleaning and sanitation operations dominate contract volume but face persistent margin compression from wage escalation and competitive bidding. Demand clusters in healthcare campuses and Class A office towers in Texas and Florida where infection-control protocols justify premium pricing tiers.
- Maintenance:HVAC, electrical, and mechanical systems upkeep generates the highest per-square-foot revenue rates due to technical certification requirements and emergency response liabilities. Hospital expansions in California and Florida are driving demand for predictive maintenance contracts that bundle sensor monitoring with technician dispatch.
- Security:Integrated access control, surveillance, and guard services serve data centers and government facilities with stringent compliance mandates.
- Landscaping:Grounds maintenance and snow removal contracts exhibit seasonal revenue volatility and lower technology penetration.
The dominant share belongs to Janitorial, while Maintenance is closing the gap fastest.
End User:
Application intensity varies sharply across sectors, with compliance burdens and asset complexity determining service premium levels.
- Commercial:Office buildings, retail centers, and mixed-use developments constitute the volume base, with corporate real estate teams unbundling services for granular cost visibility. Financial services tenants in urban cores are driving disaggregation of bundled contracts into specialist procurement.
- Healthcare:Hospitals and outpatient clinics impose the steepest technical and regulatory requirements, from Joint Commission accreditation to OSHA bloodborne pathogen protocols. EPA energy mandates and infection-control standards expand addressable demand for integrated facilities management.
- Education:K-12 districts and university campuses balance budget constraints against deferred maintenance backlogs, favoring multi-year outsourcing agreements.
- Government:Federal, state, and municipal facilities operate under procurement regulations that extend vendor selection timelines but offer contract stability.
Commercial commands the largest footprint, yet Healthcare is expanding most quickly as systems consolidate non-clinical operations.
Delivery Model:
Customer type determines capital commitment tolerance, with mid-market enterprises seeking flexibility without full infrastructure ownership.
- In-House:Direct employment of maintenance staff persists in specialized industrial and research facilities where proprietary knowledge retention outweighs cost efficiency. Legacy commercial stock in the Northeast maintains substantial in-house engineering departments.
- Outsourced:Third-party contracts dominate revenue contribution as corporations shed fixed labor costs and benefit obligations. CBRE Group and Emcor Group capture share through national scale and technical verticals.
- Hybrid:Blended arrangements retain strategic oversight in-house while outsourcing transactional work are gaining fastest among 500,000 to 2 million square foot enterprises. This model balances control with variable cost structures.
- Managed Services:Outcome-based contracts with performance guarantees are emerging in sophisticated portfolios seeking risk transfer.
Outsourced delivery holds the prevailing position, while Hybrid arrangements are gaining share fastest.
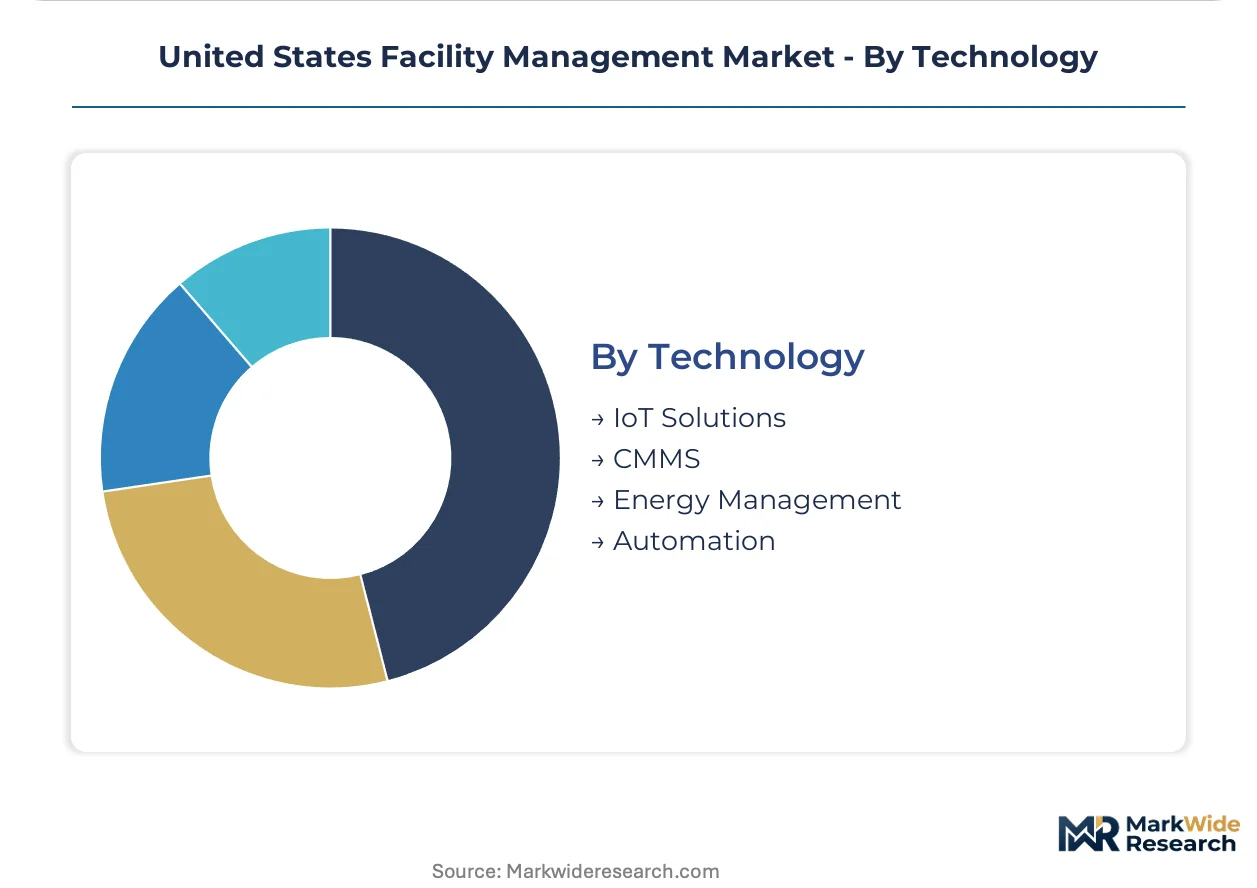
Technology:
Supply concentration in building automation hardware shapes integration complexity and vendor lock-in risks.
- IoT Solutions:Sensor networks for equipment monitoring and environmental tracking enable condition-based maintenance and reduce unplanned downtime. Texas and Florida portfolios deploy edge-based analytics at scale for chiller plant and electrical distribution monitoring.
- CMMS:Computerized maintenance management systems form the operational backbone for work order dispatch, asset tracking, and compliance documentation. OSHA safety enforcement protocols are embedding hazard assessment modules into CMMS workflows.
- Energy Management:Smart metering, demand response, and electrification optimization services attract premium margins under IRA tax incentives and state-level building performance standards.
- Automation:Building automation system integration and digital twin deployment compress response times for autonomous operations.
CMMS anchors current deployment, while Energy Management is climbing the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management procurement patterns diverge sharply across U.S. sub-regions, with coastal states prioritizing energy compliance and technology integration while Sun Belt markets emphasize scale-driven outsourcing for expanding commercial and healthcare footprints.
California
Hospital expansions in Los Angeles and San Diego metro areas are consolidating non-clinical operations into bundled facilities contracts. EPA energy-efficiency codes and state-level building performance standards mandate smart system retrofits that expand demand for energy management services. The San Francisco Bay Area's technology and financial services tenants are driving contract disaggregation for granular cost visibility.
Texas
Commercial building stock growth in Dallas-Fort Worth and Houston is concentrating outsourced maintenance demand among national providers with technical verticals. OSHA workplace safety enforcement protocols require documented hazard assessments across industrial warehouses and healthcare campuses. Edge-based analytics hardware deployment at scale is monitoring chiller plants and electrical distribution in Austin and San Antonio corridors.
Florida
Healthcare facility construction in Miami, Tampa, and Orlando is accelerating predictive maintenance contracts that bundle IoT sensor monitoring with technician dispatch. Infection-control protocols in hospital systems justify premium pricing tiers for janitorial and environmental management services. The state's humidity-driven HVAC maintenance intensity supports higher per-square-foot revenue rates for mechanical systems upkeep.
New York Metro
Corporate real estate teams in Manhattan and surrounding counties are unbundling bundled service contracts to purchase maintenance, energy management, and security through separate specialist providers. State-level efficiency and emissions requirements layer additional compliance burdens into procurement specifications. Legacy commercial stock maintains substantial in-house engineering departments alongside growing hybrid outsourcing arrangements.
Southeast
Georgia and North Carolina's logistics and distribution hub expansion is generating demand for integrated security and maintenance services in industrial warehouses. Mid-market enterprises with 500,000 to 2 million square feet are adopting managed service arrangements that blend outsourced expertise with retained oversight. Charlotte and Atlanta's financial services concentrations are replicating coastal disaggregation patterns for contract transparency.
United States Facility Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer structure where national scale competes against technical depth. The upper tier captures bundled contracts across multiple service lines, while the specialist tier dominates single-service procurement in janitorial, security, or energy management. Three archetypes define positioning: integrated property management platforms, technical systems specialists with in-house staffing, and food-service-anchored facilities integrators. Competitive intensity centers on M&A-driven geographic expansion and technology platform investments that enable predictive maintenance capabilities.
Among integrated property management platforms, CBRE Group and Jones Lang LaSalle Incorporated exemplify the national footprint archetype, leveraging lease administration relationships to bundle maintenance services. Technical systems specialists find representation in Emcor Group Inc., whose mechanical and electrical vertical capabilities sustain market presence through certified in-house staffing. Sodexo Inc. occupies a distinct position as a food-service-anchored integrator, differentiating through combined food and facilities contracts concentrated in healthcare and education campuses.
| Leading Market Players |
|---|
| Emcor Group Inc. |
| ISS Facility Services Inc. |
| CBRE Group |
| Kellermeyer Bergensons Services |
| Sodexo Inc. |
| Jones Lang LaSalle Incorporated |
| Cushman & Wakefield plc |
| MaintenX |
| ABM Industries |
| Others |
Value Network & Pricing Analysis
National-scale maintenance providers achieve cost advantages through centralized technician dispatch networks and bulk procurement of HVAC components, compressing price floors for regional competitors while elevating margin thresholds for technology-enabled service tiers. This scale concentration simultaneously shapes supply chain sourcing patterns, as tier-one facility management firms demand volume commitments from building automation hardware suppliers that smaller operators cannot match.
Pricing Analysis
Long-term bundled service contracts dominate facility management procurement, with hospital systems and corporate real estate portfolios favoring multi-year agreements that lock in maintenance, janitorial, and energy management rates. Price differentiation hinges on technician certification density and EPA compliance documentation quality, with OSHA-certified safety management systems commanding substantial premiums over baseline offerings. Pricing pressure stems from wage compression in electrical and HVAC trades, eroding margins on fixed-price agreements signed before labor cost escalations. Mid-market enterprises with 500,000 to 2 million square feet exhibit highest price sensitivity, while healthcare campuses prioritize compliance assurance over unit-cost minimization.
Supply Chain Analysis
China, Taiwan, and South Korea anchor semiconductor production for building automation controllers and IoT sensor networks that underpin predictive maintenance platforms. Facility management technology stacks draw from concentrated Asian manufacturing corridors for edge computing hardware, MEMS sensors, and wireless communication modules. Single-source vulnerability in semiconductor components exposes service providers to disruption risks from geopolitical friction or foundry capacity constraints. Distribution runs through national distributors and direct OEM relationships, with tier-one facility management firms leveraging procurement scale to secure allocation priority during supply constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician pipelines are collapsing as apprenticeship completion rates fail to replace retiring journeyman engineers, creating acute capability scarcity that reorganizes competitive advantage around in-house training infrastructure and technology-augmented staffing models.
For Market Incumbents: Fortify technical staffing depth through accredited apprenticeship programs and predictive maintenance platform investments that reduce per-site labor dependency. Emcor Group and CBRE Group sustain positioning by embedding IoT sensor networks into long-term client contracts, creating switching costs that defend against regional specialists. Vertical integration into building automation hardware servicing capabilities insulates margin structures from third-party technician wage inflation.
For New Entrants and Emerging Players: Lead with mid-market hybrid service arrangements that blend outsourced expertise with retained client oversight, targeting 500,000 to 2 million square foot enterprises underserved by national bundled providers. Georgia and North Carolina logistics hub expansions present penetrable whitespace for integrated security and maintenance specialists. Go-to-market positioning should emphasize transparent unit-cost visibility and modular service unbundling that mirrors coastal disaggregation patterns.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technical systems specialists with certified in-house staffing and vertical capabilities in mechanical and electrical systems. Long-term viability across the projection horizon rests on technology platform investments that enable predictive maintenance and CMMS-IWMS convergence. Acquisition target archetypes include regional maintenance firms with healthcare sector concentration and proprietary technician training pipelines. The signal to watch is IRA tax incentive utilization rates for building electrification projects, which accelerate demand for specialized commissioning services.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | IoT sensor networks reduce unplanned downtime for Texas and Florida hospital expansions. |
| Technician Apprenticeship Pipeline Investment | OSHA-certified training programs address certification collapse in stationary engineering trades. |
| CMMS-IWMS Convergence Integration | Unified data layers optimize space and asset utilization across corporate real estate portfolios. |
| Healthcare Sector Concentration Buildout | Joint Commission accreditation capabilities capture bundled facilities contract consolidation. |
| Edge Computing Hardware Partnership | Localized analytics processing reduces latency for critical chiller plant alerts in Sun Belt markets. |
Research Methodology
The analysis maps janitorial, maintenance, security, and energy management service lines, each validated through facility directors, corporate real estate executives, hospital procurement managers, and building automation engineers. Primary fieldwork combined structured interviews with secondary validation against OSHA enforcement protocols, EPA energy-efficiency filings, and IRA tax credit utilization databases. Trade association disclosures from IFMA and BOMA, alongside SEC 10-K filings from publicly traded service providers, anchored supply-side assessment. Bottom-up contract value aggregation and top-down market sizing triangulated revenue estimates across delivery models.
Consistency checks validated volume and value outputs against external benchmarks including commercial building stock databases and healthcare construction permits. The analytical framework segmented by service type, end-user sector, delivery structure, and technology stack across the analysis window. CAGRs were derived from regression analysis of historical outsourcing penetration rates and regulatory mandate implementation timelines. Forecast inputs incorporated skilled trade demographic projections and smart building retrofit adoption curves specific to California and New York building performance standards.
The analysis sits within stated boundaries; outcomes outside sustained healthcare outsourcing momentum or IRA incentive continuity would require recalibration. Forecasts reflect documented assumptions regarding labor supply elasticity and semiconductor availability for automation hardware. Specific risks that could revise projections include accelerated trade restriction implementation affecting Asian component sourcing or collapse of apprenticeship program funding at state level. Recalibration cycles align with material shifts in OSHA enforcement intensity and EPA code adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Canada Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Mexico Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Argentina Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Japan Facility Management Market
Facility Management
Slovenia Facility Management Market