
 Anti-Pollution Skin Care Products Market | 2026-2036
Anti-Pollution Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Pollution Skin Care Products Market Outlook
South Korea is reconfiguring regional supply chains through expanded biotech fermentation capacity for peptide-based anti-pollution actives. Shiseido Company leverages proprietary pollution-shield polymer research to sustain premium positioning across Asian metropolitan markets. L'Oréal Group anchors European demand through its Clichy-based dermatological testing infrastructure, while Beiersdorf AG differentiates via ceramide-heavy barrier repair formulations engineered for Central European climatic stressors.
Anti-pollution skin care products comprise topical formulations incorporating particulate-binding polymers, free-radical scavenging antioxidants, and metal-chelating agents designed to mitigate oxidative damage from ambient pollutants such as PM2.5, polycyclic aromatic hydrocarbons, and heavy metals. Manufacturing employs cold-process emulsification to preserve labile actives including stabilized vitamin C derivatives and fermented botanical extracts. Serum formulations command disproportionate margin pools due to concentrated active loading and premium unit economics, though cleanser segments attract volume through daily-use frequency and lower price elasticity. Peptide ingredient categories exhibit the steepest growth trajectory as consumers recognize signaling-molecule benefits for barrier resilience, while clay-based masks remain mature with limited formulation innovation.
The EU's REACH regulation and ECHA classifications restrict formaldehyde-releasing preservatives and certain nanoparticle UV filters, compelling reformulation toward GRAS-status antioxidant systems. China's SAMR enforces mandatory safety assessment filings for cosmetics claiming pollution-defense efficacy, creating compliance barriers for imported brands. India's BIS cosmetic standards and CDSCO ingredient notification requirements add incremental testing burdens for multinational entrants. Stakeholders must monitor evolving particulate matter threshold standards in megacity air quality indices, as municipal pollution alerts directly trigger demand spikes for barrier-protective topical products.
Market Dynamics
Particulate pollution thresholds in megacity air quality indices function as real-time demand triggers, with municipal alerts causing immediate spikes in barrier-protective topical purchases across urban retail channels.
Growth Catalysts
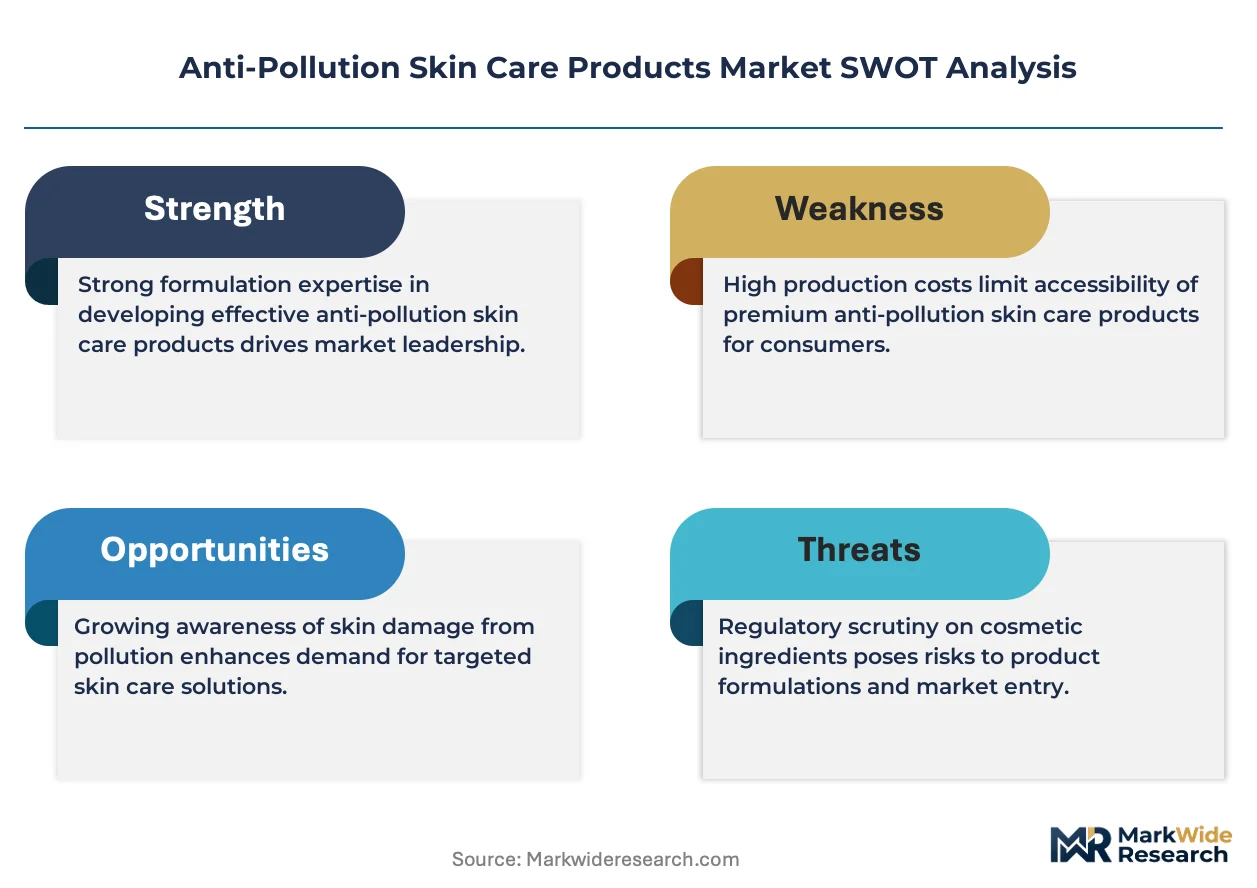
- REACH framework restrictions:The EU's ECHA classifications on formaldehyde-releasing preservatives compel brands toward GRAS-status antioxidant systems, accelerating clean-formulation R&D investment cycles.
- Peptide biotechnology:South Korea's expanded fermentation capacity for signaling-molecule actives creates regional supply advantages for barrier-resilience claims in premium serum segments.
- SAMR efficacy filings:China's mandatory safety assessments for pollution-defense claims raise compliance barriers that favor established players with in-house toxicological testing infrastructure.
Market Restraints
- Labile active instability:Stabilized vitamin C derivatives and fermented botanical extracts degrade under thermal stress, requiring cold-chain logistics that inflate finished goods cost structures.
- East Asian supply concentration:Biotech fermentation capacity for peptide actives clusters in South Korea and eastern China, creating geographic single-point vulnerability for Western formulators.
- Nanoparticle UV filter bans:ECHA restrictions on certain titanium dioxide and zinc oxide nanoforms eliminate proven photostabilization pathways, forcing expensive reformulation cycles.
Strategic Opportunities
- Tier-two Chinese urbanization:Pollution awareness spreads beyond Beijing, Shanghai, and Guangzhou into Chengdu and Xi'an, opening distribution white space ahead of premium brand saturation.
- Barrier repair-ceramide convergence:Central European climatic stressors drive demand for lipid-replenishing formulations that combine pollution defense with atopic dermatitis adjacency.
- Dermatological channel expansion:Clinic-dispensed professional lines bypass retail margin compression while capturing high-intent consumers seeking clinical validation.
Industry Challenges
- Fermentation scale-up talent scarcity:Peptide bioprocess engineering expertise concentrates in South Korean and Swiss contract manufacturers, limiting in-house capability building for mid-tier brands.
- Dual regulatory filing complexity:Brands targeting both EU REACH compliance and China SAMR efficacy claims face divergent toxicological testing protocols that extend go-to-market timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Pollution Skin Care Products Market |
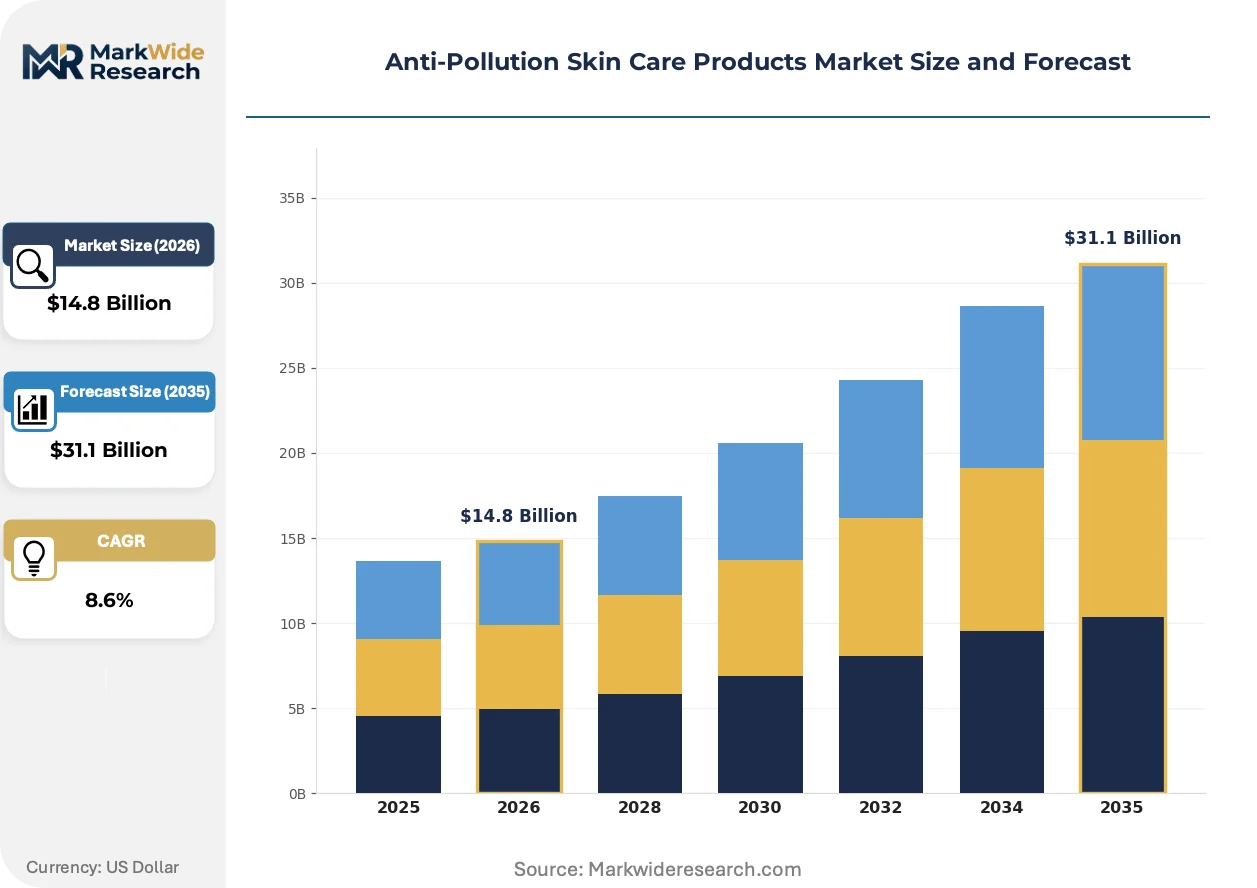
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Moisturizers, Cleansers, Masks Ingredient: Activated Charcoal, Antioxidants, Clay, Peptides Consumer Type: Men, Women, Teens, Seniors Distribution Channel: Online Retail, Specialty Stores, Drugstores, Supermarkets |
| Companies Covered | Shiseido Company, Estée Lauder Companies, L'Oréal Group, Kao Corporation, Johnson & Johnson, Procter & Gamble, Beiersdorf AG, Mary Kay, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Pollution Skin Care Products Market Strategic Shifts
Formulation science is converging with environmental monitoring data to create responsive skin protection systems that adapt to real-time pollution exposure levels rather than static defense claims.
Particulate-binding polymer technology is hybridizing with metal-chelating agent systems to create multi-mechanism pollution defense. Urban millennials in Asia-Pacific metropolitan markets adopt these hybrid formulations faster than mature demographics in Western Europe. The technology is compressing the traditional serum-moisturizer application sequence into single-step hybrid products that command premium positioning.
China's SAMR now enforces mandatory safety assessment filings for cosmetics claiming pollution-defense efficacy, creating a compliance moat that disadvantages smaller imported brands. The regulation forces reformulation toward documented antioxidant performance rather than marketing-driven ingredient storytelling. European premium houses with existing CPNP notification infrastructure adapt faster than North American indie brands lacking regulatory affairs scale.
Buying patterns are fragmenting across channel types as pollution alerts trigger impulse purchases through quick-commerce platforms rather than planned e-commerce replenishment. Traditional department store beauty halls lose traffic to clinic-dispensed professional lines and dermocosmetic specialty retail. This behavioral rotation is most pronounced in Chinese tier-one cities where municipal air quality apps integrate direct-to-purchase skin care recommendations.
Anti-Pollution Skin Care Products Market Segmentation
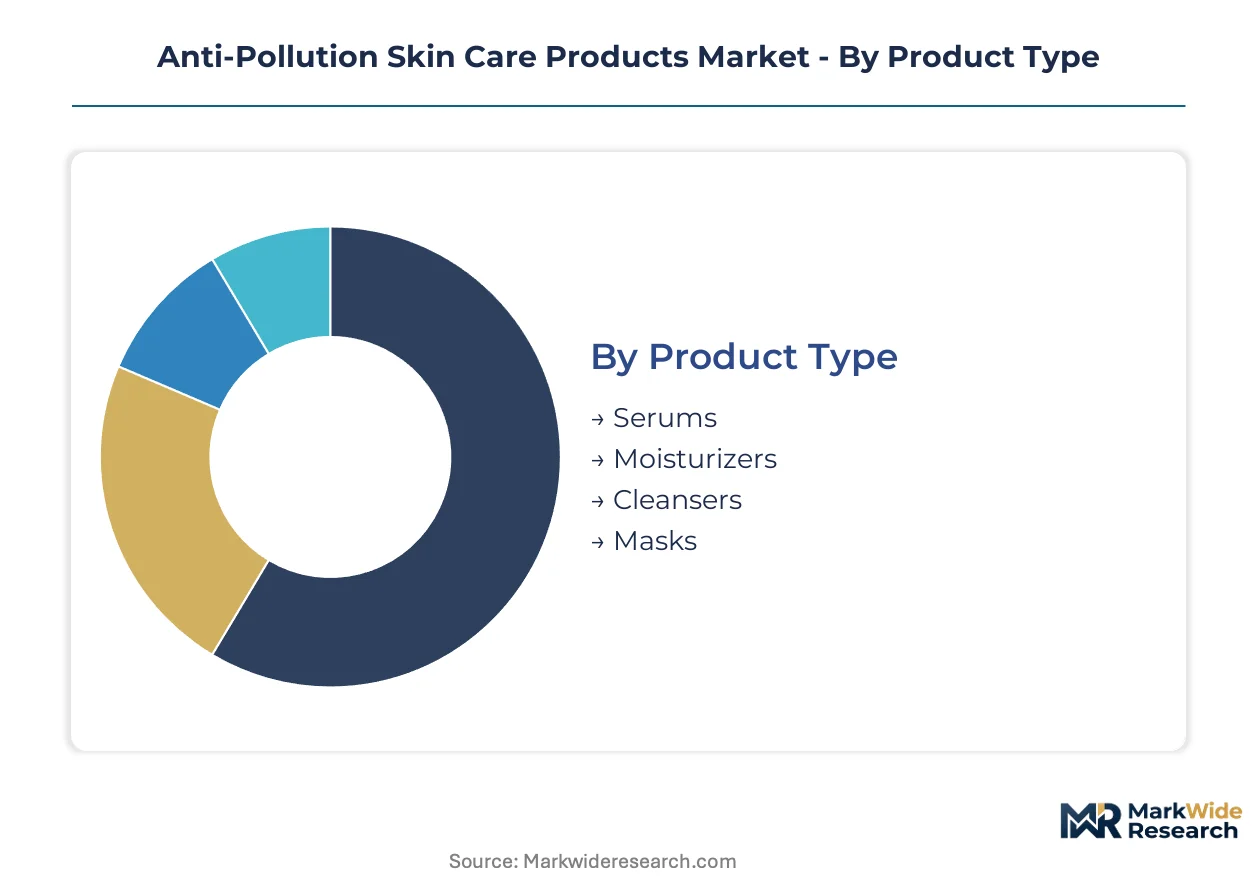
Product architecture in anti-pollution skin care reflects divergent consumer behaviors across application frequency, price sensitivity, and clinical validation requirements. Segment boundaries blur as hybrid formulations compress traditional category distinctions into multi-functional delivery systems.
Product Type:
Application frequency and margin structure divide formulations into daily-use staples versus intensive treatment modalities.
- Serums:Concentrated active-loading formulations deliver particulate-binding polymers and free-radical scavengers in low-viscosity vehicles. Urban millennials in Shanghai, Beijing, and Seoul drive premium adoption through clinic-dispensed professional lines and dermocosmetic specialty retail. Serum segments capture disproportionate margin pools due to concentrated active economics and perceived efficacy intensity.
- Moisturizers:Emulsion-based barrier repair systems incorporate ceramide-heavy lipid matrices engineered for Central European climatic stressors. Demand concentrates in tier-one Chinese cities where municipal pollution alerts trigger immediate replenishment cycles through quick-commerce platforms rather than planned e-commerce.
- Cleansers:Daily-use surfactant systems with metal-chelating agents attract volume through lower price elasticity and habitual repurchase patterns.
- Masks:Clay-based formulations remain mature with limited innovation; weekly-use frequency constrains revenue contribution despite higher per-unit prices.
Serums command the established base. The steepest expansion runs through moisturizers as barrier repair claims converge with atopic dermatitis adjacency.
Ingredient:
Active mechanism and supply chain geography determine formulation feasibility and regulatory pathway complexity.
- Peptides:Signaling-molecule biotechnology from South Korean fermentation capacity creates regional supply advantages for barrier-resilience claims. Peptide categories exhibit the steepest growth trajectory as consumers recognize cellular communication benefits for pollution-induced barrier compromise.
- Antioxidants:Stabilized vitamin C derivatives and fermented botanical extracts require cold-process emulsification and cold-chain logistics that inflate finished goods cost structures. REACH framework restrictions on formaldehyde-releasing preservatives compel brands toward GRAS-status antioxidant systems.
- Activated Charcoal:Particulate-binding adsorbent technology supports single-step hybrid product development combining cleansing with treatment functions.
- Clay:Mature mineral-based matrices offer limited differentiation beyond texture and origin storytelling for mask applications.
Antioxidants anchor current formulation portfolios. Peptides are climbing the fastest as bioprocess engineering capabilities expand.
Consumer Type:
Demographic targeting reflects divergent skin biology, purchasing autonomy, and channel access patterns across life stages.
- Women:Primary category initiators with established multi-step routines and highest willingness-to-pay for clinical validation. Urban professional women in Chinese tier-one cities integrate municipal air quality app recommendations into impulse purchase behavior through quick-commerce.
- Men:Simplified routine adoption accelerates through hybrid single-step formulations that compress traditional serum-moisturizer sequences. Male-specific marketing in South Korea and Japan normalizes pollution-defense as grooming necessity.
- Teens:Entry-level price point sensitivity and social media-driven discovery patterns concentrate demand in online retail and specialty store channels.
- Seniors:Barrier repair prioritization and dermatological channel preference align with professional line dispensing and clinical endorsement requirements.
Women retain volume concentration. Men are gaining share fastest as gendered category boundaries dissolve.
Distribution Channel:
Channel selection determines margin capture, consumer education depth, and responsiveness to pollution-alert demand spikes.
- Online Retail:Planned replenishment and subscription mechanics dominate, though quick-commerce sub-channels capture pollution-alert impulse volume in Chinese megacities. SAMR efficacy filing requirements create compliance moats that disadvantage smaller imported brands lacking regulatory affairs scale.
- Specialty Stores:Dermocosmetic retail provides education-intensive environments for peptide and antioxidant technology storytelling with trained consultant support.
- Drugstores:Mass-market accessibility and pharmacist endorsement support ceramide-heavy barrier repair formulations for Central European consumers.
- Supermarkets:Price-competitive cleanser and mask placement attracts routine replenishment with minimal decision friction.
Specialty stores hold premium positioning. Online retail shows the steepest expansion trajectory as quick-commerce integrates environmental monitoring data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex underwrites Asia-Pacific's dominance in finished formulation exports, while Rotterdam's liquid bulk terminals anchor European ingredient import flows for antioxidant and peptide feedstocks.
China
Tier-one city millennials drive serum adoption through municipal air quality app integrations that trigger quick-commerce impulse purchases. SAMR mandates safety assessment filings for pollution-defense efficacy claims, raising compliance barriers for imported brands. Shanghai's Yangpu District hosts concentrated dermocosmetic R&D facilities serving the Yangtze River Delta manufacturing corridor.
South Korea
Seoul's urban professional demographic normalizes multi-step anti-pollution routines through clinic-dispensed professional channels. MFDS regulates peptide-based biotech actives under functional cosmetic designation requirements. Songdo's biotech cluster houses expanded fermentation capacity for signaling-molecule production serving regional formulators.
United States
California and New York metropolitan consumers exhibit highest willingness-to-pay for clinical validation in barrier-protective formulations. FDA oversight of cosmetic safety claims operates alongside state-level California Proposition 65 heavy metal disclosure requirements. New Jersey's chemical corridor supplies particulate-binding polymer intermediates to North American finishers.
Germany
Central European climatic stressors drive ceramide-heavy moisturizer demand among atopic dermatitis-adjacent consumers. REACH framework restrictions on formaldehyde-releasing preservatives compel reformulation toward GRAS-status antioxidant systems. Hamburg's port infrastructure handles inbound botanical extract shipments for cold-process emulsification facilities.
India
Mumbai and Delhi-NCR pollution awareness accelerates premium adoption among urban professional women. BIS cosmetic standards and CDSCO ingredient notification requirements add testing burdens for multinational entrants. Gujarat's specialty chemical belt manufactures metal-chelating agent precursors for domestic formulation houses.
Anti-Pollution Skin Care Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in peptide fermentation and polymer synthesis. The vendor base concentrates around three strategic tiers: multinational beauty conglomerates with dermatological testing infrastructure, regional biotech specialists leveraging fermentation scale, and mid-tier formulators competing on clean-label positioning. Dominant competitive moves include vertical integration into peptide bioprocessing and geographic expansion through clinic-dispensed professional channel partnerships.
Within the multinational conglomerate tier, L'Oréal Group and Beiersdorf AG exemplify divergent regional anchoring strategies. L'Oréal's European dermatological testing infrastructure supports REACH-compliant antioxidant system development, while Beiersdorf represents ceramide-heavy barrier repair specialization engineered for Central European climatic conditions. Shiseido Company occupies a position bridging Asia-Pacific biotech sourcing with premium metropolitan distribution across Seoul, Tokyo, and Shanghai.
| Leading Market Players |
|---|
| Shiseido Company |
| Estée Lauder Companies |
| L'Oréal Group |
| Kao Corporation |
| Johnson & Johnson |
| Procter & Gamble |
| Beiersdorf AG |
| Mary Kay |
| Unilever |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on South Korean peptide fermentation capacity compresses margin structures for Western formulators while amplifying pricing tier spreads between clinic-dispensed professional lines and mass-market alternatives. REACH compliance costs and cold-chain logistics requirements for labile actives further stratify procurement economics across buyer archetypes.
Pricing Analysis
Volume-discount tiering separates clinic-dispensed professional serums from drugstore barrier-repair moisturizers and supermarket cleansers. Price differentiation hinges on clinical validation depth and cold-chain certification status. Pricing pressure stems from bioprocess engineering talent scarcity in Swiss and South Korean contract manufacturers. Mass-market buyers exhibit highest price sensitivity; dermatological channel purchasers accept premium positioning for documented efficacy.
Supply Chain Analysis
Contract manufacturing concentrates among South Korean biotech clusters, Swiss peptide specialists, and German cold-process emulsification facilities. Raw material dependencies include fermented botanical extracts, stabilized vitamin C precursors, and ceramide lipid matrices. Supply chain risk centers on East Asian geographic concentration for signaling-molecule actives. Distribution runs through dermocosmetic specialty retail, quick-commerce platforms, and clinic-dispensed professional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as pollution-alert buying patterns fragment across quick-commerce impulse channels and subscription replenishment mechanics, creating niche positioning space for specialized formulators.
For Market Incumbents: Entrench peptide bioprocessing capabilities through captive fermentation capacity or exclusive offtake agreements with Songdo biotech clusters. Deepen clinic-dispensed professional channel control to defend margin pools against quick-commerce price transparency. Prioritize SAMR efficacy filing infrastructure to maintain compliance moats against smaller imported competitors.
For New Entrants and Emerging Players: Tier-two Chinese urbanization in Chengdu and Xi'an offers white-space distribution ahead of premium brand saturation. Barrier repair-ceramide convergence for Central European atopic dermatitis-adjacent consumers represents the most penetrable positioning. Launch through dermocosmetic specialty retail with trained consultant education to bypass incumbent e-commerce dominance.
For Investors and Strategic Acquirers: Regional biotech specialists with expanded fermentation capacity and existing MFDS functional cosmetic designations represent priority acquisition targets. Long-term viability hinges on backward integration into peptide bioprocessing and geographic diversification beyond East Asian supply concentration. Watch municipal air quality index integration with quick-commerce platforms as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Fermentation Capacity Expansion | South Korean biotech clusters secure regional supply advantages for barrier-resilience claims. |
| SAMR Efficacy Filing Infrastructure | Documented pollution-defense performance creates compliance barriers against marketing-driven competitors. |
| Clinic-Dispensed Professional Channel Partnership | Dermatological validation bypasses retail margin compression while capturing high-intent consumers. |
| Cold-Chain Logistics Investment | Thermal stability preservation for labile actives supports premium serum positioning. |
| Quick-Commerce Platform Integration | Municipal pollution alert responsiveness captures impulse purchase volume in Chinese megacities. |
Study Parameters
A standing panel of formulation scientists, dermatological testing directors, regulatory affairs leads at multinational beauty conglomerates, and quick-commerce category managers provided ongoing calibration across the research cycle. Primary interviews with dermocosmetic retail buyers and peptide bioprocess engineers combined with secondary validation from SAMR filing databases, ECHA REACH registration dossiers, and customs records for antioxidant and peptide feedstock flows. Bottom-up volume builds and top-down market sizing triangulated segment-level outputs.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product architecture, active mechanism, consumer life stage, and channel type. CAGRs derived from trend-line extrapolation of peptide adoption curves, pollution-alert purchase elasticity, and clinic-dispensed professional channel penetration rates. Modeled inputs included municipal air quality index correlation coefficients and biotech fermentation capacity expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated biotech specialists or rapid regulatory harmonization between EU REACH and China SAMR would shift outcomes. Quarterly review of peptide fermentation capacity utilization rates and municipal pollution alert integration with e-commerce platforms is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Nail Polish Market
Cosmetics & Skincare
Makeup Remover Pen Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Malaysia Skin Care Products Market
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Eyeliner Pen Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market
Cosmetics & Skincare
Face Compact Market