
 Body Cream Jars Market | 2026-2036
Body Cream Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Body Cream Jars Market Analytics
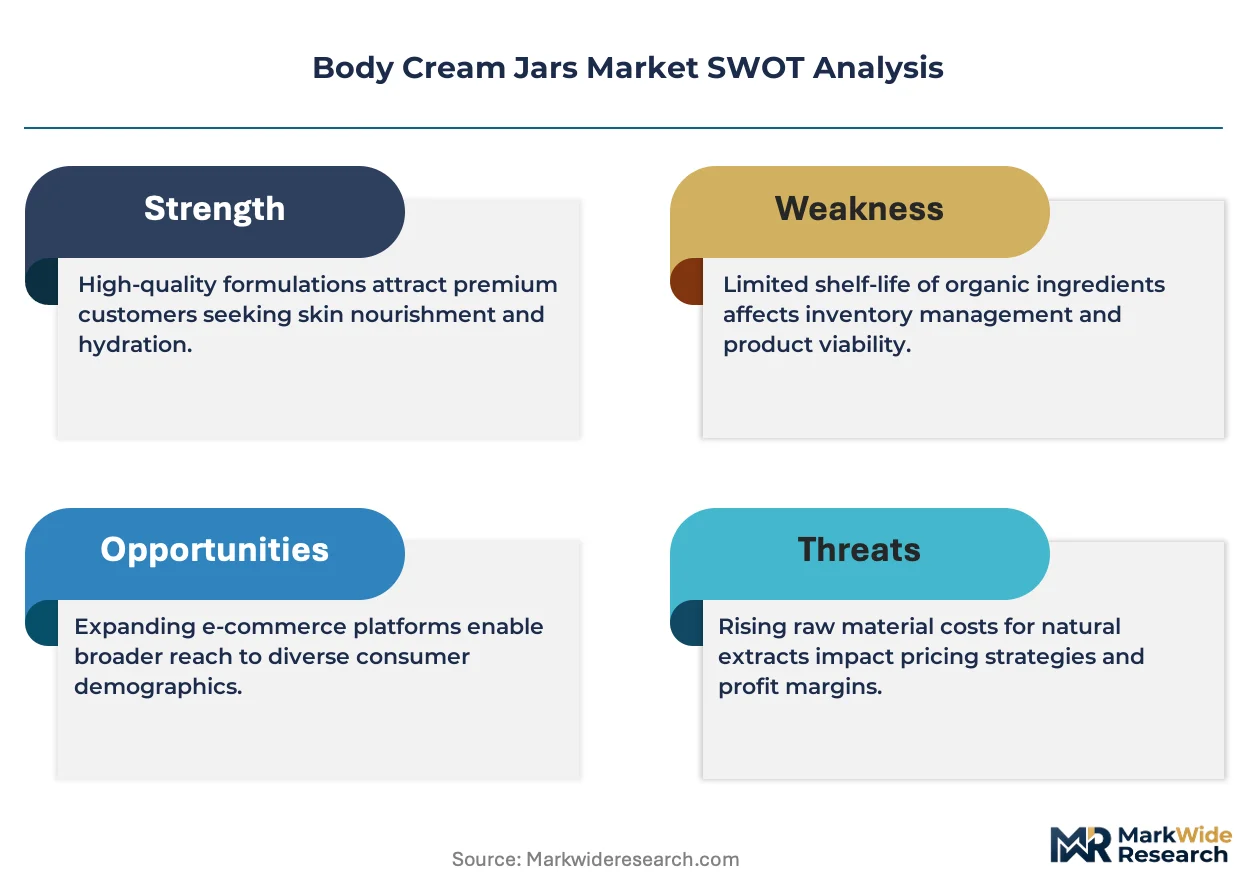
EU REACH is recalibrating the cost-of-entry calculus for body cream jar manufacturers serving European beauty brands. Berry Global leverages its multi-material platform to navigate shifting compliance requirements across polymer grades. Gerresheimer AG anchors its position through specialized glass formulations that meet pharmaceutical-grade cosmetic standards.
Body cream jars are rigid primary packaging vessels, typically injection-molded or blow-molded in capacities from 50ml to 500ml, designed to protect semi-solid emulsions from oxidation and contamination while enabling controlled dispensing. Glass and aluminum segments command premium positioning due to their compatibility with clean-label and refillable brand strategies, whereas plastic dominates unit volume through cost-scaled production for mass-market hydrating and moisturizing formulations. The 100ml and 200ml size tiers concentrate margin pools, balancing portability with per-unit economics for both travel retail and at-home replenishment cycles.
FDA cosmetic labeling rules, EU REACH substance restrictions, and ECHA microplastic regulations collectively determine material eligibility and recyclability claims across North American and European markets. Compliance documentation now extends through tier-two suppliers, forcing jar converters to validate resin provenance and post-consumer recycled content thresholds. Stakeholders must monitor pending packaging Extended Producer Responsibility frameworks in key states and member countries to anticipate capital reallocation toward circular production infrastructure.
Market Dynamics
EU REACH substance restrictions and ECHA microplastic regulations are forcing jar converters to revalidate resin provenance through tier-two suppliers, compressing material eligibility windows and accelerating capital reallocation toward circular production infrastructure.
Growth Catalysts
- EU Green Deal packaging mandates:Binding recycled content thresholds for cosmetic containers are pulling post-consumer recycled glass and bio-based polymers into mainstream formulation.
- Clean-label brand strategies:Premium skincare houses are specifying pharmaceutical-grade glass and aluminum to signal ingredient integrity and enable refillable program launches.
- German supply chain consolidation:Beauty manufacturers are concentrating European procurement decisions in Germany, creating demand density for specialized jar converters with multi-material platforms.
Market Restraints
- Post-consumer recycled resin scarcity:FDA and EFSA food-contact-grade PCR availability constrains mass-market plastic jar production at scale.
- Specialized glass furnace concentration:Borosilicate and pharmaceutical-grade glass capacity clusters in Central Europe, exposing brands to single-source geographic risk.
- Aluminum alloy specification fragmentation:Cosmetic-grade anodizing chemistries vary by brand, preventing standardization and inflating minimum order quantities.
Strategic Opportunities
- Refill infrastructure buildout:Durable glass jar platforms paired with pouch-based replenishment systems are capturing recurring revenue streams from direct-to-consumer channels.
- India PLI scheme for packaging:Domestic manufacturing incentives are lowering landed costs for European brands seeking supply diversification beyond China.
- Digital printing convergence:Direct-to-shape decoration technologies are collapsing minimum viable runs and enabling regionalized SKU proliferation without tooling changeovers.
Industry Challenges
- REACH documentation complexity:Full material disclosure requirements extend through resin compounders and additive suppliers, stretching compliance team bandwidth.
- Legacy injection mold retrofitting:Converting existing tooling for bio-based polymer rheology requires capital outlay with uncertain resin price stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Cream Jars Market |
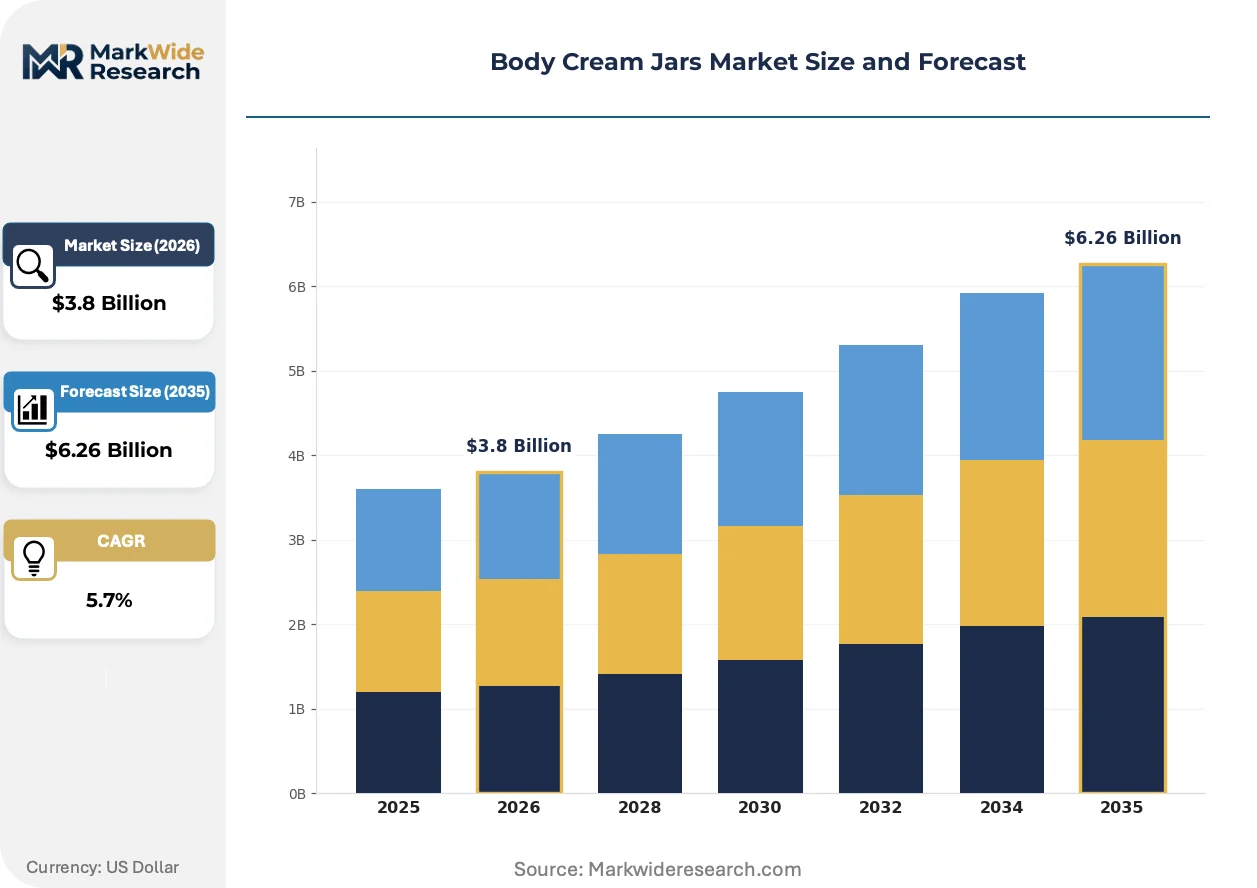
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating Cream, Anti-Aging Cream, Moisturizing Lotion, Nourishing Balm Material: Plastic, Glass, Aluminum, Bamboo Size: 50ml, 100ml, 200ml, 500ml Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Beauty Salons |
| Companies Covered | Berry Global, Gerresheimer AG, Stoelzle Glass Group, Quadpack Industries, Berlin Packaging, Albea Group, Aptar Group, APackaging Group, Verescence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Cream Jars Market Evolving Landscape
Active material science breakthroughs and regulatory disclosure mandates are reshaping how body cream jar specifications get written, tested, and sourced across European and North American beauty supply chains.
Mono-material polypropylene jar construction is converging with in-mold labeling to eliminate adhesive layers and enable single-stream recycling. Mass-market hydrating brands are piloting these formats for 200ml replenishment sizes. The structural consequence is compression of traditional multi-component assembly steps and associated quality failure modes.
REACH Annex XVII substance restrictions are recalibrating colorant and additive palettes available to European cosmetic jar producers. ECHA evaluations of microplastic-releasing ingredients are forcing reformulation of certain pearlizing agents and texture modifiers. Premium glass segments are capturing displaced demand as brands preempt regulatory uncertainty.
Direct-to-consumer sampling programs are compressing trial-size jar procurement cycles from annual to quarterly planning horizons. Indie beauty brands are bypassing traditional distributor networks for Alibaba and specialized cosmetic packaging marketplaces. This pattern concentrates in digitally native skincare launches targeting Gen Z demographics in the United States and United Kingdom.
Body Cream Jars Market Segmentation
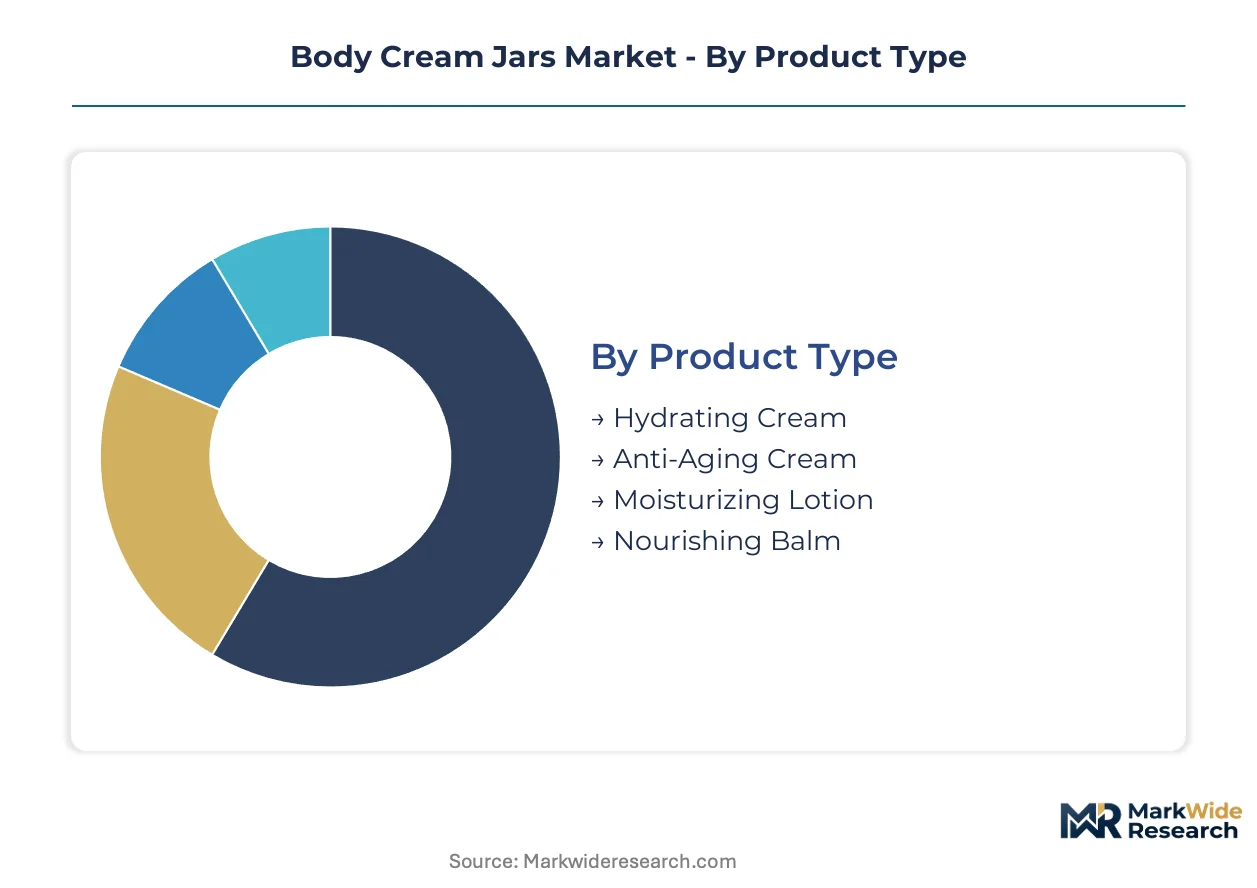
Body cream jar specifications diverge sharply between mass-market hydration products and premium anti-aging formulations, with material choices and size tiers reflecting distinct margin structures and regulatory exposure across European and North American supply chains.
Product Type:
Standalone skincare regimens drive specification divergence, with embedded multi-step routines demanding jar formats that signal functional differentiation at shelf and support refillable program architectures.
- Hydrating Cream:Water-in-oil emulsions with high glycerin content require barrier-grade polypropylene or borosilicate glass to prevent moisture loss through permeation. Demand concentrates in German drugstore chains and US mass-market retailers where unit economics favor 200ml plastic formats and streamlined decoration budgets.
- Anti-Aging Cream:Retinol and peptide formulations mandate amber glass or UV-blocking polymer additives to preserve active ingredient stability through shelf life. Premium skincare houses in France and Switzerland specify pharmaceutical-grade glass with metallized closures, embedding these jars within subscription-based replenishment ecosystems.
- Moisturizing Lotion:Lower-viscosity formulations accommodate wider mouth diameters and snap-fit closures for high-throughput filling lines.
- Nourishing Balm:Occlusive petrolatum and shea butter bases tolerate lower-grade resins but require heat-resistant materials for warm-fill processing.
Hydrating cream leads volumes today; anti-aging cream is gaining share fastest.
Material:
Cost tier stratification separates premium positioning strategies from mass-market scale economics, with regulatory compliance thresholds acting as gatekeepers for material eligibility in EU REACH jurisdictions.
- Plastic:Injection-molded polypropylene and PET dominate unit economics through high-cavity tooling and lightweight logistics. REACH Annex XVII restrictions on additives and colorants are compressing resin provenance windows, forcing converters to validate post-consumer recycled content through tier-two compounders.
- Glass:Soda-lime and borosilicate formats command 3-4x unit premiums, justified by compatibility with clean-label positioning and refillable infrastructure. German and Italian glass furnaces concentrate pharmaceutical-grade capacity, exposing brands to single-source geographic risk during energy price volatility.
- Aluminum:Anodized cosmetic-grade alloys enable lightweight durability for travel retail and solid balm formats.
- Bamboo:Bio-based composite shells with plastic liners navigate greenwashing scrutiny through partial material substitution.
Plastic leads volumes today; glass is climbing the fastest among premium repositioning strategies.
Size:
Volume throughput and margin concentration diverge across size tiers, with mid-capacity formats balancing portability economics against per-unit manufacturing efficiency.
- 100ml:Travel retail and airline-compliant formats concentrate margin pools through premium per-gram pricing and gift-set bundling. Sephora and duty-free operators in Paris Charles de Gaulle and Frankfurt specify this tier for trial-size programming.
- 200ml:At-home replenishment cycles favor this capacity for bathroom vanity positioning and quarterly purchase cadences. German drugstore private labels and US Target exclusives anchor procurement volumes here.
- 50ml:Sampling programs and subscription box inserts drive quarterly procurement cycles.
- 500ml:Value-oriented family formats and professional salon back-bar usage.
200ml leads volumes today; 100ml is expanding most quickly through travel retail recovery.
Distribution Channel:
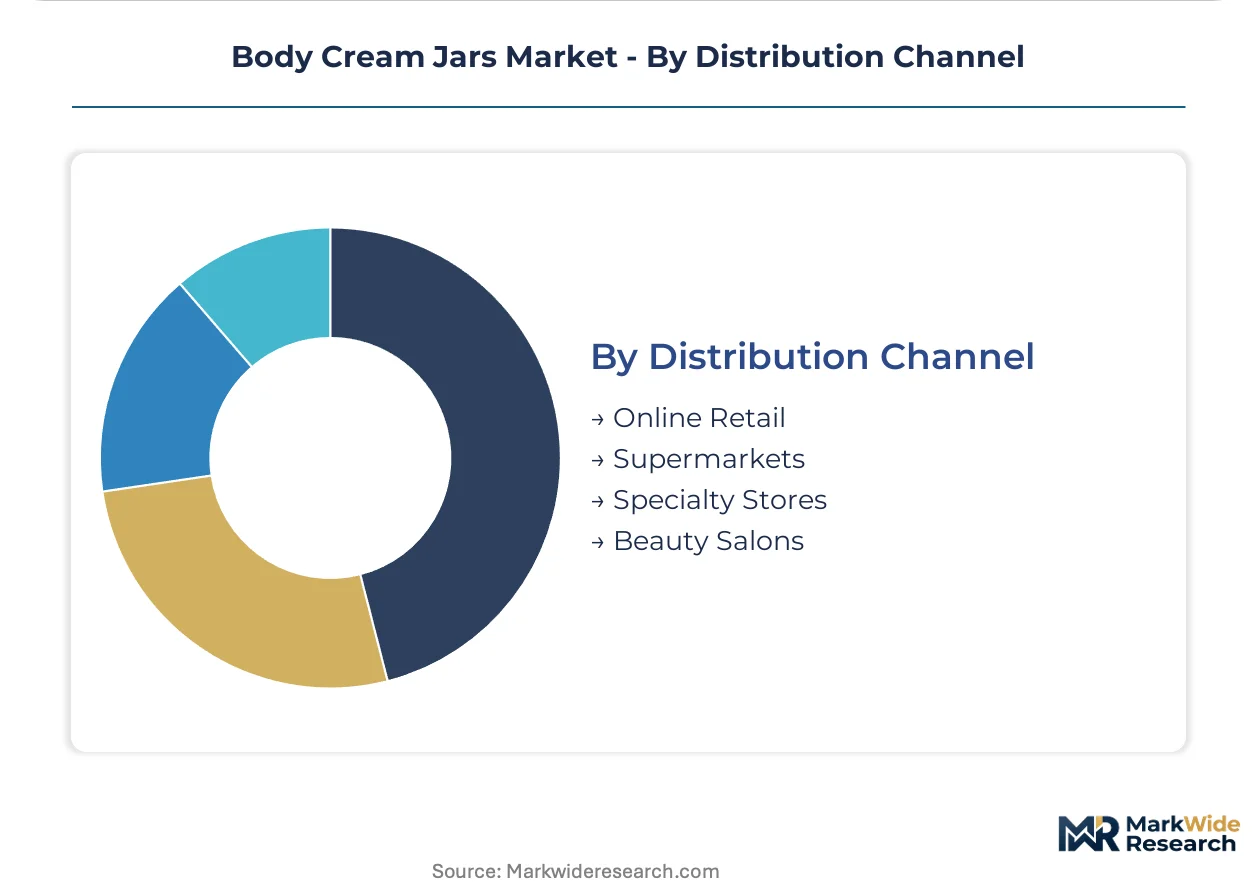
Customer type fragmentation separates digitally native purchasing patterns from traditional retail procurement, with channel-specific packaging requirements driving SKU proliferation and decoration complexity.
- Online Retail:Direct-to-consumer shipping durability demands enhanced wall thickness and cushion-fit secondary packaging. Amazon and Shopify-native brands specify mono-material formats to preempt customer recycling friction and support unboxing shareability.
- Specialty Stores:Sephora, Douglas, and Space NK require distinctive silhouette differentiation and premium haptic finishes to justify brick-and-mortar rent structures.
- Supermarkets:High-velocity replenishment cycles prioritize shelf-ready packaging and pallet-optimized cube efficiency.
- Beauty Salons:Professional back-bar formats emphasize pump-dispense compatibility and bulk refill economics.
Online retail leads volumes today; specialty stores are gaining share fastest through experiential retail investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Body cream jar manufacturing originated in European glassmaking centers during the early twentieth century, with German and Italian furnace complexes establishing the technical standards for pharmaceutical-grade cosmetic packaging that persist today.
Germany
Beauty manufacturers concentrate European procurement decisions in German supply chains, pulling specialized jar converters toward Rhine-Main and North Rhine-Westphalia industrial zones. REACH compliance documentation requirements from ECHA force resin compounders to validate full material disclosure through tier-two suppliers. Gerresheimer AG anchors pharmaceutical-grade glass capacity in Mainz, supplying premium skincare houses with amber and borosilicate formats.
United States
FDA cosmetic labeling rules and state-level packaging Extended Producer Responsibility frameworks reshape material eligibility for brands serving Sephora and Target exclusives. Post-consumer recycled resin scarcity constrains mass-market plastic jar production at California and New Jersey conversion facilities. Berry Global operates multi-material platforms across Midwestern states, navigating shifting compliance requirements across polymer grades.
France
Clean-label brand strategies from L'Oréal and LVMH beauty divisions mandate pharmaceutical-grade glass and aluminum to signal ingredient integrity. ANSM and CNIL oversight extends to packaging material safety assessments for direct-to-consumer channels. Verescence maintains specialized furnace operations in the Bordeaux region, capturing displaced demand from REACH-driven reformulation cycles.
China
SAMR cosmetic registration requirements and dual carbon goals accelerate domestic converter investment in bio-based polymer research. Zhejiang and Jiangsu province injection molders supply European brands seeking cost-scaled production for mass-market hydrating formulations. NMPA alignment with ISO standards enables export qualification for glass and aluminum jar segments.
India
PLI scheme incentives for packaging manufacturing lower landed costs for European brands diversifying beyond Chinese supply sources. Maharashtra and Gujarat state converters develop mono-material polypropylene capabilities for digitally native skincare launches targeting Gen Z demographics. BIS standards harmonization with REACH substance restrictions enables qualified market access.
Body Cream Jars Market Competitive Landscape
The competitive structure tilts toward diversified material specialists with multi-platform capabilities. Tier-one converters with glass, plastic, and aluminum competencies capture procurement consolidation from beauty manufacturers seeking single-source accountability. Three archetypes dominate: integrated packaging conglomerates with global furnace and molding networks, specialized glass houses with pharmaceutical-grade certifications, and regional plastic converters with high-cavity tooling scale. Competitive moves center on backward integration into resin compounding and strategic partnerships with refill infrastructure platforms.
Among integrated packaging conglomerates, Berry Global and Aptar Group exemplify the multi-material archetype, spanning polymer conversion and dispensing closure systems. Specialized glass capacity concentrates with Gerresheimer AG and Verescence, occupying positions defined by pharmaceutical-grade certification and premium brand relationships. Regional scale players include Stoelzle Glass Group and Quadpack Industries, representing European converter networks with proximity to German and French beauty supply chains. Berlin Packaging and Albea Group sit within the distribution-integrated tier, combining sourcing leverage with decoration and logistics capabilities.
| Leading Market Players |
|---|
| Berry Global |
| Gerresheimer AG |
| Stoelzle Glass Group |
| Quadpack Industries |
| Berlin Packaging |
| Albea Group |
| Aptar Group |
| APackaging Group |
| Verescence |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap glass specialists concentrated in Germany and Italy maintain pricing discipline through furnace capacity control, while private-equity-rolled-up plastic converters compress margins to capture volume from mass-market hydrating brands. REACH compliance costs and post-consumer recycled resin scarcity feed directly into tiered pricing spreads between pharmaceutical-grade glass and commodity polypropylene.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade borosilicate glass from soda-lime formats and injection-molded polypropylene. Price differentiation hinges on certification grade for EU REACH compliance and volume scale for tooling amortization. Cost compression in the plastic tier is intensifying because post-consumer recycled resin availability constrains mass-market production. German drugstore chains exhibit highest price sensitivity; French luxury houses demonstrate least.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's dual carbon goals are reshaping sourcing patterns for European beauty brands seeking supply diversification. Manufacturing gravity centers on Germany, China, and India for finished jars, with borosilicate glass feedstock drawn from Central European furnace complexes. Single-source vulnerability concentrates in pharmaceutical-grade glass capacity clustered around Mainz and Bordeaux. Distribution runs through specialized cosmetic packaging distributors and direct Alibaba marketplace procurement for digitally native brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through refill infrastructure economics, where durable glass platforms capture recurring pouch-based replenishment revenue at premium per-gram pricing.
For Market Incumbents: Anchor pharmaceutical-grade glass capacity in Mainz and Bordeaux through furnace modernization investments. Defend against aluminum alloy converters by securing exclusive amber glass supply contracts with LVMH and L'Oréal beauty divisions. Backward integration into borosilicate raw material sourcing mitigates energy price volatility exposure. For New Entrants and Emerging Players: Digital printing convergence offers entry into regionalized SKU proliferation serving Gen Z skincare launches. White-space concentrates in 50ml trial-size formats for quarterly subscription box procurement and mono-material polypropylene construction for Amazon-compliant shipping durability. Go-to-market through specialized cosmetic packaging marketplaces bypasses traditional distributor gatekeepers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional plastic converters with high-cavity tooling scale but limited REACH documentation capabilities. Long-term viability favors diversified material platforms with glass, plastic, and aluminum competencies serving consolidated German procurement offices. Watch for India PLI scheme beneficiary announcements as inflection signal for supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Refill Infrastructure Buildout | Durable glass platforms paired with pouch systems capture recurring DTC revenue from Sephora and Target exclusives. |
| Backward Integration into Resin Compounding | In-house PCR validation secures REACH-compliant supply for German drugstore private labels. |
| Digital Printing Convergence | Direct-to-shape decoration collapses MOQs for regionalized Gen Z skincare launches in UK and US. |
| India Manufacturing Footprint | PLI scheme incentives lower landed costs for European brands diversifying beyond Zhejiang molders. |
| Pharmaceutical-Grade Certification Investment | Amber glass qualification opens LVMH and Swiss prestige house supply relationships. |
Research Methodology
Multiple input streams — procurement directors at German beauty manufacturers, converters with multi-material platforms, and ECHA regulatory affairs specialists — were reconciled against secondary validation. Primary interviews captured tier-two supplier disclosure practices and REACH documentation workflows. Secondary sources included customs records for glass and polymer trade flows, EU packaging Extended Producer Responsibility framework filings, and SEC disclosures from listed packaging conglomerates. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Historical capacity utilization patterns from German and Italian furnace operations were cross-referenced against panel input from category buyers at Douglas and Sephora. Segmentation dimensions spanned material type, size tier, product formulation compatibility, and distribution channel density. CAGRs were derived from elasticity-adjusted demand curves incorporating refill program adoption rates and regulatory compliance cost pass-through assumptions. Bio-based polymer rheology data and pharmaceutical-grade glass certification timelines fed industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH Annex XVII substance restriction expansions and PCR resin price volatility. Projections reflect documented assumptions around German supply chain consolidation and travel retail recovery trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Nail Polish Market
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Israel Cosmetics Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Asia-Pacific Face Compact Market
Cosmetics & Skincare
Thailand Skin Care Products Market
Cosmetics & Skincare
Essential Oil Soap Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Setting Spray Market
Cosmetics & Skincare
France Lip Care Products Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Makeup Setting Powder Market