
 PCB Laminate Market | 2026-2036
PCB Laminate Market Size, Share, and Industry Trends Forecast 2026-2036
PCB Laminate Market Analysis
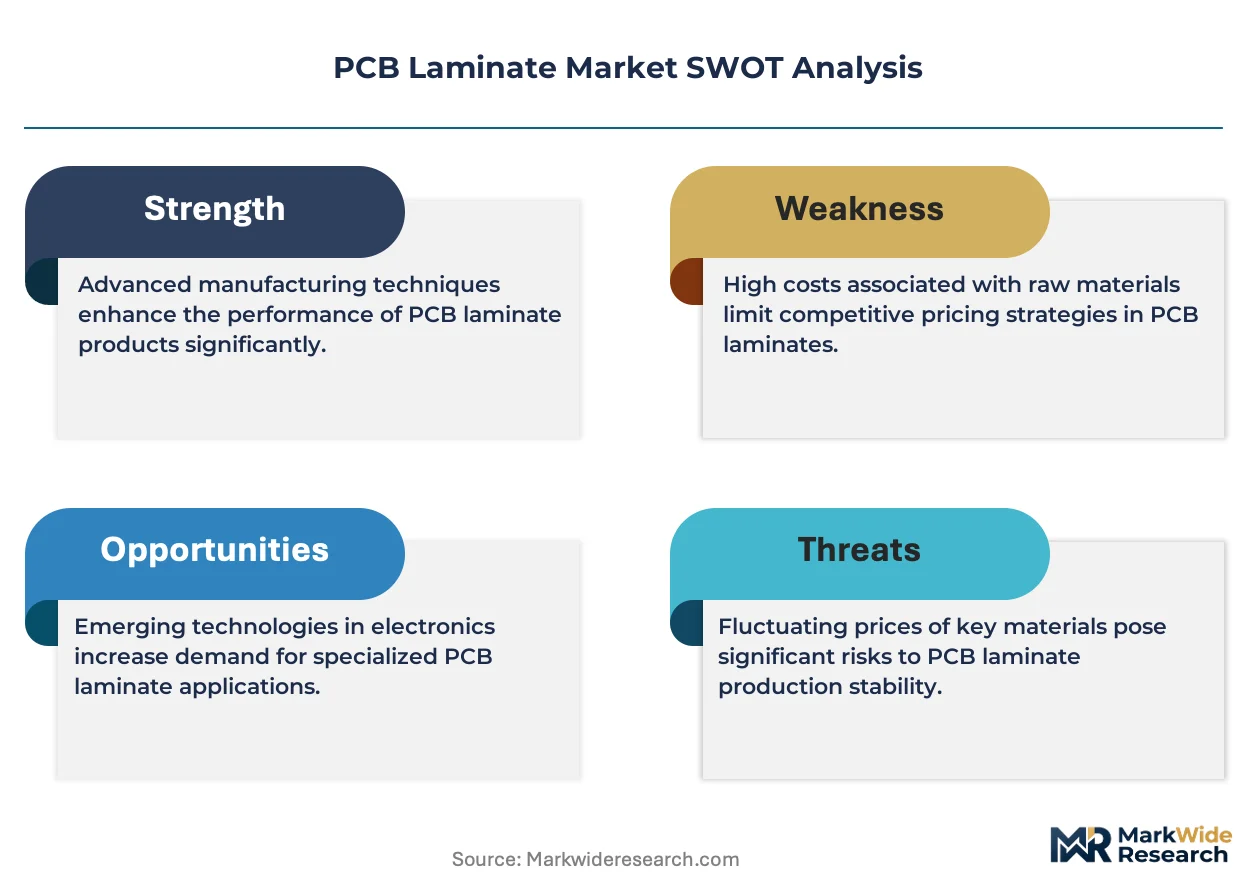
The performance gap between premium and commodity PCB laminate tiers is broadening as high-frequency applications demand specialized dielectric constants while cost-sensitive consumer electronics prioritize volume scale. Rogers Corporation leverages its ceramic-filled hydrocarbon expertise to dominate aerospace and 5G base station niches. Shengyi Technology Co. Ltd. anchors the mid-tier segment through massive FR-4 production capacity across southern China. Panasonic Corporation differentiates via halogen-free material leadership for server and automotive modules.
PCB laminate refers to the reinforced resin substrate that provides mechanical structure and electrical insulation between conductive copper layers in printed circuit boards, typically manufactured through impregnation of glass fiber or aramid fabric with thermosetting epoxy, polyimide, or ceramic-modified resin systems followed by hot-press lamination. These substrates must maintain dimensional stability across temperatures exceeding 150°C while controlling dielectric loss for signal integrity in high-speed digital and RF applications. FR-4 remains the volume backbone across consumer and industrial applications, though margin pools concentrate in polyimide and Rogers Material segments serving satellite communications and advanced driver-assistance systems. Multi-layer and HDI configurations are outpacing single-layer demand as miniaturization drives layer count expansion in smartphones and medical imaging equipment.
REACH and RoHS frameworks in Europe restrict halogenated flame retardants and specific heavy metals in laminate formulations, compelling reformulation investments across the supply base. China's GB standards and MIIT directives enforce stricter recycling mandates and hazardous substance limits for domestically manufactured electronics substrates. The US EPA and OSHA jointly regulate volatile organic compound emissions from laminate curing processes, affecting plant location and capital expenditure decisions. Stakeholders must monitor evolving PFAS restrictions and copper foil supply constraints as these factors will determine which material platforms achieve cost-competitive scale.
Market Dynamics
Supply concentration around East Asian manufacturing clusters is compressing lead times for high-frequency laminates while simultaneously creating vulnerability to regional logistics disruptions. Taiwan and South Korea now control critical resin impregnation capacity that Western aerospace and automotive OEMs depend upon for thermal-grade substrates.
Growth Catalysts
- EV Platform Thermal Requirements:Electric vehicle battery management systems and inverter modules now specify laminates rated above 180°C continuous operation. Automotive electronics OEMs in Germany, Japan, and the United States are qualifying ceramic-filled hydrocarbon substrates for 800V architectures.
- REACH and RoHS Reformulation Mandates:The European Union's restriction of halogenated flame retardants is forcing substrate suppliers to develop phosphorus-nitrogen synergist systems. Compliant halogen-free laminates command sustained premium positioning in server and medical imaging applications.
- 5G Infrastructure Deployment:Base station antenna arrays and massive MIMO systems require ultra-low loss dielectric materials. China's MIIT spectrum allocations and the United States' FCC mid-band auctions are synchronizing demand cycles for high-frequency PTFE and ceramic-modified laminates.
Market Restraints
- Copper Foil Supply Bottlenecks:Electrodeposited copper foil for ultra-thin laminate constructions faces allocation constraints from Japanese and Taiwanese smelters. Rolling capacity for low-profile foil suitable for fine-line etching remains concentrated with three suppliers.
- PFAS Regulatory Uncertainty:The United States EPA and European ECHA are evaluating per- and polyfluoroalkyl substance restrictions that would impact PTFE-based laminates used in radar and satellite communications. Formulation alternatives remain unqualified for millimeter-wave frequencies.
- Aramid Fiber Cost Volatility:Meta-aramid reinforcement fabrics for aerospace-qualified laminates depend on sole-source polymer supply from DuPont and Teijin. Price swings in aerospace-grade Nomex directly compress margins for satellite PCB fabricators.
Strategic Opportunities
- India Electronics Manufacturing:The country's PLI scheme for semiconductor and component production is attracting laminate distributors to establish regional compounding facilities. Domestic PCB fabrication for consumer and automotive applications will require localized FR-4 and mid-tier material supply.
- Low Earth Orbit Satellite Constellations:SpaceX, Amazon's Project Kuiper, and Chinese state-backed operators are procuring radiation-hardened polyimide laminates in volumes that justify dedicated production lines. Qualification protocols from NASA and ESA create barrier-to-entry protection for early entrants.
- Automotive Functional Safety Certification:ISO 26262 ASIL-rated laminate traceability requirements are displacing commodity suppliers from advanced driver-assistance system modules. Material lots with full chemical composition disclosure capture design wins in lidar and camera processing units.
Industry Challenges
- Process Engineer Scarcity:Lamination press operation and resin rheology optimization require tacit knowledge that aging workforces in Japan and Taiwan possess. Knowledge transfer to Southeast Asian greenfield facilities proceeds slower than capacity expansion timelines.
- Multi-physics Simulation Complexity:Predicting dielectric constant drift across temperature and humidity cycles demands coupled thermal-electrical-mechanical modeling capabilities that most laminate suppliers lack. Customer co-development cycles extend qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCB Laminate Market |
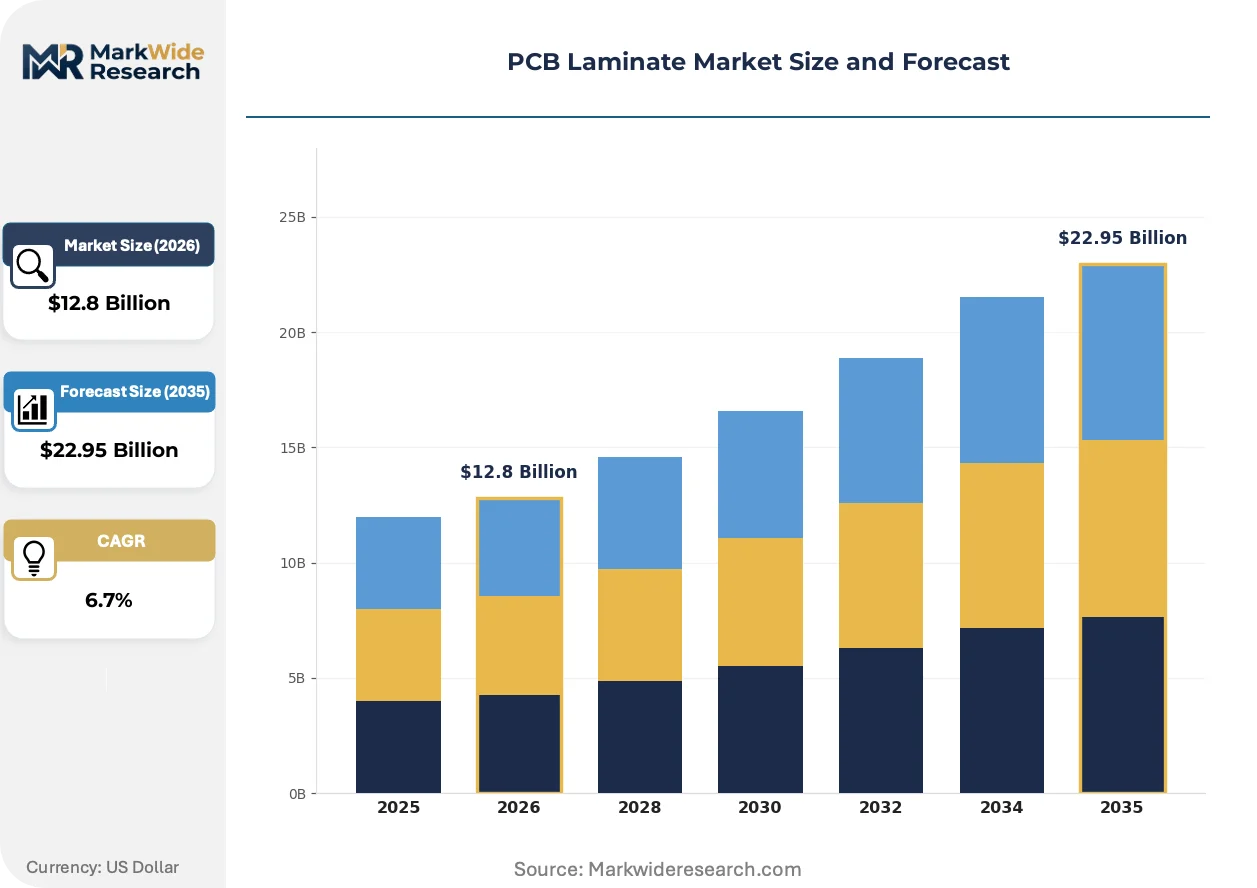
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FR-4, Polyimide, Rogers Material, Epoxy Application: Consumer Electronics, Automotive Electronics, Industrial Applications, Telecommunication Layer Count: Single Layer, Double Layer, Multi-Layer, HDI End User: OEMs, Tier-1 Suppliers, Contract Manufacturers, Aftermarket Providers |
| Companies Covered | Taiyo Yuden Co. Ltd., DuPont de Nemours Inc., Rogers Corporation, Kingboard Chemical Holdings Limited, Shengyi Technology Co. Ltd., Isola Group, Mitsubishi Gas Chemical Company Inc., ITEQ Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCB Laminate Market Emerging Trajectories
Material platforms are diverging into specialized high-frequency formulations and cost-optimized commodity grades as application requirements polarize. The technical frontier now sits at the intersection of thermal management, signal integrity, and regulatory compliance.
Ceramic-filled hydrocarbon laminates is expanding into automotive radar and 5G millimeter-wave backhaul applications. Tier-1 automotive suppliers in Germany and Japan are qualifying these materials for 77-81 GHz frequency bands at volumes that justify dedicated press lines. The technology is expanding into territory previously reserved for pure PTFE constructions, compressing the addressable market for fluoropolymer substrates while enabling cost-down roadmaps for mass-market autonomous driving systems.
China's GB standards and MIIT hazardous substance limits are accelerating domestic substitution of imported halogen-free laminates. Local suppliers in Guangdong and Jiangsu provinces are achieving dielectric performance parity with Japanese competitors for FR-4 and mid-loss categories. Domestic smartphone and server OEMs now specify GB-compliant materials as primary sources, forcing multinational laminate producers to establish in-country compounding joint ventures or accept share erosion.
Direct material sourcing contracts between laminate producers and copper foil mills are displacing distributor-mediated procurement in high-volume consumer electronics. Foxconn, Pegatron, and other contract manufacturers in Taiwan and Vietnam are consolidating resin and foil purchases to secure allocation priority during supply crunches. This concentration is most visible in smartphone PCB procurement, where annual volume commitments now determine laminate pricing tiers and technical service access.
PCB Laminate Market Segmentation
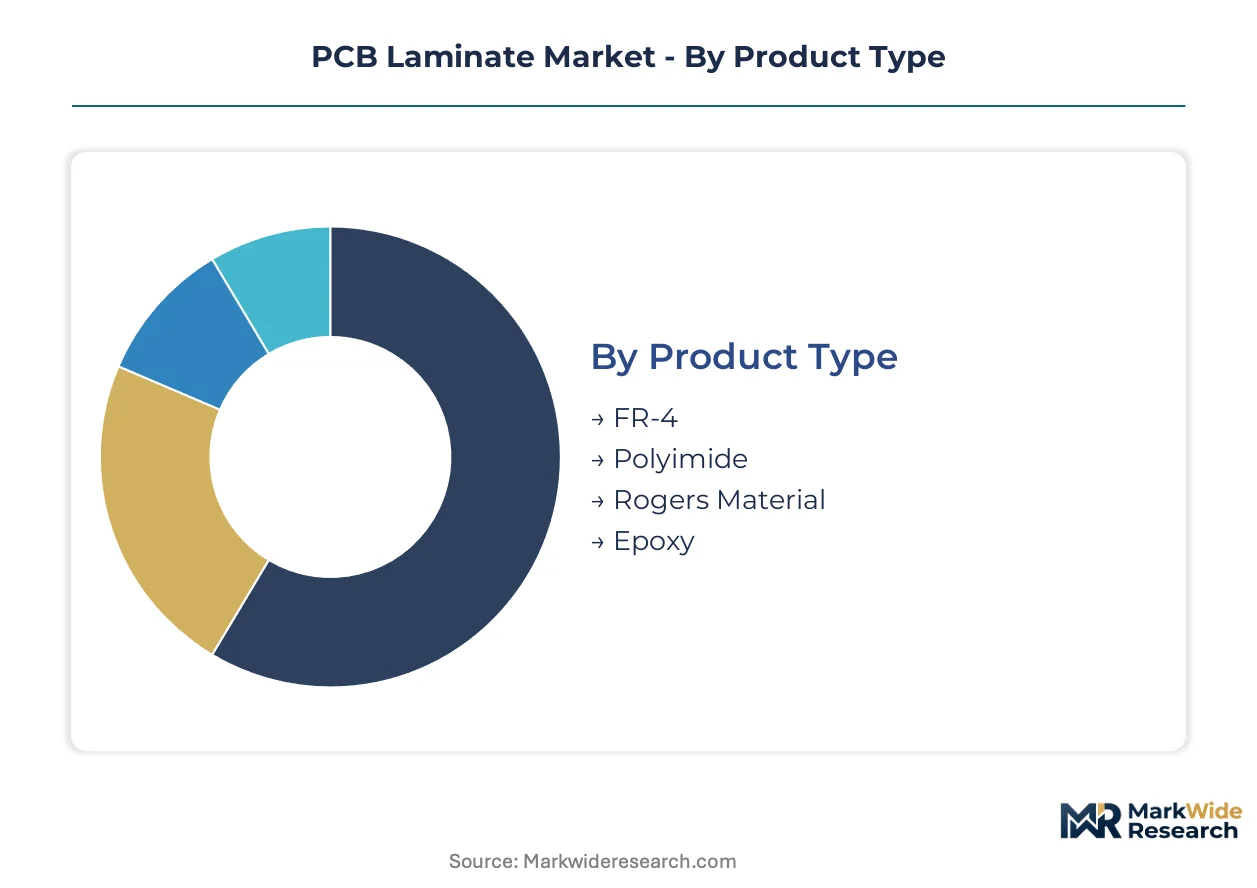
PCB laminate segmentation reveals how material specifications, application requirements, and manufacturing complexity create distinct competitive arenas. Each dimension carries different margin structures, qualification barriers, and supply chain configurations that determine supplier positioning.
Product Type:
Customization intensity varies from standardized commodity formulations to application-engineered specialty resins requiring joint development programs.
- FR-4:Glass-reinforced epoxy laminate remains the volume foundation across consumer and industrial electronics. Chinese contract manufacturers in Shenzhen and Dongguan consume massive quantities for smartphone and appliance PCBs where cost optimization dominates material selection.
- Polyimide:High-temperature thermoplastic substrates withstand continuous operation above 200°C without mechanical degradation. Aerospace OEMs in France and satellite fabricators in California specify these materials for radiation-hardened applications where thermal cycling resistance is non-negotiable.
- Rogers Material:Ceramic-filled hydrocarbon systems deliver controlled dielectric constants for millimeter-wave frequencies. 5G base station deployments in South Korea and automotive radar modules in Germany drive specialized demand.
- Epoxy:Standard thermoset formulations serve cost-sensitive single-layer and double-layer constructions. White goods manufacturers in India and Southeast Asia specify these grades for control board applications.
Leading the category by volume: FR-4. Growing fastest: Rogers Material.
Application:
End-use requirements split between high-reliability qualification-heavy segments and high-volume price-sensitive procurement.
- Consumer Electronics:Smartphones, laptops, and wearables demand thin-core laminates with tight thickness tolerances for HDI processing. Foxconn and Pegatron procurement teams in Taiwan negotiate annual volume contracts that determine laminate pricing tiers.
- Automotive Electronics:Battery management systems and inverter modules specify thermal-grade materials rated above 180°C continuous operation. German automotive OEMs are qualifying ceramic-filled substrates for 800V EV architectures.
- Industrial Applications:Factory automation and power electronics require flame-retardant laminates with extended operating lifespans. Japanese industrial equipment makers prioritize supply continuity over marginal cost reductions.
- Telecommunication:Base station infrastructure and optical networking equipment need ultra-low loss dielectrics. China's MIIT spectrum allocations synchronize demand cycles for high-frequency materials.
Volume concentration: Consumer Electronics. Steepest expansion trajectory: Automotive Electronics.
Layer Count:
Manufacturing complexity escalates with layer multiplication, creating tiered capability requirements across the supplier base.
- Multi-Layer:Four to twelve conductive layers separated by impregnated prepregs enable dense interconnect routing. Server motherboard fabricators in Taiwan and Korea drive technical specifications for high-layer-count constructions.
- HDI:High-density interconnect configurations use microvias and sequential lamination for miniaturized devices. Smartphone PCB specialists in Vietnam and China require ultra-thin dielectric layers for space-constrained designs.
- Double Layer:Simple top-and-bottom copper constructions serve basic consumer and industrial applications. Domestic Indian PCB shops favor these grades for appliance and lighting control boards.
- Single Layer:Single-sided copper on reinforced substrate addresses lowest-cost applications. Toy electronics and disposable medical sensors in China specify these minimal constructions.
Production volume leader: Multi-Layer. Technology momentum: HDI.
End User:
Procurement authority distributes across design-owning OEMs, system integrators, and manufacturing specialists with divergent technical priorities.
- OEMs:Original equipment manufacturers with in-house PCB design teams specify laminate grades directly. Apple and Samsung material engineering groups qualify suppliers through intensive reliability testing protocols.
- Contract Manufacturers:Electronics manufacturing services providers consolidate procurement across multiple OEM programs. Foxconn and Jabil leverage volume aggregation to secure allocation priority during copper foil shortages.
- Tier-1 Suppliers:Automotive and industrial subsystem vendors translate OEM specifications into material orders. Bosch and Continental purchasing organizations maintain approved vendor lists with traceability requirements.
- Aftermarket Providers:Repair and refurbishment specialists source compatible laminates for legacy equipment replacement. Independent repair networks in Europe and North America serve extended product lifecycles.
Dominant procurement authority: OEMs. Fastest-growing engagement model: Contract Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taoyuan and Hsinchu anchor global laminate manufacturing, hosting resin impregnation facilities that supply thermal-grade substrates to automotive and aerospace OEMs across three continents.
China
Guangdong and Jiangsu provinces drive domestic substitution of imported halogen-free laminates through GB standards alignment. MIIT directives enforce stricter hazardous substance limits, accelerating local supplier qualification for smartphone and server OEMs. Shenzhen and Dongguan clusters now supply FR-4 and mid-loss categories to Foxconn and Pegatron assembly operations.
South Korea
Seoul Capital Area fabricators qualify ceramic-filled hydrocarbon substrates for 5G massive MIMO deployments. MFDS chemical safety regulations and dual carbon goals shape resin formulation requirements. Suwon and Gwangmyeong production lines serve Samsung Electronics and LG Innotek with ultra-low loss dielectrics for millimeter-wave applications.
Germany
Bavaria and Baden-Württemberg automotive OEMs specify laminates rated above 180°C for 800V EV inverter modules. REACH restrictions on halogenated flame retardants compel phosphorus-nitrogen synergist adoption. Ingolstadt and Stuttgart engineering centers qualify material lots with full chemical composition disclosure for ISO 26262 ASIL-rated traceability.
United States
California satellite fabricators procure radiation-hardened polyimide laminates for SpaceX and Amazon Project Kuiper constellations. EPA and OSHA jointly regulate volatile organic compound emissions from laminate curing processes. San Jose and Los Angeles qualification labs enforce NASA and ESA protocols that create barrier-to-entry protection for early material entrants.
Japan
Kanto and Kansai regions maintain electrodeposited copper foil supply for ultra-thin laminate constructions. METI industrial standards and JIS certification requirements preserve technical service relationships with aging workforces. Nagoya and Osaka resin compounders optimize rheology for high-layer-count server motherboards through tacit knowledge transfer challenges.
PCB Laminate Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered supply base where resin impregnation capacity determines allocation priority during copper foil crunches. Three to five Asian conglomerates control critical thermal-grade substrate output, while Western specialists dominate aerospace qualification protocols. Strategic archetypes separate ceramic-filled hydrocarbon innovators, halogen-free material leaders, and massive FR-4 volume players. Competitive moves concentrate on backward integration into copper foil supply and geographic expansion through Southeast Asian greenfield facilities.
Within the specialty laminate tier, Rogers Corporation and Isola Group exemplify qualification-heavy positioning for millimeter-wave and satellite applications. Shengyi Technology Co. Ltd. and Kingboard Chemical Holdings Limited occupy the scale-driven commodity segment across southern China manufacturing corridors. Panasonic Corporation represents the halogen-free transition archetype serving server and automotive module demand. These three strategic positions—specialty qualification, volume scale, and regulatory compliance—capture distinct margin pools as material platforms diverge.
| Leading Market Players |
|---|
| Taiyo Yuden Co. Ltd. |
| DuPont de Nemours Inc. |
| Rogers Corporation |
| Kingboard Chemical Holdings Limited |
| Shengyi Technology Co. Ltd. |
| Isola Group |
| Mitsubishi Gas Chemical Company Inc. |
| ITEQ Corporation |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Process engineer concentration in Taiwan and Japan establishes labor-cost differentials that widen pricing spreads between premium ceramic-filled hydrocarbon grades and commodity FR-4 volumes. Resin rheology expertise in aging workforces commands compensation premiums that transmit directly to aerospace-qualified laminate pricing tiers.
Pricing Analysis
Yield-based pricing anchors premium tiers, with aerospace OEMs paying for lot-level traceability that guarantees thermal cycling performance. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-certified automotive grades from industrial FR-4 and disposable single-layer constructions. Cost compression in mid-loss categories intensifies as Chinese suppliers achieve dielectric parity with Japanese incumbents. Contract manufacturers exhibit highest price sensitivity, while satellite fabricators accept sustained premiums for radiation-hardened polyimide qualifications.
Supply Chain Analysis
Refurbishment flows for legacy telecom equipment create secondary copper recovery channels that supplement primary foil supply from Japanese and Taiwanese mills. Critical resin impregnation capacity concentrates in Taiwan, South Korea, and southern China provinces. Raw material inputs draw from DuPont meta-aramid polymers, ceramic filler suppliers, and halogen-free flame retardant compounders. Single-source vulnerability sits with electrodeposited copper foil rolling capacity controlled by three suppliers. Distribution runs through Foxconn and Pegatron procurement consolidators that secure allocation priority during supply crunches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into copper foil supply and captive resin compounding capabilities is reshaping competitive positioning as players race to secure input control. This vertical-integration race rewards early movers with allocation certainty during raw material crunches.
For Market Incumbents: To counter Chinese domestic substitution in halogen-free grades, secure long-term copper foil offtake agreements with Japanese smelters and accelerate Southeast Asian greenfield resin capacity to exploit labor-cost differentials against aging Taiwan workforces. For New Entrants and Emerging Players: Enter via India's PLI-backed electronics manufacturing corridors, targeting domestic FR-4 supply for smartphone and automotive PCB fabrication. Qualify with contract manufacturers seeking second-source security beyond East Asian supply concentration. For Investors and Strategic Acquirers: Re-rating potential sits with ceramic-filled hydrocarbon specialists given 5G massive MIMO and automotive radar qualification pipelines. Long-term viability favors platforms with demonstrated millimeter-wave performance and existing aerospace certification protocols. Monitor ECHA PFAS restriction timelines as inflection indicators for PTFE laminate demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Foil | Captive foil supply insulates against Japanese and Taiwanese smelter allocation constraints during demand surges. |
| Halogen-Free Certification Investment | REACH and RoHS compliance opens premium positioning in German automotive and server module procurement. |
| Southeast Asian Greenfield Expansion | Vietnam and Thailand facilities exploit labor-cost advantages against aging Taiwan process engineering workforces. |
| Automotive ASIL Traceability Systems | ISO 26262 material lot disclosure captures design wins in Bosch and Continental lidar processing units. |
| Satellite Qualification Protocol Entry | NASA and ESA radiation-hardening certification creates barrier-to-entry protection for polyimide laminate supply. |
Methodological Framework
Document review covered customs trade records, SEC filings from laminate producers, and MIIT hazardous substance directives, complemented by interviews with resin compounders, PCB fabrication plant managers, OEM material engineering directors, and copper foil procurement leads at contract manufacturers. Secondary validation drew from Taiwan PCB Association production statistics, Japan Electronics Packaging Circuits Association technical bulletins, and ECHA substance restriction databases. Bottom-up demand modeling across EV platform thermal requirements and top-down supply capacity assessments triangulated market sizing.
Segment-level value outputs reflect material-grade pricing spreads across FR-4, polyimide, Rogers Material, and epoxy categories, with layer count complexity and end-user procurement authority as cross-cutting dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating 5G infrastructure deployment cycles and automotive electronics thermal-grade adoption curves. Forecast inputs included copper foil capacity expansion timelines and PFAS regulatory evaluation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restrictions or copper supply disruptions. Practitioners should monitor ECHA restriction proposal advancement and Japanese foil mill capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
UK Real Estate Hospitality Market
Others
Bitcoin Mining Servers Market
Others
Dried Fruit Extracts Market
Others
Lined Tank Market
Others
Social Media Engagement Applications Market
Others
Hybrid Switchgear Market
Others
Global Application Testing Services Market
Others
Mobile Computer Cart Market
Others
Digital Education Projector Market
Others
Europe Street Lighting Market
Others
Content Experience Platforms Market
Others
Global Extruded Plastics Market
Others
Sunflower Husk Pellets Market
Others
Handheld Mobile Computers Market
Others
North America Compressor Oil Market
Others
Europe Transportation Management Systems Market