
 Asia-Pacific Arts Promoters Market | 2026-2036
Asia-Pacific Arts Promoters Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Arts Promoters Market Insights
Premium experiential programming is unwinding across the Asia-Pacific Arts Promoters Market as audiences trade passive attendance for immersive, multi-format cultural events. Hong Kong Art Basel leverages its auction-house partnerships to secure pre-event provenance narratives that command higher ticket tiers. Sydney Opera House Trust anchors waterfront programming with permanent technical infrastructure that reduces per-show setup costs for touring promoters. National Centre for the Performing Arts competes through state-backed commissioning power that locks in multi-year residency cycles with international touring companies.
Arts promoters are specialized service entities that coordinate talent procurement, venue logistics, sponsorship aggregation, and audience development for live cultural events, typically operating on fee-plus-commission structures tied to gross event revenue or fixed retainer contracts with institutional clients. The service-type dimension shows event promotion and sponsorship facilitation commanding the deepest margin pools where promoter risk-sharing with corporate underwriters creates recurring revenue anchors. Within industry verticals, performing arts and music dominate current transaction volumes while visual arts programming is expanding fastest through hybrid physical-digital exhibition formats that extend audience reach beyond single-city footprints.
Japan's Agency for Cultural Affairs and METI administer Cool Japan export subsidies that lower promoter capital requirements for overseas touring, while Australia's Creative Australia framework directs federal funding toward presenter-consortium models that pool regional venue networks. Singapore's National Arts Council licensing requirements for public assembly events shape promoter insurance and safety compliance costs. Stakeholders must track how evolving digital-content rights frameworks across Australian, Japanese, and Singaporean jurisdictions redefine promoter revenue participation in streamed and recorded ancillary outputs.
Market Dynamics
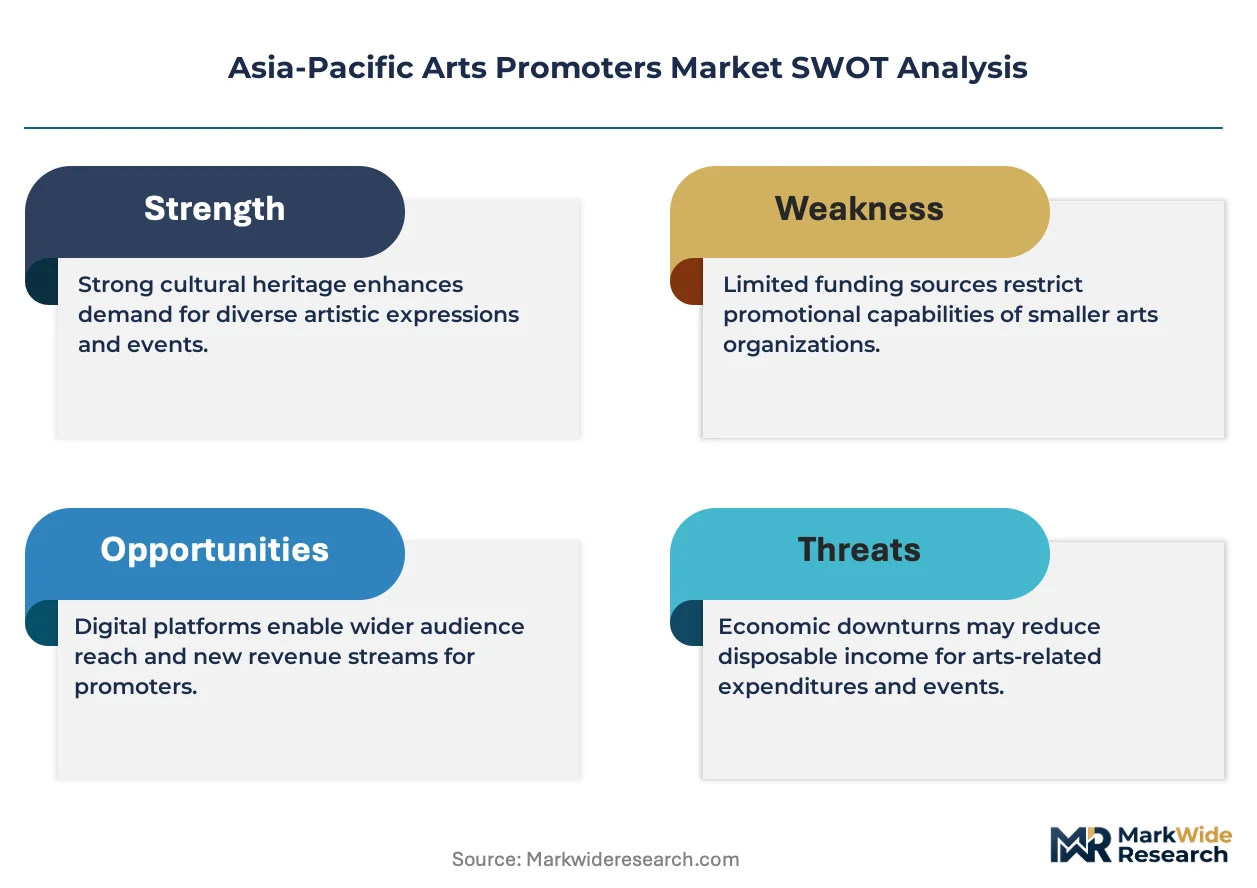
Corporate sponsorship aggregation is consolidating promoter revenue models across the Asia-Pacific Arts Promoters Market, with underwriters demanding deeper risk-sharing and longer-term programming commitments in exchange for capital access.
Growth Catalysts
- Creative Australia funding framework:Federal presenter-consortium models pool regional venue networks, reducing per-tour logistics costs for touring promoters operating across multiple Australian states.
- Hybrid physical-digital exhibition formats:Visual arts promoters extend audience reach beyond single-city footprints through streamed ancillary outputs and virtual gallery extensions.
- Southeast Asia:Corporate sponsorship budgets for live music festivals are expanding, creating recurring revenue anchors for promoters willing to co-develop branded experiential programming.
Market Restraints
- Cool Japan subsidy dependency:Promoters targeting Japanese cultural exports face capital requirement volatility when METI export subsidy allocations fluctuate between fiscal cycles.
- Singapore licensing compliance:National Arts Council public assembly requirements impose elevated insurance and safety certification costs that compress margins on smaller-scale events.
- Technical infrastructure concentration:Permanent waterfront technical installations at Sydney Opera House Trust reduce setup costs for favored partners while raising barriers for independent touring promoters lacking comparable venue relationships.
Strategic Opportunities
- Indonesia and Philippines live music markets:Underpenetrated secondary cities present first-mover advantages for promoters establishing recurring festival properties before venue network consolidation.
- Digital-content rights frameworks:Evolving Australian and Japanese jurisdiction definitions for streamed and recorded ancillary outputs create new revenue participation models for promoter-held intellectual property.
- Cool Japan-METI convergence with Creative Australia:Bilateral presenter exchange programs could unlock joint commissioning pools for cross-regional touring productions.
Industry Challenges
- Multi-year residency contract negotiation:Securing locked cycles with international touring companies demands specialized talent procurement expertise that concentrates among established National Centre for the Performing Arts relationships.
- Provenance narrative development:Auction-house partnership cultivation for pre-event authentication requires dedicated staff capabilities that smaller promoters struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Arts Promoters Market |
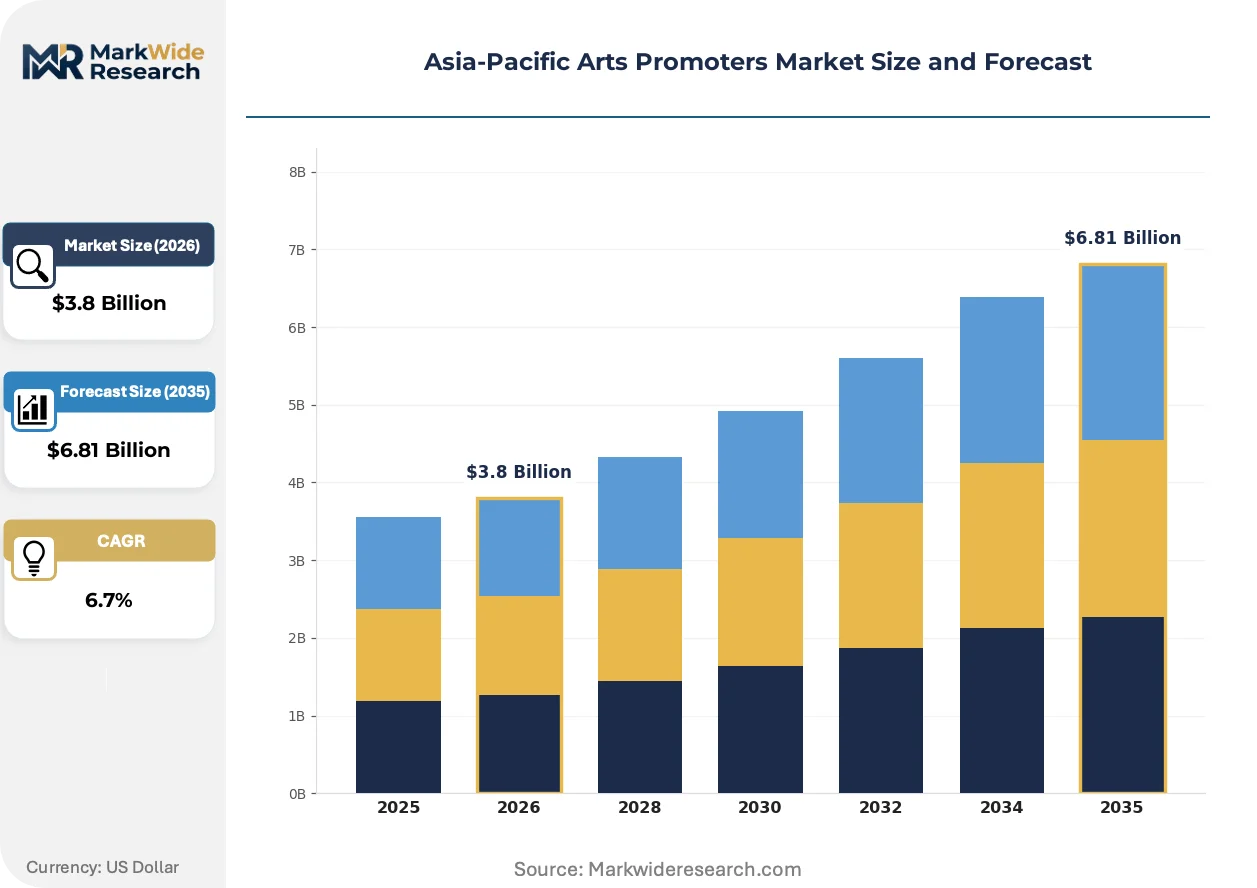
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Event Promotion, Talent Management, Venue Booking, Sponsorship Facilitation Industry Vertical: Music, Visual Arts, Performing Arts, Literature Client Type: Individual Artists, Business Corporations, Educational Institutions, Non-Profit Organizations Distribution Channel: Online Platforms, Physical Venues, Social Media, Direct Sales |
| Companies Covered | Digital Arts, Hong Kong Art Basel, Tokyo Art Fair, Jakarta Contemporary Art and Design Fair, Singapore Art Museum, National Centre for the Performing Arts, Shanghai Grand Theatre, Art Basel Hong Kong, Sydney Opera House Trust, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Arts Promoters Market Trends and Innovations
Experiential programming formats are fragmenting audience attention across simultaneous physical and digital touchpoints, forcing promoters to reconfigure talent procurement and venue logistics around hybrid delivery architectures.
Immersive multi-format cultural events are supplanting passive attendance models as the default programming architecture. Younger demographics in Hong Kong and Singapore demand participatory installations over traditional seated performances. This shift is compressing promoter planning cycles and requiring permanent technical infrastructure investments that favor institutional venue partnerships over rental models.
Australia's Creative Australia framework is redirecting federal capital toward presenter-consortium structures that aggregate regional venue networks. Promoters must now navigate pooled procurement requirements and shared technical rider standards across consortium members. Visual arts verticals face the steepest adaptation curve as funding eligibility ties to demonstrated multi-venue touring capacity.
Audience development strategies now center on pre-event provenance narrative construction rather than post-event critical reception. Hong Kong Art Basel's auction-house partnerships command premium ticket tiers through authenticated backstories. Japanese gallery-district clusters are replicating this model, though smaller promoters lack the institutional relationships to source comparable narrative assets.
Asia-Pacific Arts Promoters Market Segmentation
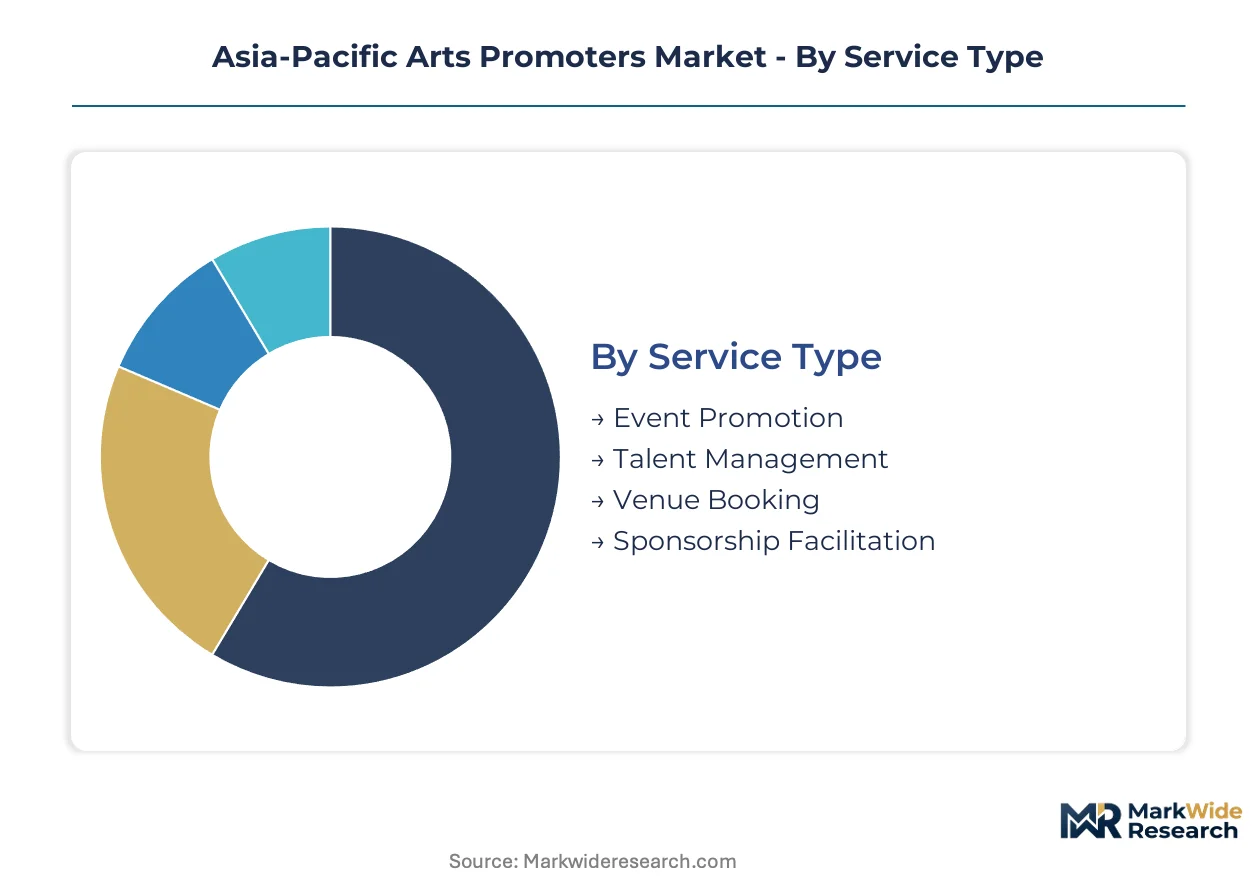
Promoter revenue models diverge sharply across service configurations, with fee-plus-commission structures varying by risk-sharing depth and client institutional backing. Regulatory frameworks in Australia, Japan, and Singapore reshape segment profitability through divergent subsidy access and compliance cost burdens.
Service Type:
Australia's Creative Australia funding framework privileges presenter-consortium models that reshape which service types capture federal capital flows.
- Event Promotion:Coordinates end-to-end production logistics including talent procurement, venue contracting, and audience development for single or recurring cultural properties. Australia's major performing arts centers concentrate demand where Sydney Opera House Trust technical infrastructure reduces per-show setup costs for favored promoter partners.
- Sponsorship Facilitation:Aggregates corporate underwriters and negotiates risk-sharing arrangements tied to branded experiential programming. Southeast Asian live music festivals are expanding corporate budgets, creating recurring revenue anchors where promoter co-development commitments secure multi-year capital access.
- Talent Management:Maintains exclusive or preferred artist representation agreements that lock in procurement priority for touring cycles.
- Venue Booking:Secures performance windows across institutional and commercial rental properties with technical rider compliance.
Established volume favors Event Promotion; emerging adoption favors Sponsorship Facilitation.
Industry Vertical:
Cost tier differentiation separates state-backed commissioning power from independent promoter margin pressure.
- Performing Arts:Encompasses theater, dance, and opera programming where multi-year residency contracts demand specialized procurement expertise. Japan's National Centre anchors demand through locked cycles with international touring companies that concentrate among established promoter relationships.
- Visual Arts:Spans gallery exhibitions, biennales, and hybrid physical-digital formats that extend audience reach beyond single-city footprints. Hong Kong Art Basel auction-house partnerships command premium ticket tiers through pre-event provenance authentication capabilities.
- Music:Covers live concerts, festivals, and touring productions across amplified and acoustic configurations.
- Literature:Includes author tours, festival programming, and spoken-word events with lower technical infrastructure requirements.
Margin concentration sits with Performing Arts; Visual Arts climbs the fastest through hybrid format expansion.
Client Type:
Customer type determines fee structure rigidity and payment security terms across the Asia-Pacific promoter base.
- Business Corporations:Engages promoters for branded experiential programming, employee cultural programming, and client entertainment properties with fixed retainer contracts. Singapore's National Arts Council licensing requirements for public assembly events shape insurance and safety compliance costs that compress margins on smaller-scale corporate engagements.
- Non-Profit Organizations:Relies on grant-funded programming where Creative Australia and Cool Japan subsidy eligibility determines project viability.
- Individual Artists:Purchases à la carte services on fee-plus-commission structures tied to gross event revenue.
- Educational Institutions:Contracts campus programming and student audience development with pooled procurement across consortium networks.
Payment security favors Business Corporations; subsidy access favors Non-Profit Organizations.
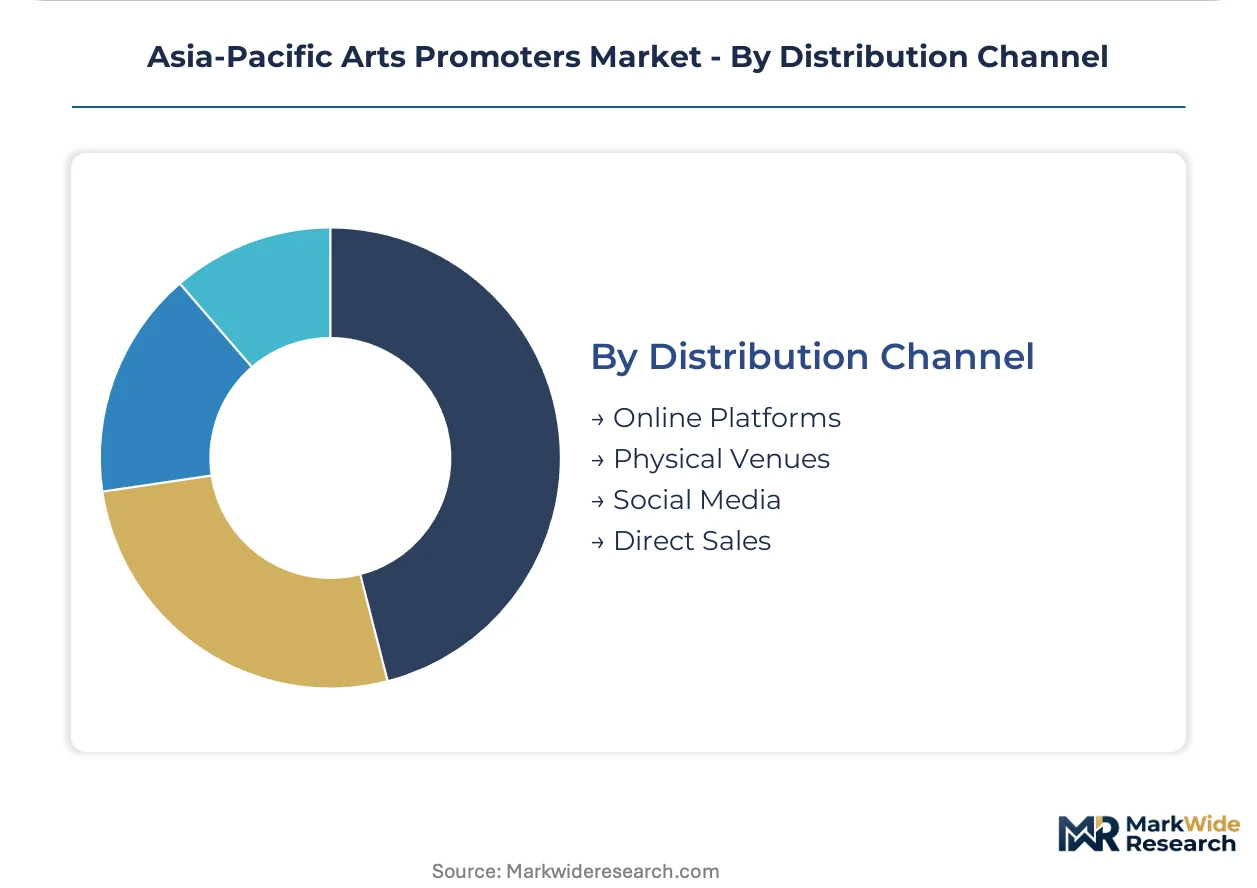
Distribution Channel:
Supply concentration in permanent technical installations advantages certain channel combinations over rental-dependent models.
- Physical Venues:Delivers programming through owned or contracted performance spaces where waterfront technical infrastructure at Sydney Opera House Trust reduces setup costs for touring promoters with established venue relationships. Independent operators face elevated barriers without comparable institutional partnerships.
- Online Platforms:Streams and records ancillary outputs where evolving Australian and Japanese digital-content rights frameworks redefine promoter revenue participation.
- Social Media:Builds pre-event audience development and provenance narrative distribution for authenticated backstory construction.
- Direct Sales:Maintains subscriber bases and membership programs for recurring patron relationships.
Revenue stability favors Physical Venues; rights complexity favors Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Promoter infrastructure concentrates in Australia's major performing arts centers and Japan's gallery-district clusters, where permanent technical installations and state-backed commissioning power create divergent competitive barriers across the region.
Australia
Sydney Opera House Trust anchors waterfront programming with permanent technical infrastructure that reduces per-show setup costs for favored touring partners. The Creative Australia funding framework directs federal capital toward presenter-consortium models that pool regional venue networks across multiple states. Melbourne and Sydney dominate transaction volumes where consortium procurement requirements reshape promoter service configurations.
Japan
Tokyo's gallery-district clusters replicate Hong Kong's provenance narrative model for premium ticket tier construction. METI and the Agency for Cultural Affairs administer Cool Japan export subsidies that lower promoter capital requirements for overseas touring cycles. Osaka and Nagoya present secondary concentration points where smaller promoters struggle to source comparable auction-house partnerships.
Singapore
Corporate demand for branded experiential programming drives promoter revenue models in live music and visual arts verticals. National Arts Council licensing requirements for public assembly events impose elevated insurance and safety certification costs that compress margins on smaller-scale engagements. The city-state's institutional venue network concentrates procurement power among established promoter relationships.
China
National Centre for the Performing Arts competes through state-backed commissioning power that locks in multi-year residency cycles with international touring companies. Shanghai Grand Theatre anchors demand in the Yangtze River Delta with technical infrastructure comparable to Sydney's waterfront installations. Beijing's state-funded institutions concentrate procurement expertise that independent promoters cannot replicate.
Indonesia
Jakarta Contemporary Art and Design Fair represents first-mover positioning in underpenetrated secondary cities before venue network consolidation accelerates. Limited permanent technical infrastructure elevates setup costs for touring promoters lacking established local partnerships. Bali and Surabaya present expansion corridors where recurring festival properties could anchor regional promoter presence.
Asia-Pacific Arts Promoters Market Competitive Landscape
Concentration sits with institutional venue operators and state-backed cultural agencies that control permanent infrastructure and subsidy access. The market structures around three tiers: federally funded national centers with commissioning power, municipal venue trusts with technical infrastructure advantages, and independent promoters dependent on rental models and volatile sponsorship cycles. Competitive moves center on consortium formation for pooled procurement and bilateral presenter exchange programs for cross-regional touring rights.
Within the institutional venue tier, Sydney Opera House Trust and National Centre for the Performing Arts exemplify state-backed competitive positioning where permanent infrastructure and multi-year residency contracts concentrate procurement power. Hong Kong Art Basel and Tokyo Art Fair occupy positions in the premium visual arts segment where auction-house partnerships enable provenance narrative construction. Digital Arts represents the independent promoter archetype operating without comparable institutional relationships or subsidy access.
| Leading Market Players |
|---|
| Digital Arts |
| Hong Kong Art Basel |
| Tokyo Art Fair |
| Jakarta Contemporary Art and Design Fair |
| Singapore Art Museum |
| National Centre for the Performing Arts |
| Shanghai Grand Theatre |
| Art Basel Hong Kong |
| Sydney Opera House Trust |
| Others |
Pricing and Supply Chain Analysis
Permanent technical infrastructure at Sydney Opera House Trust and National Centre for the Performing Arts generates scale economies that compress per-show setup costs for favored partners while elevating price floors for independent operators lacking comparable venue relationships. This capacity-utilization asymmetry concentrates pricing power among institutional venue operators and reshapes promoter margin structures across the Asia-Pacific region.
Pricing Analysis
Singapore's National Arts Council licensing requirements dictate the pricing tier structure for public assembly events, imposing elevated insurance and safety certification costs that compress margins on smaller-scale engagements. Three-tier pricing structure across premium, standard, and economy levels separates state-backed commissioning power from independent promoter offerings, with provenance-authenticated visual arts programming commanding the highest tier. Pricing pressure stems from corporate sponsorship underwriters demanding deeper risk-sharing and longer-term programming commitments in exchange for capital access. Non-profit organizations with Creative Australia or Cool Japan subsidy eligibility exhibit lowest price sensitivity; individual artists purchasing à la carte services face highest cost compression.
Supply Chain Analysis
Container availability fluctuations across the Shanghai-Singapore trade lane elevate inbound logistics costs for touring equipment and temporary exhibition infrastructure. Supply concentration rests on Japan for specialized gallery lighting and audio-visual systems, Australia for permanent waterfront technical installations, and China for modular staging components. Raw material dependencies include aluminum truss systems, LED display panels, and acoustic dampening materials. Single-source vulnerability runs through METI's Cool Japan subsidy allocation cycles, which determine promoter capital access for overseas touring. Distribution feeds from institutional venue networks with permanent infrastructure toward rental-dependent independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid physical-digital exhibition formats are disrupting traditional promoter revenue models, with Australia's evolving digital-content rights frameworks creating new intellectual property participation mechanisms that reshape competitive positioning across the Asia-Pacific Arts Promoters Market.
For Market Incumbents: Shield commission structures from margin erosion by deepening permanent technical infrastructure partnerships with Sydney Opera House Trust and National Centre for the Performing Arts. Consolidate auction-house relationships for provenance narrative development before smaller competitors replicate Hong Kong Art Basel's authentication capabilities. Vertical integration into digital-content rights management represents the critical defensive lever against independent promoters leveraging streamed ancillary outputs. For New Entrants and Emerging Players: Differentiate on underpenetrated secondary city positioning in Indonesia and Philippines live music markets before venue network consolidation accelerates. Target Jakarta Contemporary Art and Design Fair's first-mover corridor for recurring festival properties that anchor regional presence. White-space availability concentrates in hybrid-format visual arts programming where technical infrastructure requirements favor consortium membership over independent rental models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors presenter-consortium operators with demonstrated multi-venue touring capacity and established relationships with Creative Australia funding frameworks. Long-term viability hinges on subsidy-access durability and digital-rights portfolio depth. Acquisition target archetype: independent promoters with locked talent management agreements and nascent corporate sponsorship facilitation capabilities. The signal to watch is bilateral presenter exchange program formation between Cool Japan-METI and Creative Australia consortia.| Strategic Initiative | Industry Significance |
|---|---|
| Presenter-Consortium Formation | Creative Australia funding eligibility requires pooled regional venue networks across Australian states. |
| Digital-Content Rights Acquisition | Australian and Japanese jurisdiction evolution creates new revenue participation models for streamed outputs. |
| Corporate Sponsorship Facilitation | Southeast Asian live music festivals demand multi-year branded experiential programming commitments. |
| Provenance Narrative Development | Hong Kong Art Basel's auction-house partnerships command premium ticket tiers through authentication capabilities. |
| Permanent Technical Infrastructure Investment | Sydney Opera House Trust waterfront installations reduce per-show setup costs for favored touring partners. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with arts promoters, venue trust executives, corporate sponsorship managers, and National Arts Council licensing officers. Secondary validation drew from Creative Australia funding disclosures, METI Cool Japan subsidy allocations, Singapore public assembly regulatory filings, and institutional venue procurement records. Bottom-up promoter revenue modeling triangulated against top-down federal arts funding appropriations across the analysis window.
Across the projection horizon, the analytical framework segmented volume and value outputs by service type, industry vertical, client type, and distribution channel dimensions specific to promoter operations. CAGRs were derived from trend extrapolation of federal funding trajectories and corporate sponsorship budget growth patterns. Industry-specific forecast inputs included METI export subsidy allocation volatility and evolving digital-content rights framework definitions in Australian and Japanese jurisdictions.
Decision-makers should treat outputs as directional under stable subsidy allocation and corporate sponsorship commitment assumptions; material deviation in METI fiscal cycles or Creative Australia funding priorities would warrant model refresh. Specific risk factors include regulatory restriction tightening in Singapore public assembly licensing and auction-house partnership concentration barriers in Japanese gallery-district clusters. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Virtual Events Market
Media and Entertainment
Indonesia Digital Advertising Market
Media and Entertainment
United States Gaming Market
Media and Entertainment
GCC Gaming Headsets Market
Media and Entertainment
Mobile Game Controller Market
Media and Entertainment
Japan Webtoons Market
Media and Entertainment
Online Video Platform Market
Media and Entertainment
Global Blogging Platforms Market
Media and Entertainment
Camera Jib Market
Media and Entertainment
Traditional TV and Home Video Market
Media and Entertainment
RPG Games Market
Media and Entertainment
South Korea Gaming Peripherals Market
Media and Entertainment
Global Online Gambling and Betting Market
Media and Entertainment
Japan Catalog Market
Media and Entertainment
Australia OOH and DOOH Market
Media and Entertainment
Pay TV Services Market