
 North America Arts Promoters Market | 2026-2036
North America Arts Promoters Market Size, Share, and Industry Trends Forecast 2026-2036
North America Arts Promoters Market Insights
Live music festivals is recalibrating the revenue mix for North American arts promoters, pulling budgets from traditional exhibition formats toward immersive, multi-day experiences. Gagosian leverages its blue-chip artist roster to sustain collector loyalty across Los Angeles and New York. Hauser & Wirth anchors its competitive position through integrated venue management, operating exhibition spaces that double as event infrastructure. David Zwirner Gallery differentiates via digital programming, streaming studio visits and virtual previews to extend geographic reach beyond physical gallery walls.
Arts promoters are entities that contract, organize, and publicize cultural events across live and mediated formats, typically managing talent procurement, venue logistics, audience development, and sponsorship fulfillment for fee-based or commission-based compensation. Their primary commercial purpose is reducing transaction costs between artists, venues, and audiences while capturing value through ticket sales, sponsorship packages, and ancillary merchandise or concession revenue. Event management services command the deepest margin pools due to recurring corporate contracts and multi-year festival properties. Music festivals represent the fastest-growing event type, driven by brand sponsorship inflation and demographic skew toward experiential consumption among younger attendees. Art exhibitions remain mature, with stable but slower growth tied to institutional funding cycles and collector travel patterns.
The U.S. Federal Communications Commission shapes digital promotion channels through advertising disclosure requirements, while Canada's Competition Bureau enforces truth-in-advertising standards for event claims and ticket pricing. Mexico's Federal Consumer Protection Agency monitors refund and cancellation policies, creating compliance costs for cross-border touring productions. Stakeholders must monitor how platform liability rules and state-level ticket resale legislation reshape channel economics and pricing autonomy.
Market Dynamics
Digital ticketing infrastructure is compressing audience acquisition timelines while algorithmic distribution on social platforms concentrates promotional reach among a handful of dominant channels, reshaping how arts promoters allocate marketing spend and negotiate platform dependencies.
Growth Catalysts
- Experiential marketing budgets:Corporate sponsors are redirecting advertising dollars toward live music festivals as brand-safe environments for immersive consumer engagement, expanding the addressable revenue pool for multi-day event properties.
- Integrated venue management:Promoters operating captive exhibition and performance spaces capture ancillary concession and merchandise revenue streams that third-party rentals cannot access.
- Canada's Competition Bureau enforcement:Truth-in-advertising standards for ticket pricing and event claims are building consumer trust in primary market transactions, reducing friction in advance sales cycles.
Market Restraints
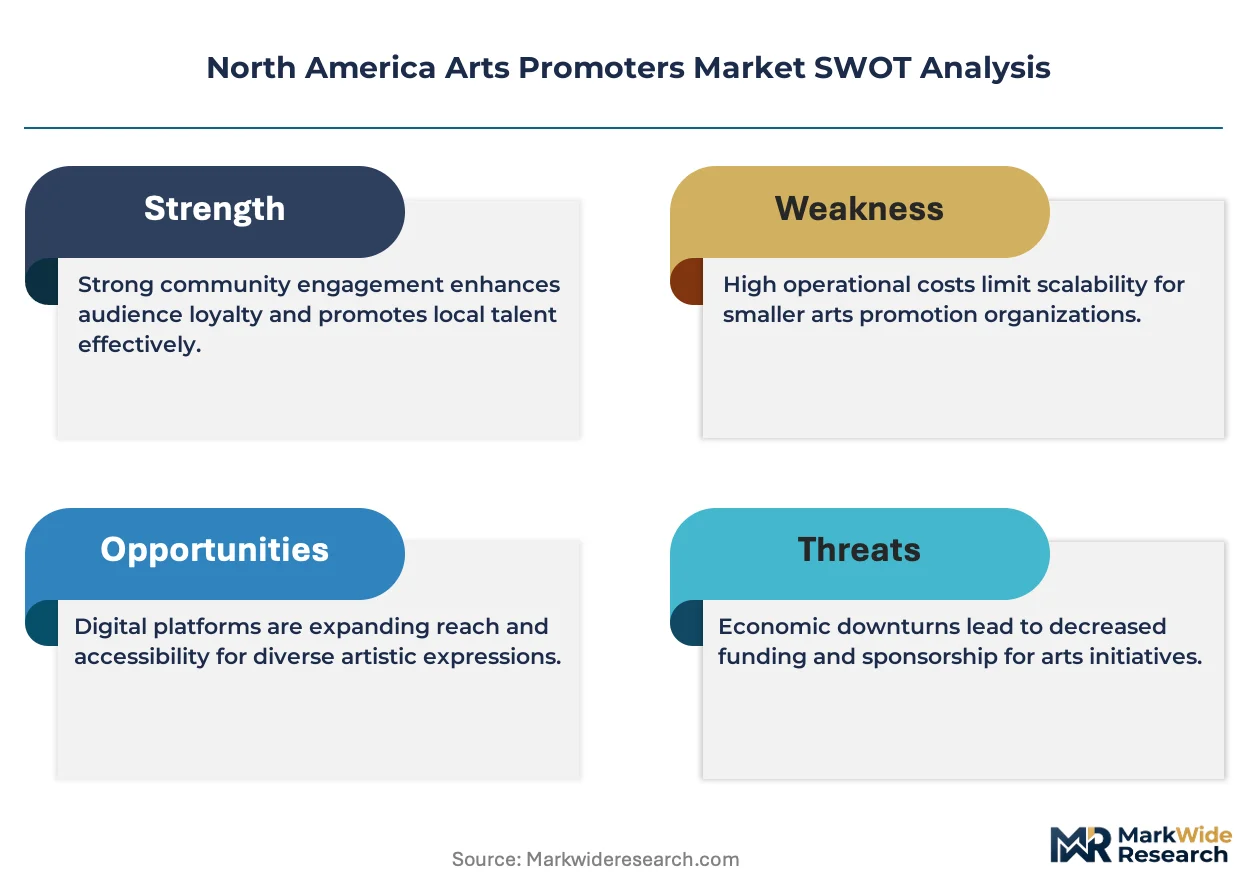
- Talent procurement cost inflation:Headliner artist guarantees have escalated as streaming revenue reduces touring frequency, squeezing promoter margins on single-night engagements.
- Venue concentration in coastal metros:California, New York, and Texas host disproportionate shares of suitable infrastructure, limiting scalable touring economics for mid-tier acts in secondary markets.
- Platform algorithm dependency:Social media distribution gatekeepers extract rising advertising tolls for audience reach, converting organic discovery into pay-to-play dynamics.
Strategic Opportunities
- Underpenetrated Texas corridor:Houston and Dallas-Fort Worth exhibit venue supply constraints relative to disposable income growth, creating first-mover advantages for integrated promoter-developer partnerships.
- Hybrid physical-digital programming:Streaming studio visits and virtual previews extend geographic reach beyond physical gallery walls, unlocking subscriber revenue from non-attendee audiences.
- Mexico cross-border touring:The Federal Consumer Protection Agency's standardization of refund policies reduces operational uncertainty for promoters routing productions through Mexico City and Guadalajara.
Industry Challenges
- Technical production labor scarcity:Specialized roles in lighting design, stage engineering, and live broadcast integration face pipeline gaps as training programs lag technology evolution.
- Legacy ticketing system integration:Promoters operating acquired festival properties confront fragmented data architectures that obstruct unified customer analytics and dynamic pricing deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Arts Promoters Market |
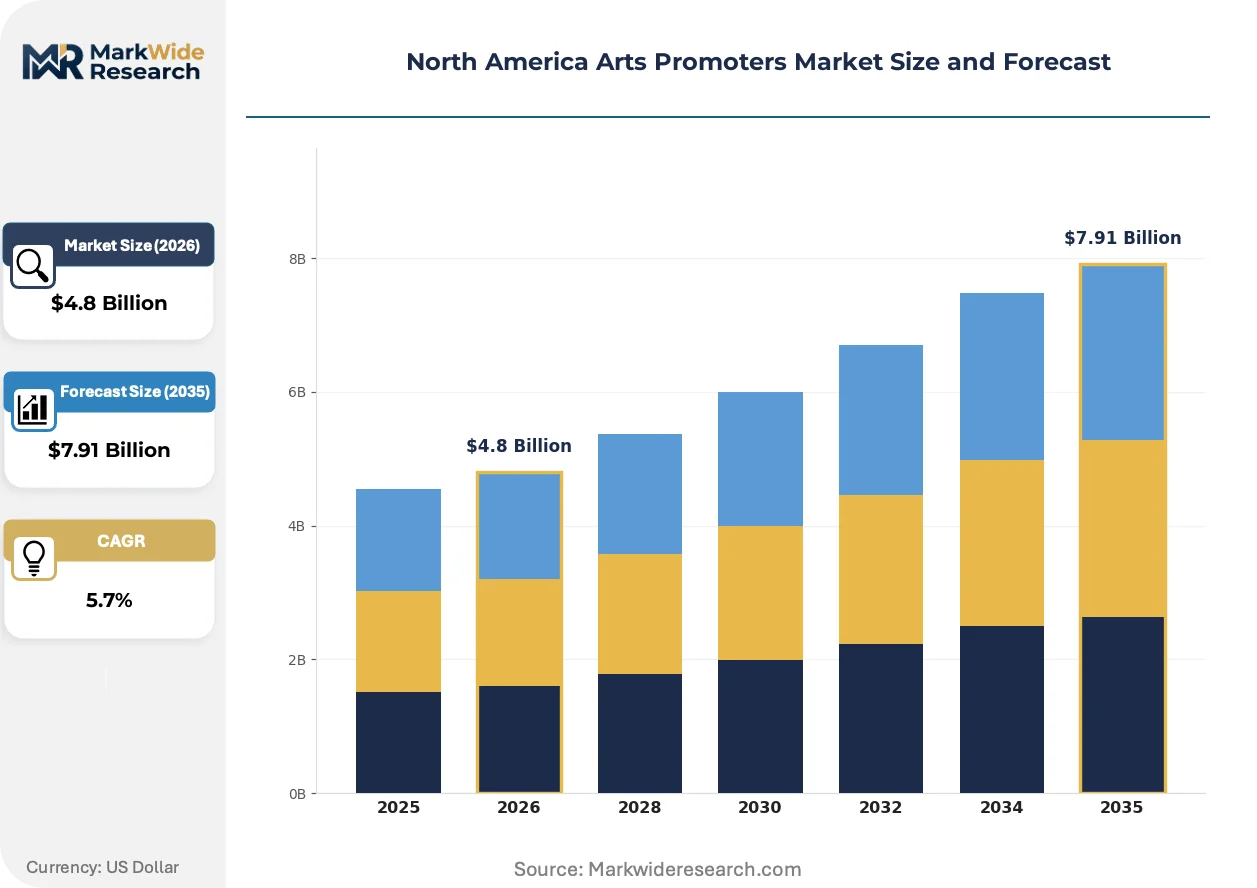
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Event Management, Promotion Services, Venue Management, Sponsorship Coordination Client Type: Corporates, NGOs, Individuals, Government Agencies Promotion Channel: Social Media, Direct Mail, Online Advertising, Print Media Event Type: Music Festivals, Art Exhibitions, Trade Shows, Cultural Events |
| Companies Covered | Gagosian, Hauser & Wirth, David Zwirner Gallery, Pace Gallery, Matthew Marks Gallery, Ascaso Gallery, Chroma Gallery, Fabien Castanier Gallery, RoGallery, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Arts Promoters Market Trends and Innovations
Algorithmic content distribution and immersive production technologies are reconfiguring how audiences discover, purchase, and experience cultural events across North American markets.
Dynamic pricing engines are electrifying revenue optimization for arts promoters by adjusting ticket values in real-time based on demand velocity, inventory position, and competitor pricing. Major festival operators and regional theater chains are deploying these systems for 40-60% of available inventory. The technology is compressing the revenue gap between early-bird and final-release pricing tiers while reducing unsold seat rates.
The U.S. Federal Communications Commission's advertising disclosure requirements for digital promotion channels are tightening compliance obligations for social media campaigns and influencer partnerships. Promoters must now maintain auditable records of sponsored content relationships and algorithmic targeting parameters. Music festival marketing teams are responding by building in-house legal review functions and platform-specific disclosure templates.
Collector travel patterns are fragmenting across multiple hub cities rather than concentrating on traditional seasonal calendar peaks. Art fair promoters are responding by dispersing programming across Los Angeles, Miami, and Mexico City rather than anchoring exclusively on New York fall seasons. This geographic rotation is forcing exhibitors and galleries to maintain year-round presence costs across multiple metropolitan markets rather than seasonal deployment.
North America Arts Promoters Market Segmentation
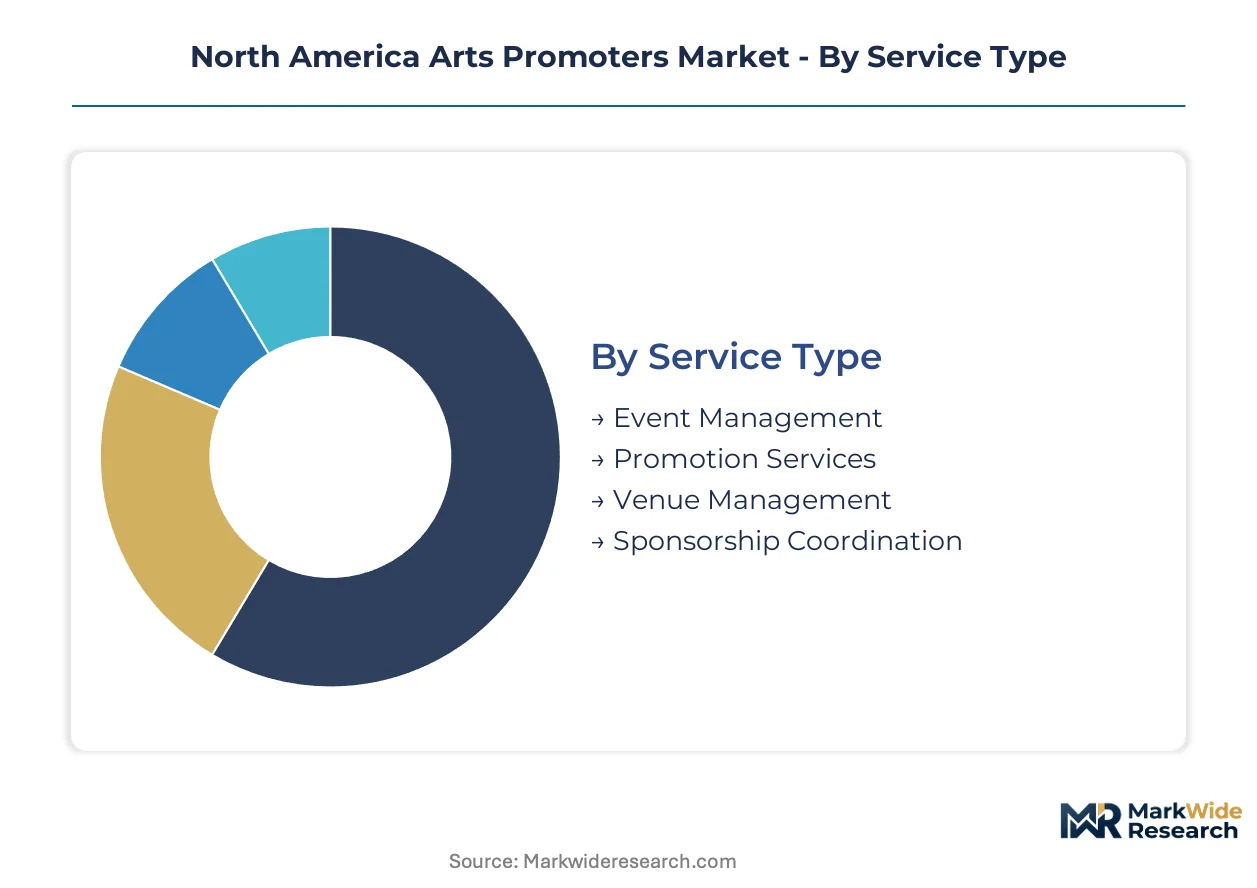
Segmentation in the North America arts promoters market reveals distinct capital requirements and margin profiles across service delivery models. Promoters must match infrastructure investments to client risk tolerance and event scale.
Service Type:
Capital intensity varies sharply across service models, with physical infrastructure commanding the heaviest upfront commitments.
- Event Management:Full-cycle production coordination spanning talent procurement, technical staging, and on-site logistics. California and Texas promoters concentrate here to capture corporate hospitality budgets and multi-day festival properties. Recurring contracts with Fortune 500 sponsors stabilize cash flow across seasonal demand cycles.
- Venue Management:Captive ownership or long-term leases of exhibition halls, theaters, and outdoor amphitheaters. Operators in New York and Los Angeles leverage these assets for ancillary concession, parking, and merchandise revenue streams unavailable to rental-dependent competitors. Fixed cost bases demand high utilization rates.
- Promotion Services:Campaign design, media buying, and audience development without operational liability for physical production. Lower barriers to entry attract boutique agencies serving regional theater chains and museum exhibition cycles.
- Sponsorship Coordination:Brand partnership negotiation and fulfillment, typically layered atop other service lines. Margins compress as direct brand-to-artist relationships displace intermediary roles.
Event management absorbs the bulk of installed capacity; venue management is expanding most quickly as promoters seek captive revenue streams.
Client Type:
Contract structures diverge by client sophistication, with corporate accounts demanding outcome-based fee arrangements.
- Corporates:Experiential marketing budgets from technology, financial services, and consumer brands fund proprietary festivals and executive retreat programming. Texas energy sector and California technology firms dominate commissioning volume.
- Individuals:Private collectors and family offices underwriting solo exhibitions, gala fundraisers, or commemorative performances. New York and Los Angeles concentrate ultra-high-net-worth demand.
- Government Agencies:Municipal tourism authorities and federal cultural programs supporting public festivals and heritage site activations. Canada's Canada Council for the Arts and U.S. National Endowment for the Arts shape funding cycles.
- NGOs:Museum foundations, educational institutions, and advocacy organizations with restricted endowment-driven budgets and board governance requirements.
Corporate clients absorb the bulk of installed capacity; individual commissioning is climbing the fastest as wealth concentration accelerates bespoke programming.
Promotion Channel:
Platform economics reshape promotional spend allocation, with algorithmic gatekeepers extracting rising tolls for audience reach.
- Social Media:Algorithmic distribution on Meta and TikTok concentrates discovery among dominant channels. Promoters must maintain in-house content studios and influencer relationship networks to sustain organic visibility.
- Online Advertising:Programmatic display and search marketing with precise demographic targeting. FCC disclosure requirements for sponsored content impose compliance costs on campaign architecture.
- Direct Mail:Physical invitation and membership renewal programs retaining effectiveness for aging collector demographics and institutional donor bases.
- Print Media:Arts journalism and specialized magazine placements sustaining credibility signaling for blue-chip gallery exhibitions and museum openings.
Social media absorbs the bulk of installed capacity; online advertising is gaining share fastest as attribution precision improves.
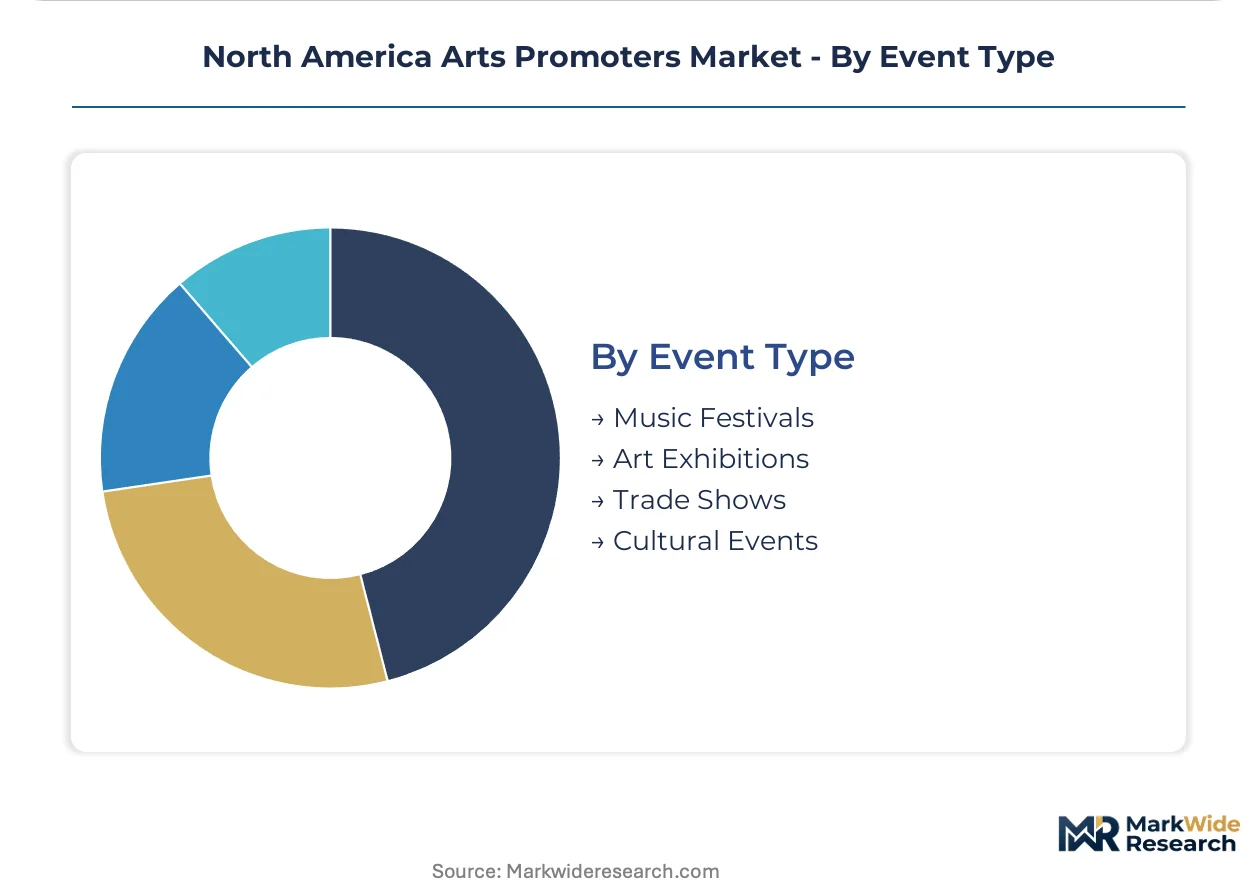
Event Type:
Production complexity and sponsorship attach rates vary dramatically across format categories.
- Music Festivals:Multi-day immersive experiences with camping, food programming, and brand activation villages. Texas and California host the dominant properties; talent procurement costs escalate as streaming revenue reduces artist touring frequency.
- Art Exhibitions:Gallery and museum presentations with extended run times and collector travel dependencies. New York fall season and Miami Art Week anchor the calendar; dispersed programming across Los Angeles and Mexico City fragments presence costs.
- Trade Shows:B2B convention formats with exhibitor booth revenue and corporate hospitality programming. Las Vegas and Chicago concentrate infrastructure supply.
- Cultural Events:Heritage celebrations, performing arts series, and community festivals with mixed public-private funding models.
Music festivals absorb the bulk of installed capacity; art exhibitions are expanding most quickly as digital programming extends geographic reach beyond physical walls.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in coastal metropolitan corridors where venue density and disposable income align, while consumption spreads across inland growth corridors where experiential spending rises faster than infrastructure deployment.
United States
California, Texas, and New York host the dominant share of purpose-built venues and promoter headquarters. The FCC enforces advertising disclosure requirements for digital promotion channels, tightening compliance for social media campaigns. Los Angeles and New York anchor blue-chip gallery programming, while Austin and Miami emerge as festival economy hubs.
Canada
Toronto and Montreal concentrate corporate event commissioning and public arts funding. The Competition Bureau enforces truth-in-advertising standards for ticket pricing and event claims, reducing friction in advance sales. Vancouver's integrated venue management sector is expanding through public-private partnerships for waterfront cultural infrastructure.
Mexico
Mexico City and Guadalajara generate rising demand for cross-border touring productions and corporate hospitality programming. The Federal Consumer Protection Agency monitors refund and cancellation policies, standardizing operational frameworks for international promoters. Monterrey's venue supply constraints relative to industrial wealth creation attract integrated promoter-developer partnerships.
North America Arts Promoters Market Competitive Landscape
Top-tier vendors anchor blue-chip gallery networks and festival properties with multi-decade brand equity, while mid-tier promoters compete on regional venue access and corporate hospitality relationships. Market structure tilts toward consolidation at the premium end and fragmentation in regional event management. Three archetypes dominate: integrated venue owners capturing ancillary revenue streams, digital-first operators extending geographic reach through streaming, and specialist agencies serving corporate experiential marketing budgets. Competitive moves concentrate on captive venue acquisition and hybrid physical-digital programming deployment.
Within the blue-chip gallery tier, Gagosian, Hauser & Wirth, and David Zwirner Gallery exemplify divergent strategic positioning. Gagosian occupies a position anchored on Los Angeles and New York collector relationships. Hauser & Wirth represents the integrated venue management archetype through exhibition spaces doubling as event infrastructure. David Zwirner Gallery sits within the digital programming vector, extending reach beyond physical walls through streaming formats.
| Leading Market Players |
|---|
| Gagosian |
| Hauser & Wirth |
| David Zwirner Gallery |
| Pace Gallery |
| Matthew Marks Gallery |
| Ascaso Gallery |
| Chroma Gallery |
| Fabien Castanier Gallery |
| RoGallery |
| Others |
Pricing and Supply Chain Analysis
Technical production labor concentration in Los Angeles and New York amplifies cost differentials between premium festival productions and regional theater programming, compressing mid-tier pricing spreads as talent procurement costs escalate.
Pricing Analysis
Margin tightening in single-night engagements traces to headliner guarantee inflation as streaming revenue reduces artist touring frequency. Three-tier pricing structure across premium VIP, general admission, and early-bird tiers stratifies by access level and purchase timing. Pricing pressure intensifies in corporate hospitality packages as direct brand-to-artist relationships displace intermediary markups. Corporate sponsors exhibit lowest price sensitivity; individual collectors show highest elasticity to ticket surcharges.
Supply Chain Analysis
Dual-sourcing requirements for staging equipment and lighting systems mandate multi-vendor qualification across California, Texas, and Nevada suppliers. Raw material dependencies span aluminum truss systems, LED display panels, and professional audio components. Supply chain risk centers on single-source vulnerability for specialized stage engineering talent. Distribution runs through captive venue networks and third-party rental depots serving touring circuits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive venue ownership represents the dominant competitive race, with promoters pursuing ancillary concession and merchandise revenue streams unavailable to rental-dependent operators.
For Market Incumbents: Lock in multi-year festival properties through exclusive talent procurement agreements and integrated venue management partnerships. Defensive positioning requires countering digital-first entrants by deploying hybrid physical-digital programming that extends geographic reach beyond physical walls. Threat vectors include algorithmic platform dependency extracting rising advertising tolls for audience reach. For New Entrants and Emerging Players: Streaming-enabled virtual previews offer a technology-first wedge into collector audiences beyond traditional gallery walls. White-space targets concentrate in Houston and Dallas-Fort Worth, where venue supply constraints relative to disposable income growth create first-mover advantages. Go-to-market positioning should emphasize outcome-based fee arrangements for corporate experiential marketing budgets. For Investors and Strategic Acquirers: Re-rating potential sits with integrated venue management archetypes given their capture of ancillary revenue streams unavailable to rental-dependent competitors. Long-term viability over the next decade hinges on scalable touring economics and captive infrastructure ownership. Signal to monitor: algorithmic content distribution concentration among dominant social platforms reshaping promotional spend allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Venue Acquisition | Integrated ownership unlocks concession and merchandise revenue streams in California and Texas corridors. |
| Hybrid Programming Deployment | Streaming studio visits extend collector reach beyond Los Angeles and New York physical walls. |
| Corporate Sponsorship Expansion | Experiential marketing budgets from technology and energy sectors stabilize cash flow across seasonal cycles. |
| Dynamic Pricing Engine Implementation | Real-time demand adjustment reduces unsold inventory for festival operators and theater chains. |
| Cross-Border Touring Infrastructure | Mexico City and Guadalajara routing standardizes operational frameworks under Federal Consumer Protection Agency guidelines. |
Research Methodology
Multi-period observation of ticket pricing velocity, sponsorship attach rates, and venue utilization patterns anchored the trend analysis, supplemented by interviews with festival operators, gallery directors, corporate event commissioners, and technical production specialists. Secondary validation drew from U.S. Federal Communications Commission disclosure filings, Canada Competition Bureau enforcement records, SEC filings of publicly traded venue operators, and Mexico Federal Consumer Protection Agency regulatory bulletins. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the North American arts economy.
Input-output matrix modeling connected talent procurement costs, venue fixed-cost bases, and sponsorship revenue pools to project segment-level value flows across the analysis window. Segmentation dimensions included service type, client sophistication tier, promotion channel, and event format complexity. CAGRs derived from historical growth trajectory analysis adjusted for regulatory intervention timelines and technology adoption curves. Industry-specific inputs incorporated algorithmic distribution platform economics and collector travel pattern fragmentation.
Several conditions sit outside the modeled scope, including force majeure event cancellations, abrupt platform algorithm changes, and geopolitical disruptions to cross-border touring circuits. Forecasts reflect assumptions around sustained corporate experiential marketing budget growth and stable regulatory enforcement patterns. Deviation in talent procurement cost inflation or social media platform liability rules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Volumetric Video Market
Media and Entertainment
Brazil Social Media Management Market
Media and Entertainment
Asia-Pacific (APAC) Media and Entertainment Market
Media and Entertainment
Austria OOH and DOOH Market
Media and Entertainment
South East Asia Advertising Market
Media and Entertainment
Europe Inflight Entertainment and Connectivity Market
Media and Entertainment
Hong Kong OOH and DOOH Market
Media and Entertainment
Global Music Video Production Market
Media and Entertainment
Podcasting Market
Media and Entertainment
Indonesia OOH and DOOH Market
Media and Entertainment
Europe K-Pop Events Market
Media and Entertainment
Chinese Gaming Industry Market
Media and Entertainment
Internet Radio Market
Media and Entertainment
Nigeria OOH and DOOH Market
Media and Entertainment
FM Transmitters Market
Media and Entertainment
Asia Pacific Programmatic Advertising Market