
 Virtual Events Market | 2026-2036
Virtual Events Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Events Market Intelligence
Cloud infrastructure is recalibrating the cost base of virtual event delivery as edge computing replaces centralized server architectures for low-latency streaming. Kaltura leverages its broadcast-grade video infrastructure to anchor enterprise-grade virtual conferences. Eventbrite competes through its self-service ticketing and registration ecosystem that extends into hybrid event workflows. Goldcast specializes in branded, high-production webinar experiences for B2B marketers seeking pipeline generation over generic meeting tools.
Virtual events are digitally orchestrated gatherings delivered through internet-connected platforms, typically incorporating real-time video encoding at 1080p or 4K resolution, adaptive bitrate streaming, and interactive layer architectures for Q&A, polling, and breakout networking. Their primary commercial purpose is to replicate or augment the information exchange, lead generation, and community-building functions of physical conferences without geographic constraints. Webinars and hybrid formats now capture disproportionate investment as enterprises seek scalable audience reach while preserving sponsorship monetization structures. Video streaming technology leads platform development spend, though VR platforms represent the fastest-growing capability segment as headset penetration improves and spatial computing standards mature.
FCC guidelines on broadband quality and net neutrality shape streaming reliability expectations for US-hosted events, while GDPR and the EU AI Act impose data governance and algorithmic transparency obligations on platforms serving European attendees. India's IT Act amendments and data localization directives from its central technology regulator add compliance layers for platforms storing participant information across borders. Stakeholders must monitor which regulatory jurisdiction's rules apply when a single virtual event spans multiple national audiences with divergent data protection regimes.
Market Dynamics
Edge computing architectures are displacing centralized cloud delivery for virtual events, compressing latency budgets below 50 milliseconds while redistributing infrastructure investment toward metropolitan fiber nodes and 5G edge zones.
Growth Catalysts
- GDPR Article 32:Mandatory encryption and pseudonymization requirements for European attendee data are accelerating platform investment in zero-trust security architectures.
- Corporate training departments:Technology and financial services clusters in California and New York are expanding dedicated virtual event budgets for internal upskilling and external certification programs.
- Spatial computing:Improving headset penetration and maturing WebXR standards are pulling B2B marketers toward immersive product demonstrations and virtual trade floors.
Market Restraints
- Data localization mandates:India's IT Act amendments and central technology regulator directives require domestic storage of participant biometric and behavioral data, fragmenting platform architecture costs.
- Input cost volatility:GPU and specialized video encoding hardware shortages are pressuring margin structures for broadcast-grade streaming infrastructure.
- Technical limitation:Persistent network asymmetry in emerging markets caps adaptive bitrate streaming quality below enterprise SLA thresholds for real-time interaction.
Strategic Opportunities
- Brazil and Mexico:Underpenetrated Latin American enterprise segments present first-mover advantages for localized payment integration and Portuguese-Spanish language support.
- EU AI Act:Algorithmic transparency obligations for automated content moderation and recommendation engines create compliance service revenue streams for audit-ready platform modules.
- Convergence of AI and edge encoding:On-device neural processing for real-time transcription and translation is opening low-bandwidth market access without centralized server dependency.
Industry Challenges
- Live production engineering talent:Scarcity of specialists combining broadcast television workflow expertise with cloud-native DevOps skills is extending platform deployment timelines.
- Legacy AV integration:Hybrid event workflows require seamless bridging between IP-based virtual platforms and installed base of SDI/Hardware video switchers in convention centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Events Market |
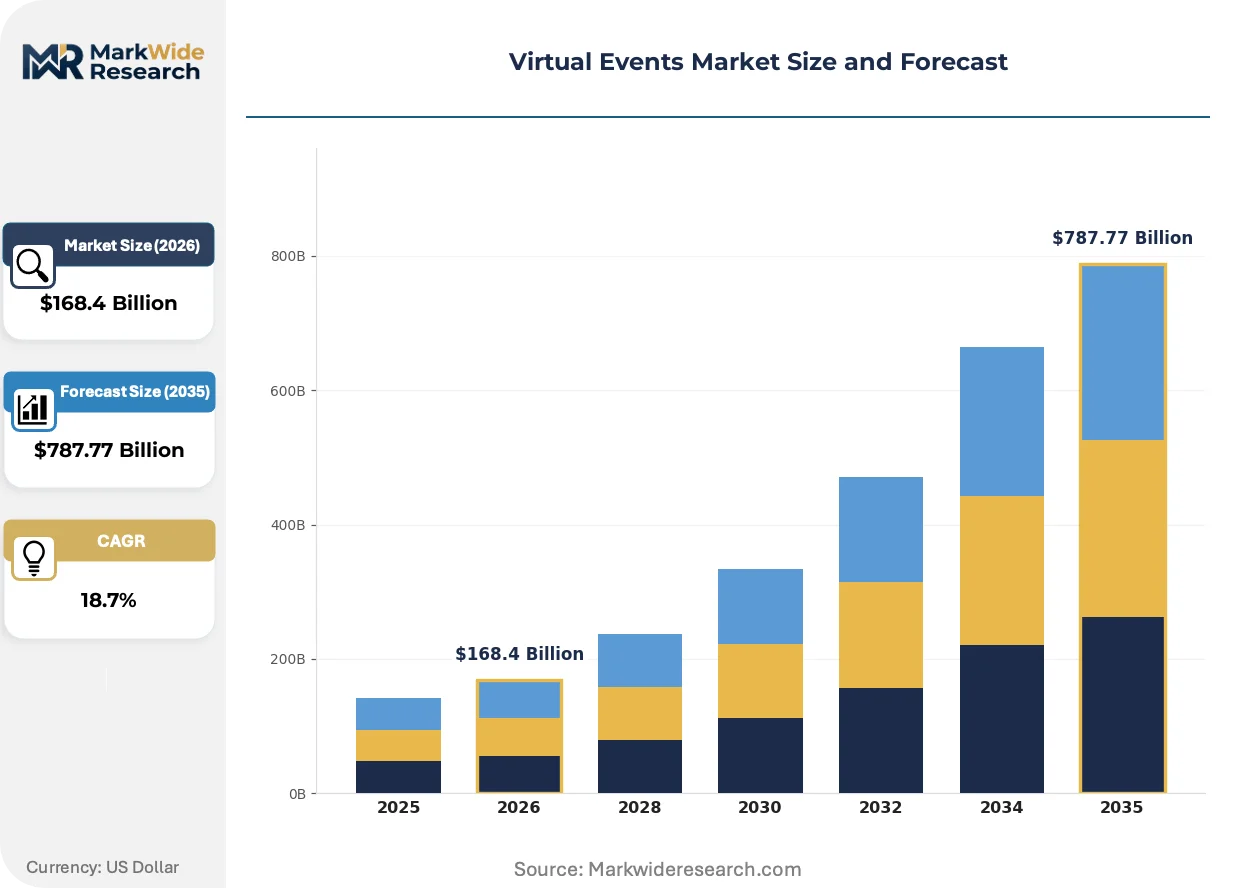
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $787.77 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Webinars, Conferences, Trade Shows, Workshops Technology: Video Streaming, VR Platforms, Event Management Software, Networking Tools End User: Corporates, Educational Institutions, Non-profits, Freelancers Engagement Model: Live Events, Recorded Sessions, Interactive Panels, Hybrid Formats |
| Companies Covered | Accelevents, Kaltura, CrowdComms, Jifflenow, Eventbrite, Goldcast, Topia, EventStub, Goosechase, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Events Market Strategic Shifts & Innovations
Virtual event platforms are converging around three developmental axes: infrastructure automation, regulatory compliance tooling, and audience engagement personalization. Each axis carries distinct investment priorities and competitive differentiation potential.
AI-powered content indexing is automating post-event asset repurposing, extracting searchable clips and automated highlight reels from multi-hour broadcasts. Marketing operations teams at B2B software vendors are adopting these tools at compressed implementation cycles, collapsing what required manual editor hours into minutes. This compression is automating the economics of content marketing, allowing single events to feed month-long nurture campaigns without proportional labor scaling.
GDPR enforcement actions by CNIL and other European data protection authorities are hardening requirements for granular consent logging and automated data retention enforcement. Platform vendors must now embed privacy-by-design into registration workflows, breakout room allocation logic, and analytics dashboards. European financial services and healthcare verticals are responding by demanding SOC 2 Type II and ISO 27701 certifications as table stakes for procurement.
Attendee engagement models are pivoting from passive consumption toward participatory credentialing, where virtual event participation feeds directly into professional certification and continuing education credits. Medical and legal professional associations are displacing traditional in-person seminar requirements with verified virtual attendance tracking. This behavioral shift is most visible in Germany and the United Kingdom, where professional bodies have accelerated accreditation of virtual formats post-pandemic.
Virtual Events Market Segmentation
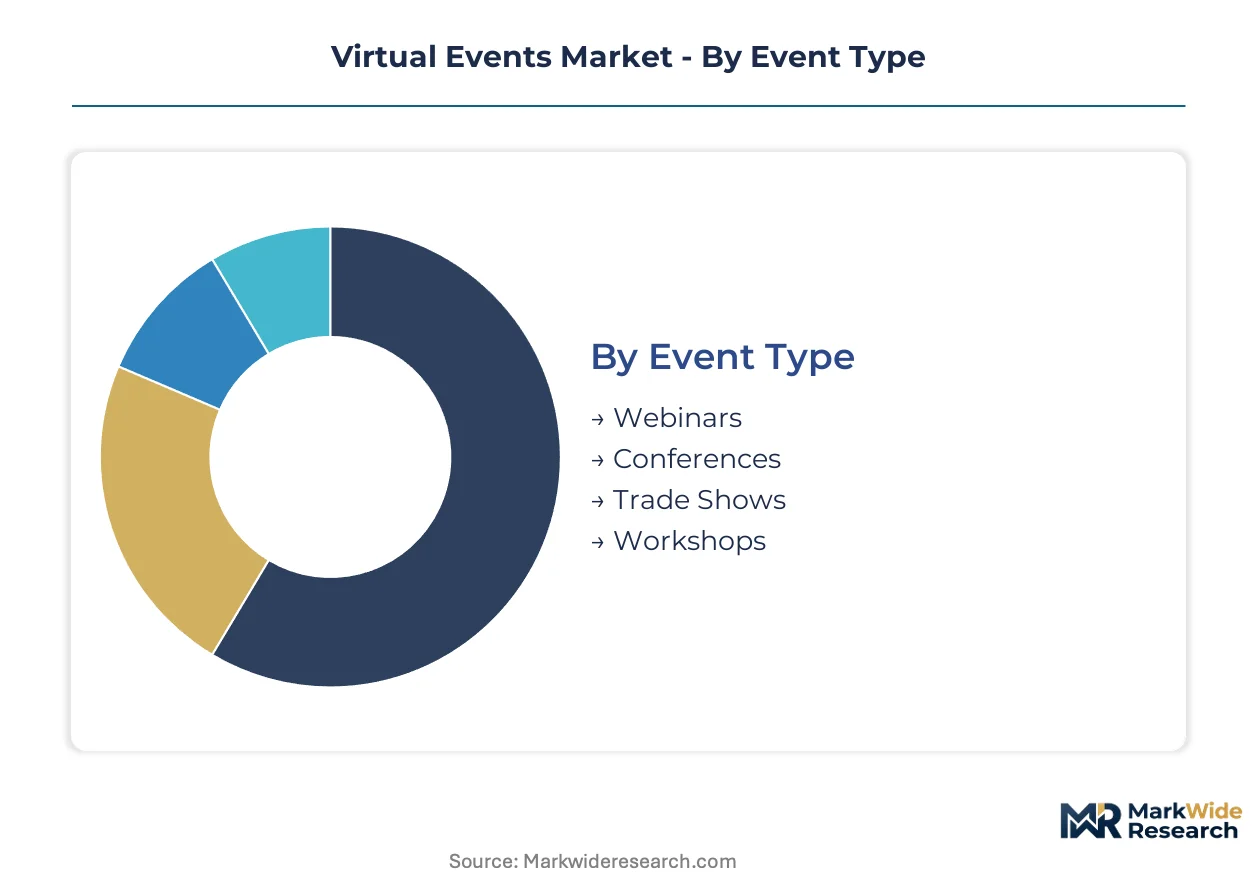
Virtual event platforms must architect distinctly for latency-tolerant webinars versus immersive VR trade floors. Segmentation reveals where infrastructure investment concentrates and which compliance regimes govern each deployment pattern.
Event Type:
Format specifications dictate encoding pipelines, with synchronous multi-track delivery demanding fundamentally different compute architectures than on-demand archives.
- Webinars:Single-speaker or panel formats at 1080p with adaptive bitrate streaming dominate B2B lead generation workflows. California technology clusters and New York financial services deploy these for scalable executive thought leadership without venue logistics.
- Conferences:Multi-session architectures with concurrent breakout tracks require broadcast-grade redundancy and CDN edge distribution. Demand concentrates among professional associations in Germany and the United Kingdom seeking continuing education credit verification.
- Trade Shows:Exhibitor booth virtualization with spatial navigation and lead retrieval APIs serves manufacturing and healthcare verticals.
- Workshops:Hands-on formats with screen sharing and collaborative whiteboarding anchor corporate training departments.
Mature deployment sits with webinars. Newer deployment is concentrated in trade shows.
Technology:
Platform development spend tracks capability differentiation, with video infrastructure commanding baseline investment and spatial computing capturing experimental budgets.
- Video Streaming:Real-time encoding at 4K resolution with sub-50ms edge latency anchors enterprise SLA requirements. Technology clusters in California and financial services in New York drive specification demands for broadcast-grade reliability.
- VR Platforms:WebXR-compliant spatial environments with headset and desktop fallback modes enable immersive product demonstrations. B2B marketers in Germany and the United Kingdom are pulling capability development fastest as professional association accreditation expands.
- Event Management Software:Registration, ticketing, and analytics orchestration with GDPR Article 32 encryption compliance.
- Networking Tools:AI-moderated breakout matching and persistent social graphs for attendee relationship building.
Video streaming captures the steepest expansion trajectory for infrastructure spend. VR platforms are gaining share fastest in capability roadmaps.
End User:
Budget authority and procurement complexity segment platform sales cycles, with enterprise security reviews contrasting self-service adoption patterns.
- Corporates:Technology and financial services clusters in California and New York mandate SOC 2 Type II and ISO 27701 certifications for procurement. GDPR and EU AI Act compliance tooling separates vendor shortlists in European headquarters.
- Educational Institutions:Learning management system integration with attendance verification for accreditation drives specification requirements. Professional medical and legal associations in Germany and the United Kingdom are displacing in-person seminar mandates.
- Non-profits:Donor-funded event budgets prioritize low-cost self-service onboarding with volunteer-operated production.
- Freelancers:Individual practitioners monetize expertise through ticketed virtual sessions with minimal platform overhead.
Corporates anchor mature procurement with extended security review cycles. Educational institutions represent the fastest-growing budget expansion as accreditation accelerates.
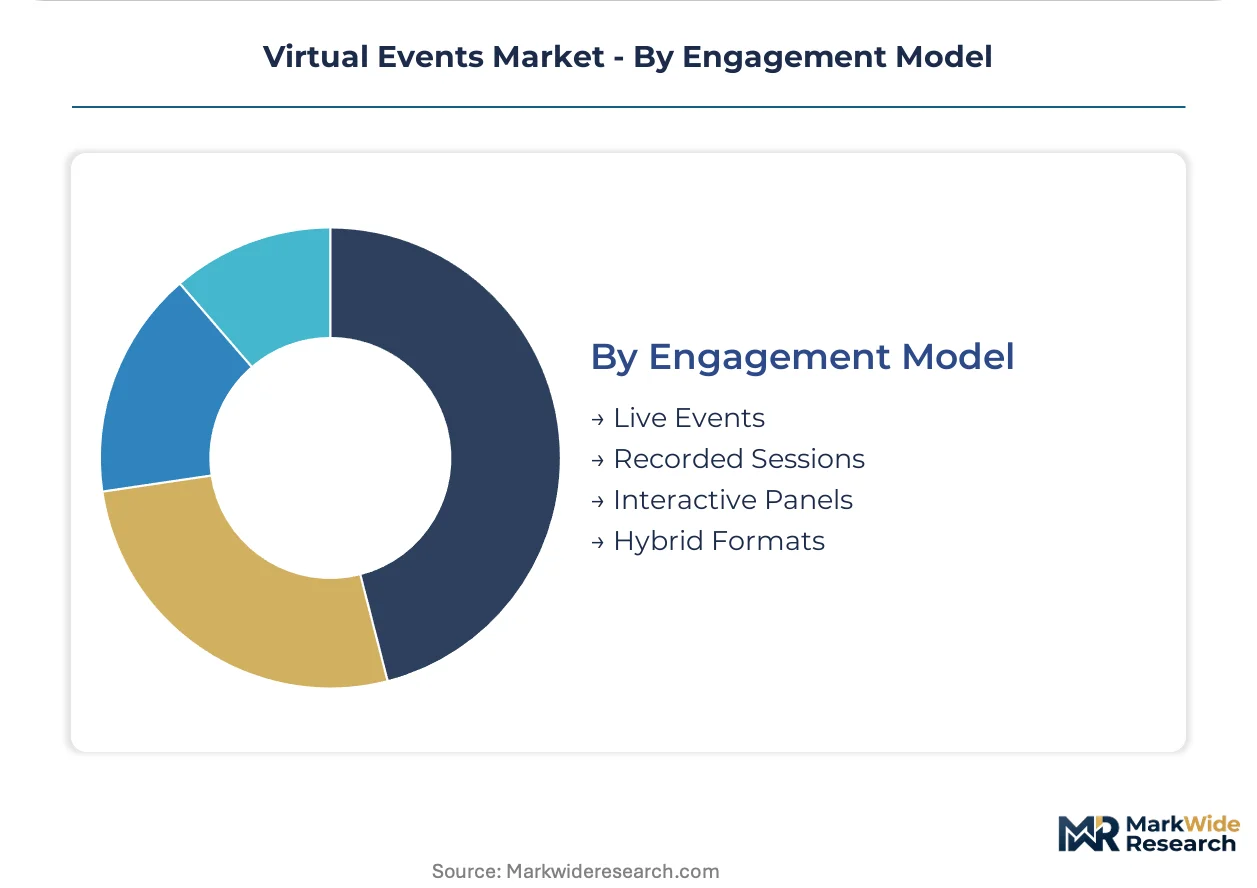
Engagement Model:
Temporal architecture determines infrastructure cost structures and sponsorship monetization potential, with synchronous formats commanding premium delivery investments.
- Live Events:Real-time encoding with redundant failover and interactive layer management for Q&A and polling. Demand concentrates in corporate training departments and professional associations requiring verified attendance for certification.
- Hybrid Formats:Seamless bridging between IP-based virtual platforms and SDI/Hardware video switchers in physical venues. Convention centers in California and New York require legacy AV integration expertise for enterprise client retention.
- Recorded Sessions:On-demand archives with AI-powered content indexing for post-event asset repurposing.
- Interactive Panels:Moderated multi-speaker formats with audience submission curation and live polling.
Live events dominate current infrastructure deployment. Hybrid formats are climbing the fastest as venue operators rebuild integrated capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate training departments in the United States concentrate the largest virtual event procurement budgets, while GDPR enforcement and India's data localization mandates reshape platform architecture requirements across jurisdictions.
United States
Technology clusters in California and financial services in New York drive specification demands for broadcast-grade streaming with sub-50ms edge latency. FCC net neutrality guidelines and broadband quality standards shape streaming reliability expectations for US-hosted events. Enterprise clients in San Francisco and Manhattan mandate SOC 2 Type II certifications as procurement table stakes.
Germany
Professional medical and legal associations accelerate virtual format accreditation for continuing education credits. GDPR Article 32 encryption requirements and CNIL enforcement actions harden demands for granular consent logging and automated data retention. Frankfurt and Munich anchor demand for verified attendance tracking systems that displace traditional in-person seminar mandates.
India
Corporate training departments expand dedicated virtual event budgets for internal upskilling and external certification programs. IT Act amendments and central technology regulator directives require domestic storage of participant biometric and behavioral data, fragmenting platform architecture costs. Bengaluru and Mumbai clusters drive demand for localized payment integration and regional language support.
United Kingdom
B2B marketers pull capability development fastest toward immersive product demonstrations as professional association accreditation expands. GDPR and EU AI Act algorithmic transparency obligations create compliance service revenue streams for audit-ready platform modules. London financial services and professional services clusters mandate ISO 27701 certifications alongside SOC 2 Type II.
Brazil
Underpenetrated Latin American enterprise segments present first-mover advantages for platform vendors with Portuguese language support and localized payment rails. General data protection law enforcement patterns follow European precedents, though with shorter implementation timelines. São Paulo anchors regional demand for scalable audience reach without venue logistics overhead.
Virtual Events Market Key Industry Players
Portfolio diversification dominates the current landscape as vendors extend from core video infrastructure into adjacent compliance tooling and AI-powered engagement layers. The vendor base segments across three tiers: broadcast-grade infrastructure specialists, self-service ticketing platforms, and immersive experience architects. Strategic archetypes include edge-computing infrastructure providers, GDPR compliance module developers, and spatial computing early movers. M&A activity concentrates on acquiring real-time encoding capabilities and automated content moderation algorithms.
Within the broadcast-grade infrastructure tier, Kaltura exemplifies vendors leveraging video-native architectures to anchor enterprise-grade virtual conferences. Eventbrite occupies a position representing self-service ticketing ecosystems that extend into hybrid event workflows. Goldcast sits within the branded experience specialist archetype, targeting B2B marketers seeking pipeline generation capabilities beyond generic meeting tools. These three anchors illustrate how competitive positioning fragments across infrastructure depth, workflow automation, and production value differentiation.
| Leading Market Players |
|---|
| Accelevents |
| Kaltura |
| CrowdComms |
| Jifflenow |
| Eventbrite |
| Goldcast |
| Topia |
| EventStub |
| Goosechase |
| Others |
Cost & Logistics Intelligence
Corporate training departments in California technology clusters and New York financial services concentrate procurement authority, driving SaaS-tiered subscription models that scale per-seat licensing against broadcast-grade infrastructure commitments. This buyer concentration compresses margin structures for mid-tier vendors while anchoring premium pricing for SOC 2 Type II certified platforms serving enterprise security reviews.
Pricing Analysis
Volume-driven self-service tiers capture the mass market while broadcast-grade enterprise deployments defend margins through certification premiums. Pricing stratifies across premium compliance-certified, standard professional-grade, and economy self-service tiers, with SOC 2 Type II and ISO 27701 certifications commanding substantial premiums in European financial services procurement. Cost compression in the mid-market intensifies as GPU encoding hardware shortages pressure infrastructure economics. Freelancers and non-profits exhibit highest price sensitivity, while corporate training departments in regulated verticals demonstrate lowest sensitivity to compliance-tier premiums.
Supply Chain Analysis
India's data localization mandates under IT Act amendments are reshaping sourcing patterns, forcing domestic edge node deployment for biometric and behavioral data storage. Cloud infrastructure draws from hyperscaler networks concentrated in the United States, Germany, and India, with specialized video encoding hardware resting on Taiwan and South Korea semiconductor supply chains. Single-source vulnerability sits with GPU and ASIC encoder shortages disrupting broadcast-grade streaming capacity. Distribution runs through direct enterprise sales for compliance-heavy deployments and self-service digital channels for volume tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
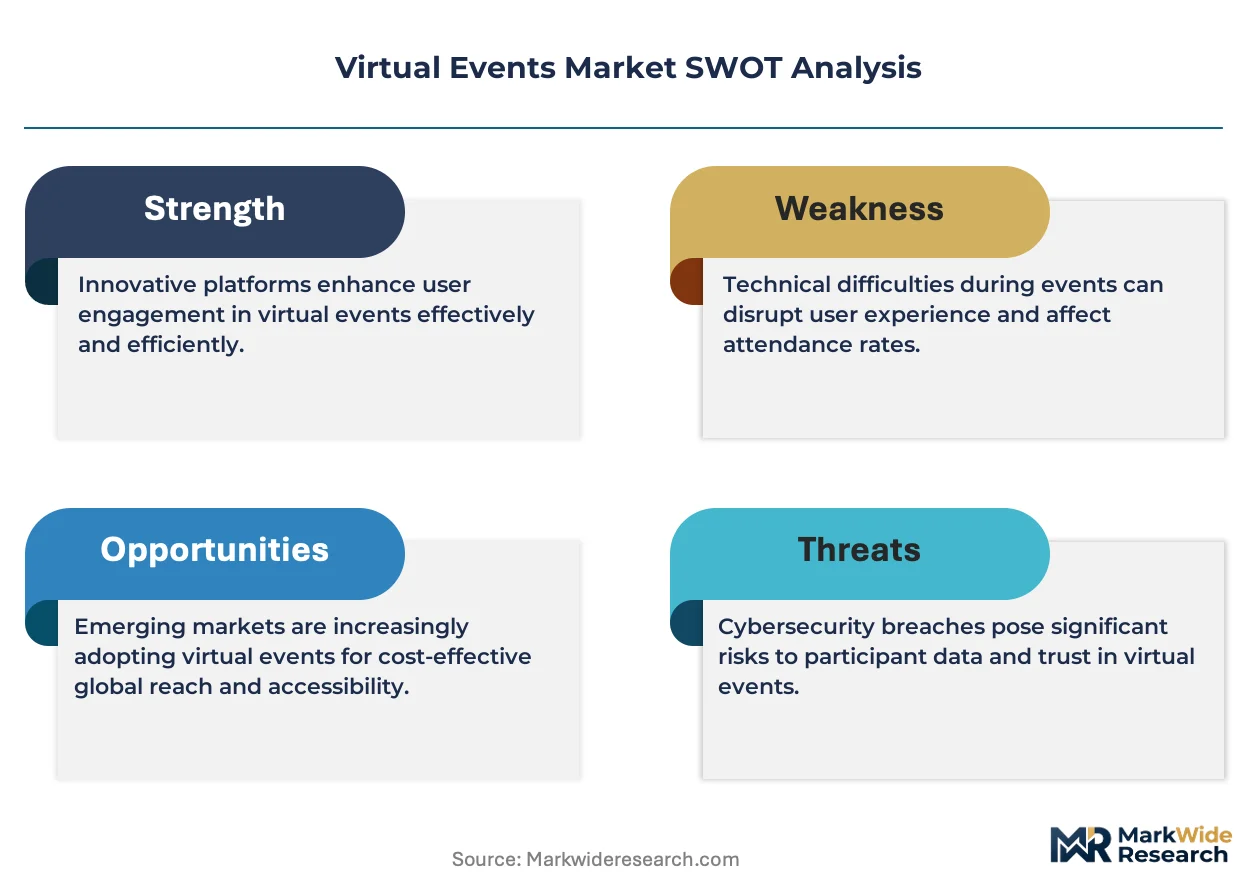
This market is becoming a vertical-integration race as platform vendors pursue captive control over edge encoding infrastructure to escape hyperscaler dependency and defend margin structures against input cost volatility.
For Market Incumbents: Anticipate margin compression from GPU hardware shortages and hyperscaler pricing power by securing long-term encoding ASIC supply agreements or acquiring specialized compression technology firms. Prioritize backward integration into edge computing infrastructure across metropolitan fiber nodes in California, New York, and Frankfurt to reduce latency SLA dependency on third-party CDN networks. For New Entrants and Emerging Players: Enter via Brazil and Mexico's underpenetrated enterprise segments, where Portuguese-Spanish language support and localized payment integration remain unsatisfied by incumbent global platforms. Target professional medical and legal associations in Germany and the United Kingdom seeking verified attendance tracking for continuing education accreditation, deploying compliance-first positioning against generic webinar tools. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized encoding technology firms in Taiwan and South Korea facing near-term demand softness, with long-term viability hinging on spatial computing headset penetration trajectories. Monitor WebXR standard adoption curves and professional association accreditation velocity as the critical inflection signal for immersive platform capability valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Infrastructure Buildout | Sub-50ms latency SLAs for California and New York enterprise clients require metropolitan fiber node deployment. |
| GDPR Compliance Module Development | CNIL enforcement actions in France and Germany mandate granular consent logging as procurement table stakes. |
| Spatial Computing Capability Acquisition | WebXR-compliant immersive trade floors capture B2B marketing budgets shifting from passive webinars. |
| Localized Payment Integration | Brazil and Mexico enterprise adoption hinges on Portuguese-Spanish language support and domestic payment rails. |
| AI-Powered Content Indexing | Automated highlight reel extraction collapses manual editor hours for B2B software vendor marketing operations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across platform engineering directors, corporate training procurement managers, broadcast production specialists, and GDPR compliance officers. SEC filings from publicly traded platform vendors, FCC broadband quality reports, EDPB enforcement action databases, and Indian IT Act amendment texts supplied validation layers. Bottom-up deployment sizing across technology clusters triangulated against top-down corporate training budget surveys.
Segmentation granularity modeled event type, engagement model, technology stack, and end-user vertical across the projection horizon, with regional regulatory clusters treated as distinct demand environments. CAGRs derived from trend extrapolation of corporate training budget allocations, spatial computing headset penetration curves, and professional association accreditation velocity. Edge infrastructure capex cycles and GPU encoder supply constraints fed infrastructure cost assumptions throughout the modeling period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated GDPR enforcement severity or prolonged semiconductor supply disruption. Forecasts reflect assumptions documented in regulatory scenario modeling and input cost sensitivity analysis. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
North America K-Pop Events Market
Events and Festivals
Global Exhibition Market
Events and Festivals
India Event and Exhibition Market
Events and Festivals
K-Pop Events Market
Events and Festivals
Global Live Event Ticketing Market
Events and Festivals
Europe Event Pro-Av Services Market
Events and Festivals
Global Roller Coaster Market
Events and Festivals
US Amusement and Theme Park Market
Events and Festivals
Sports Events Tickets Market
Events and Festivals
Event Services Market
Events and Festivals
Events and Exhibition Market
Events and Festivals
Event Photography Service Market
Events and Festivals
Corporate Luxury Events Market
Events and Festivals
Drone Art Performance Market
Events and Festivals
Global Special Effects Fog and Smoke Machines Market
Events and Festivals
Asia-Pacific K-Pop Events Market