
 Hair Texturizer Products Market | 2026-2036
Hair Texturizer Products Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Texturizer Products Market Foresight
Buyer fragmentation across independent stylists and specialty barbershops is expanding as digital education platforms democratize professional technique. Procter & Gamble Company leverages its mass-market distribution infrastructure to sustain shelf presence across multi-channel retail. L'Oréal S.A. anchors premium texturizer development through specialized curl-care laboratories in Paris. Unilever PLC competes in emerging markets with localized formulations adapted to humidity and hard-water conditions.
Hair texturizer products comprise styling formulations incorporating polymers, waxes, and humectants that modify fiber alignment and increase inter-strand friction to create controlled volume or definition. These products typically deliver hold factors ranging from light to maximum through resin systems suspended in aqueous or emulsion bases, serving both consumer self-styling and professional finishing applications. The texture type dimension shows curly and coily segments commanding premium pricing due to ingredient complexity and smaller batch production requirements. Creams dominate moisturizing applications where emollient load drives margin pools, while sprays lead in styling velocity for time-constrained professionals.
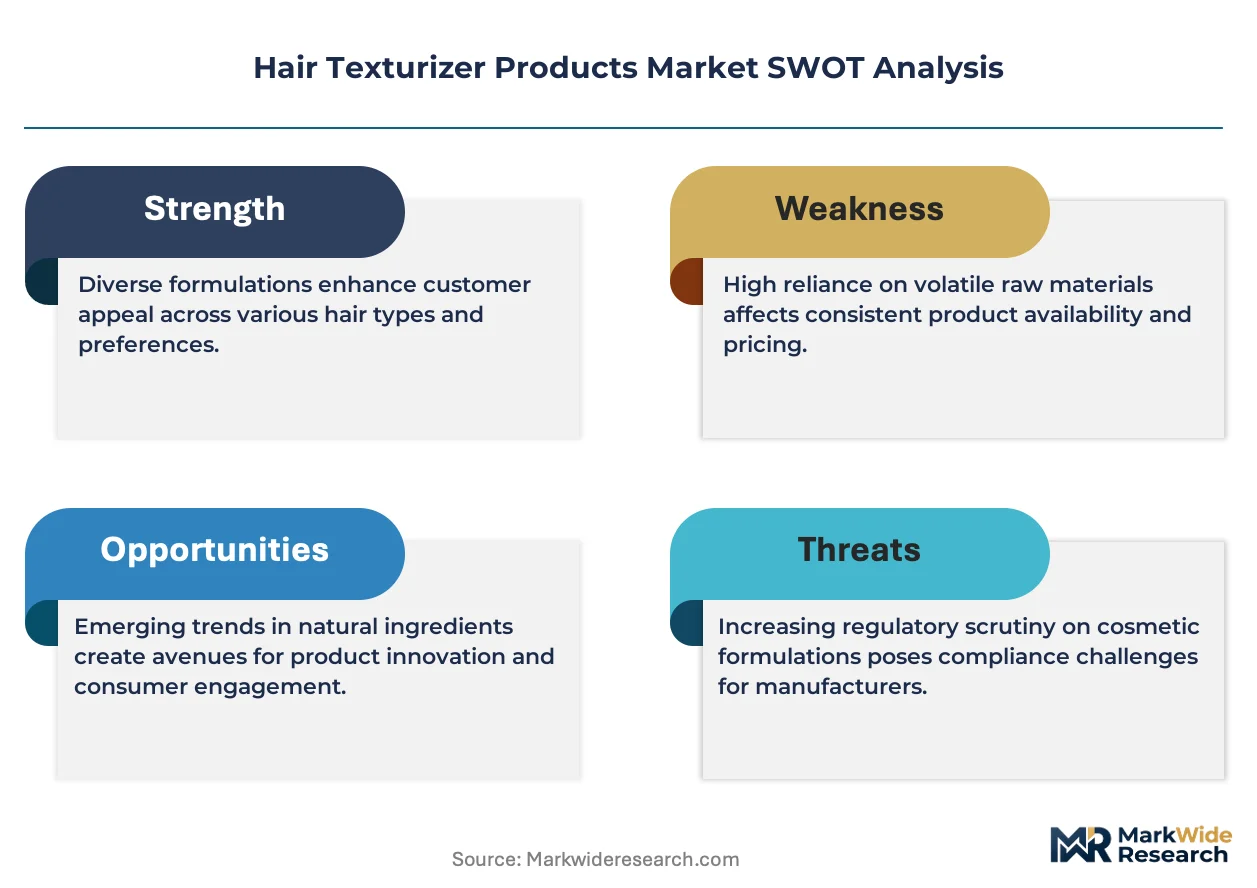
The U.S. Food and Drug Administration oversees cosmetic ingredient safety through voluntary reporting systems, while the European Chemicals Agency enforces REACH documentation for polymer components entering EU formulations. California's Proposition 65 creates additional compliance layers for brands distributing across American retail channels. Stakeholders must monitor evolving state-level ingredient restrictions and professional licensing requirements that govern salon-grade product dispensing authority.
Market Dynamics
Professional salon channels are consolidating purchasing power while REACH and RoHS compliance in Europe tightens ingredient disclosure requirements, forcing reformulation cycles that reshape competitive positioning across texture-specific product lines.
Growth Catalysts
- Curly and coily hair specialization:Consumer demand for fiber-specific formulations drives premium batch production and specialized polymer research in Paris curl-care laboratories.
- Digital education platforms:Independent stylists and specialty barbershops access professional technique training, fragmenting buyer bases and expanding addressable professional accounts.
- REACH polymer documentation:European Chemicals Agency enforcement creates compliance barriers that favor established formulators with dedicated regulatory affairs infrastructure.
Market Restraints
- Petrochemical resin volatility:Hold-system polymers depend on ethylene derivatives subject to energy-price fluctuations that compress margin pools on mid-tier emulsion products.
- California Proposition 65 layers:State-level ingredient warning requirements add compliance costs for brands distributing across American retail channels beyond federal FDA voluntary reporting.
- Humectant substitution pressure:Natural oil and butter alternatives displace synthetic glycerin complexes in moisturizing creams, requiring reformulation investment without price recovery mechanisms.
Strategic Opportunities
- Hard-water adapted formulations:Emerging market consumers in mineral-rich water regions present white space for chelating polymer systems that Unilever PLC has begun localizing.
- Professional dispensing authority:Salon-grade licensing requirements create channel exclusivity for concentrated resin systems unavailable in mass retail.
- Spray velocity optimization:Time-constrained stylists in high-turnover metropolitan markets drive demand for fast-dry alcohol suspension technologies.
Industry Challenges
- Trichology certification timelines:Professional product dispensing authority requires state-level cosmetology board approvals that delay market entry by 18-24 months.
- Legacy emulsion equipment retrofitting:Batch manufacturers face capex burdens upgrading aqueous suspension lines to handle high-viscosity cream loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Texturizer Products Market |
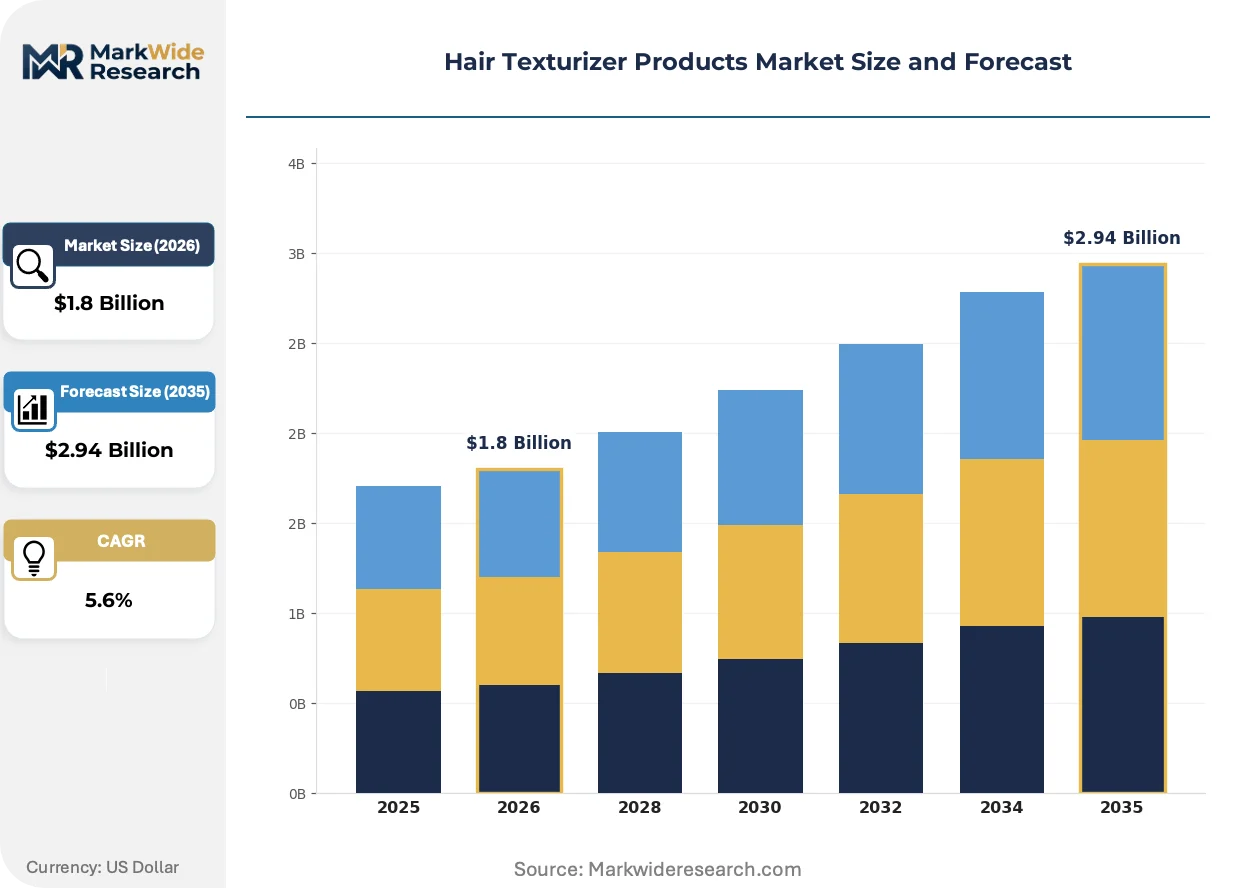
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Sprays, Mousse Application: Styling, Conditioning, Moisturizing, Curl Defining End User: Retail Consumers, Salons, Professionals, Barbershops Texture Type: Straight, Wavy, Curly, Coily |
| Companies Covered | Procter & Gamble Company, Unilever PLC, L'Oréal S.A., Henkel AG & Co. KGaA, Beiersdorf AG, Coty Inc., Oribe Hair Care LLC, Hain Celestial Group, Revlon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Texturizer Products Market Shifts & Advancements
Formulation science is converging fiber-alignment polymers with moisture-management actives, compressing the traditional separation between styling hold and conditioning functions into single-application products.
Biopolymer resin systems derived from fermentation processes are unifying hold performance with biodegradability credentials. Premium curl-care laboratories in Paris adopt these materials fastest, integrating them into texture-specific lines for coily hair segments. This convergence is unifying previously separate R&D streams—synthetic polymer chemistry and plant biotechnology—into unified formulation teams that compress development cycles.
REACH documentation requirements for polymer components entering EU formulations now mandate full supply-chain substance disclosure. European Chemicals Agency enforcement has industrialized compliance departments within formulators, shifting cost structures toward regulatory affairs. Professional-grade resin suppliers face the steepest documentation burdens, accelerating consolidation toward integrated polymer manufacturers with captive toxicology testing.
Independent stylists now source directly from manufacturer education platforms, bypassing traditional distributor markups. Specialty barbershops in Atlanta and Houston lead this disintermediation, purchasing professional texturizers through verified digital credential systems. This channel compression is most visible in the United States, where licensing verification infrastructure enables manufacturer-direct relationships that reshape wholesale economics.
Hair Texturizer Products Market Segmentation
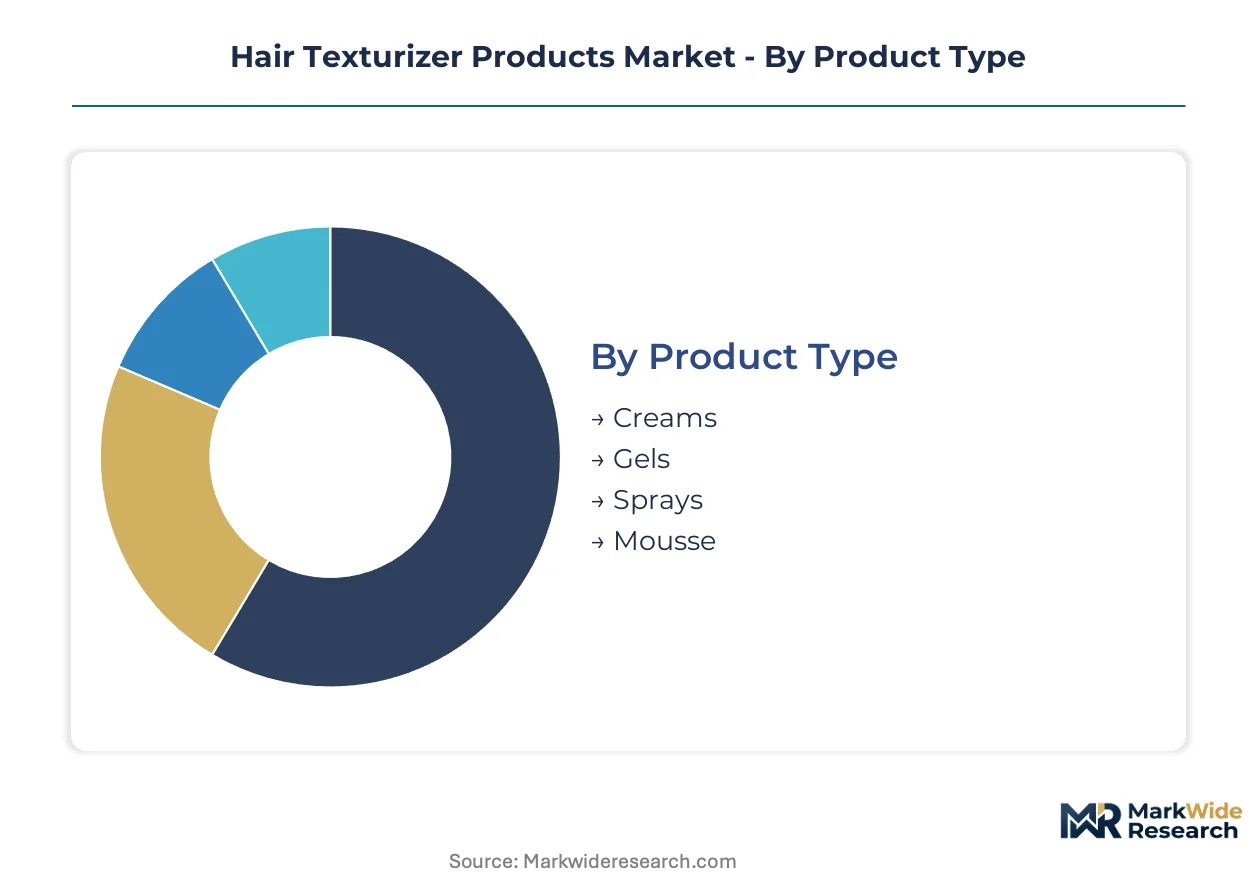
Hair texturizer markets fragment across fiber-specific needs and professional versus consumer application contexts. Formulation chemistry, dispensing authority, and texture-specific polymer requirements create distinct margin pools that reward specialized positioning.
Product Type:
Volume concentrates in spray formats for professional velocity, while creams capture premium positioning through emollient complexity and batch production constraints.
- Creams:High-viscosity emulsion bases loaded with humectants and natural butters deliver intensive moisture management for coily hair segments. Demand clusters among specialty barbershops in Atlanta and Houston where fiber-specific finishing commands price premiums. Manufacturing requires legacy equipment retrofitting for aqueous suspension lines handling dense loads.
- Sprays:Alcohol or water-based resin suspensions enable rapid application turnover in high-volume metropolitan salons. Fast-dry technologies from Paris curl-care laboratories are penetrating professional channels fastest. Time-constrained stylists drive formulation investment in velocity-optimized delivery systems.
- Gels:Cross-linked polymer matrices provide maximum hold factors through resin concentration in clear aqueous bases.
- Mousse:Aerosol or pump-dispensed foam carriers deliver lightweight volume amplification with lower resin loading.
Mature deployment sits with creams. Newer deployment is concentrated in sprays.
Application:
Functional convergence is compressing traditional category boundaries as fiber-alignment polymers merge with conditioning actives in single-application products.
- Styling:Hold-system formulations employing petrochemical-derived resins modify inter-strand friction for controlled volume and shape retention. Professional dispensing authority in licensed salons creates channel exclusivity for concentrated resin systems unavailable through mass retail.
- Curl Defining:Texture-specific polymer research targets fiber alignment in coily and curly segments through specialized curl-care laboratories. Premium batch production requirements and smaller manufacturing runs support margin expansion in this technically demanding category.
- Conditioning:Emollient-rich bases prioritize fiber health over structural hold, competing with dedicated hair care products.
- Moisturizing:Humectant and natural oil formulations address porosity management in dry or damaged hair types.
Styling applications retain the largest revenue base. Curl defining is climbing the fastest as specialized texture care expands.
End User:
Channel compression through digital education platforms is fragmenting buyer bases and enabling manufacturer-direct relationships that bypass traditional distributor economics.
- Salons:Licensed professional channels consolidate purchasing power while requiring state-level cosmetology board approvals that delay new product entry by 18-24 months. REACH documentation and professional-grade resin supplier consolidation favor established formulators with dedicated regulatory affairs infrastructure.
- Barbershops:Specialty establishments in the United States lead disintermediation through verified digital credential systems enabling direct manufacturer sourcing. Independent stylists accessing professional technique training expand addressable accounts beyond traditional distributor networks.
- Retail Consumers:Mass-market distribution infrastructure sustains shelf presence across multi-channel retail with lower per-unit margins.
- Professionals:Individual licensed practitioners represent a fragmented segment increasingly targeted through education platforms.
Salon channels dominate value capture. Barbershops are gaining share fastest through digital channel compression.
Texture Type:
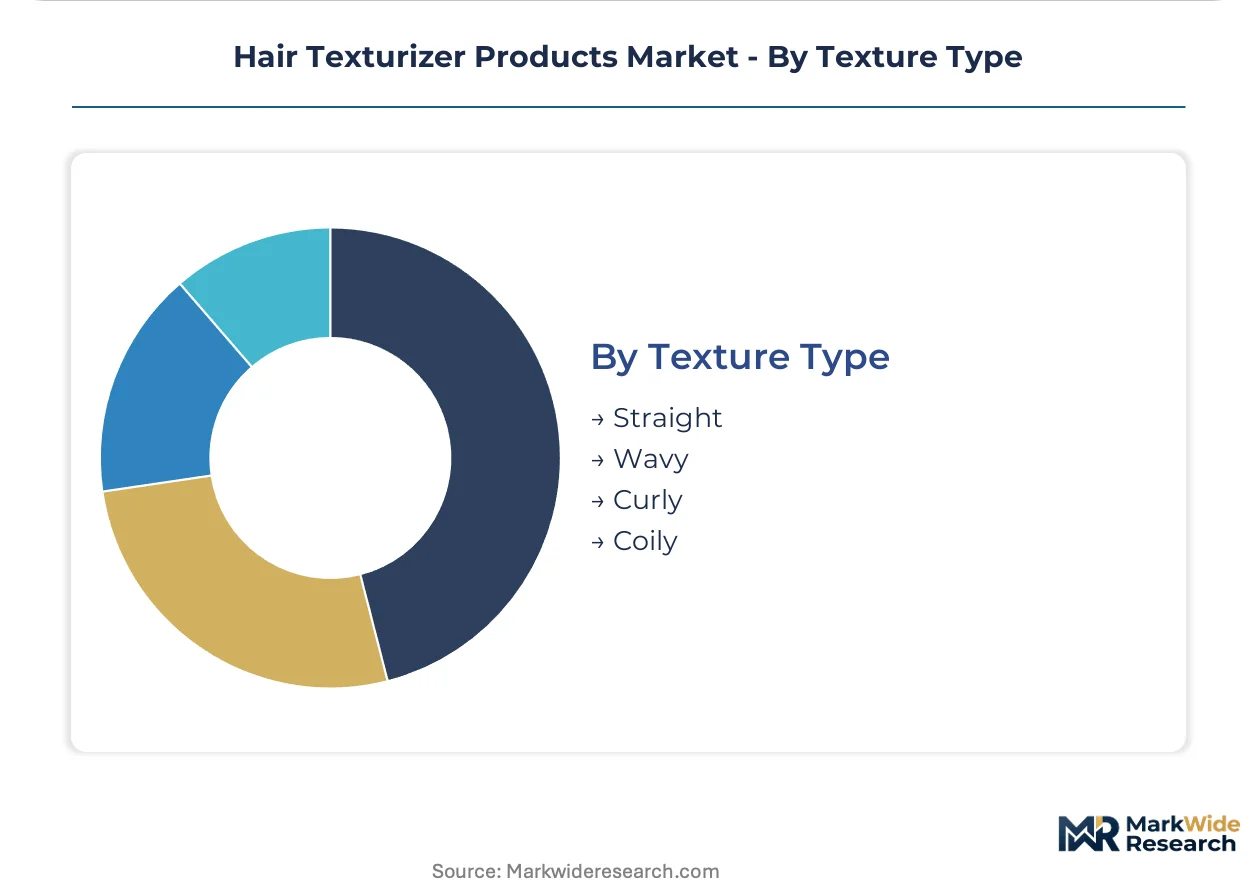
Ingredient complexity and specialized polymer requirements create pricing stratification that rewards fiber-specific formulation investment.
- Coily:Tight curl patterns demand maximum emollient load and specialized moisture-management actives that justify premium positioning. Smaller batch production requirements and dedicated curl-care laboratory development in Paris anchor technical leadership in this segment.
- Curly:Moderate curl structures require balanced hold and conditioning that drives biopolymer resin adoption from fermentation processes. European Chemicals Agency REACH enforcement creates compliance barriers favoring integrated manufacturers with captive toxicology testing.
- Wavy:Loose texture patterns accept lighter resin systems with lower ingredient complexity and broader manufacturing compatibility.
- Straight:Minimal structural modification needs limit premium positioning opportunity in texturizer-specific formulations.
Straight hair applications represent the mature volume base. Coily textures are expanding most quickly as specialized care penetrates previously underserved consumer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hair texturizer products concentrates in the United States among curly and coily hair consumers seeking specialized texture formulations. European regulatory frameworks reshape competitive positioning through compliance-driven reformulation cycles. Emerging market localization efforts target humidity and hard-water adaptation requirements.
United States
Curly and coily hair specialization drives premium batch production and fiber-specific polymer research. The FDA oversees cosmetic ingredient safety through voluntary reporting systems while California's Proposition 65 adds state-level warning requirements. Specialty barbershops in Atlanta and Houston lead channel disintermediation through verified digital credential systems enabling direct manufacturer sourcing.
Germany
REACH documentation requirements for polymer components entering EU formulations mandate full supply-chain substance disclosure. The European Chemicals Agency enforces compliance barriers that favor established formulators with dedicated regulatory affairs infrastructure. Industrial clusters in North Rhine-Westphalia host integrated polymer manufacturers with captive toxicology testing capabilities serving professional-grade resin markets.
France
Premium curl-care laboratories in Paris anchor technical leadership in biopolymer resin systems derived from fermentation processes. ANSM and CNIL oversight intersect with cosmetic safety and data protection requirements for digital education platforms. The Île-de-France region concentrates specialized R&D teams unifying synthetic polymer chemistry and plant biotechnology into unified formulation development.
Brazil
Humidity-adapted formulations address emerging market consumers in mineral-rich water regions presenting white space for chelating polymer systems. ANVISA regulates cosmetic ingredient safety with documentation requirements that parallel REACH structures. São Paulo anchors localized production for Latin American distribution networks targeting professional salon channel consolidation.
India
Hard-water conditions in major metropolitan centers drive demand for chelating polymer systems adapted to mineral-rich environments. BIS standards govern product quality certification while state-level cosmetology board approvals govern professional dispensing authority. Maharashtra and Karnataka host manufacturing facilities targeting salon-grade licensing requirements that create channel exclusivity for concentrated resin systems.
Hair Texturizer Products Market Competitive Landscape
United States producers anchor one tier; European specialists hold premium formulation leadership through regulatory compliance infrastructure. The vendor base fragments across mass-market distribution infrastructure and professional channel exclusivity models. Three strategic archetypes dominate: integrated consumer goods conglomerates with multi-channel retail presence, specialized curl-care laboratories with fiber-specific R&D capabilities, and emerging market localizers with humidity-adapted formulation expertise. Competitive moves concentrate on portfolio diversification into texture-specific lines and geographic expansion through regulatory affairs infrastructure deployment.
Within the integrated conglomerate tier, Procter & Gamble Company and Unilever PLC occupy positions representing mass-market distribution scale and emerging market localization expertise respectively. L'Oréal S.A. exemplifies the premium laboratory archetype through Paris-based specialized curl-care facilities. These three entities represent the dominant competitive anchors across professional salon channels and retail consumer segments, with each sitting within distinct strategic positioning vectors shaped by regulatory compliance capabilities and fiber-specific formulation depth.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Unilever PLC |
| L'Oréal S.A. |
| Henkel AG & Co. KGaA |
| Beiersdorf AG |
| Coty Inc. |
| Oribe Hair Care LLC |
| Hain Celestial Group |
| Revlon Inc. |
| Others |
Supply & Pricing Matrix
Ethylene derivative costs for petrochemical resin systems cascade through three distinct pricing tiers, with polymer volatility compressing margins on mid-tier emulsion products while premium curl-care formulations in Paris laboratories sustain markups through batch scarcity and fiber-specific R&D investment.
Pricing Analysis
Volume concentrates in mass-market sprays with thin margins, while premium creams for coily hair capture wider spreads through emollient complexity and smaller production runs. Three-tier pricing structure across professional salon, specialty barbershop, and retail consumer levels separates channel-exclusive resin systems from diluted mass-market variants. Pricing pressure stems from natural butter substitutes displacing synthetic glycerin complexes without commensurate price recovery mechanisms. Retail consumers exhibit highest price sensitivity, whereas licensed salons absorb premiums for concentrated dispensing authority.
Supply Chain Analysis
Biopolymer resin supply rests on fermentation capacity concentrated in France, Germany, and emerging biotechnology clusters in India. Key inputs include petrochemical ethylene derivatives, plant-derived fermentation feedstocks, and specialized humectant complexes. Single-source vulnerability sits with integrated polymer manufacturers possessing captive REACH documentation capabilities, creating consolidation pressure as ECHA enforcement tightens. Distribution runs through professional salon networks and direct-to-stylist digital platforms that bypass traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as formulators pursue captive control over biopolymer fermentation capacity to secure supply-chain documentation advantages under tightening REACH requirements.
For Market Incumbents: Lock in professional dispensing authority through accelerated state-level cosmetology board approvals before regulatory timelines extend further. Deepen backward integration into fermentation-derived resin production to capture biodegradability credentials and eliminate third-party REACH documentation vulnerability. Natural oil substitution pressure from clean-label demands threatens mid-tier emulsion margins without captive supply.
For New Entrants and Emerging Players: Enter via hard-water adapted formulations for mineral-rich regions in India and Brazil where chelating polymer systems remain underdeveloped. Target humidity-specific applications in emerging markets where Unilever has only begun localization efforts. Pursue verified digital credential systems enabling direct manufacturer relationships with independent stylists in Atlanta and Houston.
For Investors and Strategic Acquirers: REACH documentation consolidation among integrated polymer manufacturers is the leading indicator that regulatory affairs infrastructure will determine competitive survival over the next decade. Acquisition targets should prioritize formulators with captive toxicology testing and Paris-based curl-care laboratory assets. Watch for state-level cosmetology board approval bottlenecks as signals of channel exclusivity value.
| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Fermentation Capacity Buildout | Captive supply of REACH-compliant resins eliminates third-party documentation dependency for EU market access. |
| Direct-to-Stylist Digital Platform Launch | Bypasses distributor markups in Atlanta and Houston where specialty barbershops lead disintermediation. |
| Hard-Water Formulation Localization | Chelating polymer systems address mineral-rich conditions in São Paulo and Mumbai metropolitan centers. |
| Professional Licensing Fast-Track Investment | Accelerates 18-24 month cosmetology board approvals to secure channel exclusivity before competitors. |
| Curl-Care Laboratory Acquisition | Paris-based R&D assets provide fiber-specific polymer expertise for coily hair premium positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced with primary interviews among formulation chemists, professional salon procurement managers, specialty barbershop owners, and regulatory affairs directors at polymer suppliers. FDA voluntary reporting systems, ECHA REACH submissions, ANVISA cosmetic registrations, and BIS quality certifications provided compliance documentation trails. Bottom-up volume estimates from professional channel purchasing data were reconciled with top-down market sizing from beauty industry retail audits.
Granularity was maintained at the product-type level for creams, sprays, gels, and mousses, with further disaggregation by texture type across coily, curly, wavy, and straight hair segments and by end-user channel between salons, barbershops, and retail consumers. CAGRs were derived from trend extrapolation of polymer research investment cycles and professional licensing expansion rates. Forecast inputs incorporated humidity adaptation requirements for tropical markets and hard-water chelation demand in mineral-rich regions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price volatility or sudden state-level ingredient restrictions. Projections assume continued ECHA enforcement intensity and stable professional licensing timelines. A small set of named triggers—biopolymer fermentation scale-up rates, cosmetology board approval delays, and natural oil substitution cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Russia Salon Hair Care Market
Hair Care
Plant-Based Hair Dye Market
Hair Care
China Hair Care Products Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Germany Hair Care Market
Hair Care
Latin America Hair Care Market
Hair Care
Hair Serum Market
Hair Care
Australia Hair Care Market
Hair Care
Anti-Pollution Hair Care Market
Hair Care
Global Premium Hair Care Market
Hair Care
China Hair Care Market
Hair Care
Anti Pollution Hair Care Products Market
Hair Care
Italy Hair Care Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Qatar Hair Care Market
Hair Care
Chile Hair Care Market