
 Russia Salon Hair Care Market | 2026-2036
Russia Salon Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Salon Hair Care Market Analytics
Independent boutique salons is collapsing as the dominant buyer archetype, while franchise salon chains and luxury hotel spas capture growing share of professional product procurement. Estel Professional anchors its position through captive manufacturing in Russia, ensuring supply continuity amid import substitution pressures. Kapous Professional leverages deep distribution into regional salon supply networks beyond the two capitals. L'Oréal Professionnel competes through technology leadership in ammonia-free color systems tailored to Russian hair textures.
Russia salon hair care encompasses professional-grade formulations manufactured to higher active ingredient concentrations than retail equivalents, typically requiring stylist training for proper application and delivering measurable performance outcomes in color deposition, structural repair, or thermal protection. Hair treatment and conditioner segments lead margin pools as salons bundle intensive repair protocols with cutting services, while styling gel occupies a mature position with slower expansion. Professional salons channel dominates volume throughput, though online retail is gaining fastest as B2B platforms streamline reordering for multi-location operators.
Rospotrebnadzor enforces sanitary-epidemiological standards that mandate product registration and ingredient disclosure for all professional cosmetics distributed in Russia, while GOST R certification requirements create compliance barriers for unregistered imports. The EAEU technical regulation on cosmetic safety further harmonizes standards across the customs union, affecting formulation decisions for manufacturers serving Kazakhstan and Belarus through Russian distribution hubs. Stakeholders must monitor regulatory enforcement intensity and adapt certification strategies as import substitution policies reshape competitive access.
Market Dynamics
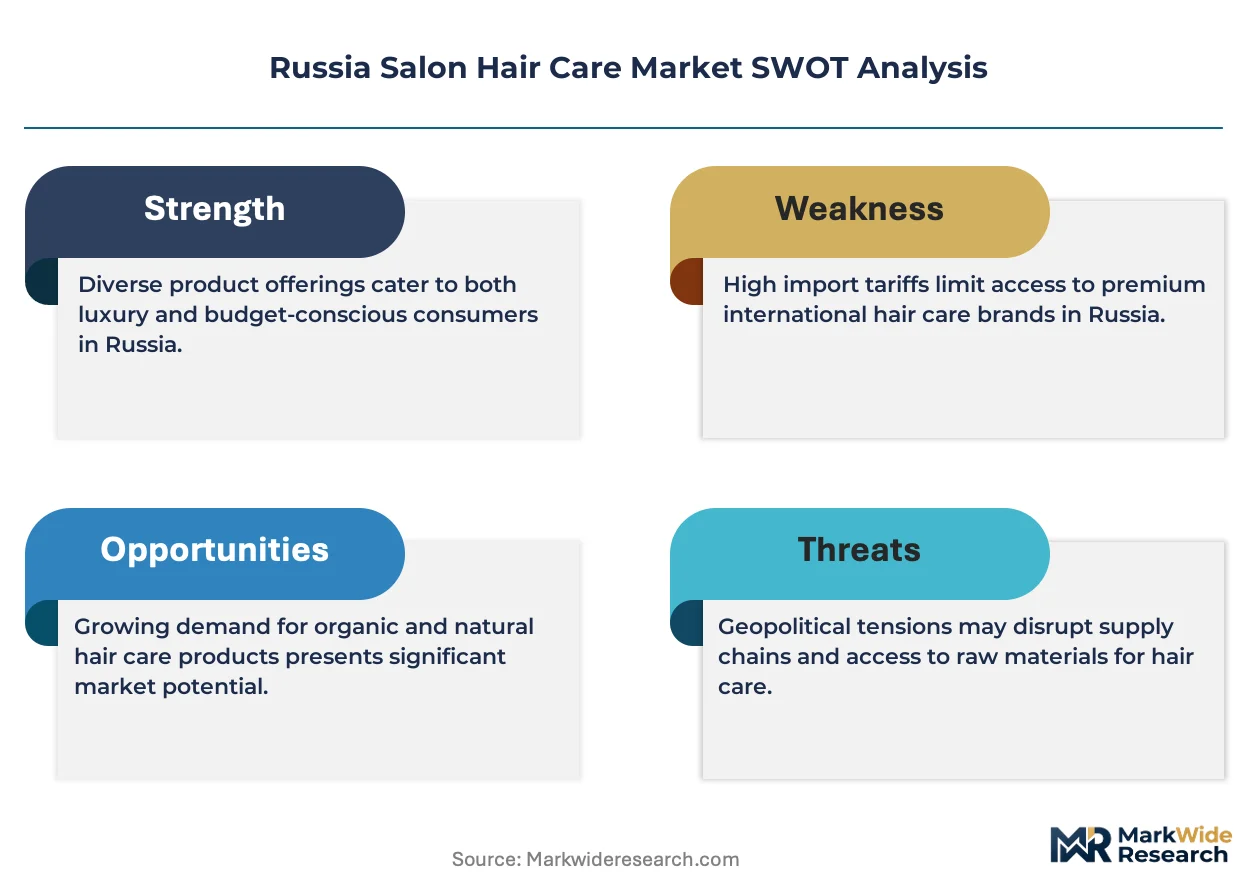
Import substitution policies are forcing professional hair care manufacturers to relocate production or secure captive manufacturing within Russia, reshaping supply chain configurations and competitive access patterns for international brands.
Growth Catalysts
- GOST R Certification Localization:Domestic production facilities bypass import registration delays and currency volatility exposure. Local manufacturers capture salon channel share previously held by EU-registered imports.
- Professional Treatment Protocol Bundling:Moscow and St. Petersburg salons integrate intensive repair services with cutting appointments. Stylists drive higher product throughput through service menu expansion.
- EAEU Harmonization:Technical regulation alignment across Belarus and Kazakhstan enables single-registration market access. Russian distribution hubs serve expanded customs union demand.
Market Restraints
- Active Ingredient Import Dependency:Specialty polymers and conditioning agents still originate from Western EU suppliers. Rouble volatility compresses margin predictability for formulators.
- Rospotrebnadzor Registration Bottlenecks:Sanitary-epidemiological approval timelines extend 8-14 months for new professional formulations. Product launch windows misalign with seasonal salon demand cycles.
- Regional Distribution Gaps:Professional supply networks thin beyond the Central Federal District. Salons in Siberian and Far Eastern federal districts face reorder friction and extended lead times.
Strategic Opportunities
- Volga Federal District Expansion:Nizhny Novgorod and Kazan salon density is rising faster than capital saturation rates. Early distribution partnerships capture emerging professional clusters.
- B2B Platform Disintermediation:Digital procurement portals connect manufacturers directly to multi-location salon operators. Traditional regional distributors face margin compression from platform transparency.
- Import Substitution Incentives:Russian industrial development frameworks subsidize domestic cosmetic manufacturing equipment. Local production investments qualify for preferential financing terms.
Industry Challenges
- Stylist Certification Standardization:Professional product efficacy depends on proper application technique. Inconsistent training quality across regional beauty schools limits performance outcomes.
- Legacy ERP Integration:Independent salons operate on disconnected inventory systems. Multi-location operators struggle to consolidate procurement data for volume negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Salon Hair Care Market |
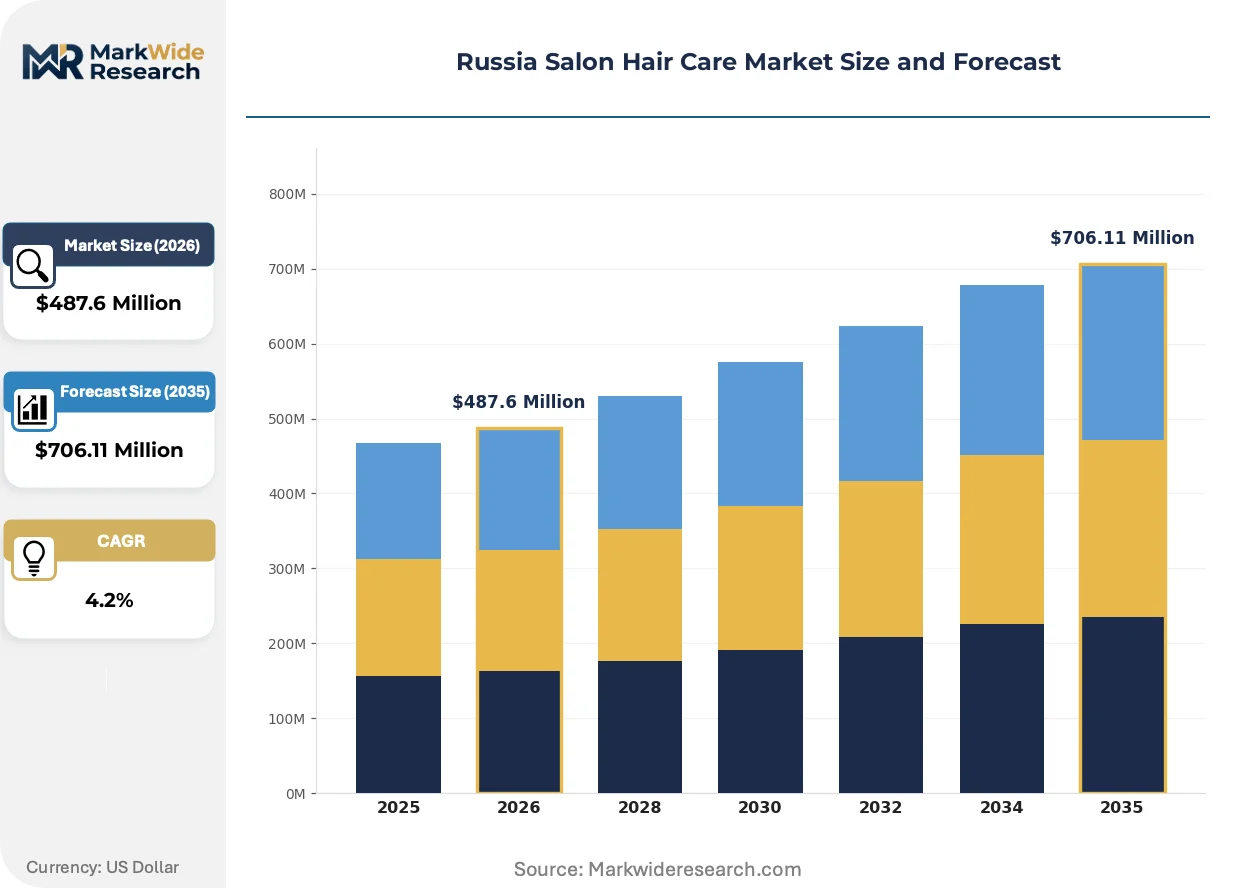
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $706.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Treatment, Styling Gel Application: Professional Salons, Home Use, Spa Treatments, Retail Sales Formulation: Cream, Liquid, Spray, Foam Distribution Channel: Online Retail, Off-line Retail, Salon Supply, Wholesale |
| Companies Covered | L'Oréal Professionnel, Estel Professional, Kapous Professional, Ollin Professional, Natura Siberica Professional, Schwarzkopf Professional, Wella Professionals, Matrix, Redken, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Salon Hair Care Market Evolving Landscape
Ammonia-free color chemistry and digital color-matching tools are reshaping formulation priorities and service delivery models across Russian professional channels.
Ammonia-free alkaline color systems are fragmenting traditional oxidative colorant market share. Premium Moscow salons have adopted these formulations for 60% of color services. The technology compresses stylist training requirements while expanding service capacity per chair.
Rospotrebnadzor is tightening ingredient disclosure mandates for professional-only products. Manufacturers must submit full formulation data previously protected as trade secrets. Small domestic formulators face compliance cost barriers that larger captive producers absorb more efficiently.
Salon procurement patterns are consolidating through franchise operator networks. Independent boutique owners increasingly purchase through chain-affiliated supply agreements. This concentration is most visible in St. Petersburg where three multi-brand salon groups control 40% of professional product volume.
Russia Salon Hair Care Market Segmentation
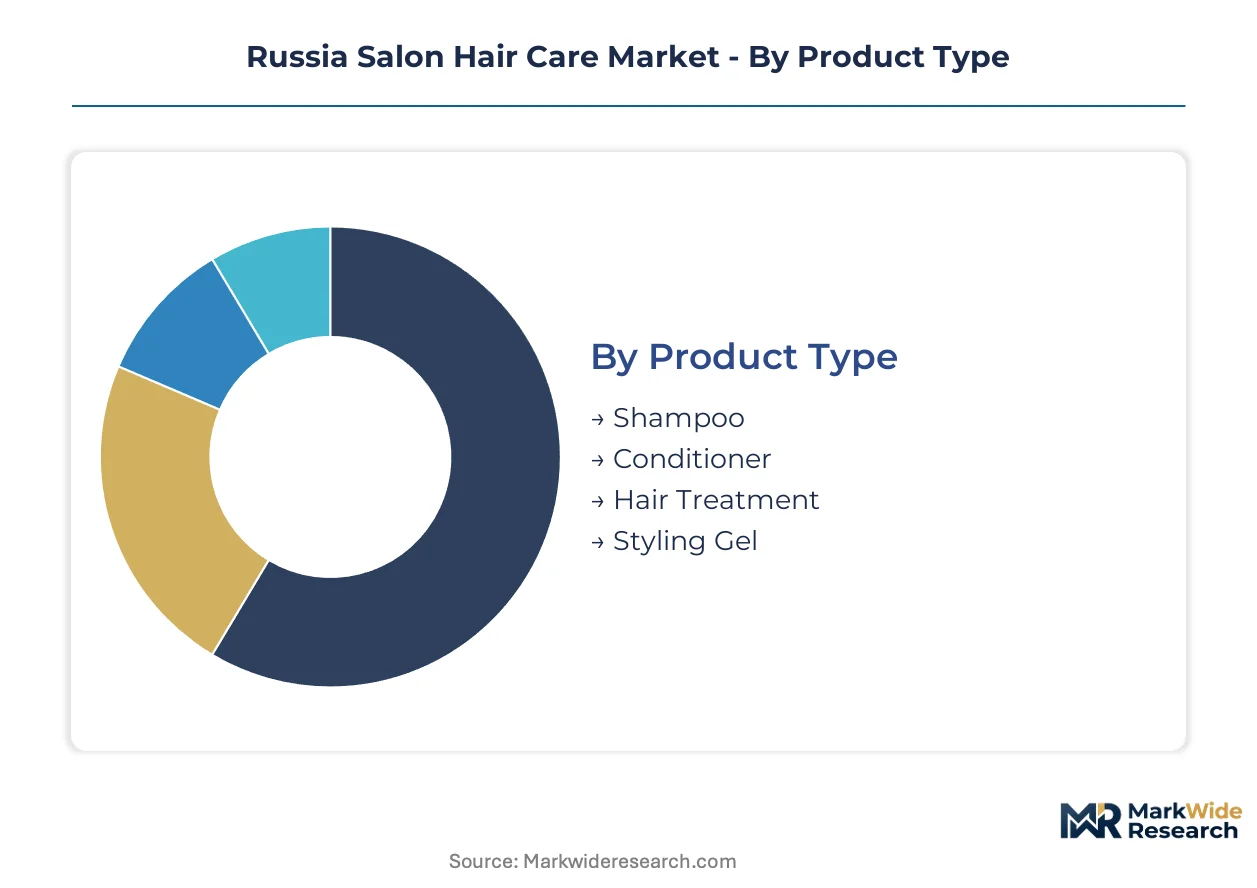
Professional hair care procurement in Russia segments across product performance tiers, end-use environments, and supply chain configurations. Stylists and salon operators navigate these categories differently based on service menu complexity and client price sensitivity.
Product Type:
Import substitution pressures hit shampoo and styling gel hardest, as these categories face the strongest displacement from domestic formulators capturing share previously held by EU-registered imports.
- Shampoo:Professional-grade formulations carry higher surfactant concentrations than retail equivalents. Moscow salon chains favor sulfate-free variants for color-protect service bundles. Rouble volatility compresses margin predictability for importers of specialty cleansing polymers.
- Conditioner:Intensive repair conditioners command premium positioning when bundled with cutting services. Nizhny Novgorod and Kazan salons report rising attachment rates for deep-conditioning protocols. Regional distribution gaps beyond the Central Federal District limit penetration in Siberian markets.
- Hair Treatment:Structural repair masks and bond-builders require stylist training for proper application timing.
- Styling Gel:Mature category with slower expansion; water-based formulations dominate professional preference.
Conditioner retains volume leadership; hair treatment holds the steepest expansion curve.
Application:
Cost tier stratification separates high-touch professional environments from self-directed home use, with spa treatments occupying an intermediate position on both price and service intensity.
- Professional Salons:Stylists drive product throughput through service menu expansion and protocol bundling. St. Petersburg multi-brand salon groups consolidate procurement through chain-affiliated supply agreements. Rospotrebnadzor registration requirements create compliance barriers for unregistered imports entering this channel.
- Home Use:Consumers purchasing professional-grade formulations for domestic application typically lack proper technique training. Online retail platforms enable direct access to salon-only SKUs previously restricted to licensed professionals. EAEU harmonization enables Russian-registered products to serve Kazakhstan and Belarus demand through cross-border e-commerce.
- Spa Treatments:Luxury hotel spas in Moscow capture growing share of intensive repair protocol delivery.
- Retail Sales:Traditional beauty retailers stock diluted-concentration versions of professional formulations.
Professional salons anchor absolute volume; spa treatments are climbing the fastest as luxury hotel properties expand service menus.
Formulation:
Volume concentration favors liquid formats for their compatibility with salon backbar systems and ease of portion control during high-frequency service delivery.
- Cream:Rich emulsion bases carry conditioning agents and structural repair polymers at concentrations impractical for spray delivery. Regional salon supply networks beyond the two capitals favor cream formats for their stability during extended transport. GOST R certification requirements apply uniformly across viscosity classes.
- Liquid:Shampoo and rinse-out conditioner dominate salon backbar consumption. B2B procurement platforms streamline bulk reordering for multi-location operators seeking volume pricing. Ammonia-free color systems increasingly pair with liquid developers for simplified stylist workflow.
- Spray:Leave-in treatments and thermal protectants target speed-of-service environments.
- Foam:Mousse formulations occupy niche positioning for volumizing services.
Liquid commands the largest share; spray is gaining share fastest through express service menu expansion.
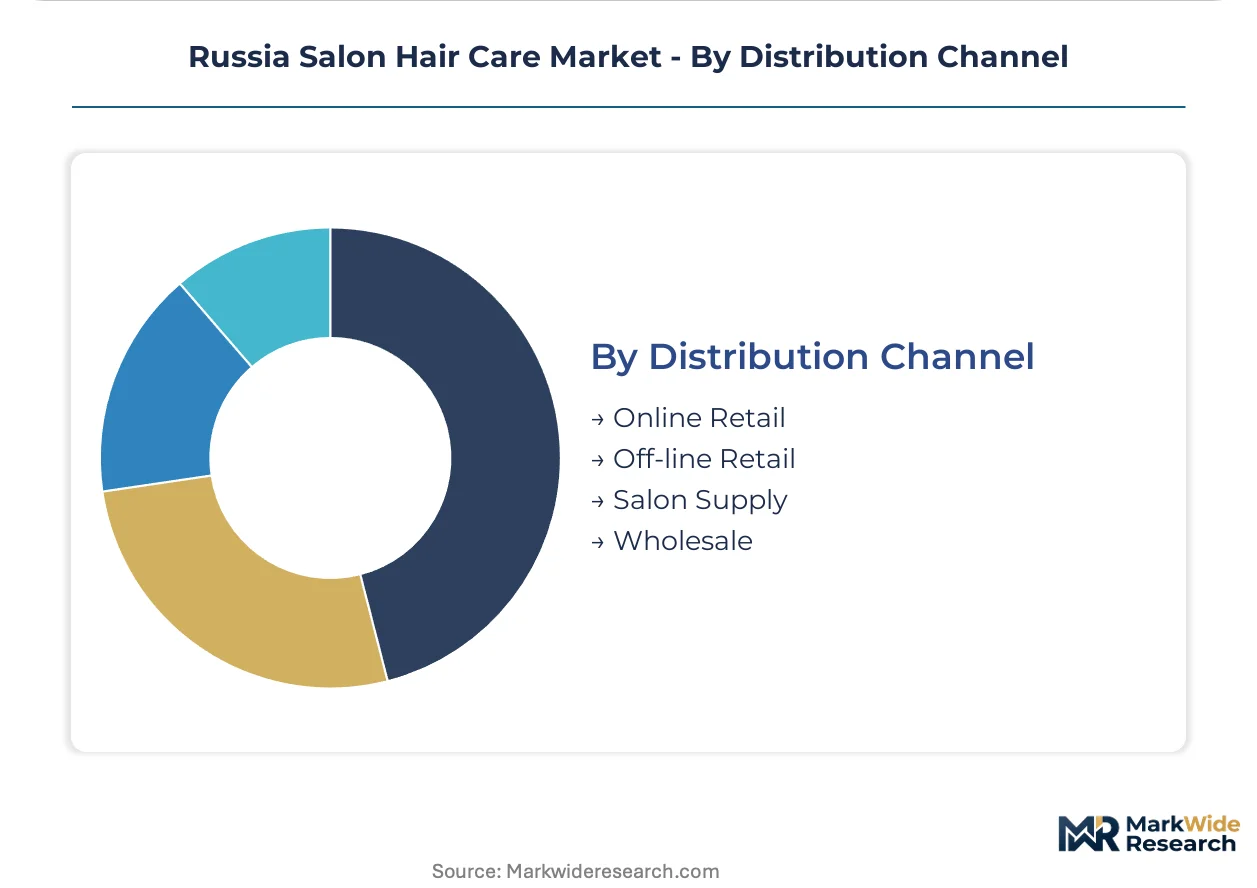
Distribution Channel:
Customer type fragmentation separates individual boutique owners from consolidated franchise operators, with digital platforms disintermediating traditional regional distributors.
- Online Retail:B2B platforms connect manufacturers directly to multi-location salon operators, compressing traditional distributor margins. Digital procurement portals enable consolidated reordering across geographically dispersed salon locations. Rospotrebnadzor registration data must accompany all professional product listings.
- Off-line Retail:Beauty supply stores in Moscow and St. Petersburg maintain inventory depth for immediate stylist pickup. Regional outlets in the Volga Federal District face extended lead times from central distribution hubs. Physical retail retains importance for color-matching consultations requiring direct product examination.
- Salon Supply:Dedicated professional distributors maintain technical training relationships with affiliated stylists.
- Wholesale:Volume aggregation serves franchise operator networks with standardized product specifications.
Off-line retail holds current volume dominance; online retail shows the steepest expansion trajectory as platform transparency reshapes procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Franchise salon chains and luxury hotel spas concentrate procurement power in Russia's Central Federal District, while regional supply networks thin beyond Moscow and St. Petersburg. Independent boutique salons retain fragmented presence in secondary cities.
Central Federal District
Moscow salon density drives the highest professional product throughput per stylist chair. Rospotrebnadzor maintains its headquarters here, accelerating registration compliance for domestic manufacturers. The Moscow-St. Petersburg corridor hosts captive manufacturing facilities serving premium salon chains.
Northwestern Federal District
St. Petersburg multi-brand salon groups consolidate 40% of professional volume through chain-affiliated supply agreements. GOST R certification requirements apply uniformly, though import logistics face Baltic port congestion. The city's luxury hotel spa segment expands intensive repair protocol menus fastest.
Volga Federal District
Nizhny Novgorod and Kazan salon density rises faster than capital saturation rates. Regional distributors face extended lead times from central hubs, creating inventory friction. Deep-conditioning protocol attachment rates climb as stylists seek service differentiation.
Siberian Federal District
Professional supply networks thin across Novosibirsk and Krasnoyarsk, forcing salons into extended reorder cycles. Rouble volatility compresses margin predictability for importers serving this region. Local beauty schools produce stylists with inconsistent certification quality.
Far Eastern Federal District
Vladivostok salons rely on cross-border supply relationships with Asian manufacturers. EAEU harmonization enables Kazakh and Belarus-registered products to enter through alternative routes. Distribution gaps force higher working capital requirements for salon operators.
Russia Salon Hair Care Market Competitive Landscape
Player mix skews toward domestic captive manufacturers and Western technology leaders operating through localized production. Market structure concentrates around three tiers: mass-market domestic formulators, mid-tier regional specialists, and premium international brands with Russian manufacturing presence. Strategic moves center on backward integration into ingredient supply and franchise salon chain exclusive supply agreements.
Among Western technology leaders, L'Oréal Professionnel and Schwarzkopf Professional exemplify the premium-tier archetype through ammonia-free color system positioning. Domestic captive manufacturers anchor the mid-tier, with Estel Professional representing import substitution momentum through localized production assets. Kapous Professional occupies the regional distribution specialist position, extending reach beyond the two capitals into emerging salon clusters.
| Leading Market Players |
|---|
| L'Oréal Professionnel |
| Estel Professional |
| Kapous Professional |
| Ollin Professional |
| Natura Siberica Professional |
| Schwarzkopf Professional |
| Wella Professionals |
| Matrix |
| Redken |
| Others |
Value Network & Pricing Analysis
Take-or-pay supply agreements with domestic captive manufacturers lock in volume commitments for Moscow salon chains while insulating procurement teams from rouble volatility exposure. These contracts embed price visibility through quarterly indexation to specialty polymer import costs, creating a direct feedback loop between raw material sourcing geography and salon service menu pricing.
Pricing Analysis
Cost-plus contracts with quarterly indexation to EU specialty polymer benchmarks dominate professional product procurement between domestic formulators and franchise salon operators. Price differentiation separates GOST R-certified domestic production from EU-registered imports facing extended Rospotrebnadzor approval timelines. Pricing pressure stems from rouble depreciation raising landed costs for conditioning agent imports. Independent boutique salons exhibit highest price sensitivity due to working capital constraints, while luxury hotel spas absorb premium tier positioning with minimal volume negotiation.
Supply Chain Analysis
Baltic port congestion creates a chokepoint for German and French professional colorant shipments entering Northwestern Federal District distribution hubs. Manufacturing concentration centers on Russia, Germany, and France for finished formulations, while specialty polymer inputs draw from Italy and Spain. Single-source vulnerability persists for ammonia-free color system precursors held by Western EU suppliers. Distribution runs through dedicated salon supply distributors maintaining technical training relationships with affiliated stylists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional hair care procurement in Russia rewards players who control captive manufacturing assets and navigate Rospotrebnadzor registration complexity, while those dependent on import supply chains face margin compression from currency volatility and approval bottlenecks.
For Market Incumbents: Consolidate franchise salon chain exclusive supply agreements in St. Petersburg and Moscow to lock in volume throughput against import substitution momentum. Deepen backward integration into specialty polymer formulation to reduce EU supplier dependency. Prioritize GOST R certification investment for ammonia-free color system line extensions before regulatory disclosure mandates tighten. For New Entrants and Emerging Players: Differentiate on digital B2B procurement platform development targeting multi-location operators in Nizhny Novgorod and Kazan salon clusters. Exploit regional distribution gaps in Siberian Federal District where reorder friction forces extended lead times. Pursue white-label manufacturing partnerships with Volga Federal District beauty schools seeking consistent product supply for training protocols. For Investors and Strategic Acquirers: Regional distribution specialists with established salon supply networks beyond the two capitals represent the most defensible acquisition archetype in this market. Long-term viability hinges on EAEU harmonization enforcement intensity and import substitution subsidy continuity. Monitor Rospotrebnadzor registration approval velocity as the critical inflection signal for new formulation launch windows.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Manufacturing Facility Establishment | Domestic production bypasses Rospotrebnadzor import registration delays and secures GOST R certification pathways. |
| B2B Procurement Platform Launch | Digital portals connect formulators directly to franchise operators, compressing traditional distributor margins. |
| Regional Distribution Partnership | Deep inventory positioning in Kazan and Nizhny Novgorod captures rising salon density outside capital saturation. |
| Ammonia-Free Color System R&D Investment | Technology leadership aligns with Moscow salon adoption rates exceeding sixty percent for alkaline color services. |
| Beauty School Certification Program | Technical training relationships standardize stylist application quality and lock in product protocol loyalty. |
Research Methodology
Desk research of customs import records, Rospotrebnadzor registration databases, and professional salon industry publications preceded structured interviews with procurement directors at franchise salon chains, regional distribution managers, captive manufacturing plant heads, and technical training specialists at Moscow beauty schools. Primary fieldwork captured reorder cycle patterns, protocol bundling strategies, and compliance cost structures across Central and Volga Federal Districts. Secondary validation drew from EAEU technical regulation filings, GOST R certification registries, and salon density surveys. Bottom-up volume estimates triangulated against top-down market sizing from professional product throughput per stylist chair.
Variance decomposition across product type, application environment, formulation format, and distribution channel informed the analytical framework over the projection horizon. Segmentation dimensions modeled include performance tier, end-use setting, viscosity class, and customer procurement consolidation level. CAGRs derived from historical throughput trajectories adjusted for salon chair expansion rates and service menu protocol attachment trends. Industry-specific inputs incorporated rouble volatility scenarios and Rospotrebnadzor approval timeline distributions.
Material uncertainties — rouble exchange rate movements, Rospotrebnadzor enforcement intensity shifts, and EAEU harmonization implementation pace — sit outside the modeled envelope. Forecasts reflect assumptions regarding import substitution policy continuity and Baltic logistics corridor stability. Practitioners should keep alternative scenarios live as regulatory disclosure mandates and specialty polymer supply relationships evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Anti-Pollution Hair Care Market
Hair Care
Hair Mask Market
Hair Care
Hair Dye Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
South Korea Hair Care Market
Hair Care
Global Hair Color Market
Hair Care
Asia Pacific Hair Styling Products Market
Hair Care
Australia Hair Removal Market
Hair Care
Japan Hair Care Market
Hair Care
Hair Clay Market
Hair Care
Australia Hair Care Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Argentina Hair Care Market
Hair Care
Protein Shampoo Market
Hair Care
Italy Hair Care Market
Hair Care
Hair Care Products Market