
 Global Banking BPS Market | 2026-2036
Global Banking BPS Market Size, Share, and Industry Trends Forecast 2026-2036
Global Banking BPS Market Foresight
The EU AI Act is realigning how European retail banks procure algorithmic fraud detection and customer onboarding services, forcing providers to embed auditability into automated workflows. Cognizant leverages its healthcare-adjacent compliance expertise to cross-sell KYC solutions into US regional banks. Infosys anchors its position through the Finacle platform, sustaining deep integration with core banking systems across Asian and African markets. Tata Consultancy Services dominates nearshore delivery from Poland and Latin America, competing on regulatory proximity for EU clients.
Banking Business Process Services encompass the outsourcing of non-core yet operationally critical functions—customer onboarding, loan processing, fraud detection, KYC compliance, and payment reconciliation—to third-party specialists who deploy robotic process automation, artificial intelligence, and cloud infrastructure to execute these workflows. The primary commercial purpose is to reduce unit transaction costs while satisfying stringent regulatory audit trails and data residency requirements. Cloud-based delivery models are capturing the fastest expansion as hybrid work architectures and distributed data centers reduce latency for real-time payment reconciliation. Artificial Intelligence segments command premium pricing due to model training complexity and the scarcity of banking-domain machine learning engineers, while pure onshore delivery shows maturity with slower growth but stickier contract renewals among US credit unions.
The European Banking Authority, the Reserve Bank of India, and the US Federal Reserve each impose distinct data localization and model governance standards that fragment vendor certification requirements and inflate compliance overhead. India's Digital Personal Data Protection Act and the US Fair Credit Reporting Act amendments are tightening consent frameworks for automated credit decisions, redirecting procurement toward providers with pre-certified regulatory stacks. Stakeholders must monitor divergence between EU algorithmic transparency mandates and US sectoral guidance to avoid stranded technology investments in incompatible compliance architectures.
Market Dynamics
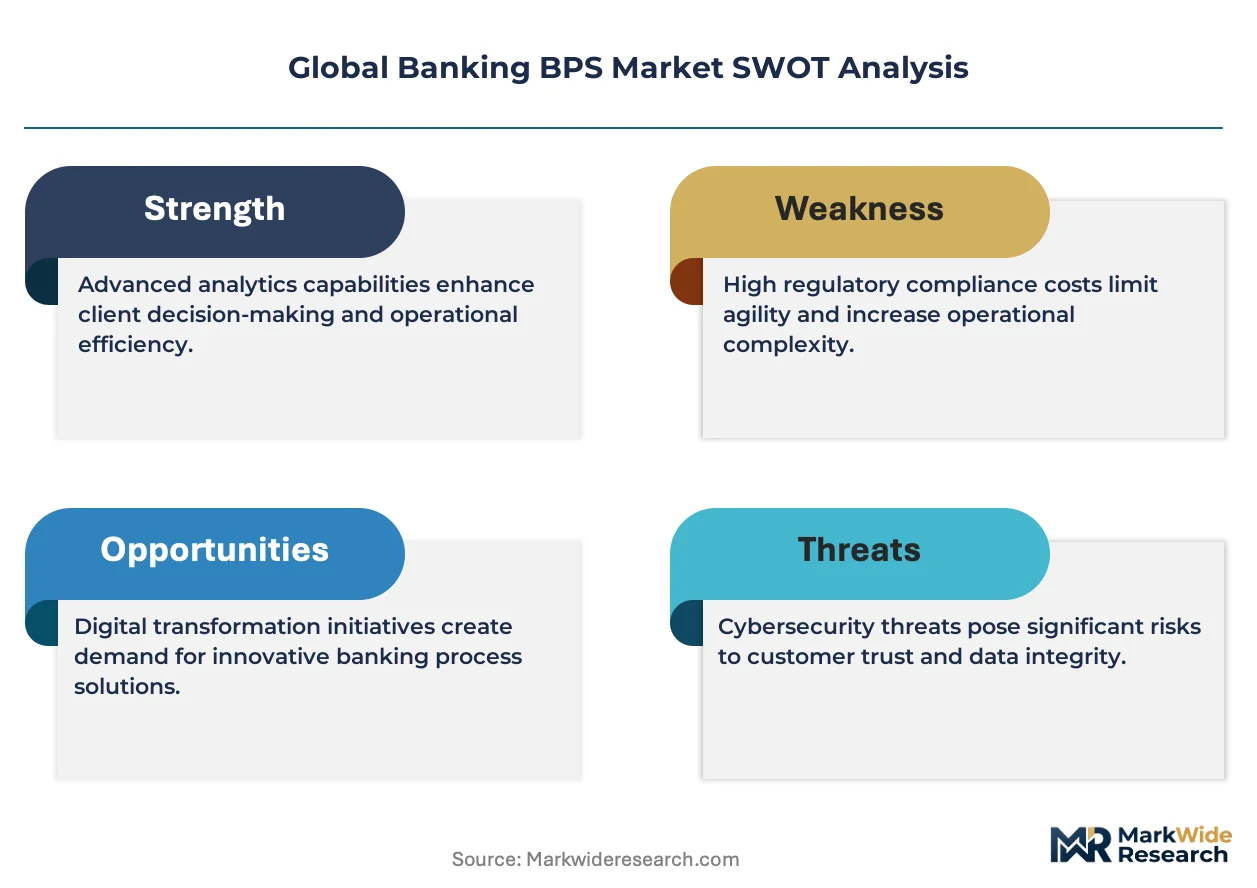
Algorithmic governance frameworks are fragmenting vendor certification requirements across jurisdictions, forcing Banking BPS providers to maintain parallel compliance architectures for EU AI Act transparency mandates, RBI data localization rules, and US Fair Credit Reporting Act amendments.
Growth Catalysts
- EU AI Act auditability mandates:European retail banks must embed explainable decision trails into automated fraud detection and customer onboarding workflows, creating procurement pull for certified providers.
- Cloud infrastructure maturation:Hybrid work architectures and distributed data centers are reducing latency for real-time payment reconciliation, accelerating migration from on-premise legacy stacks.
- India's Digital Personal Data Protection Act:Tightened consent frameworks for automated credit decisions are redirecting procurement toward providers with pre-certified regulatory stacks in Mumbai and Bangalore delivery clusters.
Market Restraints
- Scarcity of banking-domain machine learning engineers:AI segments command premium pricing due to model training complexity and limited talent pools, compressing margins for mid-tier providers.
- Data residency fragmentation:Divergent requirements from the European Banking Authority, Reserve Bank of India, and US Federal Reserve inflate compliance overhead and prevent standardization.
- Onshore delivery maturity:Pure onshore models show slower growth due to higher unit labor costs, though they retain stickier contract renewals among US credit unions.
Strategic Opportunities
- Nearshore EU delivery from Poland:Regulatory proximity to Brussels enables faster certification cycles for algorithmic transparency requirements compared to offshore alternatives.
- Healthcare-adjacent compliance cross-sell:KYC solution providers with HIPAA-grade audit experience can leverage existing trust relationships to penetrate US regional banking.
- Core banking system integration in African markets:Deep Finacle platform integration creates defensive moats against point-solution competitors in underpenetrated jurisdictions.
Industry Challenges
- Parallel compliance architecture maintenance:Providers must simultaneously satisfy EU algorithmic transparency mandates and US sectoral guidance to avoid stranded technology investments.
- Legacy system integration friction:Robotic process automation deployment faces technical debt obstacles in Asian and African banks running decades-old core banking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Banking BPS Market |
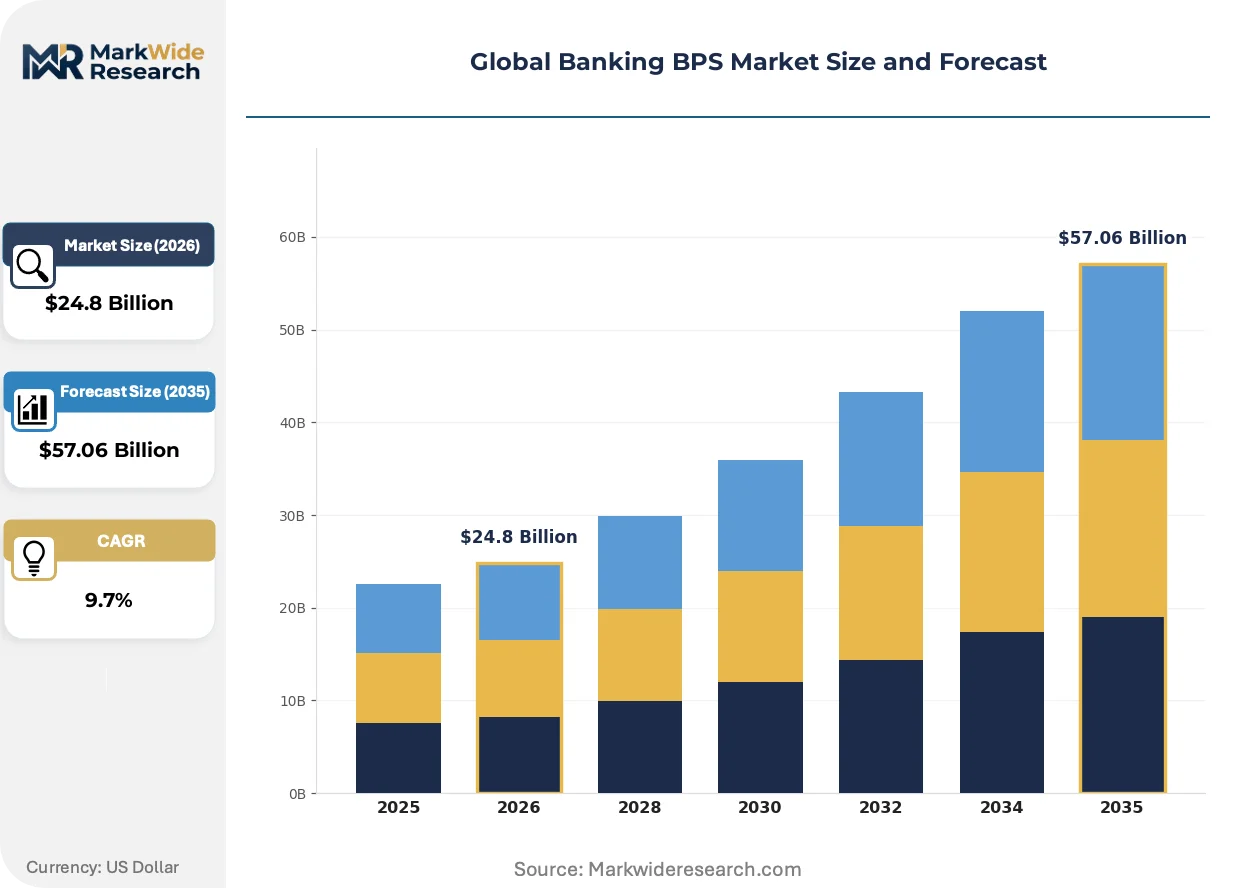
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $57.06 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Customer Onboarding, Loan Processing, Fraud Detection, KYC Compliance, Payment Reconciliation Client Type: Retail Banks, Credit Unions, Investment Firms, Payment Processors, Wealth Management Firms Delivery Model: Onshore, Nearshore, Offshore, Hybrid, Cloud-Based Technology: Robotic Process Automation, Artificial Intelligence, Blockchain, Big Data Analytics, Cloud Computing |
| Companies Covered | Atos SE, Capgemini, Cognizant, HCL Technologies, Infosys, Tata Consultancy Services, Wipro, Genpact, DXC Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Banking BPS Market Shifts & Advancements
Generative AI capabilities are compressing document processing timelines in loan origination and KYC verification, while regulatory divergence between jurisdictions is spawning specialized compliance-as-a-service offerings.
Large language models trained on banking regulatory corpora are expanding into contract abstraction and suspicious transaction narrative generation. Tier-1 institutions in London and New York are piloting these tools for adverse media screening and PEP identification. The technology is expanding into mid-market regional banks that previously lacked capital for dedicated compliance analytics teams.
The EU AI Act's risk-based classification system for credit-scoring algorithms is forcing European institutions to maintain human-in-the-loop overrides for high-risk automated decisions. Providers must now document training data provenance and model drift metrics to retain certification. French and German retail banks are responding by consolidating vendor relationships around those with pre-built algorithmic governance modules.
Subscription-based service contracts are displacing traditional per-transaction pricing in payment reconciliation and fraud detection outsourcing. US credit unions and UK building societies are leading this shift, seeking predictable cost structures amid interest rate volatility. The model is most visible in the American Midwest and Southeast, where regional banks prioritize operational expenditure predictability over volume-scaled unit economics.
Global Banking BPS Market Segmentation
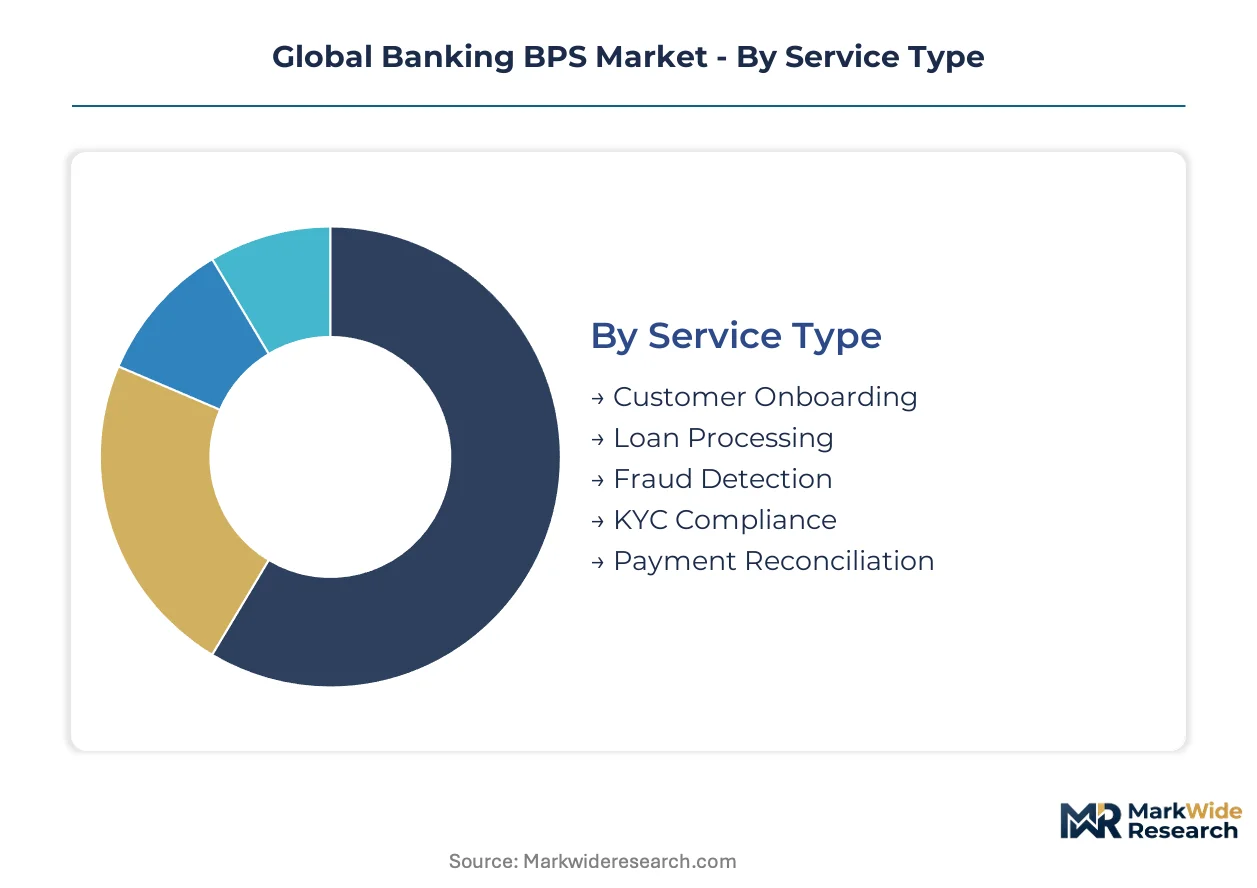
Banking BPS procurement patterns diverge sharply across service complexity tiers and regulatory exposure levels. Understanding these fault lines clarifies where automation investments concentrate and where human-in-the-loop requirements persist.
Service Type:
Technology sophistication determines contract value and renewal stickiness across service categories.
- Fraud Detection:Real-time algorithmic monitoring of transaction streams demands explainable AI architectures under EU AI Act mandates. European retail banks in Frankfurt and Paris are consolidating vendor relationships around providers with pre-certified governance modules.
- KYC Compliance:Identity verification and adverse media screening workflows integrate biometric validation and document abstraction. US regional banks are cross-purchasing HIPAA-grade audit trails from healthcare-adjacent specialists to satisfy tightened consent frameworks.
- Customer Onboarding:Digital account opening with embedded risk scoring.
- Loan Processing:Credit decision automation with human override protocols.
- Payment Reconciliation:High-volume transaction matching with exception handling.
Mature deployment sits with Payment Reconciliation. Newer deployment is concentrated in Fraud Detection.
Client Type:
Institutional scale and regulatory scrutiny shape outsourcing depth and pricing tolerance.
- Retail Banks:Full-spectrum outsourcing of core operations including payment reconciliation and fraud detection. Institutions in Mumbai and London are driving the steepest expansion trajectory as they rebalance cost pressures against algorithmic governance requirements.
- Credit Unions:Subscription-based contracts prioritizing operational expenditure predictability over volume-scaled economics. US Midwest and Southeast clusters favor this model amid interest rate volatility.
- Investment Firms:Specialized compliance and trade processing support.
- Payment Processors:Real-time infrastructure scaling and latency reduction.
- Wealth Management Firms:High-net-worth client onboarding and regulatory reporting.
Volume concentration aligns with Retail Banks. Margin expansion is strongest in Credit Unions.
Delivery Model:
Geographic placement of operations directly determines certification speed and data residency compliance.
- Cloud-Based:Distributed data centers with hybrid work architectures reduce latency for real-time payment reconciliation. This model is climbing the fastest as Asian and African banks abandon on-premise legacy stacks.
- Nearshore:Poland and Latin America delivery clusters compete on regulatory proximity for EU clients, enabling faster algorithmic transparency certification cycles compared to offshore alternatives.
- Onshore:Higher unit labor costs with stickier renewals among US credit unions.
- Offshore:Mumbai and Bangalore clusters anchored by India's data protection requirements.
- Hybrid:Mixed geographic deployment for risk distribution.
Contract velocity favors Cloud-Based. Longest average tenure sits with Onshore.
Technology:
Implementation complexity and talent scarcity create pricing stratification across technology layers.
- Artificial Intelligence:Model training for credit-scoring and fraud detection commands premium pricing due to scarcity of banking-domain machine learning engineers. EU AI Act documentation requirements for training data provenance and drift metrics add compliance overhead.
- Robotic Process Automation:Legacy system integration faces technical debt obstacles in Asian and African banks running decades-old core banking infrastructure, compressing deployment timelines.
- Big Data Analytics:Regulatory corpus training for contract abstraction and suspicious transaction narrative generation.
- Cloud Computing:Infrastructure elasticity for transaction volume spikes.
- Blockchain:Distributed ledger applications in trade finance and cross-border settlement.
Revenue intensity peaks in Artificial Intelligence. Deployment friction concentrates in Robotic Process Automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors the largest delivery cluster for banking BPS, with Bangalore and Hyderabad forming a contiguous talent corridor that processes payment reconciliation and fraud detection workflows for European and North American retail banks.
United States
Regional banks in the American Midwest and Southeast are consolidating vendor relationships around subscription-based contracts for KYC compliance and fraud detection. The US Federal Reserve's Fair Credit Reporting Act amendments tighten consent frameworks for automated credit decisions. Dallas and Charlotte delivery centers specialize in HIPAA-grade audit trails that cross-sell into credit union procurement.
United Kingdom
London-based tier-1 institutions pilot generative AI tools for adverse media screening and politically exposed person identification. The Financial Conduct Authority's algorithmic governance guidance shapes procurement requirements for explainable fraud detection workflows. Edinburgh and Manchester clusters concentrate mid-market regional bank outsourcing for payment reconciliation.
Germany
Frankfurt retail banks consolidate vendor relationships around providers with pre-certified EU AI Act governance modules for credit-scoring algorithms. BaFin's implementation of risk-based classification systems mandates human-in-the-loop overrides for high-risk automated decisions. Berlin fintech corridors attract compliance-as-a-service specialists targeting algorithmic transparency requirements.
India
The Reserve Bank of India's data localization rules redirect procurement toward providers with pre-certified regulatory stacks in Mumbai and Bangalore delivery clusters. The Digital Personal Data Protection Act tightens consent frameworks for automated credit decisions. Pune and Chennai hubs expand capacity for core banking system integration across Asian and African markets.
Poland
Warsaw and Krakow delivery centers compete on regulatory proximity for EU clients, enabling faster algorithmic transparency certification cycles compared to offshore alternatives. The Polish Financial Supervision Authority aligns with European Banking Authority standards for model governance. Katowice clusters specialize in nearshore payment reconciliation for German and French retail banks.
Global Banking BPS Market Competitive Landscape
The competitive structure tilts toward scale-driven IT services conglomerates with embedded banking domain expertise. The vendor base clusters around three strategic archetypes: India-headquartered delivery specialists with global nearshore footprints, European-origin consultancies with regulatory certification depth, and US-based technology integrators with healthcare-adjacent compliance cross-sell capabilities. Dominant competitive moves include geographic expansion into nearshore EU delivery clusters and portfolio diversification through algorithmic governance module development.
Within the India-origin delivery tier, Tata Consultancy Services, Infosys, and Wipro exemplify scale-driven competitive positioning. These entities anchor nearshore delivery from Poland and Latin America while maintaining deep integration with core banking systems across underpenetrated jurisdictions. Cognizant occupies a position bridging US regional banking relationships with healthcare-adjacent compliance expertise for KYC solution cross-selling.
| Leading Market Players |
|---|
| Atos SE |
| Capgemini |
| Cognizant |
| HCL Technologies |
| Infosys |
| Tata Consultancy Services |
| Wipro |
| Genpact |
| DXC Technology |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EU AI Act-compliant algorithmic governance modules and standard automation stacks manifests in both pricing premiums and supply chain configuration. Tier-1 providers with pre-certified transparency architectures command sustained margin premiums, while mid-tier vendors face cost compression from parallel compliance architecture maintenance across Mumbai, Warsaw, and Dallas delivery clusters.
Pricing Analysis
Outcome-based pricing tied to fraud detection throughput and KYC verification accuracy anchors contract structures for AI-enabled service tiers. Three-tier pricing structure across premium algorithmic governance, standard RPA automation, and economy-grade back-office processing reflects certification depth and audit trail sophistication. Pricing pressure stems from scarcity of banking-domain machine learning engineers compressing margins in mid-tier AI segments. US credit unions exhibit highest price sensitivity through subscription-based procurement, while Frankfurt retail banks tolerate premium pricing for EU AI Act pre-certification.
Supply Chain Analysis
Reverse-logistics flows for model retraining and algorithmic drift remediation create secondary value recovery in fraud detection and credit-scoring service tiers. Talent supply concentrates in India, Poland, and the United States as primary delivery clusters for algorithmic governance and core banking integration. Raw material dependencies span cloud compute capacity, regulatory corpus training data, and biometric validation infrastructure. Single-source vulnerability sits with concentrated machine learning engineering pools in Mumbai and Bangalore. Distribution runs through direct enterprise sales for tier-1 institutions and channel partners for mid-market regional banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as algorithmic governance fragmentation and parallel compliance architecture costs force weaker providers toward exit or acquisition by scale-driven IT services conglomerates.
For Market Incumbents: Hedge against regulatory divergence by embedding modular algorithmic governance stacks that port across EU AI Act, RBI data localization, and US Fair Credit Reporting Act requirements. Deepen Finacle platform integration in African and Asian markets to create defensive moats against point-solution competitors. Prioritize nearshore capacity expansion in Poland and Latin America to compress certification cycles for EU retail banking clients. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for compliance-as-a-service specialists targeting algorithmic transparency documentation and model drift monitoring. White-space targets include mid-market US regional banks lacking capital for dedicated governance analytics teams and underpenetrated African jurisdictions with legacy core banking infrastructure. Go-to-market positioning should anchor on pre-certified regulatory stacks that accelerate procurement timelines for risk-averse compliance officers. For Investors and Strategic Acquirers: Re-rating potential sits with India-headquartered delivery specialists with embedded nearshore EU footprints given accelerating consolidation pressure from compliance cost inflation. Long-term viability favors scale-driven providers with cross-sell capability into healthcare-adjacent KYC compliance and core banking system integration depth. Monitor divergence between EU algorithmic transparency mandates and US sectoral guidance as inflection indicator for stranded technology risk in incompatible compliance architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Governance Module Development | Pre-certified EU AI Act stacks accelerate procurement cycles for Frankfurt and Paris retail banks. |
| Nearshore EU Delivery Expansion | Poland and Latin America clusters compress certification timelines versus offshore alternatives. |
| Healthcare-Adjacent Compliance Cross-Sell | HIPAA-grade audit expertise penetrates US regional banking through existing trust relationships. |
| Core Banking System Integration Deepening | Finacle platform moats defend against point-solution competitors in African markets. |
| Subscription-Based Contract Transition | Predictable OPEX structures attract US Midwest credit unions amid interest rate volatility. |
Research Methodology
Independent corroboration across primary interviews with banking operations executives, regulatory compliance officers, procurement leads at retail banks, and cloud infrastructure specialists underwrites the qualitative findings. Secondary validation draws from European Banking Authority guidance documents, Reserve Bank of India circulars, US Federal Reserve supervisory letters, and SEC filings from listed IT services providers. Bottom-up service-line revenue triangulation against top-down market sizing anchors volume and value estimates.
Comparable-period anchoring to historical outsourcing penetration rates and automation adoption curves structures the projection framework across the analysis window. Segmentation dimensions span service type complexity tiers, client institutional scale, delivery model geographic placement, and technology implementation layers. CAGRs derive from regression against correlated macro indicators including banking sector IT spend growth and regulatory compliance cost inflation. Forecast inputs incorporate algorithmic governance certification timelines and cloud infrastructure maturation trajectories.
Caveats apply where abrupt regulatory divergence between EU AI Act implementation and US sectoral guidance could materially shift the outlook for stranded technology investments. Practitioners should monitor central bank data localization rulings and machine learning engineering talent migration patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Data Analytics in Banking Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
South Korea Data Analytics in Banking Market
Banking
US Banking-As-A-Service Market
Banking
Cloud Computing Banking Market
Banking
US Retail Banking Market
Banking
Europe Machine Learning in Banking Market
Banking
Machine Learning in Banking Market
Banking
Asia-Pacific Machine Learning in Banking Market
Banking
Internet of Things (IoT) in Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
UK Retail Banking Market
Banking
Corporate Digital Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Global Banking Systems Software Market
Banking
Investment Banking and Trading Services Market