
 Global Organic Furniture Market | 2026-2036
Global Organic Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Furniture Market Foresight
Southeast Asian bamboo processors are pivoting toward certified organic supply chains to serve European and North American buyers. Greenington Bamboo Furniture leverages its vertical plantation-to-finished-goods pipeline to sustain cost advantages in solid bamboo seating. Vermont Woods Studios anchors its competitive position through domestically sourced reclaimed timber and direct-to-consumer channel control. Moso International B.V. dominates European specification markets with engineered bamboo panels that meet ECHA REACH compliance thresholds.
Organic furniture comprises seating, storage, and sleep systems fabricated from untreated or minimally processed renewable materials including bamboo, reclaimed wood, cork, rattan, and seagrass, with finishes free of synthetic volatile organic compounds and flame retardants; these products serve residential, hospitality, and workplace environments where indoor air quality certification and material traceability are specified procurement criteria. Bamboo and reclaimed wood command the largest current volume positions, while seagrass weaving techniques are gaining fastest among artisanal and boutique hospitality segments. Online retail and direct-to-consumer channels capture the highest margin pools by eliminating wholesale markups, though specialty stores remain essential for tactile material validation.
The EU Green Deal and REACH frameworks mandate chemical content disclosure for imported furniture, while the U.S. EPA administers formaldehyde emission standards under the Toxic Substances Control Act; Japan's METI enforces JIS standards for indoor air quality that effectively filter non-compliant imports. These regulatory layers compel manufacturers to maintain dual certification portfolios or risk exclusion from premium procurement channels. Stakeholders must monitor evolving extended producer responsibility proposals in the European Union and California that would impose end-of-life recovery obligations on furniture brands.
Market Dynamics
The EU Green Deal and REACH frameworks are compressing chemical disclosure timelines for furniture imports, forcing manufacturers to reconfigure certification portfolios or forfeit access to premium procurement channels across Germany, France, and the Netherlands.
Growth Catalysts
- EU F-Gas Regulation:Tighter chemical disclosure mandates for imported furniture are filtering non-compliant producers from German and French specification markets, elevating certified organic suppliers.
- Bamboo plantation-to-finished-goods pipelines:Southeast Asian processors are achieving cost parity with conventional timber through captive supply control and reduced chemical finishing requirements.
- Residential bedroom and dining procurement:Certified organic sleep systems and storage pieces are capturing specification share in US and Japanese markets where indoor air quality certification is a mandatory bid criterion.
Market Restraints
- Reclaimed timber input volatility:Supply of domestically sourced reclaimed wood in the United States fluctuates with demolition cycles and competing demand from construction salvage markets.
- Bamboo processor concentration:Engineered bamboo panel supply for European specification markets clusters among a narrow base of certified processors in Vietnam and Indonesia.
- Formaldehyde emission compliance friction:The US EPA Toxic Substances Control Act testing protocols create certification bottlenecks for small-batch artisanal producers lacking in-house laboratory capacity.
Strategic Opportunities
- Japanese METI JIS standards expansion:Stricter indoor air quality enforcement is creating import substitution opportunities for certified organic producers in hospitality and workplace verticals.
- Direct-to-consumer channel capture:Specialty organic furniture brands are eliminating wholesale markups through owned digital channels, capturing margin pools previously allocated to retail intermediaries.
- Seagrass weaving technique convergence:Artisanal hospitality segments in boutique hotels and eco-resorts are specifying hand-woven seagrass seating systems that command premium positioning over synthetic rattan alternatives.
Industry Challenges
- Dual certification portfolio maintenance:Manufacturers serving both EU REACH and US EPA compliance regimes face duplicated testing costs and divergent documentation standards.
- Extended producer responsibility preparation:Proposed EU end-of-life recovery obligations require furniture brands to develop reverse logistics capabilities and material recovery partnerships.
- Skilled seagrass weaving labor scarcity:Traditional weaving techniques for hospitality-grade seating face generational skill transfer gaps in coastal Vietnamese and Indonesian production clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Furniture Market |
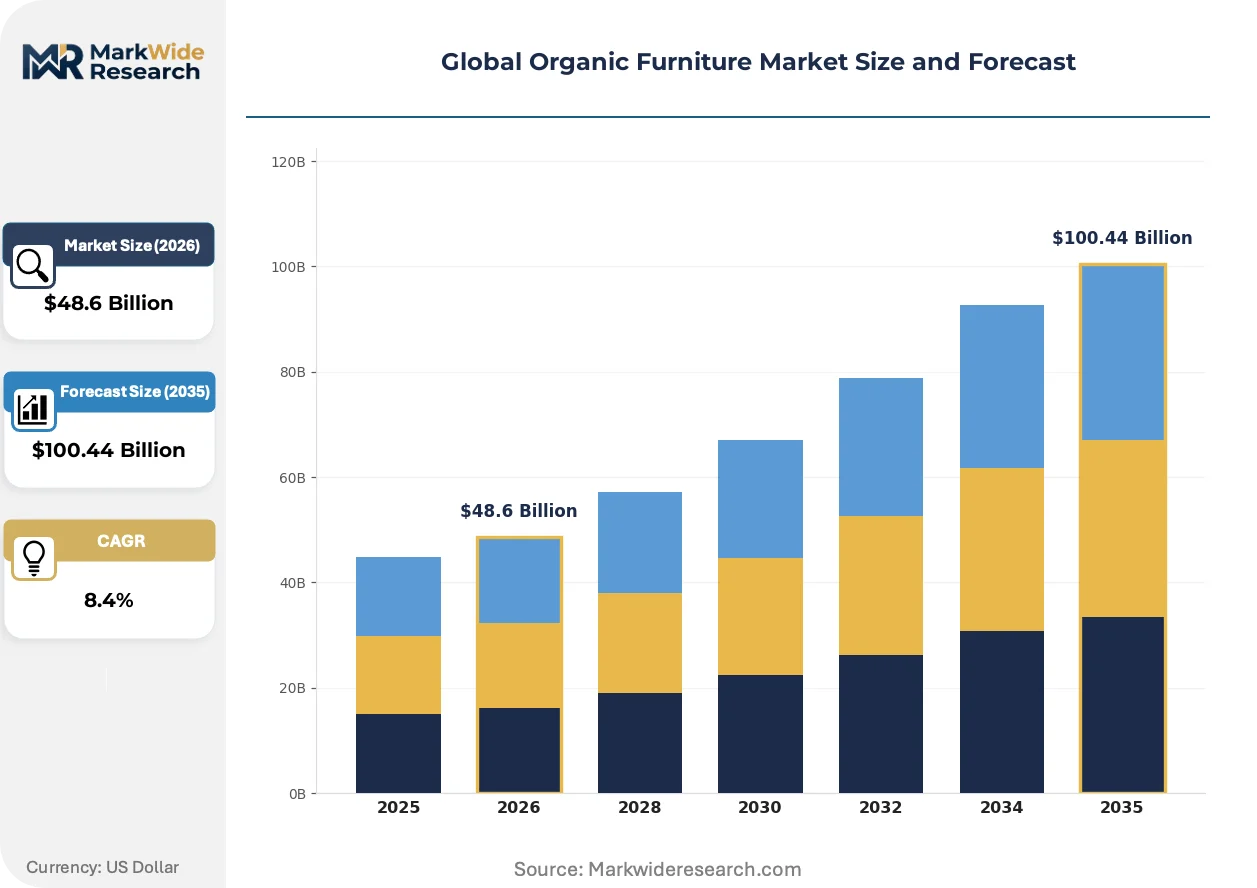
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $100.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Bamboo, Reclaimed Wood, Cork, Rattan, Seagrass Product Category: Chairs, Tables, Bed Frames, Cabinets, Sofas Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct-to-Consumer, Pop-up Shops End User: Residential Consumers, Eco-Friendly Hotels, Sustainable Cafes, Boutique Offices, Green Co-Working Spaces |
| Companies Covered | Eco Blanza, Greenington Bamboo Furniture, Inter IKEA Holding BV, Moso International B.V., Savvy Rest Inc., Shenzhen Vincent Handicraft Co. Ltd., T.Y. Fine Furniture, The Futon Shop, Vermont Woods Studios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Furniture Market Shifts & Advancements
Material traceability systems and chemical-free finishing protocols are compressing the gap between artisanal production values and industrial-scale output, reshaping how organic furniture manufacturers compete on specification and cost simultaneously.
Blockchain-enabled supply chain verification is unifying plantation origin documentation with finished-goods certification for bamboo and reclaimed timber products. Hospitality procurement teams in Germany and California are mandating this traceability layer for contract furniture bids. The technology is unifying previously fragmented compliance documentation into single-source audit trails that satisfy both ECHA REACH and corporate sustainability reporting requirements.
The EU Green Deal's circular economy action plan is mandating recycled content thresholds and end-of-life recoverability disclosures for furniture placed on the European market. Manufacturers are redesigning joinery systems to enable disassembly and material separation. Solid bamboo seating producers serving Dutch and Belgian workplace markets are responding by eliminating synthetic adhesives in favor of mechanical fastening systems.
Corporate sustainability officers are consolidating vendor relationships around certified organic suppliers capable of delivering indoor air quality documentation, material origin certificates, and carbon footprint data through single interfaces. Direct-to-consumer organic furniture brands in the United States are capturing this consolidated procurement preference by offering dedicated account management for commercial workplace and hospitality buyers. This concentration is most visible in California and New York where municipal green building codes intersect with corporate ESG reporting mandates.
Global Organic Furniture Market Segmentation
Organic furniture markets fragment across material chemistry, product architecture, and channel economics in ways that determine margin capture and compliance burden. Manufacturers must align segment-specific production capabilities with divergent certification requirements across EU REACH, US EPA, and Japanese METI jurisdictions.
Material Type:
Integration depth varies sharply: bamboo and reclaimed wood anchor standalone product lines with full supply chain control, while cork and seagrass typically embed as accent materials within multi-material systems.
- Bamboo:Engineered and solid bamboo variants dominate volume through plantation-to-finished-goods pipelines that compress chemical finishing costs. German and Dutch workplace procurement teams specify bamboo seating systems where ECHA REACH compliance documentation is mandatory for contract bids.
- Reclaimed Wood:Domestically sourced reclaimed timber commands premium positioning in US direct-to-consumer channels where Vermont Woods Studios and comparable brands leverage origin storytelling. Supply fluctuates with demolition cycles and competing construction salvage demand.
- Cork:Portuguese and Spanish cork oak harvesting supplies acoustic panels and tabletops for boutique office segments seeking sound dampening without synthetic foams.
- Rattan:Indonesian and Philippine rattan weaving serves hospitality seating where synthetic alternatives face indoor air quality scrutiny under California green building codes.
- Seagrass:Coastal Vietnamese and Indonesian hand-weaving clusters produce hospitality-grade seating for eco-resort procurement teams specifying biodegradable fiber systems over petroleum-based wicker.
Bamboo leads volumes today; seagrass is gaining share fastest among artisanal hospitality specifications.
Product Category:
Margin architecture separates sleep and storage systems with complex certification requirements from seating categories where material substitution is simpler.
- Chairs:Solid bamboo and seagrass-woven seating capture specification share in German hospitality and US co-working verticals where indoor air quality certification filters non-compliant imports. Mechanical fastening systems eliminate synthetic adhesive disclosure burdens under EU circular economy proposals.
- Tables:Reclaimed wood dining and conference surfaces anchor Vermont Woods Studios' direct-to-consumer positioning, while engineered bamboo panels from Moso International B.V. dominate Dutch workplace specification markets.
- Bed Frames:Certified organic sleep systems face dual US EPA formaldehyde testing and EU REACH chemical disclosure requirements that favor manufacturers with in-house laboratory capacity.
- Cabinets:Storage systems incorporate cork and bamboo composites where Japanese METI JIS standards for indoor air quality create import substitution opportunities for certified producers.
- Sofas:Upholstered seating with organic frame construction and natural latex cushioning serves California and New York residential markets where municipal green building codes intersect with corporate ESG procurement mandates.
Chairs and tables drive current revenue concentration; bed frames are expanding most quickly as residential buyers prioritize certified organic sleep environments.
Distribution Channel:
Channel selection determines margin retention and customer data ownership, with digital-native brands capturing wholesale-equivalent economics previously allocated to retail intermediaries.
- Online Retail:Owned digital channels enable Greenington Bamboo Furniture and comparable brands to eliminate wholesale markups while delivering ECHA REACH documentation through single interfaces for German and French commercial buyers.
- Specialty Stores:Tactile material validation remains essential for reclaimed timber and seagrass products where texture and grain variation influence purchase decisions in Tokyo and New York showrooms.
- Department Stores:Mass retail placement demands inventory scale and standardized SKUs that favor bamboo seating over artisanal seagrass lines with production batch variability.
- Direct-to-Consumer:Vermont Woods Studios anchors competitive position through channel control and domestic origin narratives that resonate with US residential buyers seeking supply chain transparency.
- Pop-up Shops:Temporary retail formats test localized demand for experimental seagrass weaving patterns and limited reclaimed timber editions before committed inventory investment.
Online retail and direct-to-consumer channels retain the highest margin pools; specialty stores maintain essential positioning for material validation-dependent categories.
End User:
Procurement sophistication separates residential buyers motivated by health certification from commercial segments where sustainability reporting mandates drive vendor consolidation.
- Residential Consumers:Bedroom and dining purchases concentrate in US and Japanese markets where indoor air quality certification is a mandatory bid criterion for premium housing developments.
- Eco-Friendly Hotels:Boutique hospitality procurement teams in Germany and California mandate blockchain-enabled supply chain verification for bamboo and reclaimed timber contract furniture bids.
- Sustainable Cafes:Small-format food service operators prioritize cost-competitive bamboo seating with rapid replacement cycles over heirloom-quality reclaimed wood systems.
- Boutique Offices:Dutch and Belgian workplace markets specify disassembly-ready joinery systems that satisfy EU Green Deal end-of-life recoverability disclosure requirements.
- Green Co-Working Spaces:California and New York operators consolidate vendor relationships around certified organic suppliers capable of delivering carbon footprint data alongside material origin certificates.
Residential consumers anchor current demand volumes; eco-friendly hotels are climbing the fastest as hospitality ESG reporting mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration follows compliance-cost gradients: Southeast Asian processors capture European specification volume by front-loading ECHA REACH certification investments, while North American brands defend margins through domestic origin narratives that satisfy municipal green building codes.
Germany
Workplace procurement teams in Berlin and Hamburg specify disassembly-ready bamboo seating systems where EU Green Deal end-of-life recoverability disclosures are mandatory for contract furniture bids. ECHA REACH chemical content thresholds filter non-compliant imports from Eastern European suppliers. The Rhine-Ruhr industrial corridor hosts specification distributors consolidating vendor relationships around certified organic producers capable of unified compliance documentation.
United States
California and New York municipal green building codes intersect with corporate ESG procurement mandates, driving residential bedroom and dining purchases toward certified organic sleep systems. EPA Toxic Substances Control Act formaldehyde emission testing creates certification bottlenecks for small-batch producers lacking in-house laboratory capacity. The Pacific Northwest and New England regions concentrate direct-to-consumer brands leveraging domestically sourced reclaimed timber origin storytelling.
Japan
METI JIS standards for indoor air quality filter non-compliant furniture imports, creating specification opportunities for certified organic producers in Tokyo and Osaka hospitality verticals. Premium housing developments mandate indoor air quality certification as a bid criterion for bedroom and dining procurement. The Kanto region anchors demand concentration as corporate sustainability officers consolidate vendor relationships around suppliers delivering carbon footprint data alongside material origin certificates.
Vietnam
Engineered bamboo panel supply for European specification markets clusters among certified processors in the Red River Delta and Mekong Delta regions. Plantation-to-finished-goods pipelines achieve cost parity with conventional timber through captive supply control and reduced chemical finishing requirements. Coastal provinces face generational skill transfer gaps in traditional seagrass weaving techniques for hospitality-grade seating systems.
Netherlands
Dutch workplace markets specify bamboo seating systems where ECHA REACH compliance documentation is mandatory for contract bids. The Randstad metropolitan region concentrates procurement teams mandating blockchain-enabled supply chain verification for bamboo and reclaimed timber furniture. Circular economy action plan recycled content thresholds drive joinery system redesigns toward mechanical fastening and material separation capabilities.
Global Organic Furniture Market Competitive Landscape
Southeast Asian producers anchor the plantation-to-finished-goods tier; North American specialists hold the direct-to-consumer premium channel. The vendor base stratifies across three tiers: integrated bamboo processors with captive supply control, domestic reclaimed timber brands with origin storytelling, and multi-material contract furniture suppliers serving hospitality specification markets. Competitive moves center on certification portfolio expansion to satisfy dual EU REACH and US EPA compliance regimes, and direct-to-consumer channel capture to eliminate wholesale markups.
Within the integrated bamboo processor tier, Greenington Bamboo Furniture and Moso International B.V. exemplify archetypes of vertical supply control and engineered panel specification dominance respectively. Vermont Woods Studios occupies a position representing domestic reclaimed timber origin narratives in North American direct-to-consumer channels. These three entities anchor competitive positioning patterns without exhausting the market's structural diversity.
| Leading Market Players |
|---|
| Eco Blanza |
| Greenington Bamboo Furniture |
| Inter IKEA Holding BV |
| Moso International B.V. |
| Savvy Rest Inc. |
| Shenzhen Vincent Handicraft Co. Ltd. |
| T.Y. Fine Furniture |
| The Futon Shop |
| Vermont Woods Studios |
| Others |
Supply & Pricing Matrix
EU Green Deal end-of-life recoverability mandates gate both qualified supply and premium-tier pricing access, compressing margins for non-compliant producers while rewarding certified organic suppliers with pricing power in German and Dutch workplace procurement channels.
Pricing Analysis
Direct-to-consumer channel margins eliminate wholesale markups of 40-60% that specialty stores command, enabling Greenington Bamboo Furniture and Vermont Woods Studios to capture premium positioning through owned digital platforms. Price differentiation hinges on certification grade—ECHA REACH and US EPA compliance tiers—and volume scale for contract hospitality bids. Cost compression in small-batch artisanal tiers intensifies as laboratory testing burdens accumulate under divergent regulatory regimes. Sustainable cafes and budget hospitality operators exhibit highest price sensitivity, while eco-friendly hotels and corporate workplace buyers prioritize documented compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor European specification fulfillment for engineered bamboo panels, with hub-and-spoke patterns radiating toward workplace procurement clusters in the Randstad and Rhine-Ruhr corridors. Manufacturing concentrates in Vietnam, Indonesia, and Portugal—drawing from plantation bamboo, coastal seagrass harvesting, and cork oak forestry respectively. Raw material dependencies rest on synthetic adhesive substitutes, mechanical fastening hardware, and chemical-free finishing compounds. Single-source vulnerability pervades certified seagrass weaving capacity in Vietnamese coastal provinces. Distribution runs through specification distributors consolidating compliance documentation for ECHA REACH and corporate sustainability reporting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in captive supply control and direct-to-consumer channel capture, as plantation-to-finished-goods pipelines compress chemical finishing costs and eliminate wholesale markups.
For Market Incumbents: Extend certification portfolio coverage to dual EU REACH and US EPA compliance regimes before extended producer responsibility mandates impose reverse logistics obligations. Invest in in-house laboratory capacity to eliminate testing bottlenecks that artisanal competitors cannot match. Deepen backward integration into plantation bamboo supply to defend cost position against emerging Southeast Asian processors. For New Entrants and Emerging Players: Boutique hospitality procurement teams in California and Germany represent the most penetrable white-space target, as ESG reporting mandates tighten faster than incumbent response capacity. Seagrass weaving cooperatives in Indonesian coastal clusters offer acquisition-ready artisanal production networks absent from consolidated vendor lists. Pursue direct-to-OEM supply relationships that bypass specification distributor markups for eco-resort development projects. For Investors and Strategic Acquirers: Roll-up economics work for domestic reclaimed timber brands because supply fragmentation across demolition salvage markets prevents organic scale growth without acquisition. Five-to-ten year viability hinges on regulatory harmonization momentum across EU, US, and Japanese chemical disclosure regimes. Monitor EU extended producer responsibility legislative progression as the decisive inflection signal for reverse logistics capability valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | Dual EU REACH and US EPA compliance unlocks German and California workplace specification channels. |
| Direct-to-Consumer Channel Launch | Owned digital platforms eliminate wholesale markups and capture customer data for repeat purchase. |
| Backward Integration into Plantation Supply | Captive bamboo supply compresses chemical finishing costs and secures ECHA REACH origin documentation. |
| Mechanical Fastening System Redesign | Eliminates synthetic adhesive disclosure burdens under EU circular economy end-of-life mandates. |
| Blockchain Traceability Implementation | Unifies plantation documentation with finished-goods certification for hospitality procurement bids. |
Research Methodology
Bottom-up residential and hospitality procurement modeling reconciled against top-down plantation supply and import tracking forms the analytical core of this study. Primary interviews with sustainability procurement officers, furniture specification distributors, bamboo plantation managers, and chemical compliance consultants informed demand-side assumptions. Secondary validation drew from ECHA REACH registration databases, US EPA Toxic Substances Control Act compliance filings, Japanese METI JIS standard publications, and customs trade records for bamboo and reclaimed timber imports. Triangulation across these sources reconciled volume estimates with certification penetration rates.
Input-output matrices mapped material flow from plantation harvesting through finished-goods distribution across the analysis window, with segmentation dimensions spanning material chemistry, product architecture, channel economics, and end-user procurement sophistication. CAGRs were derived from regression analysis of historical certification adoption curves and regulatory enforcement intensity indices. Industry-specific forecast inputs included EU Green Deal implementation timelines and Japanese METI indoor air quality standard revision patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization failures and generational skill transfer gaps in traditional weaving techniques. Outputs reflect documented assumptions around certification cost trajectories and procurement mandate adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
UK Sustainable Office Furniture Market
Furniture
Exam Tables Market
Furniture
Global Furniture Fittings Market
Furniture
Rattan Furniture Market
Furniture
Entryway Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Japan Home Furniture Market
Furniture
India Furniture Market
Furniture
Unfinished Wood Furniture Market
Furniture
GCC Luxury Furniture Market
Furniture
US School Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Portering Chair Market
Furniture
Europe Multifunctional Furniture Market
Furniture
Europe Upholstered Furniture Market