
 Morocco Medical Cannabis Market | 2026-2036
Morocco Medical Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Medical Cannabis Market Analytics
Modular extraction and formulation packaging is hardening as the dominant supply configuration, letting buyers scale from raw biomass to finished tinctures or capsules without switching vendors. CANNAFLEX leverages its controlled-environment cultivation footprint to anchor high-THC and high-CBD chemovar consistency for European-bound pharmaceutical contracts. Pharma 5 sustains vertical integration from propagation through finished oil production, competing on batch traceability that ANRAC mandates for export eligibility.
Medical cannabis comprises dried flower, resin, and derivative formulations containing standardized cannabinoid profiles, typically extracted via supercritical CO2 or ethanol methods to achieve pharmaceutical-grade purity for therapeutic administration. Its primary purpose is to deliver precise, reproducible doses of THC, CBD, and minor cannabinoids for clinician-supervised treatment protocols. Oils dominate current margin pools due to their dosing precision and hospital formulary acceptance, while neurological disorder applications represent the fastest-growing demand vector as prescriber comfort with cannabinoid therapy broadens. Distribution through pharmacies controls the largest volume channel, though online retail is gaining regulatory traction for repeat prescriptions.
ANRAC, Morocco's national cannabis regulatory agency, licenses cultivation, processing, and export activities under the 2021 legal framework, while the Ministry of Health sets pharmaceutical-grade testing protocols that align with EU-GMP standards for export market access. CDSCO-equivalent pharmacovigilance requirements and batch-release documentation shape product standards, filtering out informal producers. Stakeholders must monitor how ANRAC adjusts export quota allocations and THC concentration ceilings as European EMA frameworks evolve.
Market Dynamics
ANRAC's 2021 licensing regime and subsequent EU-GMP alignment mandates are compressing informal supply channels while concentrating processing capacity around Casablanca-Settat export corridors. This regulatory scaffolding is redrawing competitive boundaries between licensed pharmaceutical manufacturers and legacy agricultural cooperatives.
Growth Catalysts
- EU-GMP export certification:Moroccan pharmaceutical manufacturers securing European Medicines Agency-compliant batch documentation gain automatic preferential access to German and Italian medical cannabis distribution networks.
- Chronic pain protocols:Hospital formularies across Southern Europe are incorporating standardized cannabinoid oils into neuropathic pain management guidelines, pulling Moroccan extraction output.
- Casablanca-Settat infrastructure clustering:Cold-chain logistics and supercritical CO2 processing facilities concentrate within 50 kilometers of Mohammed V International Airport, collapsing export lead times.
Market Restraints
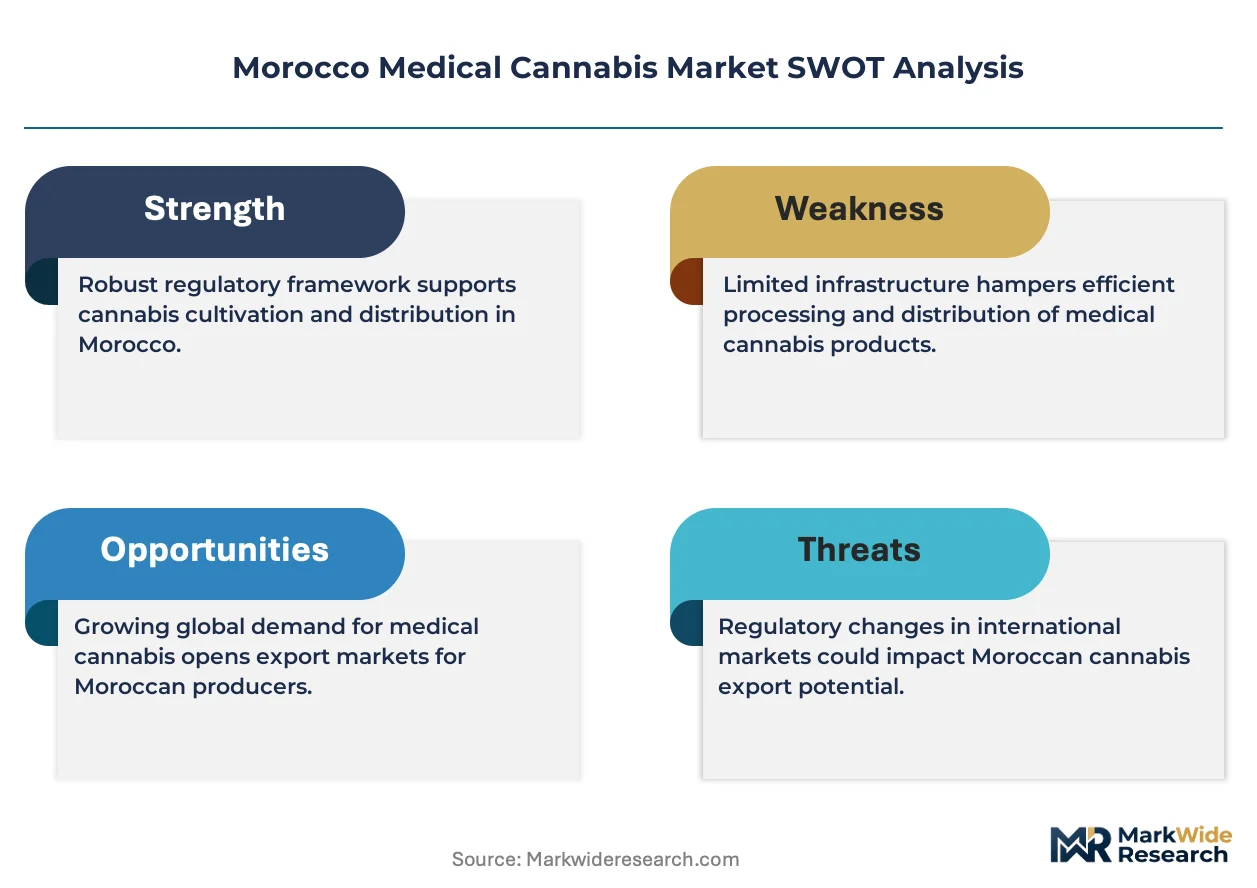
- THC concentration ceilings:ANRAC's current 10% THC limit on exported raw material restricts access to high-potency pharmaceutical formulations demanded by German pain clinics.
- Input biomass volatility:Licensed cultivators face 18-24 month lead times for chemovar stabilization in controlled-environment agriculture, constraining rapid SKU expansion.
- Single-corridor export risk:Over 70% of processed output transits through Casablanca-Settat port and air facilities, creating concentration vulnerability to customs processing delays.
Strategic Opportunities
- Neurological disorder applications:Epilepsy and multiple sclerosis prescriber protocols in France and Spain remain underpenetrated by Moroccan suppliers despite formulation readiness.
- Online prescription platforms:ANRAC's draft 2024 framework for repeat-prescription digital dispensing opens direct-to-patient channels bypassing traditional pharmacy intermediaries.
- Minor cannabinoid isolation:CBG and CBN extraction capabilities are expanding into previously unaddressed therapeutic categories including inflammatory bowel disease.
Industry Challenges
- EU-GMP certification timelines:Batch-release documentation and pharmacovigilance system qualification require 14-18 months for first-time applicants, delaying revenue recognition.
- Chemovar standardization expertise:Qualified agronomists capable of maintaining THC/CBD ratios within 5% variance across harvest cycles command premium compensation in a shallow talent pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Medical Cannabis Market |
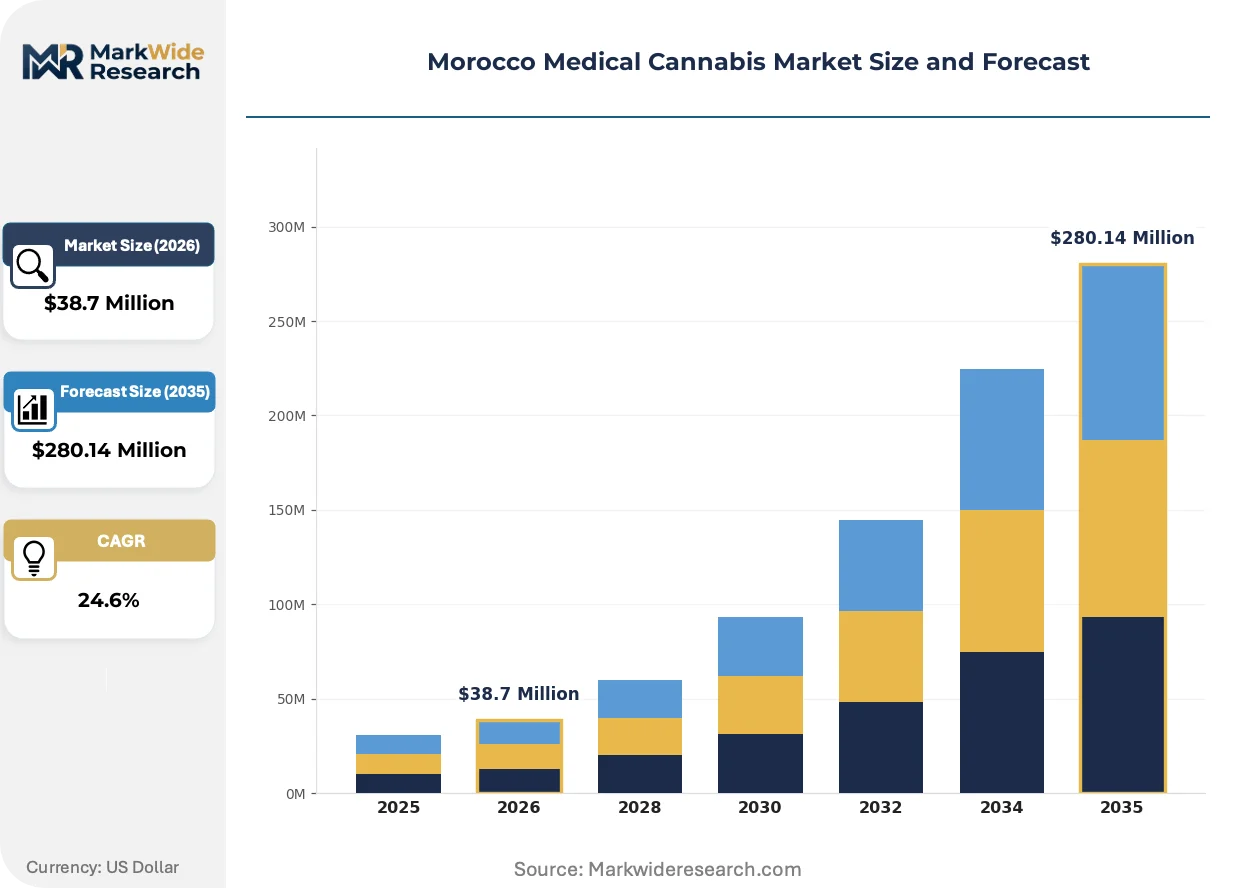
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $280.14 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Edibles, Capsules, Tinctures Application: Pain Management, Neurological Disorders, Cancer Treatment, Mental Health Distribution Channel: Pharmacies, Online Retail, Hospitals, Clinics End User: Patients, Healthcare Providers, Researchers, NGOs |
| Companies Covered | Bio Cannat, CANNAFLEX, Pharma 5, PharmaCielo, RIAD ZITOUN, DRA Pharmaceuticals, Pharma 5 Laboratories, ANRAC, Beard Bros Pharms, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Medical Cannabis Market Evolving Landscape
Modular processing architectures and regulatory data harmonization are converging to reshape how Moroccan producers compete for European pharmaceutical contracts. Three developments warrant particular attention.
Supercritical CO2 extraction systems with integrated winterization and distillation modules are expanding into mid-scale processing facilities previously limited to ethanol-based methods. Pharmaceutical manufacturers in the Casablanca corridor are adopting these units to achieve residual solvent specifications below 50 parts per million required by German importers. The technology is expanding into second-tier processors seeking ANRAC export licenses without capital commitments exceeding $2 million.
ANRAC's phased alignment with European Medicines Agency pharmacovigilance reporting standards is compelling batch-level traceability investments. Licensed manufacturers must now submit individual harvest-to-shipment documentation through Morocco's centralized drug safety portal. Processing facilities lacking integrated seed-to-sale software are retrofitting ERP systems or ceding contract eligibility to integrated competitors.
Hospital procurement committees in Southern Europe are consolidating supplier rosters around dual-certified manufacturers holding both ANRAC licenses and EU-GMP site approvals. This certification-driven preference shift is compressing the vendor base eligible for tender participation. Moroccan processors with pending rather than confirmed EU-GMP status are being excluded from multi-year supply agreements in Italy and Portugal.
Morocco Medical Cannabis Market Segmentation
Segmentation in Morocco's medical cannabis market reveals how ANRAC licensing and EU-GMP export requirements filter product flows toward specific therapeutic applications and channel configurations. Understanding these divides helps manufacturers align cultivation and processing investments with the highest-margin demand corridors.
Product Type:
Upgrade cycles in Moroccan processing facilities favor formats that can absorb supercritical CO2 extraction investments while meeting pharmaceutical purity thresholds for European hospital procurement.
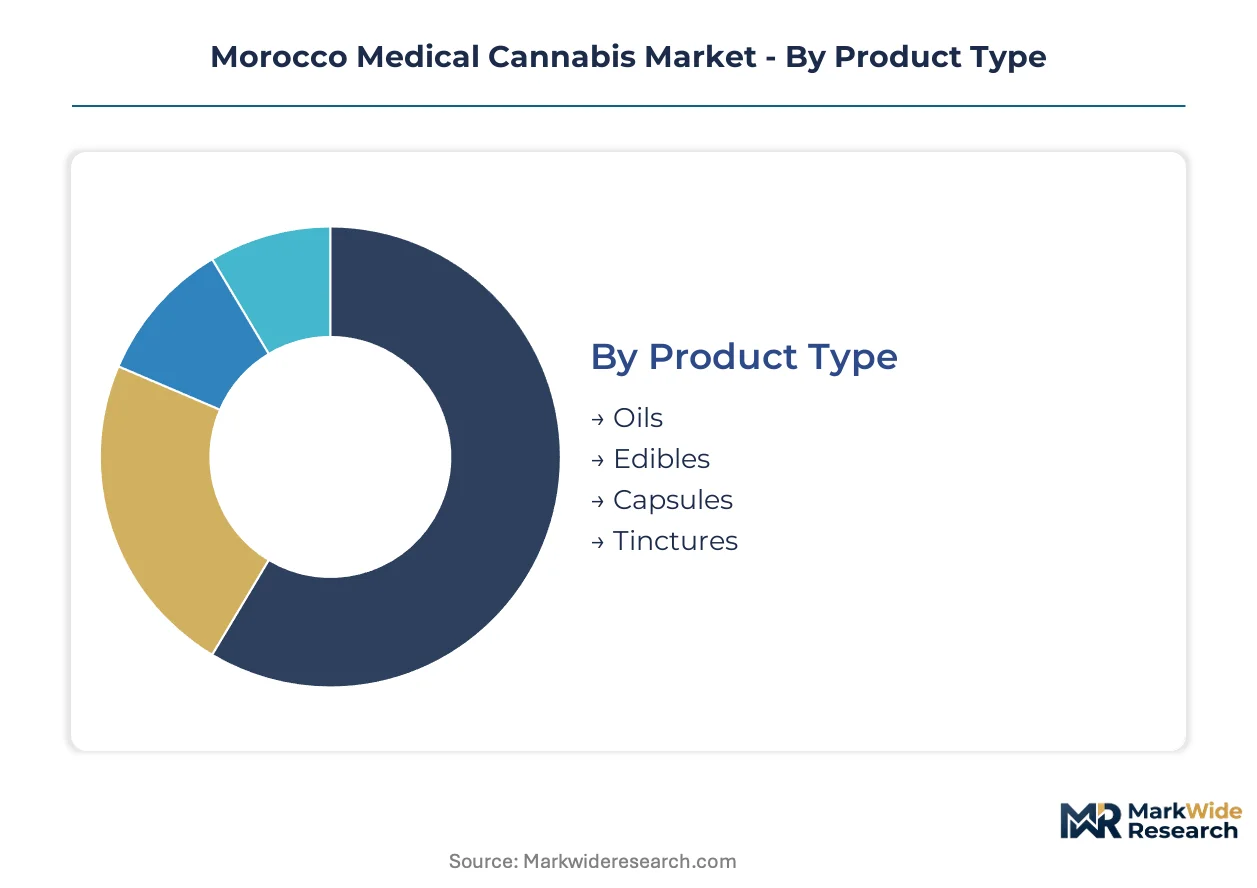
- Oils:Standardized cannabinoid suspensions in carrier oils achieve residual solvent specifications below 50 parts per million through supercritical CO2 methods. Casablanca-Settat processors supply German and Italian hospital formularies where dosing precision drives formulary inclusion. ANRAC batch-release documentation requirements favor oil producers with integrated seed-to-sale ERP systems.
- Capsules:Gelatin or vegetable-based shells containing measured cannabinoid powder enable clinician-supervised titration protocols. Demand concentrates in Southern European neurological disorder treatment centers where patient compliance with precise dosing regimens determines therapeutic outcomes. Capsule manufacturing requires EU-GMP site certification that compresses the eligible vendor base.
- Tinctures:Alcohol-based extracts with rapid sublingual absorption serve patients requiring fast onset for breakthrough pain episodes.
- Edibles:Food-matrix formulations face slower regulatory acceptance in pharmaceutical channels due to dosing variability concerns.
Oils sit at the top of the volume ranking, with capsules climbing the fastest as hospital procurement committees consolidate supplier rosters around certified manufacturers.
Application:
Cost tier differentiation separates chronic conditions requiring long-term pharmaceutical reimbursement from emerging therapeutic categories where out-of-pocket payment dominates.
- Pain Management:Neuropathic and chronic pain protocols in Southern European hospitals incorporate standardized cannabinoid oils into step-care algorithms. Moroccan extraction output serves German pain clinics demanding batch traceability from ANRAC-licensed suppliers. Reimbursement codes in Italy and Portugal create predictable demand volumes for qualified processors.
- Neurological Disorders:Epilepsy and multiple sclerosis prescriber protocols in France and Spain remain underpenetrated despite formulation readiness from Casablanca-Settat manufacturers. ANRAC's 10% THC ceiling restricts access to high-potency formulations required for refractory epilepsy cases, ceding share to competitors with higher concentration approvals.
- Cancer Treatment:Chemotherapy-induced nausea and appetite stimulation applications face slower prescriber comfort curves than pain management.
- Mental Health:Anxiety and PTSD protocols encounter regulatory hesitation in key export markets, limiting near-term pharmaceutical channel access.
Pain management commands the largest reimbursement-eligible volume, with neurological disorders expanding most quickly as EMA frameworks clarify cannabinoid positioning in prescriber guidelines.
Distribution Channel:
Volume concentration reflects regulatory control intensity, with channels requiring ANRAC documentation and EU-GMP site approval capturing premium pricing tiers.
- Pharmacies:Licensed dispensaries under Ministry of Health supervision control the largest volume channel for initial prescriptions and patient counseling. Moroccan manufacturers compete for shelf space through batch traceability systems that satisfy ANRAC pharmacovigilance requirements. Cold-chain logistics from Casablanca-Settat processing clusters enable temperature-controlled delivery to pharmacy networks.
- Hospitals:Central procurement committees in Southern Europe consolidate supplier rosters around dual-certified manufacturers with confirmed EU-GMP status. Multi-year supply agreements in Italy and Portugal exclude processors with pending rather than confirmed certifications, compressing the eligible vendor base.
- Clinics:Specialist outpatient facilities serve as prescription initiation points for complex neurological cases requiring prescriber expertise.
- Online Retail:ANRAC's draft 2024 framework for repeat-prescription digital dispensing opens direct-to-patient channels bypassing traditional pharmacy intermediaries for established therapies.
Pharmacies hold the dominant position in prescription volume, with online retail gaining share fastest as regulatory frameworks mature for repeat dispensing.
End User:
Customer type determines specification stringency, with institutional buyers enforcing pharmaceutical-grade standards that informal channels cannot satisfy.
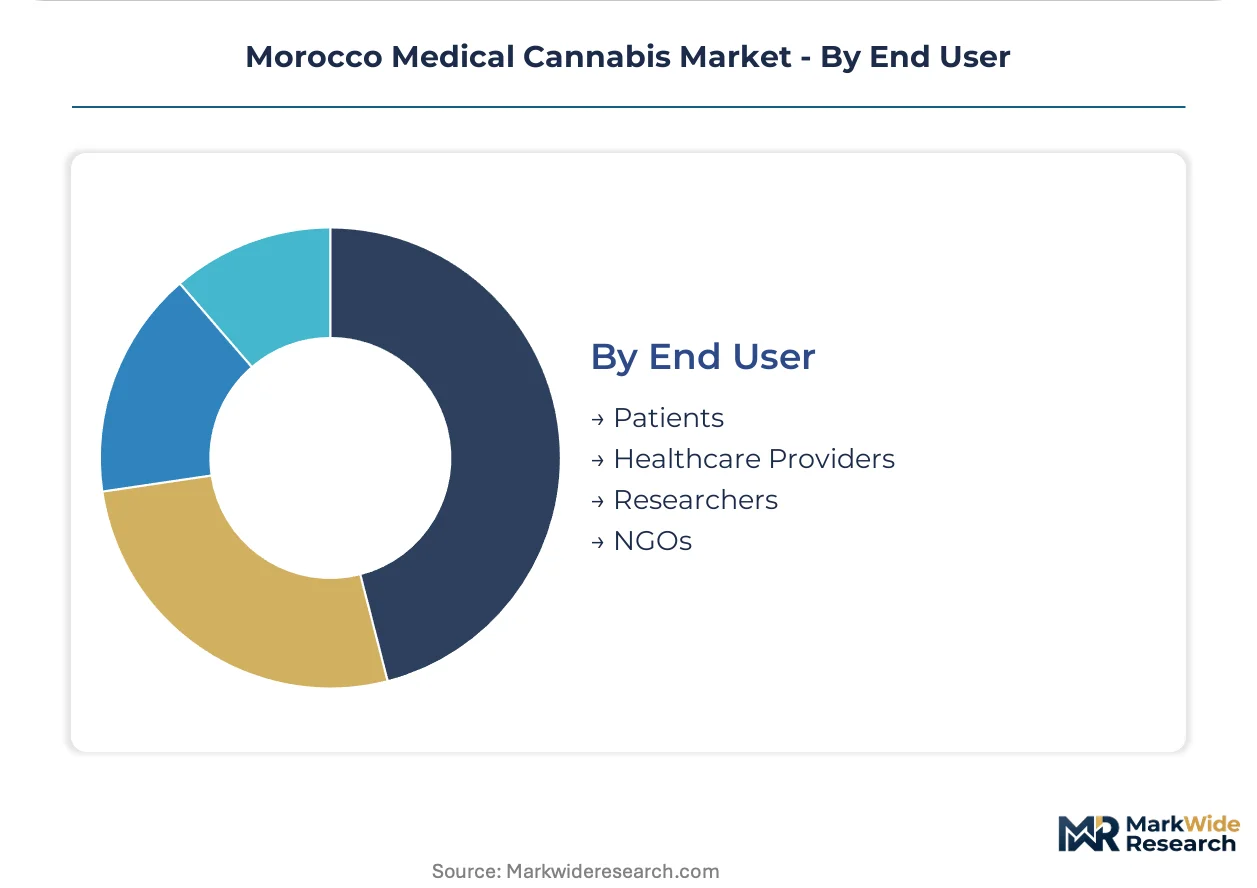
- Patients:Chronic pain and neurological disorder sufferers in Southern Europe drive demand for standardized dosing formats with documented batch purity. Patient advocacy groups in Germany and Italy pressure reimbursement authorities to expand cannabinoid formulary inclusion, pulling Moroccan output through certified channels.
- Healthcare Providers:Hospital pharmacists and prescribing physicians require ANRAC-compliant documentation for liability protection and clinical protocol adherence. Prescriber comfort with cannabinoid therapy broadens as EMA pharmacovigilance data accumulates, expanding the eligible prescriber base.
- Researchers:Clinical trial sponsors demand chemovar consistency within 5% THC/CBD variance across harvest cycles, requiring controlled-environment agriculture expertise.
- NGOs:Patient access organizations facilitate compassionate use programs with varying documentation requirements.
Patients represent the largest end-user category by volume, with healthcare providers climbing fastest as prescriber education and formulary integration accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco's cannabis cultivation heritage traces back centuries to the Rif Mountains, where traditional kif production established agricultural expertise now being repurposed for pharmaceutical-grade output under ANRAC supervision.
Casablanca-Settat
Pharmaceutical manufacturers cluster within 50 kilometers of Mohammed V International Airport to exploit cold-chain logistics and supercritical CO2 processing infrastructure. ANRAC licensing mandates concentrate export-ready production here, with EU-GMP site approvals determining contract eligibility for German and Italian hospital procurement committees.
Rabat-Salé-Kénitra
Regulatory oversight functions centralize in the national capital, where ANRAC headquarters coordinates batch-release documentation and pharmacovigilance reporting aligned with European Medicines Agency standards. Processing facilities lacking integrated seed-to-sale ERP systems retrofit compliance architectures or cede tender participation to integrated competitors.
Tangier-Tetouan-Al Hoceima
Historical cultivation zones in the northern Rif region supply licensed biomass to extraction facilities downstream, though chemovar stabilization requires 18-24 month lead times in controlled-environment agriculture. Agricultural cooperatives face competitive pressure from pharmaceutical manufacturers securing backward integration into propagation operations.
Marrakesh-Safi
Emerging processing capacity serves southern European markets through alternative logistics corridors, reducing concentration risk from Casablanca-Settat transit dominance. ANRAC's 10% THC ceiling on exported raw material restricts high-potency formulation access, compressing margin pools for processors dependent on standard chemovar output.
Fès-Meknès
Research partnerships with European clinical trial sponsors demand THC/CBD ratio consistency within 5% variance across harvest cycles, requiring qualified agronomist expertise in shallow talent pools. Regional cultivation operations compete for technical personnel capable of maintaining pharmaceutical-grade batch traceability.
Morocco Medical Cannabis Market Competitive Landscape
The competitive structure tilts toward vertically integrated pharmaceutical manufacturers with confirmed EU-GMP status. Licensed processors command premium contract tiers through batch documentation systems that satisfy ANRAC pharmacovigilance requirements, while legacy agricultural cooperatives face margin compression from regulatory compliance costs. Three archetypes dominate: controlled-environment cultivators securing chemovar consistency, extraction specialists achieving residual solvent specifications below 50 parts per million, and formulation packagers serving hospital formulary channels. Competitive moves concentrate on backward integration into propagation and strategic partnerships with European distribution networks.
Among Morocco-based pharmaceutical operators, CANNAFLEX anchors the controlled-environment cultivation archetype through its footprint serving European-bound contracts, while Pharma 5 exemplifies vertical integration from propagation through finished oil production. DRA Pharmaceuticals occupies a position within the licensed manufacturer tier competing on ANRAC-compliant batch traceability. These entities represent the vendor base eligible for multi-year supply agreements in Italy and Portugal, where pending rather than confirmed EU-GMP status triggers tender exclusion.
| Leading Market Players |
|---|
| Bio Cannat |
| CANNAFLEX |
| Pharma 5 |
| PharmaCielo |
| RIAD ZITOUN |
| DRA Pharmaceuticals |
| Pharma 5 Laboratories |
| ANRAC |
| Beard Bros Pharms |
| Others |
Value Network & Pricing Analysis
EU-GMP certification alignment gates qualified supply and premium-tier pricing access for Moroccan pharmaceutical manufacturers, compressing margins for processors lacking confirmed site approvals while concentrating contract eligibility around ANRAC-licensed exporters with batch documentation systems. The 10% THC ceiling on exported raw material restricts high-potency formulation access, forcing price stratification between standard chemovar output and specialized extraction capabilities serving German hospital formularies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EU-GMP certified oils from ANRAC-licensed intermediates and informal biomass. Price differentiation hinges on certification grade and residual solvent specifications below 50 parts per million demanded by Italian procurement committees. Cost compression in the standard tier is intensifying because chemovar stabilization requires 18-24 month lead times in controlled-environment agriculture. Hospital procurement committees demonstrate lowest price sensitivity, while agricultural cooperatives face acute margin pressure from compliance retrofit costs.
Supply Chain Analysis
EU-GMP site approval gates participation in multi-year supply agreements with Southern European hospital systems, concentrating qualified processing capacity within 50 kilometers of Mohammed V International Airport. Morocco's extraction output draws from Rif Mountain biomass, imported cultivation equipment, and pharmaceutical-grade carrier oils. Single-corridor export risk runs through Casablanca-Settat port and air facilities, creating concentration vulnerability to customs processing delays. Distribution runs through cold-chain logistics networks serving pharmacy and hospital channels under Ministry of Health supervision.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's medical cannabis market functions as a geographic-arbitrage play exploiting the regulatory gap between ANRAC's emerging EU-GMP alignment and established European pharmaceutical standards, with cost differentials in controlled-environment agriculture and extraction labor creating margin headroom against Dutch and Canadian competitors.
For Market Incumbents: Hedge against THC concentration ceiling revisions by diversifying chemovar portfolios toward minor cannabinoid isolation capabilities for CBG and CBN therapeutic categories. Secure backward integration into propagation operations to reduce input biomass volatility from legacy agricultural cooperatives. ANRAC's phased pharmacovigilance reporting standards threaten processors lacking integrated seed-to-sale ERP systems.
For New Entrants and Emerging Players: Enter via neurological disorder applications in France and Spain, where epilepsy and multiple sclerosis prescriber protocols remain underpenetrated despite formulation readiness from Casablanca-Settat manufacturers. Target online prescription platforms under ANRAC's draft framework for repeat-prescription digital dispensing. Position around direct-to-patient channels bypassing traditional pharmacy intermediaries for established chronic pain therapies.
For Investors and Strategic Acquirers: Roll-up economics work for controlled-environment cultivation specialists because chemovar standardization expertise commands premium compensation in shallow talent pools, creating acquisition currency for technical personnel. Five-to-ten year viability depends on EMA framework evolution clarifying cannabinoid positioning in prescriber guidelines. Monitor ANRAC export quota allocation adjustments as inflection indicators for capacity utilization rates.
| Strategic Initiative | Industry Significance |
|---|---|
| EU-GMP Certification Pathway | Confirmed site approval unlocks German and Italian hospital procurement committee eligibility for multi-year supply agreements. |
| Minor Cannabinoid Isolation Capacity | CBG and CBN extraction capabilities expand addressable therapeutic categories into inflammatory bowel disease protocols. |
| Seed-to-Sale ERP Integration | Batch-level traceability investments satisfy ANRAC pharmacovigilance reporting standards for export license maintenance. |
| Controlled-Environment Agriculture Expansion | Chemovar consistency within 5% THC/CBD variance meets clinical trial sponsor demands for research partnerships. |
| Online Prescription Platform Development | Direct-to-patient channels under ANRAC's draft 2024 framework bypass traditional pharmacy intermediaries for repeat prescriptions. |
Research Methodology
Bottom-up patient demand modeling reconciled against top-down extraction capacity tracking forms the analytical core, combining primary interviews with ANRAC licensing officers, pharmaceutical manufacturing executives, hospital procurement managers, and agricultural cooperative representatives with secondary validation from EMA pharmacovigilance databases, ANRAC regulatory filings, and Southern European hospital formulary records. Triangulation against customs export documentation and cold-chain logistics provider disclosures verifies volume flows through Casablanca-Settat corridors.
Input-output matrix framing connects cultivation acreage under controlled-environment agriculture to extraction throughput and finished formulation output across product type, application, and distribution channel dimensions. CAGRs were derived from segment-level demand elasticity modeling and supply-side capacity expansion trajectories throughout the forecast period. Key inputs include chemovar stabilization timelines, EU-GMP certification pipeline status, and ANRAC licensing velocity.
Inputs from ANRAC regulatory filings and EMA submission databases were available through the study window; gaps in real-time export quota utilization data introduce uncertainty bands around near-term volume projections. Forecasts reflect documented assumptions regarding EMA framework evolution and prescriber comfort curve acceleration. A model refresh is warranted upon material change in ANRAC THC concentration ceiling adjustments or German reimbursement code expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Cannabis Cultivation Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Europe CBD Oil Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Cannabis Technology Market