
 Nuts and Nut Products Market | 2026-2036
Nuts and Nut Products Market Size, Share, and Industry Trends Forecast 2026-2036
Nuts and Nut Products Market Insights
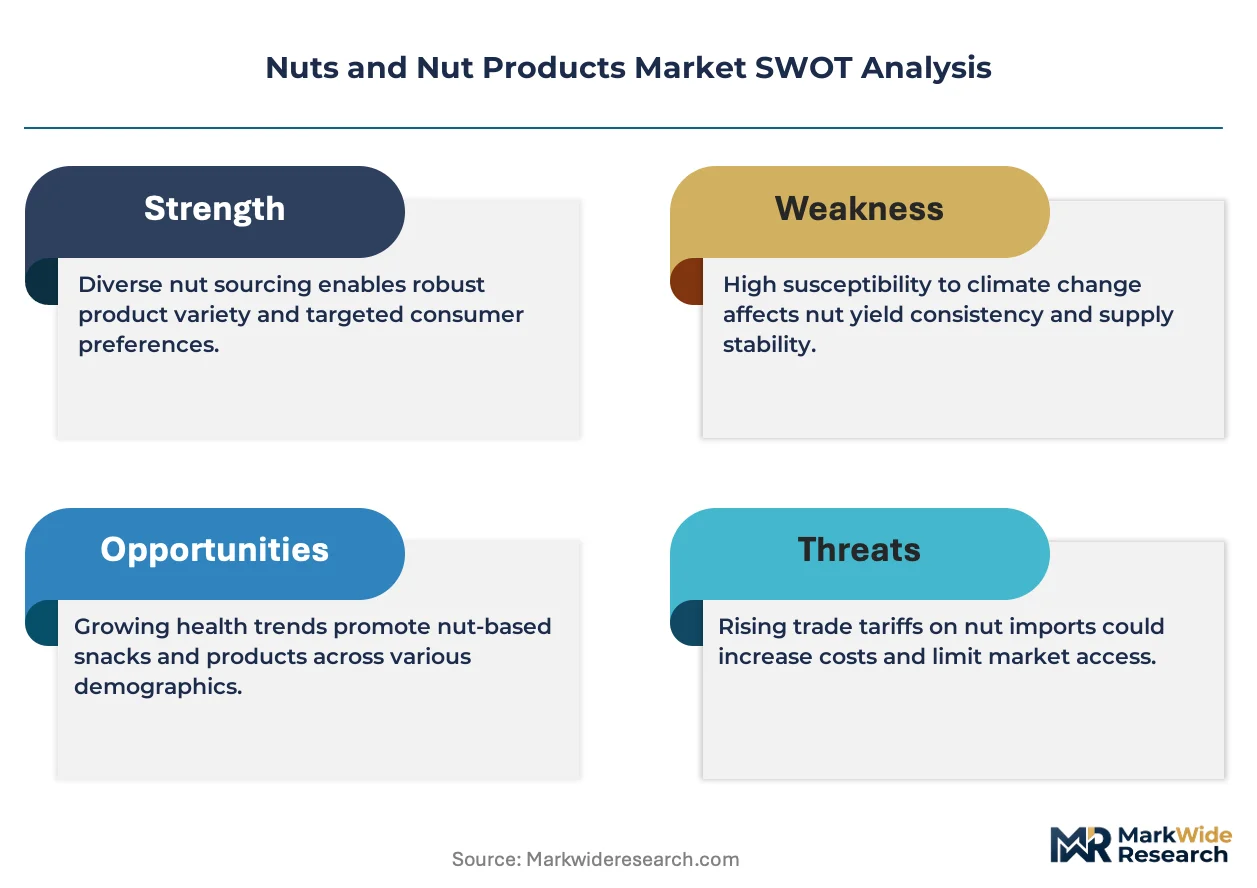
REACH compliance is pivoting the cost-of-entry calculus for European nut importers, forcing reformulation of processing aids and packaging substrates. Olam Group leverages its integrated supply chain from orchards to retail to sustain margin control across volatile commodity cycles. Blue Diamond Growers anchors its competitive position through deep specialization in almond cultivation and value-added product innovation. Mariani Nut Company differentiates via precision roasting technology and regional brand strength in North American premium channels.
Nuts and nut products encompass shelled and processed tree nuts and legumes, typically containing 45-75% lipid content by weight, delivered raw, roasted, or as butters, flours, and dairy alternatives for food manufacturing and direct consumption. Almonds dominate volume trade due to mechanized harvesting scale and versatile ingredient functionality across bakery and beverage applications. Organic grade commands premium positioning as clean-label procurement tightens specifications in European and North American retail. Bulk packaging retains cost leadership in industrial channels, while single-serve bags capture snacking occasions in convenience retail.
FDA food safety standards, USDA organic certification, and EU Green Deal sustainability frameworks collectively shape product specifications, import documentation burdens, and carbon accounting disclosures across major trade corridors. BIS quality mandates in India and EFSA contaminant thresholds in Europe further fragment compliance requirements for multinational suppliers. Stakeholders must monitor divergence between regional sustainability metrics and traceability technology investments to preserve market access without eroding operational returns.
Market Dynamics
EU Green Deal carbon-accounting mandates are restructuring procurement specifications across European retail channels, forcing suppliers to retrofit orchards and processing facilities with traceability infrastructure that captures embedded emissions from cultivation through packaging.
Growth Catalysts
- Plant-based protein substitution:Food manufacturers reformulate bakery and beverage lines with almond and cashew bases to capture flexitarian household spending.
- REACH compliance upgrading:European processors investing in solvent-free extraction and biodegradable packaging substrates to maintain supermarket listings.
- India household income expansion:Urban middle-class consumption of premium shelled almonds accelerates as organized retail penetration deepens in tier-two cities.
Market Restraints
- Water input cost volatility:Almond cultivation in California's Central Valley faces irrigation allocation cuts and groundwater pumping restrictions.
- Single-origin supply concentration:Cashew shelling capacity clusters in Vietnam and India, exposing buyers to monsoon disruption and labor availability swings.
- Aflatoxin technical limitation:Pre-shipment testing protocols cannot eliminate border rejection risk for raw peanut shipments to EU ports.
Strategic Opportunities
- Brazil nut geographic underpenetration:Amazon-sourced supply chains remain undeveloped for European organic snack channels.
- Precision roasting technology convergence:IoT-enabled thermal profiling and AI-driven moisture detection enable batch consistency for private-label contracts.
- USDA organic certification tailwind:Clean-label mandates from North American supermarket chains expand price premiums for certified handlers.
Industry Challenges
- Specialized equipment operator scarcity:Automated harvesting and optical sorting systems require technicians trained on proprietary software interfaces.
- Organic certification timeline compression:Three-year land conversion periods and documentation audits delay revenue recognition for transitioning growers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuts and Nut Products Market |
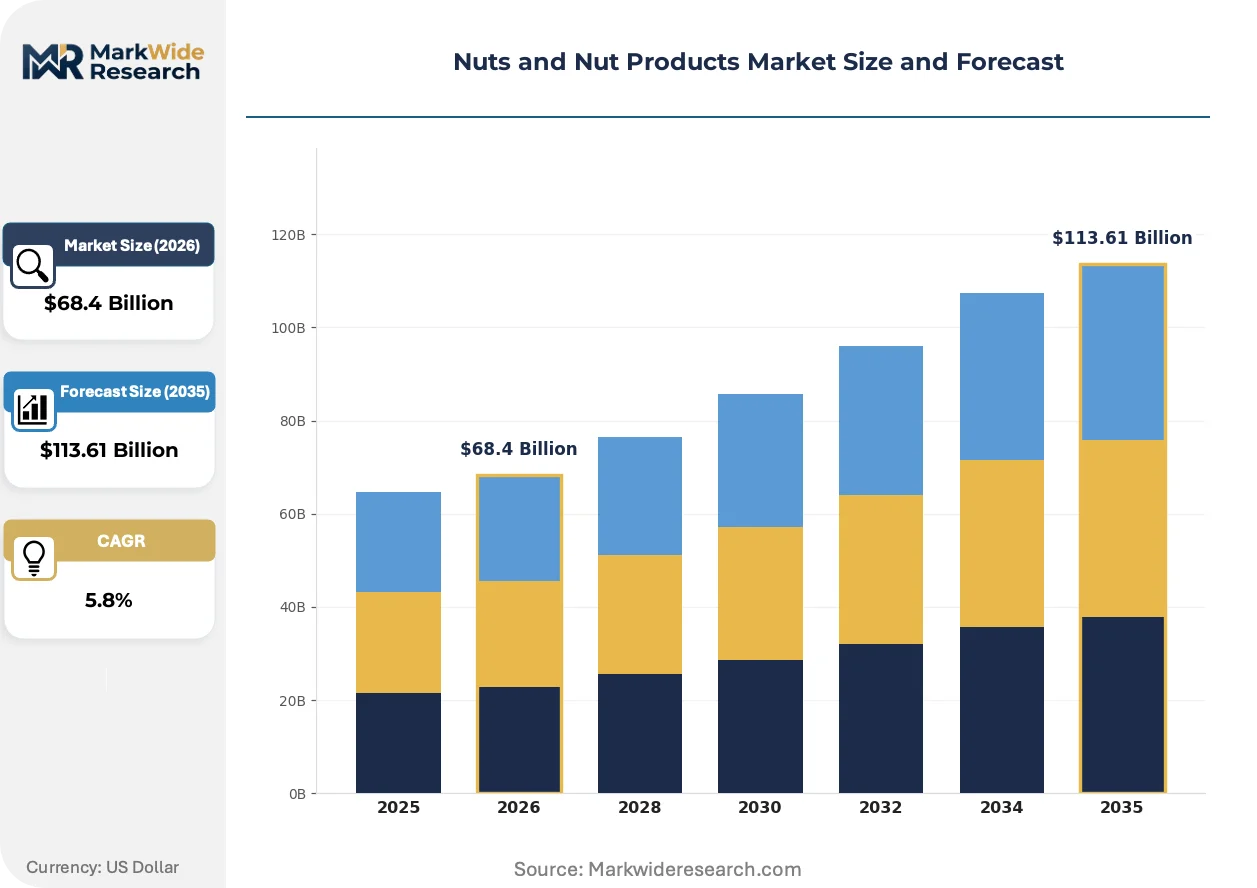
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almonds, Walnuts, Cashews, Pecans Grade: Organic, Non-Organic, Premium, Standard Packaging Type: Bags, Jars, Cans, Bulk Application: Snacking, Baking, Cooking, Confectionery |
| Companies Covered | Blue Diamond Growers, Olam Group, John B. Sanfilippo & Son, Hormel Foods, Barry Callebaut, The Wonderful Company, Archer Daniels Midland Company, Mariani Nut Company, Kraft Heinz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuts and Nut Products Market Trends and Innovations
Processing technology and regulatory disclosure requirements are converging to compress batch sizes and accelerate product development cycles across tree nut and legume categories.
Hyperspectral sorting technology is modularizing quality control workflows at receiving stations and roasting facilities. Mid-sized processors in Spain and Australia deploy portable units to segregate incoming loads by defect density and moisture content. Equipment modularity allows facilities to reconfigure lines between raw bulk output and value-added seasoned products without dedicated capital installations.
EU Green Deal sustainability frameworks now mandate supply-chain carbon intensity disclosures for nut products entering European retail. Processors must document cultivation inputs, transport modes, and packaging substrates through blockchain-anchored traceability systems. Almond handlers in California and pistachio packers in Iran face the steepest documentation burden as they supply premium European supermarkets.
Direct-to-manufacturer procurement is displacing traditional commodity broker intermediation in industrial nut ingredient channels. Large bakery and confectionery groups in Germany and the Netherlands establish multi-year offtake agreements with specific cooperatives. This channel compression is most visible in almond butter and flour categories where specification consistency outweighs spot-price flexibility.
Nuts and Nut Products Market Segmentation
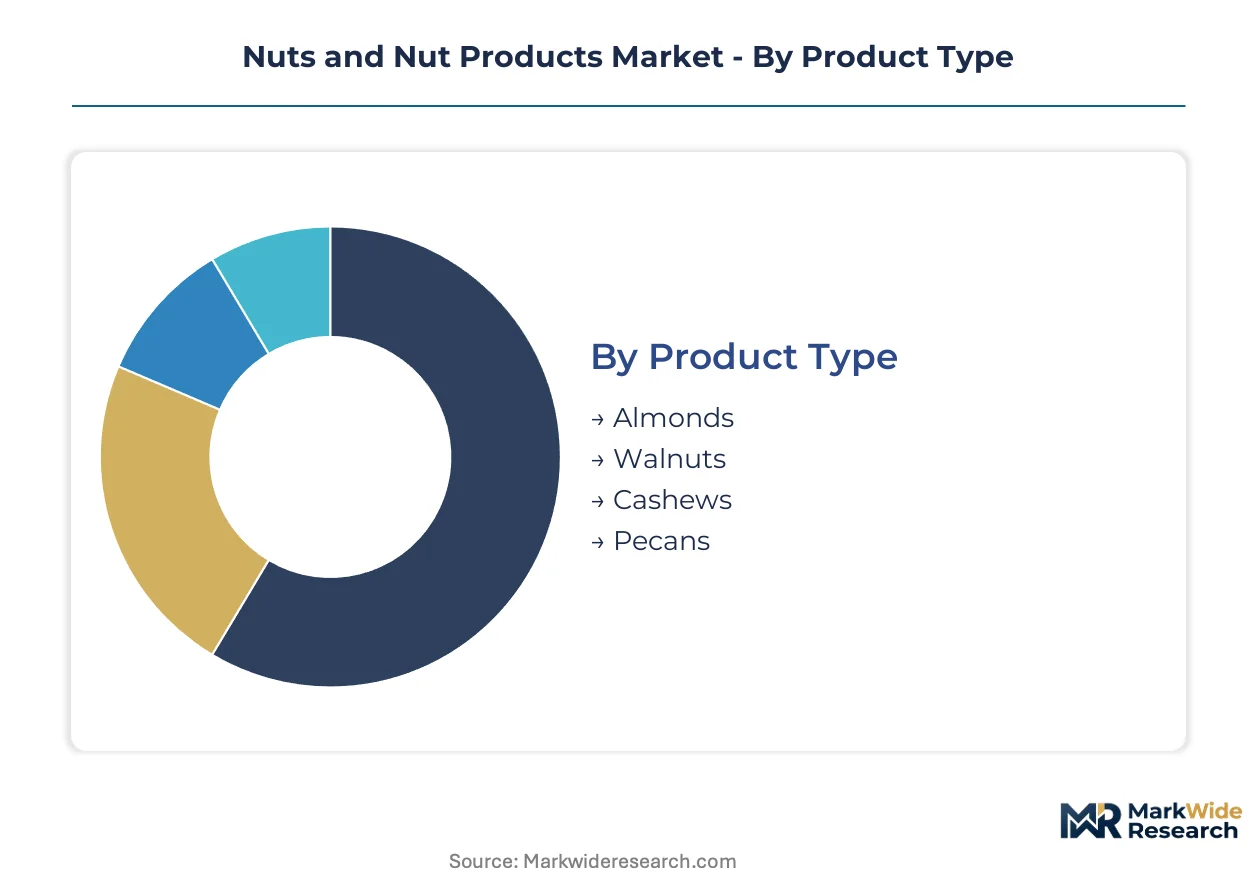
Segmentation in the nuts and nut products market reveals how procurement specifications diverge across food manufacturing, retail, and foodservice channels. Understanding these splits exposes where margin pools concentrate and which specifications command compliance investments.
Product Type:
Buyers differentiate primarily by oil composition, shelling mechanics, and ingredient functionality in downstream formulations.
- Almonds:Contain 50-55% lipid content with high oleic acid stability, making them preferred for extended-shelf-life applications. California's Central Valley supplies mechanized harvesting scale that underpins cost structures for almond butter and flour processors in Germany and the Netherlands.
- Walnuts:Deliver the highest alpha-linolenic acid concentration among tree nuts, positioning them for functional food and nutraceutical procurement. Demand from European bakery manufacturers concentrates on light-colored halves that minimize visual defect in premium product lines.
- Cashews:Vietnam and India dominate shelling capacity with labor-intensive processing that shapes landed cost volatility. Kernel grades from West African origins are gaining traction as buyers diversify beyond Asian supply concentration.
- Pecans:Native to the Mississippi River Valley with harvest cycles tied to US domestic confectionery demand. Shelling infrastructure in Georgia and Texas limits export volume flexibility compared to almond handlers.
Volume sits with almonds; growth tilts toward cashews as Asian shelling capacity expands and flexitarian formulations absorb more cashew base.
Grade:
Certification tiers separate procurement budgets and determine which suppliers qualify for supermarket private-label and foodservice contract tiers.
- Organic:Requires three-year land conversion and USDA-accredited handler certification. Clean-label mandates from North American retail chains expand price premiums for certified handlers, though documentation audits compress supplier margins.
- Non-Organic:Conventional cultivation without synthetic input restrictions. California almond growers achieve yield advantages of 15-25% over organic counterparts, preserving cost leadership in industrial ingredient channels.
- Premium:Defined by kernel size uniformity, defect thresholds below 2%, and origin-specific traceability. European confectionery manufacturers in Belgium and Switzerland specify premium grades for whole-nut chocolate inclusions.
- Standard:Accepts broader size variation and higher shell fragment tolerance. Bulk procurement for food manufacturing and extraction applications prioritizes standard grades where visual presentation matters less than oil yield.
Standard grade commands volume; premium and organic segments are expanding most quickly as clean-label procurement tightens specifications.
Packaging Type:
Channel requirements dictate format selection, with convenience retail and industrial procurement following diverging cost and shelf-life logic.
- Bags:Flexible film structures dominate snacking channels with reseal features and high-barrier laminates. Single-serve formats capture convenience retail in India's tier-two cities where organized penetration deepens.
- Jars:Rigid PET and glass containers anchor nut butter and seasoned nut positioning in North American and European supermarkets. Label surface area supports nutritional claims and origin storytelling for premium positioning.
- Cans:Metal containers preserve roasted product freshness in ambient distribution. Traditional formats retain share in Middle Eastern and Southeast Asian retail where packaging durability outweighs material cost premiums.
- Bulk:Poly-lined fiber totes and super-sacks minimize per-unit packaging cost for industrial bakery and confectionery processors. Direct-to-manufacturer procurement is displacing traditional commodity broker intermediation in this channel.
Bulk packaging retains volume leadership; bags are gaining share fastest as snacking occasions fragment across convenience retail formats.
Application:
End-use specifications determine roasting profiles, particle size, and microbiological thresholds that processors must certify.
- Snacking:Ready-to-eat products with seasoned coatings and flavor inclusions. Precision roasting technology enables batch consistency for private-label contracts across European and North American retail.
- Baking:Ingredient formats include meal, flour, and paste with controlled moisture and fat specifications. German and Dutch bakery groups establish multi-year offtake agreements with specific cooperatives for specification consistency.
- Cooking:Whole and chopped kernels for foodservice and home preparation. India's urban middle-class consumption of premium shelled almonds accelerates as household incomes climb.
- Confectionery:Whole nut inclusions and praline bases with stringent aflatoxin and foreign material limits. EU EFSA contaminant thresholds enforce pre-shipment testing protocols that cannot eliminate border rejection risk entirely.
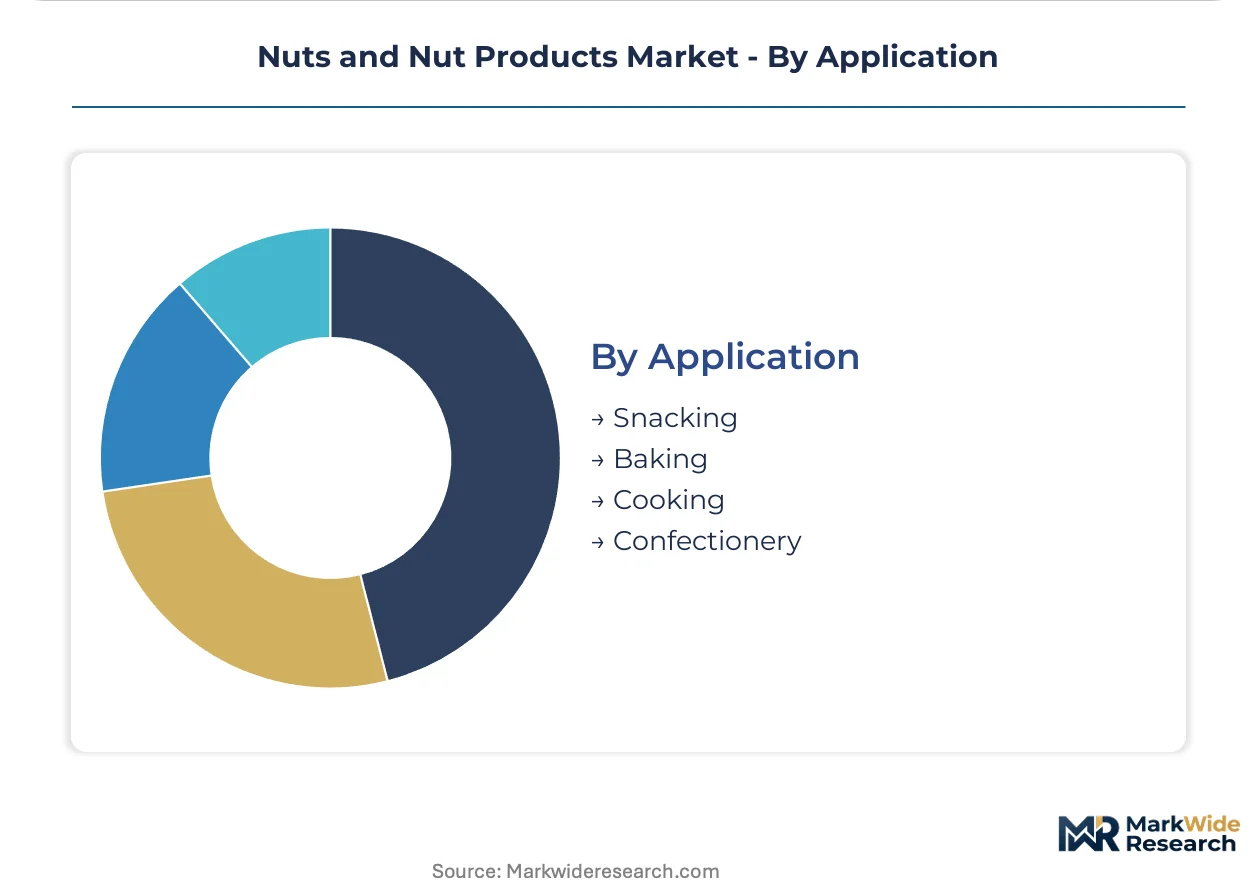
Snacking anchors volume; baking and confectionery applications show the steepest expansion trajectory as plant-based protein substitution accelerates formulation reformulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand acceleration as urban household incomes expand organized retail penetration for premium shelled almonds and cashews. California's Central Valley anchors almond supply scale, while Vietnam and India dominate labor-intensive cashew shelling. European procurement tightens sustainability specifications under EU Green Deal frameworks.
United States
California's Central Valley supplies mechanized almond harvesting scale that underpins global ingredient cost structures. FDA food safety standards and USDA organic certification shape export documentation burdens for European and Asian shipments. Sacramento Valley processing clusters retrofit traceability infrastructure to capture embedded emissions data for supermarket compliance.
Germany
Bakery and confectionery manufacturers in North Rhine-Westphalia drive industrial procurement of almond butter and flour with multi-year offtake agreements. REACH compliance mandates solvent-free extraction and biodegradable packaging substrates for retail listings. Hamburg port facilities handle bulk nut ingredient imports for redistribution across Benelux markets.
India
Urban middle-class consumption of premium shelled almonds accelerates as organized retail deepens penetration in tier-two cities. FSSAI quality mandates and BIS standards fragment import documentation requirements for multinational suppliers. Mumbai and Delhi-NCR distribution hubs consolidate cashew shelling capacity alongside rising domestic processing investment.
Vietnam
Binh Phuoc and Dong Nai provinces concentrate labor-intensive cashew shelling infrastructure that shapes global kernel supply availability. Monsoon disruption and labor availability swings expose buyers to landed cost volatility. Local processors expand automated sorting capacity to meet European supermarket contaminant thresholds.
Spain
Valencia and Catalonia roasting facilities deploy hyperspectral sorting technology for quality control at receiving stations. EU Green Deal carbon-accounting mandates force documentation of cultivation inputs through blockchain-anchored traceability systems. Mid-sized processors reconfigure lines between raw bulk output and value-added seasoned products.
Nuts and Nut Products Market Competitive Landscape
United States producers anchor one tier of mechanized scale and vertical orchard control; Asian specialists hold labor-dependent processing concentration. The vendor base splits between integrated agricultural conglomerates with captive supply and regional roasting specialists serving premium private-label contracts. Two strategic archetypes dominate: orchard-integrated handlers with backward control over cultivation inputs, and precision-processing specialists with thermal profiling technology. Competitive moves center on multi-year offtake agreements with industrial bakery groups and retrofitting traceability infrastructure for EU supermarket compliance.
Within the integrated agricultural tier, Olam Group exemplifies orchard-to-retail supply chain control, while Blue Diamond Growers represents deep specialization in almond cultivation geography. Mariani Nut Company occupies a position among precision-roasting specialists serving North American premium channels. These three anchors illustrate how competitive positioning splits between scale-driven upstream integration and technology-enabled processing consistency.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| Olam Group |
| John B. Sanfilippo & Son |
| Hormel Foods |
| Barry Callebaut |
| The Wonderful Company |
| Archer Daniels Midland Company |
| Mariani Nut Company |
| Kraft Heinz |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon-accounting mandates are forcing European retailers to demand blockchain-anchored traceability documentation from suppliers, compelling California almond handlers and Vietnamese cashew processors to invest in emissions-capture infrastructure that compresses margins at the origin tier.
Pricing Analysis
Volume sits with standard-grade bulk shipments to industrial bakery and confectionery channels, while margin concentrates in organic-certified and premium-grade retail formats. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and kernel uniformity specifications. Price differentiation stems from USDA organic handler status and EU EFSA contaminant compliance thresholds. Cost compression in conventional almond tiers is intensifying because California irrigation allocation cuts raise cultivation input costs. Industrial buyers in Germany and the Netherlands show highest price sensitivity, while North American premium channel distributors absorb organic premiums with least resistance.
Supply Chain Analysis
Ocean freight rates from California to Rotterdam and from Ho Chi Minh City to Hamburg remain the dominant landed cost variable for almond and cashew shipments. Geographic supply concentration centers on the United States for almonds, Vietnam and India for cashew shelling, and Iran and Turkey for pistachios. Raw material dependencies include irrigation water access in California's Central Valley, labor availability in Vietnamese shelling facilities, and aflatoxin-free peanut sourcing for EU confectionery. Single-origin supply concentration in Vietnamese cashew processing exposes buyers to monsoon disruption and labor availability swings. Distribution runs through direct-to-manufacturer procurement channels displacing traditional commodity brokers in industrial ingredient segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around orchard-integrated handlers with traceability infrastructure, as EU Green Deal compliance costs force smaller regional roasters without captive supply to exit or sell.
For Market Incumbents: Hedge against water input cost volatility in California by securing groundwater banking rights and retrofitting processing facilities with solvent-free extraction systems to maintain REACH-compliant supermarket listings. Backward integration into organic almond cultivation in Spain's Valencia region diversifies geographic supply exposure. Precision roasting technology investments in thermal profiling equipment defend private-label contract renewals against emerging AI-enabled processing specialists. For New Entrants and Emerging Players: Enter via Brazil nut geographic underpenetration in European organic snack channels, where Amazon-sourced supply chains remain undeveloped and certification infrastructure gaps create white-space for first-movers. Target precision-roasting contract manufacturing for mid-sized European private-label brands seeking batch consistency without capital investment. Lead with IoT-enabled moisture detection capabilities as the go-to-market differentiator against legacy equipment operators. For Investors and Strategic Acquirers: The window for entry favors precision-processing specialists with thermal profiling technology and established EU supermarket compliance documentation. Long-term viability hinges on traceability infrastructure ownership that becomes mandatory for premium channel access. Acquire handlers with blockchain-anchored emissions accounting already deployed. Watch for California groundwater pumping restriction enforcement as the inflection signal that accelerates orchard asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captures three-year land conversion premiums before USDA certification timelines compress supplier margins. |
| Blockchain-Anchored Traceability Deployment | Satisfies EU Green Deal carbon intensity disclosure mandates for premium supermarket listings. |
| Precision Roasting Technology Acquisition | Enables batch consistency for private-label contracts against commodity-grade competitors. |
| Direct-to-Manufacturer Procurement Channels | Displaces traditional commodity brokers in industrial almond butter and flour segments. |
| Geographic Diversification into West African Cashew | Reduces Vietnam-India supply concentration exposure to monsoon and labor volatility. |
Research Methodology
Multi-period observation of California irrigation allocation trends, Vietnamese shelling capacity utilization, and EU EFSA border rejection rates anchored the trend analysis, supplemented by interviews with almond cooperative managers, cashew shelling facility operators, European supermarket category buyers, and USDA-accredited organic handlers. Secondary validation drew from FDA food safety inspection data, EU REACH compliance registries, FAO trade statistics, and SEC filings of integrated agricultural conglomerates. Bottom-up volume estimates from cultivation acreage and yield assumptions triangulated against top-down retail audit data across the analysis window.
Segment-weighting applied product type splits across almonds, cashews, walnuts, and pecans, crossed with grade tiers spanning organic, non-organic, premium, and standard certifications. Packaging format and application channel dimensions further disaggregated volume. CAGRs derived from regression against household income elasticity in India, flexitarian protein substitution rates in European bakery reformulation, and REACH compliance investment cycles. Forecast inputs included California groundwater pumping restriction enforcement probability and Vietnam labor availability indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained drought conditions in the Central Valley or abrupt EU Green Deal timeline acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Walnut-Based Spreads Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Walnut Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Passionfruit Seed Oil Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Almond Protein Market
Nuts and Seeds
China Fox Nuts Market
Nuts and Seeds
Europe Tahini Market