
 US Alcoholic Drinks Packaging Market | 2026-2036
US Alcoholic Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Alcoholic Drinks Packaging Market Analytics
Domestic aluminum can producers is pivoting toward lighter-gauge, decorated formats to capture craft beer migration from glass. Amcor leverages its film and closure portfolio to serve spirits pouches and wine bag-in-box formats. Ball Corporation anchors North American beverage can supply through continuous furnace investment and recycling loop integration. Crown Holdings competes aggressively in aluminum bottle and specialty can shaping for premium positioning.
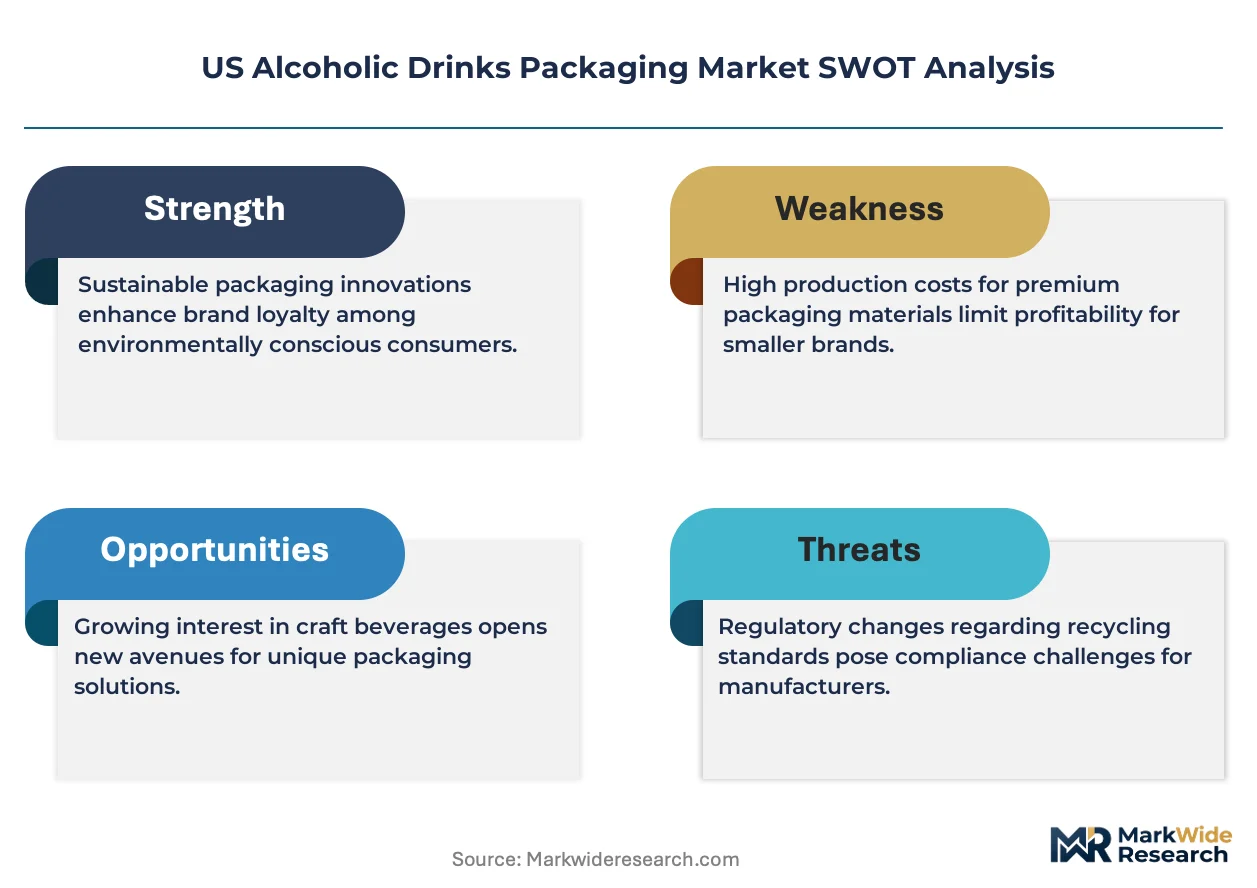
US alcoholic drinks packaging encompasses primary and secondary containment systems for beer, wine, and distilled spirits, typically engineered to preserve organoleptic stability, prevent UV degradation, and withstand carbonation pressures. Glass bottles remain dominant for wine and premium spirits due to oxygen barrier performance and consumer aesthetic expectations, while aluminum cans capture beer volume through chill efficiency and retail portability. Aluminum material segments lead growth trajectory given circular economy tailwinds and brewery preference for infinitely recyclable formats. Glass bottle categories sustain margin concentration in super-premium and aged-spirit applications where weight and opacity signal quality. Cardboard secondary packaging occupies e-commerce fulfillment channels as DTC alcohol shipping expands.
The Alcohol and Tobacco Tax and Trade Bureau governs label approval, health statements, and container standards for interstate commerce, while FDA maintains oversight of food-contact substances and packaging safety. State-level deposit-return systems in California, Oregon, and Maine mandate minimum recycled content thresholds that redirect procurement toward post-consumer aluminum and rPET. Stakeholders must monitor emerging extended producer responsibility legislation and TTB digital labeling pilots that could reshape compliance costs and format flexibility.
Market Dynamics
Migration from glass to aluminum formats among craft breweries is compressing supplier margins while reshaping capital allocation across primary packaging tiers. TTB label approval backlogs and state deposit-return thresholds are forcing simultaneous compliance investments that favor integrated converters over fragmented suppliers.
Growth Catalysts
- Deposit-return mandates:California, Oregon, and Maine enforce minimum recycled content thresholds that redirect brewery procurement toward post-consumer aluminum and rPET streams.
- Chill-efficiency preference:Aluminum cans capture beer volume from glass as retailers prioritize faster cooling and reduced breakage in distribution.
- E-commerce fulfillment expansion:DTC alcohol shipping growth drives demand for corrugated secondary packaging engineered for parcel durability and branding surface area.
Market Restraints
- Aluminum sheet supply concentration:Domestic smelter capacity constraints and import tariff exposure create input cost volatility for can manufacturers.
- TTB label approval timelines:Interstate commerce container standards generate 60-90 day regulatory friction for seasonal and limited-release SKUs.
- Oxygen barrier limitations:Aluminum bottles and pouches face technical constraints for aged spirits applications where glass maintains organoleptic stability thresholds.
Strategic Opportunities
- Digital labeling pilots:TTB testing of QR-code health statements and dynamic content creates format flexibility for premium spirits brand storytelling.
- Texas manufacturing clusters:Underpenetrated canning capacity relative to brewery density in Hill Country and Dallas-Fort Worth offers brownfield expansion potential.
- Wine bag-in-box acceleration:3-liter and 5-liter formats gain traction in Florida retirement communities and California outdoor recreation segments.
Industry Challenges
- Extended producer responsibility legislation:Emerging state bills mandate packaging take-back infrastructure that requires capital deployment ahead of volume certainty.
- Furnace technology integration:Glass bottle manufacturers face complexity retrofitting regenerative furnaces for lower-carbon fuel mixes without compromising clarity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Alcoholic Drinks Packaging Market |
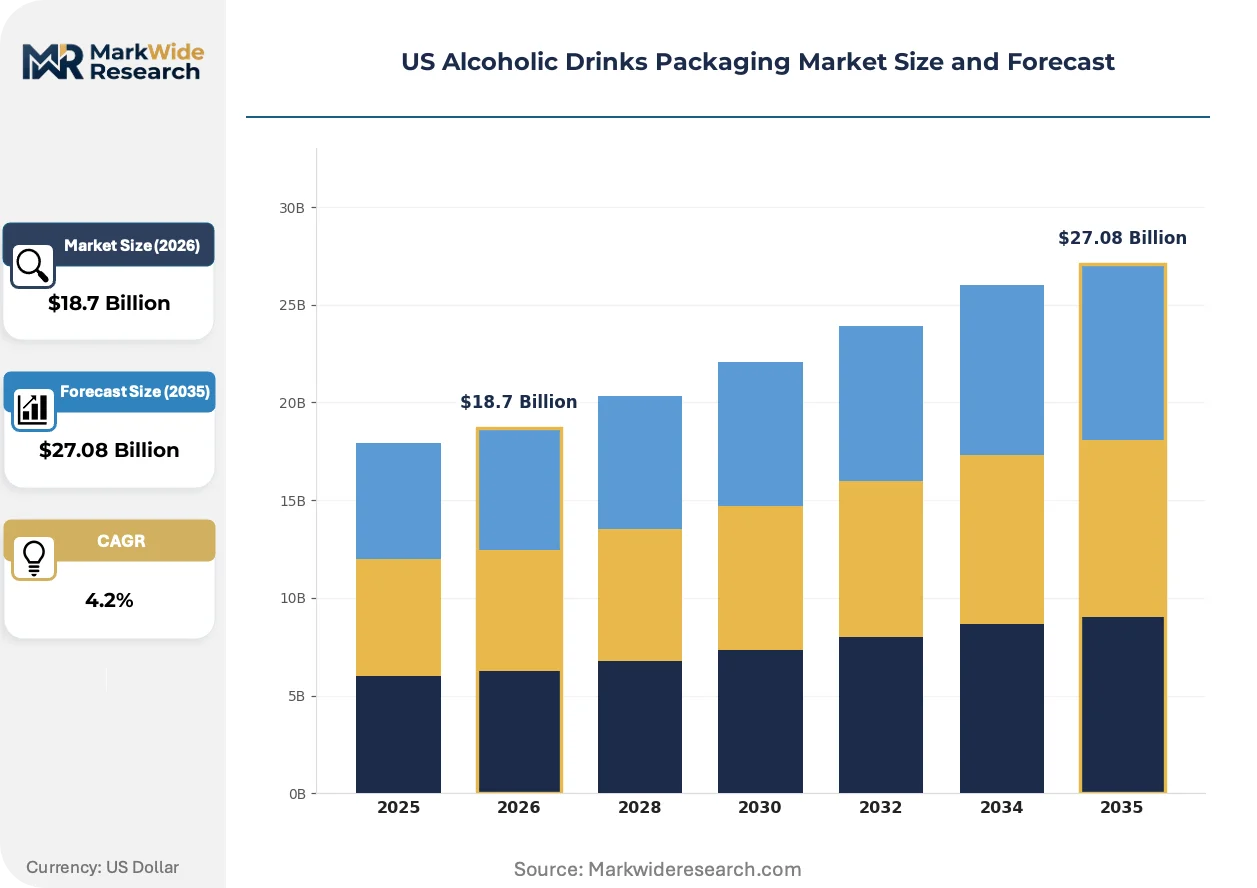
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Kegs, Pouches Material: Glass, Aluminum, Plastic, Cardboard Closure Type: Corks, Screw Caps, Snap-on Lids, Resealable Straws End User: Retail, Food Service, E-commerce, Wholesalers |
| Companies Covered | Amcor, United Bottles & Packaging, Ball Corporation, WestRock, Berry Global, Crown Holdings, Ardagh Group, IntraPac International, Owens-Illinois, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Alcoholic Drinks Packaging Market Evolving Landscape
Active differentiation through material science and regulatory positioning is compressing commoditized formats while elevating specialty converters. Sustainability verification and digital traceability are becoming baseline bid requirements rather than premium positioning tools.
Digital printing on aluminum cans is consolidating craft brewery brand expression by enabling micro-batch decoration without plate-change costs. Regional breweries in Colorado and Michigan adopt this technology for seasonal rotations. Short-run flexibility is consolidating market share among converters with installed direct-to-shape inkjet capacity.
State-level deposit-return system expansion is reshaping material specifications for interstate shippers. Oregon's 10-cent container value and California's rPET minimums force national brands to standardize across their highest-barrier jurisdiction. Wine and spirits producers in Florida and Texas face compliance complexity as deposit legislation spreads.
Buyer concentration among national beverage distributors is compressing packaging specification diversity. Large retail chains mandate unified SKUs across state lines, eroding regional format variation. California and Texas retail consolidation most visibly constrains boutique glass bottle and closure supplier access to shelf placement.
US Alcoholic Drinks Packaging Market Segmentation
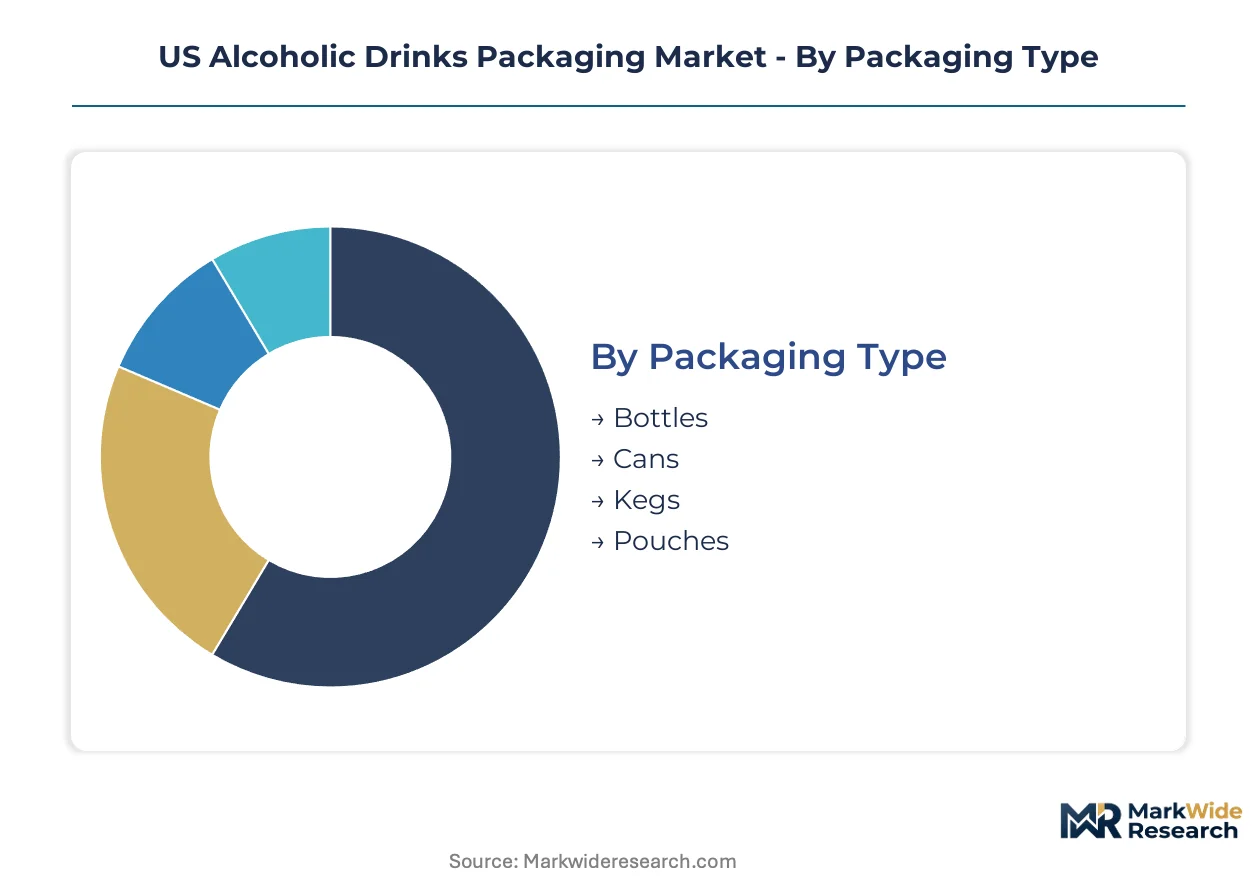
Packaging format selection in the US alcoholic drinks market hinges on thermal performance, recyclability mandates, and distribution channel requirements. Material and closure specifications cascade from these choices, creating interdependent procurement decisions across brewery and distillery operations.
Packaging Type:
Upgrade cycles from glass to aluminum accelerate as deposit-return legislation spreads across state lines, forcing format standardization for national distribution.
- Bottles:Glass bottles dominate wine and aged spirits applications where oxygen barrier performance preserves organoleptic stability. California and Florida wineries sustain demand for heavyweight flint and antique green glass despite aluminum encroachment in beer.
- Cans:Aluminum cans capture craft brewery volume through chill efficiency and retail portability. Texas Hill Country and Michigan brewery clusters drive specification for lighter-gauge, decorated formats with direct-to-shape digital printing capability.
- Kegs:Stainless steel kegs serve on-premise draft distribution for food service channels, with refillable logistics constraining geographic radius to regional brewery density.
- Pouches:Flexible spirits pouches and wine bag-in-box formats expand in Florida retirement communities and outdoor recreation segments, limited by TTB label approval complexity for non-standard containers.
Cans sit at the top of the volume ranking, with pouches climbing the fastest as bag-in-box gains shelf acceptance.
Material:
Procurement patterns bifurcate between infinite recyclability credentials and functional barrier requirements.
- Glass:Soda-lime silica compositions sustain super-premium positioning where weight and opacity signal quality. Oregon and Maine deposit-return thresholds preserve glass furnace output for wine and spirits despite energy intensity.
- Aluminum:Beverage can sheet commands brewery preference for circular economy alignment and carbonation pressure tolerance. Domestic smelter capacity constraints in the Pacific Northwest create input cost volatility for converters.
- Plastic:rPET bottles face California minimum recycled content mandates, with FDA food-contact substance approvals limiting formulation flexibility for spirits applications.
- Cardboard:Corrugated secondary packaging expands with DTC alcohol shipping growth, engineered for parcel durability and branding surface area in e-commerce fulfillment.
Aluminum leads volume, though cardboard expands most quickly alongside digital-native brand launches.
Closure Type:
Closure selection tracks premium positioning tiers and resealability requirements across consumption occasions.
- Corks:Natural and synthetic corks maintain wine industry standard for oxygen transmission management in cellar-aging applications. Napa and Sonoma producers resist screw cap conversion for reserve-tier SKUs.
- Screw Caps:Aluminum screw closures displace cork in value-tier wine and ready-to-drink spirits, with tamper-evident bands satisfying TTB container standards for interstate commerce.
- Snap-on Lids:Steel and aluminum snap closures serve malt beverage cans and specialty aluminum bottles, with Crown Holdings and Ball Corporation competing on opening torque specifications.
- Resealable Straws:Integrated straw closures enable pouch-based consumption for outdoor and event occasions, limited by oxygen ingress constraints for extended shelf life.
Screw caps dominate volume, with resealable straws gaining share fastest in recreational consumption segments.
End User:
Channel concentration among national beverage distributors compresses packaging specification diversity across state lines.
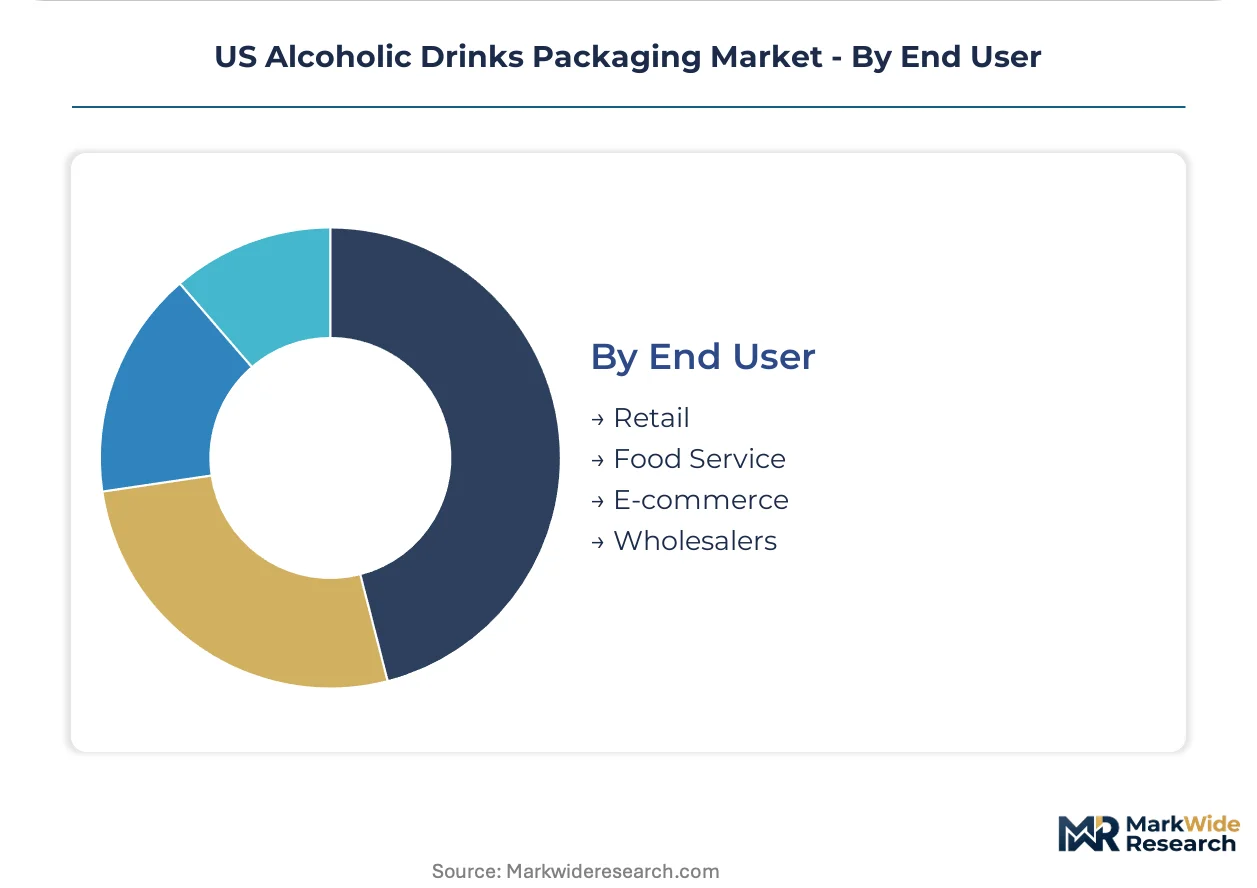
- Retail:Grocery and liquor store chains mandate unified SKUs across California, Texas, and Florida operations, eroding regional format variation and favoring aluminum can standardization.
- Food Service:On-premise draft and bottle service drives keg and premium glass demand, with Texas and Florida hospitality density supporting dedicated supply contracts.
- E-commerce:DTC shipping expansion requires corrugated secondary packaging and breakage-resistant primary formats, with TTB digital labeling pilots enabling compliance flexibility for online-only SKUs.
- Wholesalers:Three-tier distribution consolidation in California and Texas constrains boutique supplier access, with large distributors standardizing procurement across aluminum and glass categories.
Retail commands volume, with e-commerce showing the steepest expansion trajectory as DTC regulations stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as brewers and distillers migrate toward jurisdictions with favorable deposit-return thresholds and lower compliance friction. State-level variation in bottle deposit legislation creates procurement cost gaps that redirect capital allocation across the US.
California
Wineries in Napa and Sonoma sustain demand for heavyweight flint glass despite energy intensity, as premium positioning requires opacity and tactile weight. CalRecycle enforces rPET minimums and container redemption values that force national brands to standardize formulations. Los Angeles and San Diego brewery clusters are accelerating aluminum can adoption for distribution efficiency.
Texas
Hill Country and Dallas-Fort Worth brewery density exceeds regional canning capacity, creating brownfield expansion opportunities for converters. The Texas Alcoholic Beverage Commission maintains container standards that align with TTB interstate commerce rules. Houston petrochemical corridors supply rPET feedstock for spirits applications facing California export requirements.
Florida
Retirement communities and outdoor recreation segments drive wine bag-in-box and spirits pouch volume in Tampa and Orlando metro areas. The Florida Department of Business and Professional Regulation oversees labeling compliance for DTC shipping channels. Miami-Dade distribution hubs consolidate procurement for Caribbean export markets.
Oregon
Craft brewery concentration in Portland and Bend sustains demand for digitally printed aluminum cans with seasonal rotation flexibility. The Oregon Liquor and Cannabis Commission administers the nation's highest container deposit value at ten cents, preserving glass furnace output for wine despite energy costs. Corvallis and Eugene packaging innovation labs test biodegradable secondary materials.
New York
Brooklyn and Queens distillery clusters require premium glass and specialty closures for super-premium spirits positioning. The New York State Liquor Authority enforces label approval timelines that compress seasonal SKU windows. Finger Lakes wineries balance glass tradition against aluminum encroachment in retail channels.
US Alcoholic Drinks Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty formats and digital printing capabilities. The market structure consolidates around integrated converters with furnace and rolling mill assets, while fragmented regional suppliers serve craft brewery micro-batch requirements. Three archetypes dominate: multinational diversified packaging conglomerates, aluminum-focused beverage can specialists, and glass bottle heritage manufacturers. Capacity expansion and recycling loop integration constitute the primary competitive moves, with secondary emphasis on strategic partnerships for digital labeling technology.
Within the multinational diversified tier, Amcor leverages film and closure portfolios across spirits pouches and wine bag-in-box formats. Ball Corporation anchors North American beverage can supply through continuous furnace investment. Crown Holdings competes in aluminum bottle and specialty can shaping for premium positioning. These three exemplify distinct strategic postures: materials breadth, scale infrastructure, and format innovation respectively.
| Leading Market Players |
|---|
| Amcor |
| United Bottles & Packaging |
| Ball Corporation |
| WestRock |
| Berry Global |
| Crown Holdings |
| Ardagh Group |
| IntraPac International |
| Owens-Illinois |
| Others |
Value Network & Pricing Analysis
LME aluminum spot pricing cascades through US beverage can supply chains, compressing converter margins while amplifying procurement leverage for national brewery chains with volume commitments across California, Texas, and Florida distribution networks.
Pricing Analysis
Distributor margin layers absorb raw material volatility before retailer markup finalizes shelf pricing. Three-tier pricing structure across premium, standard, and economy levels separates craft brewery specialty formats from mass-market aluminum cans and value-tier glass spirits bottles. Price differentiation stems from decoration complexity and recycled content certification grade. Cost compression in standard-tier cans is intensifying because domestic smelter capacity constraints elevate sheet input costs. National beverage distributors exhibit lowest price sensitivity; regional craft breweries face highest procurement pressure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale brewery demand, while fragmented converters serve micro-batch craft requirements through distributor intermediaries. Primary aluminum supply draws from domestic Pacific Northwest smelters, Canadian ingot imports, and Gulf Coast secondary refining. Key inputs include beverage can sheet, recycled post-consumer aluminum, and direct-to-shape digital printing equipment. Tariff exposure on Canadian primary aluminum creates input cost volatility for Midwest converters. Distribution runs through three-tier beverage alcohol systems anchored by California and Texas wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where deposit-return legislation in California, Oregon, and Maine continuously reshapes material specifications and procurement thresholds.
For Market Incumbents: Deepen recycling loop integration through captive aluminum collection infrastructure to defend against emerging rPET specialists and glass furnace retrofits. Prioritize furnace technology investment in lower-carbon fuel mixes to preempt Oregon and Maine energy intensity regulations. Secure long-term can sheet offtake agreements with domestic smelters to buffer tariff exposure on Canadian imports. For New Entrants and Emerging Players: TTB digital labeling pilots in interstate commerce open a window for QR-code enabled packaging formats that bypass traditional plate-change constraints. Target Florida retirement communities with wine bag-in-box formats where pouch acceptance outpaces national averages. Pursue direct-to-consumer e-commerce channels where corrugated secondary packaging requirements favor agile fulfillment specialists over legacy glass converters. For Investors and Strategic Acquirers: Asymmetric upside sits with digitally capable aluminum converters serving craft brewery seasonal rotation demand. Five-to-ten year viability hinges on deposit-return system expansion across state lines. Monitor Texas Hill Country and Dallas-Fort Worth brewery density relative to regional canning capacity as inflection indicator for brownfield expansion returns.| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Loop Integration | Captive aluminum collection infrastructure secures post-consumer supply for California rPET minimums. |
| Digital Printing Capacity Expansion | Direct-to-shape inkjet installation captures craft brewery micro-batch decoration without plate costs. |
| Furnace Technology Retrofit | Regenerative furnace conversion for lower-carbon fuels addresses Oregon energy intensity thresholds. |
| Corrugated Secondary Packaging Scale-Up | Parcel-durable formats align with DTC alcohol shipping growth through California and Florida hubs. |
| Deposit-Return Compliance Standardization | Unified SKU formats across California, Oregon, and Maine reduce interstate distribution friction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brewery procurement directors, packaging converter plant managers, TTB regulatory affairs specialists, and national distributor category buyers with secondary validation against FDA food-contact substance filings, TTB label approval databases, CalRecycle container reporting, and SEC disclosures from listed packaging conglomerates. Bottom-up volume builds across format and material segments triangulated against top-down macroeconomic consumption indicators.
Segment-weighting approaches applied differential growth assumptions across packaging types, material compositions, closure specifications, and end-use channels. Modeled dimensions included primary format selection, recycled content tier, distribution channel concentration, and state-level regulatory cluster. CAGRs derived from historical shipment data elasticity and forward-looking brewery capacity announcements. Forecast inputs incorporated aluminum price trajectory assumptions and deposit-return system expansion probabilities.
Revisions become necessary when TTB digital labeling pilots accelerate beyond pilot phase, when extended producer responsibility legislation mandates packaging take-back infrastructure ahead of volume certainty, or when domestic smelter capacity constraints trigger sustained input cost dislocation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market