
 Middle East and Africa Alcoholic Drinks Packaging Market | 2026-2036
Middle East and Africa Alcoholic Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Alcoholic Drinks Packaging Market Foresight
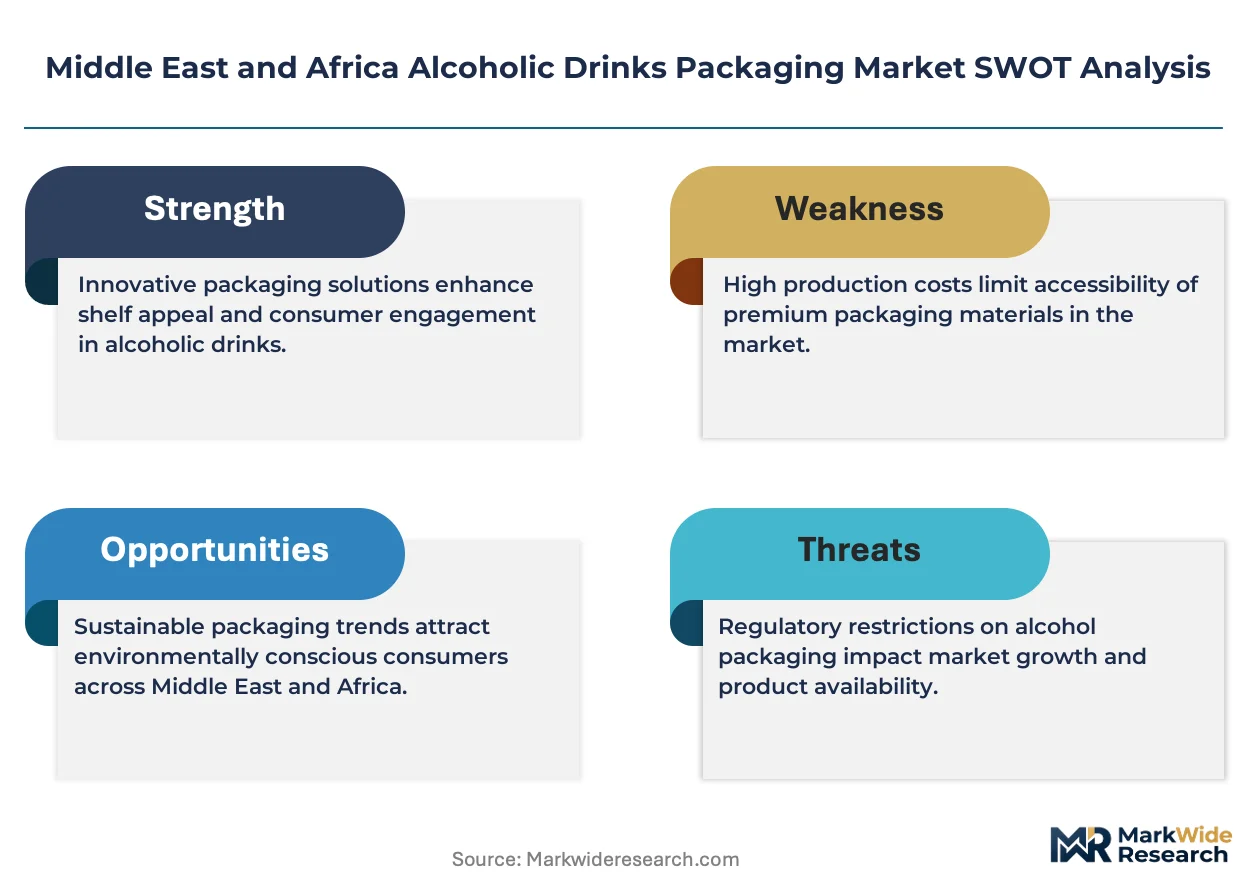
CE marking for food-contact materials is reorganizing supplier qualification across the Middle East and Africa alcoholic drinks packaging value chain, raising barriers for uncertified converters. Crown Holdings Inc. leverages its aluminum can technology leadership to anchor supply relationships with breweries in Nigeria and Kenya. Ball Corporation competes through manufacturing scale in North Africa, while Consol Glass Ltd dominates container glass output in Southern Africa with captive silica access.
Middle East and Africa alcoholic drinks packaging encompasses primary and secondary containment systems engineered to preserve beverage integrity, prevent oxidation, and comply with regional labeling mandates for alcohol content and health warnings; glass bottles typically employ borosilicate or soda-lime compositions with wall thickness calibrated for carbonation pressure and transit durability. Aluminum cans are gaining share in lager and ready-to-drink segments where chilled distribution infrastructure is expanding. Glass bottles sustain premium positioning in wine and spirits where closure type—cork versus screw cap—signals quality tier to retail and on-trade buyers.
EU REACH compliance requirements shape material sourcing for exporters serving European markets, while South Africa's National Regulator for Compulsory Specifications enforces local packaging standards for alcoholic beverages. The UAE's Emirates Authority for Standardization and Metrology governs import specifications for packaging materials entering duty-free zones. Stakeholders must monitor how Gulf Cooperation Council harmonization of food-contact regulations alters testing and certification costs for regional producers.
Market Dynamics
Extended producer responsibility mandates across EMEA jurisdictions are forcing packaging converters to internalize end-of-life costs, compressing margins for non-integrated suppliers while advantaging firms with captive recycling infrastructure.
Growth Catalysts
- Tourism-linked hospitality recovery:South Africa's premium wine estates and Cape Town's on-trade venues are expanding glass bottle orders as international visitor arrivals rebound, pulling container demand from Consol Glass and imported alternatives.
- CE marking reorganization:The European Union's revised food-contact material certification requirements are disqualifying uncertified Middle Eastern converters from export supply chains, creating procurement slots for compliant regional producers.
- Chilled distribution infrastructure:Aluminum can adoption is accelerating in Nigerian and Kenyan lager segments where cold-chain investments enable shelf-stable packaging to compete with returnable glass systems.
Market Restraints
- Silica sand supply concentration:Container glass production depends on high-purity silica deposits concentrated in South Africa's Northern Cape, exposing Nigerian and Kenyan bottlers to freight-cost volatility and import dependency.
- REACH compliance friction:EU chemical registration requirements create documentation burdens for Middle Eastern exporters using non-European ink and coating suppliers, delaying shipment clearances at Rotterdam and Hamburg.
- Returnable glass system entrenchment:Heineken and Diageo-operated refillable bottle pools in Nigeria sustain depreciation-amortized cost structures that resist one-way aluminum can substitution despite convenience advantages.
Strategic Opportunities
- UAE duty-free channel formalization:Emirates Authority for Standardization and Metrology import specifications are consolidating previously fragmented packaging procurement for Dubai and Abu Dhabi airport retail, creating volume aggregation points for qualified suppliers.
- Lightweighting technology convergence:Laser engraving and direct-to-glass digital printing are converging to enable premium spirits brands to eliminate paper labels, reducing material mass and simplifying Gulf Cooperation Council recycling compliance.
- Nigerian brewery consolidation:International Breweries and Nigerian Breweries capacity expansions in Lagos and Ibadan are standardizing can formats, opening procurement windows for aluminum suppliers with regional tolling arrangements.
Industry Challenges
- Food-contact certification timelines:Migration testing for new barrier coatings under EFSA and South Africa's National Regulator for Compulsory Specifications protocols extends qualification cycles to 18-24 months, delaying product launches for reformulated packaging.
- Legacy closure equipment incompatibility:Screw-cap adoption in South African wine confronts bottling lines configured for cork insertion, requiring capital-intensive retooling at Stellenbosch and Paarl production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Alcoholic Drinks Packaging Market |
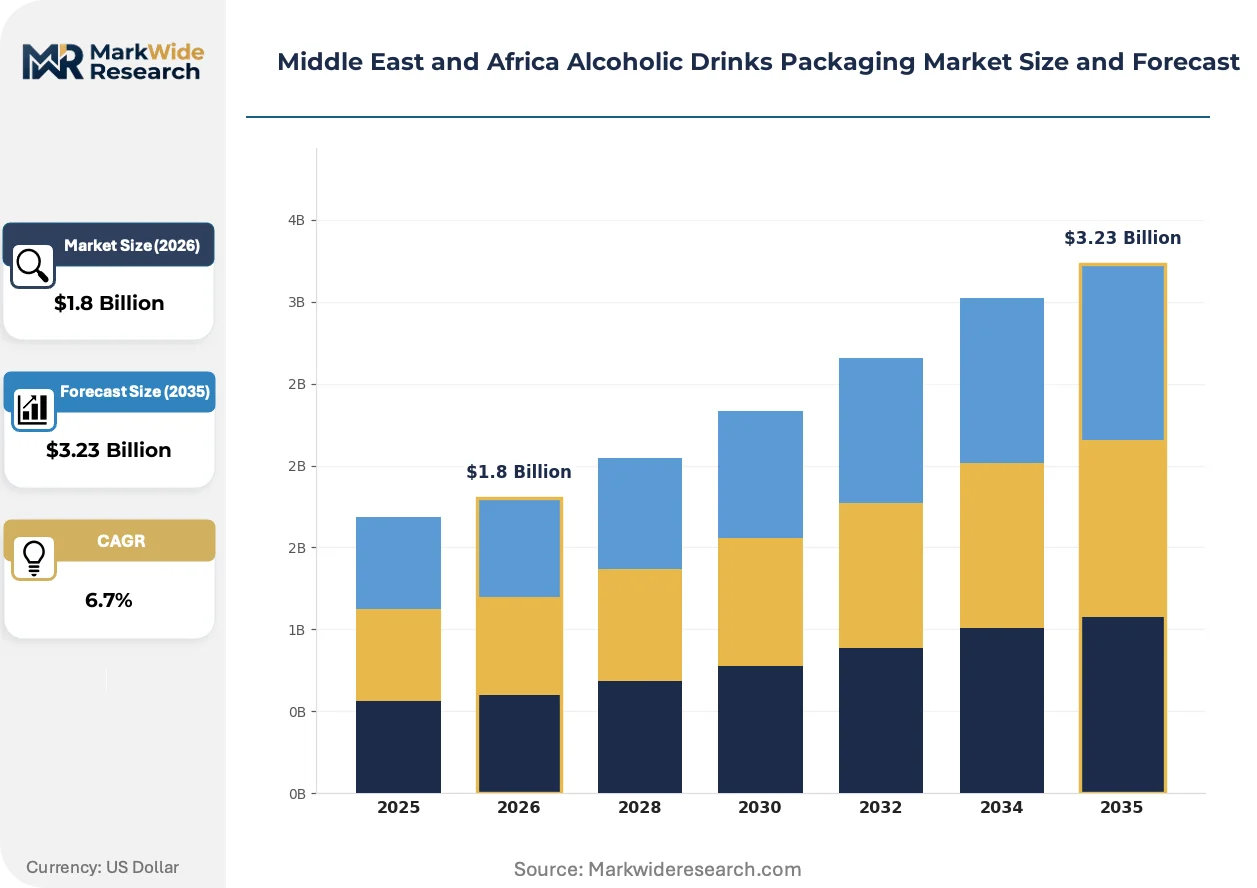
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Pouches, Kegs Material: Glass, Aluminum, Plastic, Cardboard Closure Type: Cork, Screw Cap, Crown Cap, Flip Top End User: Retail, Bars, Restaurants, Cafes |
| Companies Covered | Huhtamäki Oyj, Ball Corporation, Crown Holdings Inc., Middle East Glass Manufacturing Co SAE, Can-Pack SA, Saudi Arabian Glass Co. Ltd, Consol Glass Ltd, Saverglass SAS, Nampak Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Alcoholic Drinks Packaging Market Shifts & Advancements
Active packaging functionality and regulatory digitization are compressing traditional material specifications while creating new qualification hierarchies across Middle East and Africa supply chains.
Barrier-coated polyethylene terephthalate is decomposing glass's monopoly in mid-tier spirits where weight reduction and shatter resistance outweigh premium signaling. Kenyan and Tanzanian distributors are piloting PET replacements for 750ml liquor bottles in informal retail channels where breakage rates exceed acceptable thresholds. This substitution is decomposing the traditional glass-or-aluminum binary and forcing container suppliers to develop hybrid material portfolios.
South Africa's National Regulator for Compulsory Specifications enforcement of alcoholic beverage packaging standards is mandating alcohol content legibility and health warning dimensions that exceed voluntary industry guidelines. Converters serving both domestic and export markets must maintain dual specification inventories or absorb redesign costs for unified compliance. Wine exporters to the European Union face overlapping EFSA migration limits and NRCS dimensional rules, compressing design flexibility.
Buyer consolidation among UAE hospitality groups is compressing supplier negotiation cycles and unbundling historical distributor relationships. Rotana and Marriott procurement teams in Dubai are establishing direct packaging specifications with manufacturers, bypassing legacy trading houses that previously aggregated fragmented orders. This disintermediation is most visible in premium spirits glass procurement where volume commitments now flow to Consol Glass and selected European importers on multi-year frameworks.
Middle East and Africa Alcoholic Drinks Packaging Market Segmentation
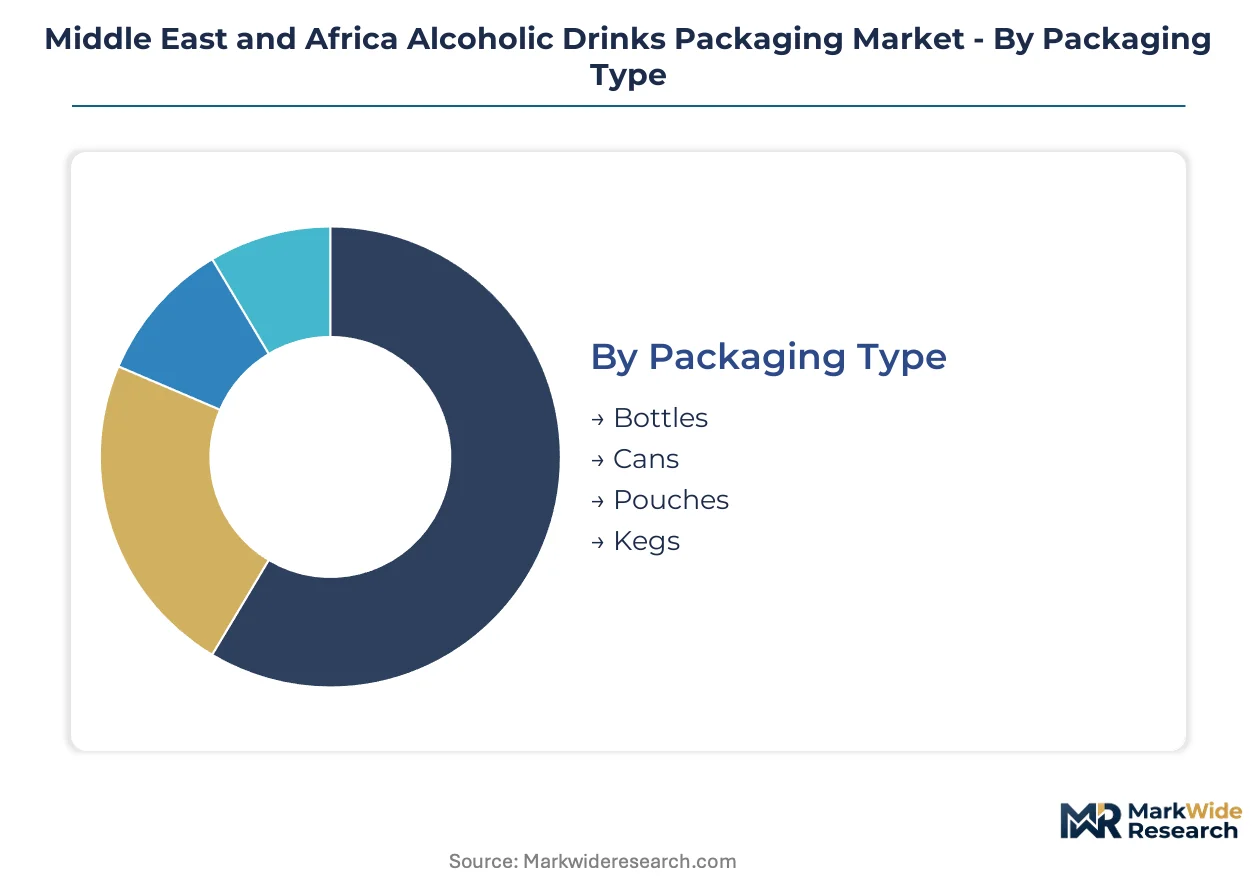
Packaging specifications diverge sharply across Middle East and Africa alcoholic drinks markets, with material choices driven by distribution infrastructure maturity, regulatory labeling mandates, and tourism-linked hospitality recovery patterns. Segment boundaries are blurring as barrier-coated plastics penetrate spirits categories and aluminum cans gain share in lager segments.
Packaging Type:
Margin pools concentrate in primary containment systems where carbonation pressure requirements and premium signaling create specification premiums.
- Bottles:Soda-lime and borosilicate glass compositions dominate wine and spirits, with wall thickness calibrated for transit durability across South Africa's Cape Winelands distribution corridors. Cape Town's premium on-trade venues are expanding glass orders as international tourism rebounds, pulling demand toward Consol Glass and European import alternatives.
- Cans:Two-piece aluminum draws from Crown Holdings' regional tolling arrangements, with lightweighting technology enabling 330ml and 500ml format standardization. Nigerian and Kenyan brewery expansions in Lagos and Ibadan are accelerating can adoption where chilled distribution infrastructure now supports shelf-stable packaging.
- Pouches:Flexible laminated films serve ready-to-drink cocktails and wine-in-bag formats for informal retail channels in Tanzania and Kenya where breakage risk and weight constraints outweigh premium positioning needs.
- Kegs:Stainless steel and PET variants supply on-trade draught systems, with returnable keg pools operated by Heineken and Diageo sustaining depreciation-amortized cost structures in Nigerian urban markets.
The dominant share belongs to bottles, while cans are closing the gap fastest as brewery consolidation standardizes aluminum formats.
Material:
Raw material access and regulatory migration limits are reshaping converter qualification hierarchies across the value chain.
- Glass:High-purity silica from South Africa's Northern Cape feeds container production with captive mining access insulating Consol Glass from import dependency. Nigerian and Kenyan bottlers face freight-cost volatility and supply concentration risk.
- Aluminum:Rolled can sheet and tab stock specifications align with EU REACH compliance requirements for exporters, with Ball Corporation leveraging North African manufacturing scale to anchor supply relationships.
- Plastic:Barrier-coated polyethylene terephthalate is decomposing glass's monopoly in mid-tier spirits where Kenyan distributors pilot 750ml liquor bottle replacements for informal retail channels with excessive breakage rates.
- Cardboard:Folding carton and corrugated secondary packaging serve gift sets and multi-packs, with Emirates Authority for Standardization and Metrology specifications governing import approval for Dubai and Abu Dhabi duty-free retail.
Glass commands the volume base, though aluminum is expanding most quickly in lager segments with cold-chain investment.
Closure Type:
Equipment compatibility and quality tier signaling create divergent capital requirements across wine and spirits production facilities.
- Cork:Natural and agglomerated cork closures sustain premium positioning in South African wine exports, though screw-cap adoption confronts bottling lines configured for insertion at Stellenbosch and Paarl facilities.
- Screw Cap:Aluminum and plastic screw closures enable consistent oxygen transmission control, with Stellenbosch producers retooling lines to capture convenience advantages and eliminate cork taint risk.
- Crown Cap:Pressed steel crown seals serve returnable and one-way beer bottles, with Heineken's Nigerian refillable pools sustaining entrenched cost structures that resist aluminum can substitution.
- Flip Top:Swing-top and hinged closures appear in premium spirits and craft beer segments where resealability and ceremonial opening rituals support price positioning.
Cork retains the premium tier anchor, while screw cap is gaining share fastest through equipment modernization and quality consistency.
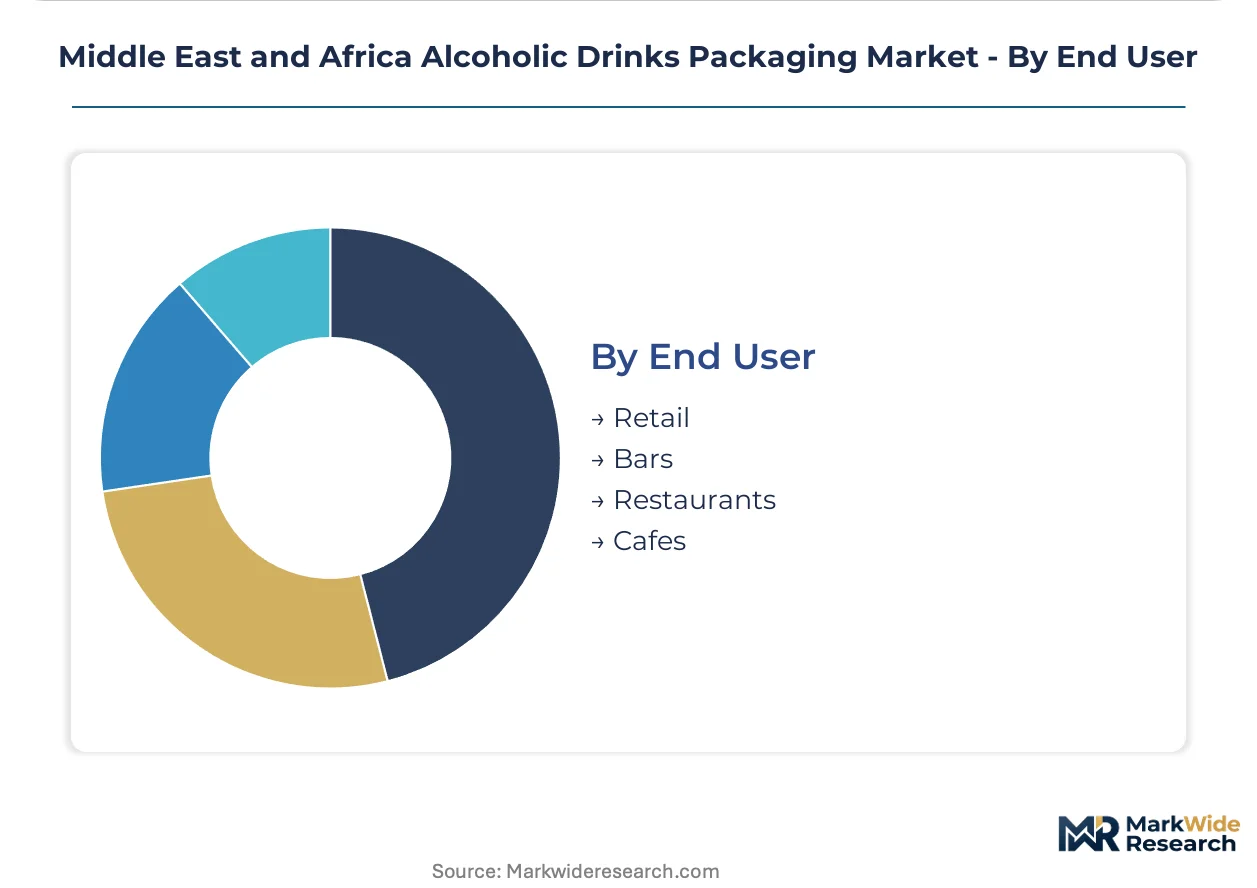
End User:
Procurement consolidation and specification unbundling are compressing supplier negotiation cycles across hospitality channels.
- Retail:Licensed liquor stores and supermarket chains in South Africa, Nigeria, and the UAE are formalizing distribution channels, with packaging specifications now flowing direct to manufacturers rather than through legacy trading house aggregation.
- Bars:Cape Town's on-trade recovery is expanding glass bottle orders, while Nigerian urban venues standardize aluminum can formats for chilled service efficiency.
- Restaurants:Rotana and Marriott procurement teams in Dubai are establishing direct packaging specifications, bypassing historical distributor relationships in premium spirits glass procurement.
- Cafes:Limited alcohol licensing constrains volume, though ready-to-drink canned cocktails are penetrating casual dining in Nairobi and Lagos where daytime consumption norms differ from evening bar culture.
Retail holds the dominant procurement volume, while restaurants are restructuring fastest through hospitality group consolidation and direct manufacturer engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility mandates across EMEA jurisdictions are redirecting packaging investment toward countries with established recycling infrastructure and formalized distribution channels.
South Africa
Tourism-linked hospitality recovery in Cape Town and the Winelands is expanding glass bottle procurement from Consol Glass and European import alternatives. The National Regulator for Compulsory Specifications enforces local packaging standards that exceed voluntary industry guidelines for alcohol content legibility. Stellenbosch and Paarl production facilities confront equipment retooling requirements as screw-cap adoption accelerates.
Nigeria
Brewery consolidation by International Breweries and Nigerian Breweries in Lagos and Ibadan is standardizing aluminum can formats for lager segments. Returnable glass systems operated by Heineken and Diageo sustain depreciation-amortized cost structures that resist one-way packaging substitution. Lagos urban markets are expanding chilled distribution infrastructure that enables shelf-stable aluminum formats.
United Arab Emirates
Emirates Authority for Standardization and Metrology import specifications are consolidating fragmented packaging procurement for Dubai and Abu Dhabi duty-free retail. Buyer consolidation among Rotana and Marriott hospitality groups is compressing supplier negotiation cycles and unbundling historical distributor relationships. Dubai airport retail is creating volume aggregation points for qualified glass and aluminum suppliers.
Kenya
Chilled distribution infrastructure investments are accelerating aluminum can adoption in Nairobi and Mombasa lager markets. Kenyan distributors are piloting barrier-coated PET replacements for 750ml liquor bottles in informal retail channels where glass breakage rates exceed thresholds. Nairobi-based production facilities are standardizing formats to capture cold-chain efficiency gains.
Saudi Arabia
Non-alcoholic beverage packaging specifications governed by the Saudi Food and Drug Authority create adjacent demand for transferrable barrier technologies and labeling systems. Jeddah and Riyadh industrial zones host converters that supply GCC markets with compliant food-contact materials. The Kingdom's packaging industrialization programs are attracting regional tolling arrangements from aluminum and glass suppliers.
Middle East and Africa Alcoholic Drinks Packaging Market Competitive Landscape
Listed leaders compete with private specialists across material technology and geographic coverage dimensions. Container glass production concentrates around captive silica access in South Africa's Northern Cape, while aluminum can supply fragments across regional tolling arrangements. Three archetypes dominate: integrated miners-converters with raw material control, multinational fabricators with EMEA manufacturing scale, and regional specialists with duty-free channel relationships. Capacity expansion and strategic tolling partnerships represent the dominant competitive moves as breweries consolidate procurement.
Among multinational fabricators, Ball Corporation and Crown Holdings Inc. exemplify scale-driven positions in aluminum can supply, while Consol Glass Ltd anchors the integrated glass tier with captive Northern Cape silica access. These three companies occupy distinct competitive spaces: Ball Corporation leverages North African manufacturing scale, Crown Holdings Inc. deploys technology leadership in two-piece can formats, and Consol Glass Ltd commands Southern African container output through vertical integration into raw material supply.
| Leading Market Players |
|---|
| Huhtamäki Oyj |
| Ball Corporation |
| Crown Holdings Inc. |
| Middle East Glass Manufacturing Co SAE |
| Can-Pack SA |
| Saudi Arabian Glass Co. Ltd |
| Consol Glass Ltd |
| Saverglass SAS |
| Nampak Ltd |
| Others |
Supply & Pricing Matrix
Ninety-day CE marking qualification cycles for food-contact materials now govern procurement decisions across Middle East and Africa alcoholic drinks packaging, compressing supplier margins for converters without pre-certified inventory while amplifying pricing power for firms with compliant stock on hand. This lead-time structure concentrates buyer leverage toward integrated glass and aluminum producers with captive certification pipelines.
Pricing Analysis
Certification level creates the primary spread across Middle East and Africa alcoholic drinks packaging tiers, with CE-marked and NRCS-compliant converters commanding 15-25% premiums over uncertified alternatives. Three-tier pricing structure separates premium glass bottles with direct-to-glass digital printing from standard aluminum cans and economy-grade barrier-coated PET for informal retail channels. Cost compression in mid-tier aluminum is intensifying because Nigerian brewery consolidation standardizes 330ml and 500ml formats, forcing tolling arrangements toward volume-scaled contracts. Licensed retail chains in South Africa and the UAE exhibit lowest price sensitivity given tourism-linked hospitality recovery, while Kenyan informal distributors face acute margin pressure from glass breakage losses.
Supply Chain Analysis
Just-in-time aluminum can sheet procurement dominates Nigerian and Kenyan brewery operations, whereas South African glass bottlers maintain strategic silica sand stockpiles against Northern Cape supply concentration. Raw material flows draw from South Africa's captive silica deposits, Gulf Cooperation Council aluminum smelters, and European ink and coating suppliers for export-compliant labeling. Single-source vulnerability runs through the Northern Cape silica corridor, where freight-cost volatility exposes Nigerian and Kenyan container glass producers to input price swings. Distribution runs through formalizing licensed channels in South Africa, consolidated duty-free procurement in the UAE, and brewery-operated returnable pools in Nigeria that resist one-way packaging substitution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier-coated PET substitution in mid-tier spirits and ready-to-drink cocktails threatens glass incumbents across East African informal retail channels, requiring defensive repositioning around certification barriers and cold-chain partnerships.
For Market Incumbents: Secure captive recycling infrastructure to internalize extended producer responsibility costs before EMEA mandates tighten margin structures for non-integrated converters. Anchor supply relationships through multi-year framework agreements with Rotana and Marriott procurement teams in Dubai, leveraging Emirates Authority for Standardization and Metrology qualification as a switching-cost barrier against aluminum can encroachment in premium spirits. For New Entrants and Emerging Players: Lead with barrier-coated PET pilot programs targeting Kenyan and Tanzanian distributors where glass breakage rates exceed acceptable thresholds in informal retail channels. Capture white-space in UAE duty-free channel formalization by pre-qualifying packaging specifications with Emirates Authority for Standardization and Metrology before legacy trading houses adapt to direct manufacturer engagement models. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because brewery procurement standardization and hospitality group buyer concentration favor scaled converters with regional tolling arrangements and captive raw material access. Target acquisition archetypes include Northern Cape silica-integrated glass producers and North African aluminum can manufacturers with EU REACH export compliance. Watch Nigerian chilled distribution infrastructure buildout as the inflection signal for aluminum can share acceleration versus entrenched returnable glass systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Mining | Captive Northern Cape feedstock insulates Consol Glass from import dependency and freight volatility. |
| CE Marking Pre-Qualification | Early certification with EFSA protocols secures procurement slots as EU REACH compliance disqualifies uncertified Middle Eastern converters. |
| Regional Tolling Arrangements | Localized aluminum can production near Lagos and Ibadan brewery clusters reduces logistics costs and format standardization friction. |
| Direct-to-Glass Digital Printing | Laser engraving eliminates paper labels, reducing material mass and simplifying Gulf Cooperation Council recycling compliance for premium spirits. |
| Duty-Free Channel Formalization | Emirates Authority for Standardization and Metrology qualification creates volume aggregation points at Dubai and Abu Dhabi airport retail. |
Research Methodology
Cross-validation between primary interviews with packaging procurement managers at Nigerian and South African breweries and secondary analysis of EFSA migration testing protocols anchors the qualitative findings on certification timeline compression. Conversations with Consol Glass supply planners, Crown Holdings regional tolling directors, and UAE hospitality group category managers combined with Emirates Authority for Standardization and Metrology import specifications, South Africa's National Regulator for Compulsory Specifications enforcement records, and EU REACH compliance databases enabled bottom-up and top-down triangulation across the value chain.
Sensitivity analysis around tourism recovery trajectories and brewery capacity expansion schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include packaging type, material composition, closure technology, and end-user channel with regional regulatory cluster overlays. CAGRs were derived from installed capacity buildouts, cold-chain investment pipelines, and licensed distribution channel formalization patterns rather than extrapolated historical trends.
The analysis sits within stated boundaries; outcomes outside sustained EMEA regulatory harmonization and Gulf Cooperation Council food-contact standardization would require recalibration. Forecasts reflect assumptions about brewery consolidation timelines, hospitality procurement centralization, and silica sand logistics stability. Revision becomes warranted when Nigerian returnable glass pool depreciation schedules accelerate or UAE duty-free passenger traffic thresholds diverge materially from modeled recovery paths.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market