
 Alcoholic Beverage Packaging Market | 2026-2036
Alcoholic Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Alcoholic Beverage Packaging Market Analysis
The EU Green Deal is decoupling virgin material dependence from packaging economics across European alcoholic beverage supply chains. Crown Holdings leverages its aluminum can technology leadership to capture share in craft beer transitions from glass. Ardagh Group anchors European demand through its specialized lightweight glass furnace network. Amcor plc differentiates via barrier-enhanced sustainable films for premium spirits pouches.
Alcoholic beverage packaging encompasses the engineered containment systems—bottles formed from soda-lime or borosilicate glass, aluminum cans with internal epoxy liners, steel kegs with double-walled construction, and multilayer flexible pouches—designed to preserve organoleptic properties, prevent oxidation, and withstand pasteurization or cold-chain distribution. Glass bottles retain dominance in wine and premium spirits due to inert surface chemistry and established consumer ritual, while aluminum cans represent the fastest-expanding format as craft breweries and ready-to-drink cocktail brands prioritize portability, chill speed, and recycling loop efficiency. Closure systems generate concentrated margin pools, with screw-top and synthetic cork innovations displacing natural cork in mid-tier wine segments.
The EPA regulates manufacturing emissions from glass furnace operations and aluminum smelting feedstock, while the EU F-Gas Regulation constrains blowing agent chemistry in insulation-dependent production. FDA standards govern indirect food-contact materials and migration limits for container liners and closures. ISO 9001 and ISO 14001 certifications function as baseline market-access filters for supplier qualification by multinational beverage manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in closed-loop collection infrastructure or outsource compliance to specialized packaging-as-a-service operators.
Market Dynamics
The EU Green Deal's recycled-content mandates are compressing virgin glass demand and forcing furnace operators to reconfigure batch chemistry around cullet ratios. This regulatory pressure intersects with aluminum can recycling economics to accelerate format substitution in mid-tier beer and ready-to-drink spirits.
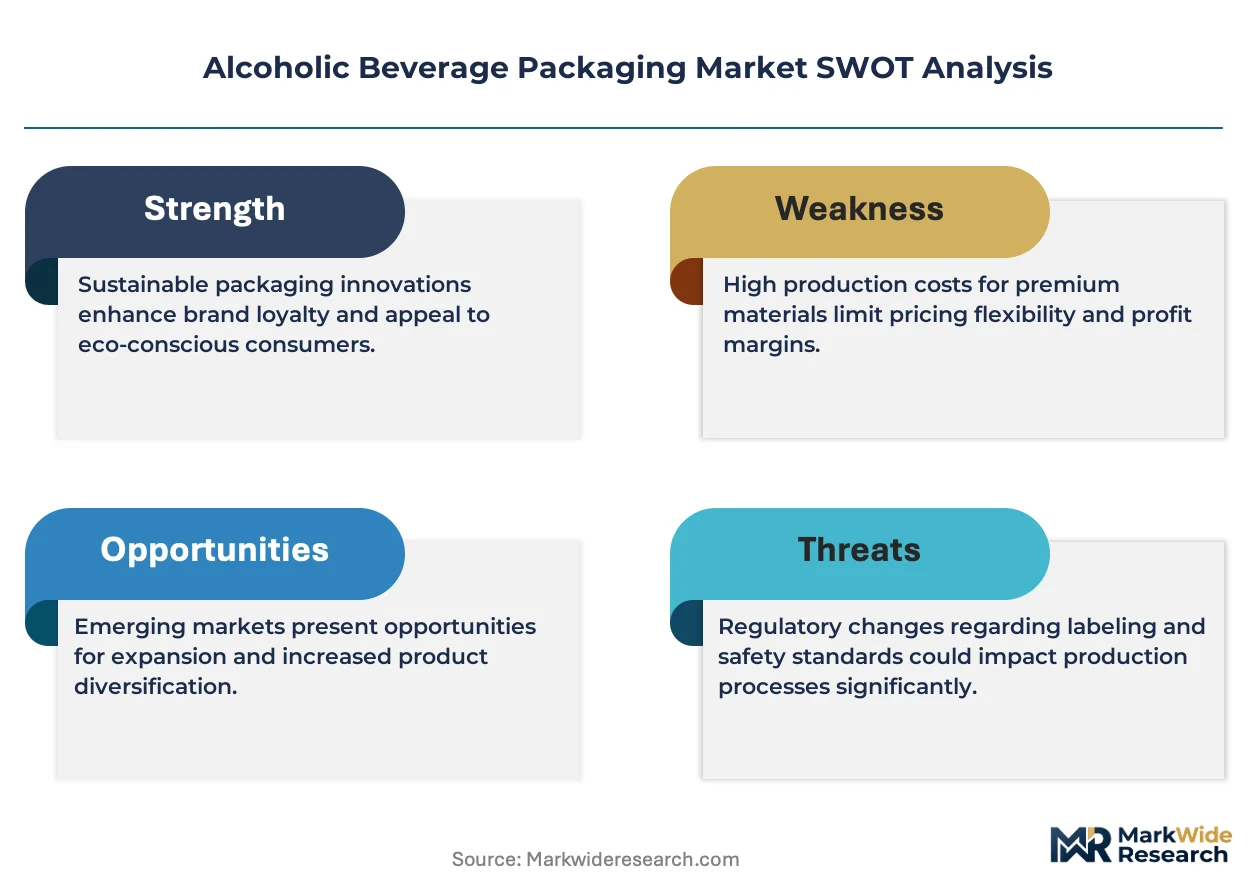
Growth Catalysts
- Lightweight Glass Furnace Technology:Specialized oxy-fuel combustion systems cut energy intensity per ton of container glass. German and French distilleries now specify sub-300 gram standard wine bottles as procurement conditions.
- EU F-Gas Regulation Phase-Down:Constraints on hydrofluorocarbon blowing agents for insulation materials are pushing beverage packaging plants toward vacuum-insulated panel retrofits that reduce cold-chain energy loads.
- Deposit-Return Scheme Expansion:Mandatory container deposit systems in Germany, Lithuania, and Croatia achieve aluminum can recovery rates above 95 percent, tightening closed-loop material availability for European smelters.
Market Restraints
- Natural Gas Price Volatility:Glass furnace operations depend on natural gas for 60-70 percent of thermal energy input. European spot price spikes since 2021 have compressed margins at container glass specialists.
- High-Purity Silica Sand Concentration:Premium container glass requires low-iron silica deposits concentrated in Belgium, Slovakia, and select Spanish quarries. Transportation costs penalize distant furnace locations.
- Epoxy Liner Substitution Limits:Internal can coatings based on bisphenol-A epoxy chemistry face EFSA migration scrutiny. Alternative polyester and vinyl-organosol liners exhibit inferior adhesion during high-acid beverage pasteurization.
Strategic Opportunities
- Premium Spirits Pouch Barrier Films:Metallized polyethylene terephthalate laminates with ethylene vinyl alcohol copolymer cores enable 1.5 liter bag-in-box formats for aged rum and whiskey. Scotch distilleries in Speyside pilot these for duty-free retail channels.
- CSRD-Aligned Packaging-as-a-Service:Extended producer responsibility frameworks in the Netherlands and Austria create revenue pools for logistics operators managing keg pooling and bottle washing at industrial scale.
- Digital Printing on Aluminum:Direct-to-can inkjet systems eliminate label substrate waste and enable lot sizes below 5,000 units. Craft breweries in Denmark and Czechia adopt this for seasonal limited releases.
Industry Challenges
- Color-Sorted Cullet Procurement:Amber and flint glass furnace batches require strict color separation that municipal recycling streams fail to deliver. Container manufacturers must invest in optical sorting infrastructure or accept quality penalties.
- ISO 14001 Certification Timeline:Major beverage manufacturers require environmental management system certification as a supplier qualification gate. Mid-tier packaging converters face 12-18 month implementation cycles with third-party audit backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcoholic Beverage Packaging Market |
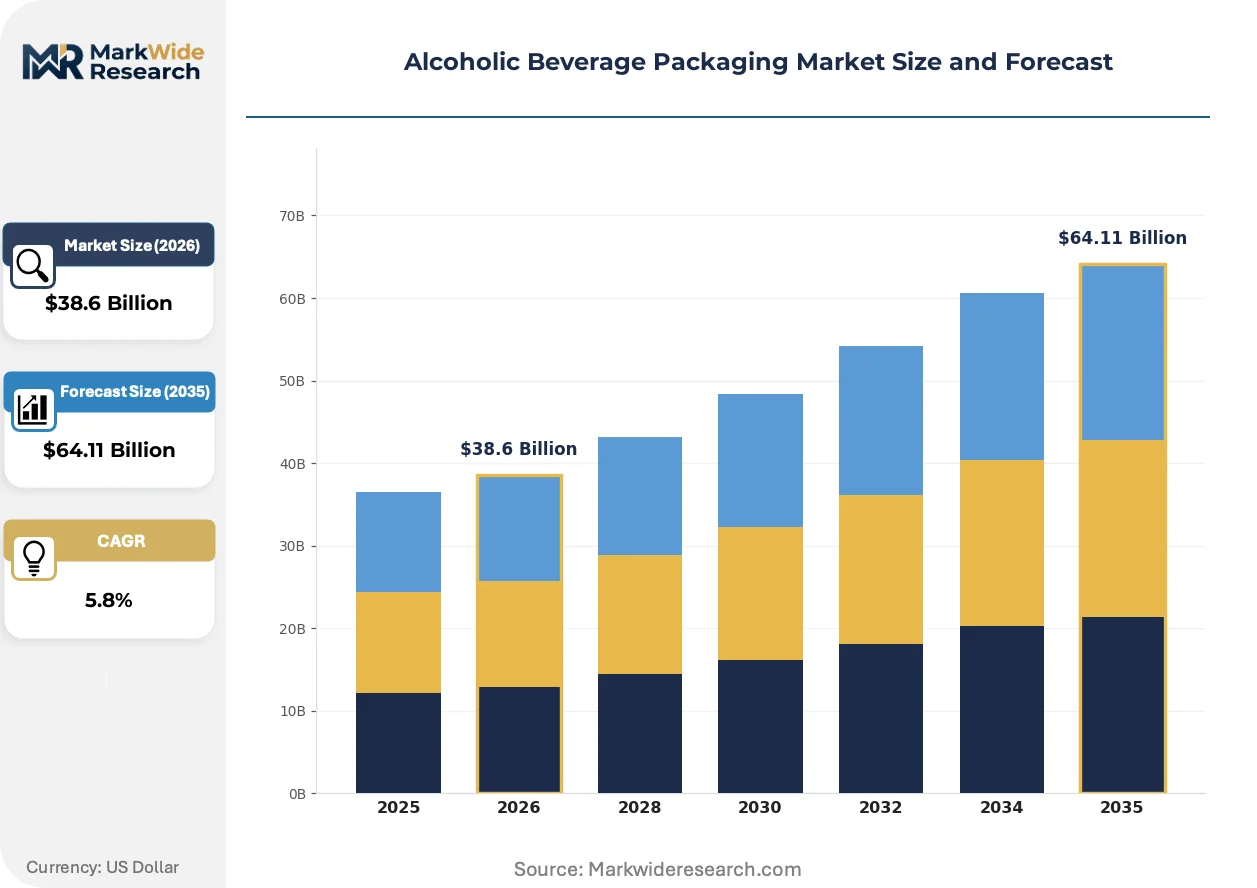
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Kegs, Pouches Material: Glass, Aluminum, Plastic, Cardboard Closure Type: Cork, Cap, Screw Top, Seal End User: Beverage Manufacturers, Distributors, Retailers, Importers |
| Companies Covered | Owens-Illinois, Crown Holdings, Amcor plc, Sonoco Products Company, Berry Global, Ardagh Group, Tetra Pak Group, ProAmpac, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcoholic Beverage Packaging Market Emerging Trajectories
Active packaging intelligence and format hybridization are compressing traditional material boundaries. Regulatory chemistry constraints and consumer portability expectations are jointly determining which containment technologies achieve commercial scale.
Barrier-enhanced flexible films are converging with precision dosing tap systems to enable premium spirits packaging that rivals glass for shelf-life performance while cutting logistics weight by 85 percent. Ready-to-drink cocktail brands in the United Kingdom and Germany specify these laminates for 3-liter festival formats. The technology is compressing the traditional glass monopoly in outdoor and event consumption occasions.
REACH restrictions on per- and polyfluoroalkyl substances are forcing closure liner manufacturers to abandon polytetrafluoroethylene-based barrier coatings. Wine screw-cap producers in Italy and Portugal accelerate migration to tin-saran and aluminum-polyethylene laminates that satisfy EFSA migration limits. Sparkling wine segments face the steepest compliance timeline given pressure retention requirements.
Direct-to-consumer subscription channels are fragmenting traditional wholesale procurement patterns for specialty beer packaging. Microbreweries in Belgium and the United States now order mixed-format assortments—cans, crowlers, and mini-kegs—in single pallet quantities through digital platforms. This pattern is most visible in craft-heavy metropolitan markets where on-premise taproom sales coexist with home delivery logistics.
Alcoholic Beverage Packaging Market Segmentation
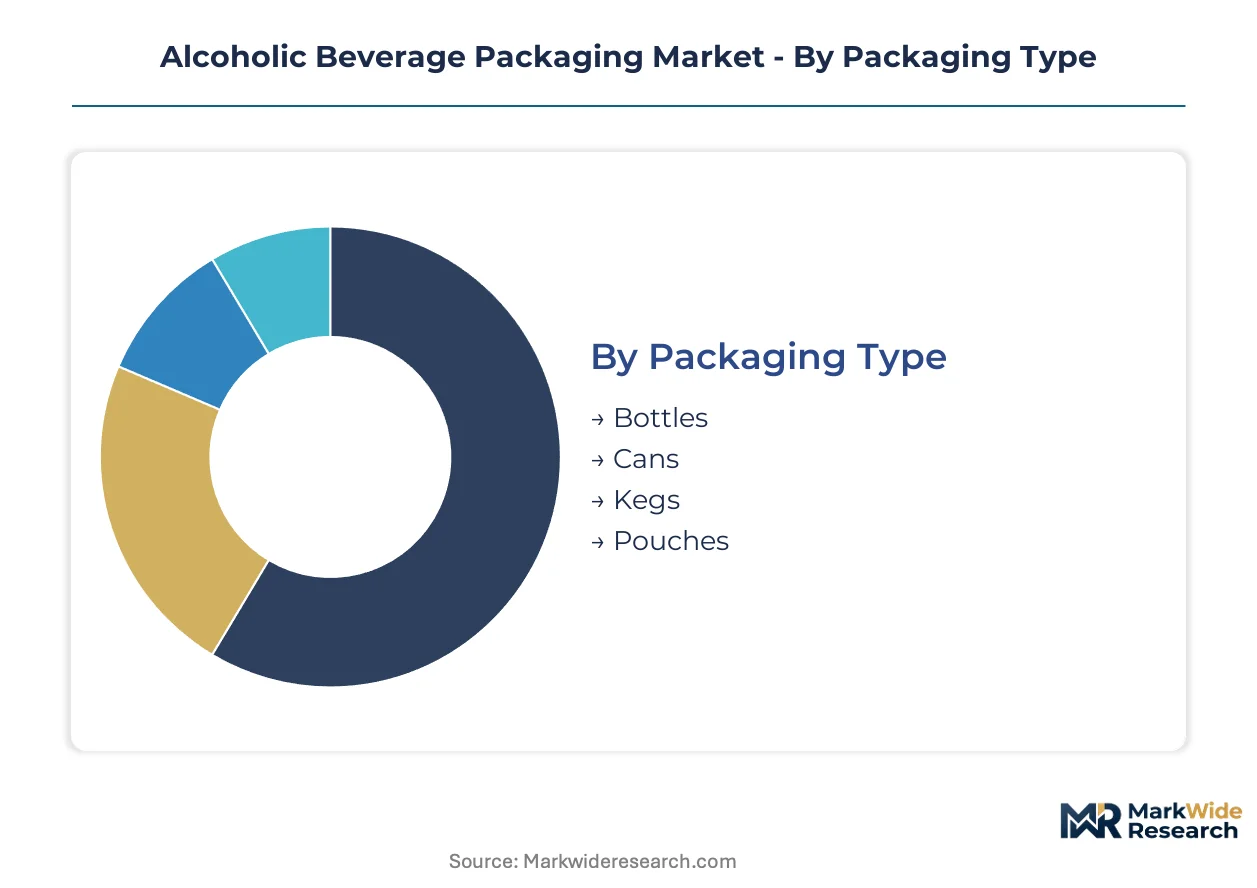
Packaging format selection in alcoholic beverages hinges on the tension between ritual preservation and logistics efficiency. Material chemistry and closure engineering determine shelf-life performance across distribution temperature bands. End-user procurement scale dictates whether suppliers configure for high-volume furnace runs or agile digital-printing workflows.
Packaging Type:
Brand owners prioritize thermal stability and consumer occasion alignment when specifying containment systems for beer, wine, and spirits portfolios.
- Bottles:Soda-lime glass dominates wine and premium spirits due to inert surface chemistry preventing oxidation. German distilleries now mandate sub-300 gram lightweight specifications as procurement conditions to cut transport emissions.
- Cans:Aluminum two-piece containers with internal epoxy liners achieve chill speeds fifteen times faster than glass. Craft breweries in Denmark and Czechia adopt direct-to-can digital printing for seasonal limited releases below 5,000 units.
- Kegs:Double-walled stainless steel construction supports on-premise draft distribution with returnable logistics loops.
- Pouches:Multilayer flexible films with metallized PET barriers enable 1.5 liter bag-in-box formats for aged rum and whiskey in duty-free retail channels.
Volume sits with bottles; growth tilts toward cans.
Material:
Regulatory mandates on recycled content and furnace emissions are compressing virgin material economics across European supply chains.
- Glass:Container glass furnaces in Belgium and Slovakia depend on high-purity low-iron silica deposits concentrated in select quarries. EU Green Deal cullet-ratio mandates force batch chemistry reconfiguration that penalizes distant furnace locations.
- Aluminum:European smelters source from deposit-return schemes in Germany, Lithuania, and Croatia achieving recovery rates above 95 percent. Crown Holdings leverages can technology leadership to capture craft beer transitions from glass.
- Plastic:Barrier-enhanced PET and ethylene vinyl alcohol copolymer laminates serve pouch formats where logistics weight reduction outweighs premium perception constraints.
- Cardboard:Corrugated secondary packaging and outer sleeves support e-commerce subscription channels fragmenting traditional wholesale procurement patterns.
Glass commands installed furnace capacity; aluminum climbs fastest on recycling loop efficiency.
Closure Type:
Pressure retention requirements and migration compliance timelines determine liner chemistry selection across still and sparkling wine segments.
- Cork:Natural cork faces displacement in mid-tier wine segments as screw-top and synthetic alternatives satisfy oxidation prevention at lower unit cost.
- Cap:Crown corks with tin-saran or aluminum-polyethylene laminates replace PTFE-based barrier coatings under REACH restrictions on per- and polyfluoroalkyl substances.
- Screw Top:Aluminum roll-on pilfer-proof closures dominate convenience-oriented still wine formats where ritual preservation matters less than resealability.
- Seal:Heat-induction membranes and tamper-evident bands secure spirits bottles against counterfeiting in high-value distribution channels.
Cork retains heritage positioning; screw tops gain volume on operational simplicity.
End User:
Procurement scale and vertical integration depth shape supplier relationship structures from multinational beverage manufacturers to specialty importers.
- Beverage Manufacturers:Multinational brewers and distilleries require ISO 14001 certification as supplier qualification gates, forcing 12-18 month implementation cycles on mid-tier packaging converters.
- Distributors:Logistics operators managing keg pooling and bottle washing at industrial scale capture revenue pools from extended producer responsibility frameworks in the Netherlands and Austria.
- Retailers:Supermarket chains and on-premise operators specify deposit-return-compatible formats to comply with mandatory container systems.
- Importers:Specialty operators source mixed-format assortments through digital platforms enabling single-pallet orders of cans, crowlers, and mini-kegs for fragmented distribution.
Manufacturers anchor volume commitments; distributors expand fastest on packaging-as-a-service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of alcoholic beverage packaging concentrates in manufacturing clusters with furnace infrastructure and metal forming capacity, while consumption patterns fragment across regulatory jurisdictions with divergent deposit-return schemes and recycled-content mandates.
Germany
Breweries and distilleries anchor packaging innovation clusters in Bavaria and North Rhine-Westphalia, driving demand for sub-300 gram lightweight glass specifications. The country's mandatory container deposit system achieves aluminum can recovery rates above 95 percent, tightening closed-loop material availability for European smelters. Cologne and Munich host specialized oxy-fuel combustion furnace operations that supply standardized procurement conditions to premium spirits producers.
United States
Craft breweries and ready-to-drink cocktail brands prioritize aluminum can portability, accelerating format substitution from glass in mid-tier beer segments. EPA regulations govern manufacturing emissions from glass furnace operations and aluminum smelting feedstock, constraining batch chemistry configurations. Wisconsin and Colorado manufacturing corridors concentrate digital printing adoption for seasonal limited releases below 5,000 units.
France
Champagne and sparkling wine producers face pressure retention requirements that complicate screw-cap liner substitution under REACH restrictions on per- and polyfluoroalkyl substances. EFSA migration scrutiny shapes closure chemistry selection across still and sparkling segments. Reims and Épernay clusters pilot tin-saran laminate alternatives to PTFE-based barrier coatings for crown cork applications.
Italy
Wine screw-cap producers accelerate migration to aluminum-polyethylene laminates as EFSA compliance timelines tighten for sparkling wine segments. Natural cork faces displacement in mid-tier wine categories where synthetic alternatives satisfy oxidation prevention at lower unit cost. Tuscany and Piedmont packaging converters navigate 12-18 month ISO 14001 certification cycles to qualify as multinational beverage manufacturer suppliers.
United Kingdom
Ready-to-drink cocktail brands specify barrier-enhanced flexible films for 3-liter festival formats, compressing glass monopoly in outdoor consumption occasions. CSRD-aligned extended producer responsibility frameworks create revenue pools for logistics operators managing industrial-scale bottle washing. London and Manchester direct-to-consumer subscription channels fragment traditional wholesale procurement patterns for specialty beer mixed-format assortments.
Alcoholic Beverage Packaging Market Vendor Landscape
The competitive structure tilts toward integrated container manufacturers with captive furnace networks and metal forming capacity. Tier-one players command procurement relationships with multinational beverage manufacturers through ISO 14001 certification gates, while mid-tier converters compete on digital printing agility and sub-5,000 unit lot flexibility. Three archetypes dominate: furnace-integrated glass specialists, aluminum can technology leaders, and barrier film laminators. Capacity expansion in lightweight glass and strategic partnerships for closed-loop collection infrastructure represent the dominant competitive moves.
Among North American packaging conglomerates, Owens-Illinois and Crown Holdings exemplify scale-driven furnace and can technology archetypes respectively. Ball Corporation occupies a position within aluminum container manufacturing. European specialists include Ardagh Group, representing furnace-network integration, and Amcor plc, sitting within flexible barrier film laminations. These named entities anchor the supplier landscape without exhausting the competitive set.
| Leading Market Players |
|---|
| Owens-Illinois |
| Crown Holdings |
| Amcor plc |
| Sonoco Products Company |
| Berry Global |
| Ardagh Group |
| Tetra Pak Group |
| ProAmpac |
| Ball Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap glass furnace operators in Belgium and Slovakia anchor supply-side discipline through captive silica sand quarries, translating geological concentration into pricing power over premium spirits producers while insulating batch chemistry from spot energy volatility.
Pricing Analysis
Margin tightening in lightweight glass specifications reflects natural gas price volatility compressing furnace operator returns. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified suppliers from uncertified converters from spot-market cullet traders. Pricing pressure intensifies in mid-tier beer cans as aluminum smelters pass through deposit-return scheme logistics costs. Craft breweries exhibit highest price sensitivity; multinational distilleries absorb premium for sub-300 gram bottle specifications.
Supply Chain Analysis
Regional distribution centers in Cologne and Munich operate hub-and-spoke patterns feeding German brewery clusters. Supply concentrates in Germany, France, and Italy for furnace capacity; Belgium and Slovakia for high-purity silica extraction. Raw material dependencies include low-iron silica sand, primary aluminum ingot, and ethylene vinyl alcohol copolymer resin. Single-source vulnerability sits with Slovakian silica deposits feeding multiple EU furnace networks. Distribution runs through specialized beverage logistics operators managing returnable keg pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-purity silica sand concentration in select quarries props pricing discipline by constraining furnace location flexibility and preserving captive supply advantages for integrated operators.
For Market Incumbents: Deploy oxy-fuel combustion retrofits to defend energy cost position against natural gas volatility. Backward integration into optical cullet sorting infrastructure addresses color-separation quality penalties from municipal recycling streams. Crown Holdings and Ardagh Group anchor this defensive posture through furnace network consolidation. For New Entrants and Emerging Players: Digital direct-to-can inkjet systems offer technology-first wedge into craft brewery seasonal releases below 5,000 units. Target Czechia and Denmark microbreweries through platform-based procurement portals enabling mixed-format single-pallet orders. White-space concentration sits in CSRD-aligned packaging-as-a-service logistics for Dutch and Austrian extended producer responsibility frameworks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier ISO 14001 certification backlog converters in Italy and Portugal facing 12-18 month audit timelines. Long-term viability hinges on aluminum can recycling loop efficiency outpacing glass furnace emissions compliance costs. Watch aluminum spot price spreads against LME futures as inflection indicator for format substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweight Glass Furnace Retrofit | Oxy-fuel combustion cuts energy intensity per ton for German distillery procurement conditions. |
| Closed-Loop Collection Infrastructure | Deposit-return scheme operators capture 95 percent aluminum recovery rates in Germany. |
| Barrier Film Lamination Scale-Up | Metallized PET with EVOH cores enable 1.5 liter duty-free spirits formats for Speyside distilleries. |
| Digital Printing Capability Addition | Direct-to-can inkjet eliminates label waste for Danish craft brewery seasonal releases. |
| Packaging-as-a-Service Partnership | CSRD-aligned logistics operators industrialize keg pooling and bottle washing in Netherlands. |
Methodological Framework
Trade association filings, customs import records, and EU regulatory databases formed the secondary backbone, cross-referenced with primary interviews of furnace operations managers, beverage procurement directors, and closure liner chemists. Bottom-up volume triangulation against top-down value estimates validated segment splits across packaging format, material chemistry, and end-user procurement scale.
Historical trendline analysis of furnace capacity utilization and aluminum can shipment patterns informed projection modeling across the analysis window. Segmentation dimensions included packaging type, material substrate, closure engineering, and geographic regulatory cluster. CAGRs derived from curve-fitting observed substitution rates between glass and aluminum formats, with explicit modeling of EU Green Deal cullet mandate compliance timelines and F-Gas Regulation phase-down impacts on insulation materials.
Several conditions sit outside the modeled scope, including abrupt natural gas price spikes beyond historical volatility bands and unilateral REACH restrictions on epoxy liner chemistries without viable polyester alternatives. Forecasts reflect documented assumptions on furnace energy efficiency trajectories and deposit-return scheme expansion schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market