
 Global Cider Packaging Market | 2026-2036
Global Cider Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cider Packaging Market Intelligence
The adoption of direct-to-shape digital printing technology is reconfiguring how cider brands approach container decoration and market testing. This innovation allows for cost-effective short runs, benefiting craft producers and seasonal product launches. Ball Corporation leverages its expertise in aluminum can manufacturing to offer these advanced printing options. Ardagh Group competes by providing a diverse portfolio of glass and metal packaging solutions, while Crown Holdings, Inc. specializes in supporting large-volume cider producers with efficient can lines.
Cider packaging comprises the primary containers and materials engineered to preserve the quality, carbonation, and flavor of fermented apple or pear beverages. These solutions must provide a barrier against light and oxygen ingress while ensuring structural integrity during transport. Glass bottles and aluminum cans dominate the material segment, with cans gaining share due to lower shipping weights and higher recycling rates. While bottles remain the standard for premium offerings, cans represent the fastest-growing packaging type, particularly for multi-packs in the retail channel.
Regulatory frameworks like the EU's Packaging and Packaging Waste Regulation and the US FDA's food contact material standards directly influence material selection. These rules mandate specific recycling targets and safety certifications, shaping design choices for all market participants. Producers must balance consumer preference for convenience and premium aesthetics with the escalating pressure for sustainable and circular packaging formats.
Market Dynamics
The central dynamic shaping cider packaging is the direct conflict between the marketing imperative for unique, premium branding and the regulatory push for standardized, easily recyclable materials. This tension forces producers to innovate within the constraints of circular economy frameworks, balancing aesthetic appeal with sustainability mandates from bodies like the EU.
Growth Catalysts
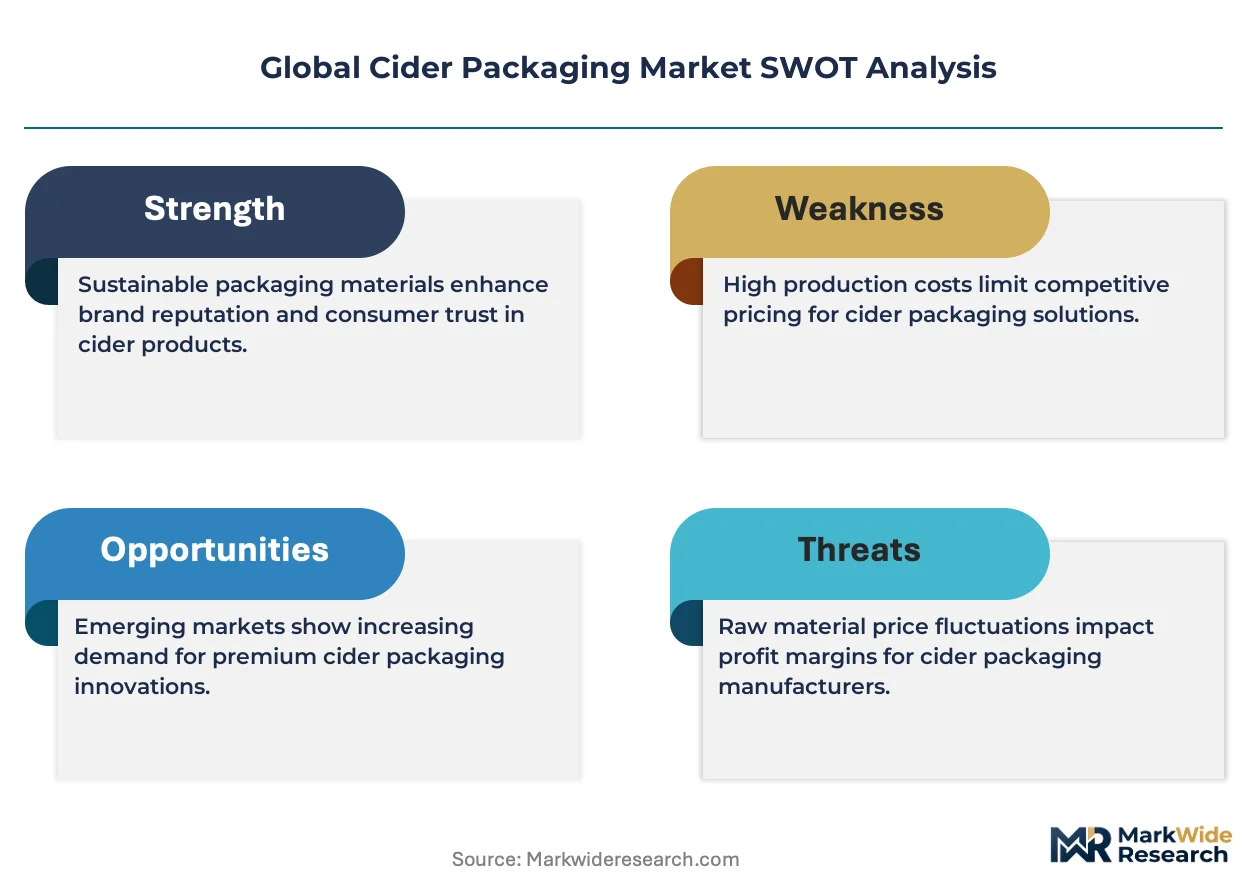
- Craft Segment Expansion:The proliferation of craft and artisanal cideries creates demand for distinctive, small-batch packaging solutions that can communicate a premium brand story on crowded retail shelves.
- Regulatory Tailwinds for Recyclability:Mandates like the EU's Packaging and Packaging Waste Regulation favor materials with established recycling streams, boosting the market share of aluminum cans and glass bottles over less circular alternatives.
- Logistical Advantages of Cans:Aluminum cans offer lower shipping weights, reduced breakage, and superior stacking efficiency compared to glass, providing significant cost savings in transportation and distribution for producers.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the global prices of aluminum and energy required for glass manufacturing create margin pressure and sourcing instability for packaging converters and cider producers.
- Glass Weight and Fragility:The inherent weight and breakability of glass bottles increase transportation costs, limit shipping distances, and contribute to product loss throughout the supply chain.
- Substitution from Other Beverages:Cider competes for shelf space and consumer attention with a growing array of packaged alcoholic beverages, including hard seltzers and ready-to-drink (RTD) cocktails, which often use similar packaging formats.
Strategic Opportunities
- Emerging Market Penetration:There is a significant opportunity to introduce cider in diverse packaging formats to developing alcoholic beverage markets, particularly in urban centers across Asia-Pacific and Latin America.
- Smart Packaging Integration:Incorporating QR codes or NFC tags into packaging designs allows brands to connect directly with consumers, offering provenance details, food pairing suggestions, or promotional content.
- E-commerce Channel Optimization:Designing robust, lightweight, and visually appealing multi-packs specifically for the direct-to-consumer online retail channel can capture a growing segment of at-home consumption.
Industry Challenges
- Supply Chain Complexity:Managing a dual supply chain for both glass bottles and aluminum cans introduces significant logistical and inventory management challenges for cider producers of all sizes.
- Regulatory Compliance Burden:Adhering to evolving food contact safety standards from regulators like the US FDA and Europe's EFSA requires continuous investment in material testing and compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cider Packaging Market |
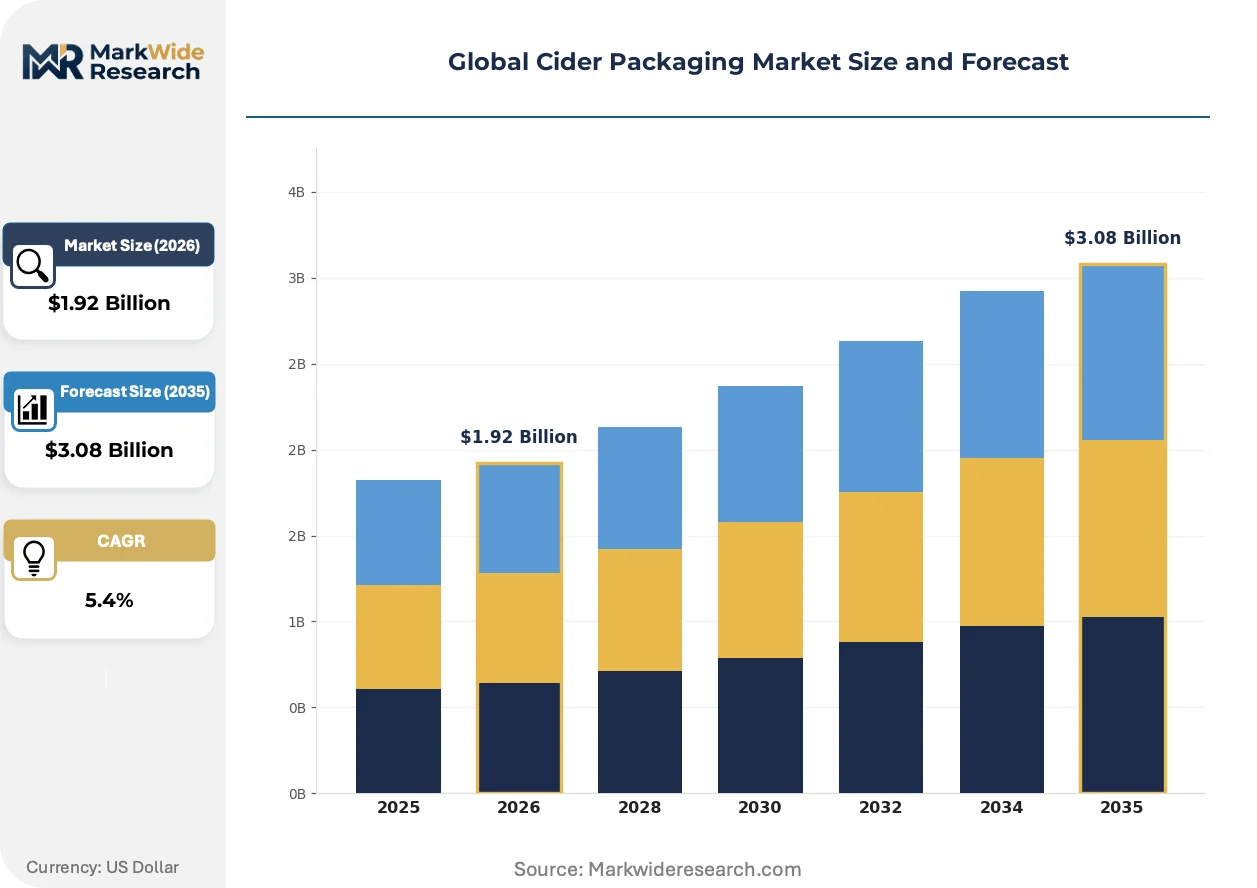
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.08 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottle, Can, Tetra Pak, Keg, Carton Material: Glass, Aluminum, Plastic, Composite, Steel Application: Retail, On-Trade, Events, E-Commerce, Direct Sales Customer Type: Cider Breweries, Distributors, Hospitality Chains, Specialty Retailers |
| Companies Covered | Ardagh Group, Ball Corporation, Crown Holdings, Inc., O-I Glass, Smurfit Kappa Group, Silgan Holdings Inc., WestRock Company, Vidrala, CANPACK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cider Packaging Market Strategic Shifts & Innovations
Digitalization of container decoration and a strong regulatory push towards material circularity are the primary forces defining innovation. These trends compel a re-evaluation of traditional packaging design, prioritizing both sustainability metrics and the ability to execute rapid, targeted marketing campaigns through the package itself.
Direct-to-shape digital printing applies high-resolution graphics onto cans and bottles without requiring a separate label. Craft cider producers and brands launching seasonal varieties are the primary adopters, using it for cost-effective short production runs. This technology is virtualizing the prototyping and market-testing process, which dramatically reduces the time and expense needed to bring new brand concepts to retail.
The EU's Packaging and Packaging Waste Regulation (PPWR) is establishing aggressive targets for recycled content inclusion and overall material circularity. This directive forces cider companies and their suppliers to prioritize mono-material designs and enhance the recyclability of every component, from crowns to closures. The glass bottle segment is particularly affected, facing intense pressure to increase post-consumer recycled (PCR) content and improve collection infrastructure.
A significant behavioral shift is the consumer pivot towards multi-pack formats, especially for aluminum cans sold through large retail and convenience store channels. This trend is displacing the purchase of single, large-format glass bottles from specialty stores for many consumption occasions. This consumption pattern is most visible in mature cider markets, including the United Kingdom and the United States.
Global Cider Packaging Market Segmentation
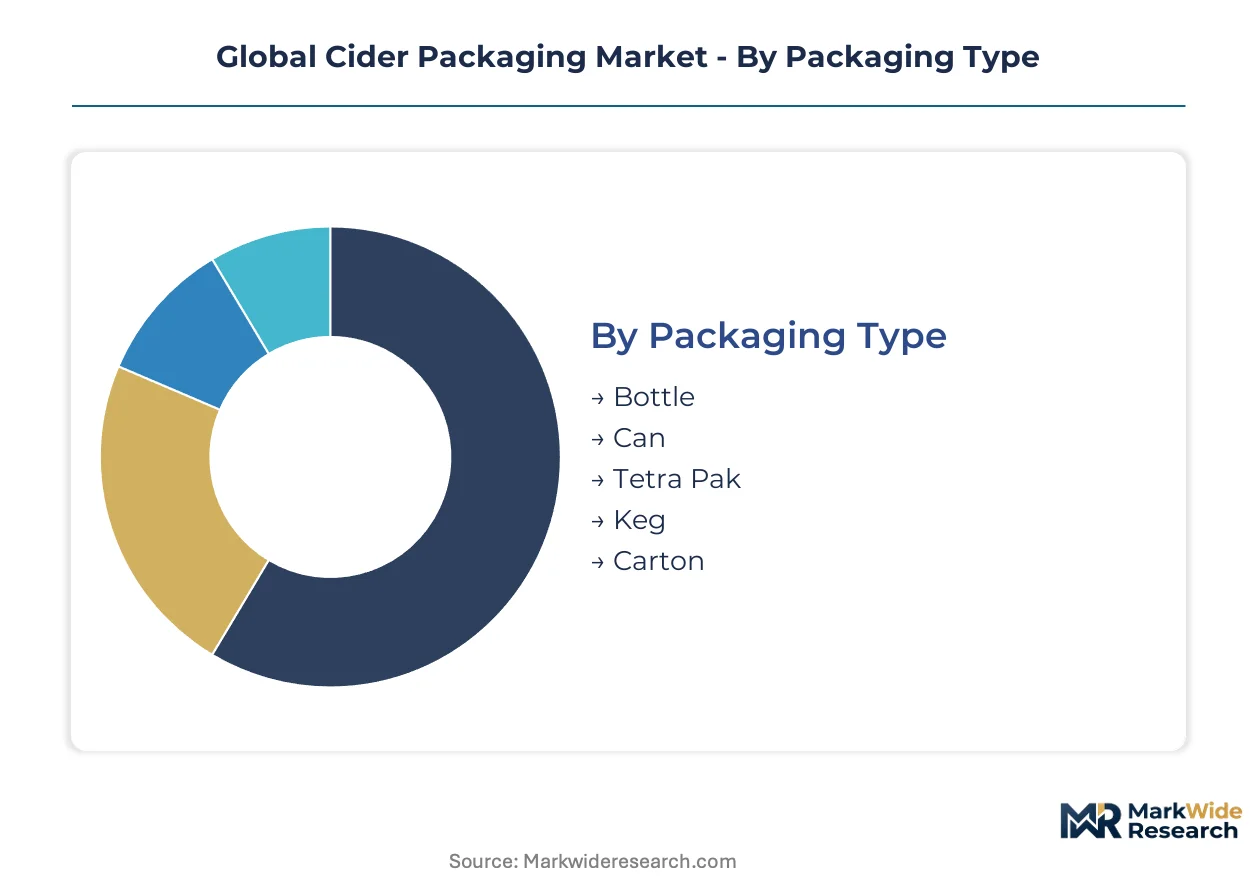
Segmentation analysis provides a granular understanding of the Global Cider Packaging Market, revealing distinct consumer preferences, material demands, and channel-specific requirements. This detailed breakdown helps producers and packaging suppliers align their strategies with evolving market dynamics and regulatory pressures.
Packaging Type:
The packaging type spectrum reflects varied consumption occasions and logistical requirements for cider products.
- Bottle:Glass bottles remain a standard for premium cider offerings, providing excellent barrier properties against light and oxygen ingress, crucial for flavor preservation. Their heavier weight and fragility increase transportation costs and limit shipping distances, especially for export markets.
- Can:Aluminum cans offer significant logistical advantages, including lighter weight, reduced breakage, and superior stacking efficiency for multi-packs in retail channels. Cans provide a complete light and oxygen barrier, contributing to longer shelf life and are highly recyclable, aligning with circular economy goals.
- Tetra Pak:These composite cartons are primarily used for non-carbonated or lower-alcohol cider products, offering lightweight and space-efficient packaging solutions.
- Keg:Large-format kegs are essential for on-trade consumption, supplying bars, restaurants, and events with bulk cider for draught service.
- Carton:Paperboard cartons, often lined with plastic or foil, serve as an alternative for bag-in-box or multi-pack secondary packaging, prioritizing cost-effectiveness and transport.
Established volume favors Bottles; emerging adoption favors Cans.
Material:
Material choices are increasingly driven by sustainability mandates and consumer demand for circular formats.
- Glass:Glass is a traditional material valued for its inertness, premium aesthetic, and high recyclability, particularly in established markets like the United Kingdom. Regulatory frameworks like the EU's Packaging and Packaging Waste Regulation push for increased post-consumer recycled content in glass bottles.
- Aluminum:Aluminum offers excellent barrier properties, lightweight characteristics, and a high recycling rate globally, making it a preferred material for cans. The demand for aluminum is boosted by its lower shipping weights and superior performance in e-commerce channels.
- Plastic:Plastic packaging, such as PET bottles, offers lightweight and shatterproof alternatives, though its use in cider is limited due to carbonation retention challenges and lower recycling rates compared to glass and aluminum.
- Composite:Composite materials combine different layers, often found in Tetra Pak formats, to achieve specific barrier properties for extended shelf life.
- Steel:Steel is primarily used for larger format kegs, providing robust and reusable containers for bulk cider distribution to hospitality venues.
Aluminum's recyclability advantages propel its expansion, while glass maintains its premium market position.
Application:
Cider packaging applications span diverse sales channels, each presenting unique demands for convenience and brand visibility.
- Retail:The retail segment encompasses supermarkets, hypermarkets, and convenience stores, where multi-packs, particularly aluminum cans, dominate sales. Packaging designs here focus on shelf appeal and consumer convenience.
- E-Commerce:Online retail requires robust, lightweight, and easily shippable packaging formats that can withstand transit. Multi-packs optimized for direct-to-consumer delivery are gaining traction in this channel.
- On-Trade:This segment includes bars, pubs, restaurants, and hotels, primarily served by kegs and single-serve bottles for immediate consumption.
- Events:Festivals, concerts, and sports events demand portable and often single-serve packaging solutions, with cans increasingly preferred for their safety and ease of disposal.
- Direct Sales:Cider producers selling directly from their premises or through farmers' markets often use packaging that emphasizes artisanal quality and local provenance.
Retail channels dominate current sales volumes, with e-commerce showing significant growth potential.
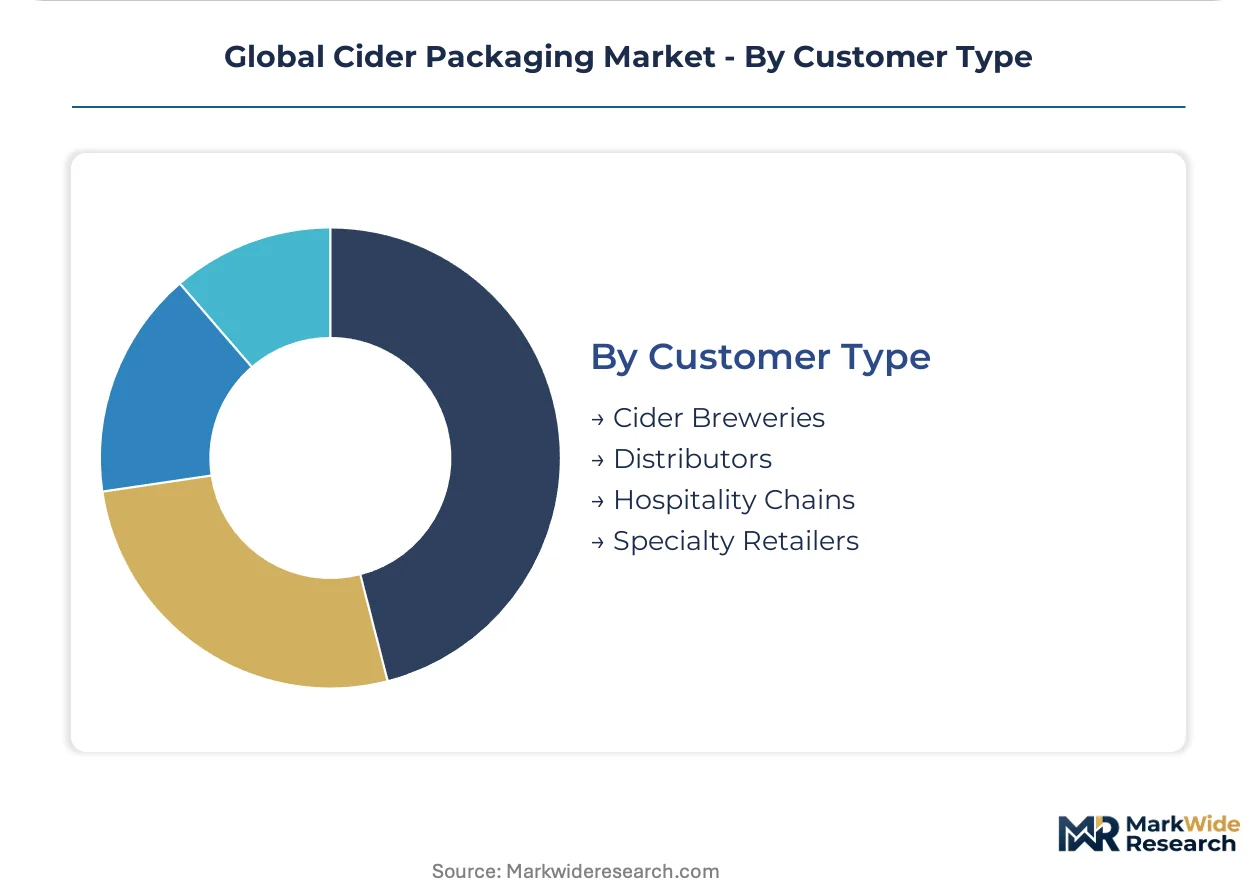
Customer Type:
Different customer types necessitate distinct packaging solutions, ranging from high-volume industrial needs to specialized craft requirements.
- Cider Breweries:These are the primary end-users, ranging from large-scale industrial producers requiring efficient can lines to craft cideries needing flexible, short-run digital printing solutions.
- Distributors:Distributors manage the logistics and supply chain for cider products, requiring packaging that is robust, stackable, and optimized for bulk transportation.
- Hospitality Chains:These include hotel groups, restaurant chains, and pub groups that purchase cider in formats suitable for on-premise consumption, often in kegs or individual bottles.
- Specialty Retailers:Independent bottle shops and gourmet food stores often stock premium and craft ciders, favoring aesthetically pleasing glass bottles with unique branding.
Cider Breweries represent the primary purchasers, with Distributors managing the extensive supply chain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cider packaging market's regional dynamics are shaped by where cider breweries and their distribution networks are most concentrated. This concentration drives demand for packaging solutions tailored to local consumer preferences and regulatory frameworks. Established markets often prioritize premium aesthetics, while emerging regions focus on cost-effective, scalable formats.
United Kingdom
Demand for multi-pack cans is high, driven by retail channels and consumer preference in the United Kingdom. The UK government's packaging waste regulations promote materials with established recycling streams. London and the West Country represent significant cider production hubs, driving innovation in sustainable packaging.
United States
Craft cider breweries in the United States create demand for unique branding and flexible short-run packaging solutions. The US FDA's food contact material standards directly influence material selection for packaging safety. The Pacific Northwest and New York State cider regions show strong adoption of advanced digital printing technologies.
Germany
Germany's market for cider packaging emphasizes recyclability and high-quality glass for traditional Apfelwein products. The EU's Packaging and Packaging Waste Regulation mandates specific recycling targets for packaging materials here. The Frankfurt region, a center for Apfelwein production, sees consistent demand for premium bottle formats.
China
Emerging market penetration in China presents opportunities for diverse cider packaging formats, especially in urban centers. China's dual carbon goals are driving material choices towards more sustainable options. Shanghai and Beijing's metropolitan areas are experiencing growth in packaged alcoholic beverage consumption.
Brazil
Brazil's growing alcoholic beverage market offers potential for cider, requiring lightweight and robust packaging for distribution. The country's environmental regulations increasingly favor recyclable materials to reduce waste. São Paulo and Rio de Janeiro, as major urban hubs, show rising interest in convenient, single-serve formats.
Global Cider Packaging Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure. The market sees large, integrated packaging manufacturers alongside smaller, agile providers focusing on niche solutions. Strategic archetypes include global material suppliers, regional converters, and specialized printing firms. Dominant competitive moves involve capacity expansion in aluminum can lines and strategic partnerships for advanced printing technologies.
On the global supplier vector, Ball Corporation exemplifies large-scale aluminum can manufacturing, offering advanced printing options. Ardagh Group, a diversified European-headquartered entity, occupies a position providing a broad portfolio of glass and metal packaging solutions. Crown Holdings, Inc., another major player, anchors the segment for large-volume cider producers with efficient can lines. These companies represent the industrial backbone of cider packaging supply.
| Leading Market Players |
|---|
| Ardagh Group |
| Ball Corporation |
| Crown Holdings, Inc. |
| O-I Glass |
| Smurfit Kappa Group |
| Silgan Holdings Inc. |
| WestRock Company |
| Vidrala |
| CANPACK |
Cost & Logistics Intelligence
The West Country's concentrated cider production capacity directly influences packaging procurement costs, particularly for smaller craft breweries. This regional supply dynamic establishes a baseline for broader market pricing.
Pricing Analysis
Cost-plus contracts, often indexed to aluminum or glass commodity prices, dominate packaging procurement for large-volume cider producers. Price differentiation stems from order volume scale and the complexity of direct-to-shape digital printing customization. Pricing softness in standard formats reflects intense competition from hard seltzers and RTD cocktails. Craft cideries, prioritizing brand premium and unique aesthetics, demonstrate lower price sensitivity compared to large industrial buyers.
Supply Chain Analysis
Raw material price volatility for aluminum and silica sand dominates the cider packaging supply chain, impacting converters globally. Geographic supply concentration for glass production centers in Germany and for aluminum can manufacturing in North America. Key dependencies include energy for glass melting and specialized coatings for can linings. Distribution runs through multi-tier networks, from large packaging manufacturers to regional distributors serving smaller cideries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cider packaging market experiences a buyer-power shift, driven by the increasing consolidation of large retail chains. These powerful buyers dictate terms for multi-pack formats and sustainable material sourcing.
For Market Incumbents: Harden strategic partnerships with key raw material suppliers to mitigate commodity price volatility. Invest in next-generation direct-to-shape digital printing technologies to counter the threat from agile niche printing firms. Expand aluminum can manufacturing capacity in emerging markets like Asia-Pacific to capture new growth. Control over advanced printing capabilities represents a critical lever against margin erosion from standardized packaging.
For New Entrants and Emerging Players: Pursue specialized packaging solutions for the craft cider segment, offering highly customizable, short-run digital printing services. The e-commerce channel for multi-packs presents the most penetrable segment, demanding robust and lightweight designs. A go-to-market angle focused on rapid prototyping and sustainable material options will differentiate new players. Target regional craft brewery clusters in the United States and the United Kingdom.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because scale economies in material sourcing and manufacturing capacity are paramount. Acquisition targets should be mid-sized regional converters with strong intellectual property in advanced printing or sustainable material processing. The signal to watch is the increasing market share of aluminum cans, particularly in multi-pack formats, indicating a shift in consumer preference and logistical efficiencies. Focus on companies with established recycling infrastructure partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion: Aluminum Can Lines | Increases supply for the fastest-growing packaging type, supporting retail multi-pack demand. |
| Advanced Digital Printing Investment | Enables cost-effective short runs and unique branding for craft and seasonal cider products. |
| Sustainable Material Sourcing Partnerships | Ensures compliance with EU's Packaging and Packaging Waste Regulation and consumer preferences. |
| E-commerce Optimized Packaging Development | Captures growth in direct-to-consumer online sales by providing robust, lightweight solutions. |
| Regional Converter Acquisition | Expands geographic footprint and strengthens local supply chains for specialized packaging needs. |
Research Approach
A spread of perspectives from cider brewery executives, packaging procurement leads, material suppliers, and retail channel managers converged on the working assumptions for this study. Primary interviews validated market dynamics, complemented by secondary research from regulatory bodies like the US FDA and Europe's EFSA. Trade association reports and company financial disclosures provided further quantitative context. This approach ensured bottom-up and top-down triangulation.
Demand-supply balance models informed the quantitative forecast across the analysis window, integrating market growth drivers with production capacities. Segmentation dimensions included packaging type, material, application, and customer type, alongside regional consumption patterns. Compound Annual Growth Rates (CAGRs) derived from historical trends and projected market shifts. Key forecast inputs included raw material price projections and regulatory mandates.
Macroeconomic conditions sit as an overlay; deviation in global commodity prices or consumer spending would shift the trajectory of market expansion. Forecasts reflect assumptions documented through primary and secondary research. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market