
 Beer Packaging Market | 2026-2036
Beer Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Packaging Market Analysis
ISO 18601 sustainable packaging management certification is rotating competitive access across the beer packaging supply chain, with only converters meeting lifecycle audit thresholds qualifying for multinational brewery tenders. Amcor leverages integrated film and rigid plastic operations to capture pouch and shrink-wrap demand in emerging markets. Ball Corporation anchors North American aluminum can supply through dedicated beverage can capacity expansions. Crown Holdings competes on decorated steel and aluminum closure systems tied to premium brand portfolios.
Beer packaging encompasses primary and secondary containment systems engineered to preserve carbonation, block UV degradation, and withstand pasteurization thermal cycles between 60°C and 70°C. Glass bottles dominate premium positioning due to inert chemistry and infinite recyclability, while aluminum cans lead volume growth through lightweight logistics and chilled distribution efficiency. The material segment stratifies by performance tier: aluminum captures share in outdoor and stadium channels, glass holds ground in craft and import positioning, and cardboard secondary packs gain traction in e-commerce multipacks. Closure type innovation concentrates in screw-cap bottles for convenience retail, displacing traditional crown caps in specific consumption occasions.
The U.S. EPA guides container deposit legislation and recycling rate targets that reshape aluminum and glass collection economics across state programs. The EU F-Gas Regulation and Packaging and Packaging Waste Directive impose recycled content minimums and extended producer responsibility fees that elevate compliance costs for imported formats. China's SAMR enforces GB standards for food-contact materials that govern glass and metal imports. Stakeholders must monitor how deposit-return scheme expansions and recycled-content mandates alter material cost structures and regional sourcing decisions.
Market Dynamics
Aluminum can capacity expansions and EU Green Deal compliance deadlines are compressing converter margins while rerouting procurement toward certified sustainable suppliers. The structural pivot from glass to lighter formats is reshaping logistics networks and brewery capital allocation simultaneously.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Mandatory recycled content minimums for aluminum and glass are pulling converters toward ISO 18601 certification to qualify for multinational brewery tenders.
- Stadium and outdoor channel expansion:Aluminum can demand concentrates in sports venue concessions and festival circuits where lightweight logistics and chilled distribution efficiency dominate.
- Craft brewery scaling:Premium positioning requirements across North America and Europe are sustaining glass bottle volumes for import and craft portfolios despite material cost premiums.
Market Restraints
- Aluminum ingot price volatility:Raw material cost swings compress converter margins and complicate long-term contract pricing with mega-breweries.
- Supply concentration in beverage can manufacturing:North American capacity is anchored by a limited converter base, creating allocation risk during peak summer demand windows.
- Glass furnace energy intensity:Natural gas dependency and carbon border adjustment exposure elevate European glass packaging costs relative to aluminum alternatives.
Strategic Opportunities
- E-commerce multipack formats:Cardboard secondary packs and shrink-wrapped configurations are capturing direct-to-consumer brewery channels previously dominated by retail case packs.
- Screw-cap bottle convenience retail:Crown cap displacement in specific consumption occasions opens closure system innovation for premium brand portfolios.
- Deposit-return scheme expansion:State-level container deposit legislation across the United States is improving aluminum and glass collection economics and circular feedstock access.
Industry Challenges
- ISO 18601 lifecycle audit timelines:Certification delays are blocking converter access to multinational brewery tenders and compressing qualification windows.
- Legacy pasteurization equipment compatibility:Thermal cycle requirements between 60°C and 70°C constrain material experimentation and slow format transitions.
- Extended producer responsibility fee structures:Compliance cost allocation disputes between brewers and converters are prolonging contract negotiations and souring supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Packaging Market |
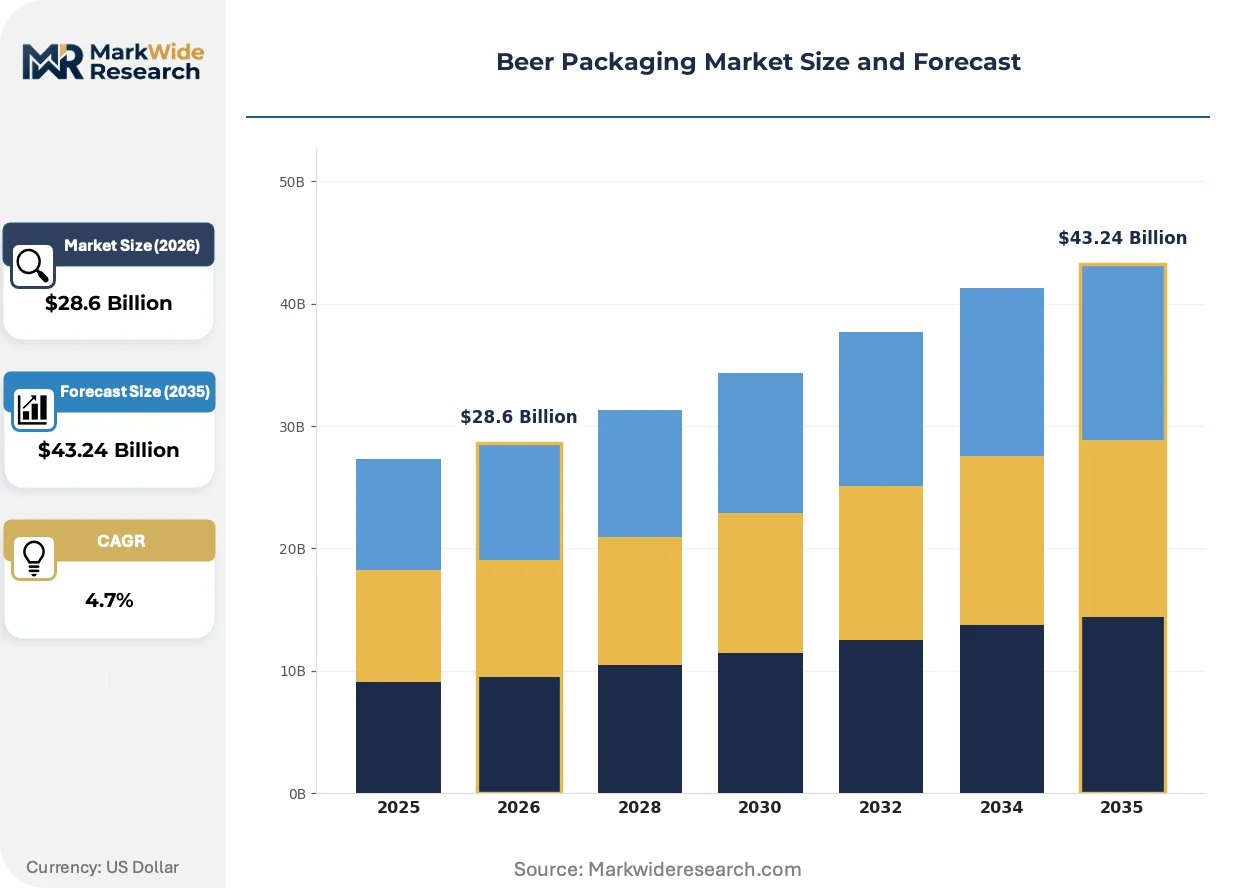
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Kegs, Pouches Material: Glass, Aluminum, Plastic, Cardboard Form: Rigid, Flexible, Semi-Rigid, Composite Closure Type: Crown Caps, Screw Caps, Flip Tops, Others |
| Companies Covered | Amcor, Ball Corporation, Ardagh Group, Crown Holdings, WestRock Company, Smurfit Kappa, Owens-Illinois, Berry Global, Graphic Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Packaging Market Emerging Trajectories
Material science advances and regulatory compliance automation are fragmenting traditional converter specializations. The competitive boundary between rigid and flexible packaging is dissolving as breweries demand format-agnostic sustainability credentials.
Lightweighting technology in aluminum can manufacturing is bifurcating the premium and mass-market tiers. Mega-breweries are adopting sub-12-gram can bodies to reduce logistics costs and carbon footprints. This engineering trajectory is compressing commodity can margins while opening specialty alloy premiums for craft positioning.
REACH and F-Gas Regulation compliance automation is forcing converter IT infrastructure upgrades across European operations. Lifecycle tracking software investments are becoming tender prerequisites. German and Belgian breweries are penalizing suppliers lacking real-time carbon footprint verification.
Buyer consolidation among multinational brewers is compressing switching cycles and unbundling after-sales service contracts. Procurement teams are demanding outcome-based packaging performance guarantees rather than unit-price agreements. This behavioral shift is most visible in Mexico and the United States where mega-brewery procurement functions have centralized.
Beer Packaging Market Segmentation
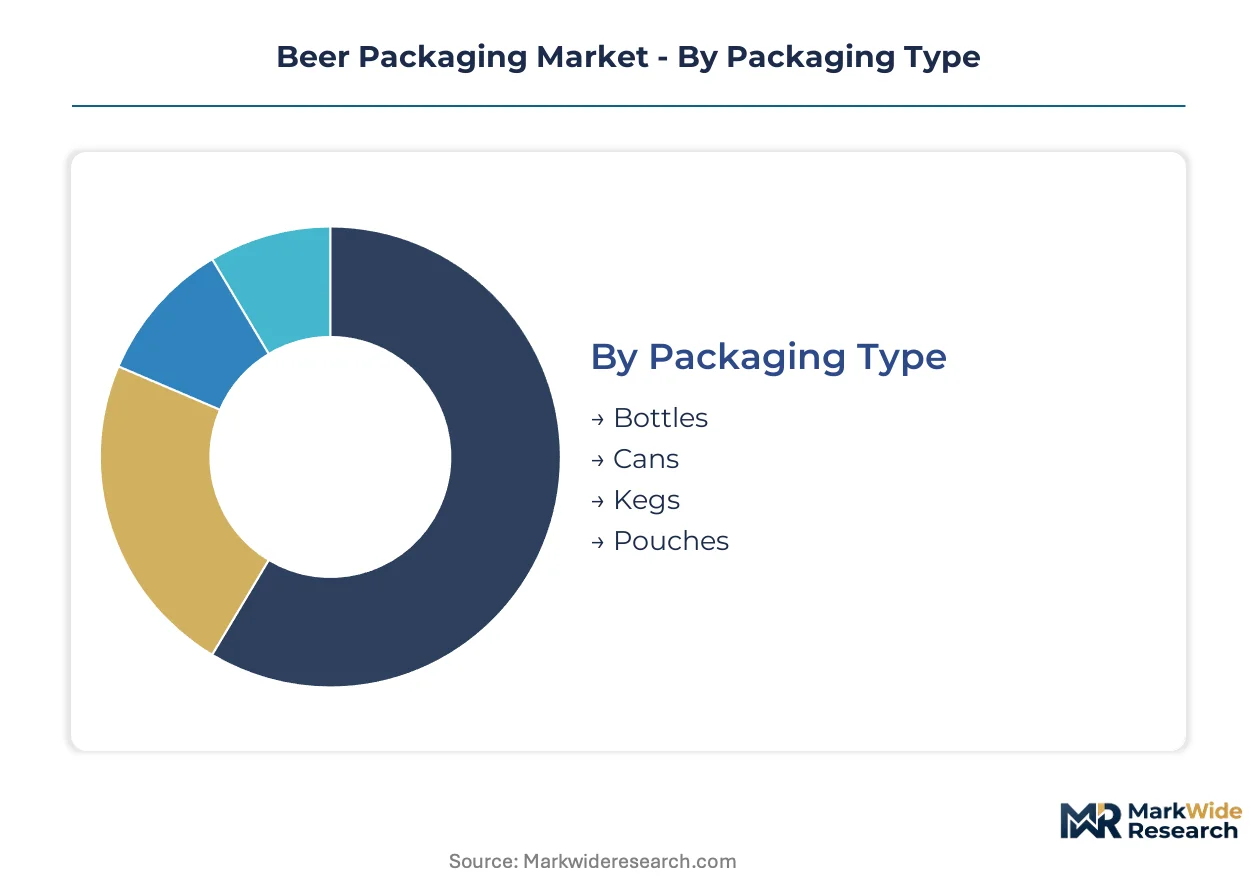
Beer packaging segmentation tracks how format choices cascade through distribution economics and regulatory compliance. Material and closure specifications determine pasteurization compatibility, recycling economics, and channel access across stadium, retail, and direct-to-consumer routes.
Packaging Type:
Bottles flow through premium retail and import channels, while cans dominate outdoor and stadium concessions where lightweight logistics matter most.
- Bottles:Glass construction delivers inert chemistry for craft and import positioning. Demand concentrates in Germany and Belgium where traditional brewing heritage sustains premium formats despite aluminum cost advantages.
- Cans:Aluminum bodies below 12 grams enable chilled distribution efficiency and carbon footprint reduction. Ball Corporation and Crown Holdings are expanding North American capacity to capture stadium and festival circuit growth.
- Kegs:Stainless steel and aluminum kegs serve on-premise draft systems with returnable logistics.
- Pouches:Flexible film formats target outdoor recreation and single-serve convenience retail.
Bottles dominate installed base. Cans are where expansion concentrates.
Material:
Cost tiers separate premium positioning from mass-market logistics, with energy intensity and recycled-content mandates reshaping procurement decisions.
- Glass:Infinite recyclability sustains craft brewery preference despite furnace energy intensity. EU carbon border adjustments are elevating European glass costs relative to aluminum alternatives.
- Aluminum:Lightweight logistics and deposit-return scheme economics drive volume leadership. The EU Packaging and Packaging Waste Directive mandates recycled content minimums that favor established smelter relationships.
- Plastic:PET and barrier films serve shrink-wrap multipacks and emerging pouch formats.
- Cardboard:Secondary pack demand is climbing fastest in e-commerce multipacks and direct-to-consumer brewery channels.
Glass anchors premium positioning. Aluminum is climbing the fastest on volume metrics.
Form:
Structural rigidity determines pasteurization thermal cycle compatibility and logistics stacking efficiency across distribution networks.
- Rigid:Glass bottles and aluminum cans withstand 60°C to 70°C pasteurization without deformation. This specification locks in material choices for breweries with legacy thermal processing equipment.
- Flexible:Film-based pouches and wraps reduce shipping cube and enable direct-to-consumer formats. Amcor and similar converters are capturing emerging market demand through integrated film operations.
- Semi-Rigid:Composite cans and bag-in-box configurations occupy niche positions in catering and event channels.
- Composite:Multi-material laminates balance barrier performance with sustainability credentials.
Rigid formats command installed capacity. Flexible configurations are gaining share fastest in emerging channels.
Closure Type:
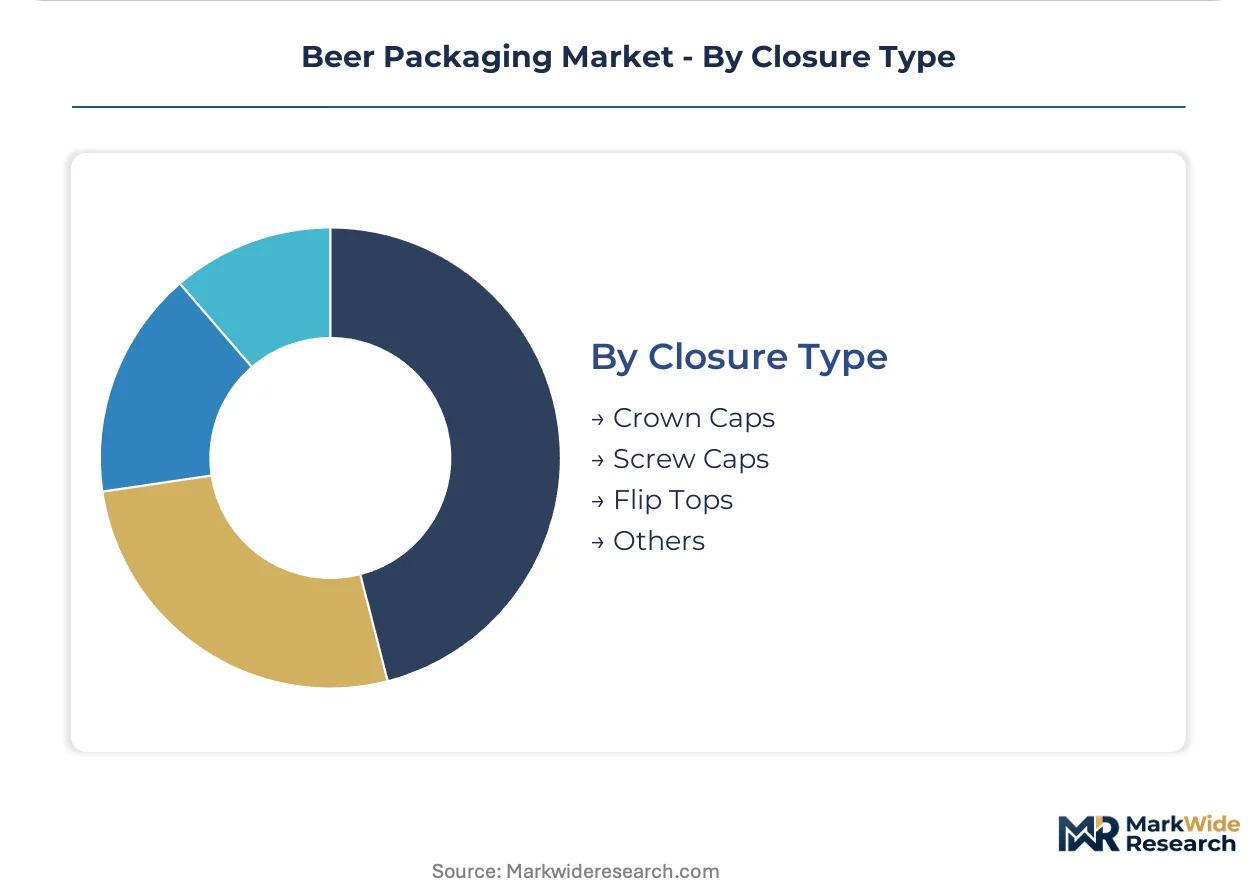
Convenience retail and consumption occasion differentiation are displacing traditional sealing methods in specific premium segments.
- Crown Caps:Pressed steel with liner compound remains standard for mass-market bottles and deposit-return schemes. German and Mexican mega-breweries anchor volume demand through established capping lines.
- Screw Caps:Aluminum and plastic threaded closures enable resealability for convenience retail and outdoor consumption. Crown Holdings competes on decorated closure systems tied to premium brand portfolios.
- Flip Tops:Swing-top glass and ceramic mechanisms serve specialty and gift-pack positioning.
- Others:Crown cork alternatives and proprietary sealing systems occupy niche craft and experimental formats.
Crown caps dominate production lines. Screw caps are expanding most quickly in premium convenience segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mega-brewery procurement functions concentrate in Germany, Mexico, and the United States, with craft scaling in Belgium and the Netherlands adding premium format demand. Regulatory fragmentation across deposit-return schemes and recycled-content mandates is reshaping converter qualification timelines in each jurisdiction.
United States
Stadium concession demand and e-commerce multipack growth are pulling aluminum can volumes toward outdoor channels. The EPA guides state-level container deposit legislation that improves aluminum collection economics in California and New York. Milwaukee and St. Louis anchor mega-brewery procurement concentration where Ball Corporation and Crown Holdings have expanded dedicated beverage can capacity.
Germany
Traditional brewing heritage sustains glass bottle preference for premium and import portfolios despite aluminum cost advantages. The EU Packaging and Packaging Waste Directive imposes recycled content minimums that elevate compliance costs for imported formats. Bavaria and North Rhine-Westphalia concentrate craft brewery scaling where ISO 18601 certification has become a tender prerequisite.
Mexico
Export-oriented mega-breweries are centralizing procurement functions to capture North American aluminum can supply. SAMR-aligned GB standards for food-contact materials govern cross-border glass and metal trade with China. Mexico City and Monterrey anchor volume production where Crown Holdings competes on decorated closure systems for premium brand portfolios.
Belgium
Specialty and lambic brewing traditions sustain swing-top and cork-sealed formats in gift-pack positioning. The EU F-Gas Regulation and REACH compliance automation are forcing converter IT infrastructure upgrades across Flemish and Walloon operations. Brussels and Leuven concentrate craft brewery scaling where real-time carbon footprint verification has become a supplier penalty threshold.
China
Barrier film pouch formats are capturing outdoor recreation and single-serve convenience retail in tier-two cities. SAMR enforces GB standards for food-contact materials that govern glass and metal import qualification timelines. Yangtze River Delta manufacturing clusters are expanding aluminum can capacity to serve domestic brewery demand and Southeast Asian export routes.
Beer Packaging Market Vendor Landscape
Player mix skews toward integrated metal and glass converters with multinational brewery relationships, creating a tiered structure where ISO 18601 certification separates qualified suppliers from commodity competitors. Three strategic archetypes dominate: aluminum can specialists with dedicated beverage capacity, glass furnace operators with premium craft positioning, and integrated film converters capturing flexible format demand. Competitive moves concentrate in capacity expansion for aluminum body lightweighting and strategic partnerships for lifecycle tracking software deployment.
Among integrated packaging conglomerates, Amcor and Ball Corporation exemplify divergent specialization strategies. Amcor leverages integrated film and rigid plastic operations to represent the flexible format archetype in emerging markets. Ball Corporation anchors the aluminum can specialist tier through dedicated beverage capacity concentration in North America. Crown Holdings occupies a position between these archetypes, competing on decorated closure systems that tie to premium brand portfolio requirements across steel and aluminum substrates.
| Leading Market Players |
|---|
| Amcor |
| Ball Corporation |
| Ardagh Group |
| Crown Holdings |
| WestRock Company |
| Smurfit Kappa |
| Owens-Illinois |
| Berry Global |
| Graphic Packaging International |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with aluminum ingot indexation lock in both supply access and price visibility for mega-breweries across North America and Europe, insulating volume buyers from spot market volatility while compressing converter margins through fixed-volume commitments. These arrangements concentrate procurement power with Ball Corporation and Crown Holdings in the United States, where dedicated beverage can capacity anchors regional supply security against peak summer demand windows.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation dominate converter-brewery agreements, with price differentiation resting on ISO 18601 certification tier and volume scale commitments. Three-tier pricing structure across premium, standard, and economy levels separates certified sustainable suppliers from commodity competitors, with mega-breweries extracting standard-tier rates and craft portfolios absorbing premium alloy surcharges. Cost compression in sub-12-gram can bodies is intensifying because lightweighting engineering investments require volume amortization, and craft breweries show least price sensitivity due to brand positioning requirements.
Supply Chain Analysis
Inventory cycles stretching 8-12 weeks for aluminum coil and 4-6 weeks for glass cullet expose converters to ingot price swings and furnace energy cost spikes. Supply concentrates in the United States, Germany, and China, with raw material dependencies on bauxite refining, natural gas for glass melting, and recycled aluminum scrap streams. Single-source vulnerability in North American beverage can manufacturing creates allocation risk during festival and stadium season peaks. Distribution runs through mega-brewery centralized procurement hubs in Milwaukee, St. Louis, and Mexico City, with secondary e-commerce channels bypassing traditional retail case pack logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EU Green Deal compliance deadlines force material transitions and certified supplier qualification windows compress competitive access. Stadium channel growth and craft brewery scaling sustain dual-format demand across aluminum and glass substrates.
For Market Incumbents: Shield core mega-brewery relationships through captive aluminum can capacity additions in Mexico and the United States, while accelerating ISO 18601 certification timelines to block emerging converter competitors from multinational tenders. Vertical integration into recycled aluminum scrap collection secures circular feedstock access against ingot price volatility and EU recycled-content mandate tightening.
For New Entrants and Emerging Players: Differentiate on real-time carbon footprint verification software to capture German and Belgian craft brewery procurement where lifecycle transparency commands premium positioning. Target e-commerce multipack cardboard secondary packs and flexible film pouches in China and Southeast Asia, where Amcor's integrated operations leave white space for regional specialists with barrier film expertise and direct-to-consumer logistics partnerships.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with dormant glass furnace assets in Europe and pending ISO 18601 certification, as carbon border adjustments and extended producer responsibility fees elevate compliant asset values over the next decade. Watch for state-level container deposit legislation expansion across the United States as the inflection signal improving aluminum collection economics and circular feedstock security.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 18601 Certification Investment | Qualifies converters for multinational brewery tenders under EU Packaging and Packaging Waste Directive mandates. |
| Aluminum Can Capacity Expansion | Ball Corporation and Crown Holdings anchor North American supply security against peak summer allocation risk. |
| Lightweighting Technology Deployment | Sub-12-gram can bodies reduce logistics costs and carbon footprints for mega-brewery sustainability commitments. |
| Lifecycle Tracking Software Integration | German and Belgian breweries penalize suppliers lacking real-time carbon footprint verification systems. |
| Deposit-Return Scheme Partnership | Improves aluminum and glass collection economics across California, New York, and emerging state programs. |
Methodological Framework
Operator-level perspectives from brewery procurement directors, converter plant managers, aluminum smelter sales executives, and glass furnace operations heads anchored the qualitative base, supplemented by secondary validation from U.S. EPA container deposit guidance, EU Packaging and Packaging Waste Directive filings, SAMR GB standards documentation, and SEC 10-K disclosures from listed packaging conglomerates. Bottom-up volume modeling across material, format, and closure segments triangulated against top-down macroeconomic indicators and beverage consumption forecasts.
Sensitivity analysis tested forecast robustness across aluminum ingot price scenarios, EU carbon border adjustment implementation timelines, and craft brewery scaling trajectories over the projection horizon. Segmentation dimensions modeled include packaging type, material substrate, closure mechanism, and regional regulatory cluster, with CAGRs derived from historical volume elasticities and forward-looking capacity expansion announcements. Industry-specific inputs incorporated pasteurization thermal cycle compatibility constraints, deposit-return scheme coverage expansion, and lightweighting technology adoption curves.
Forecasts assume regulatory continuity in EU F-Gas Regulation, U.S. EPA state-level deposit legislation, and SAMR food-contact material standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market