
 Europe Alcoholic Drinks Packaging Market | 2026-2036
Europe Alcoholic Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Alcoholic Drinks Packaging Market Foresight
Buyer concentration among multinational beverage groups is restructuring procurement dynamics across European packaging supply chains. Ardagh Group leverages its furnace network across France and Germany to sustain high-volume glass contracts with premium distillers. Smurfit Kappa competes through corrugated secondary packaging that anchors e-commerce fulfillment for craft breweries. Crown Holdings Inc. specializes in aluminum can ends, dominating the shift from returnable bottles in Nordic markets.
Europe alcoholic drinks packaging encompasses primary and secondary containment systems engineered to preserve organoleptic properties, withstand carbonation pressures, and comply with food-contact migration limits. Glass bottles, typically soda-lime silica with wall thickness calibrated to 3-4mm for wine and spirits, remain the dominant format for premium positioning due to inertness and brand heritage associations. Aluminum cans represent the fastest-expanding material segment as breweries and hard seltzer brands target outdoor consumption and retail single-serve channels. Cardboard multipacks and shelf-ready displays concentrate margin pools in secondary packaging, where Mondi and Smurfit Kappa extend format innovation to reduce plastic film dependency.
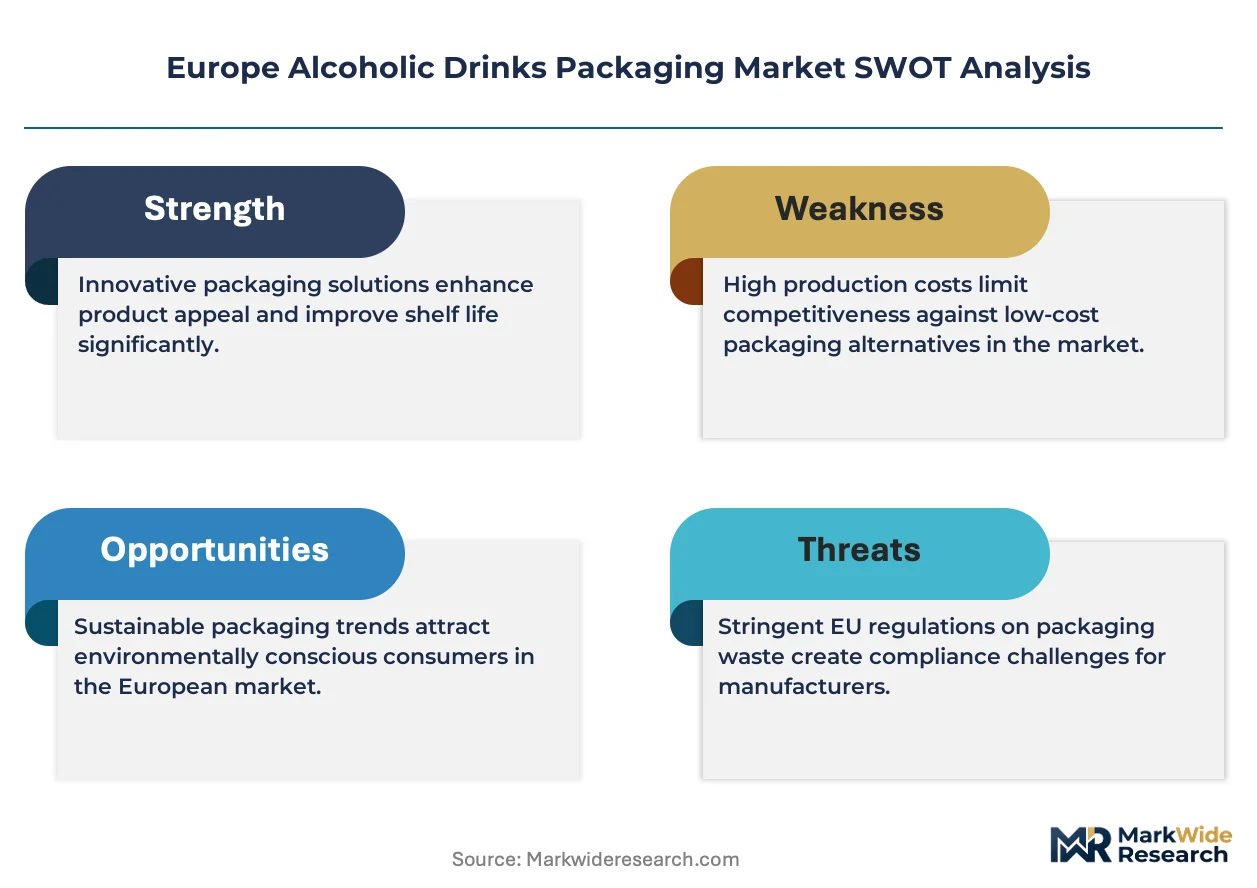
EU Green Deal carbon-border adjustments and REACH chemical compliance are reshaping material specifications and supplier qualification timelines for converters serving alcoholic drinks brands. ECHA restrictions on certain additives in food-contact plastics are forcing reformulation of closure compounds and barrier coatings. Germany's national packaging regulator enforces strict returnable quotas that preserve refillable glass systems against single-use expansion. Stakeholders must monitor how the EU AI Act and evolving extended producer responsibility schemes will redefine traceability requirements across complex multinational supply chains.
Market Dynamics
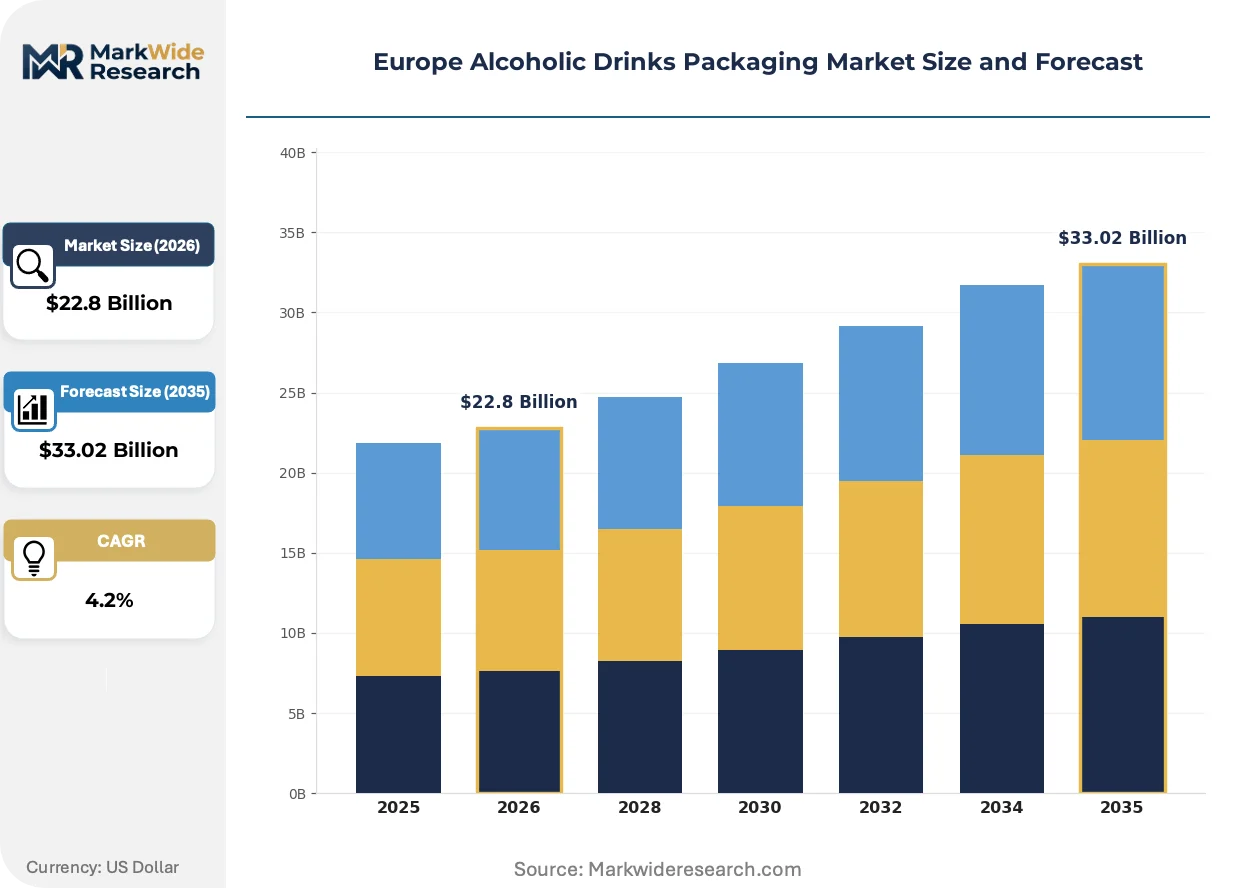
EU Green Deal carbon-border adjustments and F-Gas Regulation phase-downs are forcing converters to requalify material specifications across glass and aluminum supply chains, compressing supplier margins while accelerating furnace retrofits and recycled content adoption.
Growth Catalysts
- Lightweight glass innovation:Premium spirits producers in France and Italy are demanding thinner-walled bottles that cut transport emissions and raw material intensity without compromising structural integrity for carbonated products.
- REACH compliance migration:ECHA restrictions on food-contact additives are pushing closure compound reformulation, creating first-mover advantages for converters with certified alternative chemistries.
- Aluminum can expansion:Hard seltzer and craft brewery demand for single-serve outdoor formats is displacing returnable glass in Nordic retail channels.
Market Restraints
- Natural gas price volatility:Glass furnace operations in Germany's Rhine-Main cluster face input cost swings that erode contract profitability on fixed-price multi-year beverage agreements.
- Recycled aluminum supply concentration:Secondary smelter capacity concentrates in Southern Europe, creating logistics bottlenecks for Northern European can converters.
- Returnable glass quota enforcement:Germany's national packaging regulator mandates strict refillable thresholds that limit single-use format expansion for imported brands.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania show low aluminum can penetration for wine and spirits, offering white space for format conversion investments.
- Extended producer responsibility tailwinds:EU-wide EPR scheme harmonization creates economies of scale for pan-European labeling and take-back infrastructure.
- Digital watermarking convergence:AI-driven sorting technologies combined with invisible bottle markers enable higher-purity glass cullet recovery.
Industry Challenges
- Color-separation expertise gaps:Amber and flint glass sorting facilities lack trained technicians to meet rising demand for closed-loop cullet systems.
- Furnace reconfiguration capex:Lower-carbon oxy-fuel and electric melting retrofits require capital commitments that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Alcoholic Drinks Packaging Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $33.02 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Kegs, Pouches Material: Glass, Aluminum, Plastic, Cardboard Closure Type: Corks, Caps, Screwcaps, Flip-tops End User: Bars, Restaurants, Retailers, E-commerce |
| Companies Covered | Ball Corporation, Mondi, Amcor plc, Sealed Air, Smurfit Kappa, Owens-Illinois Inc., Ardagh Group, Verallia, Crown Holdings Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Alcoholic Drinks Packaging Market Shifts & Advancements
Material science advances and regulatory compliance automation are compressing product development cycles while fragmenting procurement authority between sustainability officers and traditional packaging engineers.
Ultralight glass bottle designs with optimized stress distribution algorithms are rewriting weight-to-strength ratios for premium wine and spirits applications. Champagne houses and Scotch distillers are piloting sub-300-gram standard bottles that maintain pressure ratings. This technology is rewriting freight economics and carbon accounting for export-oriented producers.
EU AI Act traceability mandates are forcing packaging converters to deploy machine-readable batch records across complex multinational supply chains. Automated compliance documentation systems now link raw material certificates to finished goods serialization. Spirits exporters to Germany face the steepest implementation curves given existing national returnable tracking requirements.
Direct-to-consumer subscription channels for craft beverages are fragmenting traditional wholesale procurement patterns. Smaller breweries now specify mixed-format variety packs that corrugated converters must configure for automated fulfillment. This shift concentrates in the Netherlands and Belgium where e-commerce alcohol delivery regulations have liberalized fastest.
Europe Alcoholic Drinks Packaging Market Segmentation
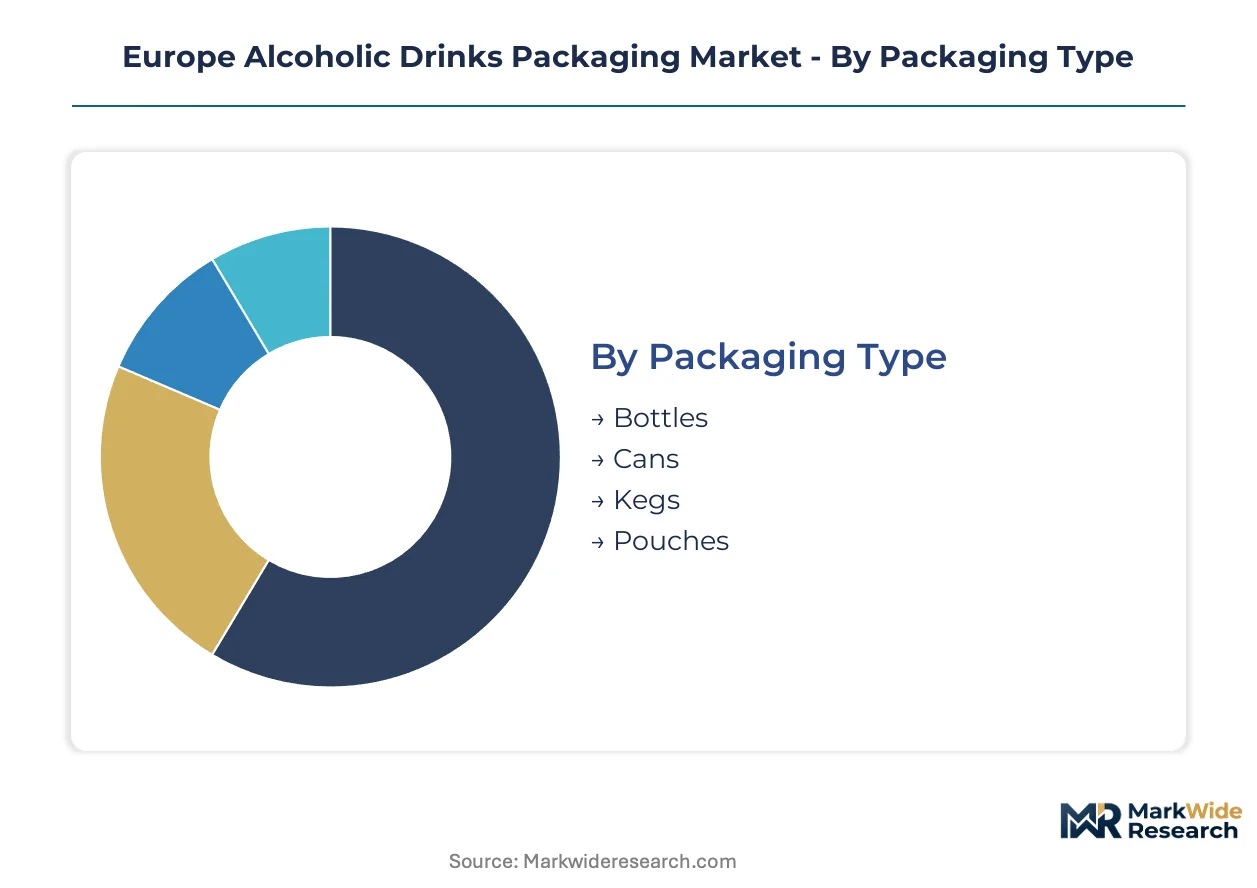
Packaging format decisions in European alcoholic beverages hinge on carbonation requirements, premium positioning needs, and compliance with national returnable quotas. Material and closure specifications cascade through supply chain qualification timelines and furnace reconfiguration investments.
Packaging Type:
Upgrade cycles in bottling infrastructure are accelerating as converters retire legacy lines for lightweight-compatible formats and aluminum can expansion.
- Bottles:Soda-lime silica construction with 3-4mm wall thickness dominates wine and spirits applications where inertness preserves organoleptic properties. Champagne houses in France and Scotch distillers are piloting sub-300-gram lightweight designs that maintain pressure ratings while cutting transport emissions.
- Cans:Two-piece aluminum construction with internal epoxy phenolic linings withstands carbonation pressures for beer and hard seltzer formats. Nordic retail channels are displacing returnable glass fastest here as outdoor consumption patterns reshape single-serve demand.
- Kegs:Stainless steel reusable formats anchor on-premise draft systems for bars and restaurants across Germany's Rhine-Main cluster.
- Pouches:Flexible laminated films with oxygen barrier layers serve low-volume wine and cocktail concentrate applications in Netherlands e-commerce channels.
Bottles sit at the top of the volume ranking, with cans climbing the fastest.
Material:
Cost tier differentiation separates premium heritage formats from mass-market convenience packaging, with carbon-border adjustments compressing margins on virgin inputs.
- Glass:Soda-lime silica furnaces in France and Germany calibrate batch chemistry for flint, amber, and green colorways. EU Green Deal carbon-border adjustments are forcing Rhine-Main cluster operators toward lower-carbon oxy-fuel retrofits and higher cullet ratios.
- Aluminum:Rolled can body stock with recycled content targets dominates single-serve beer and hard seltzer growth. Secondary smelter capacity concentrates in Southern Europe, creating logistics bottlenecks for Northern European converters.
- Plastic:PET and multilayer barrier bottles serve specific spirits and ready-to-drink applications where weight reduction outweighs premium perception.
- Cardboard:Corrugated secondary packaging and shelf-ready displays concentrate margin pools as Mondi and Smurfit Kappa reduce plastic film dependency in multipack configurations.
Glass commands the highest share by value, though aluminum gains share fastest in volume terms.
Closure Type:
Application-specific sealing requirements drive specification divergence between still wine, sparkling, and carbonated beer formats.
- Corks:Natural and agglomerated cork products maintain heritage positioning for premium still wines in France and Italy, with oxygen transfer rate specifications critical for aging potential.
- Caps:Crown corks with PVC-free compounds seal beer and cider formats, with REACH compliance migration forcing compound reformulation across German bottling lines.
- Screwcaps:Aluminum roll-on pilfer-proof closures with tin-saran liners displace cork in mid-tier wine segments where consistency outweighs tradition.
- Flip-tops:Re-sealable polypropylene closures serve ready-to-drink and cocktail formats in Belgian and Dutch retail channels.
Corks retain volume leadership in value terms, with screwcaps expanding most quickly across mid-market positioning.
End User:
Customer type fragmentation is splitting procurement authority between sustainability officers managing EPR compliance and operations teams optimizing line throughput.
- Bars:On-premise draft systems and premium bottle service drive keg and heavyweight glass demand in urban centers.
- Restaurants:Wine-by-the-glass programs and curated spirits lists concentrate mid-weight bottle specifications.
- Retailers:Hypermarket and supermarket chains enforce shelf-ready display standards and returnable quotas through Germany's national packaging regulator.
- E-commerce:Direct-to-consumer subscription channels in Netherlands and Belgium specify mixed-format variety packs requiring corrugated automation investment.
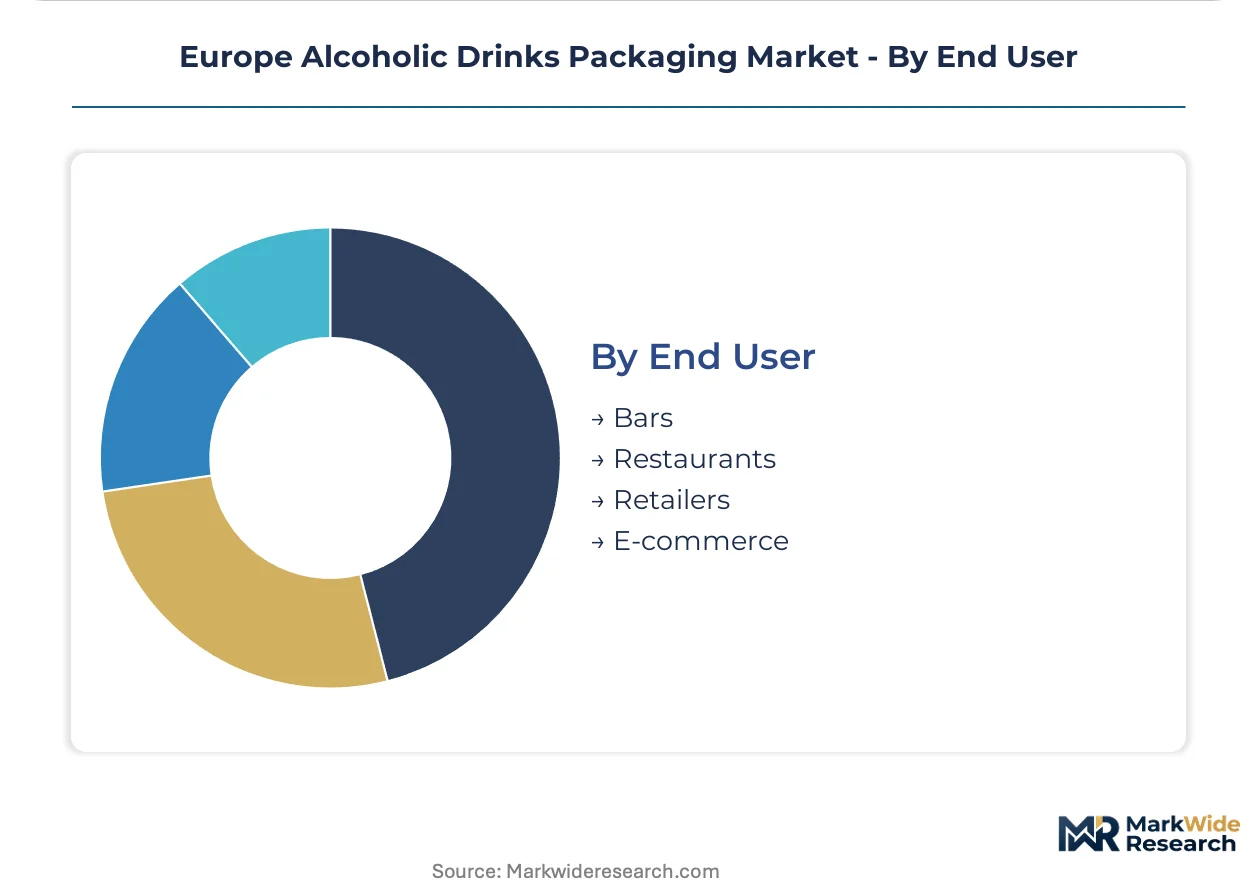
Retailers anchor volume concentration, while e-commerce posts the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest share of European alcoholic drinks packaging demand, while France concentrates premium spirits glass innovation. Italy's lightweight bottle pilots and the Netherlands' e-commerce liberalization create divergent growth vectors across the continent.
Germany
The Rhine-Main packaging cluster anchors Central European distribution networks with high-volume bottling lines serving multinational beverage groups. The national packaging regulator enforces strict returnable glass quotas that preserve refillable systems against single-use expansion. Ardagh Group leverages its furnace network across Hesse and Rhineland-Palatinate to sustain contracts with premium distillers.
France
Champagne houses and Cognac producers drive demand for sub-300-gram ultralight glass designs that maintain pressure ratings for carbonated products. EU Green Deal carbon-border adjustments accelerate furnace retrofits toward lower-carbon oxy-fuel systems in the Champagne-Ardenne glassmaking region. Verallia operates multiple facilities supplying heritage brands with flint and amber colorways.
Italy
Prosecco and premium spirits producers in Veneto and Piedmont accelerate lightweight bottle adoption to cut transport emissions. REACH compliance migration forces reformulation of closure compounds across Italian bottling lines. The Murano glassmaking tradition influences design specifications for super-premium spirits positioning.
Netherlands
Direct-to-consumer subscription channels for craft beverages fragment traditional wholesale procurement patterns. Liberalized e-commerce alcohol delivery regulations concentrate mixed-format variety pack demand around Rotterdam and Amsterdam distribution hubs. Smurfit Kappa competes through corrugated secondary packaging configured for automated fulfillment.
United Kingdom
Scotch whisky exporters face steep EU AI Act traceability implementation curves given existing serialization requirements. Crown Holdings Inc. dominates aluminum can end supply for craft brewery expansion into outdoor consumption formats. English sparkling wine producers pilot lightweight glass alternatives to compete with Champagne imports.
Europe Alcoholic Drinks Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material segments, creating a tiered structure where scale advantages clash with agility premiums. Glass furnace operators and aluminum converters anchor the supply base, while corrugated specialists capture secondary packaging margin pools. Two strategic archetypes dominate: integrated material producers controlling upstream furnace or smelter assets, and format-focused converters specializing in single categories. Capacity expansion and strategic partnerships represent the dominant competitive moves as participants respond to EU Green Deal compliance timelines.
Among integrated glass producers, Owens-Illinois Inc. and Verallia exemplify the furnace-network archetype with multi-country European footprints. Ball Corporation and Crown Holdings Inc. occupy positions within aluminum can supply, representing the metal packaging specialization vector. These named entities anchor industry-level commentary on material-specific competitive dynamics without implying specific strategic actions or market positions beyond their archetype representation.
| Leading Market Players |
|---|
| Ball Corporation |
| Mondi |
| Amcor plc |
| Sealed Air |
| Smurfit Kappa |
| Owens-Illinois Inc. |
| Ardagh Group |
| Verallia |
| Crown Holdings Inc. |
| Others |
Supply & Pricing Matrix
Lightweight glass specifications from premium spirits producers in France and Italy are forcing Rhine-Main cluster converters to recalibrate furnace chemistry and wall-thickness tolerances, compressing margins on legacy fixed-price contracts while opening premium tiers for certified low-carbon formats.
Pricing Analysis
Capacity additions in Southern European aluminum rolling are reshaping price floors for can body stock across Northern European breweries. Three-tier pricing structure across heritage glass, certified lightweight, and commodity aluminum formats separates premium spirits positioning from mass-market beer convenience. Cost compression in standard glass intensifies because natural gas input volatility erodes contract profitability on multi-year beverage agreements. Mass-market retailers exhibit highest price sensitivity, while heritage Champagne houses and Scotch distillers absorb premiums for sub-300-gram certified bottles.
Supply Chain Analysis
Recycled cullet supply rests on French and German color-sorting infrastructure with limited amber and flint technician capacity. Soda-lime silica batch chemistry, aluminum can body stock, and epoxy phenolic internal linings constitute critical input dependencies. Single-source vulnerability concentrates in Southern European secondary aluminum smelters, creating logistics bottlenecks for Nordic can converters. Distribution runs through Rotterdam and Hamburg port clusters feeding Central European bottling lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon-border adjustments against F-Gas Regulation phase-down timelines create a geographic-arbitrage window: converters with early oxy-fuel furnace retrofits in Germany capture margin premiums unavailable to Southern European peers facing delayed compliance deadlines.
For Market Incumbents: Cement furnace network consolidation across the Rhine-Main cluster to lock in multi-year contracts with premium distillers facing EU AI Act traceability mandates. Prioritize backward integration into closed-loop cullet systems before ECHA restrictions tighten food-contact additive specifications. Ardagh Group and Verallia archetypes must defend against aluminum can substitution in Nordic outdoor consumption channels. For New Entrants and Emerging Players: Begin with Poland and Romania aluminum can white space for wine and spirits format conversion, where penetration lags Western European benchmarks by substantial margins. Target Romanian retail channels with hard seltzer single-serve configurations. Partner with Rotterdam distribution hubs for automated corrugated fulfillment of mixed-format variety packs. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier glass converters possessing oxy-fuel retrofit completion and certified alternative closure compound portfolios. Five-to-ten-year viability hinges on EU-wide EPR scheme harmonization execution. Watch for German national packaging regulator relaxation of returnable glass quotas as the inflection signal for single-use format expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweight Glass Furnace Retrofit | EU Green Deal compliance secures premium contracts with Champagne houses and Cognac producers. |
| Recycled Aluminum Supply Agreement | Southern European smelter partnerships reduce logistics exposure for Nordic can expansion. |
| Digital Watermarking Deployment | AI-driven sorting technologies enable higher-purity cullet recovery for closed-loop glass systems. |
| Corrugated Automation Investment | Rotterdam and Amsterdam hubs capture Netherlands e-commerce subscription channel growth. |
| REACH-Compliant Compound Reformulation | ECHA-certified alternative chemistries create first-mover advantage in closure supply. |
Research Methodology
Direct dialogue with glass furnace operators, aluminum converters, corrugated specialists, beverage procurement directors, and national packaging regulators anchored qualitative foundations. Secondary validation drew from EU ECHA restriction filings, F-Gas Regulation implementation reports, German packaging regulator enforcement data, and customs records tracking aluminum can body stock flows. Bottom-up facility capacity assessments and top-down beverage production volume estimates underwent cross-triangulation.
Segment-level projections across packaging type, material specification, closure chemistry, and end-user channel calibrated volume and value trajectories over the analysis window. CAGRs emerged from regression analysis against EU Green Deal compliance timelines and EPR scheme rollout assumptions. Furnace retrofit completion schedules and aluminum rolling capacity additions served as industry-specific forecast inputs.
Caveats apply where natural gas price volatility, ECHA additive restriction scope expansion, or German returnable quota enforcement tightening could materially shift the outlook. Forecasts embed assumptions about EU AI Act traceability implementation pacing and cross-border cullet logistics harmonization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
Global Cider Packaging Market