
 Global Wine Packaging Market | 2026-2036
Global Wine Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wine Packaging Market Foresight
Closure and label customization revenue is reconfiguring margin pools away from commodity glass supply. Owens-Illinois Inc. leverages furnace scale and geographic plant density to dominate North American bottle supply. Ardagh Group SA anchors European production through its specialized wine glass facilities in France and Italy. Verallia SA competes on premium decoration capabilities and lightweighting technology leadership.
Wine packaging encompasses the primary and secondary containment systems used to protect, preserve, and present wine from bottling through consumer use, with glass bottles typically specified at 300-750 gram weights and closure systems engineered to manage oxygen transfer rates below 0.1 mg per year for aged products. Its commercial purpose centers on brand differentiation at point of sale while ensuring chemical stability across variable storage conditions. Glass bottles retain the dominant volume position across premium and super-premium tiers, though bag-in-box formats are capturing faster growth in everyday consumption channels. Screw caps and synthetic corks are displacing natural cork in New World wine regions where closure consistency outweighs traditional signaling value.
The European Commission's Packaging and Packaging Waste Regulation and the FDA's food contact substance notifications in the United States jointly shape material compliance burdens and recycling target obligations for cross-border suppliers. REACH chemical restrictions and California's SB 54 extended producer responsibility law further constrain substrate choices and end-of-life design requirements. Stakeholders must monitor evolving deposit-return scheme expansions and lightweighting mandates that will determine competitive positioning in closure and container specification decisions.
Market Dynamics
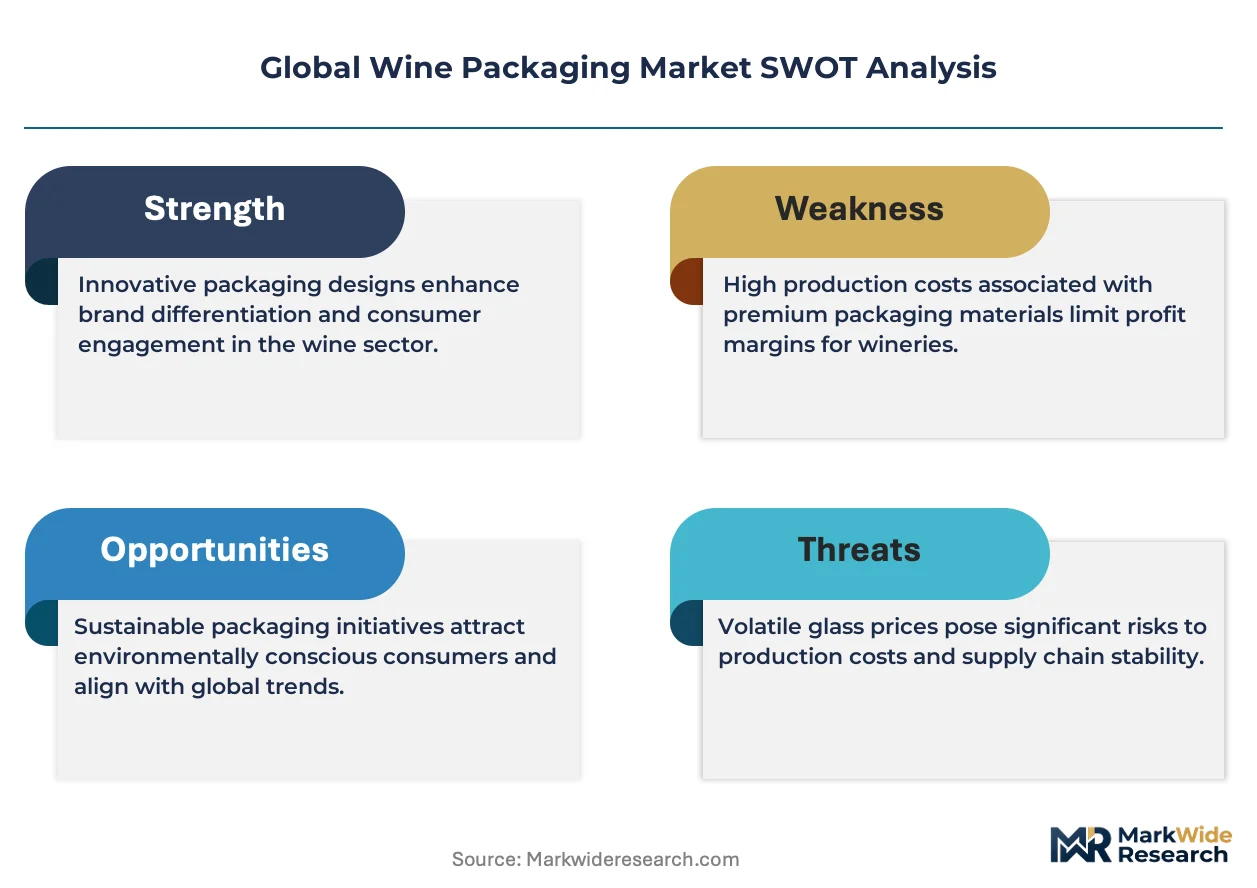
EU Green Deal packaging waste directives are forcing material substitutions across the wine packaging supply chain, compressing design cycles and redistributing margin pools toward lightweighting specialists and alternative closure providers.
Growth Catalysts
- EU Green Deal packaging mandates:The Packaging and Packaging Waste Regulation imposes strict recyclability targets and lightweighting requirements that accelerate glass weight reduction programs across French and Italian premium wineries.
- Screw cap technology maturation:Synthetic cork and aluminum screw closure systems now deliver oxygen transfer rates below 0.1 mg per year, matching natural cork performance while eliminating taint risk for aged Bordeaux and Napa Valley reserve programs.
- Bordeaux-Tuscany-Napa Valley cluster concentration:Provenance branding intensification in these three premium wine regions drives demand for differentiated primary packaging and customized closure-label combinations.
Market Restraints
- Natural cork supply concentration:Portuguese and Spanish cork oak harvesting faces climate volatility and labor constraints, creating input cost instability for traditional closure-dependent producers.
- Furnace capital intensity:Container glass manufacturing requires continuous high-temperature operations that resist rapid reconfiguration for lightweighting without multi-million euro rebuild cycles.
- REACH chemical restrictions:ECHA substance authorizations constrain coating and decoration chemistries, complicating premium decoration development for super-premium tier bottles.
Strategic Opportunities
- Bag-in-box everyday channel expansion:Three-liter and five-liter formats capture volume growth in casual consumption occasions across Germany and the United Kingdom where convenience outweighs ceremonial signaling.
- California SB 54 extended producer responsibility:The state's plastic pollution reduction mandates create first-mover advantage for suppliers offering verified recyclable or refillable packaging systems to West Coast wineries.
- Digital printing-decoration convergence:Direct-to-glass inkjet and laser etching technologies enable lot-size-one customization for small-batch releases and club-exclusive bottlings.
Industry Challenges
- Lightweighting R&D talent scarcity:Glass stress modeling and thin-wall forming expertise concentrates at a handful of specialized engineering consultancies in Germany and Italy.
- Multi-material separation infrastructure:Mixed closure-bottle-label systems require end-of-life sorting capabilities that remain underdeveloped in most municipal recycling streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wine Packaging Market |
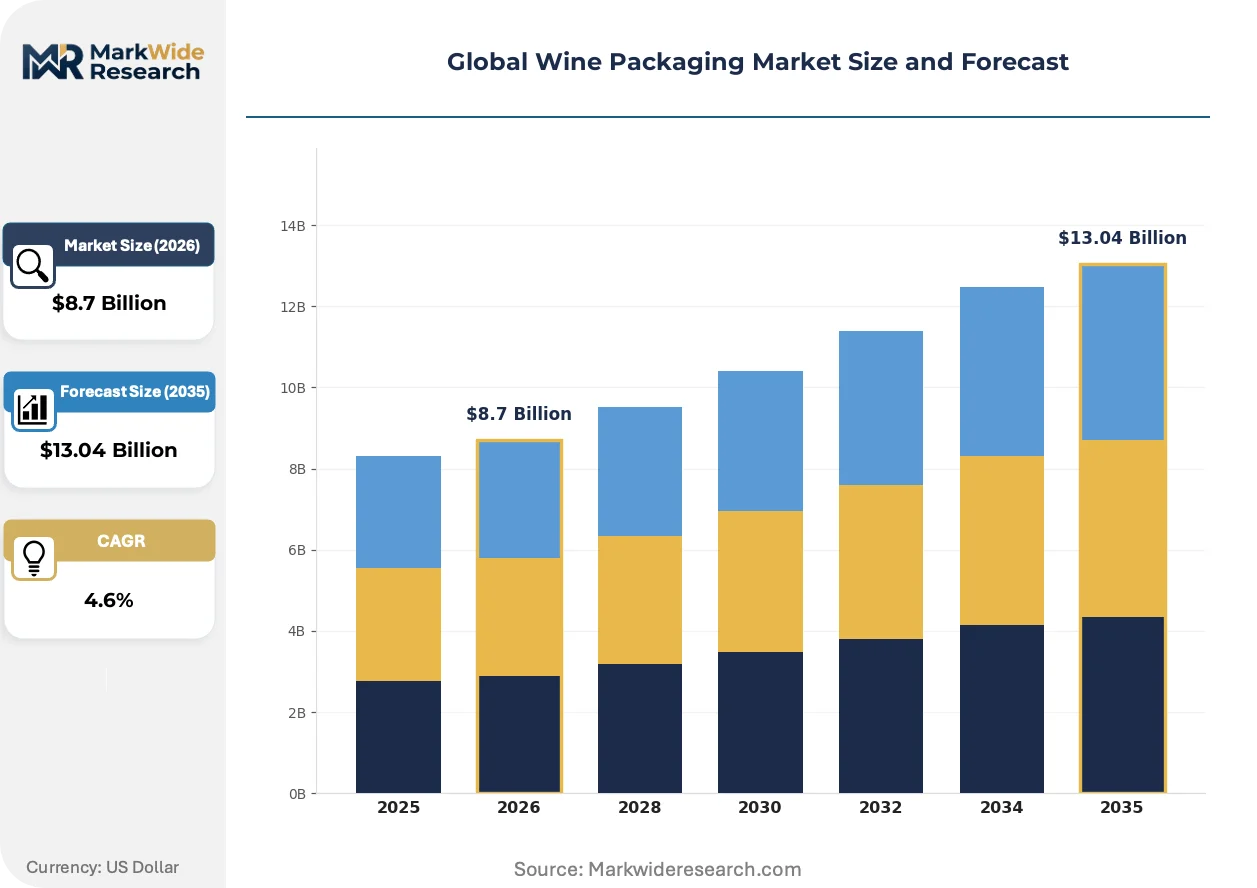
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass Bottles, Bag-in-Box, Plastic Bottles, Tetra Pak, Cans, Cartons Material: Foil Capsules, Plastic Corks, Natural Corks, Synthetic Corks, Screw Caps, Wood Boxes Application: Retail Sales, Food Service, Direct-to-Consumer, Private Label, Corporate Gifting, Events End User: Winery, Distributors, Specialty Stores, Restaurants, Beverage Exporters, Wholesalers |
| Companies Covered | Owens-Illinois Inc., Ardagh Group SA, Verallia SA, Saverglass SAS, Amcor plc, DS Smith, International Paper, Smurfit Kappa, Guala Closures Group S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wine Packaging Market Shifts & Advancements
Active packaging intelligence and regulatory compliance automation are reconfiguring how wine producers specify containment systems, shifting specification authority from brand marketing toward technical procurement functions.
Smart closure systems embedding NFC tags and temperature-logging sensors are digitizing supply chain transparency for fine wine collectors and auction houses. Château Margaux and Opus One have piloted blockchain-linked bottle authentication that tracks provenance from cellar through secondary market resale. The technology is digitizing trust mechanisms previously dependent on paper documentation and physical inspection.
REACH substance restrictions and the EU's F-Gas Regulation are eliminating certain blowing-agent chemistries and decorative coatings from glass manufacturing. Ardagh and Verallia have reformulated furnace batches and cold-end coatings to maintain optical clarity and scuff resistance under tighter chemical constraints. Italian sparkling wine producers face compressed timelines for Prosecco DOC label compliance with revised migration test protocols.
Direct-to-consumer subscription channels are fragmenting order profiles and compressing production runs for premium wineries. Naked Wines and Firstleaf have normalized mixed-case fulfillment requiring modular secondary packaging and variable-bottle-count shipper designs. This pattern concentrates in California and Oregon where tasting room visitation declined and e-commerce penetration accelerated.
Global Wine Packaging Market Segmentation
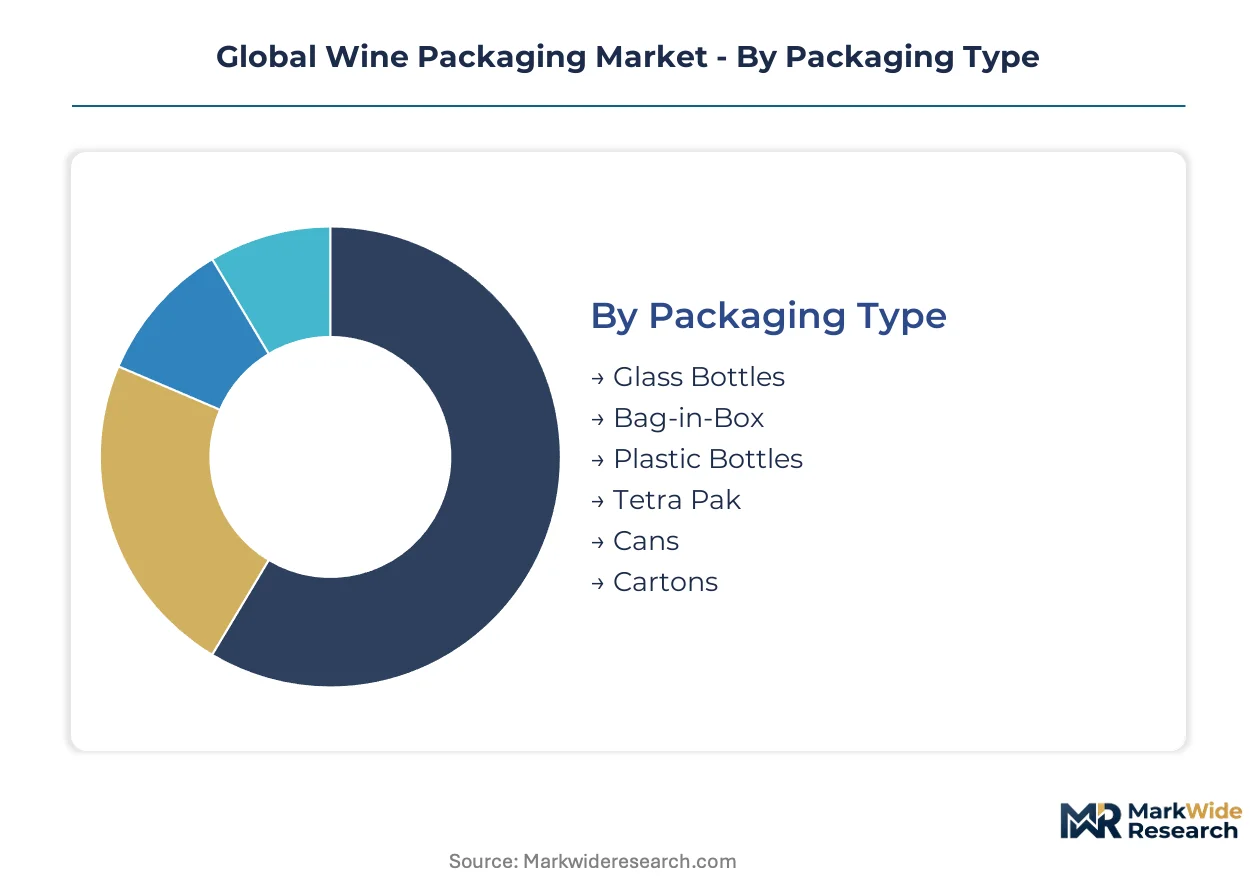
Wine packaging specification cycles vary dramatically by containment system, with primary containers commanding multi-year furnace commitments while closure and decoration decisions refresh annually. Understanding segment turnover velocity reveals where procurement authority concentrates and which suppliers capture recurring revenue streams versus capital-intensive long-cycle positions.
Packaging Type:
Replacement cycles stretch from decades for glass furnace infrastructure down to single-use formats in casual consumption channels, creating divergent supplier margin profiles and customer switching costs.
- Glass Bottles:Flint, amber, and dead-leaf glass formulations dominate premium tier specification at 300-750 gram weights. Bordeaux and Napa Valley wineries drive lightweighting investment as EU Green Deal mandates compress allowable packaging mass per liter of wine shipped.
- Bag-in-Box:Three-liter and five-liter multilayer film and tap systems capture fastest volume expansion in German and UK everyday consumption where refrigerator storage and extended shelf life outweigh ceremonial signaling. Convenience-driven households displace standard bottle purchases for mid-week consumption occasions.
- Plastic Bottles:PET and rPET formats serve airline, stadium, and poolside venues where weight reduction and shatter resistance override premium cues. California SB 54 compliance requirements favor verified recycled content claims.
- Tetra Pak:Aseptic carton systems penetrate price-sensitive southern European markets and export corridors to tropical climates where thermal stability and logistics cube efficiency matter most.
- Cans:Aluminum single-serve formats expand in outdoor recreation and music festival channels across Australia and New Zealand, with slim 250ml profiles targeting moderation trends.
- Cartons:Folding carton secondary packaging and gift boxes concentrate in corporate gifting and holiday seasonal programs where unboxing experience drives repeat purchase intent.
Glass bottles dominate installed base across premium and super-premium tiers. Bag-in-box formats are where expansion concentrates most steeply in absolute volume terms.
Material:
Specification authority migrates toward technical procurement functions as oxygen transfer rate performance and chemical compliance displace traditional aesthetic considerations in closure selection.
- Screw Caps:Aluminum roll-on pilfer-proof systems now achieve sub-0.1 mg per year oxygen ingress, matching natural cork for aged Bordeaux programs while eliminating TCA taint risk. New Zealand and Australian wineries normalized screw cap acceptance, forcing traditionalist regions to reconsider closure stigma.
- Natural Corks:Quercus suber bark harvesting from Portuguese montado ecosystems retains ceremonial value for first-growth châteaux and collectors seeking cellar aging authenticity. Climate volatility and labor constraints in Alentejo and Catalonia create supply intermittency and price volatility.
- Synthetic Corks:Extruded and injection-molded polymer closures serve consistent performance requirements in high-volume supermarket programs where batch-to-batch variation is unacceptable.
- Plastic Corks:Cellulose and foam-core constructions occupy mid-tier price positioning with lower extraction force requirements for casual consumers.
- Foil Capsules:Tin-lead and aluminum-polymer laminates provide tamper evidence and brand decoration at bottle neck, though REACH substance restrictions are eliminating certain legacy coating chemistries.
- Wood Boxes:Paulownia and pine crate systems concentrate in Chinese gift-giving culture and auction house presentation protocols where unboxing ritual reinforces provenance signaling.
Natural cork retains dominance in super-premium installed base. Screw caps capture the steepest expansion trajectory as technical performance validation spreads from New World to traditional European producers.
Application:
Channel fragmentation is compressing production runs and forcing packaging modularity as direct-to-consumer growth reconfigures fulfillment requirements away from pallet-scale retail logistics.
- Retail Sales:Supermarket and hypermarket channels specify standard bottle formats with high-contrast shelf presence and case-stackability for warehouse club formats. Label decoration investments concentrate here as point-of-sale competition intensifies.
- Direct-to-Consumer:Subscription clubs and winery e-commerce drive demand for mixed-case shippers, individual bottle protective inserts, and variable-count packaging that accommodates 2, 4, 6, and 12-bottle orders. Naked Wines and Firstleaf normalized this fulfillment complexity.
- Food Service:On-premise consumption requires rapid-pour formats, bag-in-box back-of-house systems, and glassware-compatible bottle weights that sommeliers can maneuver tableside.
- Private Label:Retailer-controlled brands prioritize cost-engineered packaging with standardized closures and reduced decoration passes to hit aggressive price points.
- Corporate Gifting:Customized wood boxes, etched bottles, and seasonal sleeves serve year-end client retention programs with high margin and low volume recurrence.
- Events:Single-serve cans, plastic flutes, and pre-filled glassware address stadium, wedding, and festival venues where glass breakage liability and cleanup costs dominate specification.
Retail sales anchor installed volume across all tiers. Direct-to-consumer is where packaging innovation and supplier technical service investment concentrate most intensely.
End User:
Procurement sophistication varies sharply across the value chain, with integrated wineries specifying primary packaging directly while distributors and wholesalers aggregate fragmented demand with limited customization leverage.
- Winery:Château Margaux, Opus One, and similarly positioned producers maintain direct relationships with Ardagh, Verallia, and Owens-Illinois for furnace-customized glass and closure co-development programs.
- Distributors:Southern Glazer's and comparable tier-one distributors consolidate volume across multiple winery clients, capturing scale leverage on standard formats but ceding specification authority upstream.
- Specialty Stores:Independent wine merchants and high-end retailers influence packaging through exclusive cuvée programs and private label development with regional producers.
- Restaurants:Sommelier-driven accounts prioritize bottle aesthetics and tableside handling ergonomics, with limited direct procurement role beyond by-the-glass program format selection.
- Beverage Exporters:Freight forwarders and export houses specify ISPM-15 compliant wood packaging and container-loading optimization for ocean transit to Asian markets.
- Wholesalers:Cash-and-carry and broadline foodservice distributors stock high-velocity SKUs with minimal customization, prioritizing inventory turns over packaging differentiation.
Wineries dominate specification authority for primary packaging. Distributors and wholesalers aggregate volume but exercise limited influence over material and format selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and Italy consume wine packaging through provenance-lens ceremonial formats, while Germany and the United Kingdom favor bag-in-box convenience for everyday occasions. This consumption-mix differential shapes supplier specialization and regulatory compliance priorities across markets.
France
Bordeaux châteaux and Champagne maisons drive specification for ultra-lightweight flint glass below 400 grams. The EU Green Deal Packaging and Packaging Waste Regulation imposes strict recyclability targets that compress allowable packaging mass per liter shipped. Verallia's specialized furnaces in Châlons-en-Champagne anchor premium decoration capabilities for first-growth producers.
Italy
Tuscan DOCG producers and Prosecco DOC consortia concentrate demand for customized closure-label combinations and sparkling-specific bottle formats. REACH chemical restrictions constrain cold-end coating chemistries, forcing reformulation of scuff-resistant treatments. Ardagh's Italian facilities in Empoli serve the Chianti Classico cluster with dedicated lightweighting programs.
United States
Napa Valley and Sonoma County wineries normalize direct-to-consumer subscription fulfillment requiring modular mixed-case shippers. California's SB 54 extended producer responsibility law mandates plastic pollution reduction, favoring verified recyclable packaging systems. Owens-Illinois leverages plant density across the Pacific Northwest to serve West Coast premium producers.
Germany
Rheinhessen and Pfalz cooperatives anchor bag-in-box volume expansion for three-liter and five-liter everyday consumption formats. The country's national packaging regulator enforces strict deposit-return scheme compliance for multilayer film and tap systems. Convenience-driven households in Berlin and Hamburg displace standard bottle purchases for mid-week occasions.
Australia
Barossa Valley and Margaret River producers pioneered screw cap normalization for premium tier acceptance, eliminating closure stigma through technical performance validation. The TGA and national standards bodies govern food contact substance notifications for alternative closure materials. Aluminum single-serve cans expand in outdoor recreation channels across New South Wales and Victoria.
Global Wine Packaging Market Competitive Landscape
Capability concentration sits with specialized glass decorators and lightweighting engineers; scale advantage sits with furnace operators commanding geographic plant density. The market structures around three tiers: integrated container glass multinationals with furnace networks, premium decoration specialists serving provenance-brand wineries, and flexible packaging converters capturing bag-in-box expansion. Dominant competitive moves include capacity consolidation through asset acquisitions and co-development partnerships with closure technology providers.
Among integrated glass manufacturers, Owens-Illinois Inc., Ardagh Group SA, and Verallia SA exemplify the furnace-scale archetype, each occupying positions defined by geographic production density and customer proximity to premium wine clusters. Owens-Illinois anchors North American supply through plant network concentration. Ardagh and Verallia compete across European markets where EU regulatory compliance and decoration capabilities determine specification authority. These three represent the capital-intensive tier where multi-million euro rebuild cycles and continuous high-temperature operations create barriers to rapid reconfiguration.
| Leading Market Players |
|---|
| Owens-Illinois Inc. |
| Ardagh Group SA |
| Verallia SA |
| Saverglass SAS |
| Amcor plc |
| DS Smith |
| International Paper |
| Smurfit Kappa |
| Guala Closures Group S.p.A. |
| Others |
Supply & Pricing Matrix
EU REACH chemical restrictions on cold-end coatings and decorative chemistries create dual pressure on both input cost volatility and furnace reconfiguration timelines, compressing margin spreads between premium decorated glass and commodity bottle supply while forcing producers to consolidate specification authority around compliant material sourcing.
Pricing Analysis
Long-term offtake contracts dominate furnace-scale glass supply, with Bordeaux and Napa Valley wineries locking multi-year volume commitments to Owens-Illinois and Verallia in exchange for lightweighting co-development access. Three-tier pricing structure across premium, standard, and economy levels separates first-growth château custom decoration from supermarket private-label commodity bottles. Cost compression in mid-tier glass is intensifying because EU Green Deal mandates accelerate allowable weight reduction programs without corresponding price premiums. Supermarket private-label buyers exhibit highest price sensitivity, while provenance-brand wineries prioritize oxygen transfer rate performance and decoration capability over unit cost.
Supply Chain Analysis
Export-control regimes on specialized furnace equipment and lightweighting engineering talent from Germany and Italy constrain capacity expansion outside established production clusters. Container glass manufacturing concentrates in France, Italy, and the United States, with raw material batches drawing from silica sand deposits in Belgium, soda ash from Wyoming and Kenya, and cold-end coatings reformulated under REACH substance authorizations. Single-source vulnerability sits with Portuguese montado ecosystems for natural cork supply, where climate volatility and labor constraints create input intermittency. Distribution runs through integrated winery direct procurement for premium tiers and consolidated distributor networks for standard formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from bag-in-box formats capturing everyday consumption occasions and aluminum screw closures displacing natural cork in aging programs, requiring defensive repositioning around provenance authenticity and technical performance validation.
For Market Incumbents: Build lightweighting R&D capability moats through captive engineering partnerships with German and Italian specialized consultancies. Anchor furnace capacity in Bordeaux-Tuscany-Napa Valley clusters to defend against alternative format encroachment. Secure backward integration into compliant cold-end coating chemistries ahead of REACH expansion timelines. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer mixed-case shipper systems serving California and Oregon subscription channels. Target bag-in-box tap and film systems for German and UK convenience-driven households where incumbent glass producers lack service infrastructure. Lead with modular secondary packaging enabling variable bottle-count fulfillment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized decoration technology owners over commodity furnace operators. Five-to-ten year viability hinges on regulatory compliance automation capabilities and digital printing-convergence positioning. Watch for EU Packaging and Packaging Waste Regulation enforcement intensity as inflection signal for lightweighting investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Partnership | Verallia and Ardagh co-development programs with Bordeaux châteaux reduce bottle mass below 400 grams while maintaining structural integrity. |
| Alternative Closure Scale-Up | Guala Closures Group expansion of aluminum screw cap capacity matches natural cork oxygen transfer performance for Napa Valley reserve programs. |
| Digital Decoration Convergence | Direct-to-glass inkjet and laser etching capabilities enable lot-size-one customization for small-batch club-exclusive releases. |
| Bag-in-Box Channel Expansion | Amcor and Smurfit Kappa three-liter and five-liter multilayer film systems capture fastest volume growth in German everyday consumption. |
| Regulatory Compliance Automation | REACH substance tracking and EU Green Deal reporting systems reduce reformulation cycles for premium decoration chemistries. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with technical procurement directors at French and Italian premium wineries, plant managers at Ardagh and Verallia furnace facilities, and packaging specification leads at California direct-to-consumer subscription platforms. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, ECHA substance authorization databases, FDA food contact substance notifications, and Owens-Illinois SEC disclosure materials. Bottom-up volume triangulation across bottle weight categories, closure types, and application channels converged with top-down market sizing from customs trade flows and industry association production statistics.
Calibration against historical furnace capacity utilization rates and lightweighting program adoption curves anchored projection modeling across the analysis window. Segmentation dimensions included packaging type, material substrate, application channel, and end-user procurement sophistication tier. CAGRs were derived from trend extrapolation of EU regulatory compliance timelines, screw cap penetration rates in traditionalist wine regions, and bag-in-box volume displacement patterns in Northern European markets. Industry-specific inputs incorporated oxygen transfer rate performance benchmarks, REACH substance restriction phase-in schedules, and California SB 54 extended producer responsibility implementation milestones.
Sensitivities concentrate around EU Green Deal enforcement intensity, natural cork supply intermittency from Iberian montado ecosystems, and direct-to-consumer channel growth sustainability. Forecasts reflect documented assumptions regarding regulatory timeline adherence and substitution elasticity between glass and alternative formats. Material shifts in REACH chemical authorization scope or deposit-return scheme expansion beyond current municipal coverage would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Beer Packaging Market