
 Alcohol Packaging Market | 2026-2036
Alcohol Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Packaging Market Analysis
Mexico is tilting toward expanded aluminum can fabrication to serve North American beverage clients. Amcor leverages integrated film and container operations across multiple continents to sustain flexible packaging supply for spirits pouches. Owens-Illinois anchors high-volume glass bottle production through furnace upgrades in key manufacturing corridors. Ball Corporation competes aggressively in aluminum beverage can capacity, particularly for craft beer and ready-to-drink cocktails.
Alcohol packaging encompasses primary and secondary containment systems engineered to preserve organoleptic properties, prevent oxidation, and comply with beverage-specific migration limits. Glass bottles dominate premium spirits and wine segments due to inert barrier performance and established consumer perception, while aluminum cans gain structural share in beer and seltzer categories driven by recycling economics and logistics efficiency. Plastic and cardboard materials occupy niche positions in bulk shipping and airline miniatures, though regulatory scrutiny on microplastics constrains expansion. Closure type selection—cork versus screw cap versus crown—directly correlates with shelf-life requirements and brand positioning tiers across price segments.
The FDA governs food-contact substance notifications for alcohol packaging materials in the United States, while the EU Green Deal and REACH framework impose recycled content minimums and substance restrictions across European supply chains. These overlapping compliance architectures compel converters to maintain dual certification streams and traceability documentation. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return system expansions that will reshape collection infrastructure and material cost structures.
Market Dynamics
EU Green Deal mandates on recycled content minimums are compressing virgin glass and aluminum feedstock demand while forcing furnace retrofits across European manufacturing corridors. This regulatory pressure cascades through supply chains as converters scramble for certified secondary material streams.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated gases accelerate lightweight container designs and alternative barrier coatings in spirits packaging.
- Craft beverage proliferation:Small-batch distilleries and seltzer brands demand short-run aluminum can flexibility and premium glass embossing capabilities.
- Deposit-return system expansion:Germany and Scandinavian markets achieve closed-loop aluminum recovery rates above ninety percent, lowering effective material costs.
Market Restraints
- Energy cost volatility:Natural gas price spikes in Germany and Italy render continuous glass furnace operation uneconomical during winter peaks.
- Secondary material scarcity:Food-grade recycled aluminum and cullet availability concentrates in coastal logistics hubs, stranding inland converters.
- Migration limit complexity:REACH substance restrictions and FDA food-contact notifications impose divergent testing protocols that extend qualification timelines.
Strategic Opportunities
- India:FSSAI packaging regulations and PLI scheme incentives create openings for domestic aluminum can fabrication serving premium whiskey exports.
- Smart packaging convergence:NFC-enabled closures and blockchain traceability layers command price premiums in authenticated luxury spirits.
- Direct-to-consumer channels:Subscription wine clubs and craft distillery e-commerce bypass traditional three-tier distribution, favoring protective corrugated formats.
Industry Challenges
- Specialized furnace engineering talent:Oxy-fuel conversion and electric melting expertise resides with a shrinking cohort of European equipment specialists.
- Dual certification burden:Maintaining parallel REACH and FDA documentation streams strains quality assurance teams at mid-size converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Packaging Market |
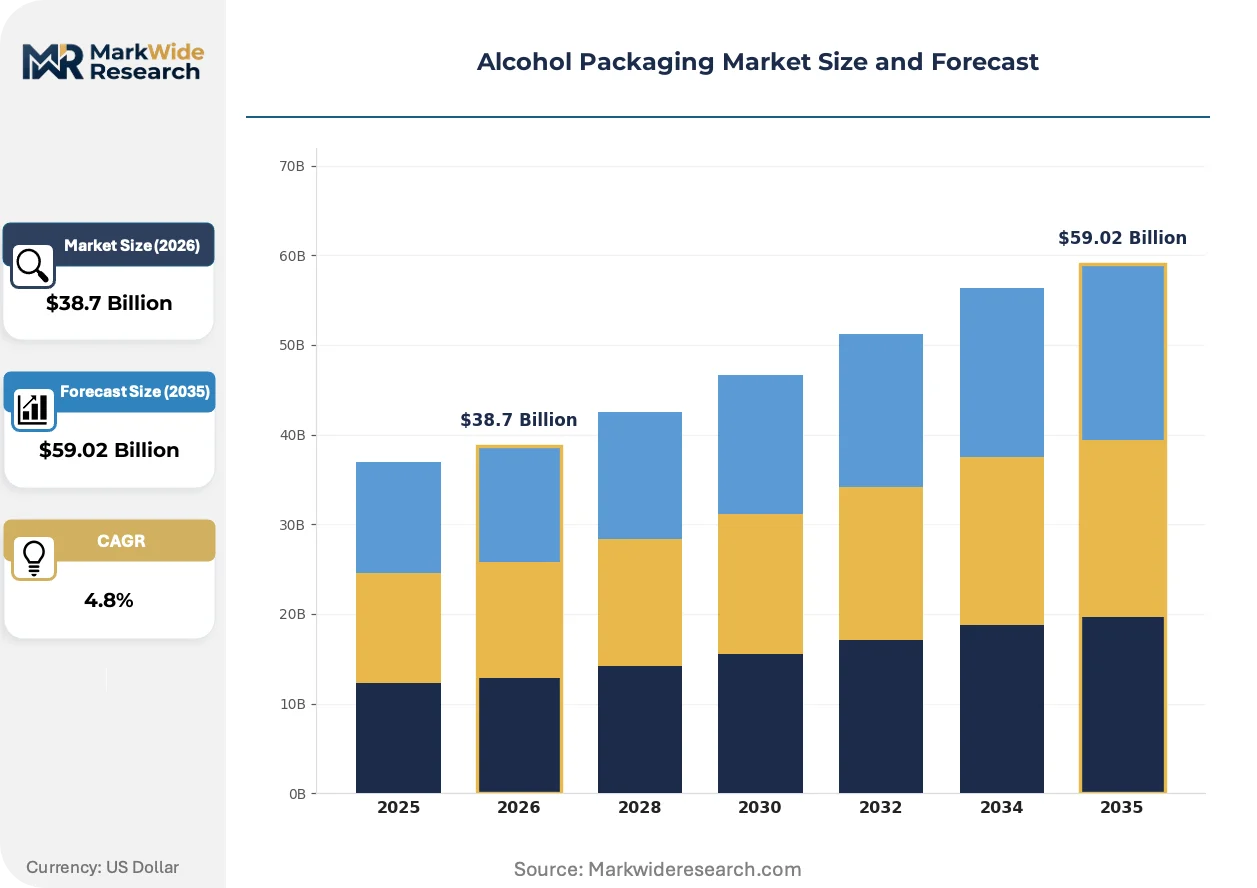
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Kegs, Pouches Material: Glass, Aluminum, Plastic, Cardboard Closure Type: Cork, Screw Cap, Flip Top, Crown End User: Retailers, Wholesalers, Distributors, Online Retailers |
| Companies Covered | Amcor, Owens-Illinois, Ball Corporation, Ardagh Group, Crown Holdings, Berlin Packaging, Vidrala, Gerresheimer, Verallia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Packaging Market Emerging Trajectories
Lightweighting technologies and digital printing are compressing minimum viable run lengths and eroding the traditional economies of scale that protected high-volume incumbents. These shifts favor agile converters with modular equipment footprints.
Ultralight glass bottle designs using finite element modeling are collapsing the weight differential between premium glass and aluminum formats for wine and spirits. Owens-Illinois and European specialists deploy these designs for luxury tequila and single-malt brands seeking reduced transport emissions without sacrificing heft perception. The structural consequence is collapsing demand for traditional heavyweight bottles in segments above fifty dollars retail.
EU Green Deal packaging and packaging waste regulations mandate recycled content thresholds and extended producer responsibility fees scaling with non-recyclable material choices. These rules force brand owners to redesign multi-material labels and adhesives that previously contaminated glass and aluminum recovery streams. Spirits producers in France and Italy now specify mono-material closures to avoid sorting penalties.
Buyer procurement patterns are consolidating volume with fewer converters capable of certifying carbon footprint data across Scope 1, 2, and 3 emissions. Large beverage groups in the United States and Germany now require supplier-specific lifecycle assessments as table stakes for RFP participation. This certification-driven preference shift most visibly concentrates contract awards in the Netherlands and California, where converters invested early in verified environmental product declarations.
Alcohol Packaging Market Segmentation
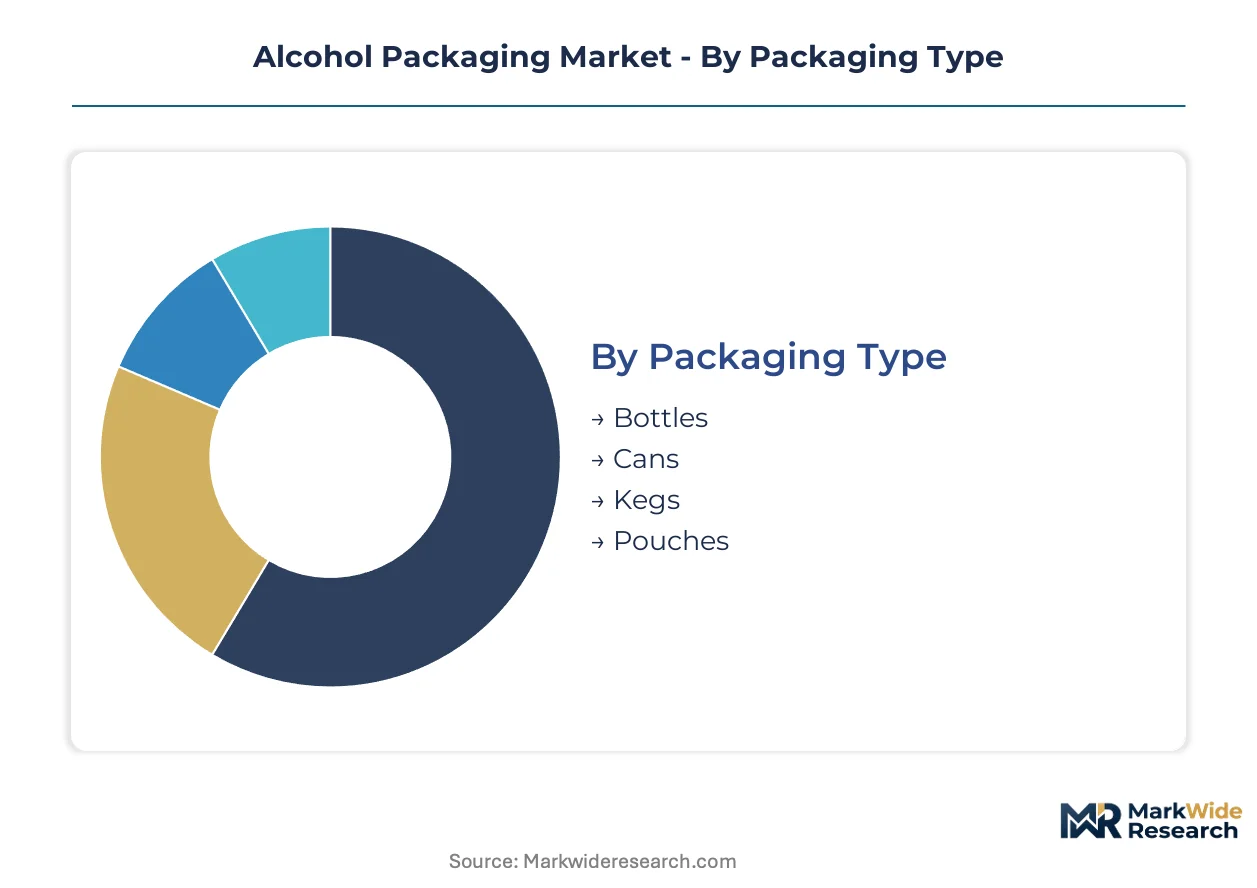
Alcohol packaging segmentation reflects divergent preservation requirements across beverage categories and the tension between premium perception and logistics efficiency. Each dimension—container format, material substrate, closure mechanism, and channel destination—carries distinct regulatory, cost, and brand-positioning implications that shape procurement decisions.
Packaging Type:
Container geometry dictates barrier performance, filling-line compatibility, and end-consumer usage rituals across consumption occasions.
- Bottles:Glass bottles dominate wine and premium spirits segments due to oxygen impermeability and established luxury signaling. Owens-Illinois furnaces in the United States and Germany supply embossed and silk-screened variants for single-malt whiskey and luxury tequila brands navigating EU Green Deal recycled content mandates.
- Cans:Aluminum two-piece cans are displacing glass in craft beer and hard seltzer categories where recycling economics and pallet density matter. Ball Corporation production lines in Mexico and the United States serve North American beverage clients with short-run digital printing capabilities.
- Kegs:Stainless steel and PET kegs circulate in on-premise draft systems for beer and cider, with deposit-return schemes in Germany and Scandinavian markets achieving recovery rates above ninety percent.
- Pouches:Flexible laminated pouches occupy airline miniatures and festival concessions where weight reduction trumps premium perception, though FDA food-contact notifications and EU migration limits constrain material choices.
Bottles hold installed capacity. Cans are rotating up the share rankings.
Material:
Substrate selection balances chemical inertness, recycled content availability, and furnace or extrusion energy intensity.
- Glass:Soda-lime silica formulations provide absolute barrier properties for oxidative-sensitive wines and aged spirits. European manufacturers face F-Gas Regulation pressure to convert oxy-fuel furnaces and secure food-grade cullet streams.
- Aluminum:Rolled canstock and impact-extruded bottles offer infinite recyclability and lightweight logistics. Demand concentrates in the United States and China where craft beverage proliferation and e-commerce fulfillment favor shatter-resistant formats.
- Plastic:PET and HDPE containers serve bulk shipping totes and airline miniatures, with REACH substance restrictions and emerging microplastic regulations in the European Union limiting expansion into premium segments.
- Cardboard:Corrugated formats and bag-in-box systems protect direct-to-consumer wine club shipments, with German and California converters investing in verified environmental product declarations to meet large beverage group procurement requirements.
Glass commands premium positioning. Aluminum is climbing the fastest.
Closure Type:
Sealing mechanism directly correlates with shelf-life engineering and price-tier signaling in consumer perception.
- Cork:Natural and agglomerated cork stoppers maintain dominance in Bordeaux and Burgundy wine segments where tradition and micro-oxygenation protocols are brand-defining. Portuguese and Spanish suppliers face competition from screw cap incursions in everyday wine tiers.
- Screw Cap:Aluminum ROPP closures and plastic continuous-thread designs secure spirits and New World wines, with Australian and New Zealand producers normalizing metal screw caps across all price points.
- Flip Top:Hinged polypropylene closures serve ready-to-drink cocktails and premium mixers in German and United States convenience channels.
- Crown:Crimped metal crowns remain standard for beer and cider bottles, with European producers specifying mono-material designs to avoid EU extended producer responsibility sorting penalties.
Cork retains ritual value. Screw cap is gaining share fastest.
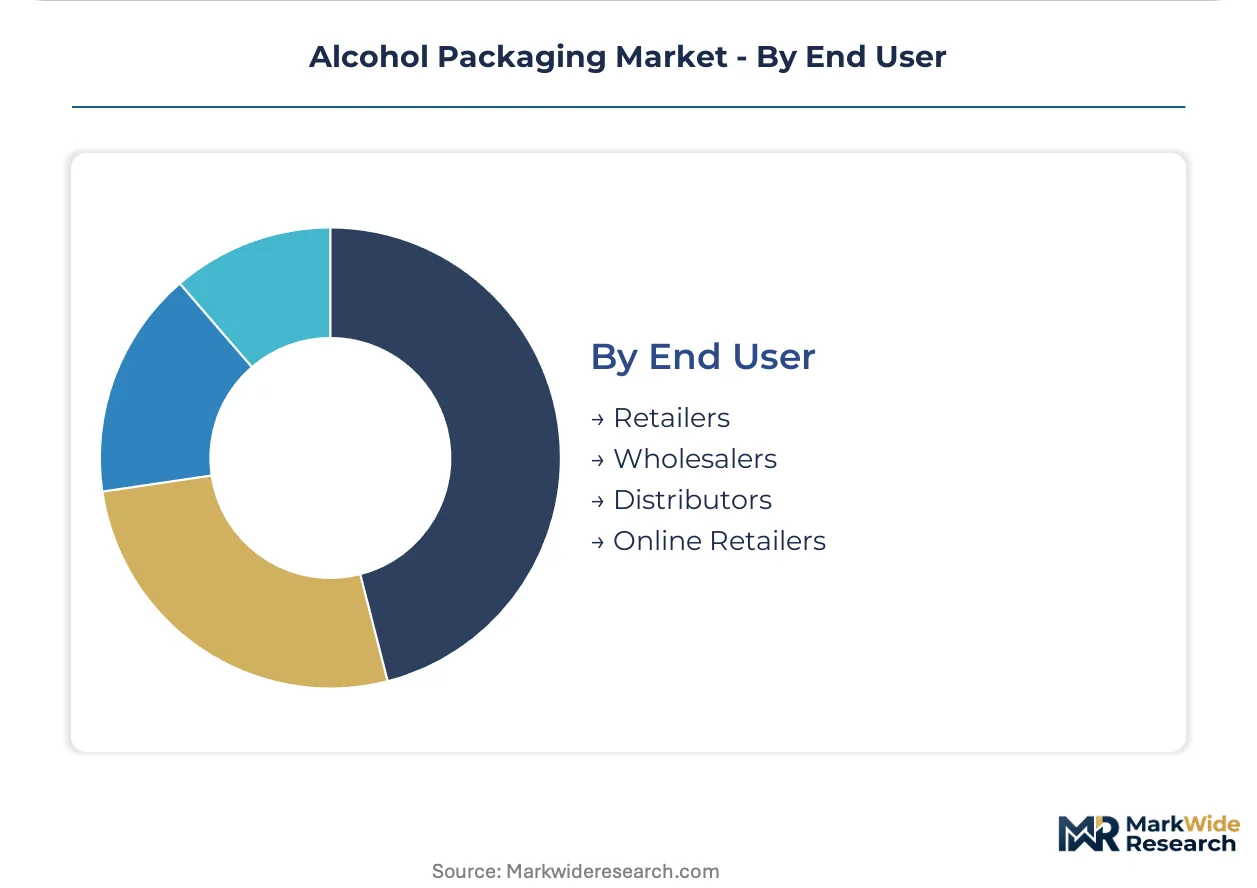
End User:
Channel destination determines order minimums, packaging mix complexity, and regulatory documentation burdens.
- Retailers:Supermarkets and liquor chains in the United States and Germany demand shelf-ready packaging with EPR-compliant labeling and carbon footprint data across Scope 1, 2, and 3 emissions.
- Wholesalers:Three-tier distribution intermediaries in North American alcohol markets specify durable corrugated shippers and mixed-SKU pallet configurations.
- Distributors:On-premise specialists supplying bars and restaurants prioritize keg return logistics and branded glassware programs.
- Online Retailers:Subscription clubs and e-commerce platforms in California and the Netherlands require protective molded pulp and air-cell cushioning to survive parcel carrier handling.
Retailers anchor volume concentration. Online retailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass furnace clusters in Germany, Italy, and the United States anchor primary capacity for premium spirits bottles. Aluminum can fabrication concentrates in Mexico and China to serve craft beverage export demand. Regulatory divergence between EU Green Deal mandates and FDA food-contact protocols fragments certification requirements across these manufacturing corridors.
United States
Craft distillery proliferation and hard seltzer brand expansion drive aluminum can demand in Texas and Colorado. The FDA maintains food-contact substance notification requirements for all packaging materials. Owens-Illinois operates high-volume furnace corridors in Ohio and Illinois serving bourbon and tequila brands with embossed glass formats.
Germany
Deposit-return system infrastructure achieves closed-loop aluminum recovery rates above ninety percent, lowering effective material costs for beverage clients. The EU Green Deal and F-Gas Regulation mandate recycled content minimums and lightweight container designs. Verallia and Gerresheimer anchor glass production in Bavaria and North Rhine-Westphalia with oxy-fuel furnace retrofits.
China
Domestic whiskey consumption growth and e-commerce fulfillment requirements favor shatter-resistant aluminum formats. SAMR and GB standards govern food-contact packaging migration limits. Ball Corporation and Crown Holdings operate can fabrication clusters in Guangdong and Zhejiang provinces serving premium spirits exporters.
Mexico
Nearshoring advantages for North American beverage clients accelerate aluminum can capacity expansion in Nuevo León and Jalisco. The country's environmental regulator enforces extended producer responsibility frameworks for packaging waste. Ardagh Group and Crown Holdings anchor production corridors supplying craft beer and ready-to-drink cocktail brands.
India
Premium whiskey export growth creates demand for aluminum can and glass bottle fabrication serving Middle Eastern and African markets. FSSAI packaging regulations and PLI scheme incentives support domestic manufacturing capacity. Mumbai and Pune clusters host emerging converter operations targeting authenticated spirits packaging with NFC-enabled closures.
Alcohol Packaging Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and closure engineering. The vendor base spans three structural tiers: multinational converters with continental furnace networks, regional specialists in short-run digital printing, and niche players in authenticated luxury formats. Strategic archetypes include sustainability-certification leaders, flexible-run digital converters, and premium-embossing specialists. Competitive dynamics center on M&A consolidation for furnace capacity and strategic partnerships for closed-loop aluminum supply.
Among North American-based converters, Owens-Illinois and Ball Corporation exemplify divergent platform strategies—one anchored in glass furnace infrastructure, the other in aluminum rolling and can fabrication. European specialists including Ardagh Group and Verallia occupy positions defined by EU Green Deal compliance capabilities and oxy-fuel retrofit expertise. Amcor represents the flexible-format archetype with integrated film and container operations spanning multiple continents.
| Leading Market Players |
|---|
| Amcor |
| Owens-Illinois |
| Ball Corporation |
| Ardagh Group |
| Crown Holdings |
| Berlin Packaging |
| Vidrala |
| Gerresheimer |
| Verallia |
| Others |
Supply Flow & Price Mechanics
Food-grade cullet concentration in coastal European logistics hubs anchors margin capture for glass converters serving premium spirits brands, while inland furnace operators absorb higher feedstock transport costs that compress operating leverage.
Pricing Analysis
EU Green Deal mandates dictate the pricing tier structure across container formats, with recycled-content certification separating premium glass contracts from standard-grade aluminum can supply. Price differentiation hinges on Scope 3 carbon footprint verification and FDA dual-certification status, with large beverage groups in Germany and the United States demanding supplier-specific lifecycle assessments as table stakes. Cost compression in standard-grade aluminum canstock is intensifying because Mexican fabrication capacity expansion feeds North American spot market liquidity. Contract brewers and small-batch distilleries exhibit highest price sensitivity, while authenticated luxury spirits brands absorb premium closures with NFC-enabled traceability layers.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for aluminum canstock procurement, with converters diversifying rolling mill relationships across Mexico and Germany to mitigate duty regime uncertainty. Raw material dependencies center on bauxite refining capacity, food-grade cullet sorting infrastructure, and soda-lime silica batch formulations. Single-source vulnerability concentrates in oxy-fuel furnace engineering expertise resident with European equipment specialists. Distribution runs through three-tier alcohol distribution intermediaries in North America, direct-to-consumer corrugated shippers in California and the Netherlands, and deposit-return system logistics in Germany and Scandinavian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing and short-run aluminum can flexibility represent the fastest-expanding service layers, outpacing traditional glass furnace volume commitments as craft beverage proliferation fragments order profiles.
For Market Incumbents: Entrench market position through backward integration into certified secondary material streams and captive oxy-fuel retrofit engineering capabilities. Defend against agile digital converters by locking multi-year furnace supply agreements with bourbon and tequila brands seeking embossed glass formats. Prioritize EU Green Deal compliance documentation as a competitive moat against mid-size rivals strained by dual certification burdens. For New Entrants and Emerging Players: Short-run spirits pouch fabrication for airline miniatures and festival concessions represents the most penetrable entry point, with flexible laminated formats escaping capital-intensive furnace economics. Target Indian domestic aluminum can capacity serving premium whiskey exports to Middle Eastern markets, leveraging FSSAI packaging regulations and PLI scheme incentives as regulatory tailwinds. Pursue partnership routes with established film laminators rather than greenfield extrusion investment. For Investors and Strategic Acquirers: Capital is best deployed toward sustainability-certification leaders with verified environmental product declarations and closed-loop aluminum supply partnerships. Long-term viability favors converters with modular equipment footprints capable of compressing minimum viable run lengths. Monitor deposit-return system expansion announcements in new geographies as the signal indicating material cost structure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | Verallia and Gerresheimer investments in Bavaria align with EU F-Gas Regulation phase-down schedules. |
| Closed-Loop Aluminum Partnership | Ball Corporation supply agreements with German deposit-return infrastructure secure sub-market cullet pricing. |
| Digital Printing Capability | Mexican can fabrication clusters attract craft beer brands seeking short-run label flexibility. |
| Dual-Certification Investment | Mid-size converters strain quality assurance teams maintaining parallel REACH and FDA documentation streams. |
| NFC-Enabled Closure Development | Mumbai and Pune specialists target authenticated spirits packaging with blockchain traceability premiums. |
Methodological Framework
Operator-level perspectives from furnace engineering directors, procurement leads at large beverage groups, regulatory affairs specialists navigating REACH and FDA protocols, and channel sales heads at aluminum rolling mills anchored the qualitative base. Secondary validation drew from EU Green Deal implementation documents, FDA food-contact substance notification databases, SEC 10-K disclosures by publicly traded converters, and customs records tracking aluminum canstock trade flows. Bottom-up volume modeling across container formats triangulated against top-down macroeconomic demand indicators.
Scenario-bracketing around regulatory implementation timelines and energy price volatility bounds the projection outputs across the analysis window. Segmentation dimensions modeled include packaging type, material substrate, closure mechanism, and channel destination, with beverage-specific migration limits and carbon footprint certification tiers as cross-cutting variables. CAGRs were derived from trend extrapolation of historical volume data adjusted for policy-driven inflection points. Forecast inputs incorporated furnace capacity utilization rates and deposit-return system recovery efficiency assumptions.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing regimes, aluminum LME volatility, or EU packaging waste fee schedules would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and secondary material availability expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market