
 Corrugated Wine Carrier Market | 2026-2036
Corrugated Wine Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Wine Carrier Market Outlook
Aftermarket customization services is reconfiguring margin capture across the corrugated wine carrier value chain. Smurfit Kappa Group leverages its European mill network to anchor supply security for premium wineries. DS Smith differentiates through circular design protocols that sustain closed-loop fiber recovery. WestRock competes on integrated containerboard-to-converting scale across North American distribution corridors.
A corrugated wine carrier is a fiber-based protective enclosure, typically constructed from E-flute or B-flute corrugated fiberboard with 150–300 gsm liner weights, engineered to immobilize glass bottles during transit while presenting printable surfaces for brand communication. Its primary commercial purpose is to merge physical protection with shelf-ready aesthetics in direct-to-consumer and retail wine distribution. Recycled paperboard and corrugated fiberboard dominate material selection as wineries prioritize post-consumer fiber content for sustainability credentials. Custom shaped and handle design variants command premium positioning in hospitality and gift segments where unboxing experience drives repeat purchase behavior.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recyclability thresholds that reshape material specifications across European wine logistics. FDA food contact substance notifications govern corrugated structures intended for beverage proximity in United States interstate commerce, while FSC chain-of-custody certification increasingly gates access to major retail and e-commerce procurement programs. Stakeholders must monitor how evolving single-use packaging restrictions in key wine-exporting jurisdictions redefine acceptable design formats and recovery infrastructure requirements.
Market Dynamics
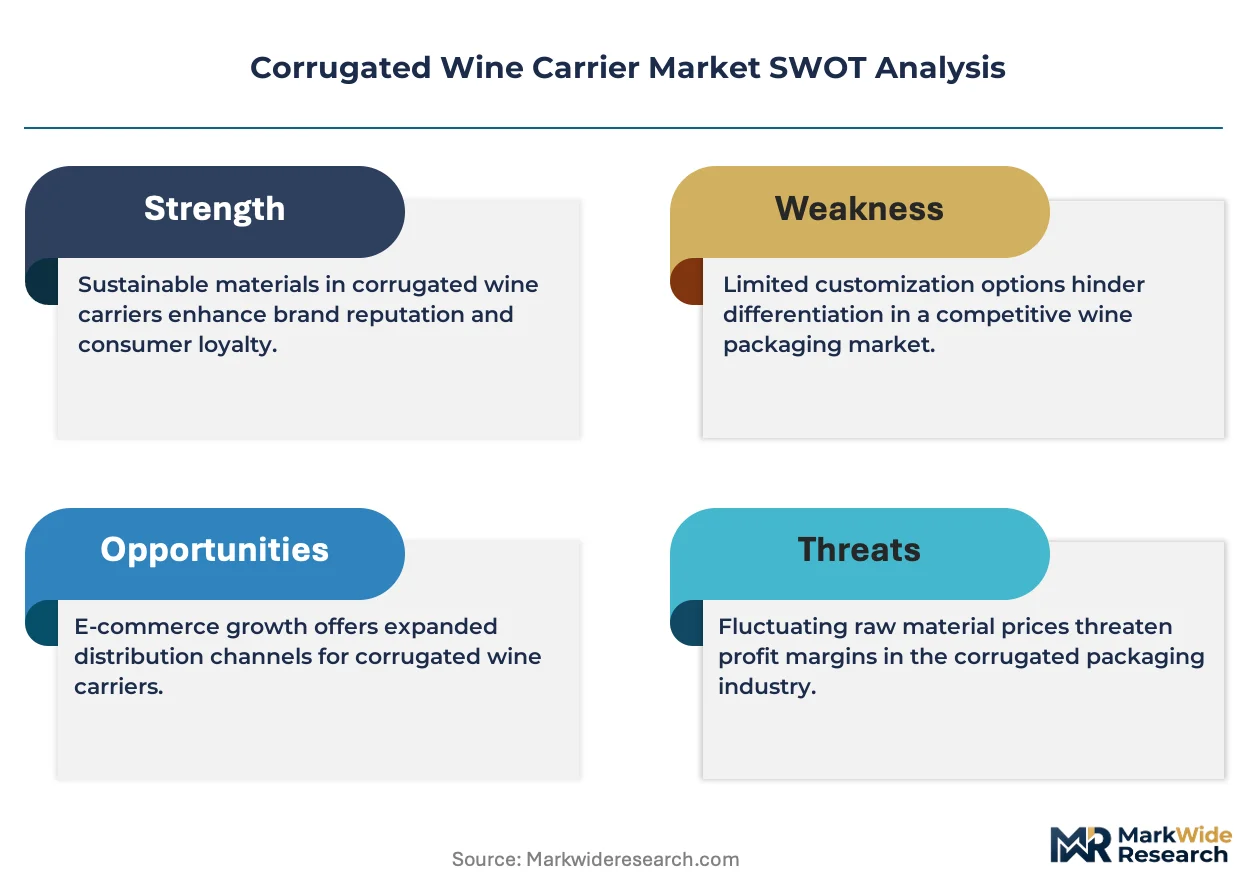
E-commerce fulfillment networks are compressing order-to-delivery windows for wine shipments, forcing corrugated converters to engineer protective structures that withstand automated sortation while preserving premium unboxing aesthetics for direct-to-consumer brands.
Growth Catalysts
- E-commerce fulfillment acceleration:Online wine sales through dedicated beverage platforms and generalist marketplaces are expanding addressable demand for ship-ready corrugated enclosures that eliminate secondary overboxing.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates across France, Italy, and Spain are compelling wineries to specify recyclable fiber-based carriers with verified post-consumer content.
- Micro-flute advancement:E-flute and F-flute corrugating technologies enable thinner-wall constructions that reduce dimensional weight charges while maintaining column-crush resistance for glass bottle protection.
Market Restraints
- Containerboard cost volatility:Kraft linerboard and recycled medium pricing fluctuations in European and North American pulp markets compress converter margins and complicate annual contract negotiations with winery procurement teams.
- Mill concentration in Nordic region:Supply security for virgin fiber-based liners depends on a concentrated Scandinavian producer base vulnerable to energy cost spikes and logistics disruptions.
- Plastic crate reusability:Returnable HDPE beverage crates in on-premise hospitality channels limit corrugated penetration in high-turnover restaurant and hotel supply chains.
Strategic Opportunities
- Direct-to-consumer subscription models:Curated wine clubs in the United States and United Kingdom are creating recurring demand for branded, gift-ready carrier formats that reinforce unboxing experience and social sharing.
- Digital print integration:Single-pass inkjet and water-based flexographic systems enable economical short-run customization for vintage-specific releases and limited-edition collaborations.
- CSRD-aligned carbon accounting:The EU Corporate Sustainability Reporting Directive creates procurement preference for corrugated suppliers offering verified lifecycle emissions data and closed-loop fiber recovery documentation.
Industry Challenges
- FSC chain-of-custody certification complexity:Multi-site converting operations struggle to maintain audit-ready documentation across toll-manufacturing relationships and spot-market fiber purchases.
- Automated packaging line integration:Ergonomic hand-pack designs must retrofit to existing winery bottling and fulfillment equipment without capital-intensive line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Wine Carrier Market |
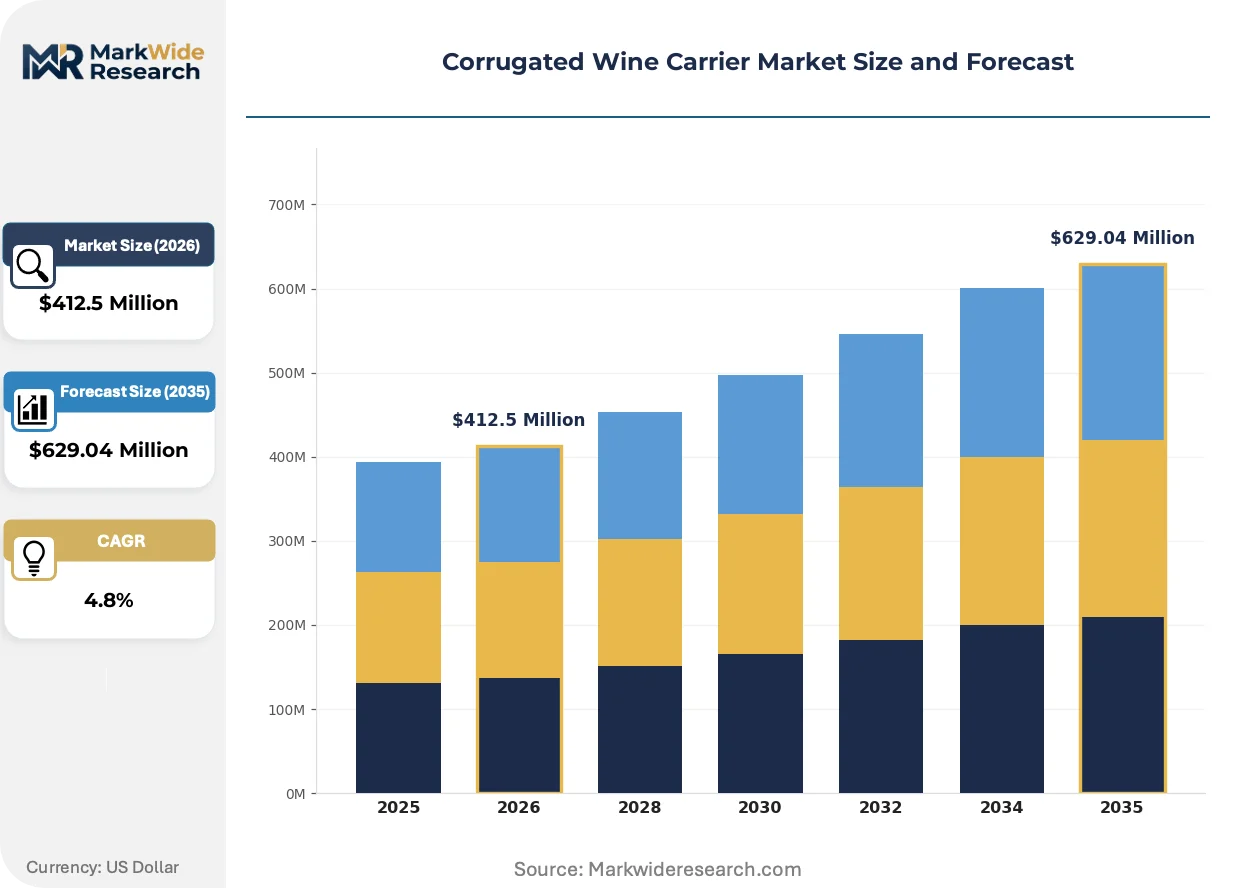
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Recycled Paperboard, Solid Bleached Sulfate, Corrugated Fiberboard, Kraft Paper Design Type: Single Bottle, Multi-Bottle, Custom Shaped, Handle Design End User: Wineries, Retailers, E-commerce, Hospitality Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Smurfit Kappa Group, International Paper, DS Smith, Mondi plc, WestRock, Packaging Corporation of America, Marber S.r.l., Shenzhen Qingxin Packaging Co. Ltd, Acorn Paper Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Wine Carrier Market Strategic Shifts
Structural design automation and regulatory disclosure requirements are converging to redefine how corrugated wine carriers balance protection performance with environmental accountability across the value chain.
Barrier-coated recycled fiberboard is hybridizing moisture resistance and printability in a single substrate layer. Premium wineries in California and Bordeaux are specifying these constructions for cellar-aged releases requiring humidity tolerance during extended distribution cycles. The technology is compressing demand for laminated plastic films that previously compromised end-of-life recyclability.
France's AGEC law and the broader EU Green Deal are mandating recyclability-by-design protocols that prohibit multi-material laminations in single-use packaging. Corrugated specifications across French cooperatives now exclude wax-impregnated or polyethylene-coated liners previously common for ice-pack compatibility. Italian exporters are responding with water-based barrier formulations that satisfy both French import requirements and domestic ANCC packaging registry obligations.
Subscription box procurement teams are consolidating supplier relationships around vertically integrated converters offering design-to-delivery accountability. This behavior compresses the vendor base for mid-size wineries that previously sourced carriers through fragmented broker networks. The shift is most visible in the United Kingdom, where Naked Wines and similar platforms specify sole-source corrugated partnerships with dedicated account engineering support.
Corrugated Wine Carrier Market Segmentation
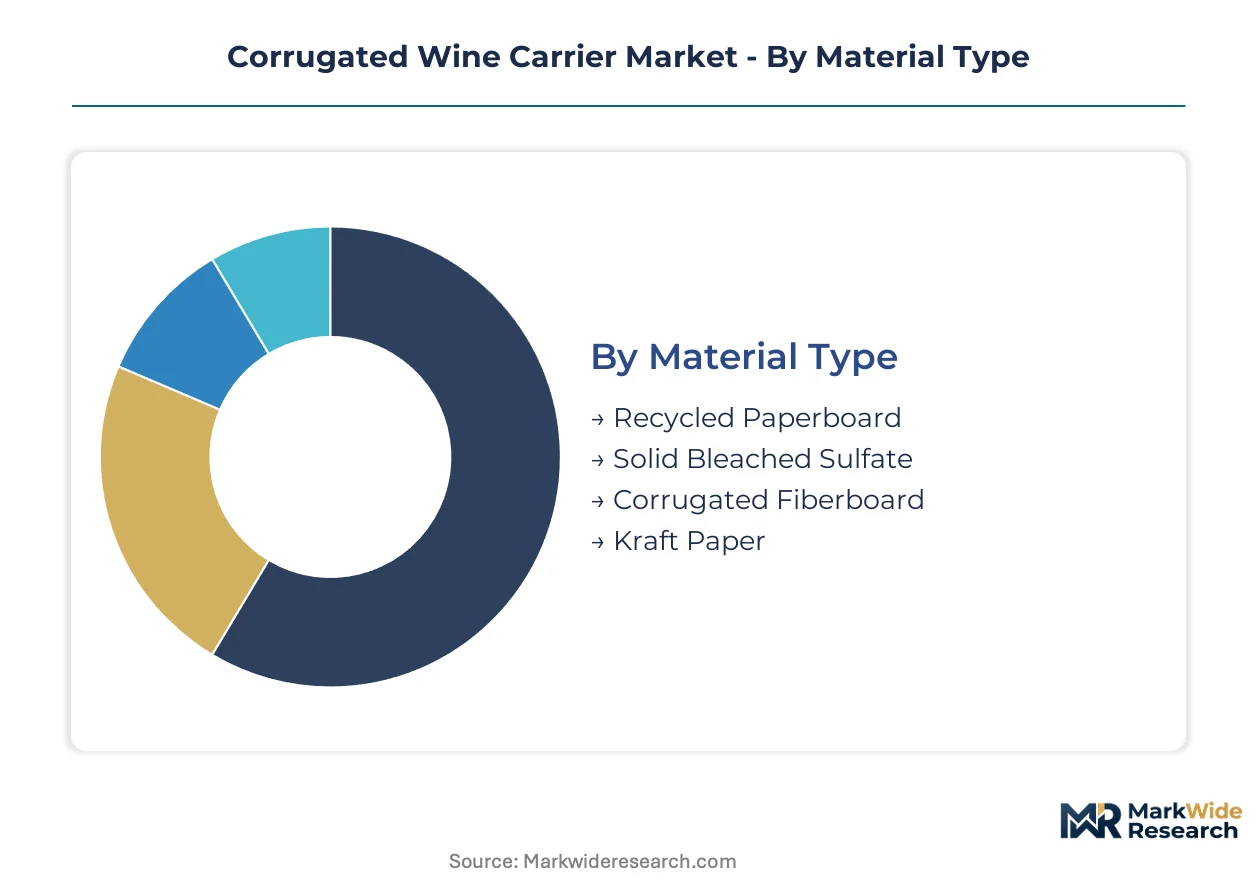
Segmentation in corrugated wine carriers reflects divergent performance requirements across material science, structural engineering, and channel economics. Procurement specifications vary sharply between mass-market retail fulfillment and premium direct-to-consumer unboxing experiences.
Material Type:
Mature fiber recovery infrastructure dominates sourcing decisions, though emerging barrier technologies are reshaping specifications for climate-sensitive distribution.
- Recycled Paperboard:Post-consumer fiber content exceeding 80% satisfies EU Packaging and Packaging Waste Regulation mandates for French and Italian export shipments. Demand concentrates in supermarket private-label programs where cost discipline overrides premium tactile properties.
- Corrugated Fiberboard:E-flute and B-flute constructions deliver calibrated crush resistance for automated sortation systems while maintaining printable surfaces for brand communication. E-commerce fulfillment networks in the United States and United Kingdom specify these grades for dimensional weight optimization.
- Solid Bleached Sulfate:Virgin fiber purity enables high-fidelity lithographic printing for luxury gift presentations and vintage-specific releases. Hospitality channel procurement in Spain favors this substrate for cellar-door retail experiences.
- Kraft Paper:Unbleached natural aesthetic aligns with organic and biodynamic winery positioning, though moisture sensitivity limits deployment in humid distribution corridors.
Corrugated fiberboard handles the majority of throughput; recycled paperboard is gaining share fastest as regulatory pressure tightens across EU member states.
Design Type:
Volume concentration follows channel economics, with automation compatibility and unboxing experience pulling specifications in opposing directions.
- Multi-Bottle:Four- and six-bottle configurations standardize palletization efficiency for retail distribution while accommodating mixed-case curation for subscription services. United Kingdom wine clubs drive specification refinement for insert-based bottle immobilization.
- Single Bottle:Slim-profile constructions minimize dimensional weight charges for individual shipment economics in direct-to-consumer channels. California wineries specify these formats for tasting-room shipping programs.
- Handle Design:Integrated die-cut carriers serve hospitality restocking and event catering where portability substitutes for secondary bagging.
- Custom Shaped:Irregular die-lines and windowed apertures command premium positioning in gift segments where shelf differentiation drives selection.
Multi-bottle formats anchor procurement volume; single-bottle designs are expanding most quickly as e-commerce penetration deepens.
End User:
Customer type determines specification rigor, from automated line integration requirements to aesthetic presentation thresholds.
- E-commerce:Ship-ready specifications eliminate overboxing through integrated protection and branded exterior surfaces. Platform procurement teams in the United States consolidate supplier relationships around drop-test certification and unboxing experience scoring.
- Wineries:Bottling line compatibility and vintage-specific customization drive converter selection, with Bordeaux cooperatives emphasizing FSC chain-of-custody documentation.
- Retailers:Pallet efficiency and shelf-ready display properties govern corrugated specifications for supermarket and specialty store distribution.
- Hospitality:High-turnover restaurant supply chains favor standardized formats compatible with existing storage infrastructure and rapid restocking protocols.
E-commerce channels concentrate the steepest specification evolution; wineries maintain the most fragmented supplier relationships.
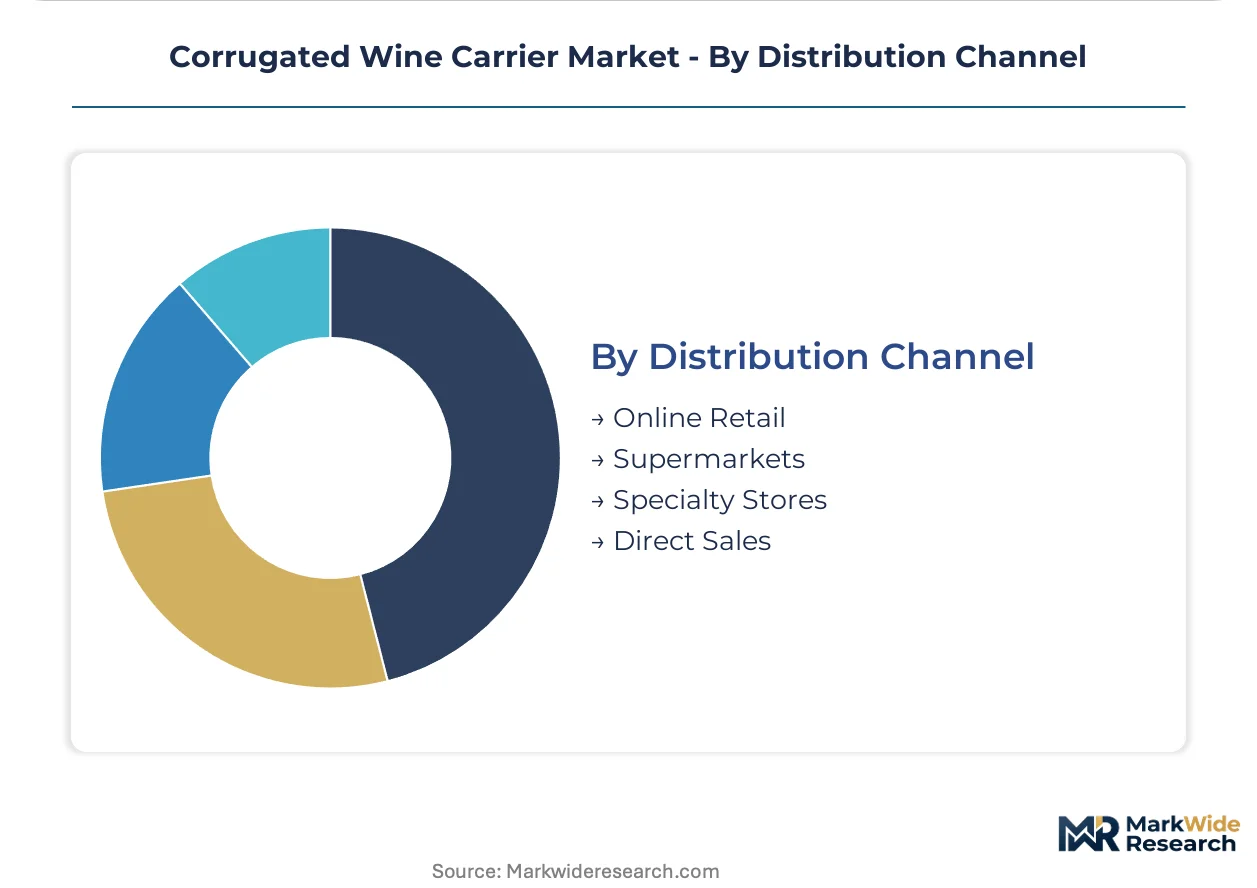
Distribution Channel:
Channel configuration dictates protective performance requirements and branding surface investment.
- Online Retail:Automated sortation survivability and consumer-facing print quality merge in specifications from dedicated beverage platforms and generalist marketplaces. United Kingdom subscription services drive innovation in tear-strip opening mechanisms.
- Direct Sales:Tasting-room and cellar-door shipments prioritize premium tactile substrates and vintage-specific customization for tourist souvenir conversion.
- Supermarkets:Pallet optimization and shelf-ready display efficiency dominate corrugated specifications for high-volume retail distribution.
- Specialty Stores:Curated assortment presentation favors distinctive structural designs that signal provenance and quality tier at point of purchase.
Online retail absorbs the fastest-growing volume share; direct sales commands the highest unit specification investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Containerboard mill capacity clusters in the Nordic region and North American Southeast, creating supply dependencies that ripple through corrugated converter networks serving wine-exporting regions. France, Italy, and Spain anchor European procurement volumes, while California and Australian viticulture zones drive Pacific Rim specifications.
France
Bordeaux and Champagne export cooperatives sustain carrier demand for FSC-certified formats with verified post-consumer fiber content. AGEC law mandates recyclability-by-design protocols that exclude wax-impregnated liners previously standard for temperature-controlled shipments. Lille-Roubaix converting clusters engineer water-based barrier formulations satisfying both domestic ANCC registry and cross-border Italian export requirements.
Italy
Tuscany and Piedmont wineries specify E-flute constructions for US and UK direct-to-consumer channels where dimensional weight optimization reduces freight costs. EU Packaging and Packaging Waste Regulation compliance documentation gates access to French supermarket private-label programs. Bologna packaging machinery manufacturers retrofit automated erecting equipment for micro-flute wine carrier formats.
Spain
Rioja and Ribera del Duero bodegas prioritize pallet-efficient six-bottle configurations for German and Benelux retail distribution. ECHA guidance on food-contact substances shapes linerboard selection for carriers storing wine in proximity to chilled gel packs. Barcelona corrugated specialists integrate digital print systems for vintage-specific short runs targeting hospitality channel procurement.
United States
Napa and Sonoma direct-to-consumer subscription programs drive specifications for tear-strip opening mechanisms and premium unboxing surfaces. FDA food contact substance notifications govern interstate commerce structures intended for beverage proximity. Pacific Northwest containerboard mills supply virgin kraft liners to California converters serving tasting-room shipping operations.
Australia
Barossa Valley and Margaret River exporters specify humidity-tolerant barrier-coated fiberboard for extended sea-freight distribution to UK and US markets. Australian Packaging Covenant targets divert corrugated recovery infrastructure toward closed-loop fiber systems. Melbourne converting operations align with CSRD-aligned carbon accounting requirements from EU-importing distributor procurement teams.
Corrugated Wine Carrier Market Competitive Environment
Vertically integrated European mill-converter networks and North American containerboard specialists split the market between supply-security and scale-driven procurement channels. Consolidation concentrates around three strategic archetypes: fiber-integrated multinationals anchoring annual contract negotiations, regional specialists engineering vintage-specific customization, and Asia-Pacific fabricators competing on short-run digital print economics. Capacity expansion and circular design certification represent the dominant competitive moves reshaping converter-vintner relationships.
Within the fiber-integrated tier, Smurfit Kappa Group and DS Smith exemplify European supply-security positioning, while WestRock occupies a scale-driven position across North American distribution corridors. Shenzhen Qingxin Packaging Co. Ltd represents Asia-Pacific short-run specialization. These anchors illustrate how geographic mill proximity, regulatory compliance documentation, and digital print integration differentiate procurement relationships without guaranteeing specific customer outcomes.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| International Paper |
| DS Smith |
| Mondi plc |
| WestRock |
| Packaging Corporation of America |
| Marber S.r.l. |
| Shenzhen Qingxin Packaging Co. Ltd |
| Acorn Paper Products |
| Others |
Value Chain & Pricing Dynamics
Trans-Atlantic container freight corridors from Nordic kraft linerboard mills to Bordeaux and Napa converting operations transmit pulp cost volatility directly into corrugated wine carrier contract negotiations. Supply concentration in Scandinavian virgin fiber production amplifies converter pricing power asymmetries, while e-commerce fulfillment economics force downstream price differentiation between automated-line-compatible and hand-pack premium formats.
Pricing Analysis
After-sales customization services including vintage-specific digital print and FSC certification documentation drive lifetime value capture for corrugated specialists. Contract-based long-term offtake agreements dominate procurement relationships, with price differentiation anchored in post-consumer fiber content thresholds and barrier-coating technology tiers. Cost compression in standard-grade recycled paperboard intensifies as supermarket private-label programs consolidate volume around sole-source suppliers. Mass-market retail buyers exhibit highest price sensitivity, while direct-to-consumer subscription platforms prioritize unboxing experience over unit cost.
Supply Chain Analysis
Tariff exposure between Nordic kraft linerboard producers and EU converting clusters dominates supply chain risk assessment for corrugated wine carrier procurement. Geographic supply concentration centers on Sweden, Finland, and Norway for virgin fiber liners, with secondary recycled medium sourcing from German and French recovered paper markets. Raw material dependencies include kraft pulp, recycled OCC grades, and water-based barrier coatings. Single-source vulnerability persists in specialized micro-flute corrugating machinery. Distribution runs through vertically integrated mill-converter networks and fragmented regional specialists serving winery bottling line integration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corrugated wine carrier incumbents face sustained substitution pressure from returnable HDPE beverage crates penetrating hospitality restocking channels. Defense requires structural moves that embed fiber-based solutions deeper into e-commerce fulfillment workflows where reusability economics falter.
For Market Incumbents: Entrench supply security through backward integration into Nordic kraft linerboard sourcing or captive recycled fiber recovery infrastructure. Prioritize CSRD-aligned carbon accounting documentation to gatekeeper EU distributor procurement programs against plastic crate substitution. Defensive capacity positioning in Lille-Roubaix and Barcelona converting clusters anchors annual contract negotiations with Bordeaux and Rioja cooperatives.
For New Entrants and Emerging Players: Australian and South American wine export corridors present geographic underpenetration for humidity-tolerant barrier-coated fiberboard specialists. Target Margaret River and Barossa Valley exporters requiring extended sea-freight protection for UK and US direct-to-consumer channels. White-space exists in short-run digital print subscription box partnerships outside consolidated UK vendor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underperforming wine-specific converting divisions. Long-term viability hinges on e-commerce penetration sustaining ship-ready corrugated demand against reusable crate hospitality encroachment. Acquisition archetypes include regional specialists with FSC chain-of-custody certification and automated line integration engineering capabilities. Monitor EU Packaging and Packaging Waste Regulation enforcement timelines as inflection indicator for fiber-based carrier procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Linerboard | Captive supply from Nordic mills insulates Smurfit Kappa and DS Smith against pulp cost volatility. |
| Digital Print Platform Deployment | Single-pass inkjet systems at Barcelona converters enable vintage-specific short runs for hospitality channels. |
| FSC Chain-of-Custody Certification | Audit-ready documentation gates access to French supermarket private-label procurement programs. |
| Barrier-Coating R&D Partnership | Water-based formulations from Lille-Roubaix clusters satisfy AGEC law recyclability mandates. |
| Subscription Box Sole-Source Contracting | Naked Wines-style partnerships consolidate fragmented UK mid-size winery supplier relationships. |
Study Parameters
A spread of perspectives from corrugated converter operations directors, winery procurement managers, e-commerce fulfillment platform category leads, and FSC certification auditors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Packaging and Packaging Waste Regulation implementation guidance, FDA food contact substance notification databases, and containerboard trade flow customs records. Bottom-up volume modeling from individual winery carrier specifications triangulated against top-down corrugated packaging industry aggregates.
Demand-supply balance framing anchored the forecast analytical framework across the projection horizon. Segmentation dimensions modeled include material type, design configuration, end-user channel, and distribution format. CAGRs derived from recursive least-squares fitting to historical corrugated wine carrier procurement data, adjusted for e-commerce penetration trajectories and EU regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs incorporated micro-flute technology adoption curves and digital print run-length economics.
Practitioners should monitor EU member state extended producer responsibility enforcement schedules and Nordic kraft linerboard energy cost spikes for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market