
 Alcoholic Drinks Packaging Market | 2026-2036
Alcoholic Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Alcoholic Drinks Packaging Market Outlook
EU Green Deal packaging waste rules is restructuring capital allocation across European bottling operations. Crown Holdings leverages its aluminum can capacity to capture share in carbonated ready-to-drink cocktails. Owens-Illinois sustains dominant position in returnable glass bottle systems for European brewers. Amcor anchors its growth in lightweight PET innovations for wine and spirits exporters.
Alcoholic drinks packaging encompasses primary and secondary containment systems engineered to preserve organoleptic properties, prevent oxidation, and comply with volume measurement standards, typically incorporating barrier coatings, tamper-evident closures, and impact-resistant geometries. Glass bottles retain the largest value share in spirit and wine segments where weight and tactile quality signal premium positioning, while aluminum cans represent the fastest-expanding format in craft beer and hard seltzer categories driven by portability and recycling efficiency. Closure type selection increasingly functions as a margin determinant, with screw caps displacing natural cork in mid-tier wine and crown caps dominating beer due to sealing reliability and line speed compatibility.
The US EPA regulates volatile organic compound emissions from glass manufacturing furnaces, while FDA sets migration limits for packaging materials contacting alcoholic beverages; in Europe, EFSA enforces specific migration limits under framework regulation 1935/2004. These layered compliance requirements elevate testing costs and disqualify non-conforming suppliers from branded alcohol supply chains. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return system expansions that will reshape format economics and regional manufacturing footprints.
Market Dynamics
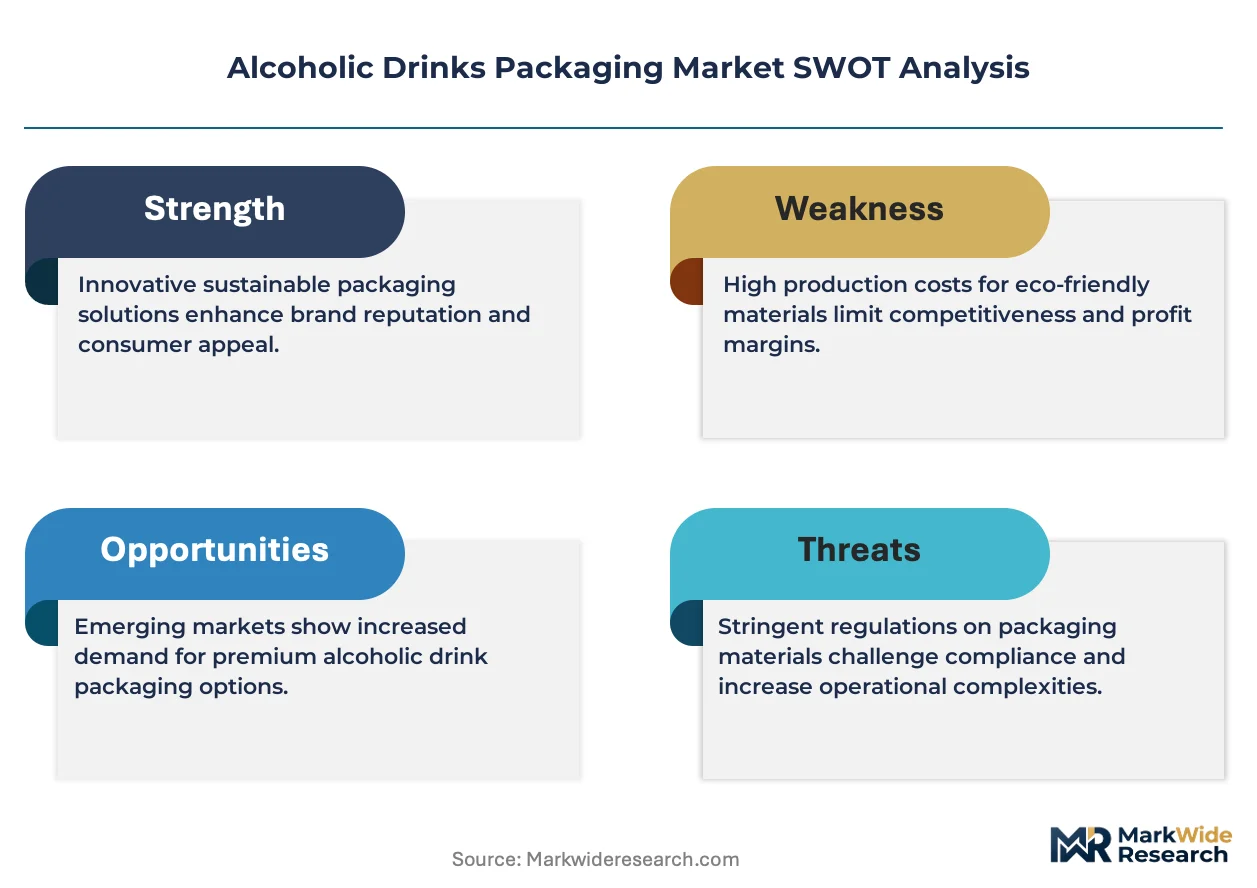
The EU Green Deal's packaging waste directives are forcing material transitions across alcoholic drinks packaging operations, restructuring capital allocation toward lighter formats and recycled content mandates while premium spirits brands simultaneously pull demand toward heavier embossed glass.
Growth Catalysts
- Deposit-Return System Expansions:Germany's DRS expansion and similar frameworks across Nordic markets are accelerating demand for returnable glass bottle systems and aluminum can formats designed for closed-loop recovery.
- Carbonated RTD Cocktail Surge:Ready-to-drink cocktail brands are driving aluminum can capacity expansion as portability and single-serve convenience reshape on-premise and off-premise consumption patterns.
- Lightweight PET Innovation:Wine and spirits exporters are adopting barrier-coated PET bottles to reduce freight costs and breakage rates in long-haul distribution corridors.
Market Restraints
- Energy Cost Volatility:Natural gas price swings directly impact glass furnace operating economics, squeezing margins for container glass manufacturers concentrated in energy-intensive European production clusters.
- Recycled Glass Supply Constraints:High-quality cullet availability remains geographically concentrated, limiting closed-loop production scale-up for premium spirits bottles requiring optical clarity.
- Migration Limit Compliance:EFSA's specific migration limits under framework regulation 1935/2004 elevate testing costs and disqualify non-conforming suppliers from branded alcohol supply chains.
Strategic Opportunities
- India's Alcoholic Beverage Liberalization:State-level excise reforms and organized retail expansion are creating first-mover advantages for packaging suppliers establishing local PET and aluminum can production.
- Smart Closure Integration:NFC-enabled and tamper-evident closure technologies are converging with blockchain traceability systems to serve premium authentication demands in spirits.
- Extended Producer Responsibility Tailwinds:France's Citeo and similar eco-modulation schemes are rewarding lightweight, recyclable formats with fee reductions, incentivizing material innovation investment.
Industry Challenges
- Hot-End Coating Specialist Shortage:Glass container manufacturers face recruitment gaps for tin oxide coating technicians critical to achieving scratch resistance in high-speed production lines.
- Legacy Equipment Retrofit Complexity:Breweries and distilleries operating vintage bottling lines encounter integration friction when adapting to lighter-weight bottle geometries and modified crown cap specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcoholic Drinks Packaging Market |
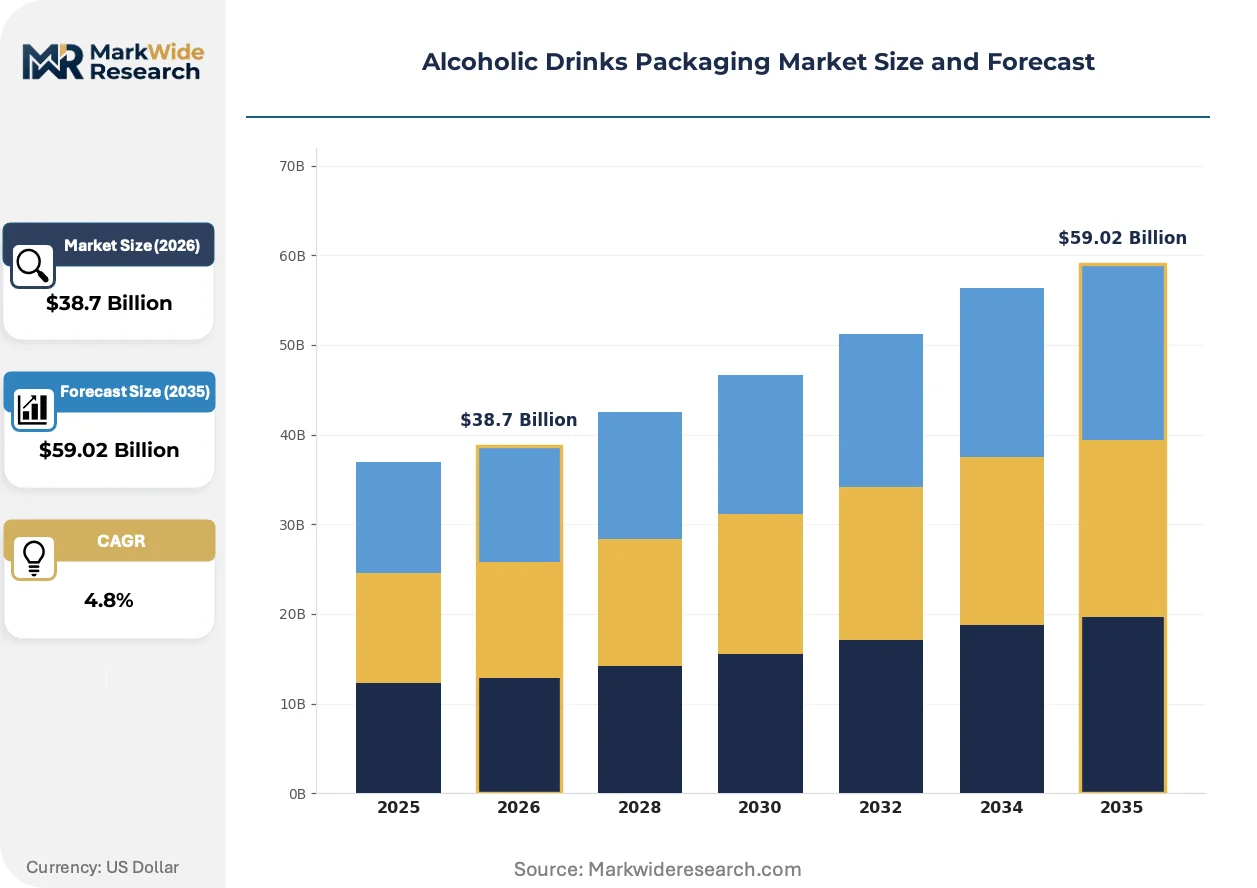
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Kegs, Pouches Material: Glass, Metal, Plastic, Cardboard Closure Type: Crown Caps, Screw Caps, Corks, Taps End User: Bars, Restaurants, Retailers, Online Stores |
| Companies Covered | Crown Holdings, Owens-Illinois, Amcor, Tetra Laval, Saint-Gobain, Ball Corporation, Ardagh Group, Krones AG, Mondi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcoholic Drinks Packaging Market Strategic Shifts
Active packaging technologies and regulatory compliance automation are reshaping competitive positioning in alcoholic drinks containment systems, with material science advances enabling simultaneous lightweighting and barrier performance gains.
Barrier-coated polyethylene terephthalate is consolidating its position in wine export logistics, with Australian and Chilean wineries adopting the format for ocean freight to European and North American markets. The technology reduces bottle weight by over 80 percent versus glass while maintaining oxygen transmission rates below spoilage thresholds. This consolidation is compressing traditional glass supply chain economics on transoceanic routes.
REACH regulation amendments targeting per- and polyfluoroalkyl substances are compelling European packaging converters to reformulate barrier coatings and adhesives used in multi-layer spirits labels and laminated cartons. The industrial consequence is accelerated R&D spending on silicone and bio-based alternatives. Wine and premium spirits segments in France and Italy are responding fastest, with cooperatives mandating PFAS-free certification from 2025.
Direct-to-consumer subscription models for craft spirits and natural wine are fragmenting traditional three-tier distribution, with brands bypassing wholesale intermediaries to control packaging unboxing experience and brand narrative. This channel shift demands smaller minimum order quantities and rapid format switching capabilities from contract packagers. California and New York metropolitan markets exhibit the highest concentration of these digitally native alcohol brands.
Alcoholic Drinks Packaging Market Segmentation
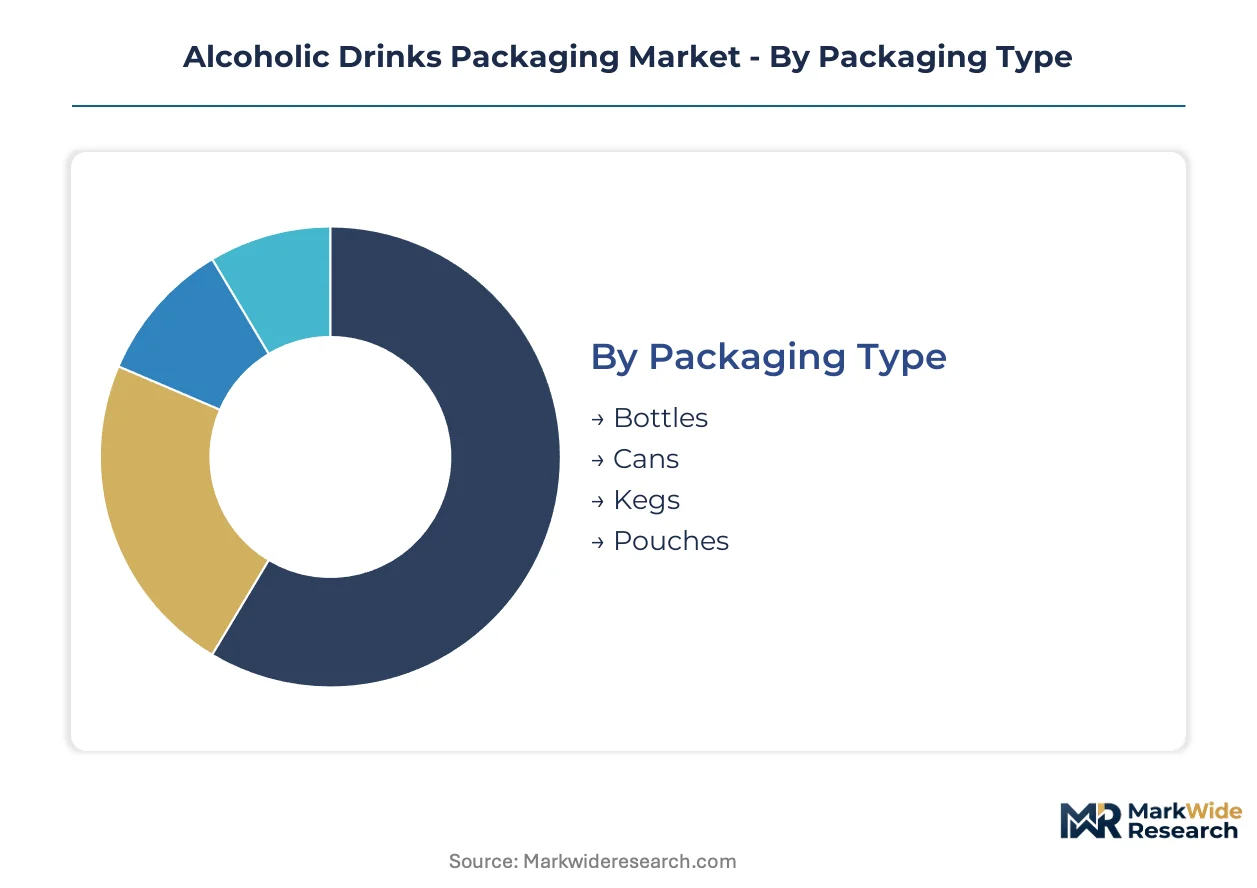
Packaging format selection in alcoholic beverages directly determines logistics economics, shelf presence, and regulatory compliance pathways. Distinct buyer priorities across on-premise versus off-premise channels create divergent specification requirements that reshape supplier R&D allocation.
Packaging Type:
Buyers differentiate primarily by distribution durability needs and consumption occasion portability.
- Bottles:Glass containers engineered with barrier coatings and impact-resistant geometries preserve organoleptic properties in spirits and wine. Demand concentrates in Germany's Rhine-Main packaging cluster where premium embossed glass production serves heritage spirits brands. Heavier bottle weights signal luxury positioning despite EU Green Deal pressure toward lightweighting.
- Cans:Aluminum two-piece containers with internal epoxy liners prevent metallic flavor migration in beer and carbonated RTD cocktails. Crown Holdings leverages existing capacity to capture share as portability requirements reshape on-premise and off-premise consumption patterns. Deposit-return system expansions accelerate closed-loop recovery economics.
- Kegs:Stainless steel returnable vessels with spear valve systems enable draught distribution to bars and restaurants. Stainless steel supply constraints and cleaning infrastructure requirements limit geographic penetration outside established brewpub networks.
- Pouches:Flexible multi-layer laminates with spout fitments target outdoor and festival consumption occasions. Migration limit compliance under EFSA framework regulation 1935/2004 elevates testing costs for European converters.
Volume sits with bottles; growth tilts toward cans.
Material:
Specification choices track energy cost exposure and recycled content mandate intensity across production clusters.
- Glass:Soda-lime silica formulations with hot-end tin oxide coatings achieve scratch resistance for high-speed filling lines. Natural gas price volatility squeezes furnace economics in European manufacturing clusters while premium spirits brands pull demand toward heavier embossed formats.
- Metal:Aluminum alloys with reduced manganese content optimize can wall thinning without buckle resistance loss. Recycling efficiency and deposit-return compatibility drive fastest share expansion in Nordic markets.
- Plastic:Barrier-coated PET bottles reduce freight costs and breakage rates for wine exporters on transoceanic routes to North American markets. Owens-Illinois and Amcor anchor competing positions in lightweight innovation versus returnable glass systems.
- Cardboard:Liquid packaging board with polyethylene barriers serves bag-in-box wine and bulk spirits formats. Extended producer responsibility schemes in France reward recyclable fiber-based containment with fee reductions.
Glass commands value share; PET climbs the fastest on export logistics cost savings.
Closure Type:
Selection criteria center on sealing reliability, line speed compatibility, and premium authentication requirements.
- Crown Caps:Lined steel shells with flanged edges dominate beer sealing due to hermetic performance at high bottling speeds. Crown Holdings maintains production scale advantages in European brewer supply chains.
- Screw Caps:Aluminum or plastic threaded closures with wad liners displace natural cork in mid-tier wine segments. Amcor's lightweight innovations target spirits exporters seeking reduced breakage and freight optimization.
- Corks:Natural or agglomerated bark stoppers with paraffin coatings retain ritual significance in premium wine and heritage spirits. Supply constraints from Portuguese cork oak harvests elevate pricing volatility.
- Taps:Polypropylene or stainless steel dispensing valves enable controlled pour from kegs and bag-in-box formats. Sanitation protocol complexity limits adoption outside commercial on-premise accounts.
Crown caps anchor beer volume; screw caps gain fastest on wine convenience preferences.
End User:
Channel economics dictate order quantity minimums, format switching flexibility, and unboxing experience investment.
- Bars:On-premise accounts prioritize keg systems and high-volume bottle formats with rapid pour efficiency. Draught infrastructure requirements concentrate procurement with regional distributors.
- Restaurants:Wine-focused establishments demand diverse bottle sizes and premium closure aesthetics to support menu pricing tiers. Sommelier influence elevates cork preference in fine dining segments.
- Retailers:Off-premise chains optimize shelf-ready secondary packaging and pallet cube efficiency. Germany's deposit-return system mandates returnable bottle and can format compliance.
- Online Stores:Direct-to-consumer subscription models fragment traditional distribution, demanding smaller minimum order quantities and rapid format switching from contract packagers. California and New York metropolitan markets exhibit highest concentration of digitally native alcohol brands.
Retailers move the volume; online stores expand most quickly on subscription model fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Main packaging cluster concentrates premium glass production capacity, drawing investment through specialized tax treatment for circular economy manufacturing zones.
Germany
Heritage spirits brands drive demand for heavier embossed glass bottles despite EU Green Deal pressure toward lightweighting. The country's extended producer responsibility framework under the Verpackungsgesetz mandates minimum recycled content thresholds. The Rhine-Main cluster anchors returnable glass system production for European brewers.
United States
Carbonated ready-to-drink cocktail brands reshape aluminum can procurement patterns across on-premise and off-premise channels. The EPA regulates volatile organic compound emissions from glass manufacturing furnaces under Clean Air Act provisions. California and New York metropolitan areas concentrate digitally native alcohol brands operating direct-to-consumer subscription models.
France
Wine cooperatives mandate PFAS-free certification from 2025, accelerating barrier coating reformulation across packaging converters. The Citeo eco-modulation scheme rewards lightweight recyclable formats with fee reductions. The Champagne-Ardenne region sustains natural cork processing for heritage spirits and premium wine closures.
India
State-level excise reforms and organized retail expansion create first-mover advantages for PET and aluminum can production localization. The Food Safety and Standards Authority of India enforces packaging material migration limits for alcoholic beverage contact. Maharashtra and Karnataka host emerging bottling infrastructure serving domestic premium spirits brands.
Australia
Wineries adopt barrier-coated PET bottles for ocean freight export to European and North American markets, reducing weight by over 80 percent versus glass. The country's national environmental regulator oversees container deposit scheme expansions across state jurisdictions. South Australia and Victoria anchor transoceanic wine export logistics corridors.
Alcoholic Drinks Packaging Market Competitive Environment
North American producers anchor one tier; European specialists hold differentiated positions in returnable glass systems and premium closure technologies. The market structure consolidates around integrated material suppliers with furnace or extrusion assets, while regional converters fill niche specification gaps. Three archetypes dominate: aluminum can specialists with beverage line integration, glass container manufacturers with hot-end coating capabilities, and flexible packaging innovators serving export logistics. Competitive moves center on capacity expansion in deposit-return-compatible formats and strategic partnerships with craft spirits brands.
Within the integrated material tier, Crown Holdings, Owens-Illinois, and Amcor occupy positions spanning aluminum, glass, and plastic containment systems respectively. Crown Holdings exemplifies the aluminum can specialist archetype with established beverage industry relationships. Owens-Illinois represents European-heritage glass manufacturing with concentration in returnable bottle systems. Amcor anchors the lightweight barrier innovation vector for wine and spirits exporters seeking freight optimization.
| Leading Market Players |
|---|
| Crown Holdings |
| Owens-Illinois |
| Amcor |
| Tetra Laval |
| Saint-Gobain |
| Ball Corporation |
| Ardagh Group |
| Krones AG |
| Mondi |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging waste directives gate qualified supply for premium-tier glass formats while compressing margins on standard container categories. Compliance-certified converters command pricing premiums as heritage spirits brands simultaneously demand heavier embossed bottles.
Pricing Analysis
Lead-time-driven pricing separates rush orders for short-turnaround embossed glass from discounted spot inventory of standard wine bottles. Three-tier pricing structure across heritage spirits, mid-tier wine, and economy beer segments tracks certification grade and customization depth. Cost compression in lightweight PET stems from freight optimization demand from Australian and Chilean exporters. Small-batch craft spirits brands exhibit highest price sensitivity; luxury heritage houses show least.
Supply Chain Analysis
Single-source vulnerability sits with Portuguese cork oak harvests for natural closure supply. Germany, Italy, and France anchor European glass furnace capacity while China and India feed aluminum can sheet demand. Raw material dependencies center on soda-lime silica, high-purity aluminum alloys, and hot-end tin oxide coating chemicals. Tariff exposure on Chinese aluminum sheet feeds margin pressure. Distribution runs through brewer-owned bottling lines, contract packagers, and spirits brand captive facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass furnace capacity constraints in Germany's Rhine-Main cluster prop pricing power for compliant suppliers. Qualified hot-end coating technicians remain the binding bottleneck.
For Market Incumbents: Acquire tin oxide coating technical capabilities through specialist recruitment or training academy partnerships. Backward integration into recycled cullet sorting infrastructure defends margin position against optical clarity specifications. Crown Holdings and Owens-Illinois exemplify the aluminum can and returnable glass archetypes respectively; emulation of their capacity discipline is warranted. For New Entrants and Emerging Players: Digitally native alcohol brands operating direct-to-consumer subscription models represent the most penetrable buyer archetype. California and New York metropolitan markets concentrate these accounts. Rapid format switching capabilities and smaller minimum order quantities provide the essential go-to-market angle against legacy contract packagers. For Investors and Strategic Acquirers: India's state-level excise reform announcements are the leading indicator that PET and aluminum can localization will accelerate. Five-to-ten year viability favors packaging converters with barrier coating R&D depth and deposit-return system format compliance. Watch for Maharashtra and Karnataka bottling infrastructure investment signals as the inflection point.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Investment | REACH PFAS amendments force silicone and bio-based formulation pivots in European converters. |
| Returnable Glass System Expansion | Germany's DRS expansion rewards closed-loop bottle economics for heritage brewer supply chains. |
| Lightweight PET Capacity Buildout | Ocean freight cost savings drive Australian winery adoption for transoceanic export corridors. |
| Smart Closure Technology Integration | NFC-enabled authentication serves premium spirits blockchain traceability demands. |
| Extended Producer Responsibility Compliance | France's Citeo eco-modulation scheme rewards recyclable format fee reductions. |
Study Parameters
Trade flow databases, ECHA regulatory filings, and beverage industry association reports formed the secondary backbone for this analysis. Primary interviews with glass furnace operations managers, spirits brand packaging directors, aluminum can procurement leads, and contract packaging executives validated demand specifications. Bottom-up volume modeling triangulated against top-down category spend estimates from customs records and production cluster surveys.
Historical trendline analysis of format substitution patterns and energy cost pass-through mechanisms anchored the projection framework. Segmentation dimensions modeled include packaging type, material substrate, closure technology, end-user channel, and regional regulatory cluster. CAGRs derived from curve-fitting observed substitution elasticities and capacity expansion announcements across the analysis window. Furnace fuel cost volatility and deposit-return system adoption curves served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal implementation pacing and natural gas price trajectories. Assumptions underlying projections reflect current regulatory enforcement intensity and observed brand format commitments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Alcohol Packaging Market