
 Cluster Packaging for Beer Market | 2026-2036
Cluster Packaging for Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Cluster Packaging for Beer Market Outlook
Recycled corrugated fiberboard is hardening as the default substrate for six-pack and twelve-pack carriers across premium beer portfolios. Graphic Packaging International leverages integrated paperboard mills to control furnish costs across North American operations. WestRock Company sustains scale advantages through automated die-cutting lines serving mass-market brewers. Smurfit Kappa Group anchors European supply through molded pulp innovation for variety pack configurations.
Cluster packaging for beer denotes multi-unit secondary containment systems—typically carriers, wraps, or baskets—engineered to group bottles or cans for transport, retail display, and consumer handling, with burst strengths commonly specified at 200-400 lb per square inch for corrugated variants. Cardboard dominates volume in retail channels where shelf-ready aesthetics and printability drive selection, while plastic ring carriers retain share in wholesale and direct-to-consumer routes where moisture resistance and stackability outweigh fiber-based alternatives. Metal overcaps and glass partition inserts occupy niche positions in premium gift packs and import portfolios where breakage protection commands priority.
EPA guidelines on recycled content thresholds shape material qualification for US brewers, while EU REACH compliance governs adhesive and ink chemistries across exported packaging lots. Germany's national packaging regulator enforces strict dual-system participation fees that elevate total cost of ownership for plastic formats versus fiber-based substitutes. Stakeholders must monitor evolving extended producer responsibility frameworks as these fee structures recalibrate format economics across core European markets.
Market Dynamics
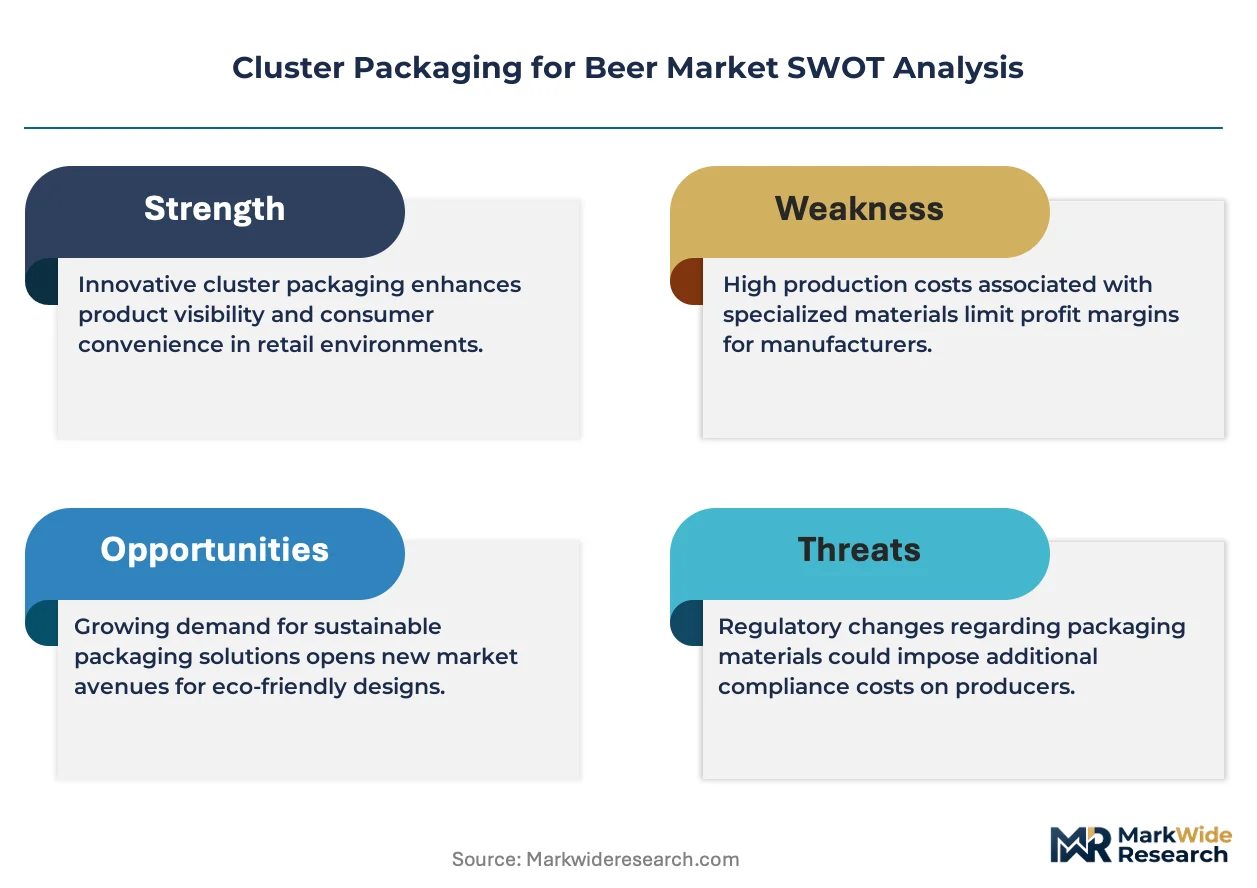
EU Single-Use Plastics Directive enforcement is compressing plastic ring carrier volumes while accelerating fiber-based format conversion across European brewing operations.
Growth Catalysts
- REACH compliance mandates:Chemical disclosure requirements under EU REACH are disqualifying conventional adhesive systems, forcing brewers toward water-based alternatives that favor fiberboard substrates with compatible bonding chemistries.
- Craft brewery expansion:Small-batch producers in Colorado, Oregon, and Michigan are scaling multi-pack SKUs to secure retail shelf presence, generating disproportionate demand for short-run printed carriers.
- Molded pulp innovation:Thermoformed fiber technology is enabling complex variety pack geometries previously requiring plastic, opening substitution pathways in Bavaria's packaging conversion facilities.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with Chinese import quota fluctuations, compressing converter margins on fixed-price annual contracts with mass-market brewers.
- German dual-system fees:Verpackungsgesetz participation costs for plastic formats remain structurally higher than fiber alternatives, yet administrative complexity delays some brewers' format transitions.
- Moisture performance ceiling:Fiber-based carriers face functional limits in cold-chain distribution exceeding 72 hours, preserving plastic ring share in export and direct-to-consumer channels.
Strategic Opportunities
- Extended producer responsibility expansion:France's Citeo modulation criteria are rewarding high-recycled-content packaging with fee reductions, creating margin capture for early-compliant suppliers.
- Subscription channel penetration:Monthly beer clubs require ship-ready multi-unit containment that balances protection with unboxing experience, favoring rigid molded pulp over loose-fill alternatives.
- Digital print convergence:Single-pass inkjet systems are collapsing minimum order quantities for versioned seasonal graphics, enabling microbrewery access to premium shelf-ready aesthetics.
Industry Challenges
- Structural adhesive reformulation:Water-based bonding agents meeting FDA indirect food contact standards require curing line modifications that strain capital budgets at mid-tier converters.
- Die-cutting precision gaps:High-speed automated lines demand tolerance control below 0.5mm for beverage can fit, yet skilled maintenance technician availability constrains line expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cluster Packaging for Beer Market |
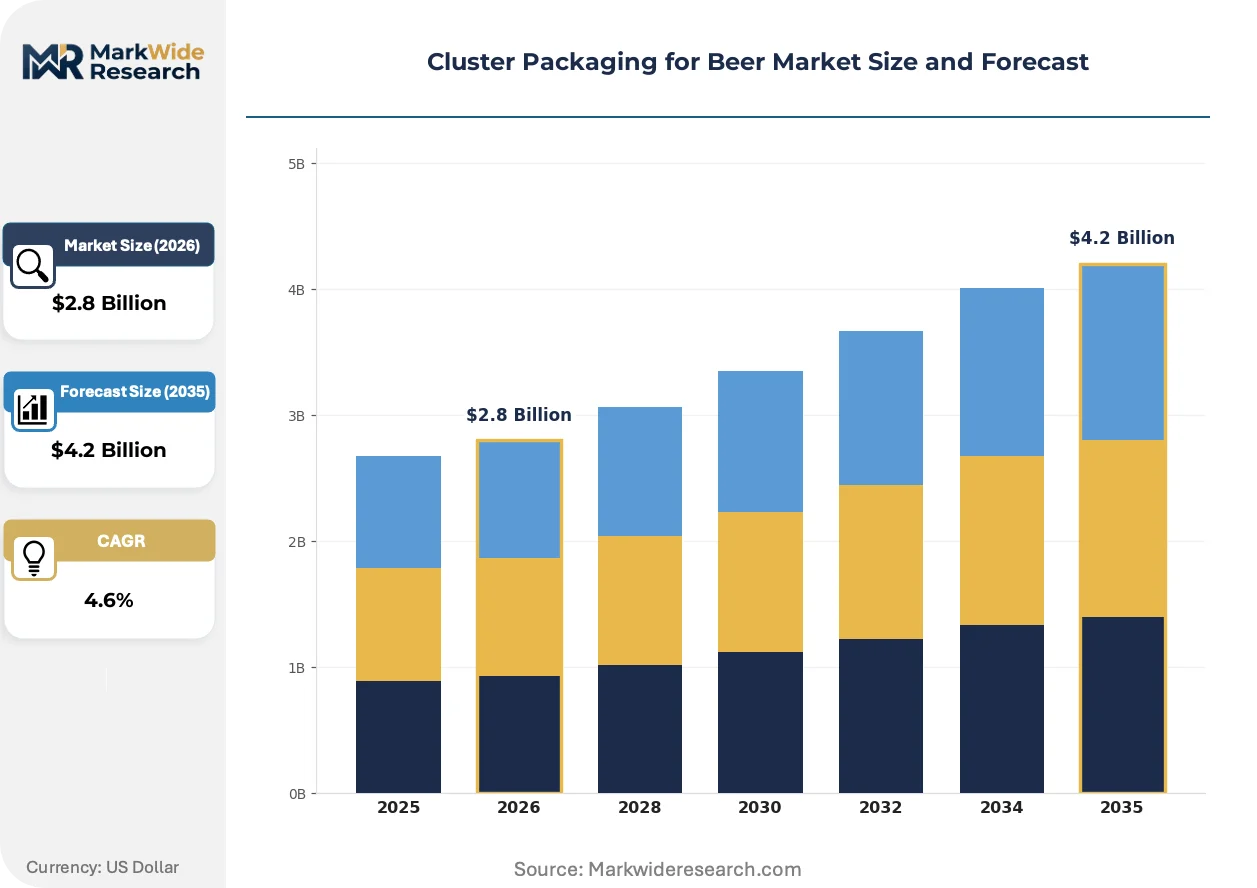
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Six-Pack, Four-Pack, Twelve-Pack, Variety Pack Material: Cardboard, Plastic, Metal, Glass Distribution Channel: Retail, Wholesale, Direct-to-Consumer, Online End User: Bars, Restaurants, Retailers, Importers |
| Companies Covered | Graphic Packaging International, WestRock Company, Smurfit Kappa Group, International Paper, Owens-Illinois, Ardagh Group, DS Smith, Ball Corporation, PakTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cluster Packaging for Beer Market Strategic Shifts
Material science advances and regulatory chemistry constraints are jointly redefining substrate selection criteria across premium and mass-market beer portfolios simultaneously.
Molded pulp carriers with integrated handle structures are overtaking folded corrugated designs in variety pack configurations where structural integrity and print surface area must coexist. Premium import brewers in Belgium and the Netherlands are specifying these formats for 12-can configurations, collapsing the traditional trade-off between protection and shelf communication space.
EU F-Gas Regulation phase-down schedules are indirectly pressuring cold-chain packaging decisions by elevating refrigeration cost sensitivity, pushing brewers toward ambient-stable distribution formats that tolerate fiber-based secondary containment. German and Czech producers are responding with modified atmospheric packaging in primary containers that relax moisture barriers on outer carriers.
Direct-to-consumer fulfillment is fragmenting order profiles toward mixed-SKU shipments that challenge standard six-pack modularity. Subscription operators in California and New York are specifying custom partition inserts and variable-count wraps that depart from retail-standard configurations, forcing packaging suppliers toward modular die systems and digital workflow integration.
Cluster Packaging for Beer Market Segmentation
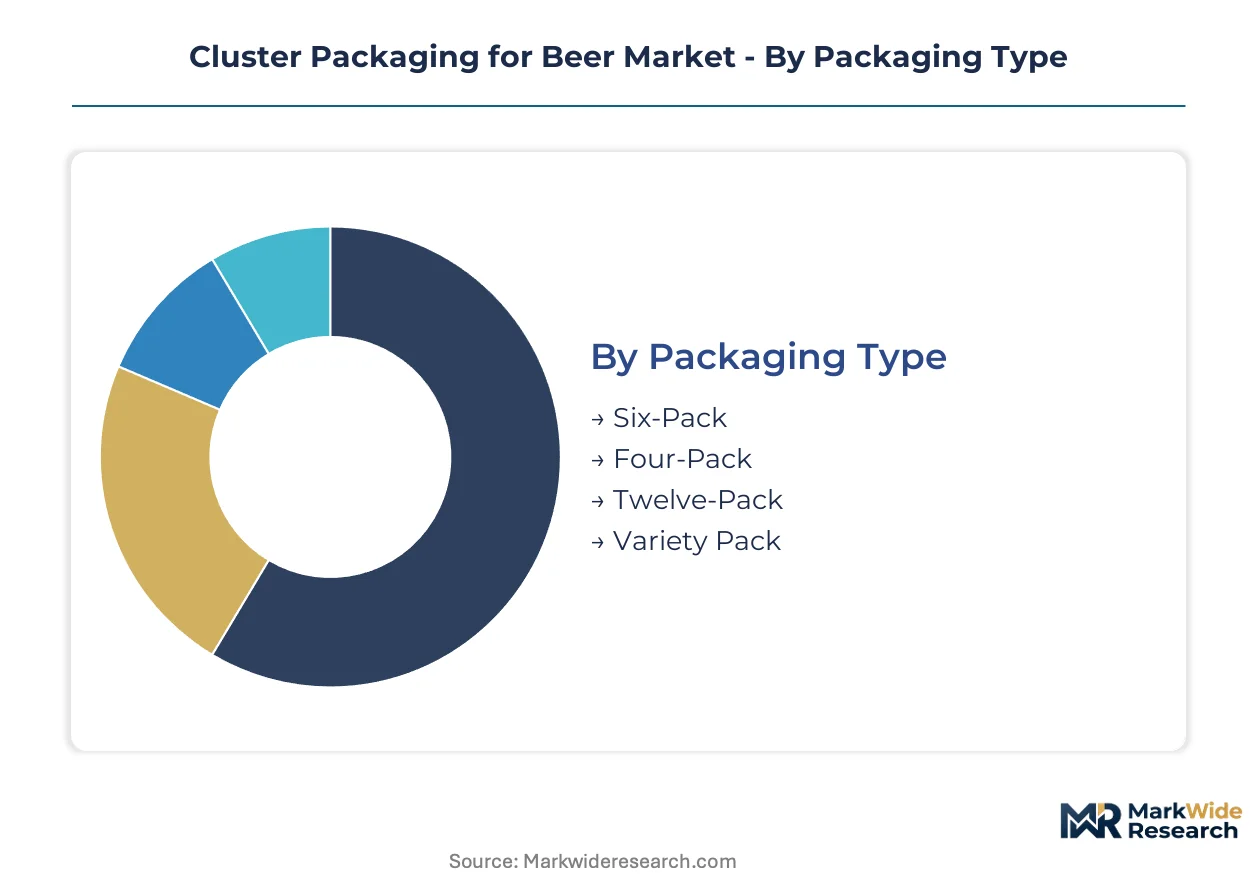
Cluster packaging configurations for beer reflect divergent requirements across retail shelf presence, cold-chain durability, and direct-to-consumer protection. Format selection determines substrate compatibility, print specifications, and regulatory compliance pathways simultaneously.
Packaging Type:
Standardization dominates high-volume brewery operations while craft producers demand flexible short-run configurations across this spectrum.
- Six-Pack:Corrugated fiberboard carriers with 200-400 lb burst strength specifications serve as the retail default for mainstream lager portfolios. German mass-market brewers in Bavaria are consolidating procurement around this format to satisfy Verpackungsgesetz dual-system fee advantages.
- Four-Pack:Compact configurations tailored to premium craft SKUs with higher unit margins. Colorado and Oregon microbreweries are scaling four-pack runs to secure refrigerated case placement without the volume commitments of larger formats.
- Twelve-Pack:Wraparound corrugated designs with reinforced corner posts for club-store palletization. The format retains plastic overwrap share in wholesale channels where moisture exposure exceeds 72 hours.
- Variety Pack:Molded pulp partitions enabling mixed-SKU containment with integrated handle structures. Belgian and Dutch importers specify these for seasonal gift configurations where structural complexity previously required plastic.
Leading the category by volume: Six-Pack. Growing fastest: Variety Pack.
Material:
Regulatory chemistry constraints and cold-chain performance requirements split procurement decisions across substrate categories.
- Cardboard:Recycled corrugated fiberboard with water-based adhesive bonding dominates retail channel specifications. EU REACH compliance mandates are accelerating format conversion as conventional adhesive systems face disqualification.
- Plastic:Ring carriers and shrink-wrap configurations retain wholesale and export channel share. Moisture resistance beyond 72-hour cold-chain thresholds preserves functional necessity despite EU Single-Use Plastics Directive compression.
- Metal:Overcap assemblies for premium gift packs requiring breakage protection. Niche deployment concentrates in Belgian import portfolios where primary glass protection commands priority.
- Glass:Partition inserts for high-value gift configurations. Czech producers utilize these for limited-release portfolios where presentation aesthetics outweigh cost considerations.
Dominant by procurement volume: Cardboard. Steepest expansion trajectory: Molded pulp fiberboard within Cardboard subcategory.
Distribution Channel:
Channel-specific protection requirements and handling intensity determine format durability specifications across the value chain.
- Retail:Shelf-ready printed carriers with high-graphic surface area for point-of-sale differentiation. EPA recycled content thresholds govern material qualification for US supermarket listings.
- Wholesale:Bulk pallet configurations prioritizing stackability and moisture tolerance over print aesthetics. Plastic ring carriers retain structural share in this channel.
- Direct-to-Consumer:Ship-ready containment balancing protection with unboxing experience. California and New York subscription operators specify custom partition inserts for mixed-SKU shipments.
- Online:E-commerce optimized formats with damage-resistant corner reinforcements. Last-mile handling intensity demands structural specifications exceeding retail-channel standards.
Highest volume throughput: Retail. Most rapid format innovation: Direct-to-Consumer.
End User:
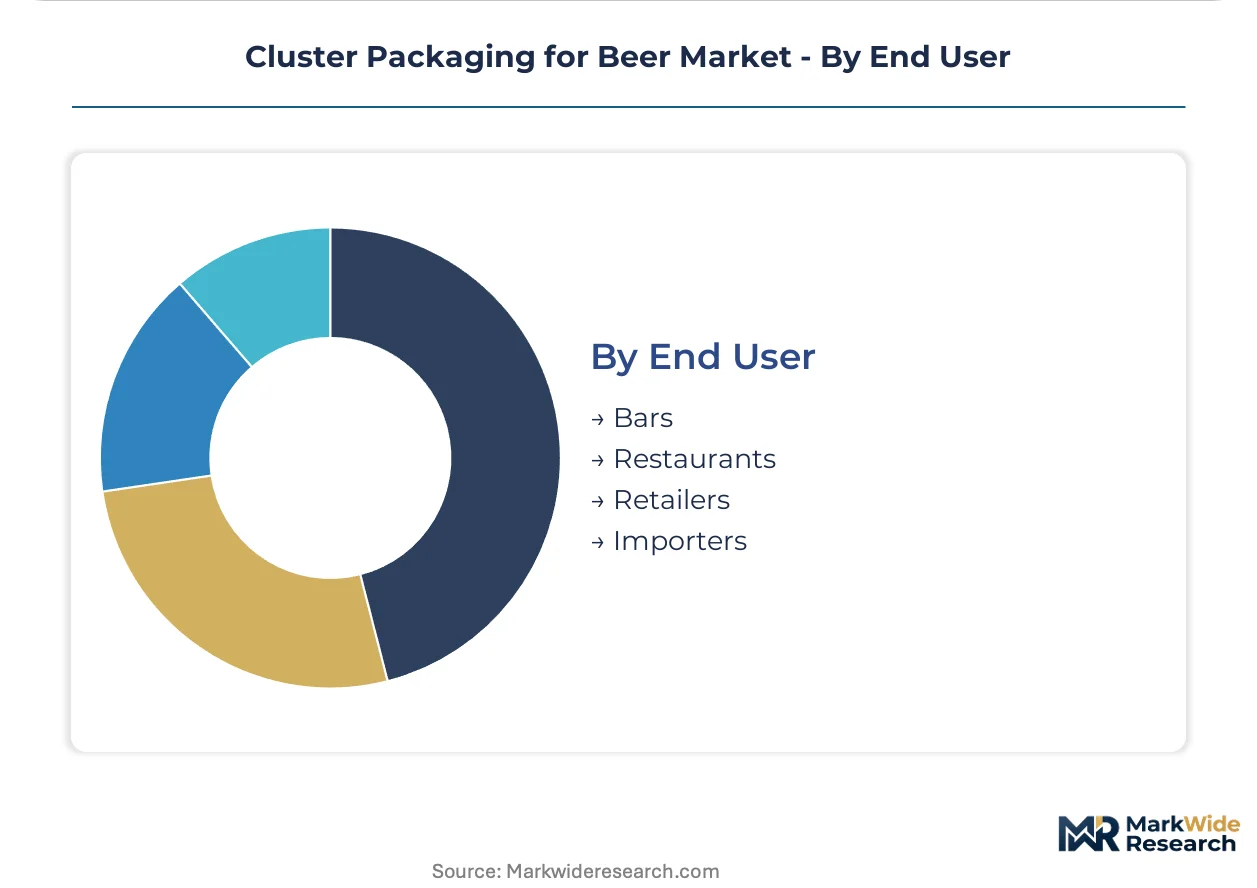
Purchasing scale and consumption occasion segmentation drive divergent packaging performance requirements.
- Bars:High-throughput draft-focused operations with minimal packaged beer requirements. Where bottled formats apply, durability specifications prioritize back-of-house handling efficiency.
- Restaurants:Table-service configurations with presentation-sensitive unboxing for premium pairings. Molded pulp carriers with integrated handles satisfy front-of-house aesthetic requirements.
- Retailers:Shelf-ready specifications with scan-cooperative barcoding and pallet-efficient case dimensions. German grocery chains enforce strict dual-system participation documentation.
- Importers:Extended cold-chain formats with moisture barriers for transoceanic distribution. Containerized shipping stress demands burst strength specifications elevated above domestic retail standards.
Primary procurement volume: Retailers. Fastest-growing demand profile: Importers responding to craft beer export expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's brewing cluster concentration in Germany anchors European fiber-based packaging conversion, while craft brewery expansion zones across the United States and regulatory pressure corridors in Belgium and the Netherlands reshape procurement geography.
Germany
Bavarian mass-market brewers are consolidating six-pack procurement around corrugated fiberboard to capture Verpackungsgesetz dual-system fee advantages. The national packaging regulator enforces strict participation documentation that elevates total cost of ownership for plastic formats. Munich and Nuremberg packaging conversion facilities are scaling molded pulp thermoforming lines for variety pack configurations.
United States
Colorado and Oregon microbreweries are scaling four-pack SKUs to secure refrigerated case placement without volume commitments of larger formats. EPA recycled content thresholds govern material qualification for supermarket listings. The Pacific Northwest craft brewery corridor is generating disproportionate demand for short-run printed carriers with seasonal versioning.
Belgium
Premium import brewers are specifying molded pulp carriers with integrated handle structures for twelve-can gift configurations. EU REACH chemical disclosure requirements are disqualifying conventional adhesive systems, forcing conversion toward water-based alternatives. Antwerp packaging suppliers are collapsing traditional trade-offs between protection and shelf communication space.
Netherlands
Rotterdam's logistics hub position is elevating demand for cold-chain-durable formats in transoceanic export corridors. The EU Single-Use Plastics Directive enforcement is compressing plastic ring carrier volumes while accelerating fiber-based conversion. Dutch converters are deploying modified atmospheric packaging in primary containers to relax moisture barriers on outer carriers.
Czech Republic
Limited-release portfolios from Bohemian brewing clusters are utilizing glass partition inserts where presentation aesthetics outweigh cost considerations. National adherence to EU packaging waste frameworks shapes format selection across export-bound production. Prague-area suppliers are specializing in premium gift pack configurations requiring breakage protection specifications.
Cluster Packaging for Beer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated paperboard producers commanding retail-channel procurement while niche fabricators capture craft brewery short-run demand. The vendor base concentrates around three strategic archetypes: integrated forest-products conglomerates with captive pulp supply, specialized beverage packaging converters with die-cutting automation, and molded pulp innovators serving variety pack complexity. Capacity expansion and adhesive chemistry reformulation represent the dominant competitive moves as REACH compliance deadlines approach.
Within the integrated conglomerate tier, Graphic Packaging International and WestRock Company exemplify scale-driven positioning through North American mill networks and automated production lines. Smurfit Kappa Group anchors European supply representation with molded pulp technology leadership for complex geometries. These three entities collectively illustrate how substrate control and geographic production density determine competitive position across diverging regulatory environments.
| Leading Market Players |
|---|
| Graphic Packaging International |
| WestRock Company |
| Smurfit Kappa Group |
| International Paper |
| Owens-Illinois |
| Ardagh Group |
| DS Smith |
| Ball Corporation |
| PakTech |
| Others |
Value Chain & Pricing Dynamics
Mass-market brewers in Bavaria concentrate procurement around corrugated fiberboard six-packs, locking in contract-based pricing that rewards volume scale and penalizes short-notice format switches. Their purchasing power compresses converter margins while elevating fiber-based substrates over plastic alternatives under Germany's dual-system fee structure.
Pricing Analysis
Short lead-time premiums apply to seasonal craft brewery orders requiring versioned graphics within compressed windows, while spot inventory discounts emerge for standardized formats with flexible delivery timing. Three-tier pricing structure across premium molded pulp, standard corrugated, and economy plastic ring configurations separates buyers by durability requirements and shelf-aesthetic priorities. Pricing pressure stems from OCC feedstock volatility tied to Chinese import quota fluctuations. Craft microbreweries exhibit highest price sensitivity due to constrained capital budgets, whereas premium import portfolios show least sensitivity given breakage-protection priorities.
Supply Chain Analysis
Elevated freight costs from German and Czech packaging conversion facilities to Benelux distribution hubs are reshaping regional procurement geography for Belgian importers. Supply concentrates in Germany, the United States, and Belgium as anchor production locations. Raw material flows draw from Swedish pulp mills, recycled OCC streams, and water-based adhesive formulations. Single-source vulnerability concentrates around thermoformed fiber tooling suppliers serving variety pack complexity. Distribution runs through brewery-direct contracts, converter-owned logistics, and third-party cold-chain operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cluster packaging sector sits at a substrate-transition inflection, with molded pulp thermoforming displacing folded corrugated and plastic ring carriers across premium and gift configurations.
For Market Incumbents: Deploy adhesive chemistry reformulation as the priority lever to satisfy EU REACH compliance deadlines before conventional bonding systems face disqualification. Backward integration into captive pulp supply secures furnish cost control against OCC volatility. Capacity addition in Bavaria and the Pacific Northwest captures craft brewery consolidation and mass-market format conversion simultaneously. For New Entrants and Emerging Players: Subscription beer clubs represent the most penetrable buyer archetype, requiring ship-ready formats that balance protection with unboxing experience. Molded pulp partition inserts for mixed-SKU monthly shipments offer white-space entry with minimal incumbent tooling investment. Digital print workflow partnerships enable seasonal versioning without minimum order quantity barriers. For Investors and Strategic Acquirers: The window for entry favors converters with thermoformed fiber capabilities and integrated handle-structure patents. Long-term viability hinges on regulatory chemistry adaptation rather than commodity scale. Watch EU Single-Use Plastics Directive enforcement acceleration as the signal for format substitution velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Chemistry Reformulation | EU REACH compliance mandates water-based bonding systems, disqualifying conventional alternatives. |
| Thermoformed Fiber Capacity Expansion | Molded pulp tooling investments capture variety pack demand from Belgian and Dutch importers. |
| Digital Print Workflow Integration | Single-pass inkjet systems collapse minimum order quantities for craft brewery seasonal versioning. |
| Backward Integration into Pulp Supply | Captive furnish control insulates converter margins from Chinese OCC import quota volatility. |
| Cold-Chain Distribution Partnership | Collaboration with third-party logistics operators extends fiber-based format viability beyond 72-hour moisture thresholds. |
Study Parameters
Independent corroboration across packaging converter executives, brewery procurement directors, and logistics operators underwrites the qualitative findings in this study. Primary fieldwork engaged plant managers at German and US conversion facilities, category buyers at Bavarian mass-market brewers, and cold-chain specialists serving transoceanic export corridors. Secondary validation drew from EU REACH regulatory filings, EPA recycled content documentation, Verpackungsgesetz participation records, and trade data on OCC feedstock flows. Bottom-up SKU-level volume estimates triangulate against top-down brewery production statistics.
Comparable-period anchoring to historical format conversion timelines shaped the projection horizon across the analysis window. Segmentation dimensions modeled include packaging type, material substrate, distribution channel, and end-user vertical. CAGRs derive from trend extrapolation of regulatory deadline impacts and craft brewery expansion patterns. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules affecting cold-chain cost sensitivity and modified atmospheric packaging adoption rates.
Revisions become necessary when EU Single-Use Plastics Directive enforcement accelerates beyond current trajectories or when OCC price volatility exceeds historical bands. Forecasts reflect assumptions about adhesive curing line modification timelines and thermoformed fiber tooling availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market