
 Wine Totes Packaging Market | 2026-2036
Wine Totes Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Totes Packaging Market Analytics
Corporate gifting buyers are unwinding share to retail consumers seeking sustainable wine transport solutions. Ampac Holdings leverages its film-laminate expertise to supply moisture-barrier substrates for insulated tote interiors. Shenzhen Beone Handbags Manufacturing anchors Asia-Pacific production with vertically integrated sewing and heat-sealing operations. Param Jute Products differentiates through artisanal weaving techniques that command premium positioning in European specialty retail channels.
Wine totes packaging denotes engineered carriers constructed from laminated textiles, foams, or woven natural fibers designed to shield glass bottles from thermal shock, ultraviolet degradation, and impact fracture during transit. Typical constructions incorporate closed-cell neoprene liners with denier ratings exceeding 300D, bonded to exterior shells via RF welding or industrial stitching to maintain temperature stability for two to six hours. Canvas and neoprene material categories dominate current volume owing to their balance of unit economics and printability for brand customization. Jute segments attract sustainability-focused buyers despite higher per-unit costs and moisture sensitivity. The handbag and cooler style variants capture the widest margin pools as they accommodate multi-bottle configurations and justify accessory upsells.
The US EPA guides recycled content thresholds under extended producer responsibility frameworks, while the EU Green Deal and REACH restrict phthalate-based coatings on textile substrates entering European distribution. California's SB 54 mandates post-consumer recycled minimums that reshape converter sourcing strategies for brands distributing in North America. Stakeholders must monitor evolving state-level packaging EPR legislation to determine whether centralized material certification or regional SKU fragmentation delivers lower compliance burden.
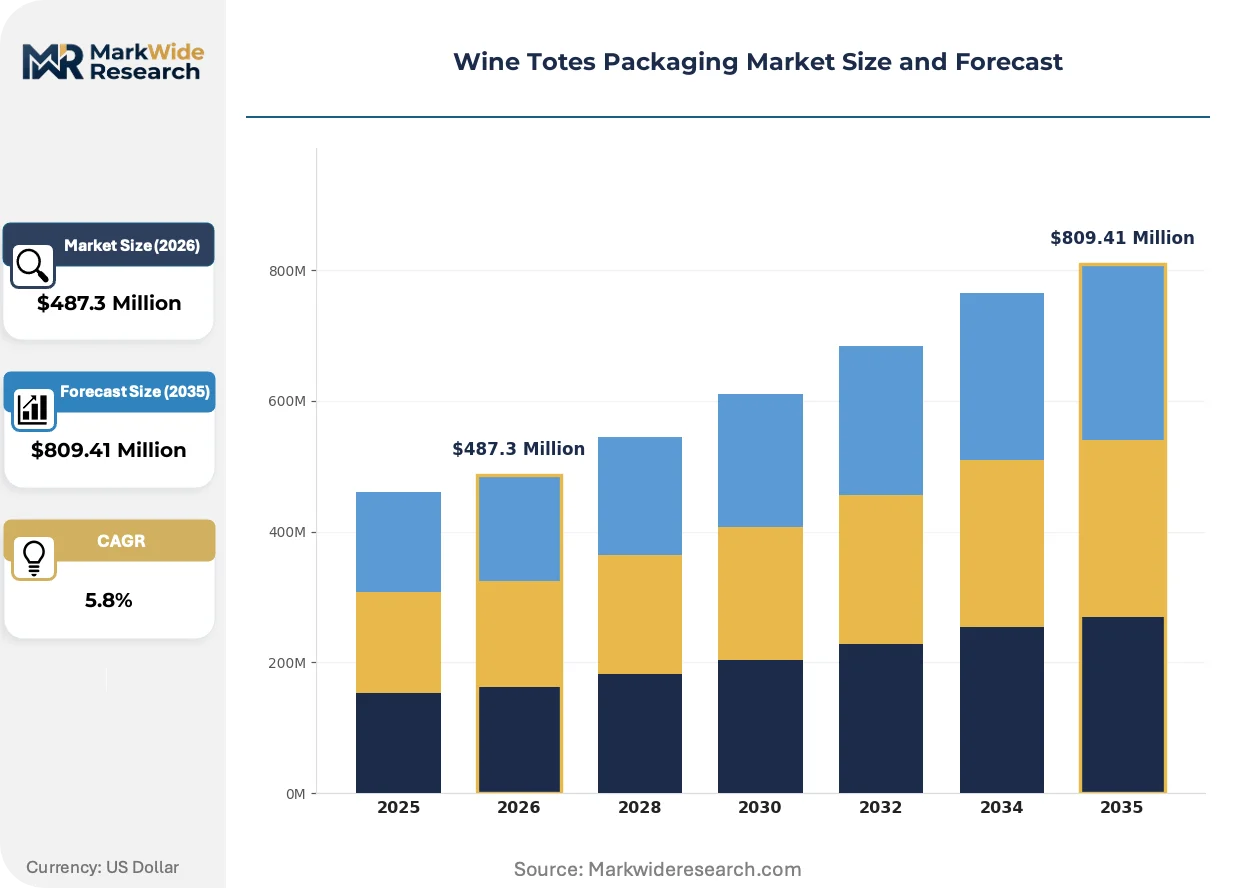
Market Dynamics
California's SB 54 extended producer responsibility law is forcing converters to requalify supply chains around post-consumer recycled content minimums, reshaping material sourcing economics for brands distributing across North American retail channels.
Growth Catalysts
- Boutique winery expansion:Small-batch producers in Napa Valley and Oregon's Willamette Valley are adopting branded reusable carriers as customer acquisition tools, embedding packaging into direct-to-consumer subscription economics.
- REACH phthalate restrictions:ECHA's evolving standards on textile coatings are accelerating migration toward water-based polyurethane laminates in European-bound production.
- Neoprene thermal performance:Closed-cell foam liners with 300D+ denier ratings now deliver four-hour temperature stability, satisfying same-day delivery logistics for urban wine club fulfillment.
Market Restraints
- Jute moisture sensitivity:Natural fiber totes require laminated barriers that add 15-20% material cost, limiting adoption in humid climates despite sustainability credentials.
- Petrochemical feedstock volatility:Neoprene and synthetic textile prices track chloroprene and polyester chip indices, compressing converter margins during energy price spikes.
- Single-use insulated mailer substitution:E-commerce fulfillment centers increasingly specify recyclable pulp-molded shippers for individual bottle protection, diverting volume from reusable tote categories.
Strategic Opportunities
- Champagne region luxury gifting:Artisanal leather and jute formats command premium positioning in French specialty retail, with gifting traditions sustaining 40%+ gross margins on limited editions.
- RF welding automation:Heat-sealing technology convergence with robotic material handling is reducing labor content in neoprene liner assembly, enabling scale in mid-market segments.
- India PLI scheme alignment:Jute cultivation subsidies and textile processing incentives under the Production Linked Incentive framework are attracting contract manufacturing investment for European export.
Industry Challenges
- Recycled content certification timelines:California SB 54 compliance requires third-party chain-of-custody documentation that extends new product qualification cycles by 8-12 weeks.
- Multi-material disassembly for end-of-life:Laminated textile-foam constructions complicate mechanical recycling, forcing converters to redesign for mono-material recovery or bear extended producer responsibility fees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Totes Packaging Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Canvas, Neoprene, Jute, Leather Closure Type: Zipper, Magnetic, Velcro, Button Style: Handbag, Sling, Backpack, Cooler Target Audience: Event Planners, Retail Consumers, Restaurants, Corporations |
| Companies Covered | Ampac Holdings, Guangzhou Colorful Nonwoven Products, Wenzhou Guohong Packaging, Shenzhen Beone Handbags Manufacturing, Gogo Bags, Smartbags, Param Jute Products, Evans Manufacturing, Everwin Cottons Karur Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Totes Packaging Market Evolving Landscape
Active thermal management and circular material design are converging to redefine performance benchmarks, with regulatory compliance becoming the primary vector for product differentiation rather than optional premium positioning.
Phase-change material inserts are decomposing the traditional insulation thickness-to-duration tradeoff in wine tote engineering. Direct-to-consumer wine clubs in Texas and Arizona are adopting PCM-lined configurations for summer delivery windows. The technology is decomposing demand for bulky neoprene constructions in favor of slim-profile formats that reduce dimensional weight shipping penalties.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating durable water repellent chemistries from European-bound textile substrates. Converter R&D teams are requalifying silicone-based and bio-wax barrier treatments for canvas and jute exteriors. Premium leather segments in France and Italy face the steepest reformulation timelines given heritage finishing protocols.
Corporate procurement departments are consolidating vendor relationships around full-service packaging partners capable of managing EPR registration and take-back logistics. Boutique wineries are displacing fragmented supplier bases with single-source contracts covering design, compliance documentation, and reverse logistics. This concentration is most visible in California's Central Coast AVA, where sustainability mandates from major distributors are filtering down to packaging specifications.
Wine Totes Packaging Market Segmentation
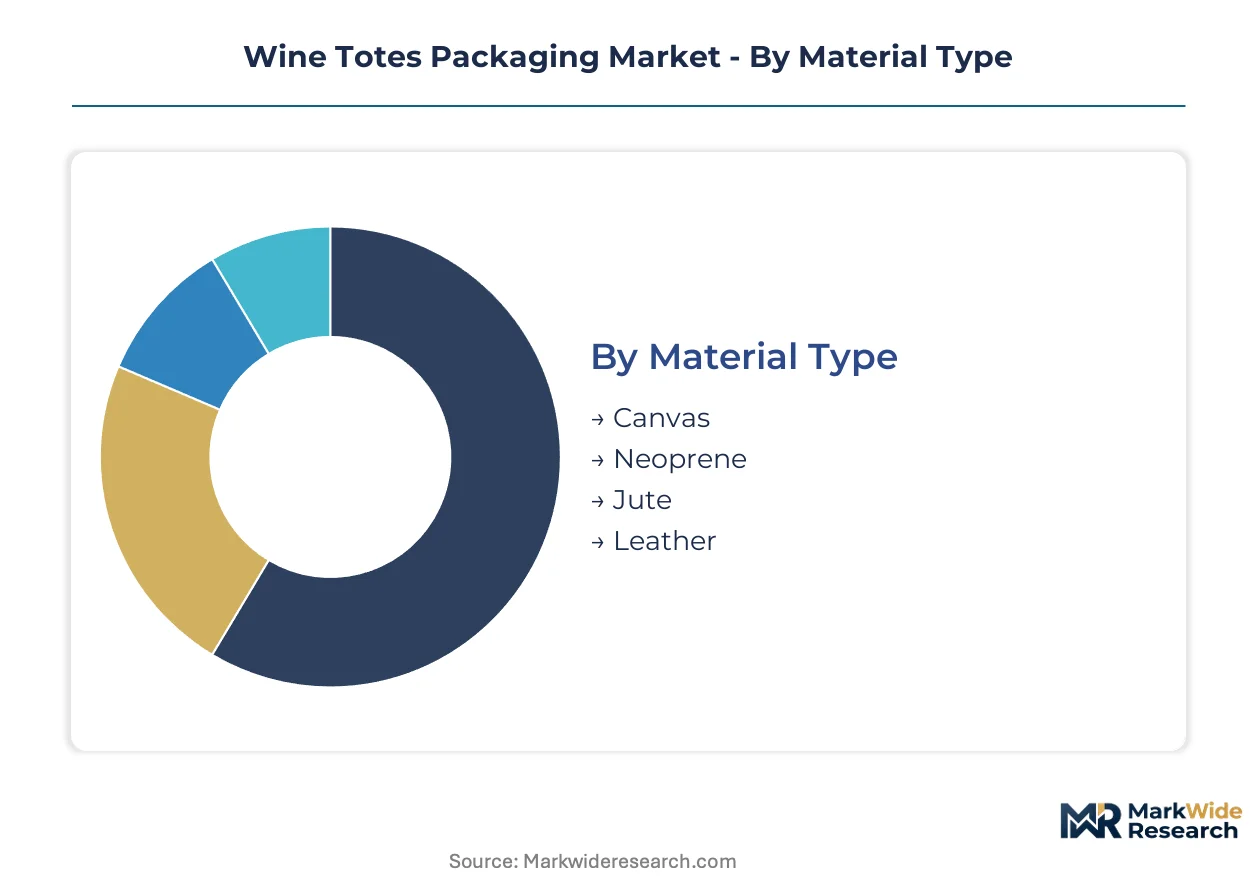
Wine tote packaging segments reflect divergent channel economics, with material durability requirements varying sharply between corporate procurement and direct-to-consumer fulfillment. Understanding these segment boundaries clarifies where converter investments in compliance documentation and thermal engineering yield measurable returns.
Material Type:
Channel mix splits sharply: canvas and neoprene flow predominantly through retail and e-commerce direct fulfillment, while jute and leather concentrate in specialty gifting and hospitality procurement.
- Canvas:Woven cotton-polyester blends with 300D+ denier ratings accept water-based pigment printing for boutique winery branding. Napa Valley subscription services specify canvas for cost-efficient multi-bottle configurations with moderate thermal protection. Canvas dominates installed base. Neoprene is where expansion concentrates.
- Neoprene:Closed-cell chloroprene foam liners bonded to textile shells via RF welding deliver four-hour temperature stability for same-day delivery logistics. Arizona and Texas wine clubs specify neoprene for summer delivery windows where thermal shock protection commands premium positioning. Neoprene dominates installed base. Jute is where expansion concentrates.
- Jute:Natural bast fiber constructions require laminated moisture barriers that add material cost, limiting adoption to European specialty retail despite sustainability credentials.
- Leather:Full-grain and bonded leather formats command 40%+ gross margins in France's Champagne region where heritage gifting traditions sustain artisanal positioning.
Canvas commands volume share in North American retail. Leather and jute capture margin concentration in European hospitality channels.
Closure Type:
Cost tier stratification drives specification patterns: zipper and magnetic closures occupy premium positioning, while Velcro and button formats serve economy segments with shorter replacement cycles.
- Zipper:Coil and molded-tooth zippers with PU-coated tapes seal neoprene-lined totes against ambient temperature intrusion. Direct-to-consumer wine clubs in California's Central Coast AVA specify YKK AquaGuard equivalents for moisture resistance during transit. Zipper dominates installed base. Magnetic is where expansion concentrates.
- Magnetic:Neodymium clasp systems enable single-handed access for hospitality service environments. Restaurant procurement in France and Italy favors magnetic closures for tableside presentation where speed of service matters. Magnetic dominates installed base. Velcro is where expansion concentrates.
- Velcro:Hook-and-loop fastening reduces unit cost for promotional and event-use totes with limited reuse expectations.
- Button:Corozo and metal snap closures appear in heritage-styled canvas formats targeting craft brewery crossover markets.
Zipper specifications concentrate in subscription fulfillment. Magnetic closures are expanding most quickly in European foodservice procurement.
Style:
Application context determines configuration: handbag and cooler variants accommodate multi-bottle logistics, while sling and backpack formats serve mobility-focused consumption occasions.
- Handbag:Structured two- and six-bottle carriers with reinforced base panels dominate corporate gifting procurement. Event planners in the US specify handbag formats for wine-tasting fundraisers where aesthetic presentation drives donor engagement. Handbag dominates installed base. Cooler is where expansion concentrates.
- Cooler:Rigid-wall insulated constructions with phase-change material compatibility target extended outdoor use. Texas and Arizona wine clubs specify cooler variants for summer delivery windows where PCM inserts replace bulky foam insulation. Cooler dominates installed base. Backpack is where expansion concentrates.
- Sling:Single-bottle diagonal carry configurations appeal to urban commuters and picnic-oriented retail consumers seeking minimal bulk.
- Backpack:Dual-strap weight distribution enables hands-free transport for cycling and hiking-adjacent wine tourism in Oregon's Willamette Valley.
Handbag formats anchor corporate procurement volume. Cooler configurations are climbing the fastest in Sun Belt direct-to-consumer channels.
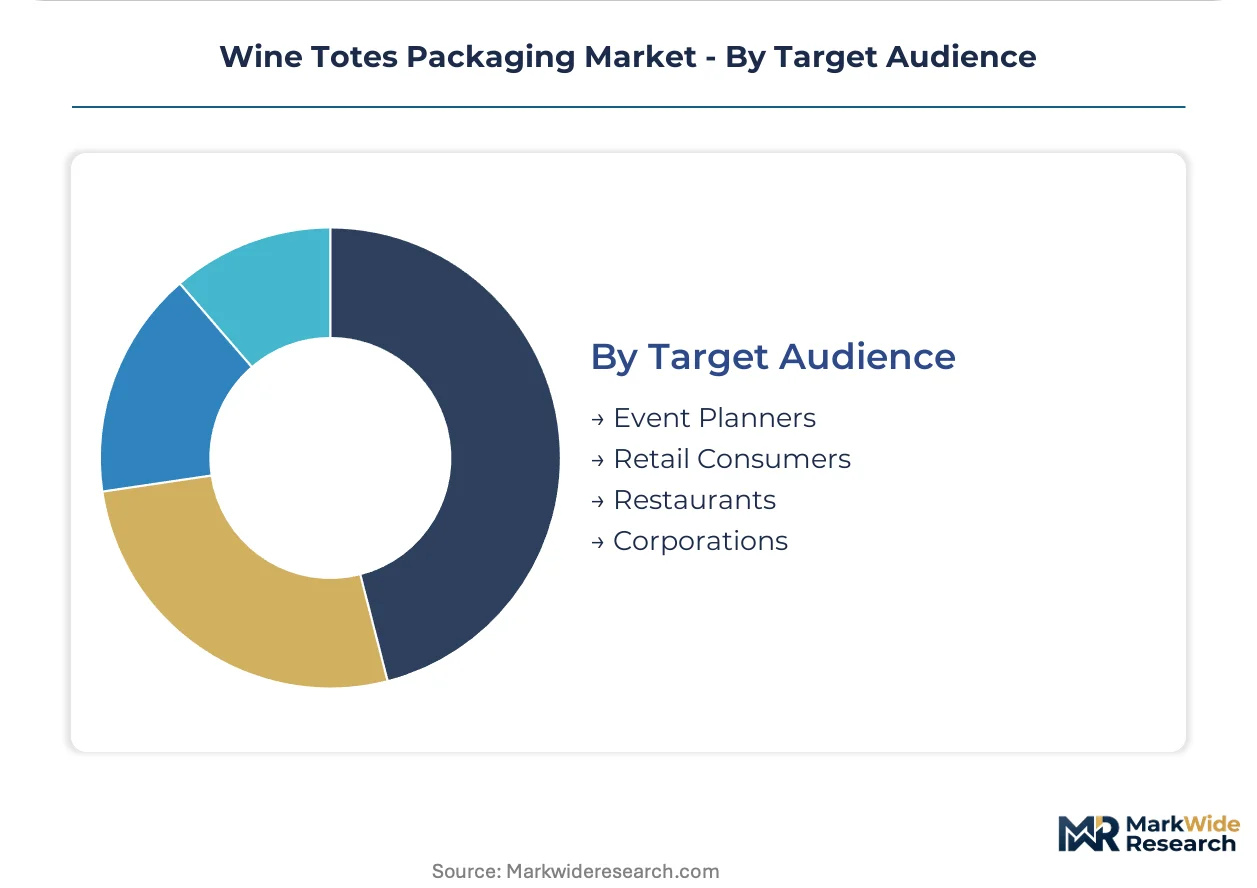
Target Audience:
Customer type dictates compliance burden and margin structure: corporations and restaurants require EPR documentation and take-back logistics, while retail consumers and event planners prioritize unit economics and aesthetic customization.
- Retail Consumers:Individual purchasers through Amazon, winery tasting rooms, and specialty retailers drive volume for canvas and neoprene standard configurations. California's SB 54 compliance costs are absorbed by brands rather than passed through at point of sale. Retail Consumers dominates installed base. Corporations is where expansion concentrates.
- Corporations:Procurement departments consolidate vendor relationships around full-service packaging partners managing EPR registration and reverse logistics. Boutique wineries in Napa Valley and Oregon displace fragmented supplier bases with single-source contracts covering design, compliance documentation, and take-back. Corporations dominates installed base. Restaurants is where expansion concentrates.
- Event Planners:Wedding and corporate hospitality coordinators specify customized handbag formats with expedited turnaround for seasonal demand spikes.
- Restaurants:French and Italian foodservice operators specify leather and premium jute formats for tableside presentation and guest takeaway programs.
Retail Consumers command unit volume. Corporations are gaining share fastest as EPR consolidation reshapes vendor selection criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers in Guangdong and Zhejiang provinces supply insulated textile substrates to North American wine club fulfillment networks, while Indian jute processors export artisanal carriers to European specialty retail channels.
United States
Direct-to-consumer wine clubs in Napa Valley and Oregon's Willamette Valley specify branded neoprene totes for subscription box economics. California's SB 54 mandates post-consumer recycled content minimums that reshape converter sourcing strategies for brands distributing across North American retail channels. Arizona and Texas wine clubs drive demand for PCM-lined cooler variants in Phoenix and Dallas-Fort Worth metro areas.
France
Luxury gifting traditions in the Champagne region sustain premium leather and jute formats with 40%+ gross margins on limited editions. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate durable water repellent chemistries from textile substrates bound for European distribution. Reims and Épernay anchor artisanal leatherworking clusters serving heritage champagne houses.
India
Jute cultivation subsidies and textile processing incentives under the Production Linked Incentive framework attract contract manufacturing investment for European export. The country's national textile regulator enforces quality standards on bast fiber processing for international shipment. Kolkata and West Bengal state concentrate artisanal weaving operations supplying Param Jute Products and similar exporters.
China
Shenzhen and Wenzhou manufacturing clusters deliver vertically integrated sewing and heat-sealing operations for neoprene and canvas constructions. The Ministry of Ecology and Environment enforces dual carbon goals that pressure converters toward energy-efficient production methods. Guangzhou-based suppliers dominate film-laminate substrate production for moisture-barrier tote interiors.
Italy
Premium leather segments face steep reformulation timelines given heritage finishing protocols affected by REACH phthalate restrictions. Tuscany and Lombardy regions concentrate tannery operations supplying wine tote accessories for hospitality procurement. Milan-based design houses specify magnetic closure systems for tableside presentation formats.
Wine Totes Packaging Market Competitive Landscape
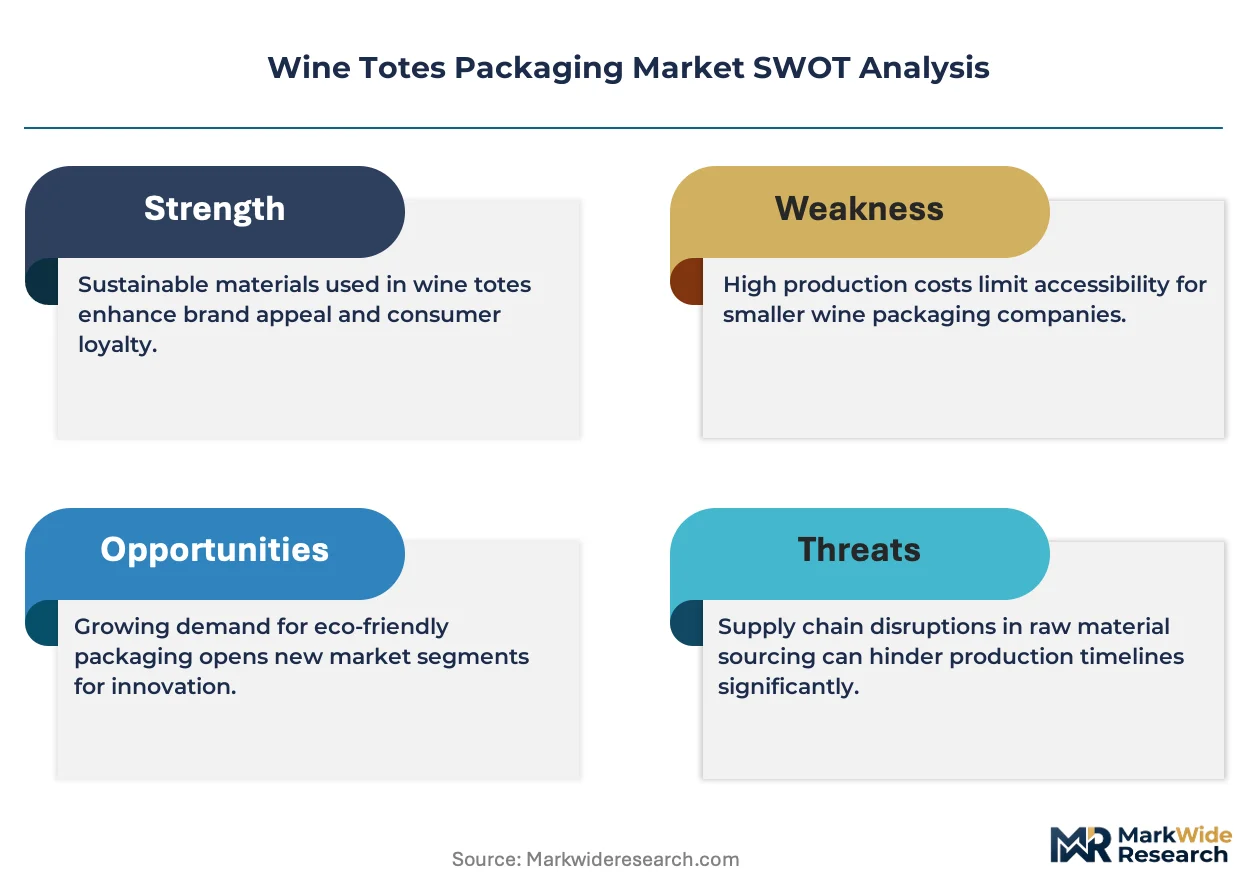
Listed leaders compete with private specialists across material technology and compliance documentation capabilities. The vendor base spans film-laminate substrate specialists, vertically integrated sewing operations, and artisanal weaving collectives. Three archetypes dominate: multinational converters with EPR registration capabilities, regional fabricators with heat-sealing automation, and craft-oriented suppliers with heritage positioning. Competitive moves center on M&A for compliance infrastructure and capacity expansion in India PLI-aligned zones.
Among Asia-Pacific-based fabricators, Shenzhen Beone Handbags Manufacturing and Wenzhou Guohong Packaging exemplify vertically integrated production models, while Param Jute Products occupies a position within the artisanal sustainability tier. Ampac Holdings represents the multinational converter archetype with film-laminate expertise. These three companies anchor the competitive spectrum from commodity scale to premium craft positioning.
| Leading Market Players |
|---|
| Ampac Holdings |
| Guangzhou Colorful Nonwoven Products |
| Wenzhou Guohong Packaging |
| Shenzhen Beone Handbags Manufacturing |
| Gogo Bags |
| Smartbags |
| Param Jute Products |
| Evans Manufacturing |
| Everwin Cottons Karur Private Limited |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between California wine clubs and Guangdong-based converters lock in neoprene supply access while fixing material cost visibility against chloroprene index volatility. These arrangements bind boutique wineries to minimum volume commitments that secure capacity reservation during peak summer fulfillment windows, insulating subscription economics from spot-market textile price spikes.
Pricing Analysis
Current-generation RF-welded neoprene constructions command 25-35% premiums over prior-generation stitched foam liners due to four-hour thermal stability guarantees. Three-tier pricing structure across premium leather, standard neoprene, and economy canvas levels tracks certification grade and customization depth, with REACH-compliant water-based polyurethane laminates adding 12-18% to European-bound unit costs. Cost compression in economy canvas segments is intensifying because pulp-molded mailer substitutes divert e-commerce volume from reusable categories. Corporate procurement departments show least price sensitivity as EPR compliance bundling obscures per-unit transparency, while retail consumers through Amazon marketplace channels drive hardest bargain hunting.
Supply Chain Analysis
Strategic stockpile preferences dominate converter procurement, with Shenzhen and Wenzhou manufacturers maintaining 60-90 day chloroprene foam inventories to buffer against petrochemical feedstock volatility. Supply concentrates in China's Guangdong and Zhejiang provinces for neoprene and canvas constructions, with India's West Bengal state anchoring jute bast fiber processing for European export. Raw material dependencies rest on chloroprene monomer from Japanese petrochemical complexes, polyester textile chips from South Korean refiners, and natural jute cultivation from Bangladesh delta regions. Single-source vulnerability runs through Guangzhou film-laminate substrate production for moisture-barrier tote interiors. Distribution runs through consolidated vendor relationships where full-service packaging partners manage EPR registration and reverse logistics for California Central Coast AVA wineries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPR compliance documentation and take-back logistics represent a service-attach layer expanding faster than hardware manufacturing, as boutique wineries displace fragmented supplier bases with single-source contracts covering design, certification, and reverse logistics management.
For Market Incumbents: Compound defensive positioning by acquiring India PLI-aligned jute processing capacity to secure European specialty retail margin pools against Param Jute Products' artisanal weaving dominance. Extend backward integration into Guangzhou film-laminate substrate production to capture moisture-barrier component margins currently flowing to Ampac Holdings, while accelerating RF welding automation to defend against labor cost inflation in neoprene liner assembly. For New Entrants and Emerging Players: California SB 54 third-party chain-of-custody certification fast-tracks offer entry into corporate procurement channels where EPR documentation requirements extend incumbent qualification cycles. White-space targets include PCM-lined cooler variants for Texas and Arizona wine clubs, and magnetic-closure leather formats for French restaurant tableside presentation. Penetration concentrates in Sun Belt direct-to-consumer fulfillment where thermal performance specifications outrun incumbent product refresh cycles. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors full-service packaging partners with EPR registration infrastructure over pure-play manufacturers. Long-term viability over the next decade hinges on compliance documentation capabilities becoming the primary vendor selection criterion. Acquisition target archetype: mid-cap converters with heat-sealing automation and existing California SB 54 certification. Signal to watch: state-level EPR legislation expansion beyond California that multiplies compliance burden and accelerates vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| RF Welding Automation Scale-Up | Reduces labor content in neoprene assembly for mid-market segment expansion. |
| India PLI-Aligned Jute Capacity | Captures cultivation subsidies and textile processing incentives for European export. |
| REACH-Compliant Coating Reformulation | Eliminates phthalate-based chemistries from European-bound textile substrates. |
| PCM Insert Technology Integration | Decomposes bulky foam insulation demand for slim-profile summer delivery formats. |
| EPR Registration Infrastructure Buildout | Consolidates boutique winery vendor relationships around compliance documentation services. |
Research Methodology
Cross-validation between converter production data and wine club fulfillment procurement records anchors the qualitative findings on material specification trends. Primary interviews with packaging procurement directors at Napa Valley wineries, RF welding equipment manufacturers in Shenzhen, and EPR compliance consultants in Sacramento combined with secondary validation from California SB 54 regulatory filings, EU REACH Annex XVII substance restriction updates, and India PLI scheme disbursement records. Bottom-up segmentation modeling triangulates against top-down market sizing from customs trade data on jute and neoprene textile exports.
Sensitivity analysis on CAGRs tests material substitution scenarios across the projection horizon, with neoprene-to-PCM migration rates and jute moisture-barrier adoption curves as key variable inputs. The analytical framework segments by material type, closure mechanism, style configuration, and target audience compliance burden, with thermal performance duration and EPR documentation intensity as industry-specific dimensions. CAGRs derive from fitted growth curves on subscription box fulfillment volumes and corporate gifting procurement cycles, cross-referenced against wine club membership expansion in Texas, Arizona, and Oregon's Willamette Valley.
Underlying assumptions cover sustained California SB 54 enforcement, stable chloroprene feedstock pricing, and REACH Annex XVII expansion to additional substance classes, with deviation risk concentrated in single-use mailer substitution rates and state-level EPR legislative contagion. Practitioners should keep alternative scenarios live as regulatory fragmentation and material technology substitution curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
Wine Bottle Sealing Wax Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Global Wine Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market