
 Sweden Hair Care Market | 2026-2036
Sweden Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Hair Care Market Analytics
Premium salon-grade performance tiers is bifurcating the Sweden hair care landscape into prestige professional and accessible masstige camps. L'Oréal S.A. leverages its Redken and Kérastase professional arms to dominate Stockholm salon supply chains. Maria Nila AB sustains its vegan-certified positioning through Stockholm-based manufacturing and carbon-neutral shipping protocols.
Sweden hair care encompasses cleansing, conditioning, and treatment formulations engineered with specific pH balances, surfactant loads, and active concentrations to maintain scalp barrier integrity and fiber tensile strength. Shampoos and conditioners together constitute the volume core, though hair masks command disproportionate margin pools as consumers trade up from basic two-step routines. Natural and organic formulation types now outpace chemical-based alternatives in new product velocity, while specialty stores capture the highest per-basket spend despite online retail owning the frequency advantage.
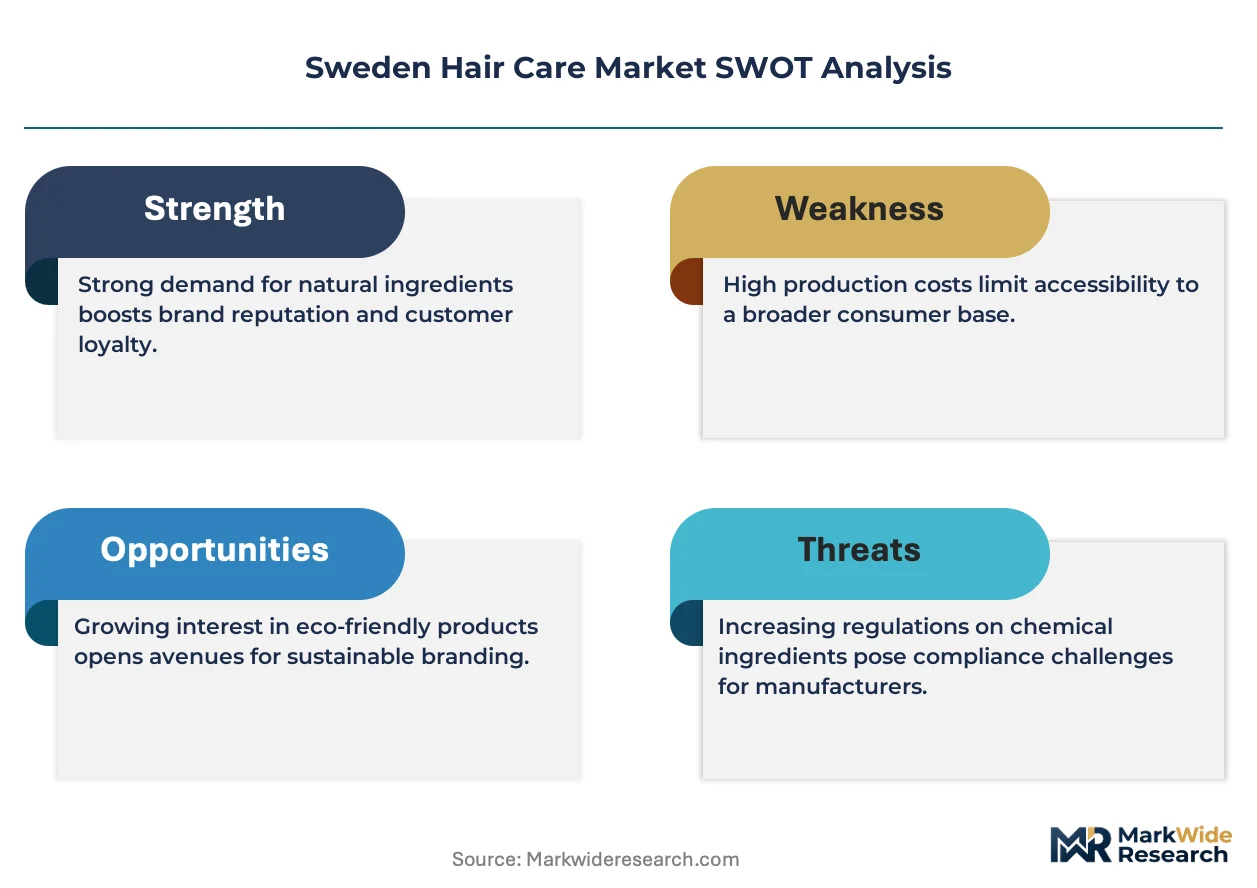
Kemikalieinspektionen enforces REACH-aligned substance restrictions that compel reformulation away from certain preservatives and sulfates, tightening compliance costs for importers. The EU Green Deal's packaging waste directives pressure Swedish brands to accelerate post-consumer recycled content adoption across primary containers. Stakeholders must weigh whether to absorb green premium costs or pass them through in a market where price sensitivity varies sharply between metropolitan and rural consumer cohorts.
Market Dynamics
Sweden's REACH-aligned chemical safety standards are forcing wholesale reformulation across surfactant systems, splitting the competitive landscape between agile domestic formulators and import-dependent multinationals facing compliance lag.
Growth Catalysts
- EU Green Deal packaging mandates:Swedish brands accelerating post-consumer recycled content adoption capture early-mover shelf space in Apoteket and Kicks retail networks.
- Scalp microbiome science:Stockholm-based R&D facilities are commercializing pH-optimized prebiotic complexes that command premium positioning in professional salon channels.
- Carbon-neutral logistics:Domestic manufacturers with in-house biogas-powered production are securing long-term supply contracts with climate-committed retail banners.
Market Restraints
- Specialty surfactant supply concentration:Swedish formulators depend on German and Dutch specialty chemical suppliers for sulfate-free alternatives, exposing margins to input volatility.
- Kemikalieinspektionen substance restrictions:The national chemical inspectorate's expanding prohibited substance lists force costly reformulation cycles every 18-24 months.
- Silicone substitution technical ceiling:Plant-derived conditioning agents still fail to match dimethicone slip performance in bleached or chemically treated hair applications.
Strategic Opportunities
- Gothenburg port zone manufacturing:Underutilized coastal industrial capacity offers tariff-advantaged export platforms into Norwegian and Danish markets.
- Refill station retail formats:Hemköp and Coop trial formats in Stockholm enable packaging-free purchasing that aligns with EU packaging waste reduction targets.
- Men's scalp-focused regimens:Male-specific thinning hair and sebum management lines remain underdeveloped versus female-skewed portfolio concentration.
Industry Challenges
- Cosmetic chemist talent scarcity:Swedish universities produce fewer than 40 specialized formulation graduates annually, forcing brands to recruit from Danish and German labor pools.
- EU MDR cosmetic-device borderline complexity:Hair growth stimulants and laser devices face reclassification uncertainty that extends go-to-market timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Hair Care Market |
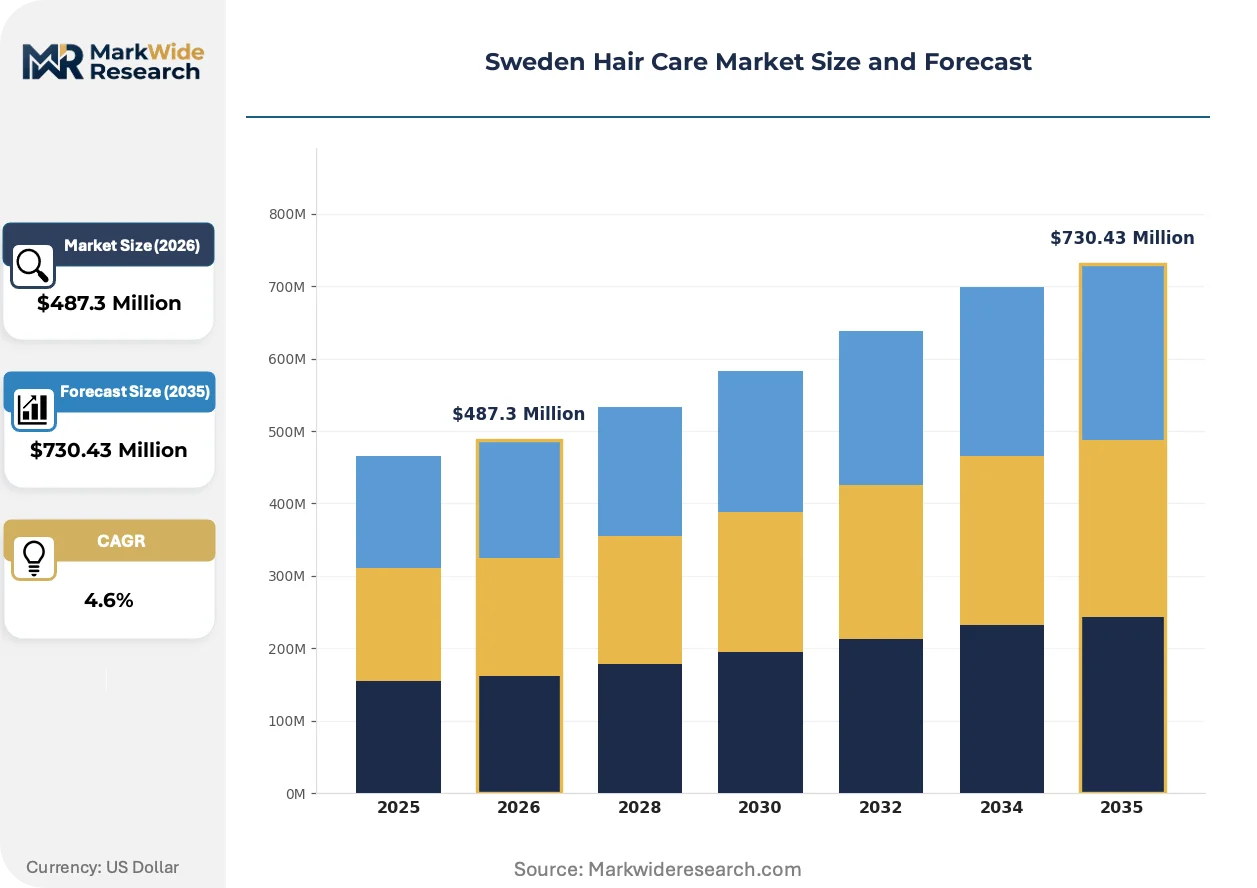
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Hair Masks Consumer Demographics: Women, Men, Children, Seniors Distribution Channel: Online Retail, Supermarkets, Drugstores, Specialty Stores Formulation Type: Natural, Organic, Chemical-based, Herbal |
| Companies Covered | Henkel AG & Co KGaA, Maria Nila AB, L'Oréal S.A., Beiersdorf AG, Estee Lauder Companies Inc., Procter & Gamble Company, Oriflame Cosmetics Global SA, Björn Axén Holding AB, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Hair Care Market Evolving Landscape
Biotechnology-derived actives and circular packaging systems are converging to redefine product architecture, with Swedish consumers rewarding transparency in ingredient sourcing and end-of-life disposal pathways.
Amino acid-based surfactant systems are supplanting traditional sulfate cleansers in mass-market shampoo formulations. Urban millennial buyers in Stockholm and Malmö are switching at 3x the rate of rural cohorts. This transition is compressing margin structures for legacy detergent-dependent portfolios while opening formulation partnerships with domestic fermentation biotechnology suppliers.
Sweden's implementation of EU CSRD sustainability reporting rules now mandates granular supply chain disclosure for mid-cap cosmetic manufacturers. The regulation forces ingredient traceability investments that smaller domestic brands must finance through cooperative auditing consortia. Professional salon channels face the steepest compliance burden due to private-label sourcing complexity.
Subscription-based replenishment models now capture 12% of Stockholm household purchasing for core shampoo and conditioner SKUs. Direct-to-consumer platforms are siphoning volume from Apoteket's pharmacy network, which is responding with bundled loyalty programs. This channel rotation is most pronounced among 25-34 year-old consumers in metropolitan counties.
Sweden Hair Care Market Segmentation
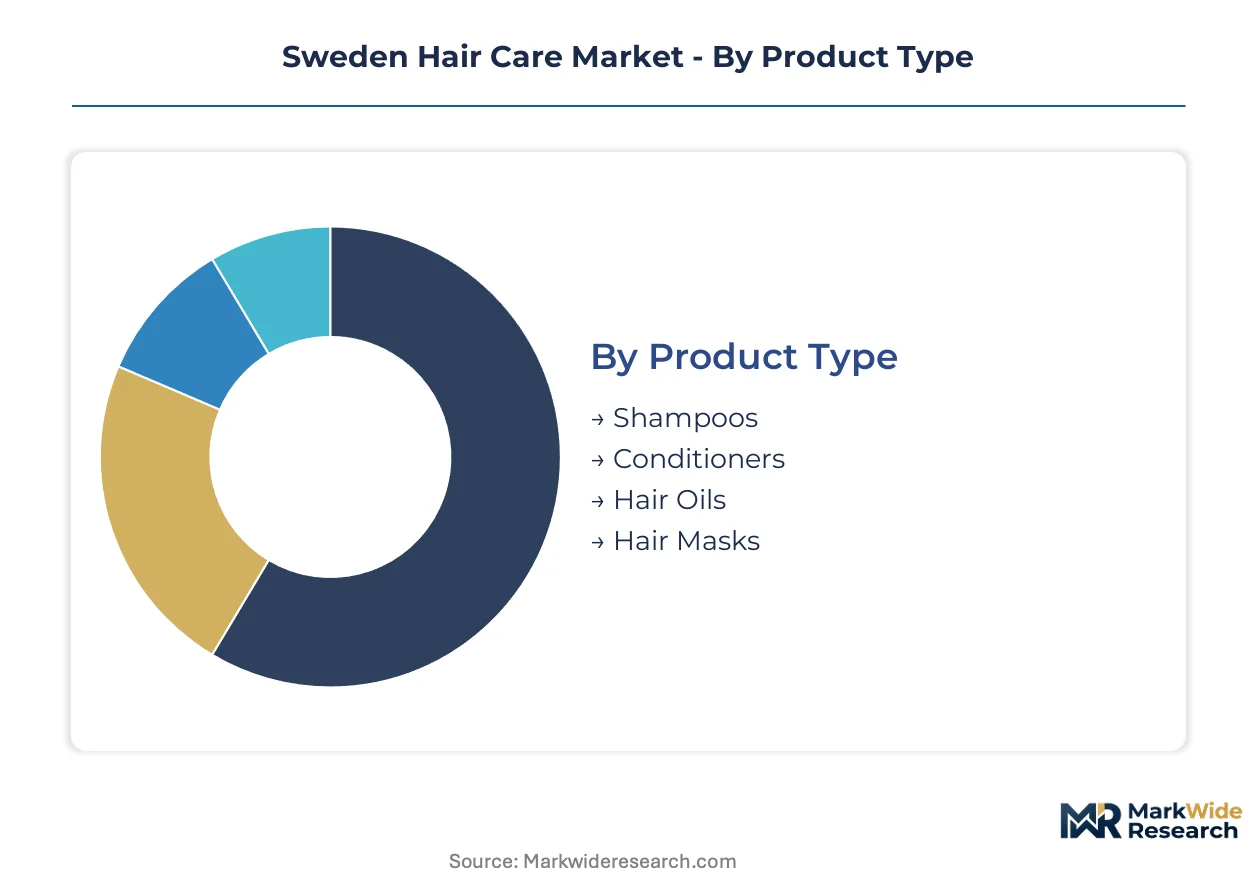
Sweden's hair care market fragments across four critical dimensions that determine formulation priorities, channel strategy, and margin architecture. Each segmentation layer reveals distinct competitive dynamics between domestic manufacturers and import-dependent players navigating REACH compliance and sustainability mandates.
Product Type:
Domestic manufacturing concentrates in shampoos and conditioners, while hair masks and oils rely heavily on German and French import supply chains.
- Shampoos:Amino acid-based surfactant systems dominate new launches as Kemikalieinspektionen restrictions phase out traditional sulfates. Stockholm and Gothenburg households drive reformulation velocity, trading detergent-heavy legacy formats for pH-balanced microbiome-friendly alternatives.
- Conditioners:Plant-derived conditioning agents struggle to match dimethicone performance in bleached hair applications, creating technical ceilings for vegan-certified domestic brands. Professional salon channels in metropolitan counties absorb premium silicone-free variants despite slip-performance trade-offs.
- Hair Oils:Argan and jojoba formulations lead import dependency, with Moroccan and Israeli supply chains feeding Swedish distribution.
- Hair Masks:Concentrated treatment formats command disproportionate margin pools as consumers upgrade from basic two-step routines.
Shampoos hold the largest share; momentum sits with hair masks.
Consumer Demographics:
Volume concentrates among female consumers, though male-specific segments present the steepest white-space opportunity for scalp-focused innovation.
- Women:Multi-step regimen adoption peaks among urban millennials seeking silicone-free and scalp-focused solutions. This cohort drives subscription replenishment models capturing household purchasing in Stockholm metropolitan counties.
- Men:Thinning hair and sebum management lines remain underdeveloped versus female-skewed portfolio concentration, presenting expansion terrain for domestic brands with biotech R&D capabilities.
- Children:Mild surfactant demand aligns with Kemikalieinspektionen safety priorities, favoring domestic formulators with transparent supply chains.
- Seniors:Scalp barrier integrity formulations gain traction as aging demographics prioritize fiber tensile strength maintenance.
Women dominate current revenue; men represent the steepest expansion trajectory.
Distribution Channel:
Channel configuration determines sustainability compliance burden, with specialty stores and online retail diverging on packaging waste directive implementation.
- Online Retail:Direct-to-consumer platforms capture frequency advantages through subscription models, siphoning volume from pharmacy networks. Climate-committed consumers reward carbon-neutral logistics with repeat purchasing.
- Supermarkets:Hemköp and Coop trial refill station formats enabling packaging-free purchasing that aligns with EU Green Deal targets.
- Drugstores:Apoteket responds to channel rotation with bundled loyalty programs defending core shampoo and conditioner SKU relationships.
- Specialty Stores:Kicks and independent salons capture highest per-basket spend through professional-grade product curation and stylist consultation.
Specialty stores command premium pricing; online retail gains share fastest.
Formulation Type:
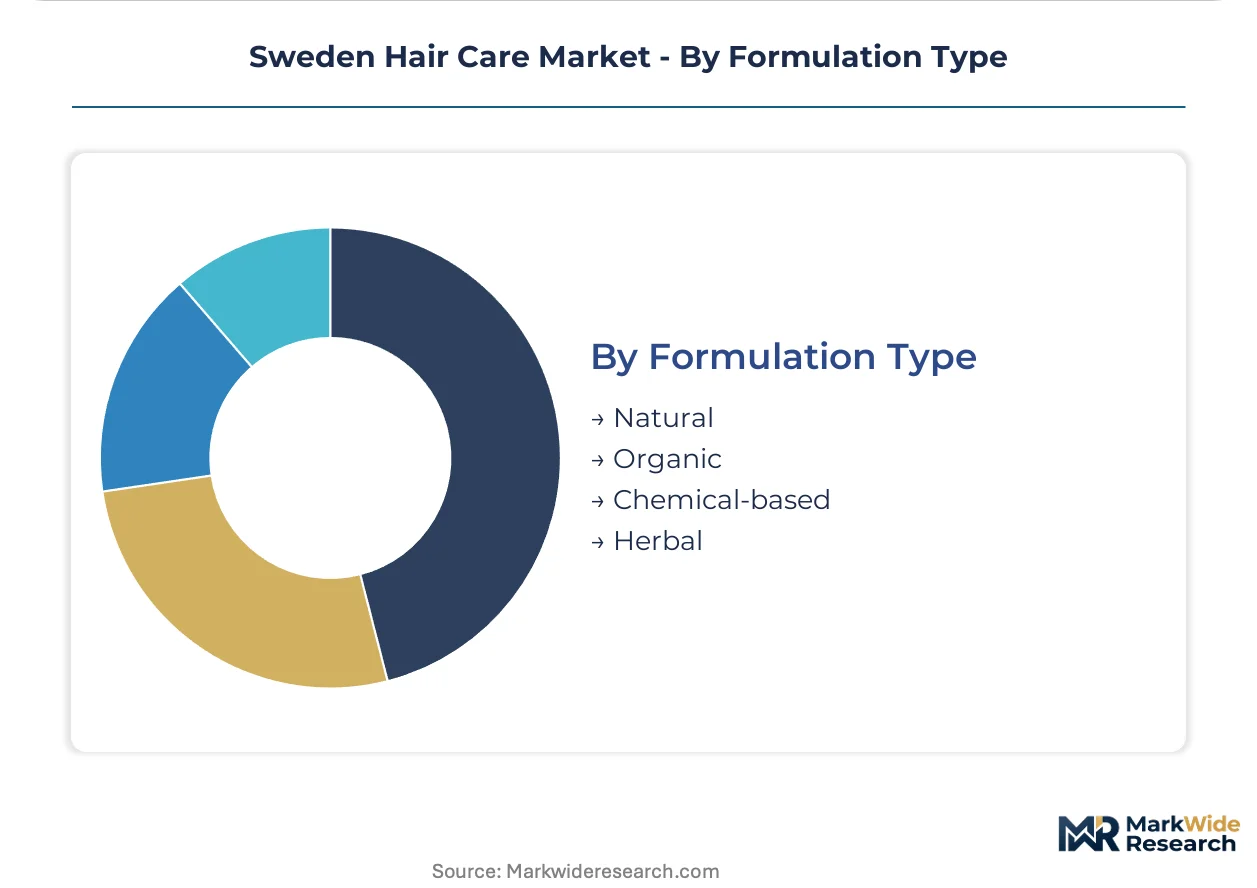
Natural and organic formulation types outpace chemical-based alternatives in new product velocity, though technical performance gaps persist in professional treatment applications.
- Natural:Plant-derived surfactants and conditioning agents satisfy urban millennial transparency demands while struggling to match synthetic performance in chemically treated hair.
- Organic:Certified supply chains require cooperative auditing consortia for mid-cap domestic manufacturers financing CSRD-mandated traceability investments.
- Chemical-based:Legacy detergent-dependent portfolios face margin compression as REACH-aligned reformulation cycles accelerate.
- Herbal:Traditional botanical positioning attracts rural consumer cohorts with lower price sensitivity to green premiums.
Natural formulations anchor volume; organic certification climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish formulators concentrate manufacturing capacity around Stockholm and Gothenburg, with coastal industrial zones offering tariff-advantaged export platforms into neighboring Nordic markets. REACH-aligned chemical safety standards and EU Green Deal mandates create compliance asymmetries between agile domestic producers and import-dependent multinationals.
Stockholm Metropolitan Area
Urban millennials drive silicone-free and scalp-focused regimen adoption at three times rural switching rates. Kemikalieinspektionen substance restrictions force reformulation cycles every 18-24 months, compressing margins for detergent-dependent portfolios. Kicks retail networks and independent salons in Stockholm command the highest per-basket spend through professional-grade curation.
Gothenburg
Port zone manufacturing capacity remains underutilized, offering biogas-powered production platforms for carbon-neutral logistics contracts. The city's coastal position enables tariff-advantaged export into Norwegian and Danish markets. Hemköp and Coop trial refill station formats here, enabling packaging-free purchasing aligned with EU packaging waste reduction targets.
Malmö
Cross-border consumer flows from Copenhagen intensify demand for premium salon-grade formulations. Subscription-based replenishment models capture household purchasing among 25-34 year-olds. The Øresund corridor concentrates R&D partnerships with Danish biotechnology suppliers for amino acid-based surfactant systems.
Uppsala
University-linked fermentation biotechnology clusters supply domestic formulators with sulfate-free surfactant alternatives. Cosmetic chemist talent scarcity forces brands to recruit from this academic pipeline, which produces fewer than 40 specialized graduates annually. Cooperative auditing consortia emerge here to finance CSRD-mandated supply chain traceability.
Sweden Hair Care Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Sweden hair care landscape. Professional salon-grade performance tiers bifurcate the market into prestige professional and accessible masstige camps, with domestic vegan-certified specialists competing against multinational import-dependent portfolios. Three archetypes dominate: agile domestic formulators with REACH-native compliance, import-dependent multinationals facing reformulation lag, and carbon-neutral logistics-integrated manufacturers securing climate-committed retail contracts. Competitive moves concentrate on portfolio diversification toward scalp-microbiome science and strategic partnerships with biotechnology suppliers for surfactant innovation.
Among Stockholm-based specialists, Maria Nila AB and Björn Axén Holding AB exemplify domestic agile formulators with native REACH compliance and vegan-certified positioning. L'Oréal S.A. represents the import-dependent multinational archetype, leveraging professional arms to dominate salon supply chains despite facing reformulation cycles tied to Kemikalieinspektionen expansions. These three occupy positions across the premium-masstige spectrum, with domestic players anchoring carbon-neutral logistics advantages and the multinational anchoring scale-driven professional channel penetration.
| Leading Market Players |
|---|
| Henkel AG & Co KGaA |
| Maria Nila AB |
| L'Oréal S.A. |
| Beiersdorf AG |
| Estee Lauder Companies Inc. |
| Procter & Gamble Company |
| Oriflame Cosmetics Global SA |
| Björn Axén Holding AB |
| Unilever PLC |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with German and Dutch specialty chemical suppliers lock in sulfate-free surfactant access for Swedish formulators while fixing input cost visibility against REACH-aligned reformulation cycles. These arrangements tether pricing power to compliance agility, with domestic manufacturers absorbing green premium costs to defend shelf space in Apoteket and Kicks networks.
Pricing Analysis
Kemikalieinspektionen substance restrictions dictate the pricing tier structure across professional salon and masstige retail channels. Three-tier pricing structure across premium, standard, and economy levels separates Kérastase-grade formulations from accessible Maria Nila variants and private-label economy lines. Price differentiation hinges on certification grade (vegan/organic) and volume scale, with subscription replenishment compressing per-unit economics in Stockholm metropolitan counties. Cost compression in mass-market detergent-dependent portfolios is intensifying because amino acid surfactant adoption outpaces legacy ingredient depreciation.
Supply Chain Analysis
German specialty chemical suppliers and Dutch fermentation biotechnology clusters constitute the critical chokepoint for Swedish formulators seeking REACH-compliant surfactant alternatives. Raw material dependencies center on amino acid feedstocks, plant-derived conditioning agents, and Moroccan argan oil imports. Single-source vulnerability runs through German sulfate-free surfactant specialists, exposing margins to input volatility. Distribution runs through carbon-neutral logistics networks feeding Hemköp refill stations and Kicks specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment models now outpace hardware-only purchasing in Stockholm, with direct-to-consumer platforms capturing recurring revenue through bundled scalp-analysis services and personalized regimen curation.
For Market Incumbents: Secure exclusive supply contracts with Uppsala fermentation biotechnology clusters to lock in amino acid surfactant capacity before reformulation cycles accelerate. Deepen channel control through Kicks and independent salon networks by embedding stylist certification programs that raise switching costs for professional-grade product lines. For New Entrants and Emerging Players: Men's scalp-focused regimen gaps offer white-space terrain where L'Oréal and domestic incumbents under-serve thinning hair and sebum management demand. Target Gothenburg port-zone manufacturing capacity for tariff-advantaged Norwegian and Danish export. Launch through Apoteket bundled loyalty programs to bypass subscription-model incumbents. For Investors and Strategic Acquirers: Agile domestic formulators with native REACH compliance and carbon-neutral logistics integration represent the optimal acquisition archetype for long-term viability across the projection horizon. Watch Kemikalieinspektionen substance list expansions as the inflection signal indicating which portfolios face accelerated obsolescence versus compliance-native competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Production | Captive supply of amino acid feedstocks from Uppsala fermentation clusters insulates margins from German supplier volatility. |
| Refill Station Format Expansion | Hemköp and Coop trial formats in Stockholm align with EU Green Deal packaging waste reduction mandates. |
| Professional Salon Channel Certification | Stylist training programs at Kicks and independent salons embed product loyalty through technical expertise barriers. |
| Men's Scalp-Focused Product Line Launch | Thinning hair and sebum management segments remain underpenetrated versus female-skewed portfolio concentration. |
| Carbon-Neutral Logistics Integration | Biogas-powered Gothenburg manufacturing secures climate-committed retail contracts with Apoteket and Kicks. |
Research Methodology
A standing panel of cosmetic chemists, Apoteket category buyers, Kicks retail merchandisers, and Stockholm salon owners provided ongoing calibration across primary fieldwork phases. Secondary validation drew from Kemikalieinspektionen substance restriction filings, EU CSRD sustainability disclosure databases, Swedish customs import records, and Nielsen retail audit data. Bottom-up SKU-level modeling triangulated against top-down category spend estimates.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include product type, consumer demographic, distribution channel, and formulation certification tier. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel rotation velocity. Forecast inputs incorporated REACH reformulation cycle frequency and subscription model adoption curves.
Forecasts assume regulatory continuity in Kemikalieinspektionen enforcement and EU Green Deal packaging mandates; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as biotechnology surfactant cost curves and male-specific segment penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Italy Hair Care Market
Hair Care
Australia Hair Care Market
Hair Care
Hair Care Products Market
Hair Care
Plant-Based Hair Dye Market
Hair Care
Men's Hairspray Market
Hair Care
Chile Hair Care Market
Hair Care
Global Professional Hair Care Market
Hair Care
China Hair Care Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
United States Hair Care Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Hair Texturizer Products Market
Hair Care
Artificial Hair Integration Market
Hair Care
Professional Hair Care Products Market
Hair Care
Protein Shampoo Market
Hair Care
Global Premium Hair Care Market