
 South Korea Dermocosmetics Market | 2026-2036
South Korea Dermocosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Dermocosmetics Market Insights
The EU Green Deal's influence on ingredient transparency standards is rebalancing procurement priorities for Korean dermocosmetics exporters. Amorepacific Corporation leverages its integrated R&D campus in Yongin to sustain formulation leadership across peptide-based lines. LG Household & Health Care anchors its position through controlled distribution in premium beauty clinics nationwide. COSMAX Group competes as a contract manufacturer with specialized capacity for nanotechnology delivery systems.
Dermocosmetics denotes dermatologically tested skincare products containing active pharmaceutical or biologically functional ingredients at concentrations requiring clinical validation, typically manufactured under GMP conditions with pH-balanced, hypoallergenic formulations designed for therapeutic or preventive skin management. The segment spans cleansers, moisturizers, serums, sunscreens, and exfoliants, with serums capturing concentrated margin pools due to higher active ingredient loading and premium positioning. Nanotechnology and peptide complex formulations represent the fastest-expanding technology categories as brands invest in transdermal delivery efficacy. Anti-aging and UV protection applications dominate volume, while acne treatment and hyperpigmentation lines show accelerating clinic-channel growth.
MFDS, KFDA-established cosmetic safety guidelines, and ISO 22716 GMP standards collectively govern product registration, ingredient disclosure, and manufacturing compliance in South Korea. These frameworks elevate barriers for imported brands while rewarding domestic players with established quality infrastructure and regulatory familiarity. Stakeholders must monitor evolving MFDS requirements for microbiome and probiotic ingredient classifications as these categories attract formulation investment.
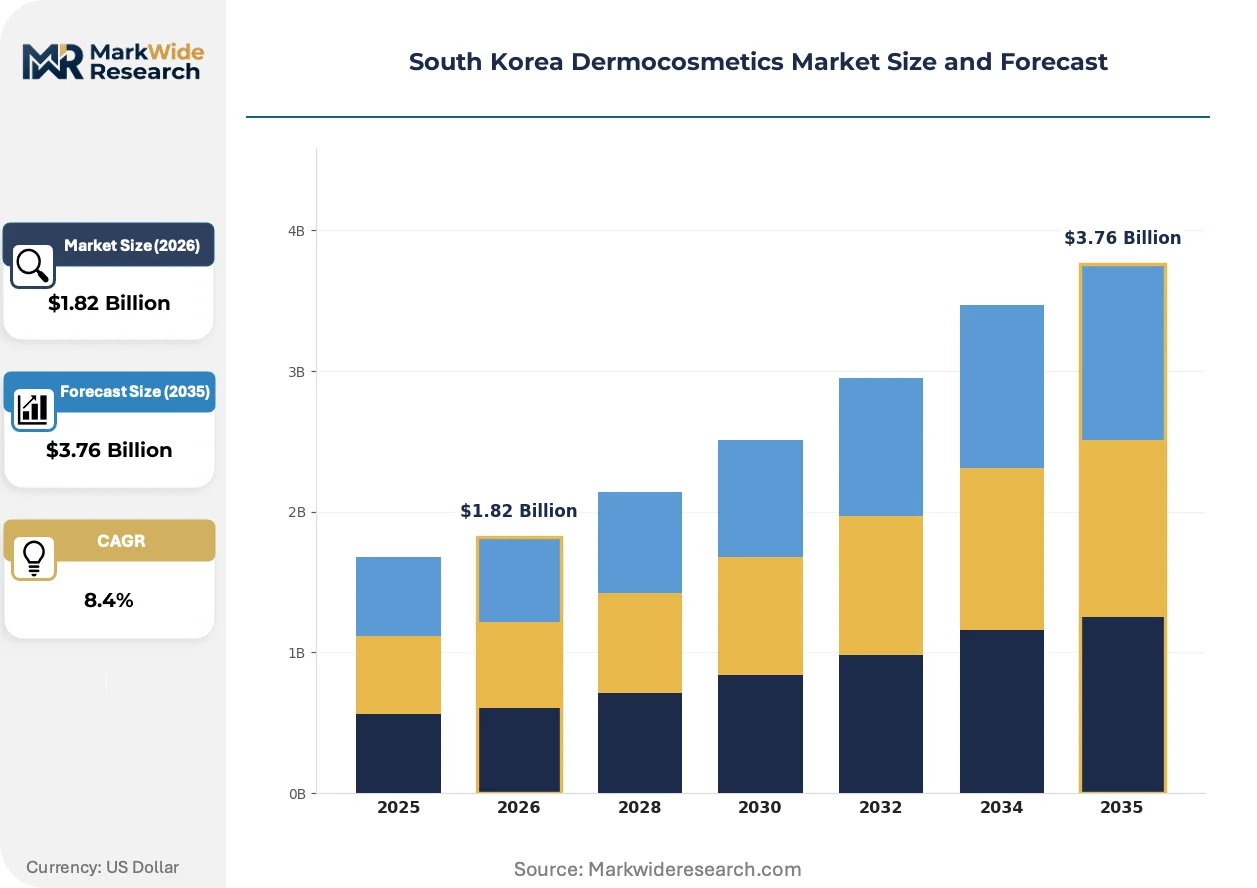
Market Dynamics
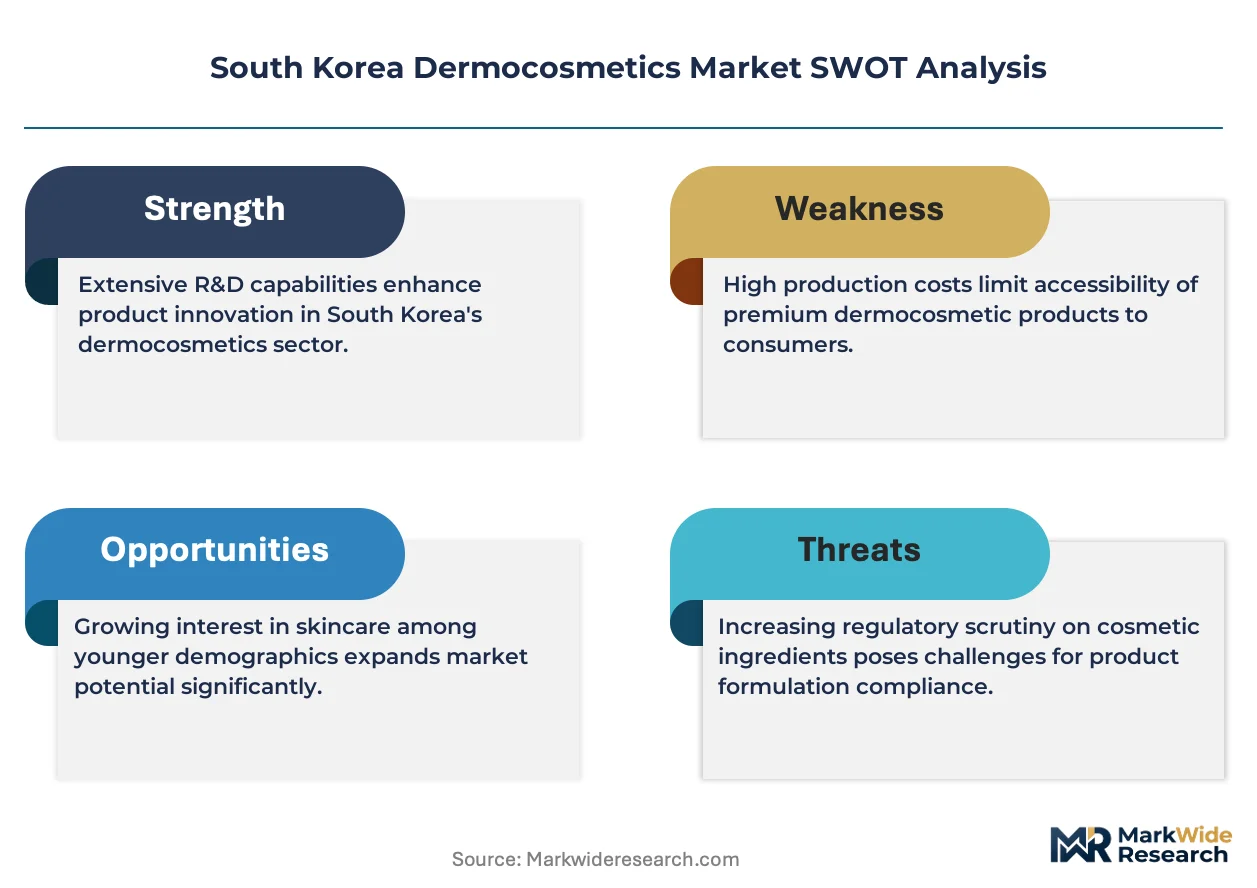
MFDS tightening of cosmetic safety assessments is compressing formulation timelines and elevating clinical validation costs across South Korean dermocosmetics manufacturers. This regulatory pressure is modularizing R&D workflows as brands restructure around GMP-compliant production clusters.
Growth Catalysts
- MFDS Safety Assessment Protocols:Stricter microbiome ingredient classifications are accelerating investment in probiotic formulation science. Domestic manufacturers with established quality infrastructure capture first-mover advantage in prebiotic skincare lines.
- Peptide Nanotechnology:Transdermal delivery systems are improving bioavailability of active compounds in anti-aging serums. Contract manufacturers with specialized nanotechnology capacity command premium positioning in clinic-channel supply.
- Seoul-Busan Consumer Corridor:Young adult demand for science-backed routines concentrates purchasing power in premium UV protection and hyperpigmentation treatments. Dermatology clinic distribution networks expand to capture this demographic.
Market Restraints
- Clinical-Grade Input Costs:Pharmaceutical-grade peptide suppliers concentrate in Switzerland and Germany, exposing Korean formulators to euro-denominated raw material volatility and extended procurement cycles.
- Import Regulatory Friction:EU REACH compliance requirements for ingredient transparency create documentation burdens for Korean exporters targeting European dermatology channels.
- Biologic Stability Limitations:Probiotic and live culture formulations face shelf-life constraints that compress distribution radius and complicate cross-border logistics.
Strategic Opportunities
- Gwangju-Jeonnam Manufacturing Belt:Underdeveloped dermocosmetics production capacity in southwestern Korea offers land and labor cost arbitrage for GMP facility expansion.
- Post-Procedure Recovery Applications:Laser and injectable aesthetic procedure growth creates adjacent demand for barrier-repair and redness-reduction formulations distributed through clinic networks.
- ISO 22716 Convergence:Harmonization between Korean GMP standards and international cosmetic manufacturing norms reduces dual-certification overhead for export-oriented players.
Industry Challenges
- Formulation Chemist Talent Scarcity:Specialized expertise in nanotechnology encapsulation and peptide stability commands premium compensation, constraining mid-tier manufacturer hiring.
- Clinical Trial Timeline Compression:MFDS validation requirements for novel active ingredients extend product development cycles, tying up capital in pre-revenue pipelines.
- Legacy ERP Integration:Batch record digitization for GMP compliance creates friction with established manufacturing execution systems at family-owned production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Dermocosmetics Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleansers, Moisturizers, Serums, Sunscreens, Exfoliants Formulation Technology: Nanotechnology, Liposome, Encapsulation, Microemulsion, Peptide Complex Application: Anti-Aging, Acne Treatment, Hyperpigmentation, Sensitive Skin Care, UV Protection End User: Dermatologists, Beauty Clinics, Pharmacies, Online Retailers, Specialty Stores |
| Companies Covered | Beiersdorf, Neogen Corporation, Amorepacific Corporation, Kolmar Korea, COSMAX Group, LG Household & Health Care, Estée Lauder Companies Inc., MEDIHEAL, L'Oréal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Dermocosmetics Market Trends and Innovations
Transdermal delivery science and regulatory data transparency are restructuring how South Korean dermocosmetics reach clinic and direct-to-consumer channels. Formulation investment concentrates on efficacy validation and supply chain traceability.
Nanotechnology encapsulation systems are modularizing peptide and antioxidant delivery across serum and ampoule formats. Dermatology clinics in Gangnam and Seongsu-dong adopt these platforms at accelerated pace for post-treatment protocols. This technology is compressing the efficacy gap between professional and at-home skincare, enabling premium pricing for clinically validated consumer lines.
MFDS disclosure requirements for biologically active ingredient concentrations are elevating documentation burdens across manufacturing. Domestic brands with integrated Yongin-based R&D campuses absorb compliance costs more efficiently than import-dependent competitors. Anti-aging and UV protection categories face the steepest reformulation timelines as safety dossier standards tighten.
Clinic-channel procurement is consolidating around outcome-verified suppliers with published clinical data. Young adult consumers in Seoul research ingredient mechanisms before purchase, displacing brand-loyalty with efficacy-driven selection. This behavioral shift concentrates margin capture among manufacturers with peer-reviewed formulation science and transparent supply chain disclosure.
South Korea Dermocosmetics Market Segmentation
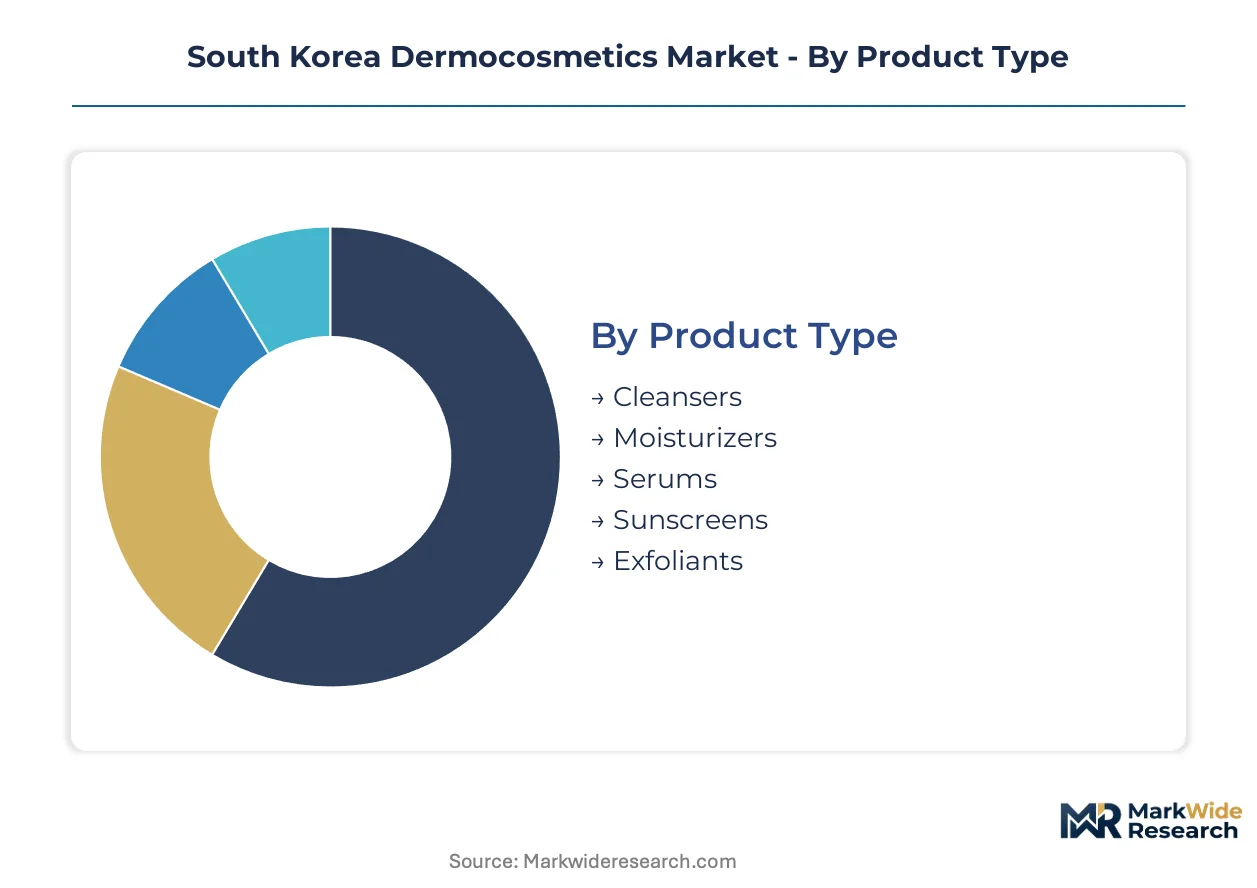
Dermocosmetics segmentation in South Korea tracks how formulation sophistication, channel access, and clinical validation requirements reshape purchasing decisions across Seoul-Busan consumer corridors. Manufacturers align R&D investments with MFDS compliance tiers and clinic-channel procurement standards.
Product Type:
Buyers in this category distinguish products by active ingredient loading density and the clinical validation burden each format carries.
- Serums:High-concentration aqueous or oil-based solutions with peptide complexes and antioxidants at therapeutic thresholds. Dermatology clinics in Gangnam prescribe these for post-laser recovery protocols, with MFDS concentration disclosure rules elevating documentation costs for imported alternatives.
- Sunscreens:Photostable formulations combining organic and inorganic UV filters at SPF ratings demanding clinical substantiation. Young adult consumers in Seoul research ingredient photodegradation profiles before purchase, compressing margin for brands without transparent supply chain data.
- Cleansers:pH-balanced surfactant systems with minimal residual irritation profiles for barrier-compromised skin.
- Moisturizers:Occlusive and humectant blends targeting transepidermal water loss reduction in post-procedure recovery.
- Exfoliants:Alpha-hydroxy acid and enzyme-based formulations with controlled penetration depths for clinic-supervised protocols.
Volume sits with sunscreens; growth tilts toward serums.
Formulation Technology:
Technology selection determines bioavailability thresholds and the manufacturing capital intensity required for GMP compliance.
- Nanotechnology:Sub-micron particle systems enhancing transdermal penetration of lipophilic actives. COSMAX Group maintains specialized production lines for this category, supplying Gangnam clinic chains with outcome-verified delivery platforms.
- Peptide Complex:Stabilized amino acid chains targeting collagen synthesis and cellular signaling pathways. Amorepacific's Yongin campus anchors domestic capacity, though pharmaceutical-grade raw material sourcing concentrates in Switzerland and Germany.
- Liposome:Phospholipid bilayer encapsulation systems protecting sensitive actives from oxidative degradation.
- Encapsulation:Polymer or lipid shell systems enabling time-release kinetics for retinoid and vitamin C formulations.
- Microemulsion:Thermodynamically stable oil-water dispersions with droplet sizes below 100 nanometers for enhanced skin penetration.
Capacity concentrates with nanotechnology; clinic procurement is climbing the fastest for peptide complex platforms.
Application:
Application segmentation follows procedure adjacency and the demographic concentration of condition-specific demand.
- Anti-Aging:Retinoid, peptide, and antioxidant formulations targeting photoaging and intrinsic collagen depletion. Premium positioning in Seongsu-dong beauty clinics sustains margin pools despite extended MFDS safety dossier timelines.
- UV Protection:Photodamage prevention products with reef-safe filter alternatives responding to EU Green Deal procurement pressure on Korean exporters.
- Acne Treatment:Benzoyl peroxide and salicylic acid formulations with microbiome-conscious adjunct ingredients.
- Hyperpigmentation:Tyrosinase inhibitor and melanin dispersal agents for post-inflammatory discoloration management.
- Sensitive Skin Care:Minimalist formulations with excluded irritant lists verified through patch testing protocols.
Revenue pools concentrate in anti-aging; UV protection is gaining share fastest among young adult segments.
End User:
Channel selection determines validation requirements, pricing autonomy, and the consumer education burden each intermediary assumes.
- Dermatologists:Prescriptive or recommendation-based distribution with outcome accountability and patient follow-up protocols. MFDS registration requirements for clinic-exclusive lines elevate barriers to entry for new market entrants.
- Beauty Clinics:Procedure-adjacent retail with staff-trained consultation models in Gangnam and Busan premium districts. LG Household & Health Care anchors position through controlled distribution networks in this channel.
- Pharmacies:Over-the-counter access with pharmacist-mediated selection for condition-specific concerns.
- Online Retailers:Direct-to-consumer platforms with ingredient transparency disclosure and review-mediated purchasing decisions.
- Specialty Stores:Curated retail environments with staff expertise in skin type matching and routine construction.
Transaction volume flows through beauty clinics; online retailers are expanding most quickly among Seoul-based young adults.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area dominates South Korean dermocosmetics demand through Gangnam and Seongsu-dong clinic clusters where young adults research ingredient mechanisms before purchase. MFDS safety dossier requirements compress formulation timelines for manufacturers serving this corridor.
Seoul Capital Area
Premium anti-aging serums and UV protection products concentrate demand in Gangnam dermatology clinics and Seongsu-dong beauty districts. MFDS disclosure rules for active ingredient concentrations elevate documentation burdens for imported brands competing against domestic players with Yongin-based R&D infrastructure. Amorepacific's integrated campus anchors peptide complex formulation capacity serving clinic-channel procurement networks.
Busan-Ulsan
Young adult consumers in Busan drive science-backed skincare adoption through specialized online channels and premium beauty clinic networks. The region's port infrastructure supports raw material imports for GMP-compliant manufacturing facilities. Contract manufacturers with nanotechnology delivery capacity supply clinic chains expanding across this southeastern corridor.
Daegu-Gyeongbuk
Post-procedure recovery formulations gain traction alongside laser and injectable aesthetic procedure growth in regional medical centers. MFDS microbiome ingredient classifications push manufacturers toward probiotic skincare lines. Production capacity remains underdeveloped relative to demand, creating procurement reliance on Seoul-based suppliers.
Daejeon-Sejong
Government research institutions in this central region contribute to peptide stability and transdermal delivery science advancing formulation capabilities. ISO 22716 GMP standard harmonization efforts concentrate regulatory expertise here. Limited manufacturing presence constrains local supply chain integration despite R&D proximity advantages.
Gwangju-Honam
The southwestern manufacturing belt offers land and labor cost arbitrage for GMP facility expansion targeting underserved clinic networks. Biologic stability limitations for probiotic formulations complicate distribution radius planning from this location. Infrastructure investment lags Seoul and Busan corridors, delaying full integration into national supply chains.
South Korea Dermocosmetics Market Competitive Landscape
The competitive structure tilts toward integrated domestic conglomerates with captive R&D infrastructure and controlled distribution networks. Market concentration rewards players with Yongin-based formulation campuses and established MFDS regulatory familiarity. Three archetypes dominate: vertically integrated beauty conglomerates, specialized contract manufacturers with nanotechnology capacity, and multinational dermatology brands with import-dependent positioning. Competitive moves center on clinic-channel exclusivity agreements and backward integration into pharmaceutical-grade peptide sourcing.
Within the integrated conglomerate tier, Amorepacific Corporation and LG Household & Health Care anchor domestic capacity through controlled distribution in premium beauty clinics nationwide. COSMAX Group occupies a position as the representative contract manufacturing specialist, supplying Gangnam clinic chains with outcome-verified delivery platforms. Among multinational players, Beiersdorf and L'Oréal exemplify import-dependent positioning navigating EU REACH compliance burdens for Korean market access.
| Leading Market Players |
|---|
| Beiersdorf |
| Neogen Corporation |
| Amorepacific Corporation |
| Kolmar Korea |
| COSMAX Group |
| LG Household & Health Care |
| Estée Lauder Companies Inc. |
| MEDIHEAL |
| L'Oréal |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's reef-safe filter mandates and ingredient transparency protocols are gating qualified supply access and premium-tier pricing power for Korean dermocosmetics exporters. Domestic manufacturers with ISO 22716 GMP certification and published clinical data capture pricing autonomy in clinic-channel procurement, while import-dependent brands absorb compliance cost premiums.
Pricing Analysis
Outcome-verified efficacy data anchors value-based pricing for anti-aging serums prescribed through Gangnam dermatology clinics. Three-tier pricing structure across premium clinic-exclusive, standard retail, and economy direct-to-consumer levels stratifies by MFDS registration tier and clinical validation depth. Pricing pressure stems from pharmaceutical-grade peptide input costs denominated in euros, compressing margins for mid-tier formulators without backward integration into raw material sourcing. Price sensitivity concentrates among young adult online purchasers researching ingredient mechanisms, while clinic-channel buyers prioritize outcome accountability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive probiotic formulations remain underdeveloped, constraining distribution radius and shelf-life management for live culture skincare lines. Active pharmaceutical ingredient supply concentrates in Switzerland, Germany, and South Korea, with Korean formulators drawing from Swiss peptide suppliers and domestic nanotechnology encapsulation specialists. Supply chain risk centers on euro-denominated raw material volatility and single-source dependency for pharmaceutical-grade inputs. Distribution runs through dermatology clinic networks in Seoul and Busan, supplemented by specialized online channels with cold-chain capabilities for biologic formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korean dermocosmetics are transitioning from brand-loyalty purchasing to efficacy-verified selection, with nanotechnology delivery systems displacing conventional formulation approaches. This technology shift rewards manufacturers with integrated R&D infrastructure and published clinical validation.
For Market Incumbents: Deploy clinic-channel exclusivity agreements to lock in procurement relationships with Gangnam and Seongsu-dong dermatology networks. Incumbents should deepen backward integration into pharmaceutical-grade peptide sourcing to offset euro-denominated input volatility threatening margin stability. MFDS microbiome classification tightening presents regulatory leverage for domestic players with established quality infrastructure.
For New Entrants and Emerging Players: Launch via specialized online channels targeting young adult consumers in Busan researching ingredient transparency before purchase. White-space opportunities concentrate in post-procedure recovery formulations for laser and injectable aesthetic adjacencies, and in the Gwangju-Jeonnam manufacturing belt where GMP capacity expansion offers land and labor cost arbitrage. Go-to-market positioning should emphasize published clinical data over brand heritage.
For Investors and Strategic Acquirers: MFDS publication of novel probiotic ingredient safety dossiers is the leading indicator that microbiome skincare lines are approaching regulatory clarity and scalable deployment. The analysis frames long-term viability around 5-10 year windows for manufacturers with captive nanotechnology delivery capacity and clinic-channel distribution control. Acquisition targets should display contract manufacturing specialization with outcome-verified platform technology. Watch for COSMAX Group capacity expansion signals as inflection markers.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Published peer-reviewed data secures clinic-channel procurement preference over brand heritage. |
| Backward Integration into Peptide Sourcing | In-house production of pharmaceutical-grade inputs insulates margin from euro volatility. |
| GMP Facility Expansion in Southwestern Belt | Gwangju-Jeonnam land cost arbitrage reduces manufacturing overhead for export-oriented lines. |
| Post-Procedure Recovery Line Launch | Laser aesthetic growth creates adjacent demand for barrier-repair formulations through clinic networks. |
| ISO 22716 Export Certification Convergence | Harmonized GMP standards reduce dual-certification overhead for EU market access. |
Research Methodology
MFDS regulatory filings, EU REACH compliance databases, and Korean customs trade records formed the secondary backbone for supply chain and regulatory mapping. Primary interviews with dermatology clinic procurement managers, formulation R&D directors at domestic manufacturers, contract manufacturing executives, and beauty clinic chain operators validated secondary findings. The analysis combined bottom-up patient procedure volume modeling with top-down manufacturer capacity assessments to triangulate market sizing across the projection horizon.
Historical trendline analysis of anti-aging and UV protection category growth informed CAGR derivation across product type, formulation technology, and application segments. The analytical framework modeled segmentation dimensions including serum versus sunscreen format, nanotechnology versus peptide complex delivery, and clinic versus online channel access throughout the forecast period. Forecast inputs incorporated MFDS safety dossier timeline compression effects and young adult consumer research behavior shifts documented in Seoul-Busan corridor fieldwork.
Euro-denominated raw material volatility, MFDS microbiome classification delays, and biologic stability logistics failures are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around regulatory clarity timelines and clinic-channel consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation of capacity expansion and formulation investment commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Beeswax for Cosmetics Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Aftershave Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market
Beauty & Personal Care
India Herbal Shampoo Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Artificial Nails Market
Beauty & Personal Care
Personal Care Ingredients Market
Beauty & Personal Care
UV Nail Gel Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Facial Massager Market