
 US Natural Personal Care Market | 2026-2036
US Natural Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
US Natural Personal Care Market Intelligence
Stricter retailer mandates for 'clean' ingredient lists, such as those implemented by major beauty retailers in the US, is hardening the criteria for market entry. Burt's Bees leverages its established brand identity built on natural sourcing and transparency to appeal to a broad consumer base. The Hain Celestial Group competes with a diverse portfolio of natural brands across multiple personal care categories. Estée Lauder Companies Inc. positions its Aveda brand to capture the premium, salon-channel segment through plant-based formulations.
US natural personal care encompasses cosmetic and hygiene products formulated without specific synthetic chemicals like parabens, phthalates, and sulfates. These products prioritize plant-derived, mineral-based, or naturally sourced active ingredients to provide alternatives to conventional formulations. Skin care products command the largest market share, driven by demand from eco-conscious consumers for anti-aging and sensitive-skin solutions. Within ingredient types, formulations based on botanical extracts are gaining traction over those relying solely on essential oils due to perceived efficacy.
The US Food and Drug Administration (FDA) governs product safety and labeling under the new MoCRA framework, increasing scrutiny on ingredient claims and facility registration. Concurrently, the Federal Trade Commission (FTC) monitors for deceptive advertising related to 'natural' or 'organic' marketing claims to protect consumers. Navigating the evolving definitions of 'natural' and substantiating marketing claims will be critical for brand differentiation and regulatory compliance.
Market Dynamics
The market's central tension is the collision between consumer demand for 'natural' purity and the FDA's new, stricter MoCRA framework, which forces a more rigorous, science-based definition of safety and ingredient transparency.
Growth Catalysts
- Regulatory Clarity:The FDA's MoCRA framework accelerates transparency by mandating ingredient list standardization and facility registration, building consumer trust in certified products.
- Demographic Demand:Growth among dermatologically sensitive users, particularly in wellness-focused states like California, drives demand for hypoallergenic and non-irritating formulations.
- Ingredient Innovation:The shift towards botanical extracts over essential oils, driven by perceived higher efficacy in anti-aging and sensitive skin applications, expands product development possibilities.
Market Restraints
- Ingredient Cost Volatility:Prices for certified organic or wild-harvested botanical extracts are subject to climate and harvest variability, creating unpredictable input costs for manufacturers.
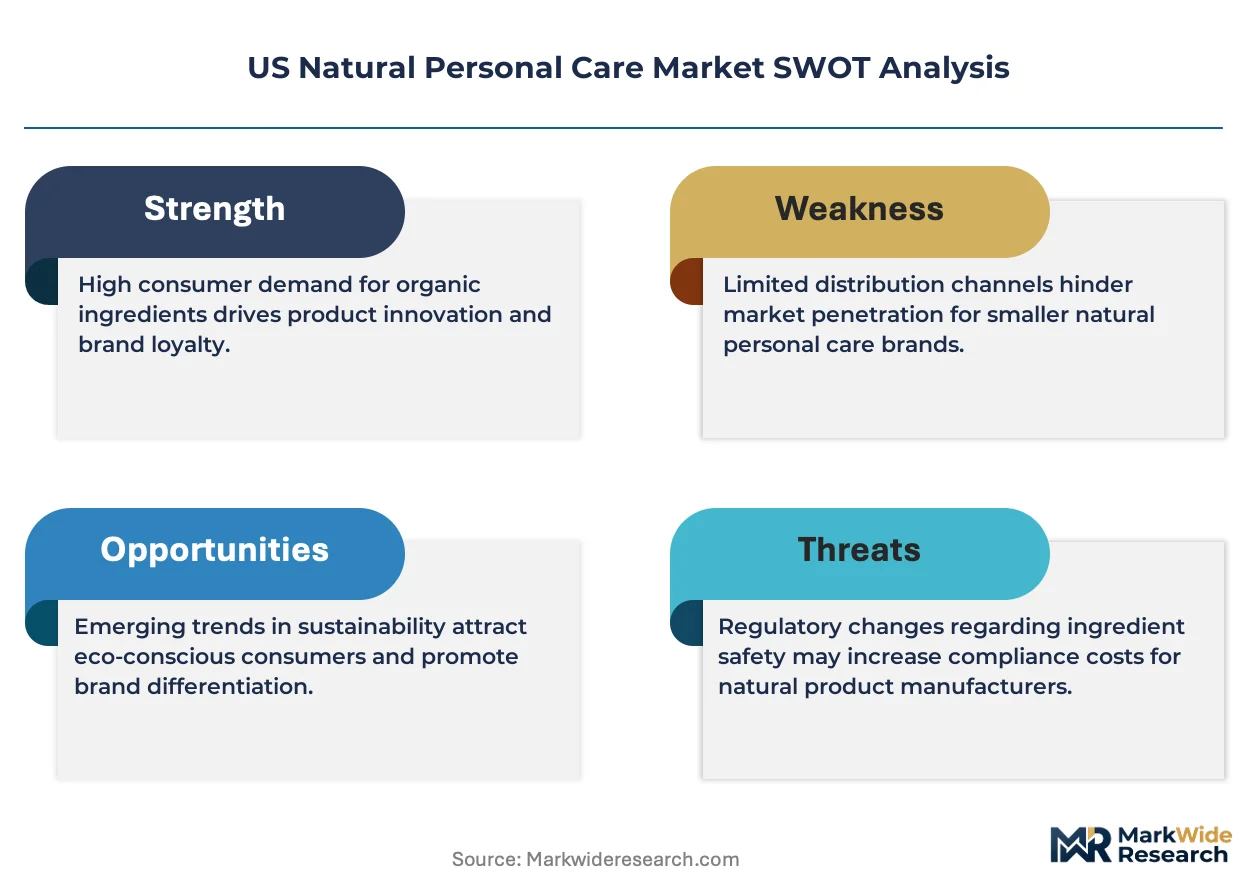
- Ambiguous Terminology:The lack of a federally regulated definition for 'natural' creates consumer confusion and exposes brands to FTC action for misleading marketing claims.
- Formulation Complexity:Creating stable, effective products without synthetic preservatives and emulsifiers requires significant R&D investment, posing a barrier for smaller brands.
Strategic Opportunities
- Geographic Expansion:Brands can target rising consumer wellness consciousness in markets beyond the coasts, such as in Colorado and Texas metropolitan areas.
- Personalized Formulations:Developing direct-to-consumer services that offer customized skincare products based on user-submitted data on skin type and environmental factors presents a growth avenue.
- Sustainable Packaging Models:Introducing refillable packaging and subscription-based replenishment programs appeals to eco-conscious consumers and builds long-term customer loyalty.
Industry Challenges
- MoCRA Compliance Burden:Small-to-mid-sized brands face significant operational challenges in implementing the facility registration and adverse event reporting systems required by the FDA.
- Claim Substantiation:Brands must navigate the high cost of clinical testing to scientifically prove efficacy claims, such as 'anti-aging', to satisfy FTC scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Natural Personal Care Market |
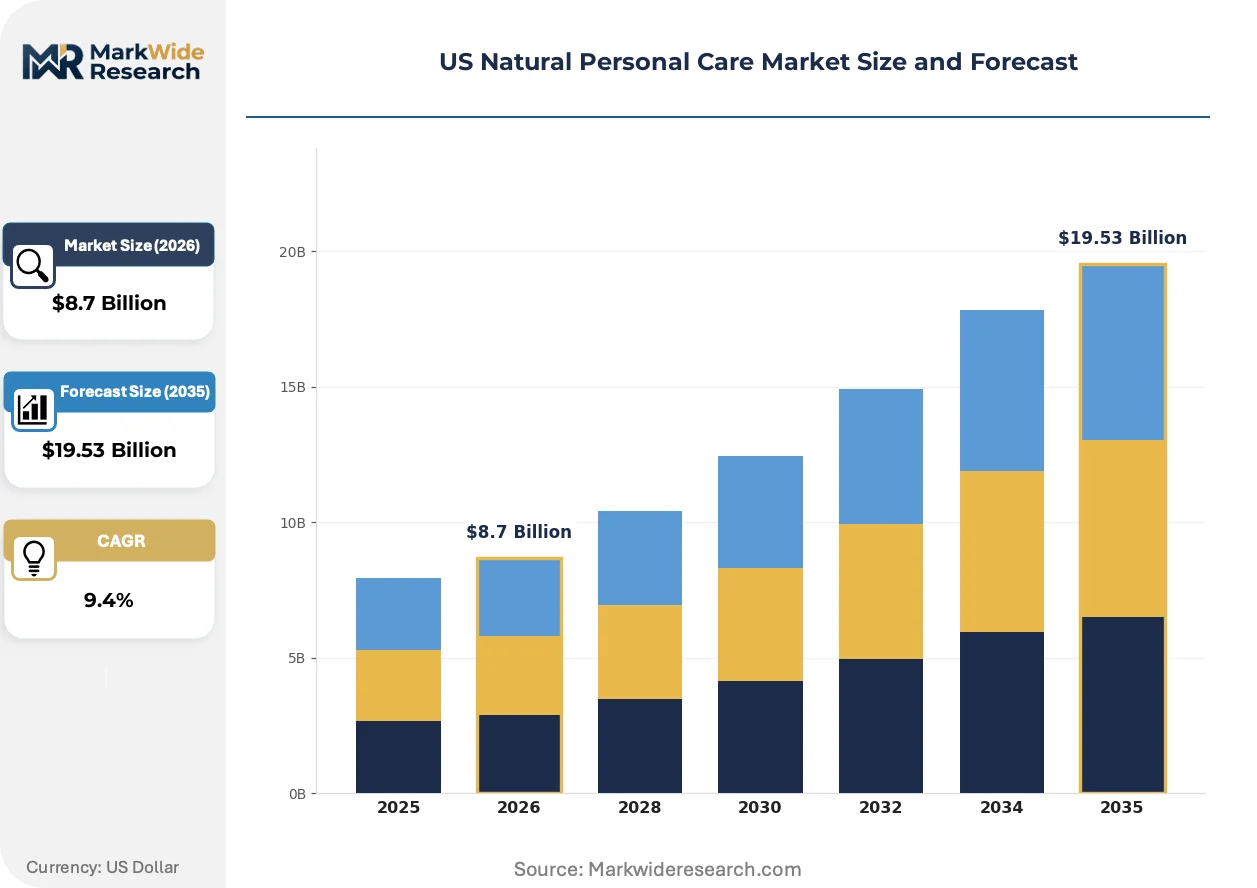
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Oral Care, Body Care Ingredient Type: Botanical Extracts, Essential Oils, Minerals, Natural Preservatives Consumer Type: Eco-Conscious Consumers, Dermatologically Sensitive Users, Luxury Shoppers, Budget Buyers Distribution Channel: Online Retail, Specialty Stores, Drugstores, Supermarkets |
| Companies Covered | L'Oréal S.A., Estée Lauder Companies Inc., Aveda Corporation, Burt's Bees, The Hain Celestial Group, Amway Corporation, Unilever PLC, Beiersdorf AG, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Natural Personal Care Market Strategic Shifts & Innovations
The convergence of data-driven personalization and ingredient-level transparency is redefining consumer expectations. This shift pressures brands to move beyond vague 'natural' marketing toward scientifically substantiated, highly targeted product formulations.
Upcycled ingredients, which repurpose byproducts from the food and agriculture industries, are gaining prominence as active components. Environmentally focused brands and consumers are rapidly adopting these materials. The underlying sustainability narrative is absorbing the traditional 'natural' sourcing story, shifting value from origin to the entire product lifecycle.
Implementation of the FDA's Modernization of Cosmetics Regulation Act (MoCRA) imposes new federal requirements on the industry. This law mandates safety substantiation, facility registration with the FDA, and formal adverse event reporting. The regulation disproportionately affects smaller brands, which now face increased compliance costs and administrative hurdles to remain on the market.
A significant behavioral shift is occurring as consumers move from broad 'clean' product categories to scrutinizing individual ingredients. This trend disrupts brand loyalty, with purchasing decisions now often guided by social media-driven ingredient hypes rather than allegiance to a specific product line. This pattern is most visible within the skincare category among younger consumers in major US cities.
US Natural Personal Care Market Segmentation
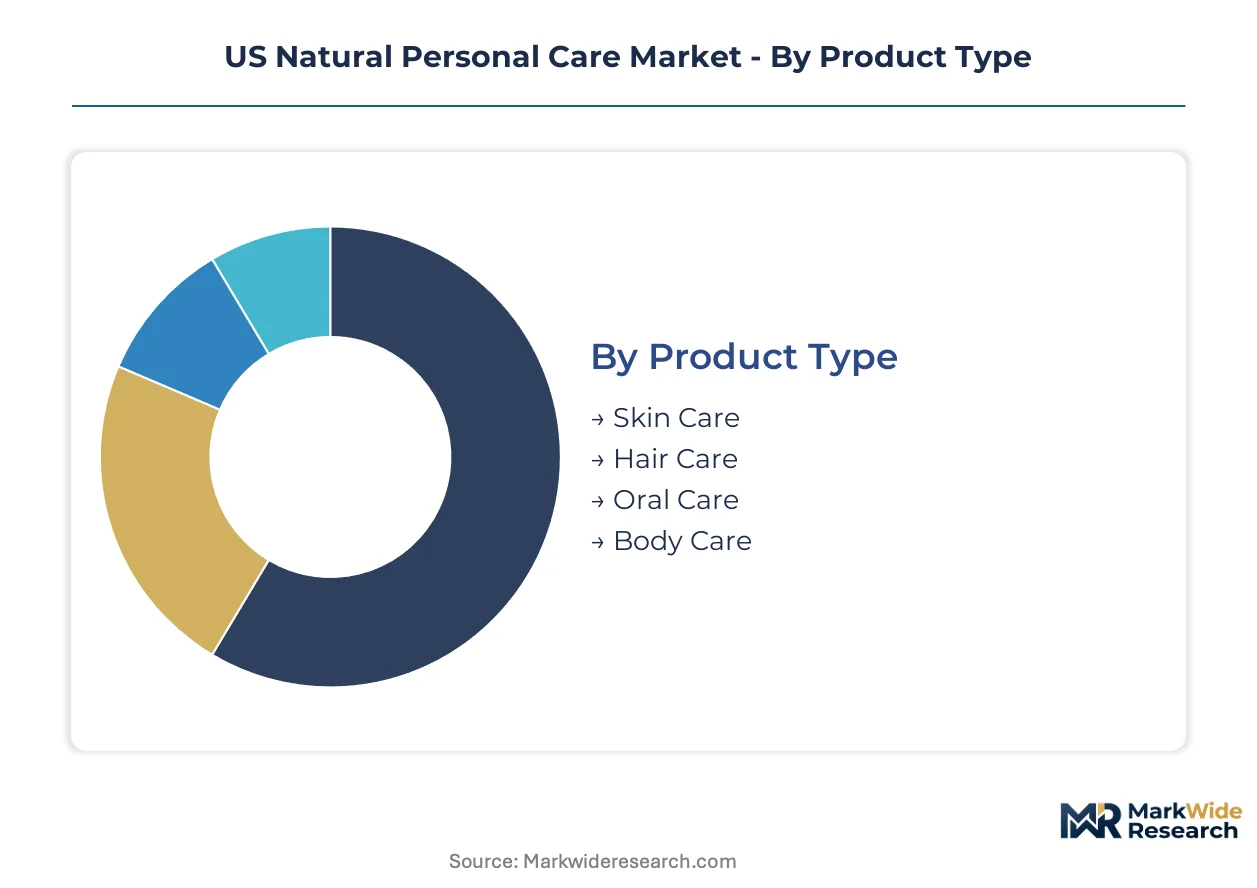
Understanding the intricate layers of the US natural personal care market requires a granular examination of its constituent segments. This segmentation analysis dissects the market along critical dimensions, revealing distinct consumer preferences, ingredient trends, and distribution dynamics that influence brand strategies and market growth across the United States.
Product Type:
The supply concentration within product types directly influences manufacturing scale and specialized R&D investments for natural formulations.
- Skin Care:This category commands the largest market share, encompassing natural cleansers, moisturizers, serums, and sunscreens. Demand from dermatologically sensitive users in states like California drives innovation for hypoallergenic and non-irritating solutions.
- Hair Care:Products such as natural shampoos, conditioners, and styling agents cater to consumers seeking plant-based alternatives to conventional hair treatments. Eco-conscious consumers in urban centers across the US prioritize formulations free from sulfates and parabens.
- Oral Care:This segment includes natural toothpastes, mouthwashes, and dental floss, often featuring ingredients like activated charcoal or essential oils. Consumers prioritize products that avoid artificial sweeteners and dyes.
- Body Care:Natural body lotions, washes, deodorants, and hand creams form this category. Consumers seek gentle, moisturizing formulations with naturally derived scents.
Today's leader: Skin Care. Tomorrow's challenger: Hair Care.
Ingredient Type:
Consumer preferences for specific ingredient types drive product development and sourcing strategies within the natural personal care sector.
- Botanical Extracts:These ingredients, derived from plants, herbs, and flowers, are increasingly favored for their perceived efficacy in anti-aging and sensitive skin applications. Their complex compositions offer diverse benefits, appealing to consumers in wellness-focused regions such as Oregon.
- Essential Oils:Concentrated aromatic compounds extracted from plants, essential oils provide fragrance and some therapeutic properties in natural personal care products. They remain popular for their sensory appeal and traditional uses, particularly in aromatherapy-inspired formulations.
- Minerals:Mineral-based ingredients like zinc oxide and titanium dioxide are primarily used in natural sunscreens and cosmetics for their protective qualities. Consumers value their natural origin and effectiveness as physical blockers.
- Natural Preservatives:Derived from sources like fruit extracts or fermentation, these ingredients extend product shelf life without synthetic chemicals. Manufacturers face formulation complexity to ensure stability and safety.
The segment expanding most quickly is Botanical Extracts, while Essential Oils maintain a significant market presence.
Consumer Type:
Tailoring products to specific consumer types allows brands to capture niche markets and build loyalty through targeted solutions.
- Dermatologically Sensitive Users:This group actively seeks hypoallergenic and non-irritating formulations, often driven by skin conditions or allergies. The growth of this consumer base, particularly in states like California, fuels demand for rigorously tested natural products.
- Eco-Conscious Consumers:These individuals prioritize products with sustainable sourcing, ethical manufacturing practices, and environmentally friendly packaging. Their purchasing decisions are influenced by a product's entire lifecycle, not just its ingredients.
- Luxury Shoppers:This segment seeks premium natural personal care products, often characterized by exotic ingredients, sophisticated packaging, and high-end brand positioning. They value efficacy alongside a luxurious experience.
- Budget Buyers:These consumers look for affordable natural personal care options that provide basic efficacy without a premium price tag. Price sensitivity dictates their purchasing choices.
Dermatologically Sensitive Users represent a significant growth segment, while Eco-Conscious Consumers continue to drive innovation in sustainable practices.
Distribution Channel:
The channel through which products reach consumers significantly impacts market access, brand visibility, and pricing strategies.
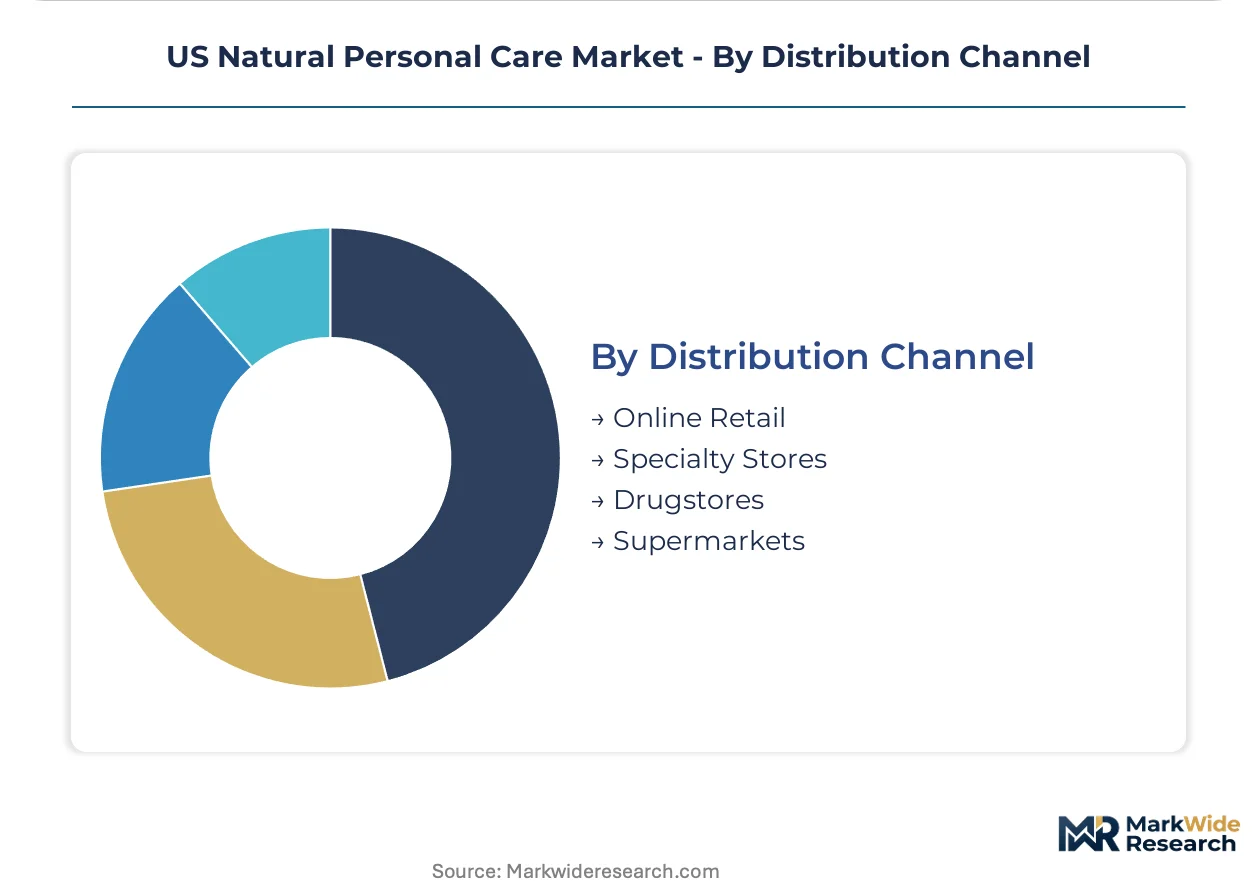
- Online Retail:E-commerce platforms provide extensive reach and convenience, allowing smaller natural brands to compete with established players. This channel experiences rapid growth due to digital marketing and direct-to-consumer models across the US.
- Specialty Stores:Retailers focusing exclusively on natural, organic, or clean beauty products offer curated selections and expert advice. These stores cater to consumers seeking specialized knowledge and a premium shopping experience.
- Drugstores:National drugstore chains provide accessible points of purchase for a broad range of personal care items, including an expanding selection of natural products. Convenience and brand familiarity drive sales in this channel.
- Supermarkets:Grocery stores offer natural personal care products alongside food items, appealing to consumers seeking one-stop shopping. This channel targets a mass market with everyday natural essentials.
Online Retail exhibits a steep expansion trajectory, while Specialty Stores maintain importance for brand discovery and premium offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US natural personal care market scaled significantly with early wellness movements. Consumer preferences for plant-derived formulations emerged from these foundational movements. This historical context shaped regional market development across the United States.
California
California exhibits strong demand from dermatologically sensitive users for hypoallergenic formulations. The state's strict environmental policies, including Prop 65, influence ingredient transparency for local brands. Los Angeles and San Francisco Bay Area brands drive innovation in sustainable packaging and ingredient sourcing.
Oregon
Oregon's wellness-focused consumers prioritize botanical extracts for perceived efficacy in skincare. State-level initiatives supporting organic farming practices foster local ingredient supply chains. Portland serves as a hub for small-batch natural brands emphasizing ethically sourced ingredients.
Texas
Texas metropolitan areas show rising consumer wellness consciousness, driving demand for natural hygiene products. Brands operating in Texas must comply with FDA's MoCRA framework for facility registration and safety substantiation. Austin and Dallas are growing centers for natural personal care startups targeting a broader Southern consumer base.
New York Metro
New York Metro consumers, particularly younger demographics, intensely scrutinize individual ingredients in personal care products. The FTC actively monitors marketing claims for 'natural' products sold within this high-visibility market. New York City remains a critical market for luxury natural brands and trend-setting ingredient innovations.
Southeast (Florida/Georgia)
The Southeast, particularly Florida and Georgia, sees demand for natural sunscreens and body care. Brands must navigate the FDA's MoCRA requirements for product safety and adverse event reporting. Miami and Atlanta serve as distribution hubs for natural products reaching diverse consumer groups.
US Natural Personal Care Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the US natural personal care market. This environment fosters a tiered structure, from large multinational corporations to specialized boutique brands. Strategic archetypes include diversified consumer goods giants, premium beauty specialists, and niche natural product innovators. Portfolio diversification across product categories and strategic partnerships remain dominant competitive moves for market share.
Among established brand portfolios, L'Oréal S.A. and Estée Lauder Companies Inc. exemplify multinational strategies. These corporations often integrate natural product lines into broader beauty offerings, leveraging extensive R&D capabilities. The Hain Celestial Group, by contrast, represents a specialist conglomerate focused on natural and organic consumer products. This group occupies a position that emphasizes brand acquisition and curated portfolio development across multiple categories. Such players underscore the market's blend of broad consumer reach and targeted natural appeal.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Estée Lauder Companies Inc. |
| Aveda Corporation |
| Burt's Bees |
| The Hain Celestial Group |
| Amway Corporation |
| Unilever PLC |
| Beiersdorf AG |
| Johnson & Johnson |
Cost & Logistics Intelligence
The divergence between certified 'clean' formulations and conventional 'natural' claims impacts both pricing power and the sourcing of botanical ingredients. This bifurcation creates distinct supply chains for premium and mass-market products.
Pricing Analysis
Value-based pricing often characterizes the US natural personal care market. Brand premium and FDA MoCRA compliance drive significant price differentiation. Pricing softness reflects intense competition from conventional brands and private labels. Budget buyers exhibit high price sensitivity, while luxury shoppers prioritize efficacy over cost.
Supply Chain Analysis
Reverse logistics for refillable packaging models are emerging, driven by eco-conscious consumer demand for sustainable practices. Botanical extracts and essential oils draw from global sources, with significant inputs from South America and Asia. Manufacturers rely on plant-derived active ingredients and natural preservatives. Ingredient cost volatility due to climate and harvest variability poses a structural risk. Distribution runs through online retail and specialty stores for premium products, with supermarkets for mass-market offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US natural personal care market operates as a regulatory compounder, with the FDA's MoCRA framework driving significant demand for transparent and safe formulations. This regulation elevates consumer trust and market standards.
For Market Incumbents: Acquire specialized R&D capabilities in botanical extract formulation to counter emerging niche brands. Invest in advanced testing infrastructure to substantiate efficacy claims, mitigating FTC scrutiny over 'natural' marketing. Deepen vertical integration into sustainable ingredient sourcing to stabilize input costs against climate variability. This defends market share against asset-light designers.
For New Entrants and Emerging Players: Launch via direct-to-consumer platforms, offering personalized formulations based on user skin data to capture dermatologically sensitive users. Target wellness-focused metropolitan areas like Austin and Portland, leveraging social media for ingredient-level transparency. Focus on upcycled ingredients to build a compelling sustainability narrative, appealing to eco-conscious consumers. This creates differentiation from established portfolios.
For Investors and Strategic Acquirers: Consolidation pressure builds where MoCRA compliance burdens smaller brands lacking R&D and regulatory resources. Investors should target mid-sized brands with established supply chains for botanical extracts and strong consumer loyalty in key states like California. Focus on companies demonstrating clear scientific substantiation for 'clean' claims. Practitioners should monitor FDA enforcement actions for early signals of market shake-out.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Repositioning | Shifting focus from 'natural' to 'entire product lifecycle' for eco-conscious consumers. |
| Direct-to-Consumer Launch | Bypassing traditional retail to offer personalized skincare solutions to specific user types. |
| Premium Tier Introduction | Capturing luxury shoppers with exotic ingredients and sophisticated packaging. |
| Certification Investment | Ensuring compliance with FDA MoCRA and reinforcing 'clean' ingredient claims. |
| Ingredient Innovation | Developing new formulations based on upcycled ingredients for product differentiation. |
Research Approach
Bottom-up skincare product modeling reconciled against top-down botanical extract supply tracking forms the analytical core. Primary interviews with brand managers, regulatory affairs leads, retail category buyers, and R&D directors informed market dynamics and validated secondary data from FDA filings, FTC guidelines, and trade reports. This approach triangulates market sizing and growth projections.
Historical trendline analysis underpins market projections across the analysis window. Segmentation dimensions modeled include product type, ingredient type, consumer type, and regional adoption patterns. Compound annual growth rates were derived through regression analysis. Key forecast inputs include consumer wellness consciousness shifts and MoCRA compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under consumer perception or regulatory shifts. Forecasts reflect assumptions regarding ingredient cost stability and MoCRA implementation. Practitioners should monitor FTC rulings on 'natural' claims and botanical sourcing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
Colombia Hair Care Market
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
China Eyelash Serum Market
Beauty & Personal Care
North America Beauty Devices Market
Beauty & Personal Care
UV Nail Gel Lamp Market
Beauty & Personal Care
Organic Baby Shampoo Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Luxury Bath and Body Products Market