
 Refillable Deodorants Market | 2026-2036
Refillable Deodorants Market Size, Share, and Industry Trends Forecast 2026-2036
Refillable Deodorants Market Analytics
Subscription-based direct-to-consumer financing is narrowing the capital gap between indie brands and incumbent conglomerates in refillable deodorants. Wild leverages aluminum-free formulations and durable case designs to anchor its European market presence. by Humankind competes through plastic-negative supply chains and modular refill pods. Unilever sustains scale advantages via its existing retail distribution networks and in-house production of biodegradable base materials.
Refillable deodorants are personal hygiene products designed for repeated replenishment of active fragrance and antimicrobial compounds into reusable primary containers, typically employing stick formats with twist-base mechanisms or spray systems with replaceable liquid cartridges. The stick segment dominates unit economics due to simpler mechanical interfaces and lower shipping weights, while gel formats capture premium positioning through transparent visual aesthetics and faster dry-down properties. Natural material formulations lead volume as sodium bicarbonate and arrowroot powder replace aluminum salts, though synthetic fragrance blends retain margin pools through proprietary encapsulation technologies. Online distribution channels command the fastest growth trajectory, fueled by subscription lock-in and lower customer acquisition costs relative to shelf-space competition in supermarkets.
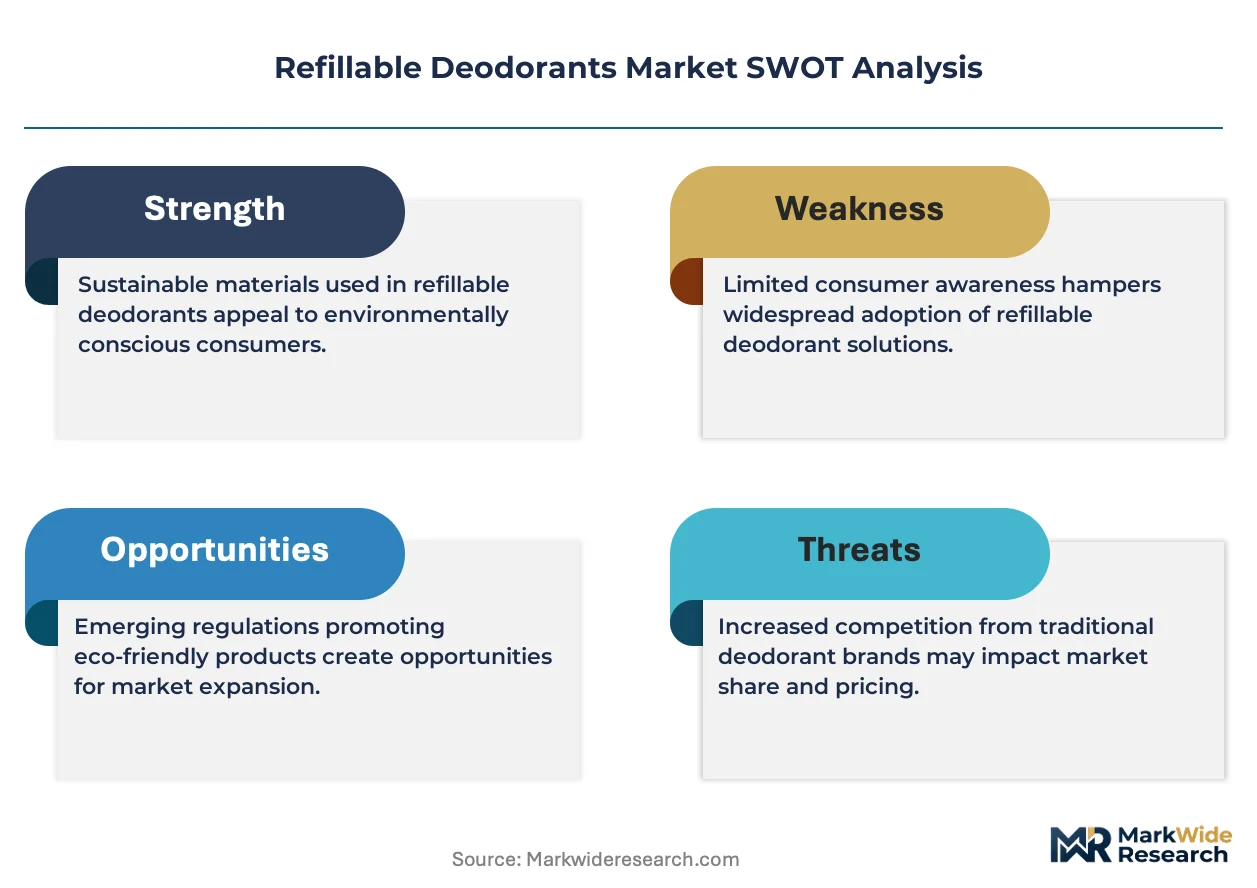
The EU Green Deal and REACH frameworks mandate recyclability thresholds and restrict paraben preservatives, compelling reformulation investments across manufacturers. The US EPA and FDA jointly influence antimicrobial claim substantiation and aerosol propellant specifications, creating compliance complexity for cross-border operators. California's Safer Consumer Products regulations extend these requirements at the state level, adding another layer of testing protocols. Stakeholders must monitor evolving extended producer responsibility schemes and bioplastics certification standards to secure first-mover positioning in emerging refill infrastructure partnerships.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing rapid container redesign and supply chain reconfiguration across refillable deodorant manufacturers, compressing legacy single-use plastic formats while elevating durable aluminum and biopolymer alternatives.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility schemes in Germany, France, and the United Kingdom compel brands to deploy refill infrastructure, accelerating retail partnerships and consumer habit formation.
- Aluminum salt substitution chemistry:Sodium bicarbonate and arrowroot powder formulations satisfy antimicrobial efficacy requirements while eliminating health concerns that previously constrained natural deodorant adoption.
- Subscription lock-in mechanics:Direct-to-consumer channels reduce customer acquisition costs relative to supermarket shelf-space competition, enabling indie brands to scale without incumbent distribution advantages.
Market Restraints
- Biodegradable base material cost volatility:Corn-derived and coconut oil feedstocks fluctuate with agricultural commodity cycles, squeezing margin pools for natural formulation specialists.
- Mechanical interface standardization gaps:Proprietary twist-base designs across stick formats prevent cross-brand refill compatibility, fragmenting consumer choice and raising switching costs.
- REACH paraben restriction compliance timelines:Reformulation investments to replace restricted preservatives extend product development cycles by 12-18 months for mid-tier manufacturers.
Strategic Opportunities
- Underpenetrated Southern European markets:Spain and Italy lack mature refill infrastructure, creating first-mover positioning for brands establishing retail partnerships before incumbent saturation.
- Modular spray cartridge convergence:Liquid refill systems for gel formats enable premium positioning through transparent visual aesthetics and faster dry-down properties.
- Bioplastics certification acceleration:TÜV Austria and DIN CERTCO standards for home-compostable pods unlock municipal waste partnership opportunities and consumer trust premiums.
Industry Challenges
- Antimicrobial claim substantiation expertise:FDA and EPA joint oversight of efficacy testing requires specialized regulatory affairs talent scarce among emerging indie brands.
- Legacy aerosol propellant reconfiguration:Transitioning spray formats from hydrocarbon to compressed air systems demands capital-intensive production line overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refillable Deodorants Market |
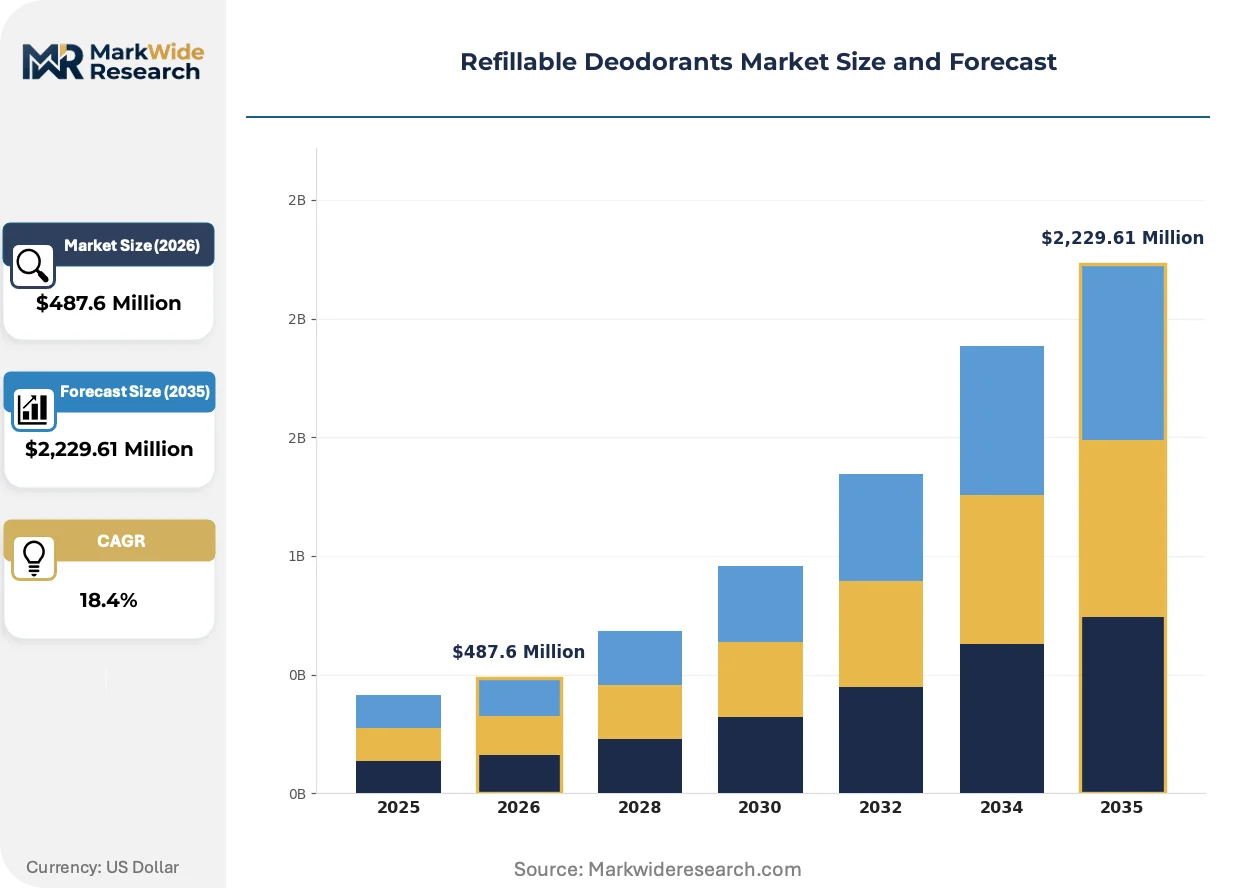
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Stick, Gel, Cream Material: Natural, Organic, Synthetic, Biodegradable Distribution Channel: Online, Supermarkets, Health Stores, Specialty Shops Customer Type: Men, Women, Unisex, Eco-Conscious Consumers |
| Companies Covered | by Humankind, Native, Unilever, Schmidt's Naturals, Wild, Procter & Gamble, Myro, The Lekker Company, Grove Collaborative, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refillable Deodorants Market Evolving Landscape
Formulation chemistry, regulatory compliance architectures, and distribution mechanics are converging to redefine competitive advantage in refillable deodorants, with sustainability credentials now table stakes rather than differentiators.
Solid-state emulsion technology is hybridizing stick and gel formats into semi-solid balms that combine the shipping efficiency of twist-base mechanics with the visual transparency and skin-feel of liquid systems. Millennial and Gen Z consumers in Germany and France are adopting these hybrid formats at twice the rate of traditional sticks. This convergence is compressing the premium-mass boundary, forcing brands to compete on ingredient provenance rather than format exclusivity.
REACH framework updates are expanding restricted substance lists to include additional synthetic musks and phthalate-based fragrance carriers, compelling European manufacturers to source proprietary encapsulation technologies from specialty chemical suppliers. The reformulation burden falls heaviest on mid-sized brands lacking in-house perfumery capabilities. French and UK regulators are accelerating enforcement timelines, compressing compliance windows from 24 to 12 months for notified substances.
Subscription bundling is displacing single-product purchases as the dominant direct-to-consumer acquisition model, with consumers expecting deodorant refills packaged alongside oral care and hair care consumables. Indie brands are unbundling these expectations by offering flexible skip-a-month mechanics that incumbent conglomerates struggle to replicate within rigid ERP systems. This behavioral shift is most visible in London and Berlin, where urban density supports same-day refill delivery partnerships with bicycle courier networks.
Refillable Deodorants Market Segmentation
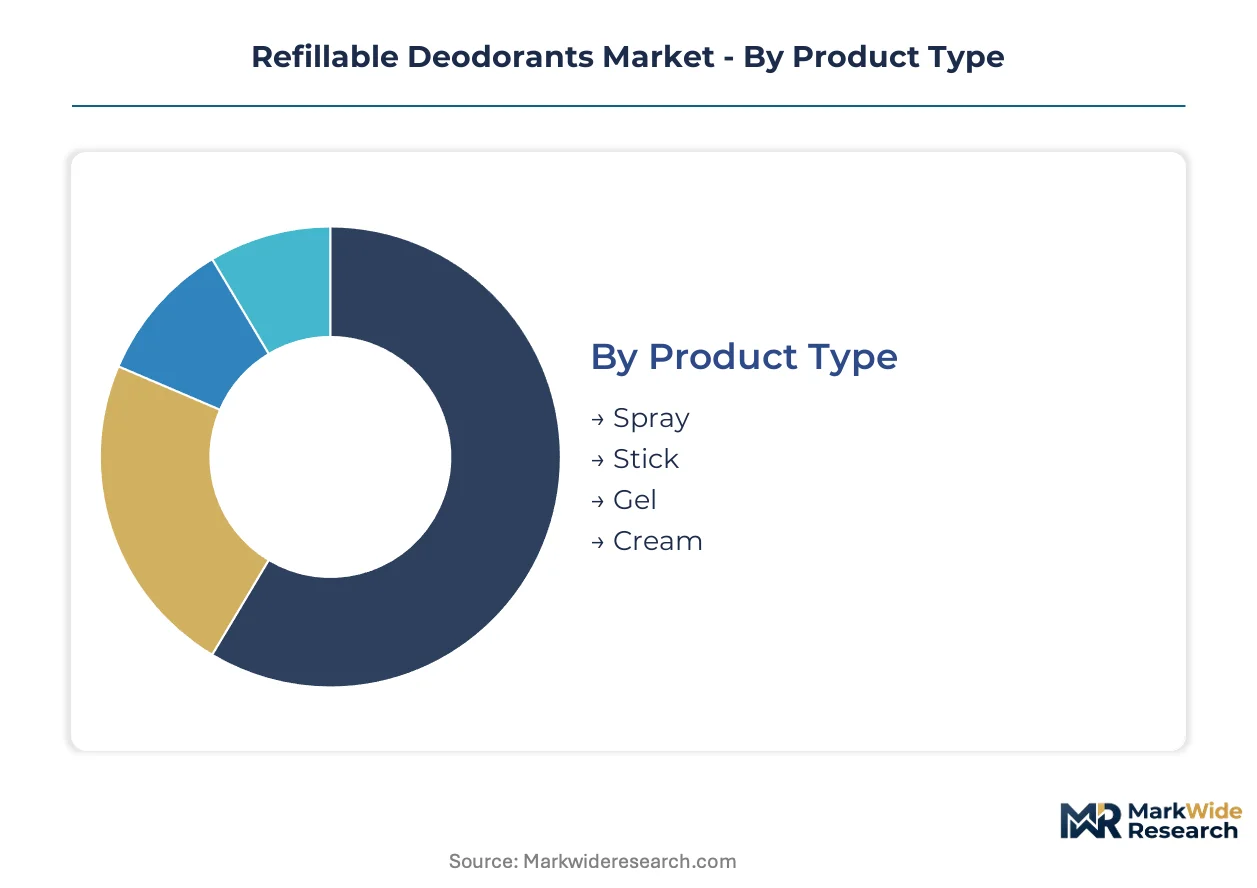
Refillable deodorant manufacturers compete across four distinct category axes where product format, material composition, channel access, and consumer identity intersect. Each segmentation layer carries different margin profiles and regulatory exposure, forcing portfolio decisions that trade volume scale against sustainability premiums.
Product Type:
Cycle times vary sharply across formats: stick refills turn over fastest due to mechanical simplicity and lower shipping weights, while spray systems require longer replacement intervals and more complex cartridge logistics.
- Stick:Twist-base mechanisms with solid emulsion cores dominate unit economics through reduced packaging mass and simplified logistics. German and UK consumers favor this format for travel compatibility and shelf stability. Sodium bicarbonate formulations in stick formats are displacing aluminum salts fastest among Millennial demographics.
- Spray:Compressed air propellant systems with replaceable liquid cartridges command premium positioning in France and urban UK clusters. The transition from hydrocarbon propellants under REACH F-Gas regulations is extending development timelines for incumbent aerosol specialists.
- Gel:Transparent semi-solid balms hybridize visual aesthetics with faster dry-down properties. London and Berlin adoption rates are twice those of traditional sticks.
- Cream:Jar-based scoop formats with finger application serve niche sensitivity-focused segments. French pharmacy channels stock these formulations for post-shaving skin compatibility.
Stick dominates installed base. Spray is where expansion concentrates.
Material:
Cost tiers separate feedstock-dependent naturals from engineered synthetics, with bioplastics certification emerging as the new margin battleground.
- Natural:Sodium bicarbonate, arrowroot powder, and coconut oil bases satisfy EU Green Deal recyclability thresholds. Corn-derived feedstock volatility squeezes margin pools for mid-tier specialists.
- Biodegradable:Home-compostable pod designs certified to TÜV Austria and DIN CERTCO standards unlock municipal waste partnerships. This segment is climbing the fastest as extended producer responsibility schemes mature in Germany and France.
- Organic:USDA and Soil Association certification requirements add 15-20% formulation cost premiums. UK health store channels prioritize these SKUs for customer trust transfer.
- Synthetic:Proprietary fragrance encapsulation technologies and aluminum salt complexes retain margin pools through performance differentiation. REACH synthetic musk restrictions are compressing this segment's formulation flexibility.
Natural materials anchor volume share. Biodegradable certification is where margin expansion concentrates.
Distribution Channel:
Customer acquisition economics favor subscription lock-in against shelf-space competition, with channel choice determining brand scale trajectory.
- Online:Direct-to-consumer subscriptions with skip-a-month mechanics reduce customer acquisition costs versus retail. Indie brands exploit ERP rigidity at incumbent conglomerates to win urban density markets.
- Supermarkets:Incumbents leverage existing retail distribution networks and in-house production of biodegradable base materials. Shelf-space fees in UK and German chains disadvantage emerging players.
- Health Stores:Pharmacy and wellness retail in France and UK stock organic and sensitivity-focused formulations. Staff recommendation dynamics drive trial conversion.
- Specialty Shops:Zero-waste boutiques and refill stations in Berlin and London neighborhoods serve as habit-formation infrastructure. Same-day bicycle courier partnerships are emerging here.
Supermarkets dominate installed base. Online is where share gains concentrate.
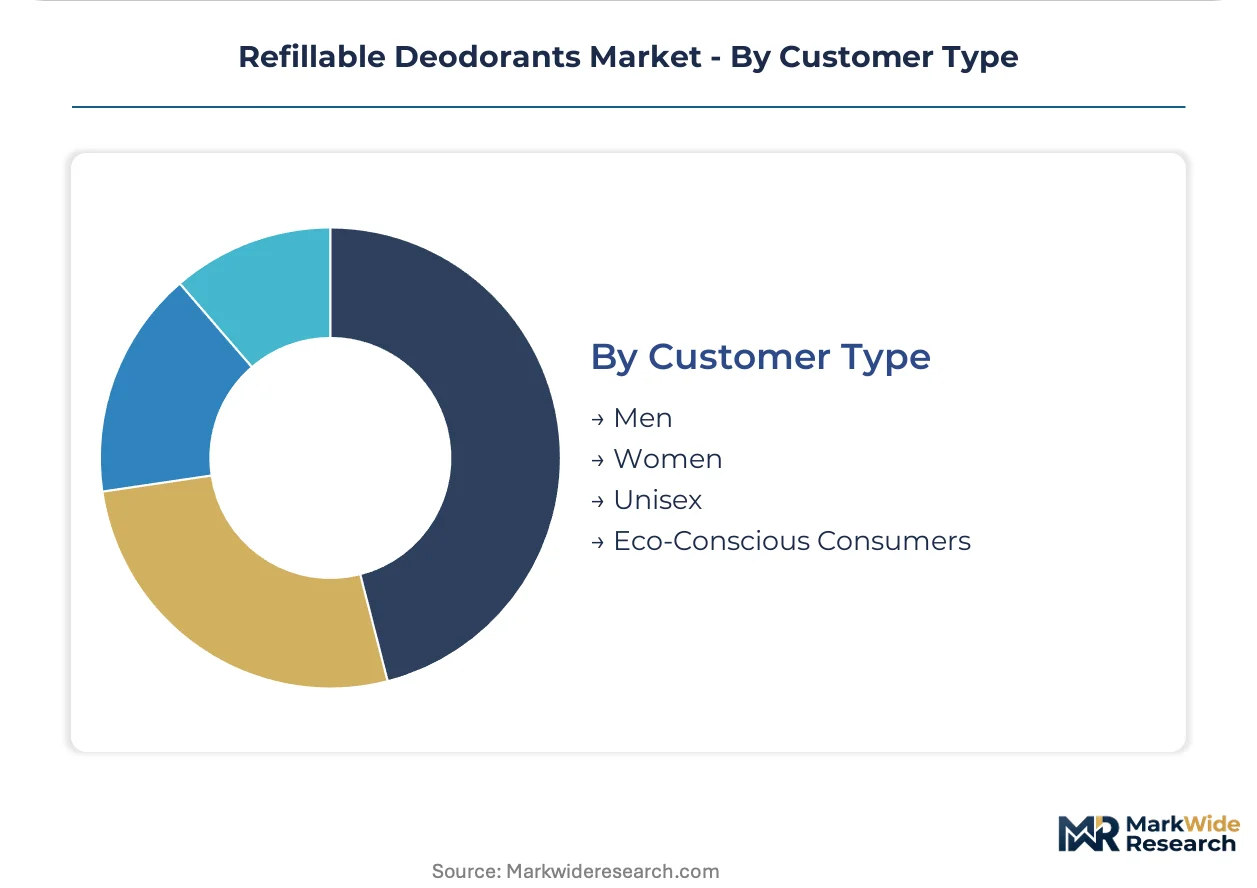
Customer Type:
Identity-based segmentation maps directly to formulation complexity and price elasticity, with eco-conscious designations cutting across gender categories.
- Eco-Conscious Consumers:Subscription bundling expectations span oral care, hair care, and deodorant refills. This segment is expanding most quickly as EU Green Deal awareness penetrates Southern European markets.
- Women:Fragrance-forward formulations with skin-conditioning additives drive repeat purchase in French and UK urban markets. Proprietary encapsulation technologies target this demographic.
- Unisex:Neutral scent profiles and minimalist packaging design appeal to cohabiting households. German consumers show highest adoption of shared-container formats.
- Men:Woody and citrus fragrance families with higher antimicrobial loadings serve gym and active lifestyle positioning. UK sports retail channels stock these variants.
Women dominate installed base. Eco-conscious designations are where portfolio expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in refillable deodorants favor net-importing European markets where regulatory pressure outpaces domestic manufacturing scale. Germany, France, and the United Kingdom absorb the majority of cross-border shipments, while production capacity concentrates in lower-cost manufacturing clusters serving private-label and indie brand demand.
Germany
Subscription penetration rates in Berlin and Hamburg exceed other European capitals, driven by dense urban logistics networks enabling same-day bicycle courier refill delivery. Extended producer responsibility schemes under the EU Green Deal mandate refill infrastructure investments by 2027, compelling supermarket chains to dedicate shelf space to durable case systems. Bavaria hosts several biopolymer research clusters developing home-compostable pod materials certified to DIN CERTCO standards.
France
Pharmacy channel dominance in Paris and Lyon creates distinct distribution economics, with staff recommendation dynamics driving trial conversion for sensitivity-focused cream formulations. ANSM enforcement of REACH paraben restrictions operates on compressed 12-month compliance timelines versus 24 months elsewhere. Île-de-France concentrates fragrance encapsulation technology suppliers serving reformulation demands from mid-tier brands lacking in-house perfumery capabilities.
United Kingdom
London's zero-waste boutique density supports habit-formation infrastructure unmatched elsewhere, with refill stations in Camden and Shoreditch serving as consumer education touchpoints. The Soil Association's organic certification requirements add 15-20% formulation cost premiums that health store channels absorb through customer trust transfer. Manchester and Birmingham are emerging as secondary markets where indie brands establish retail partnerships before incumbent saturation.
Italy
Milan and Rome lack mature refill infrastructure, creating first-mover positioning for brands establishing retail partnerships ahead of EU Green Deal packaging waste directive enforcement. Consumer familiarity with solid perfume formats eases adoption curves for stick-based deodorant refills. Northern Italian chemical suppliers are pivoting from traditional aerosol propellants to compressed air systems under REACH F-Gas regulation pressure.
Spain
Barcelona's urban density supports emerging subscription logistics, though penetration lags Northern European benchmarks by 24-36 months. Madrid supermarket chains resist shelf-space reallocation for durable case formats due to lower turnover velocity versus single-use alternatives. Andalusian agriculture provides corn-derived feedstock for biodegradable base materials, though price volatility squeezes margin pools for natural formulation specialists.
Refillable Deodorants Market Competitive Landscape
On the supply side, the industry is bifurcating between incumbent conglomerates with captive retail distribution and indie specialists leveraging direct-to-consumer subscription mechanics. Three strategic archetypes dominate: aluminum-free formulation pioneers, plastic-negative supply chain operators, and biodegradable material integrators. Competitive moves concentrate on retail partnership exclusivity and bioplastics certification acceleration rather than price-based confrontation.
Within the indie specialist tier, Wild and by Humankind exemplify divergent sustainability positioning strategies. Wild anchors European market presence through durable case designs, while by Humankind occupies a position defined by modular refill pod architectures. Unilever sits within the incumbent conglomerate archetype, leveraging existing supermarket networks and in-house production capabilities. The Lekker Company and Myro represent geographic specialization patterns, with name-derived positioning in Dutch and North American markets respectively.
| Leading Market Players |
|---|
| by Humankind |
| Native |
| Unilever |
| Schmidt's Naturals |
| Wild |
| Procter & Gamble |
| Myro |
| The Lekker Company |
| Grove Collaborative |
| Others |
Value Network & Pricing Analysis
Bavarian biopolymer research clusters anchor European supply capacity for home-compostable pod materials, translating feedstock proximity into pricing power for German manufacturers serving refillable deodorant brands. This geographic concentration compresses margins for UK and French operators forced to import certified materials or absorb DIN CERTCO compliance premiums.
Pricing Analysis
Industrial OEM buyers anchor a subscription-dominant pricing structure where direct-to-consumer channels reduce customer acquisition costs versus supermarket shelf-space competition. Three-tier pricing separates certified biodegradable pods from standard natural formulations from economy synthetic variants. Cost compression in the natural tier is intensifying because corn-derived feedstock volatility squeezes mid-tier specialists. Eco-conscious subscription bundlers show lowest price sensitivity while single-unit supermarket purchasers exhibit highest elasticity.
Supply Chain Analysis
Corn and coconut oil feedstocks draw from agricultural suppliers in Andalusia, Bavaria, and Northern French clusters, with arrowroot powder sourcing concentrated in Southeast Asian processing hubs. Sodium bicarbonate supply rests on synthetic chemical production in Germany and Belgium, while fragrance encapsulation technologies hinge on specialty suppliers in Île-de-France. Single-source vulnerability concentrates in TÜV Austria and DIN CERTCO certification bodies where queue delays extend lead times. Distribution runs through direct-to-consumer subscription platforms, supermarket retail networks, and zero-waste boutique partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as EU Green Deal packaging mandates fragment consumer demand across certification tiers, creating niche positioning for specialists who outmaneuver incumbent ERP rigidity with flexible subscription mechanics.
For Market Incumbents: Pre-empt indie brand subscription lock-in by accelerating bioplastics certification investments and deploying skip-a-month mechanics within legacy ERP constraints. Defensive consolidation should prioritize captive supply of biodegradable base materials to offset feedstock volatility. Channel control through exclusive retail partnerships in underpenetrated Southern European markets represents the critical lever against direct-to-consumer erosion.
For New Entrants and Emerging Players: Mid-market spray format adoption in French pharmacy channels represents the most penetrable entry point, with compressed air propellant systems capturing premium positioning as REACH F-Gas regulations displace hydrocarbon incumbents. Southern European refill infrastructure gaps in Milan and Rome offer first-mover retail partnership opportunities before directive enforcement. Go-to-market execution should emphasize modular refill pod architectures with TÜV Austria certification as the trust-transfer mechanism.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with proprietary encapsulation capabilities and established regulatory affairs expertise under FDA-EPA joint oversight. Long-term viability over the next decade rests on backward integration into feedstock supply and certification body relationships. The signal to watch is bioplastics queue compression at DIN CERTCO and TÜV Austria as leading indicators of supply-constrained margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioplastics Certification Acceleration | TÜV Austria and DIN CERTCO standards unlock municipal waste partnerships and consumer trust premiums. |
| Direct-to-Consumer Platform Launch | Subscription bundling with skip-a-month mechanics exploits incumbent ERP rigidity in urban density markets. |
| Backward Integration into Feedstock Supply | Captive corn and coconut oil sourcing insulates margin pools from agricultural commodity cycles. |
| Spray Format Transition Partnership | Compressed air propellant systems capture REACH F-Gas regulatory tailwinds in French pharmacy channels. |
| Southern European Retail Expansion | Pre-emptive partnerships in Milan and Rome establish habit-formation infrastructure before incumbent saturation. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with brand managers, category buyers at UK and German supermarket chains, supply planners at biopolymer manufacturers, and regulatory affairs leads at mid-tier formulation specialists informed demand-side and compliance dynamics. Secondary sources include EU Green Deal directive texts, REACH restriction updates, ECHA substance databases, and customs trade records for corn-derived feedstock flows. Bottom-up unit economics modeling and top-down market sizing triangulate volume estimates.
Calibration against historical adoption curves for natural personal care categories shapes the projection framework across the analysis window. Segmentation dimensions include product format, material certification tier, distribution channel, and customer identity archetype. CAGRs derive from fitted growth curves incorporating subscription penetration rates, refill infrastructure deployment timelines, and regulatory compliance windows. Industry-specific inputs capture sodium bicarbonate substitution velocity and bioplastics certification queue dynamics.
Practitioners should monitor REACH paraben restriction enforcement timelines and bioplastics certification body capacity for early signals of supply-constrained pricing shifts. Forecasts reflect assumptions about EU Green Deal implementation consistency and consumer habit-formation speed in Southern European markets. Cross-checking against Nielsen retail audit data for natural deodorant category velocity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Liquid Soap Market
Beauty & Personal Care
Luxury Personal Care and Cosmetics Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
China Eyelash Serum Market
Beauty & Personal Care
South Korea Dermocosmetics Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Kids Shampoo Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
Hair Removal Epilator Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Male Grooming Products Market
Beauty & Personal Care
North America Bath and Shower Products Market
Beauty & Personal Care
North America Lip Care Products Market