
 Low Voltage Disconnect Switch Market | 2026-2036
Low Voltage Disconnect Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Low Voltage Disconnect Switch Market Outlook
Data center power distribution is pivoting toward higher-density rack configurations, creating fresh pull for low voltage disconnect switches with enhanced breaking capacity. Siemens AG leverages its electromechanical R&D depth to sustain leadership in isolator switch variants for mission-critical infrastructure. ABB Ltd. anchors its position through captive supply of hybrid technology platforms that merge arc-quenching reliability with digital monitoring. Schneider Electric differentiates by controlling distribution channels across European contractor networks, a moat that competitors navigate with difficulty.
A low voltage disconnect switch is a manually or motor-operated mechanical switching device that isolates electrical circuits from their power source, typically rated up to 1000V AC or 1500V DC, with visible contact gap verification as a core safety parameter. Its primary purpose is to ensure safe maintenance access and emergency de-energization across commercial, industrial, and utility installations. Motor protection circuit breaker configurations occupy the deepest margin pools where thermal-magnetic coordination commands premium positioning. Smart technology segments are recording the fastest trajectory as facility managers embed IoT-enabled condition monitoring into retrofit specifications. Electromechanical platforms remain the volume backbone, though electronic trip units are displacing conventional bimetallic strips in precision-sensitive HVAC applications.
The US National Electrical Code through NFPA 70 mandates visible break verification for service disconnects, while IEC 60947-3 governs European switch isolation endurance testing; China's GB 14048.3 standards enforce comparable clearance requirements for domestic installations. These frameworks collectively shape product certification roadmaps and create asymmetric market access costs for uncertified suppliers. Stakeholders must monitor evolving arc flash mitigation mandates and decide whether to internalize smart technology development or source through OEM partnerships.
Market Dynamics
Data center power density requirements are forcing a wholesale reconfiguration of electrical isolation strategies, with rack-level energy densities now exceeding 30 kW per cabinet and demanding switches with enhanced thermal endurance and arc-quenching speed.
Growth Catalysts
- NFPA 70 visible break mandates:The US National Electrical Code now requires verifiable contact separation for service disconnects in commercial installations, accelerating replacement cycles for legacy fused switches across retail and healthcare infrastructure.
- Data center buildouts:Hyperscale facilities in Northern Virginia, Frankfurt, and Singapore are specifying motor-operated disconnects with remote monitoring capabilities for 24/7 operational continuity.
- IEC 60947-3 harmonization:Cross-border standard alignment is reducing certification duplication costs for manufacturers serving both European and Middle Eastern utility markets.
Market Restraints
- Copper and silver contact volatility:Raw material price swings for arc-resistant alloys are compressing gross margins on standard-duty switch variants by 8-12 percentage points during commodity spikes.
- Chinese supply concentration:Over 60% of molded case frames and contact assemblies originate from Zhejiang and Jiangsu provinces, creating geopolitical exposure for European and North American OEMs.
- Electromechanical displacement ceiling:Solid-state circuit breakers with integrated isolation functionality threaten traditional disconnect switch volumes in precision power distribution applications.
Strategic Opportunities
- India grid modernization:The country's Smart Cities Mission and rural electrification push are creating first-time demand for IEC-compliant disconnect switches in substation automation projects.
- EU Green Deal retrofit incentives:Building energy efficiency directives are subsidizing smart switchgear upgrades in commercial real estate across Germany, France, and the Netherlands.
- Digital-twin convergence:Integration of disconnect switch telemetry with building management systems and predictive maintenance platforms opens recurring software revenue streams for hardware manufacturers.
Industry Challenges
- Arc flash engineering expertise gap:Qualified technicians for incident energy calculations and switch coordination studies are scarce in secondary US markets and Eastern European industrial zones.
- Multi-standard certification timelines:Simultaneous UL 98, IEC 60947-3, and GB 14048.3 testing protocols extend product launch cycles by 14-18 months for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Voltage Disconnect Switch Market |
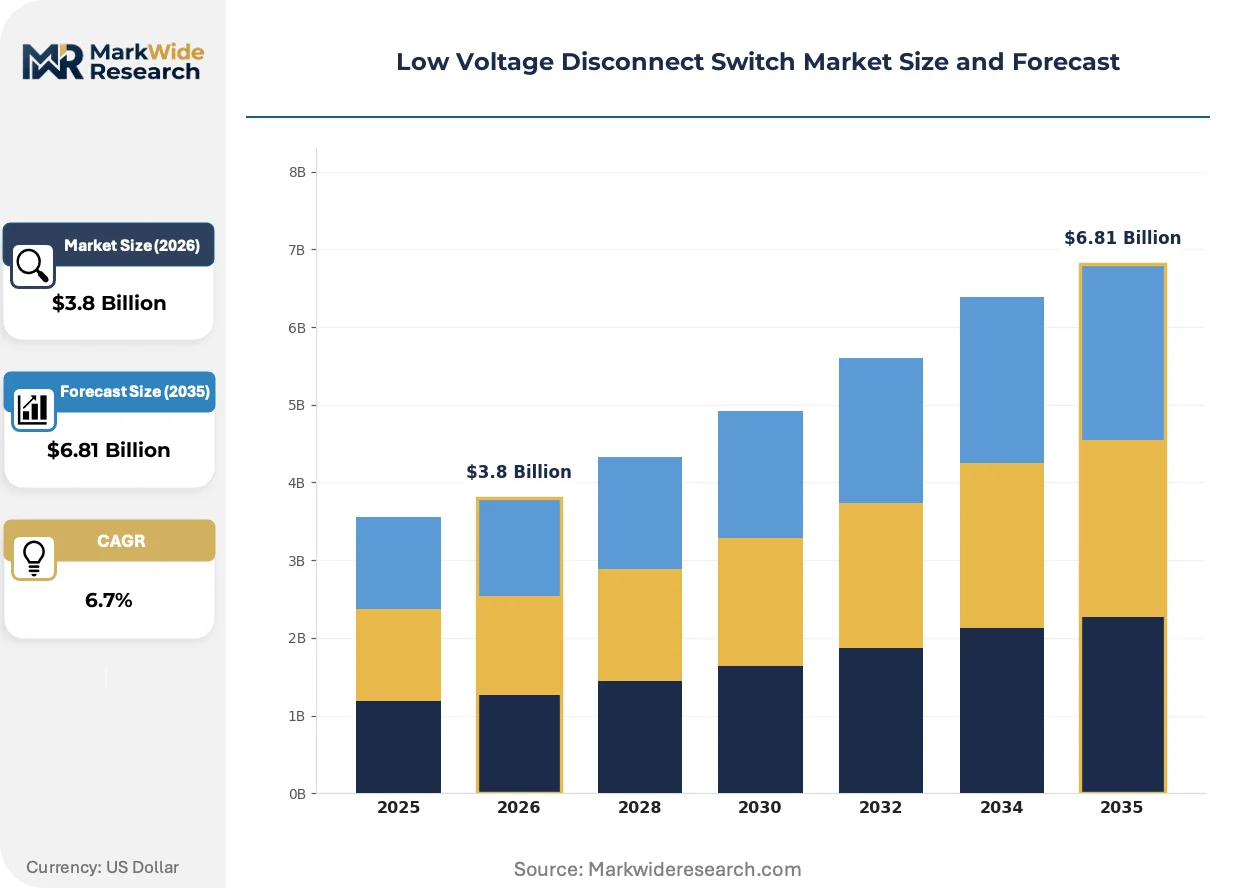
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Circuit Breaker, Motor Protection Circuit Breaker, Residual Current Circuit Breaker, Isolator Switch Technology: Electromechanical, Electronic, Hybrid, Smart Technology Application: Residential Use, Industrial Use, Commercial Use, HVAC Systems End User: Contractors, OEMs, System Integrators, Facility Managers |
| Companies Covered | Siemens AG, Mersen, ABB Ltd., Rockwell Automation Inc., Socomec Group S.A., Eaton Corporation, Littelfuse Inc., Havells India Limited, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Voltage Disconnect Switch Market Strategic Shifts
Electrification of heavy industry and mission-critical infrastructure is accelerating product evolution across contact materials, operating mechanisms, and embedded intelligence layers.
Electronic trip units with microprocessor-based coordination are overtaking thermal-magnetic releases in HVAC and data center applications. Facility managers specify these devices for precise overload selectivity and remote reset capability. The technology is overtaking conventional bimetallic designs in projects above 400A ratings where nuisance tripping costs exceed hardware premiums.
REACH restrictions on hexavalent chromium and cadmium in contact plating are forcing metallurgical pivots toward silver-graphite and tungsten-copper composites. European manufacturers face 2026 deadlines for full substitution in export-qualified product lines. German switchgear specialists are accelerating in-house sintering capabilities to secure supply chain autonomy ahead of enforcement windows.
Specification authority is migrating from electrical contractors to facility energy managers with sustainability mandates. Large commercial buyers now bundle disconnect procurement with carbon accounting and circularity requirements, bypassing traditional distribution channels. This pattern is most visible in Nordic corporate real estate and US hyperscale data center development, where direct OEM relationships secure volume pricing and custom firmware configurations.
Low Voltage Disconnect Switch Market Segmentation
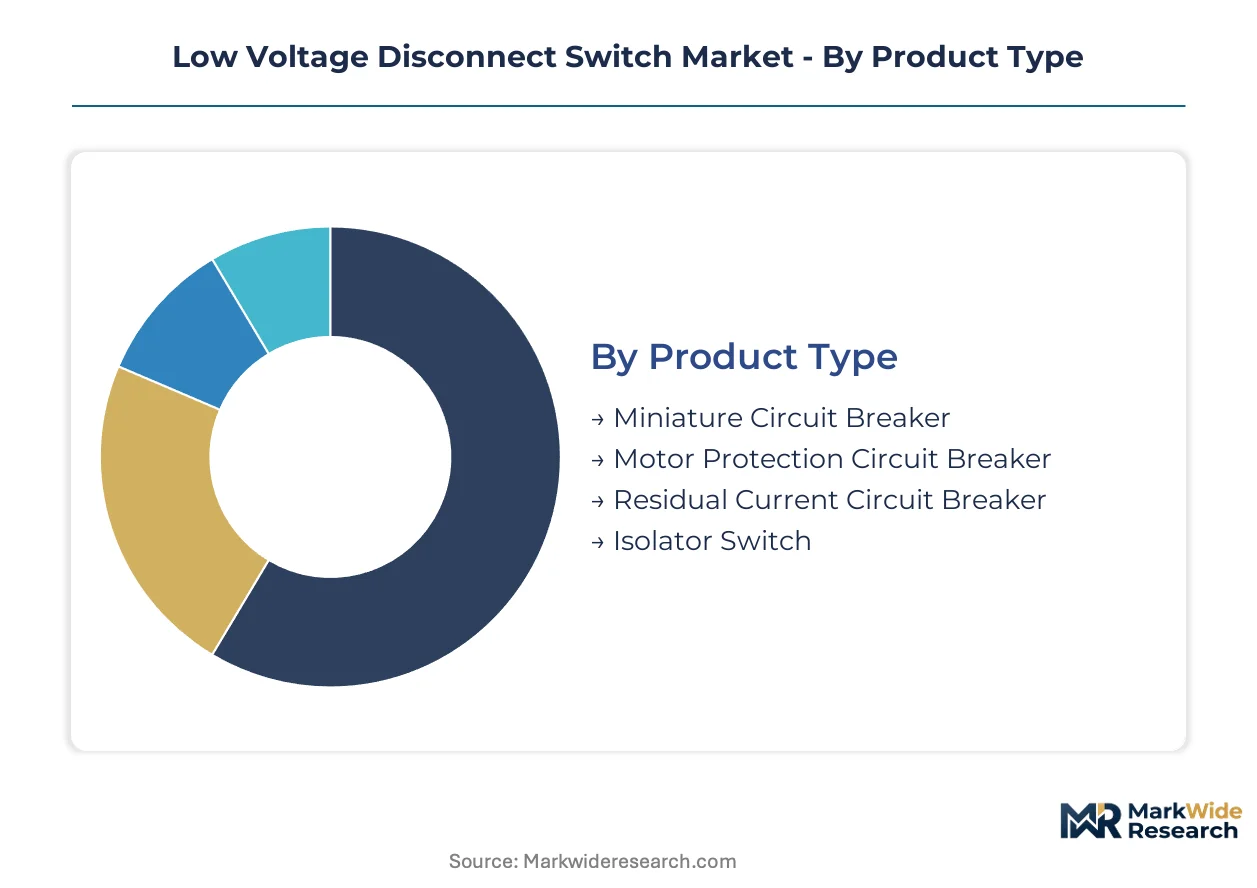
Low voltage disconnect switch procurement patterns diverge sharply across buyer sophistication, operational criticality, and regulatory exposure. Understanding these fault lines reveals where margin pools concentrate and which technology platforms command specification authority.
Product Type:
Cost tier separates specification-grade installations from commodity replacement cycles.
- Miniature Circuit Breaker:DIN-rail mounted thermal-magnetic devices rated up to 125A dominate residential and light commercial distribution boards. Demand concentrates in Germany's building renovation wave, where IEC 60898 compliance mandates drive refresh cycles in multi-tenant housing stock.
- Motor Protection Circuit Breaker:Integrates adjustable thermal overload relays with magnetic short-circuit protection for machine-tool and conveyor applications. Industrial OEMs in China's Yangtze River Delta specify these for motor control centers, where coordination with contactors and variable frequency drives determines system reliability.
- Residual Current Circuit Breaker:Detects earth leakage currents down to 30mA for personnel protection in wet-location installations.
- Isolator Switch:Provides visible break isolation without inherent overcurrent protection for maintenance safety lockout procedures.
Volume sits with Miniature Circuit Breaker; growth tilts toward Motor Protection Circuit Breaker.
Technology:
Maturity stage determines whether buyers prioritize proven reliability or predictive capability.
- Electromechanical:Bimetallic thermal elements and magnetic solenoids constitute the installed base across legacy industrial infrastructure. Facility managers in US Midwest manufacturing corridors specify these for 600V feeder applications where 30-year service life expectations override smart feature premiums.
- Electronic:Microprocessor-based trip units enable precise time-current curve programming and zone-selective interlocking. Data center operators in Northern Virginia and Frankfurt embed these into power distribution units, where nuisance tripping of hyperscale compute loads carries seven-figure outage costs.
- Hybrid:Combines electromechanical isolation with electronic sensing for arc flash mitigation.
- Smart Technology:IoT-enabled condition monitoring with Modbus and BACnet integration for predictive maintenance platforms.
Electromechanical commands current volume; Smart Technology climbs the fastest as building automation retrofits accelerate.
Application:
Operational uptime requirements dictate breaking capacity specifications and remote operability features.
- Residential Use:Single-phase and three-phase distribution protection in single-family and multi-family dwellings. India's rural electrification push under the Saubhagya scheme creates first-time demand for modular consumer units in Bihar and Uttar Pradesh, where grid instability necessitates frequent switching cycles.
- Industrial Use:Heavy-duty motor control and machine safety isolation in continuous-process manufacturing. Petrochemical complexes along the US Gulf Coast specify explosion-proof disconnects with NFPA 70 compliance for refinery maintenance protocols.
- Commercial Use:Retail, healthcare, and office building electrical distribution with aesthetic enclosure requirements.
- HVAC Systems:Dedicated protection for chiller compressors, air handling units, and rooftop package equipment.
Industrial Use anchors revenue concentration; HVAC Systems gain share fastest on heat pump electrification mandates.
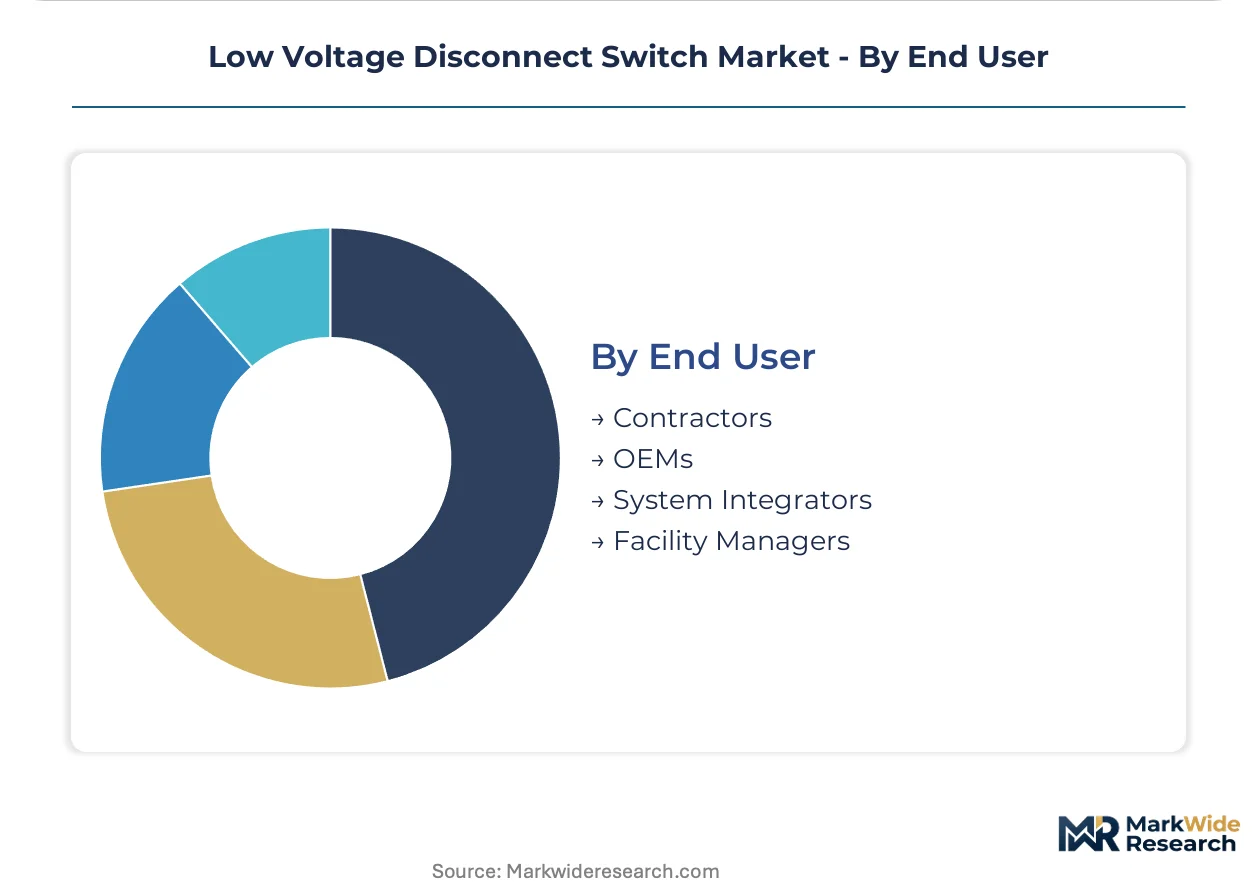
End User:
Technical authority and procurement scale determine whether transactions flow through distribution or direct OEM channels.
- Contractors:Electrical installation firms sourcing standard-duty switches through wholesale distribution. Germany's electrical contractor networks consolidate purchasing through regional buying groups, squeezing margin on commodity isolator variants.
- OEMs:Switchgear and control panel manufacturers integrating disconnects into assembled equipment. Chinese low-voltage panel builders in Wenzhou and Liushi specify Motor Protection Circuit Breakers for export-qualified motor control centers.
- System Integrators:Engineering firms designing custom power distribution architectures for mission-critical facilities.
- Facility Managers:Corporate real estate and data center operators with direct specification authority and sustainability mandates.
Contractors move the highest unit volumes; Facility Managers drive the steepest expansion trajectory on smart infrastructure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's data center corridor concentrates hyperscale procurement for motor-operated disconnects with remote monitoring capabilities. Germany's Industrie 4.0 zones and China's Yangtze River Delta manufacturing clusters drive complementary demand for isolator switches across industrial automation.
United States
Hyperscale data center buildouts in Northern Virginia, Dallas-Fort Worth, and Phoenix specify electronic trip units for 30+ kW rack densities. NFPA 70 visible break mandates accelerate replacement cycles across retail and healthcare infrastructure. Petrochemical complexes along the Gulf Coast anchor explosion-proof disconnect procurement for refinery maintenance protocols.
Germany
Industrie 4.0 adoption in Baden-Württemberg and Bavaria drives specification-grade isolator demand for machine safety lockout. EU Green Deal retrofit incentives subsidize smart switchgear upgrades in commercial real estate. Electrical contractor networks in North Rhine-Westphalia consolidate purchasing through regional buying groups.
China
Smart Cities Mission investments and rural electrification under grid modernization programs create first-time substation automation demand. GB 14048.3 standards enforce clearance requirements comparable to IEC frameworks. Zhejiang and Jiangsu provinces concentrate over sixty percent of molded case frame and contact assembly production.
India
Saubhagya rural electrification scheme generates modular consumer unit demand in Bihar and Uttar Pradesh with frequent switching cycle requirements. CEA mandates drive IEC-compliant disconnect adoption in utility-scale solar and wind integration projects. Gujarat and Maharashtra industrial corridors specify motor protection circuit breakers for OEM motor control center exports.
Singapore
Tropical data center expansion prioritizes thermal endurance and arc-quenching speed in 24/7 operational specifications. Building and Construction Authority energy efficiency codes accelerate smart switchgear retrofits in commercial developments. Jurong Island petrochemical hub maintains steady procurement for process safety isolation systems.
Low Voltage Disconnect Switch Market Competitive Environment
Top-tier vendors anchor premium specification authority, while mid-tier fabricators compete on volume throughput for standard-duty variants. The vendor base stratifies across three tiers: diversified electrotechnical conglomerates with captive R&D, specialized switchgear houses with regional channel control, and contract manufacturers serving price-sensitive replacement markets. Dominant competitive moves include backward integration into contact metallurgy and strategic partnerships for IoT-enabled condition monitoring platforms.
Among diversified electrotechnical conglomerates, Siemens AG and ABB Ltd. exemplify the premium-tier archetype through sustained electromechanical R&D depth and hybrid technology platform development. Schneider Electric occupies a position emphasizing distribution channel control across European contractor networks. Havells India Limited represents the emerging-market specialist archetype, leveraging domestic manufacturing scale to serve price-sensitive infrastructure buildouts across South Asia and the Middle East.
| Leading Market Players |
|---|
| Siemens AG |
| Mersen |
| ABB Ltd. |
| Rockwell Automation Inc. |
| Socomec Group S.A. |
| Eaton Corporation |
| Littelfuse Inc. |
| Havells India Limited |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Germany and Japan anchor premium pricing discipline through in-house contact metallurgy, while private-equity-rolled-up distributors in North America compress margins on standard-duty variants through volume aggregation. Sovereign-backed producers in China leverage state financing to undercut IEC-certified competitors on spot inventory, forcing Western OEMs to differentiate through certified-grade premiums and extended warranty bundling.
Pricing Analysis
Short lead-time premiums of 15-25 percentage points separate expedited delivery contracts from standard inventory positions across mission-critical infrastructure projects. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—UL 98 and IEC 60947-3 qualified units command positioning above uncertified alternatives. Price erosion runs through economy-tier molded case variants as Chinese contract manufacturers flood replacement markets. Facility managers in data center and healthcare segments exhibit lowest price sensitivity, prioritizing arc-quenching reliability and remote operability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for electronic trip units with custom firmware configurations, while electrical contractor networks distribute commodity isolator switches through regional buying groups. Manufacturing gravity centers on Zhejiang and Jiangsu provinces in China for molded case frames, Baden-Württemberg in Germany for precision contact assemblies, and Tamil Nadu in India for export-qualified motor protection variants. Silver-graphite and tungsten-copper composite sourcing draws from Chilean mining operations and Japanese sintering specialists. Single-source vulnerability in arc-resistant alloy supply creates exposure during commodity price spikes. Distribution runs through authorized distributor networks for specification-grade products and direct procurement for large commercial buyers with sustainability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low voltage disconnect switch market sits in an electromechanical-to-electronic transition phase, with microprocessor-based trip units displacing thermal-magnetic releases in precision applications above 400A ratings.
For Market Incumbents: Cement specification authority in data center and healthcare verticals through captive R&D in arc-quenching contact materials. Solid-state circuit breakers with integrated isolation functionality threaten traditional disconnect volumes; backward integration into silver-graphite sintering secures supply autonomy ahead of REACH enforcement deadlines. Channel control across European contractor networks remains a defensible moat against price-aggressive entrants.
For New Entrants and Emerging Players: NFPA 70 visible break mandates in the United States open a window for certified isolator switch specialists to capture replacement cycles in retail and healthcare infrastructure. India's rural electrification push under CEA directives presents first-time demand for IEC-compliant modular consumer units. Target facility managers with direct specification authority through carbon accounting and circularity bundling, bypassing traditional distribution.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier German switchgear houses with in-house contact metallurgy capabilities and established Industrie 4.0 channel relationships. Long-term viability hinges on smart technology integration revenue streams recurring over a decade horizon. Watch for inflection signals in hyperscale data center procurement shifting from electromechanical to electronic trip unit specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Metallurgy | German manufacturers secure supply autonomy ahead of REACH hexavalent chromium deadlines. |
| Smart Technology Platform Development | IoT-enabled condition monitoring opens recurring software revenue for hardware OEMs. |
| Certification Investment in Multi-Standard Compliance | Simultaneous UL 98, IEC 60947-3, and GB 14048.3 qualification accelerates market access. |
| Direct OEM Relationship Building | Hyperscale data center operators in Northern Virginia bypass distribution for volume pricing. |
| Geographic Expansion into India Grid Modernization | CEA-mandated solar and wind integration projects drive IEC-compliant disconnect demand. |
Study Parameters
Independent corroboration across electrical contractor purchasing managers, OEM procurement teams, and facility energy managers underwrites the qualitative findings in this study. Primary interviews with switchgear R&D directors, aftermarket service heads, and system integrators designing mission-critical power architectures combined with secondary validation from IEC standards documentation, NFPA code filings, and customs trade data for copper and silver alloy movements. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against national grid investment disclosures anchored the market sizing.
Comparable-period anchoring to historical switchgear refresh cycles and data center buildout timelines structured the projection horizon across the analysis window. Segmentation dimensions modeled include product type, technology maturity stage, application criticality, and end-user procurement authority. CAGRs derived from weighted average of replacement cycle frequencies, infrastructure investment trajectories, and technology displacement curves. Forecast inputs incorporated arc flash mitigation mandate adoption rates and smart building automation retrofit penetration.
The model assumes a particular technology adoption path; alternative pathways for solid-state circuit breaker displacement would alter the outlook for electromechanical platform volumes. Forecasts reflect base-case assumptions regarding copper price stability and certification timeline standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Mexico Rocker Switch Market
Switches
Molded Case Circuit Breaker Market
Switches
Global Electrical Switches Market
Switches
Smart Home Switches Market
Switches
Miniature-Circuit Breaker Market
Switches
Global Switchgear Market
Switches
Global Push Buttons and Signalling Devices Market
Switches
Cross Point Switch Market
Switches
South America Low Voltage Switchgear Market
Switches
5G Electromechanical RF Switch Market
Switches
Panel Mounted Disconnect Switch Market
Switches
Pad-Mounted Switchgear Market
Switches
Electromechanical Microwave Switch Market
Switches
Smart Dimmer Switch Market
Switches
China Switchgear Market
Switches
Saudi Arabia Switchgear Market