
 Middle East and Africa Smartwatch Market | 2026-2036
Middle East and Africa Smartwatch Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Smartwatch Market Foresight
Fitness enthusiasts is unwinding the traditional professional-user dominance that shaped early smartwatch penetration in the Middle East and Africa. Apple Inc. anchors its position through premium retail presence in Gulf Cooperation Council malls and ecosystem lock-in with iPhone penetration. Samsung Electronics Co. Ltd competes aggressively on price-performance ratios, leveraging localized marketing across West African markets. Xiaomi Corporation extends its reach through aggressive online retail pricing that undercuts most branded alternatives.
A smartwatch is a wrist-worn computational device integrating microprocessors, biometric sensors, wireless communication modules, and rechargeable power systems into a compact form factor, designed to deliver health monitoring, notification management, and application execution without requiring continuous smartphone tethering. Fitness Tracker variants dominate unit volumes across the Middle East and Africa due to accessible price points and simplified feature sets aligned with first-time wearable buyers. OLED-equipped devices command disproportionate margin pools in Gulf markets where display quality serves as a visible status signal. Online Retail channels are capturing share fastest from brick-and-mortar alternatives as logistics infrastructure matures in Kenya and Egypt.
South Africa's ICASA governs radio frequency certification for cellular-enabled wearables, while Nigeria's NCC enforces type-approval standards that filter non-compliant imports at Lagos ports. Saudi Arabia's CITC and UAE's TDRA impose additional electromagnetic compatibility testing that raises compliance costs for budget manufacturers. Stakeholders must monitor diverging national certification timelines that fragment go-to-market strategies across the region.
Market Dynamics
The transition from smartphone-tethered to standalone LTE-enabled wearables is restructuring competitive positioning across Middle East and Africa, as spectrum liberalization in key markets unlocks cellular functionality previously constrained by hardware cost and certification complexity.
Growth Catalysts
- ICASA and NCC spectrum frameworks:South Africa's ICASA and Nigeria's NCC have enabled cellular certification pathways for wearables, reducing barriers for standalone device launches.
- Fitness tracking applications:Health-conscious urban consumers across Lagos, Johannesburg, and Nairobi are adopting biometric monitoring for cardiovascular and sleep metrics.
- Online retail channel maturation:Kenya and Egypt have developed last-mile logistics infrastructure that supports direct-to-consumer wearable distribution.
Market Restraints
- Electromagnetic compatibility testing costs:Saudi Arabia's CITC and UAE's TDRA impose additional certification layers that disproportionately burden budget manufacturers.
- Battery chemistry supply concentration:Lithium-ion cell production concentrates in East Asian suppliers, exposing Middle East and Africa assemblers to input cost volatility and currency risk.
- Smartphone substitution threat:Low-cost Android handsets with health app ecosystems compete directly with entry-level smartwatches for wrist-worn health monitoring.
Strategic Opportunities
- Underpenetrated East African markets:Ethiopia and Tanzania present volume expansion potential as mobile money integration enables wearable payment functionality.
- Remote patient monitoring convergence:Telemedicine platforms in South Africa are integrating wearable biometric feeds into chronic disease management protocols.
- Halal certification alignment:Saudi Arabia and UAE demand patterns favor devices with prayer time notifications and Qibla direction features.
Industry Challenges
- Fragmented national certification timelines:Divergent type-approval schedules across ICASA, NCC, CITC, and TDRA force manufacturers to maintain parallel compliance tracks.
- Biometric sensor calibration complexity:Skin tone and ambient temperature variations across the region require localized algorithm validation that extends product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Smartwatch Market |
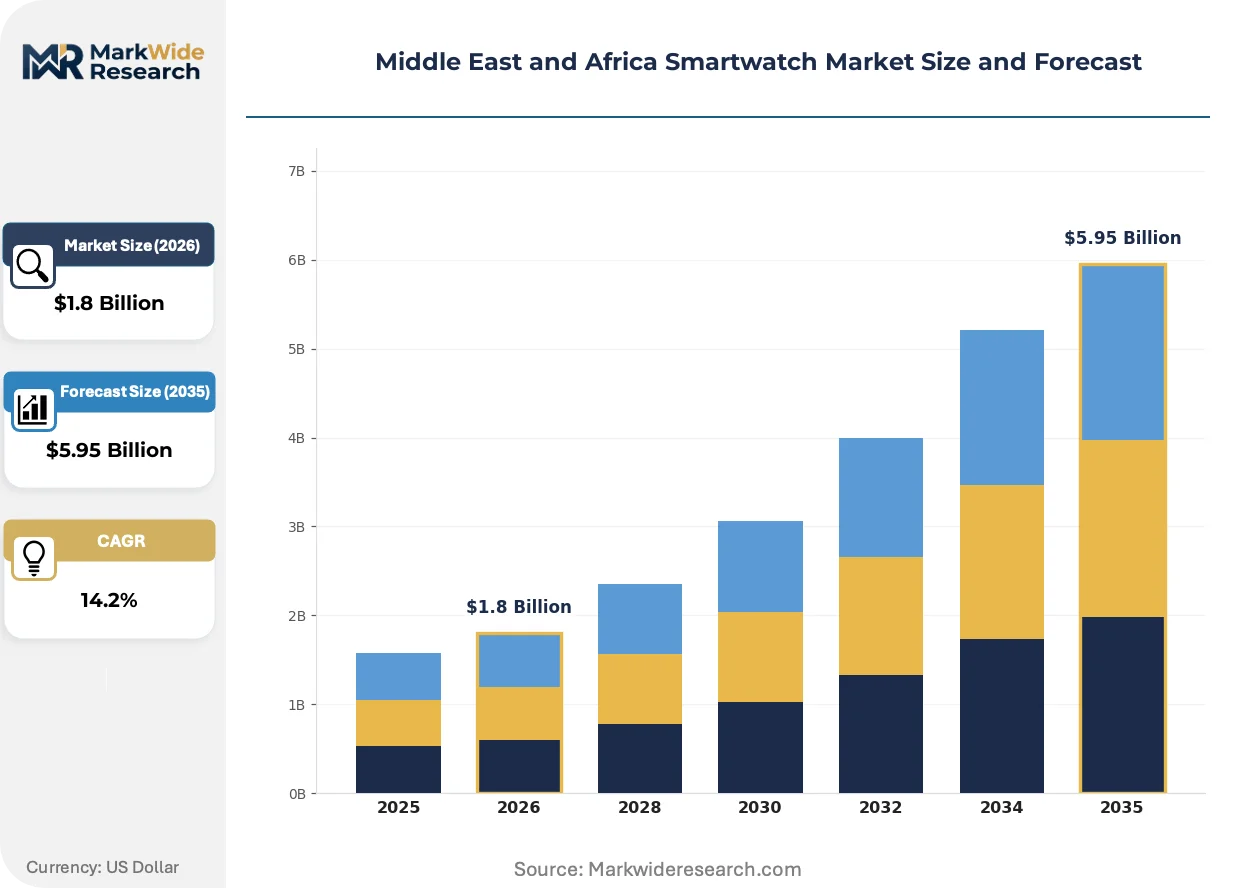
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable, Fitness Tracker, Hybrid, Luxury Technology: Touchscreen, OLED, Bluetooth, GPS End User: Fitness Enthusiasts, Professionals, Tech Savvy, General Consumers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Huawei Technologies Co. Ltd, Fitbit Inc., Apple Inc., Transsion Holdings, Xiaomi Corporation, Samsung Electronics Co. Ltd, Sony Corporation, Amazfit, Garmin Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Smartwatch Market Shifts & Advancements
Wearable computing architectures are fragmenting into modular component ecosystems, enabling regional assemblers to mix sensor modules, wireless chipsets, and power management systems without full vertical integration.
LTPO OLED display technology is decomposing the premium segment's reliance on rigid AMOLED panels, allowing Gulf Cooperation Council retailers to source variable-refresh-rate screens from multiple Asian suppliers rather than single-source arrangements. Fitness enthusiasts and status-conscious buyers in Dubai and Riyadh are adopting these displays for always-on functionality without battery penalty. This technology diffusion is compressing margin pools previously captured by integrated display manufacturers.
Saudi Arabia's CITC has implemented mandatory SAR (Specific Absorption Rate) testing protocols for cellular-enabled wearables, forcing manufacturers to redesign antenna configurations for regional compliance. The industrial consequence is extended pre-market approval timelines and elevated testing costs for first-time entrants. Premium brands with established Gulf retail partnerships are absorbing these costs while budget competitors delay launches.
Urban Nigerian consumers are bypassing traditional electronics retailers through Instagram and WhatsApp commerce, where unboxing videos and peer testimonials drive purchase decisions. Lagos-based micro-influencers are displacing mall-based brand ambassadors as the primary touchpoint for first-time wearable buyers. This channel rotation is most visible among university-educated professionals aged 25-35 seeking fitness tracker entry points.
Middle East and Africa Smartwatch Market Segmentation
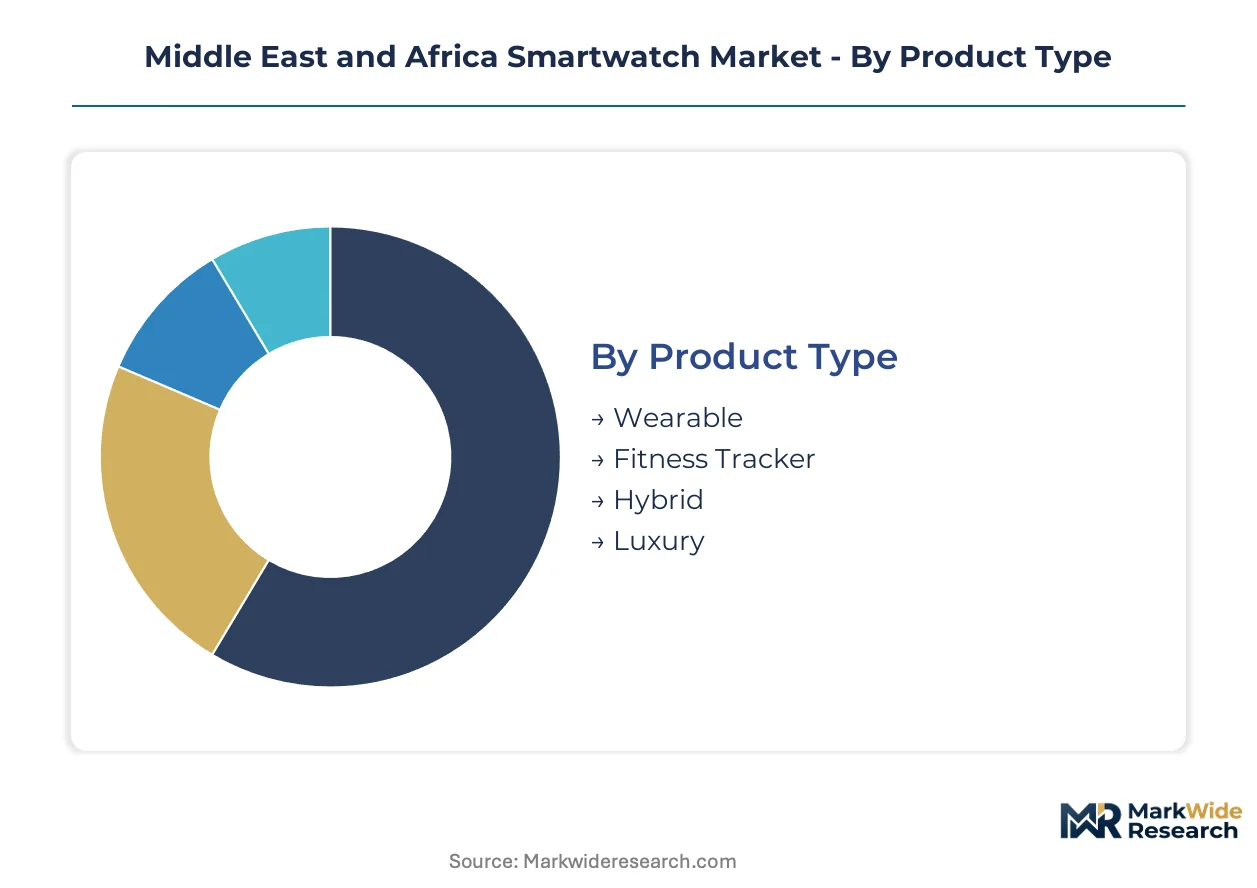
Smartwatch segmentation across the Middle East and Africa reveals divergent margin structures between Gulf premium buyers and West African volume markets. Category boundaries blur as fitness trackers gain cellular connectivity and luxury brands embed biometric sensors.
Product Type:
Margin pools concentrate in hybrid and luxury categories across Gulf Cooperation Council malls, while unit volumes flow through fitness trackers in Lagos and Nairobi.
- Wearable:Full-featured wrist-worn computers with application execution and notification management. Demand clusters in Dubai and Riyadh among iPhone ecosystem users seeking seamless handset integration.
- Fitness Tracker:Simplified devices prioritizing step counting, heart rate monitoring, and sleep tracking at accessible price points. Nigerian urban professionals aged 25-35 drive volume through Instagram and WhatsApp commerce channels.
- Hybrid:Analog watch faces conceal digital connectivity for notification filtering and activity tracking. Saudi professionals favor these for workplace appropriateness while maintaining health monitoring.
- Luxury:Premium materials and heritage branding command price multiples in Abu Dhabi and Doha retail environments. Status signaling through visible wristwear sustains margin premiums despite limited functional differentiation.
Fitness Tracker holds installed capacity. Hybrid is rotating up the share rankings.
Technology:
Display technology determines pricing tiers, with OLED-equipped devices capturing disproportionate margins in status-conscious Gulf markets.
- Touchscreen:Capacitive input surfaces enabling direct interface manipulation. Entry-level devices across Kenya and Egypt rely on this technology for cost containment in first-time buyer segments.
- OLED:Self-illuminating organic panels delivering deep blacks and always-on functionality. Johannesburg and Cape Town consumers prioritize display quality as a visible differentiator in retail environments.
- Bluetooth:Short-range wireless tethering to smartphones for notification relay and data synchronization. Remains the dominant connectivity protocol in price-sensitive West African markets where LTE certification costs burden standalone alternatives.
- GPS:Satellite positioning enabling route tracking without smartphone dependency. Marathon runners and outdoor fitness communities in Nairobi and Cape Town drive adoption for accurate pace and distance metrics.
Bluetooth holds installed capacity. OLED is rotating up the share rankings.
End User:
Customer archetypes fragment along fitness engagement depth and technology sophistication rather than income alone.
- Fitness Enthusiasts:Dedicated exercisers tracking cardiovascular metrics, recovery metrics, and training load. Lagos and Johannesburg health clubs serve as demonstration venues where peer influence accelerates purchase decisions.
- Professionals:Workplace-focused users prioritizing notification management and calendar integration. Saudi and UAE corporate environments drive demand for devices compatible with formal dress codes.
- Tech Savvy:Early adopters seeking novel applications and developer ecosystem access. Concentrated in Cairo and Casablanca university districts where coding communities experiment with custom watch faces and third-party integrations.
- General Consumers:Price-driven buyers seeking basic timekeeping with occasional health glimpses. Ethiopian and Tanzanian markets represent expansion frontiers as mobile money integration enables payment functionality.
General Consumers hold installed capacity. Fitness Enthusiasts is climbing the fastest.
Distribution Channel:
Channel economics invert as logistics infrastructure matures in East African markets previously dependent on informal import networks.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators bypassing traditional electronics retail. Kenya and Egypt have developed last-mile capabilities supporting same-day delivery in Nairobi and Cairo metropolitan zones.
- Specialty Stores:Dedicated electronics retailers with trained staff and hands-on demonstration. Gulf Cooperation Council malls anchor this channel through Apple and Samsung flagship presence.
- Supermarkets:Mass retail chains stocking entry-level fitness trackers alongside consumer electronics. South African Pick n Pay and Shoprite networks extend reach into secondary cities with limited specialty retail.
- Direct Sales:Manufacturer-owned retail and brand-operated e-commerce. Xiaomi leverages this channel in Nigeria to maintain aggressive pricing unburdened by distributor markups.
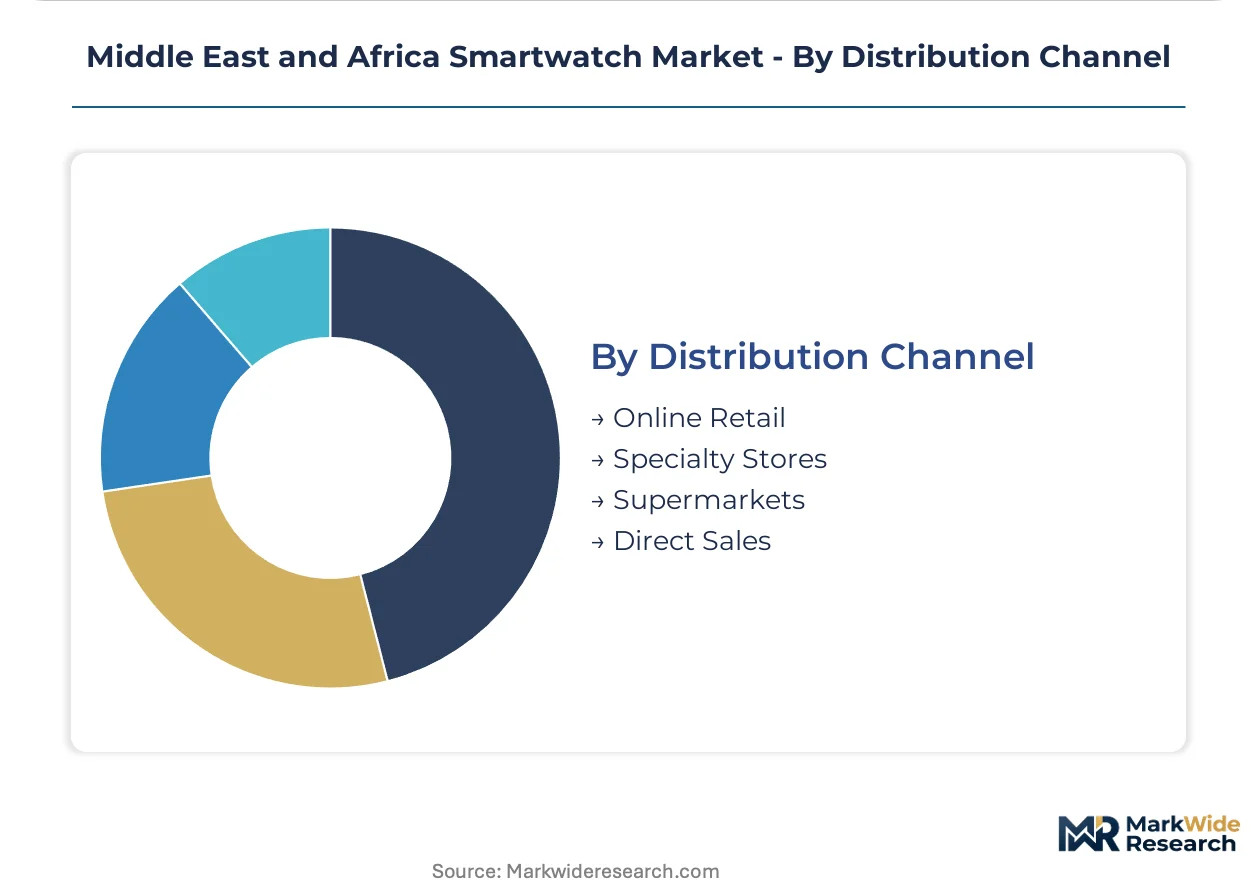
Specialty Stores hold installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port in Dubai underwrites the Gulf's role as the primary import gateway for consumer electronics entering Africa and the Levant. This logistics hub connects Asian manufacturing centers with retail distribution networks spanning Lagos to Nairobi. Regional demand fragmentation requires manufacturers to navigate divergent certification regimes and income-tier segmentation.
United Arab Emirates
Dubai Mall and Mall of the Emirates anchor premium smartwatch retail, with OLED-equipped devices commanding visible status premiums among expatriate professionals. The UAE's TDRA enforces electromagnetic compatibility testing that elevates compliance costs for budget entrants. Abu Dhabi's Yas Island retail cluster concentrates flagship store investments from ecosystem-locked brands seeking Gulf Cooperation Council market presence.
Saudi Arabia
Riyadh's Diriyah Gate and Jeddah's Red Sea Mall drive hybrid smartwatch adoption among professionals balancing workplace dress codes with health monitoring. CITC mandates SAR testing protocols that force antenna redesigns for cellular-enabled wearables. The Eastern Province's Dammam industrial corridor hosts regional distribution centers serving the kingdom's concentrated urban demand.
South Africa
Johannesburg's Sandton City and Cape Town's V&A Waterfront concentrate premium wearable retail among fitness enthusiasts tracking cardiovascular metrics. ICASA governs radio frequency certification for LTE-enabled devices, enabling standalone wearable launches previously blocked by hardware cost barriers. The Western Cape's Stellenbosch health-tech cluster incubates telemedicine platforms integrating wearable biometric feeds.
Nigeria
Lagos Island's urban middle-class drives fitness tracker volumes through Instagram and WhatsApp commerce channels, displacing traditional electronics retail. The NCC enforces type-approval standards that filter non-compliant imports at Lagos ports, fragmenting go-to-market timelines. Ikeja's Computer Village informal electronics market remains a price-sensitive entry point for first-time wearable buyers.
Egypt
Cairo's Mall of Arabia and Alexandria's City Center anchor specialty retail for professionals seeking notification management and calendar integration. The National Telecom Regulatory Authority certifies wireless devices for Egyptian market entry, adding a compliance layer for regional assemblers. The Suez Canal Economic Zone's logistics infrastructure supports last-mile delivery capabilities for online retail channels.
Middle East and Africa Smartwatch Market Competitive Landscape
Listed leaders compete with private specialists across pricing tiers and distribution channel control. The vendor base fragments across three competitive layers: premium ecosystem-locked players, mid-tier price-performance competitors, and budget online-first entrants. Two dominant strategic archetypes define positioning: Gulf Cooperation Council mall-based premium retail operators, and West African digital commerce specialists leveraging direct-to-consumer logistics. Competitive moves concentrate on exclusive retail partnerships and localized certification compliance teams.
Within the premium ecosystem tier, Apple Inc. and Samsung Electronics Co. Ltd occupy positions defined by retail presence and handset integration depth. Xiaomi Corporation exemplifies the budget-vector archetype through aggressive online pricing that bypasses distributor markups. Transsion Holdings represents the Africa-specialized challenger model with distribution networks calibrated to informal retail and mobile money integration.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd |
| Fitbit Inc. |
| Apple Inc. |
| Transsion Holdings |
| Xiaomi Corporation |
| Samsung Electronics Co. Ltd |
| Sony Corporation |
| Amazfit |
| Garmin Ltd |
| Others |
Supply & Pricing Matrix
Asian display panel scale economies concentrate margin capture among Korean and Chinese OLED suppliers, compressing price floors for Middle East and Africa assemblers while elevating entry barriers for budget manufacturers seeking LTPO technology. This concentration cascades into three-tier pricing stratification across Gulf premium retail, West African volume channels, and East African expansion markets.
Pricing Analysis
Volume-discount tiering structures separate Apple and Samsung flagship positioning in Dubai malls from Xiaomi's direct-to-consumer penetration in Lagos and Nairobi. Price differentiation hinges on ICASA and NCC certification completion status alongside display technology grade, with OLED-equipped devices commanding visible premiums in status-conscious Gulf markets. Cost compression in the fitness tracker tier intensifies as Transsion Holdings and Amazfit undercut branded alternatives through distributor bypass. General consumers in Ethiopia and Tanzania exhibit highest price sensitivity, while luxury buyers in Abu Dhabi and Doha demonstrate lowest elasticity.
Supply Chain Analysis
Just-in-time inventory preferences dominate among Gulf retailers stocking premium SKUs, while Nigerian and Kenyan distributors maintain strategic stockpiles against Lagos port clearance delays and NCC type-approval bottlenecks. Lithium-ion cell production concentrates in China, South Korea, and Japan, exposing regional assemblers to input cost volatility and currency risk. Supply chain vulnerability centers on single-source OLED driver IC dependencies from Taiwanese foundries. Distribution runs through Jebel Ali Port consolidation for Gulf markets, with last-mile fragmentation across West African informal electronics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone substitution represents the primary displacement threat as low-cost Android handsets with health app ecosystems compete directly for wrist-worn health monitoring, forcing incumbents to demonstrate clear wearable-specific value capture.
For Market Incumbents: Compound ecosystem lock-in through iPhone and Galaxy handset integration depth, while securing exclusive retail partnerships in Gulf Cooperation Council malls against Transsion's informal channel expansion. Invest in ICASA and NCC certification pre-clearance to compress launch timelines versus budget competitors. Prioritize biometric sensor algorithm localization for skin tone and ambient temperature calibration across the region. For New Entrants and Emerging Players: Post-sales service coverage gaps in East African markets present white-space opportunities as Nairobi and Cairo logistics infrastructure matures. Ethiopia and Tanzania mobile money integration offers the most penetrable entry vector for payment-enabled fitness trackers. Pursue Instagram and WhatsApp commerce direct-to-consumer models that displace traditional electronics retail in Lagos and Johannesburg. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telemedicine platform partnerships integrating wearable biometric feeds into chronic disease management protocols. Long-term viability over the next decade rests on software-service revenue attachment rather than hardware margin capture. Monitor CITC and TDRA electromagnetic compatibility testing timeline convergence as inflection signal for budget manufacturer consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | ICASA and NCC clearance acceleration compresses time-to-revenue versus competitors awaiting Lagos port filtering. |
| Telemedicine Platform Integration | Stellenbosch health-tech cluster partnerships embed biometric feeds into chronic disease management protocols. |
| Mobile Money Payment Enablement | M-Pesa and similar integrations unlock Ethiopian and Tanzanian volume expansion beyond smartphone-tethered limitations. |
| Halal Feature Localization | Prayer time notifications and Qibla direction alignment capture Saudi and UAE demand patterns favoring faith-integrated devices. |
| Direct-to-Consumer Channel Buildout | Instagram and WhatsApp commerce bypasses distributor markups that burden traditional electronics retail in West Africa. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the Middle East and Africa smartwatch value chain, including ICASA and NCC regulatory affairs leads, Gulf Cooperation Council mall retail category managers, Lagos-based micro-influencer commerce operators, Nairobi last-mile logistics coordinators, and Shenzhen contract manufacturing procurement directors. Secondary validation drew from TDRA and CITC electromagnetic compatibility filings, Nigeria Customs Service import records, Kenya Revenue Authority electronics trade data, and Apple and Samsung SEC disclosure segments. Bottom-up channel volume estimates triangulated against top-down consumer electronics spending benchmarks.
Across the analysis window, the forecasting framework modeled product type segmentation across wearable, fitness tracker, hybrid, and luxury categories; technology tiers spanning touchscreen, OLED, Bluetooth, and GPS; end user archetypes including fitness enthusiasts, professionals, tech savvy, and general consumers; and distribution channel dynamics across online retail, specialty stores, supermarkets, and direct sales. CAGRs derived from installed capacity rotation patterns and share-ranking velocity across these dimensions. Key inputs included LTE certification pathway completion rates in South Africa and Nigeria, and mobile money penetration trajectories in East African frontier markets.
Forecasts assume regulatory continuity in ICASA, NCC, CITC, and TDRA regimes; material policy shifts in electromagnetic compatibility testing mandates or SAR protocol stringency would require re-modeling. Revision becomes warranted when lithium-ion cell input cost volatility crosses margin compression thresholds forcing tier repricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
US Pet Wearable Market
Wearable Technology
Kids Watch Market
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
Smart Band Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Wearable Technology Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
Wearable Electronics Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
3D Printed Wearables Market