
 Anthracene Oil Market | 2026-2036
Anthracene Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Anthracene Oil Market Analysis
Refined-grade specification upgrades is reorganizing competitive dynamics across the anthracene oil value chain. Sasol leverages its integrated Fischer-Tropsch and coal-chemical platforms to sustain high-purity output for carbon black and dye intermediates. Jining Carbon anchors regional supply security through captive coking capacity in Shandong province. PetroChina competes via pipeline-linked distribution networks that dominate bulk delivery to northeastern chemical manufacturers.
Anthracene oil is a coal-tar distillation fraction boiling between 270°C and 360°C, containing anthracene, phenanthrene, carbazole, and other polycyclic aromatic hydrocarbons; refiners crystallize and solvent-extract these components for dye, pesticide, and carbon black feedstock applications. High-temperature anthracene oil leads volume share due to its concentration of extractable aromatics for anthraquinone production, while refined grades command margin premiums from pharmaceutical and specialty chemical buyers. Crude grades occupy a shrinking but stable position in bulk carbon black feedstock where cost sensitivity overrides purity requirements.
China's SAMR enforces GB standards on coal-tar derivative purity that disqualify unrefined product from coatings and adhesives channels, while India's BIS certification requirements for textile dyes restrict import of off-spec anthracene oil. The EU REACH framework subjects imported anthracene oil to registration and restriction protocols that elevate compliance costs for Asian exporters serving European chemical manufacturers. Stakeholders must monitor how carbon border adjustment mechanisms and evolving MEE enforcement in China reshape cost structures for cross-border refined product trade.
Market Dynamics
Refined-grade specification upgrades are reorganizing competitive dynamics across the anthracene oil value chain, as carbon black producers and dye intermediate manufacturers demand higher-purity feedstock to meet tightening purity protocols.
Growth Catalysts
- Carbon black feedstock demand:Tire manufacturers in India are scaling domestic production, pulling additional anthracene oil volumes into rubber reinforcement applications. BIS certification requirements for textile dyes reinforce quality premiums for compliant supply.
- GB standards enforcement:China's SAMR purity specifications are filtering lower-grade product from coatings and adhesives channels, compressing supply of qualified material and elevating margins for compliant refiners.
- Yangtze River Delta consolidation:Coking capacity clustering around Shanghai-Nanjing chemical corridors concentrates downstream processing infrastructure, reducing logistics costs for integrated anthracene oil derivatives production.
Market Restraints
- Coal-tar feedstock volatility:Coking economics fluctuate with steel demand cycles, creating input cost instability for anthracene oil producers dependent on metallurgical coke byproduct supply.
- Supply concentration risk:Shanxi and Shandong provinces dominate Chinese coking capacity; disruptions at key facilities propagate through refined product availability.
- Substitution pressure from petroleum-based carbon black feedstock:FCC decant oil and ethylene tar compete for carbon black furnace applications where purity specifications permit.
Strategic Opportunities
- Pharmaceutical-grade anthracene derivatives:Carbazole extraction for photoresist and OLED intermediate applications commands substantial margin premiums over commodity carbon black feedstock.
- EU REACH registration arbitrage:Asian exporters with completed substance dossiers capture displaced volumes from competitors facing elevated compliance costs under European chemical registration frameworks.
- Pipeline-linked distribution expansion:Northeastern Chinese chemical manufacturers seek dedicated supply contracts reducing drum handling and contamination risk in refined product logistics.
Industry Challenges
- Crystallization and solvent extraction expertise scarcity:Refiners face recruitment bottlenecks for process engineers capable of optimizing anthracene-carbazole separation yields.
- Dual carbon compliance capex burden:Chinese MEE enforcement of emissions intensity targets requires coking-integrated producers to fund carbon capture or hydrogen substitution retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anthracene Oil Market |
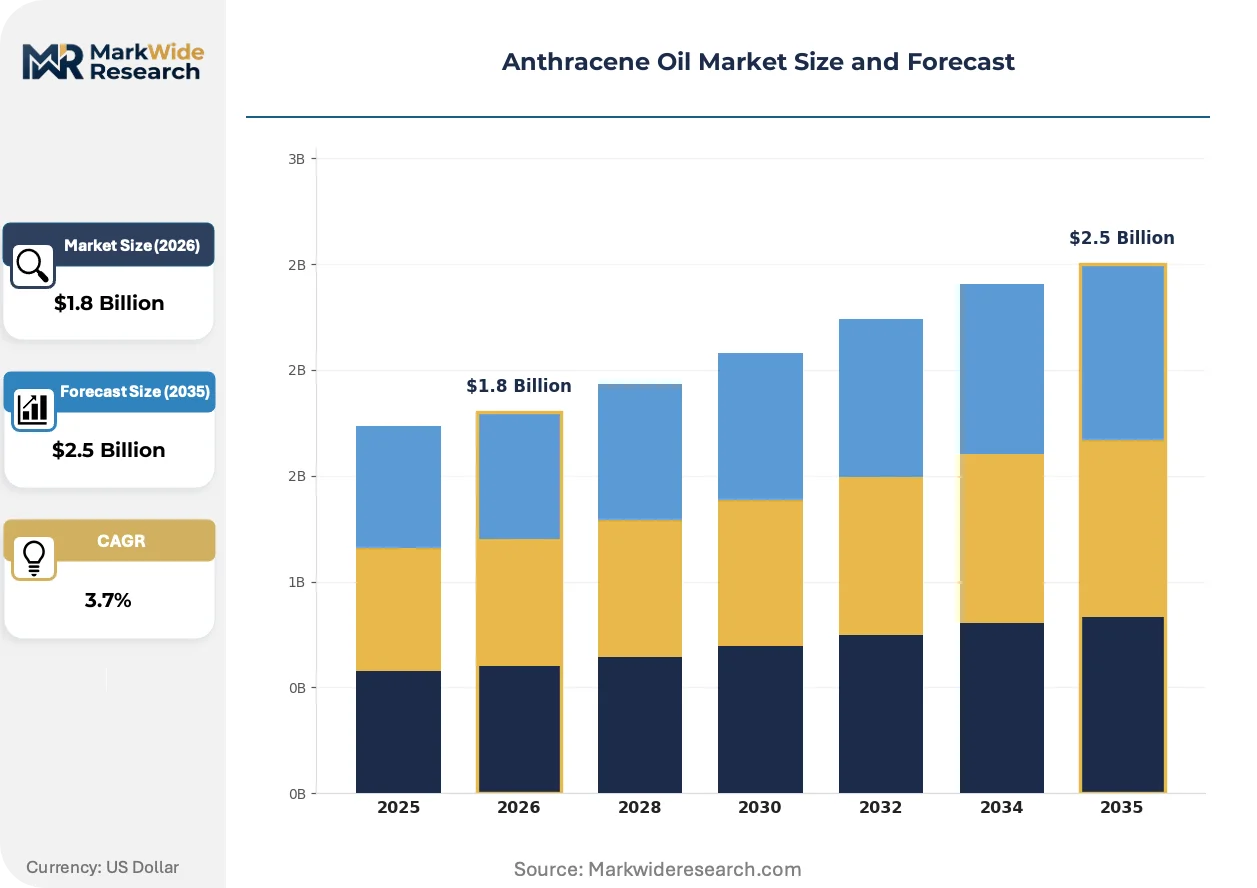
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Temperature, Low-Temperature, Crude, Refined Application: Dyes, Plastics, Coatings, Adhesives End User: Chemical Manufacturers, Textile Industry, Paints & Coatings, Construction Delivery Mode: Bulk Supply, Containerized Shipping, Drum Packaging, Tanker Shipping |
| Companies Covered | Jining Carbon, Sasol, BaoTou Steel Union, PetroChina, Phillips 66, Haiming Petrochemical, Wacker Chemie AG, Royal Dutch Shell, Shanxi Coking Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anthracene Oil Market Emerging Trajectories
Supercritical fluid extraction and continuous crystallization systems are displacing batch solvent processes, compressing production cycles and reducing wastewater burdens for anthracene oil refiners serving specialty chemical markets.
Supercritical CO2 extraction technology is decomposing the traditional multi-stage solvent crystallization workflow for anthracene and carbazole recovery. Specialty dye intermediate producers in the Yangtze Delta are piloting these units to halve processing times. The technology is decomposing capital barriers for mid-scale refiners previously locked out of pharmaceutical-grade supply chains.
REACH restriction protocols on polycyclic aromatic hydrocarbon content in consumer goods are forcing reformulation across European adhesives and sealants formulators. Anthracene oil-derived products face elevated testing and documentation burdens for market access. Carbon black producers serving EU tire manufacturers are accelerating low-PAH specification development to preempt downstream liability exposure.
Long-term offtake contracting is displacing spot market purchasing for refined anthracene oil volumes. Carbon black producers in India are locking in three-to-five year supply agreements with Shanxi refiners to secure feedstock for greenfield tire cord expansion. This shift concentrates procurement leverage with integrated coking-chemical conglomerates possessing guaranteed coal-tar supply.
Anthracene Oil Market Segmentation
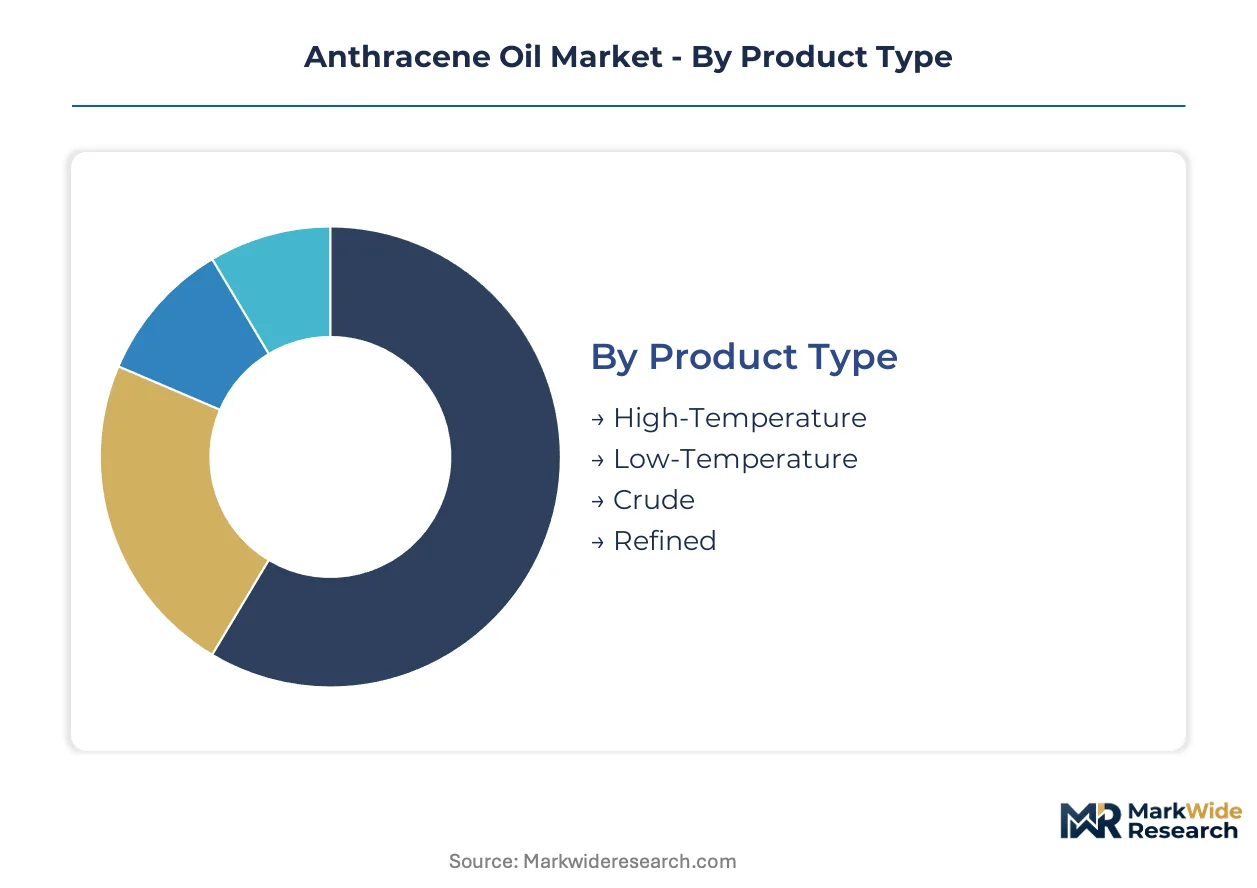
Anthracene oil segmentation reflects divergent purity requirements across carbon black feedstock, dye intermediates, and specialty chemical channels. Product grade specifications directly determine applicable end-use markets and geographic trade eligibility under regional purity protocols.
Product Type:
Domestic consumption concentrates on high-temperature and crude grades serving integrated coking-chemical complexes, while refined volumes dominate export trade to pharmaceutical and specialty chemical buyers.
- High-Temperature:Distillation fraction boiling between 270°C and 360°C with elevated anthracene and phenanthrene concentration. Demand clusters in the Yangtze River Delta for anthraquinone production serving textile dye manufacturers under China's GB standards.
- Refined:Solvent-extracted and crystallized grades meeting pharmaceutical and photoresist intermediate specifications. European REACH registration requirements filter supply to dossier-compliant Asian exporters serving EU chemical manufacturers.
- Low-Temperature:Coal-tar fraction with reduced aromatic extractability, primarily consumed in domestic carbon black feedstock applications where cost sensitivity dominates.
- Crude:Unprocessed distillation output for bulk carbon black furnace feedstock; Shanxi and Shandong coking operations supply tire manufacturers in India through long-term offtake contracts.
High-temperature grades command the established base. The steepest expansion runs through refined pharmaceutical and OLED intermediate applications.
Application:
Margin stratification separates commodity carbon black feedstock from specialty dye and adhesive formulations governed by tightening purity enforcement.
- Dyes:Anthraquinone and carbazole derivatives for textile and leather colorants. India's BIS certification requirements restrict import of off-spec material, elevating premiums for compliant supply.
- Coatings:Binder and solvent applications facing China's SAMR filtration of lower-grade product from premium channels under GB standards enforcement.
- Plastics:Processing aids and pigment carriers where petroleum-based substitutes compete on cost in less regulated segments.
- Adhesives:Formulation components subject to EU REACH PAH restrictions requiring elevated testing documentation for market access.
Dye intermediates anchor volume demand. Coatings applications face the most acute specification compression from regulatory enforcement.
End User:
Procurement leverage concentrates with integrated tire and textile manufacturers locking in multi-year supply agreements.
- Chemical Manufacturers:Integrated coking-chemical conglomerates in Shanxi and Shandong provinces dominate captive consumption and third-party sales to downstream derivative producers.
- Textile Industry:Anthraquinone consumers in India and China's coastal provinces drive specification upgrades for vat dye and disperse dye intermediates.
- Paints & Coatings:Formulators adapting to GB standards displacement of unrefined grades from premium product lines.
- Construction:Niche consumption in waterproofing membranes and sealants where crude grades suffice for cost-driven applications.
Chemical manufacturers control upstream supply. Textile sector buyers are consolidating procurement through dedicated refinery partnerships.
Delivery Mode:
Logistics configuration tracks customer scale and contamination sensitivity across bulk industrial users versus specialty chemical consignees.
- Bulk Supply:Pipeline and dedicated tanker delivery to integrated carbon black producers in northeastern China, minimizing handling costs for high-volume furnace feedstock.
- Drum Packaging:Sealed steel containers for refined grades requiring contamination prevention during pharmaceutical and photoresist intermediate transport.
- Tanker Shipping:Coastal and riverine bulk movement serving Yangtze River Delta chemical clusters with reduced drum handling overhead.
- Containerized Shipping:Intermodal units for export volumes to India and Southeast Asia, balancing flexibility with per-unit logistics cost.
Bulk supply dominates domestic volume. Containerized shipping is gaining share fastest for cross-border refined product trade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian carbon black producers exhibit the sharpest price sensitivity, locking in long-term offtake contracts to hedge coking economics volatility. European pharmaceutical and specialty chemical buyers absorb substantial premiums for REACH-compliant refined grades. Chinese domestic demand splits between cost-driven furnace feedstock and specification-upgraded dye intermediates.
China
Yangtze River Delta chemical manufacturers drive refined anthracene oil consumption for anthraquinone production serving textile dye channels. SAMR enforcement of GB standards on coal-tar derivative purity filters unrefined product from coatings and adhesives applications. Shanghai-Nanjing corridor coking capacity consolidation reduces logistics costs for integrated downstream processing.
India
Domestic tire manufacturing expansion pulls additional anthracene oil volumes into rubber reinforcement feedstock applications. BIS certification requirements for textile dyes restrict import of off-spec material, elevating quality premiums for compliant supply. Maharashtra and Gujarat chemical clusters anchor procurement leverage for integrated tire and textile manufacturers.
Germany
Specialty chemical and carbon black producers face elevated testing documentation burdens under REACH PAH restrictions on consumer goods. ECHA registration protocols filter supply to dossier-compliant Asian exporters. Ruhr industrial region chemical manufacturers seek long-term supply contracts reducing contamination risk in refined product logistics.
United States
Carbon black producers evaluate petroleum-based substitutes including FCC decant oil where purity specifications permit furnace feedstock flexibility. EPA oversight of coal-tar derivative handling shapes refiner compliance cost structures. Gulf Coast petrochemical corridor concentration influences feedstock substitution economics for domestic anthracene oil demand.
South Africa
Fischer-Tropsch and coal-chemical integration supports high-purity output for export-oriented carbon black and dye intermediate applications. Domestic regulatory frameworks align with OECD chemical safety guidelines. Sasolburg industrial complex anchors integrated production capacity serving European and Asian specialty chemical buyers.
Anthracene Oil Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the anthracene oil value chain. Integrated coking-chemical conglomerates dominate volume supply through captive coal-tar feedstock access. Independent refiners compete on crystallization and solvent extraction expertise for pharmaceutical-grade derivative markets. Strategic moves concentrate on long-term offtake contracting and pipeline-linked distribution expansion.
Among integrated energy and chemical conglomerates, Sasol and PetroChina occupy positions spanning Fischer-Tropsch platforms and pipeline-linked distribution networks. Shanxi Coking Group exemplifies the captive coking capacity archetype anchoring regional supply security. Jining Carbon represents Shandong province-based refiner integration into carbon black feedstock and dye intermediate channels.
| Leading Market Players |
|---|
| Jining Carbon |
| Sasol |
| BaoTou Steel Union |
| PetroChina |
| Phillips 66 |
| Haiming Petrochemical |
| Wacker Chemie AG |
| Royal Dutch Shell |
| Shanxi Coking Group |
| Others |
Supply Flow & Price Mechanics
Forty-five-day inventory cycles at Yangtze Delta refiners compress working capital exposure while amplifying spot-price volatility for crude-grade anthracene oil. This lead-time band concentrates pricing power with Shanxi coking conglomerates possessing captive coal-tar feedstock, leaving independent refiners exposed to metallurgical coke byproduct availability swings.
Pricing Analysis
Long-term offtake contracts now drive lifetime value beyond spot transactions, with three-to-five year supply agreements locking in volume commitments from Indian tire manufacturers. Pricing stratifies across refined pharmaceutical grades, high-temperature anthraquinone feedstock, and crude carbon black furnace input, with BIS certification and REACH dossier compliance commanding substantial premiums. Cost compression in crude grades intensifies as petroleum-based substitutes including FCC decant oil capture furnace applications where purity specifications permit flexibility. Carbon black producers in India exhibit the sharpest price sensitivity, while European specialty chemical buyers absorb premiums for compliant refined supply.
Supply Chain Analysis
Strategic stockpile preferences dominate among northeastern Chinese chemical manufacturers seeking contamination prevention, while just-in-time drum delivery serves pharmaceutical-grade consignees in the Yangtze Delta. Supply concentrates in China, India, and South Africa, with Shanxi and Shandong provinces anchoring coking-chemical integration. Raw material flows draw from metallurgical coke byproduct, coal-tar distillation fractions, and solvent extraction chemicals. Single-source vulnerability propagates from concentrated coking capacity, as disruptions at key Shanxi facilities cascade through refined product availability. Distribution runs through pipeline-linked bulk delivery for integrated carbon black producers, sealed drum logistics for specialty chemical buyers, and containerized intermodal for cross-border refined trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-layer expansion in crystallization and solvent extraction expertise outpaces hardware margins, as refiners face acute recruitment bottlenecks for process engineers optimizing anthracene-carbazole separation yields.
For Market Incumbents: Fortify captive coking capacity positions through backward integration into coal-tar distillation infrastructure, neutralizing feedstock volatility from steel demand cycles. Deepen certification investments for BIS and REACH compliance to defend margin premiums against emerging independent refiners targeting pharmaceutical-grade markets. Channel control through pipeline-linked distribution networks reduces contamination risk and locks in northeastern Chinese chemical manufacturers.
For New Entrants and Emerging Players: After-sales technical service for crystallization yield optimization represents a critical gap where incumbents under-serve mid-scale dye intermediate producers. Target Indian carbon black feedstock procurement, where domestic tire manufacturing expansion creates volume entry points without immediate pharmaceutical-grade certification burdens. Pursue joint venture structures with Shanxi coking operations to secure guaranteed coal-tar supply rather than spot market exposure.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH and GB standards compliance costs filter supply to dossier-capable Asian exporters serving European specialty chemical buyers. Acquisition targets should combine coking-chemical integration with supercritical fluid extraction pilot capacity for pharmaceutical-grade derivative expansion. Monitor MEE enforcement intensity on dual carbon targets as the inflection signal for compliance capex burden redistribution across integrated producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coking Capacity | Shanxi and Shandong conglomerates secure captive coal-tar feedstock against metallurgical coke cycle volatility. |
| Supercritical Extraction Technology Deployment | Yangtze Delta refiners halve processing times for carbazole recovery serving OLED intermediate markets. |
| REACH Dossier Completion | Asian exporters capture displaced European volumes from competitors facing elevated ECHA registration costs. |
| Long-term Offtake Contracting | Indian tire manufacturers lock in three-to-five year supply agreements hedging coking economics instability. |
| Pipeline-linked Distribution Expansion | PetroChina's northeastern network reduces drum handling contamination risk for refined pharmaceutical grades. |
Methodological Framework
A spread of perspectives from coking plant managers, carbon black procurement leads at tire manufacturers, distribution channel partners, and technical R&D directors at dye intermediate producers converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical conglomerates, and SAMR regulatory filings. Bottom-up volume builds across grade tiers and applications triangulated against top-down macroeconomic anchors.
Segmentation dimensions modeled span product grade tier, end-use application, delivery mode configuration, and regional production hub concentration across the analysis window. CAGRs were derived from regression-based trend extrapolation calibrated to historical trade flow patterns and capacity expansion announcements. Forecast inputs incorporated coking capacity utilization rates, GB standards enforcement trajectory, and REACH restriction protocol evolution for polycyclic aromatic hydrocarbon content.
Underlying assumptions cover continued steel demand cycles driving metallurgical coke byproduct availability, with deviation risk concentrated in MEE emissions intensity enforcement acceleration and carbon border adjustment mechanism implementation reshaping cross-border refined product trade economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Bioisobutene Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Propylene Market
Petrochemicals
Oman Pyrolysis Gasoline Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Propylene Carbonate Market
Petrochemicals
Pentane Market
Petrochemicals
Basic Petrochemical Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Military Propellants Market
Petrochemicals
Propane Market
Petrochemicals
Global Perfluorocarbons Market