
 Asia-Pacific Craft Beer Market | 2026-2036
Asia-Pacific Craft Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Craft Beer Market Outlook
Market Context with Strategic Players
Australian independent brewery capacity is hardening against multinational inroads across Victoria and New South Wales. Kiuchi Brewery Inc. leverages its Hitachino Nest brand equity to anchor premium positioning in Japan's saturated beer landscape. Stone & Wood Brewing Co. dominates the Pacific Pale Ale niche through coastal Queensland distribution networks. Asahi Breweries Ltd navigates craft adjacencies via minority stakes in regional operators while sustaining mass-market scale.
Technical Definition and Structural Segments
Asia-Pacific craft beer denotes malt-fermented beverages produced by breweries holding annual output below six million barrels, typically employing traditional ingredients with adjuncts limited to flavor enhancement rather than cost reduction. These products serve commercial purposes ranging from on-premise draft consumption to premium off-trade gifting, with alcohol-by-volume specifications generally spanning four to twelve percent. IPA and Stout categories lead volume contribution across specialty stores and bars, while Lager formats attract casual drinkers through supermarket channels. Cans represent the fastest-growing packaging type as brewers prioritize portability and shelf-life extension for online retail fulfillment.
Regulatory Frame and Forward Outlook
Australia's excise framework administered by the Australian Taxation Office compresses margins for sub-scale producers, while Japan's National Tax Agency governs brewing licenses with minimum annual output thresholds that disadvantage nano-operations. China's SAMR enforces labeling standards under GB codes that constrain imported craft positioning. Stakeholders must monitor excise recalibrations and licensing threshold modifications as these policy levers determine viable entry scale across the region's fragmented brewery landscape.
Market Dynamics
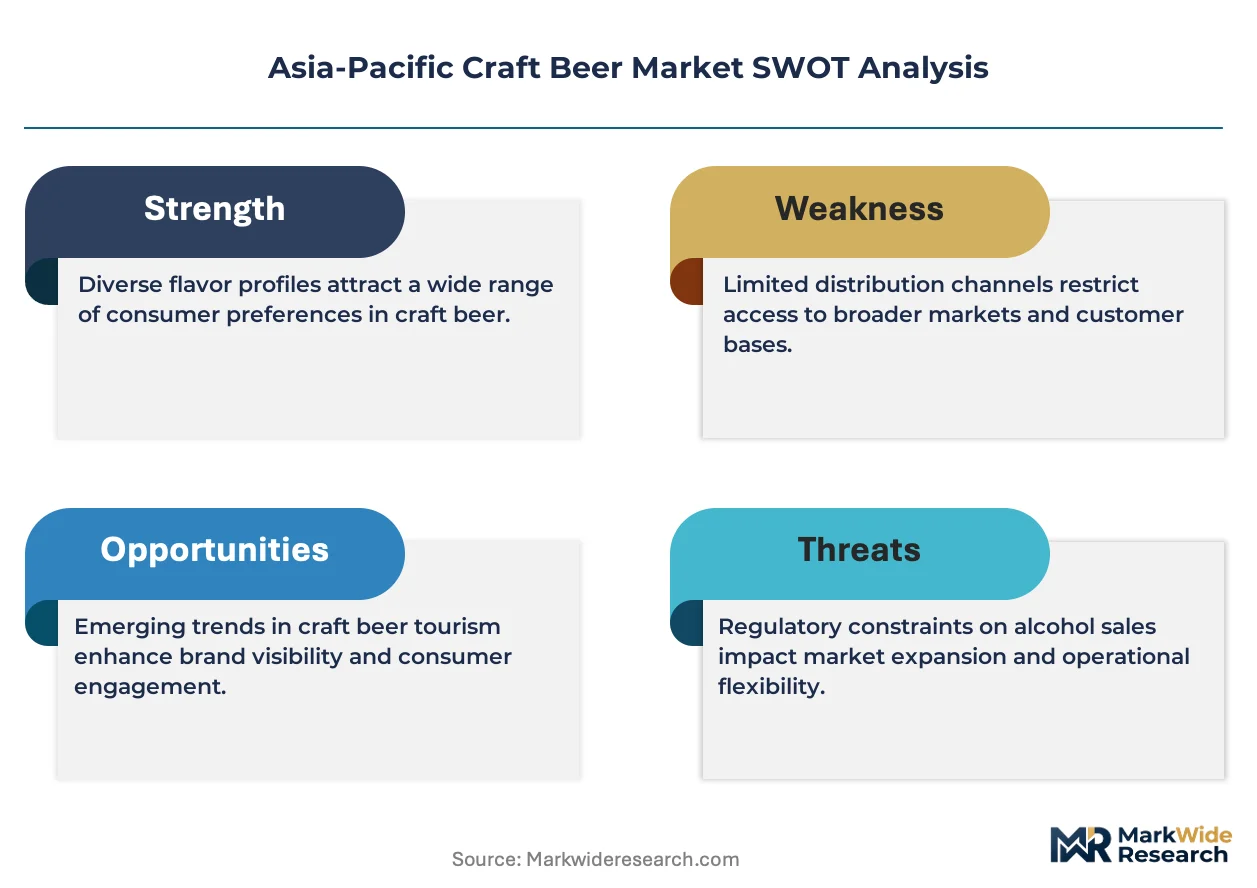
Australia's excise duty recalibration and Japan's Liquor Tax Act revisions are compressing brewery economics while channel fragmentation between on-premise specialty bars and direct-to-consumer platforms restructures go-to-market requirements across the region.
Growth Catalysts
- Urban Millennial Consumption Clusters:Sydney and Shanghai specialty bar networks concentrate demand for experimental hop profiles and limited releases. These venues function as brand incubators before supermarket rollout.
- Canning Line Automation:Mobile canning services and compact in-house lines slash packaging capital requirements for sub-scale producers. This equipment diffusion enables geographic expansion without fixed-asset commitment.
- E-commerce Fulfillment Infrastructure:Cold-chain logistics investments by regional platforms unlock direct shipping from brewery to consumer. Australia's taxation framework permits this channel under specific licensing conditions.
Market Restraints
- Malted Barley Import Dependency:Australian and Japanese brewers source base malt from Canadian and European suppliers. Currency volatility and shipping congestion transmit directly to input cost structures.
- Excise Threshold Compression:Australia's sub-1.5 million liter concessional rate creates a margin cliff at scale. Breweries approaching this threshold face discontinuous cost escalation that distorts capacity planning.
- Sake Substitution in Japan:Premium sake positioning at izakaya chains competes for the same experiential drinking occasion. Sake's domestic provenance advantage resists craft beer penetration in traditional consumption settings.
Strategic Opportunities
- Vietnam's Regulatory Opening:Decree 105 implementation reduces brewery licensing barriers for foreign-invested entities below specified capacity thresholds. Early entrants establish brand equity before market saturation.
- Non-Alcoholic Craft Formats:Controlled fermentation and vacuum distillation technologies enable sub-0.5% ABV products with retained hop character. These formats access daytime and wellness-oriented consumption occasions previously closed to beer.
- Hotel and Airline Private Label:Premium hospitality procurement teams seek exclusive craft partnerships for differentiation. Contract brewing arrangements generate stable volume without consumer marketing expenditure.
Industry Challenges
- Qualified Brewer Talent Scarcity:Institute of Brewing and Distilling certification programs in Australia and Japan produce insufficient graduates for brewery expansion plans. Compensation inflation for experienced head brewers erodes labor cost assumptions.
- Label Compliance Velocity:China's SAMR GB code modifications and Australia's allergen declaration updates require frequent artwork revision. Packaging obsolescence risk intensifies with short-run seasonal releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Craft Beer Market |
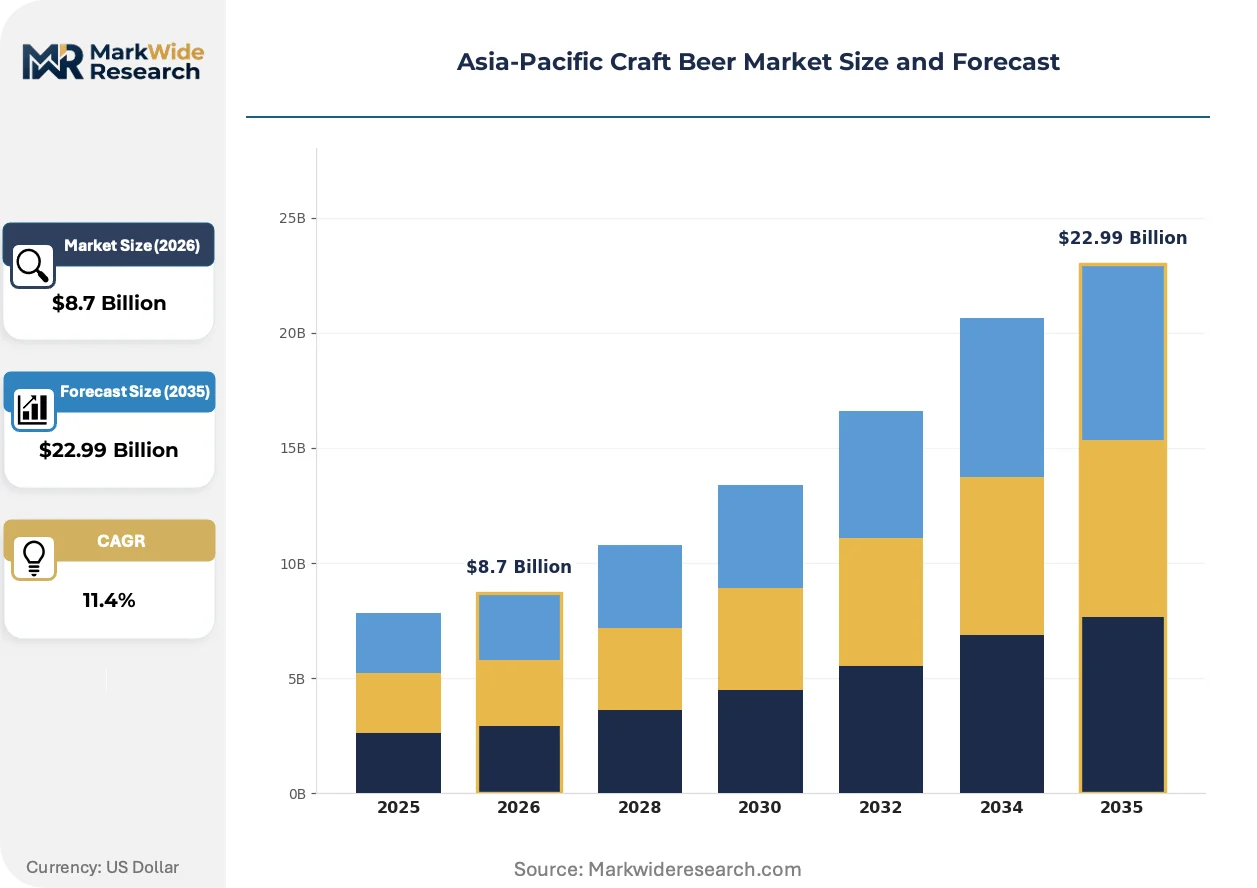
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IPA, Stout, Porter, Lager Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Bars Customer Type: Connoisseurs, Casual Drinkers, Millennials, Tourists Packaging Type: Cans, Bottles, Kegs, Growlers |
| Companies Covered | Kiuchi Brewery Inc., Kirin Holdings Co Ltd, Anheuser-Busch InBev, Stone & Wood Brewing Co., Carlsberg Group, Heineken International B.V., Asahi Breweries Ltd, BrewDog, The Boston Beer Company Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Craft Beer Market Strategic Shifts
Yeast strain banking and hop terroir differentiation are replacing style-category competition as the primary axis of brewery distinctiveness. Technical capability now determines margin sustainability more than marketing expenditure.
Precision fermentation using novel yeast strains is rewriting the economics of specialty beer production. Australian and Japanese breweries deploy proprietary cultures isolated from native botanicals to generate unique ester profiles without exotic ingredient costs. Mid-scale producers adopt this biotechnology fastest, using it to differentiate against multinational craft-adjacent brands with standardized formulations.
Australia's Taxation Office excise recalibration discussions and Japan's National Tax Agency licensing threshold reviews are compressing nano-brewery viability windows. Producers below 500 hectoliters annual output face disproportionate compliance burden relative to revenue. Victoria and New South Wales microbreweries are consolidating through shared service cooperatives to maintain scale efficiency without surrendering brand independence.
Direct subscription models displace traditional wholesale relationships as the primary growth channel for limited releases. Urban consumers in Melbourne and Tokyo pre-commit to quarterly allocations, enabling cash-flow visibility for small-batch planning. This pattern concentrates most visibly among IPA and mixed-fermentation categories where scarcity signaling drives purchase urgency.
Asia-Pacific Craft Beer Market Segmentation
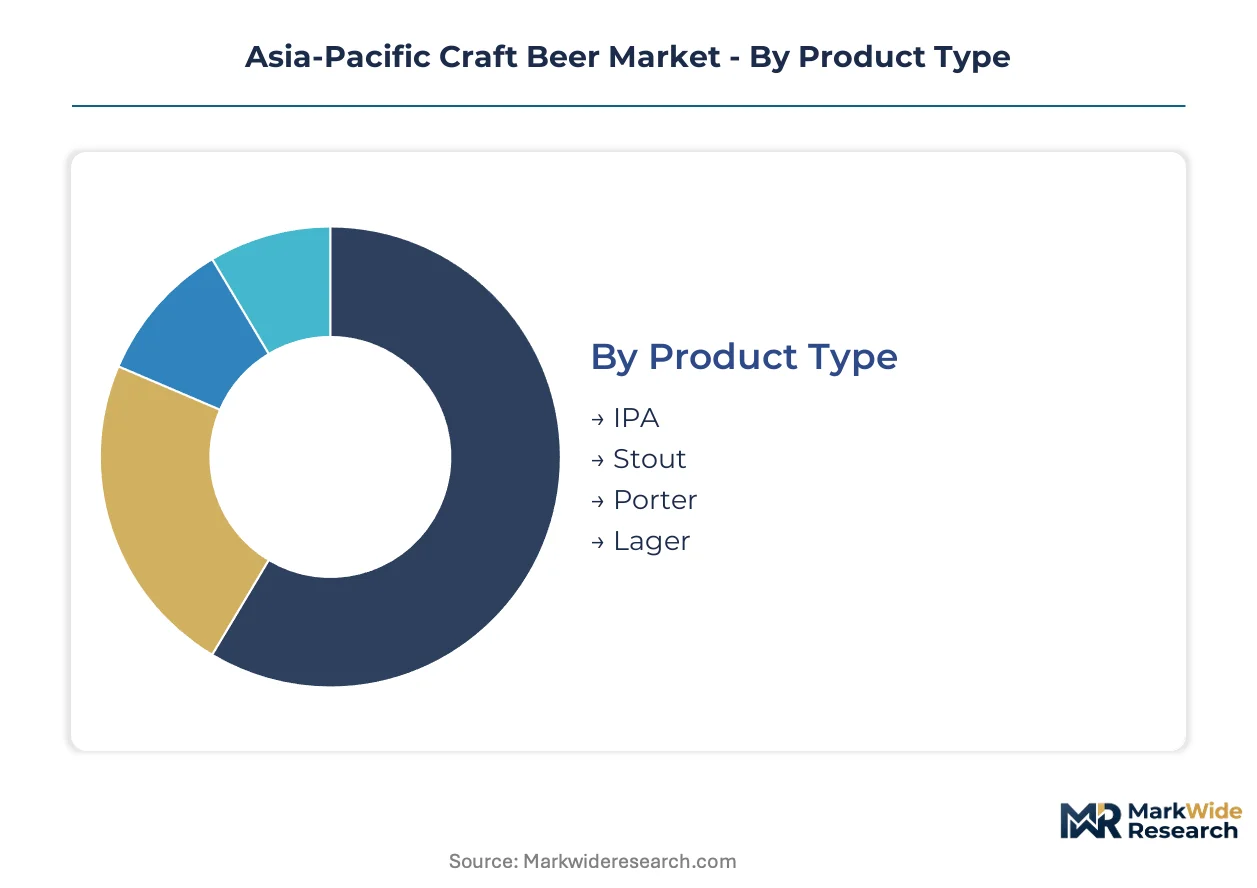
Segmentation in Asia-Pacific craft beer reveals how consumption occasions, purchase contexts, and buyer sophistication create distinct margin profiles. Producers configure brewing schedules, packaging investments, and channel strategies around these divides rather than treating the market as uniform.
Product Type:
Buyer sophistication and flavor adventurousness separate these categories more than price point alone.
- IPA:Hop-forward formulations with elevated bitterness and aromatic intensity dominate experimental consumption in Sydney and Melbourne specialty bars. Demand clusters among connoisseurs seeking limited releases with specific hop varietals, though input cost volatility from Pacific Northwest pellet supply constrains margin stability.
- Stout:Dark-roasted malt profiles with chocolate and coffee notes attract winter seasonal purchasing and food-pairing occasions in Japan's izakaya networks. Tokyo and Osaka venues deploy these as dessert alternatives, with barrel-aged variants commanding significant price premiums.
- Porter:Lower roast intensity than stout with smoother mouthfeel suits entry-level craft transitioners. Shanghai bars position these as accessible introductions for casual drinkers migrating from mass-market lagers.
- Lager:Crisp, clean fermentation profiles with restrained hop character serve volume-oriented supermarket channels. Australia's excise structure favors efficient production at scale for this segment.
Volume sits with Lager; growth tilts toward IPA.
Distribution Channel:
Channel selection determines margin capture versus brand control trade-offs for producers at different scale tiers.
- Online Retail:Direct-to-consumer platforms with cold-chain fulfillment unlock recurring revenue through subscription models. Melbourne and Tokyo consumers pre-commit to quarterly allocations, though Australia's taxation licensing creates compliance complexity for interstate shipping.
- Supermarkets:Mass retail placement demands packaging standardization and volume commitments that favor mid-scale producers with canning line automation. Queensland and New South Wales chains increasingly dedicate shelf space to local craft labels.
- Specialty Stores:Curated bottle shops with temperature-controlled storage serve connoisseur education and discovery missions. Staff recommendations drive trial of experimental styles in Shanghai's French Concession and Sydney's Inner West.
- Bars:On-premise draft consumption concentrates brand experience and margin capture. Victoria's Melbourne and Geelong networks function as incubators before broader rollout.
Margin concentrates in Bars; expansion velocity favors Online Retail.
Customer Type:
Knowledge depth and purchase frequency create distinct service requirements and lifetime value profiles.
- Connoisseurs:Deep style literacy and batch-specific purchasing drive demand for limited releases and brewery-direct relationships. Japan's sake-educated consumers translate analytical tasting frameworks to craft beer evaluation.
- Casual Drinkers:Occasional premium purchases without style allegiance respond to packaging design and occasion-based marketing. Australia's beach culture generates seasonal spikes in accessible formats.
- Millennials:Urban professionals in Sydney and Shanghai integrate craft beer into social identity construction and Instagram-native sharing. Experimental hop profiles and collaborative releases sustain engagement.
- Tourists:Travel-driven trial seeking destination-specific brewing experiences generates one-time volume with low repeat conversion. Queensland's coastal brewery trails capture this segment through location-based discovery.
Lifetime value peaks with Connoisseurs; acquisition economics favor Millennials.
Packaging Type:
Format selection balances portability, shelf-life, and brand signaling for distinct consumption contexts.
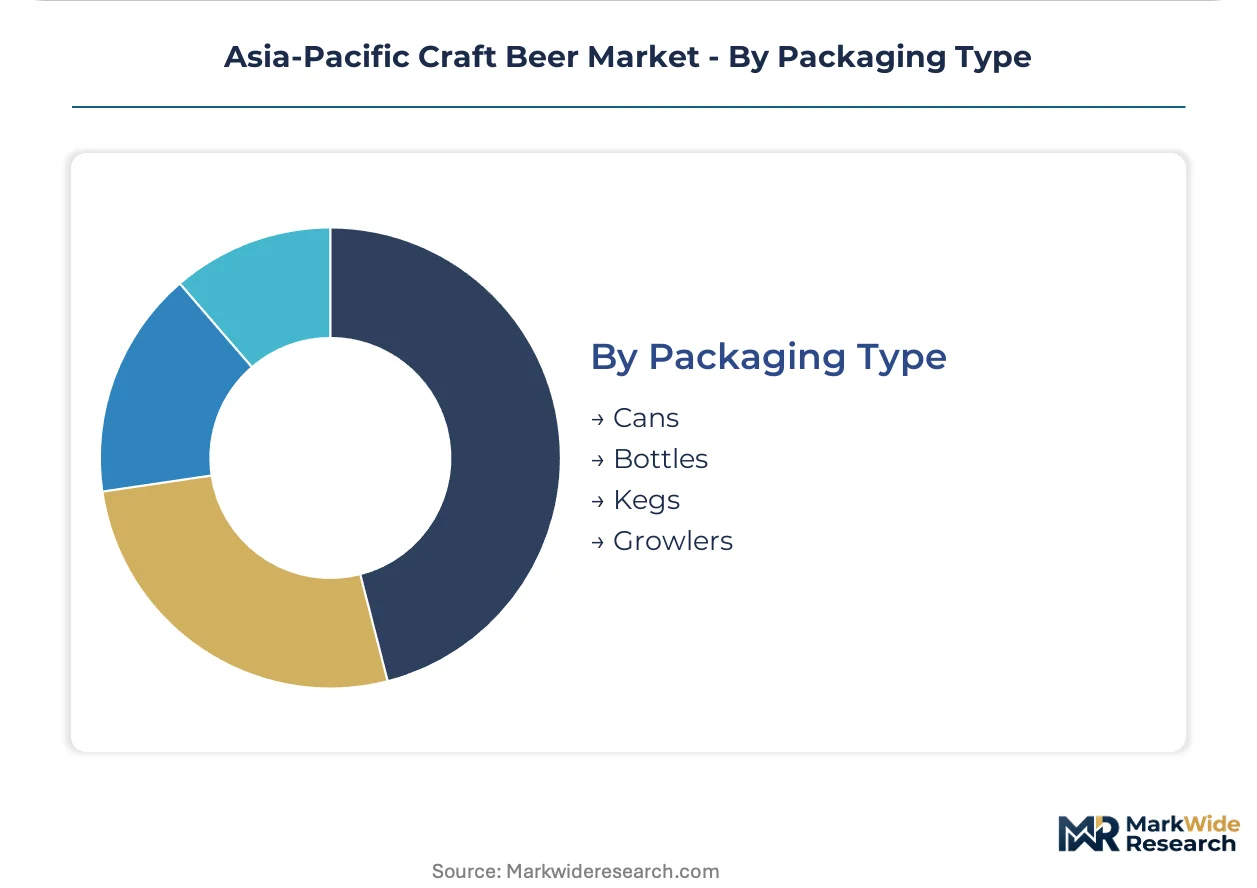
- Cans:Aluminum formats with oxygen barrier technology extend freshness and enable outdoor consumption. Australian producers prioritize this format for online retail fulfillment and festival distribution.
- Bottles:Amber and clear glass variants retain traditional craft aesthetics for specialty store positioning and gift occasions. Japan's premium retail channels favor this format for visual differentiation.
- Kegs:Stainless steel draft containers serve on-premise volume with minimal packaging cost per serving. Victoria's bar networks drive concentrated demand.
- Growlers:Refillable glass or stainless vessels enable brewery-direct freshness for local connoisseurs. Fill stations at Sydney and Melbourne taprooms build community retention.
Production volume concentrates in Kegs; format innovation centers on Cans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malted barley from Canadian prairie provinces and European malting centers anchors Asia-Pacific craft brewing supply chains, with currency fluctuations and maritime logistics transmitting directly to brewery input costs across the region.
Australia
Urban millennials in Sydney and Melbourne drive demand through specialty bar networks and direct-to-consumer subscription platforms. The Australian Taxation Office administers excise duties with concessional rates below 1.5 million liters that compress margins at scale thresholds. Victoria's Geelong corridor and New South Wales microbrewery belts are consolidating through shared-service cooperatives to maintain operational efficiency.
Japan
Sake-educated consumers translate analytical tasting frameworks to craft beer evaluation, supporting premium positioning in Tokyo and Osaka izakaya networks. The National Tax Agency governs brewing licenses with minimum annual output thresholds that disadvantage nano-operations. Kanto and Kansai metropolitan zones concentrate the sake-to-craft transition, with barrel-aged variants commanding significant price premiums.
China
Shanghai's French Concession and Beijing's Sanlitun districts concentrate experimental consumption among internationally exposed professionals. The State Administration for Market Regulation enforces GB labeling standards that constrain imported craft positioning. Yangtze River Delta brewery clusters leverage proximity to specialty malt distributors and temperature-controlled logistics infrastructure.
Vietnam
Ho Chi Minh City and Hanoi hospitality sectors generate demand for destination-specific brewing experiences among domestic and expatriate consumers. Decree 105 implementation reduces brewery licensing barriers for foreign-invested entities below specified capacity thresholds. Southern Mekong Delta provinces are attracting early entrants establishing brand equity before market saturation.
South Korea
Seoul's Gangnam and Hongdae districts concentrate craft beer consumption among younger demographics seeking social differentiation through beverage choice. The Ministry of Food and Drug Safety regulates alcohol labeling and advertising restrictions that shape marketing approaches. Seoul Capital Area microbreweries are expanding canning line automation to serve online retail channels with cold-chain fulfillment.
Asia-Pacific Craft Beer Market Competitive Environment
Global majors compete with regional champions across distribution network depth and brand portfolio breadth, creating a tiered structure where scale advantages in logistics clash with local authenticity signaling. Multinational beverage conglomerates leverage existing wholesale relationships and supermarket shelf access, while independent operators concentrate margin in on-premise draft and direct subscription channels. Three archetypes dominate: heritage Japanese brewers with sake lineage credibility, Australian coastal independents with terroir-based positioning, and multinational craft-adjacent brands with standardized formulations. Competitive moves center on minority stake acquisitions in regional operators and canning line automation investments that reduce packaging capital requirements.
Among Japan-based heritage operators, Kiuchi Brewery Inc. and Asahi Breweries Ltd occupy positions at opposite ends of the scale spectrum, with the former exemplifying premium craft authenticity and the latter representing mass-market adjacency strategies. Stone & Wood Brewing Co. anchors the Australian independent tier, demonstrating how coastal Queensland distribution networks can sustain niche dominance against multinational inroads. These three entities represent the core competitive tension between provenance-based differentiation and scale-driven efficiency that defines regional market structure.
| Leading Market Players |
|---|
| Kiuchi Brewery Inc. |
| Kirin Holdings Co Ltd |
| Anheuser-Busch InBev |
| Stone & Wood Brewing Co. |
| Carlsberg Group |
| Heineken International B.V. |
| Asahi Breweries Ltd |
| BrewDog |
| The Boston Beer Company Inc. |
| Others |
Value Chain & Pricing Dynamics
Canning line automation diffusion across Australian and Japanese microbreweries compresses per-unit packaging costs while simultaneously redistributing supply power toward mobile canning service providers and compact equipment manufacturers. This capital-light production transition enables sub-scale producers to bypass fixed-asset commitments, reshaping margin economics and supplier relationships across the Asia-Pacific brewing landscape.
Pricing Analysis
Service bundling separates premium positioning from transactional tiers, with barrel-aged variants and brewery-direct subscriptions including educational tastings while supermarket placements strip these experiential components. Three-tier pricing structure across premium, standard, and economy levels reflects alcohol-by-volume specifications and hop varietal rarity, with IPA and mixed-fermentation categories commanding scarcity premiums. Pricing pressure stems from Australia's excise duty recalibration discussions and Japan's licensing threshold reviews that compress nano-brewery viability. Casual drinkers migrating from mass-market lagers exhibit highest price sensitivity, while sake-educated connoisseurs in Tokyo demonstrate lowest elasticity for provenance-authenticated releases.
Supply Chain Analysis
Direct-to-consumer channels with cold-chain fulfillment handle connoisseur demand for limited releases, while supermarket distributors manage volume-oriented lager flows through Queensland and New South Wales retail networks. Malted barley concentrates in Canadian prairie provinces and European malting centers, with Australian and Japanese brewers drawing from these distant suppliers. Hop pellets from Pacific Northwest regions and specialty yeast strains from proprietary banks constitute critical input dependencies. Single-source vulnerability runs through maritime logistics chokepoints connecting North American grain exporters to Asia-Pacific ports. Currency volatility transmits directly to brewery input cost structures, amplifying margin instability for sub-scale producers without forward-contract coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation using novel yeast strains is displacing conventional style-category competition as the primary axis of brewery distinctiveness, with biotechnology-enabled flavor differentiation replacing marketing expenditure as the margin sustainability driver. This transition rewards technical capability investment over brand-building outlays across the Asia-Pacific craft brewing landscape.
For Market Incumbents: To counter multinational craft-adjacent brands with standardized formulations, Kiuchi Brewery Inc. and Stone & Wood Brewing Co. should deepen proprietary yeast strain banking and native botanical isolation programs. Backward integration into hop terroir development through direct farmer partnerships in Victoria and coastal Queensland secures supply continuity. Channel control through exclusive specialty bar networks in Sydney and Melbourne insulates premium positioning from supermarket price erosion.
For New Entrants and Emerging Players: Capture Vietnam's regulatory opening under Decree 105 implementation, where reduced licensing barriers for foreign-invested entities below specified capacity thresholds enable first-mover brand equity establishment before Ho Chi Minh City market saturation. Target non-alcoholic craft formats using controlled fermentation technologies to access daytime and wellness-oriented consumption occasions previously closed to beer. Deploy direct subscription models with quarterly pre-commitment allocations to bypass wholesale margin capture.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale Australian independents possessing canning line automation and coastal terroir positioning given excise recalibration catalysts compressing nano-operation economics. Long-term viability over the coming decade favors producers with technical biotechnology capabilities and shared-service cooperative structures maintaining operational efficiency without brand independence surrender. Monitor Australia's Taxation Office excise threshold modifications and Japan's National Tax Agency licensing reviews as inflection indicators for consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Yeast Strain Banking Investment | Proprietary cultures from native botanicals generate unique ester profiles without exotic ingredient cost burdens. |
| Shared-Service Cooperative Formation | Victoria and New South Wales microbreweries consolidate operations to maintain scale efficiency without brand surrender. |
| Direct-to-Consumer Subscription Launch | Melbourne and Tokyo consumers pre-commit to quarterly allocations, enabling cash-flow visibility for small-batch planning. |
| Mobile Canning Service Partnership | Equipment diffusion enables geographic expansion without fixed-asset commitment for sub-scale producers. |
| Non-Alcoholic Format Development | Sub-0.5% ABV products with retained hop character access wellness-oriented consumption occasions. |
Study Parameters
Trade association filings, excise duty administrative records, and brewing license registries formed the secondary backbone, supplemented by customs data tracking malted barley and hop pellet import flows. Head brewers, specialty bar proprietors in Sydney and Shanghai, Australian Taxation Office excise administrators, and Japan National Tax Agency licensing officials provided primary interview validation. Bottom-up brewery capacity surveys triangulated against top-down consumption estimates from on-premise and off-trade channel audits.
Historical production volume and value trendlines across IPA, Stout, Porter, and Lager categories established baseline growth patterns over the projection horizon. Segmentation modeling incorporated product type, distribution channel, customer sophistication tier, and packaging format dimensions. CAGRs derived from fitted growth curves applied to brewery-level capacity expansion plans and channel shift assumptions, with input cost volatility from currency fluctuations and shipping congestion incorporated as scenario variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Australia's excise recalibration timing and Japan's Liquor Tax Act revision implementation. Base assumptions reflect continued urban millennial demand concentration in Sydney and Shanghai, with alternative scenarios testing sake substitution resilience and multinational acquisition activity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Alcoholic Ice Cream Market
Alcoholic Beverages
Beer Pasteurization Equipment Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Cordial Drink Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market