
 Aircraft Air Conditioning Unit Market | 2026-2036
Aircraft Air Conditioning Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Air Conditioning Unit Market Analysis
Leasing-heavy fleet modernization is narrowing the supplier base for air conditioning retrofits and line-fit installations. Honeywell International Inc. leverages its integrated environmental control systems portfolio to dominate cockpit and cabin cooling architectures. Liebherr-International AG sustains European airframer relationships through specialized heat exchanger and air management units. Collins Aerospace anchors North American aftermarket channels with MRO-certified vapor compression overhaul capabilities.
An aircraft air conditioning unit is a self-contained thermal management system that regulates cabin temperature, humidity, and air quality through vapor compression or electromechanical refrigeration cycles, typically operating at altitudes up to 45,000 feet with bleed-air or electrically driven compressors. Its primary purpose is maintaining occupant safety and comfort while managing avionics heat loads in pressurized fuselage environments. Fixed units command the largest installed base across commercial aviation platforms where OEM specification locks create long replacement cycles. Vapor compression systems lead technology adoption due to mature efficiency profiles, though hybrid systems are gaining traction as airframers pursue more electric aircraft architectures. Portable units occupy a niche in military and cargo ground support applications where rapid deployment flexibility outweighs integration complexity.
FAA airworthiness directives and EPA Significant New Alternatives Policy standards are jointly tightening refrigerant chemistries and leak-rate thresholds for cabin cooling equipment. EASA CS-25 certification requirements and EU F-Gas Regulation phase-down schedules are pushing European suppliers toward lower-global-warming-potential working fluids and sealed-system designs. Stakeholders must monitor electrification roadmaps from major airframers to determine whether bleed-air-dependent architectures will cede share to electrically driven compressors in next-generation single-aisle programs.
Market Dynamics
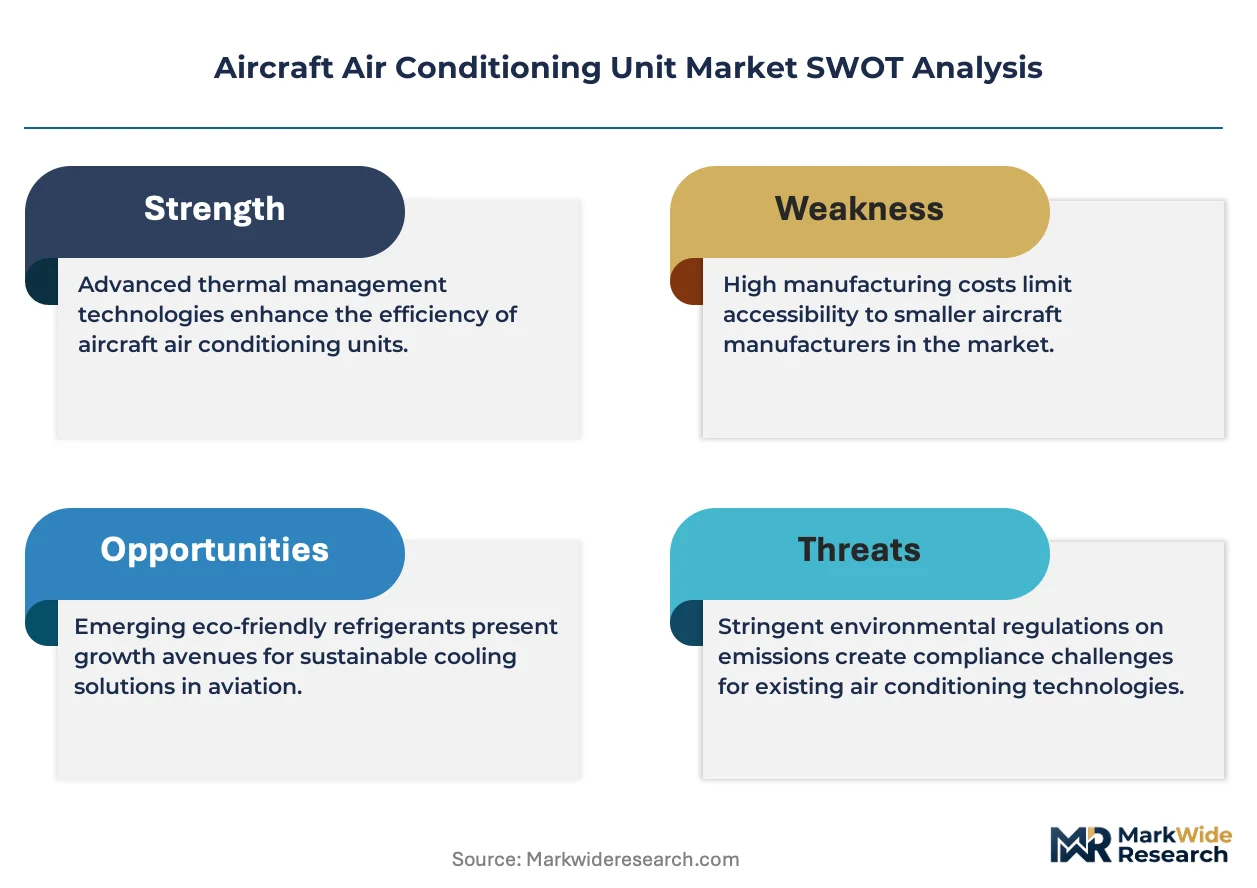
Bleed-air-to-electric compressor transitions are fragmenting established supplier relationships as airframers redesign thermal architectures for more electric aircraft programs. This shift compresses development cycles while elevating power electronics expertise above traditional pneumatic engineering.
Growth Catalysts
- Single-aisle fleet expansion:Narrow-body production rates at Boeing's Charleston and Airbus's Mobile facilities are pulling line-fit air conditioning contracts. These platforms require lighter vapor compression units with integrated power electronics.
- F-Gas Regulation phase-down:The EU's refrigerant restrictions are accelerating R&D investment in lower-global-warming-potential working fluids across European supply chains. Sealed-system designs are gaining preference over serviceable architectures.
- Heat exchanger material advances:Additive manufacturing of aluminum-lattice core structures is reducing unit weight while maintaining thermal transfer efficiency. Tier-2 suppliers in Germany and Japan are commercializing these processes.
Market Restraints
- Specialized aluminum alloy supply:Aviation-grade 6061-T6 and 7075-T6 sheet stock faces allocation pressure from competing aerospace programs. Spot pricing volatility exceeds 15% annually.
- OEM specification lock-in:Type certificates tie operators to original equipment configurations, limiting aftermarket retrofit flexibility. FAA Parts Manufacturer Approval timelines extend 18-24 months for alternative designs.
- Refrigerant chemistry constraints:EPA SNAP restrictions on high-GWP hydrofluorocarbons are forcing premature obsolescence of established compressor architectures. Inventory write-downs concentrate among legacy system specialists.
Strategic Opportunities
- Urban air mobility thermal management:eVTOL platforms require compact, high-cycle air conditioning with minimal power draw. Battery thermal integration creates specification openings outside traditional aviation supply bases.
- Indian MRO infrastructure buildout:GMR Aero Technic and Air Works India are expanding narrow-body overhaul capacity near Bangalore and Hyderabad. Local component sourcing mandates favor joint ventures with domestic metal fabrication networks.
- More electric aircraft roadmaps:Boeing's 2030 electrification targets and Airbus's ZEROe concepts are specifying distributed compressor architectures. Bleed-air elimination enables entirely new packaging and control strategies.
Industry Challenges
- Power electronics integration:Motor controller and inverter design expertise resides predominantly in automotive and industrial sectors. Aviation-specific electromagnetic interference certification requires 24-36 month qualification cycles.
- CS-25 cabin air quality compliance:EASA's ozone and VOC concentration limits demand enhanced filtration and catalytic converter integration. Test protocol complexity is extending development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Air Conditioning Unit Market |
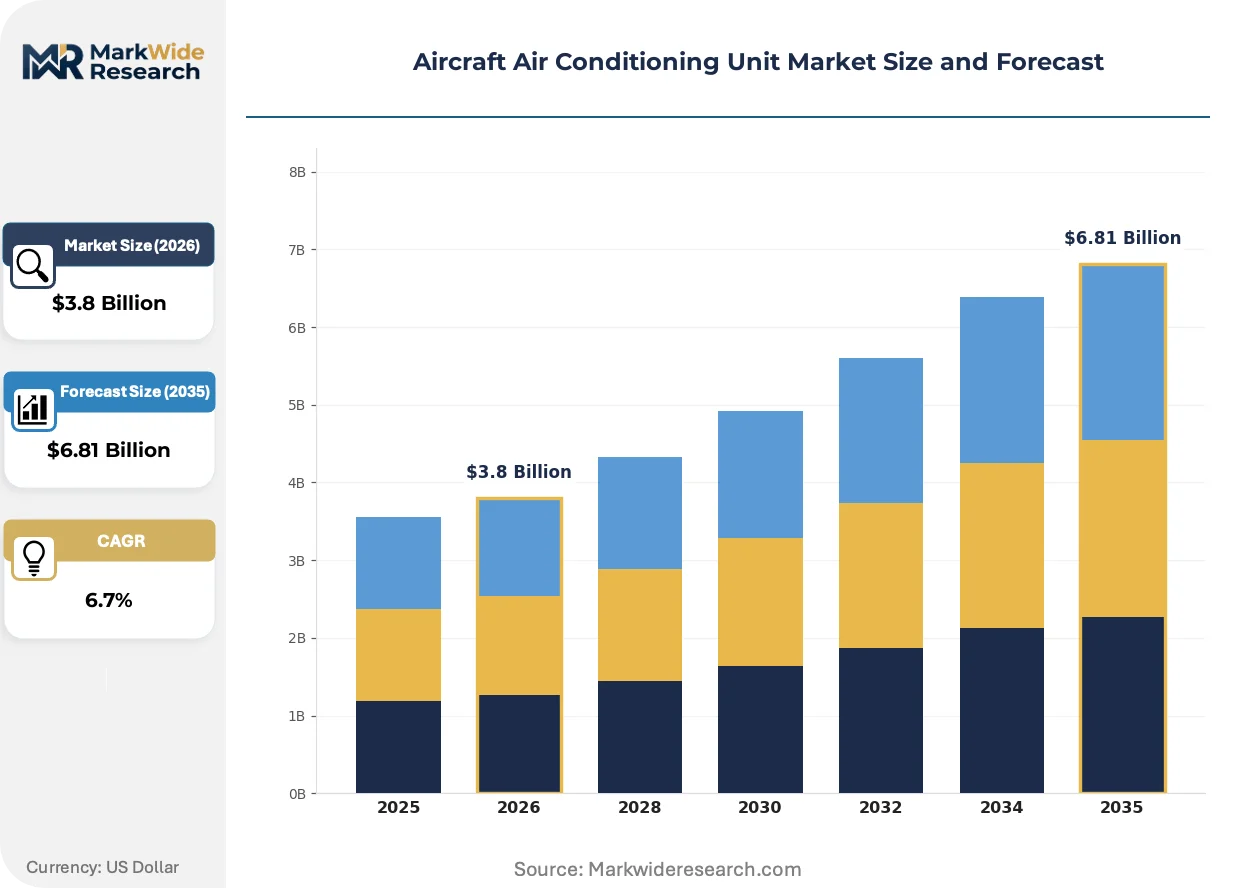
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Fixed Units, Split Systems, Centralized Systems End User: Commercial Aviation, Military Aviation, Private Aviation, Cargo Aviation Technology: Electromechanical Systems, Vapor Compression Systems, Absorption Systems, Hybrid Systems Application: Cabin Cooling, Cockpit Cooling, Air Quality Control, Refrigeration |
| Companies Covered | Honeywell International Inc., Liebherr-International AG, Collins Aerospace, Parker Hannifin, Safran, Mitsubishi Heavy Industries, JBT Corporation, Meggitt PLC, United Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Air Conditioning Unit Market Emerging Trajectories
Digital twin-based thermal modeling is compressing prototype validation cycles while enabling predictive maintenance integration. These capabilities are redefining supplier value propositions beyond hardware provision.
Electromechanical vapor compression is virtualizing traditional pneumatic distribution networks through distributed compressor nodes. Regional jet and turboprop operators are adopting these architectures for fuel burn reduction. The technology is virtualizing centralized bleed-air manifold designs into modular, fault-tolerant configurations with reduced ducting weight.
EPA SNAP and EU F-Gas Regulation convergence is harmonizing refrigerant approval pathways across transatlantic markets. Dual-certification requirements are elevating compliance costs for mid-tier suppliers while consolidating specification authority among integrated environmental control system providers. Wide-body platform retrofits face the steepest reformulation timelines as operators balance regulatory deadlines against residual asset values.
Airline technical procurement teams are unbundling overhaul services from original equipment contracts. Low-cost carriers in Southeast Asia and Latin America are driving this fragmentation through competitive tendering of MRO events. The shift is most pronounced among narrow-body fleets where standardized components enable multi-source maintenance strategies.
Aircraft Air Conditioning Unit Market Segmentation
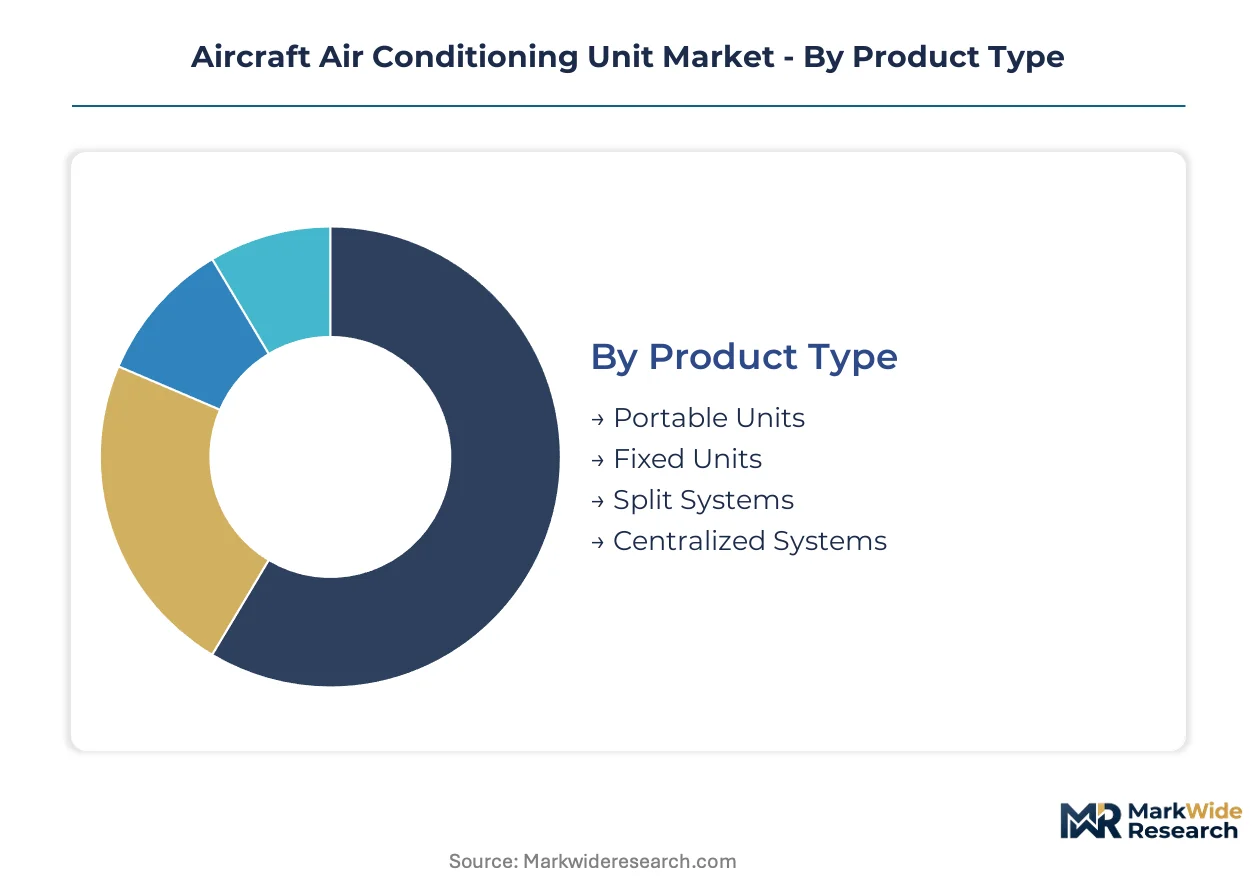
Aircraft air conditioning architectures fragment across installation permanence, operator mission profiles, thermodynamic cycles, and thermal load zones. Each segmentation axis reveals distinct specification requirements, certification pathways, and supplier capability thresholds that shape procurement decisions across OEM line-fit and aftermarket retrofit channels.
Product Type:
Installation permanence spans ground-support mobility through fully integrated fuselage-embedded systems, with weight, power draw, and maintenance access driving platform-specific selection.
- Fixed Units:Permanently installed vapor compression systems with brazed aluminum heat exchangers and hermetic compressors dominate narrow-body and wide-body production lines. Boeing's Charleston and Airbus's Mobile final assembly facilities specify these units for line-fit integration, where OEM specification locks extend replacement cycles and concentrate aftermarket revenue among MRO-certified providers.
- Portable Units:Self-contained electromechanical carts with onboard power generation serve military forward operating bases and cargo ramp operations where aircraft auxiliary power unit availability is constrained. Demand clusters in United States defense procurement and Middle East cargo hubs where rapid deployment flexibility outweighs integration efficiency penalties.
- Split Systems:Separated evaporator and condenser modules connected by refrigerant lines enable customized packaging in regional jet and business aircraft with constrained avionics bay volumes.
- Centralized Systems:Single-point distribution architectures with zone-controlled mixing valves serve VIP and head-of-state aircraft requiring cabin-wide temperature uniformity.
The dominant share belongs to Fixed Units, while Portable Units are closing the gap fastest through defense modernization programs and cargo fleet expansion.
End User:
Operator mission profiles generate divergent thermal load signatures, duty cycle requirements, and regulatory oversight intensity that reshape supplier qualification criteria.
- Commercial Aviation:Scheduled airline operations with high-cycle utilization and passenger density specifications drive demand for lightweight, high-reliability vapor compression with integrated ozone converters. FAA Part 25 and EASA CS-25 certification requirements mandate redundant capacity and emergency smoke evacuation protocols that elevate development costs.
- Military Aviation:Tactical platforms with electromagnetic interference hardening, nuclear-biological-chemical filtration integration, and austere field maintenance requirements specify militarized environmental control systems. United States Department of Defense procurement through Warner Robins Air Logistics Complex and Tinker Air Force Base sustain specialized supplier ecosystems.
- Private Aviation:Business jet and helicopter operators prioritize compact packaging, reduced acoustic signature, and premium cabin humidity control for extended-range missions.
- Cargo Aviation:Dedicated freighter operations with minimal passenger loads but substantial avionics cooling demands favor simplified architectures with reduced redundancy and extended maintenance intervals.
Commercial Aviation commands the largest installed base, though Military Aviation exhibits the steepest specification divergence from civilian architectures.
Technology:
Thermodynamic cycle selection reflects the tension between mature efficiency profiles and emerging electrification roadmaps across airframe development programs.
- Vapor Compression Systems:Refrigerant-based mechanical compression with electrically driven or engine-bleed-powered compressors delivers the highest coefficient of performance for pressurized cabin cooling. EPA SNAP and EU F-Gas Regulation restrictions on high-global-warming-potential hydrofluorocarbons are forcing refrigerant reformulation investments among legacy suppliers.
- Hybrid Systems:Combined vapor compression and solid-state thermoelectric modules enable distributed cooling architectures for more electric aircraft programs. Airbus's ZEROe concept studies and Boeing's 2030 electrification targets specify these systems to eliminate pneumatic bleed-air dependencies.
- Electromechanical Systems:All-electric compressor and fan arrays with silicon carbide power electronics serve urban air mobility platforms with severe weight and power budget constraints.
- Absorption Systems:Heat-activated refrigerant cycles using lithium bromide or ammonia-water working pairs occupy niche applications where waste heat recovery improves overall thermal efficiency.
Vapor Compression Systems retain specification dominance, yet Hybrid Systems are expanding most quickly through next-generation single-aisle development programs.
Application:
Thermal load zones within the aircraft impose distinct temperature setpoint, humidity, and air exchange rate requirements that drive subsystem specialization.
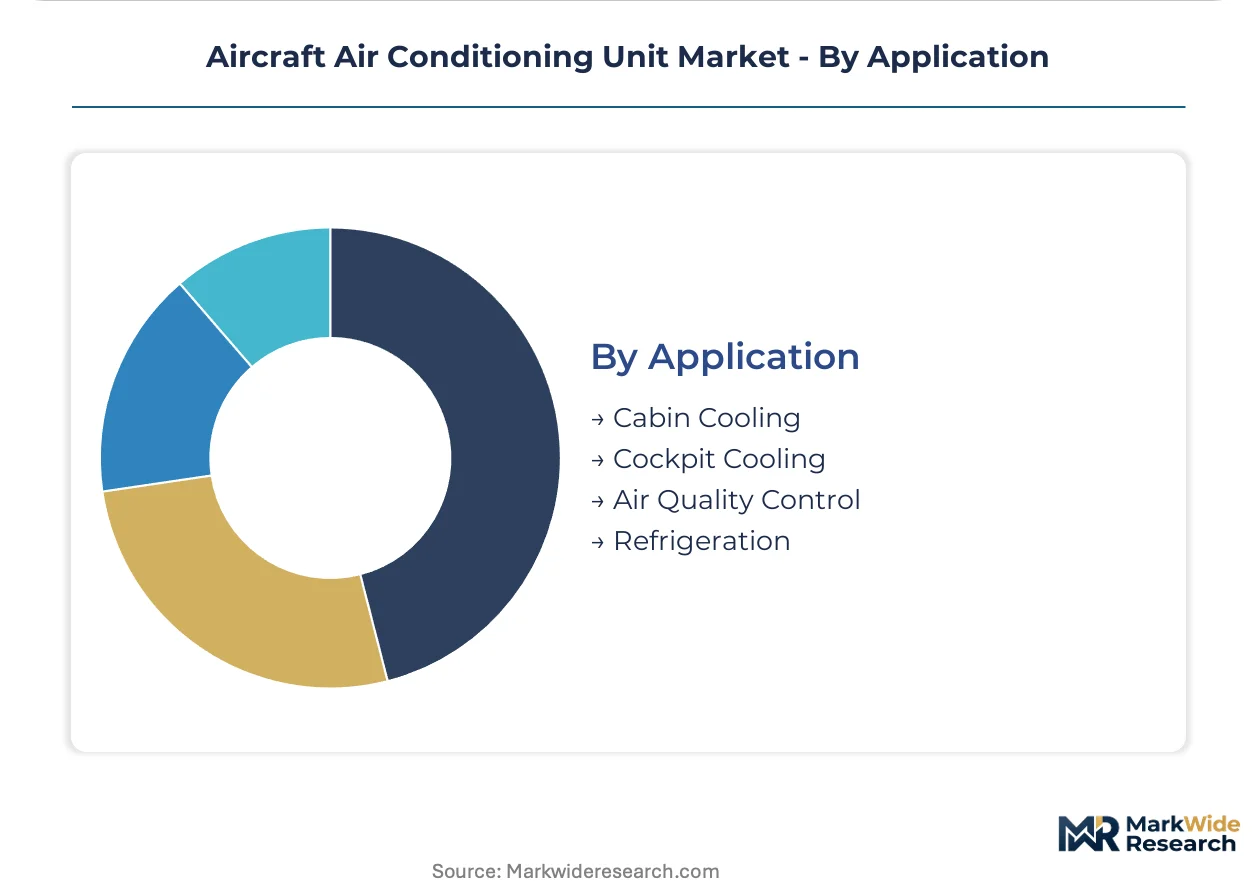
- Cabin Cooling:Passenger zone temperature and humidity regulation with 55-75°F setpoint range and 20-50% relative humidity targets requires the highest capacity and zone control granularity. Narrow-body operators in United States, Germany, and China specify these systems for 180-230 passenger capacities with 15-20 air changes per hour.
- Cockpit Cooling:Aviator thermal comfort with enhanced ozone and VOC filtration, plus dedicated electronics cooling for flight deck displays and communication suites, demands precision temperature control within ±2°F tolerance. FAA human factors requirements and EASA pilot incapacitation prevention standards mandate independent redundancy.
- Air Quality Control:Integrated filtration, catalytic oxidation, and pressure regulation subsystems managing particulate, gaseous contaminant, and cabin altitude specifications.
- Refrigeration:Galley cold storage and medical supply preservation through dedicated vapor compression or thermoelectric cold plates in long-haul and VIP configurations.
Cabin Cooling represents the largest capacity installation, while Cockpit Cooling commands the highest specification density per thermal kilowatt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing economies with aerospace tier-1 presence, while emerging MRO hubs in South Asia and the Middle East reshape service-flow patterns. The United States maintains surplus in integrated environmental control systems, offset by component imports from precision manufacturing centers in Germany and Japan.
United States
Boeing's Charleston final assembly line and Wichita's general aviation cluster sustain line-fit demand for vapor compression architectures. FAA airworthiness directives on refrigerant leak rates and EPA SNAP restrictions on high-GWP hydrofluorocarbons are tightening compliance timelines for legacy fleet retrofits. Seattle-Tacoma-Bellevue corridor hosts concentrated MRO infrastructure serving Alaska Airlines, Delta, and cargo operators with narrow-body overhaul capacity.
Germany
Airbus Hamburg final assembly and Liebherr's Lindenberg operations anchor European demand for heat exchanger-integrated air management units. EU F-Gas Regulation phase-down schedules and EASA CS-25 certification requirements are accelerating sealed-system designs over serviceable architectures. Bavaria's precision metalworking networks supply additive-manufactured aluminum-lattice cores to Tier-1 system integrators.
China
COMAC C919 production ramp-up at Shanghai Pudong and expanding Hainan Airlines narrow-body fleets are pulling localized sourcing requirements. MIIT civil aviation equipment certification and GB standards on cabin air quality are harmonizing with EASA technical guidance. Tianjin's aerospace industrial zone hosts joint ventures targeting MRO certification for regional operators.
India
IndiGo and Air India fleet expansion with A320neo family aircraft is concentrating line-fit procurement decisions with European OEMs. DGFT local content mandates and PLI scheme incentives for aerospace components are pressuring joint venture structures. Bangalore-Hyderabad corridor's GMR Aero Technic and Air Works India facilities are building narrow-body overhaul capacity with domestic metal fabrication sourcing requirements.
United Arab Emirates
Emirates and Etihad wide-body fleet scale sustains premium aftermarket demand for integrated environmental control system overhauls. GCAA airworthiness regulations aligned with EASA standards are elevating certification requirements for alternative refrigerant architectures. Dubai South's aerospace cluster hosts third-party MRO providers serving African and South Asian transit traffic.
Aircraft Air Conditioning Unit Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in heat exchanger, compressor, and power electronics supply. The supplier base concentrates around three to five integrated environmental control system providers with FAA and EASA design organization approvals, while Tier-2 and Tier-3 fabrication networks fragment across precision metalworking regions. Two strategic archetypes dominate: diversified aerospace conglomerates with cockpit-to-cabin thermal portfolios, and focused environmental control specialists with deep airframer relationships. Competitive moves center on electrification roadmap alignment with Boeing and Airbus more-electric aircraft programs, and MRO channel consolidation through airworthiness certification stacking.
Among diversified conglomerates with integrated portfolios, Honeywell International Inc., Liebherr-International AG, and Collins Aerospace occupy positions spanning vapor compression system design, certification, and aftermarket service. These entities exemplify the platform-integrator archetype through their presence across multiple thermal management subsystems and regulatory jurisdictions. Their geographic footprints—United States, Switzerland, and United States respectively—mirror the concentration of final assembly and MRO infrastructure in North America and Western Europe. The competitive terrain rewards entities with simultaneous FAA Parts Manufacturer Approval and EASA Design Organization Approval, creating qualification barriers for mid-tier entrants.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Liebherr-International AG |
| Collins Aerospace |
| Parker Hannifin |
| Safran |
| Mitsubishi Heavy Industries |
| JBT Corporation |
| Meggitt PLC |
| United Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
Aluminum alloy allocation pressure from competing aerospace programs determines both pricing tier spreads and supply chain shape in aircraft air conditioning unit procurement. Spot pricing volatility exceeding fifteen percent annually compresses margins for Tier-2 fabricators while concentrating bargaining power among integrated system providers with captive metal sourcing.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across premium, standard, and economy tiers. Price differentiation hinges on FAA Parts Manufacturer Approval certification grade and after-sales service bundling with MRO-certified overhaul networks. Cost compression in standard-tier vapor compression units is intensifying because refrigerant chemistry reformulation forces premature architecture obsolescence. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while head-of-state and VIP aircraft operators demonstrate least sensitivity due to specification rigidity.
Supply Chain Analysis
Aviation-grade aluminum sheet stock draws from precision rolling mills in Germany, Japan, and the United States. Supply rests on brazed heat exchanger cores, hermetic compressor assemblies, and silicon carbide power electronics modules. Single-source vulnerability concentrates in additive-manufactured aluminum-lattice core structures where Tier-2 suppliers in Bavaria and Osaka commercialize proprietary processes. Distribution runs through Boeing's Charleston and Airbus's Mobile final assembly facilities, with aftermarket channels consolidating around Seattle-Tacoma-Bellevue and Hamburg MRO clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against electrically driven compressor architectures that threaten to displace established bleed-air-dependent supplier relationships. Electrification roadmaps from Boeing and Airbus are accelerating specification divergence that incumbents must navigate through preemptive capability investment.
For Market Incumbents: Pre-empt obsolescence by securing silicon carbide power electronics design partnerships outside traditional pneumatic engineering bases. Backward integration into additive-manufactured heat exchanger cores defends margin position against aluminum alloy spot pricing volatility. Electrification expertise acquisition in automotive and industrial motor controller sectors addresses the twenty-four to thirty-six month FAA electromagnetic interference certification gap.
For New Entrants and Emerging Players: Pursue urban air mobility thermal management specifications where eVTOL battery thermal integration creates openings outside established aviation supply bases. Indian MRO infrastructure buildout near Bangalore and Hyderabad offers the most penetrable geography given DGFT local content mandates and PLI scheme incentives. Joint venture structures with domestic metal fabrication networks provide the essential go-to-market angle for component qualification.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors diversified environmental control system providers with simultaneous FAA and EASA design organization approvals. Long-term viability over the next decade hinges on electrification roadmap alignment with more-electric aircraft programs. Acquisition target archetypes include Tier-2 heat exchanger specialists with additive manufacturing capabilities and power electronics firms with aviation electromagnetic interference qualification progress. The signal to watch is Airbus ZEROe concept study specifications for distributed compressor architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Roadmap Alignment | Boeing's 2030 targets and Airbus ZEROe concepts specify distributed compressor architectures eliminating bleed-air dependencies. |
| Refrigerant Chemistry Reformulation | EPA SNAP and EU F-Gas Regulation convergence forces R&D investment in lower-global-warming-potential working fluids. |
| Additive Manufacturing Scale-Up | Aluminum-lattice core commercialization by Bavarian and Osaka Tier-2 suppliers reduces unit weight while maintaining thermal transfer. |
| MRO Channel Consolidation | Airworthiness certification stacking through Seattle-Tacoma-Bellevue and Hamburg clusters captures aftermarket revenue concentration. |
| Joint Venture Localization | GMR Aero Technic and Air Works India partnerships satisfy DGFT mandates while accessing narrow-body overhaul demand. |
Methodological Framework
The analysis maps vapor compression architectures, hybrid electromechanical systems, and solid-state thermoelectric modules, each validated through environmental control system engineering directors, airline technical procurement managers, MRO facility operations heads, and FAA certification specialists. Primary interview insights triangulate against EASA CS-25 certification databases, EPA SNAP refrigerant approval filings, customs trade data for aviation-grade aluminum alloys, and SEC 10-K disclosures from integrated system providers. Bottom-up unit economics from heat exchanger fabrication through final assembly converge with top-down fleet expansion projections across narrow-body and wide-body production lines.
Assumptions hold fixed current FAA and EASA regulatory timelines while varying electrification adoption rates across the projection horizon. The analytical framework models product type, end user mission profile, thermodynamic cycle technology, and thermal load zone application dimensions. CAGRs derive from production rate trajectories at Boeing Charleston and Airbus Mobile, fleet retirement schedules, and retrofit cycle timing for refrigerant compliance. Industry-specific forecast inputs include bleed-air-to-electric transition speed and F-Gas Regulation phase-down enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in aviation fuel price cycles, interest rate environments affecting airline fleet financing, or aluminum commodity pricing would shift the trajectory. Forecasts reflect assumptions about regulatory harmonization between EPA and EU frameworks and airframer electrification commitment durability. Cross-checking against IATA passenger traffic recovery benchmarks and OEM delivery backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Environment Control
Gas Turbine Air Filtration Market
Aircraft Environment Control
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market
Aircraft Environment Control
Aircraft Waste Tank Market
Aircraft Environment Control
Ice Protection Systems Market
Aircraft Environment Control
Commercial Aircraft Air Management System Market
Aircraft Environment Control
Turbine Air Filtration Market
Aircraft Environment Control
Airborne Molecular Contamination Control Services Market
Aircraft Environment Control
Aerospace Flight Control System Market