

Aircraft Exterior Thermal Gradient Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Exterior Thermal Gradient Monitoring Systems Market Insights
Defense contractors are redrawing procurement priorities for thermal gradient monitoring, while commercial OEMs scale back near-term orders. Honeywell International leverages its integrated avionics portfolio to bundle thermal sensing with flight management systems. RTX sustains dual-use engineering pipelines that serve both military fighter programs and civilian helicopter retrofits. Safran anchors European supply chains through its specialized sensor manufacturing footprint in France.
Aircraft exterior thermal gradient monitoring systems comprise distributed sensor networks measuring surface temperature differentials across wings, fuselage sections, and control surfaces, typically operating from -55°C to +85°C with millikelvin resolution to detect ice formation, thermal fatigue, and boundary layer anomalies. Fiber optic sensors dominate new platform designs due to electromagnetic immunity and multiplexing capacity, while infrared sensors retain strong positions in retrofit applications where non-contact measurement simplifies installation. Wired monitoring still occupies the majority of installed base, though wireless monitoring is gaining fastest in drone and business aircraft segments where weight reduction commands premium pricing.
FAA airworthiness standards and EASA CS-25 certification requirements mandate demonstrated ice detection accuracy for transport category aircraft, directly shaping sensor performance thresholds and validation protocols. The EU AI Act and emerging MDR-equivalent frameworks for aerospace components are introducing algorithmic transparency requirements for predictive thermal analytics embedded in monitoring systems. Stakeholders must track evolving certification timelines for wireless sensor networks in safety-critical exterior applications.
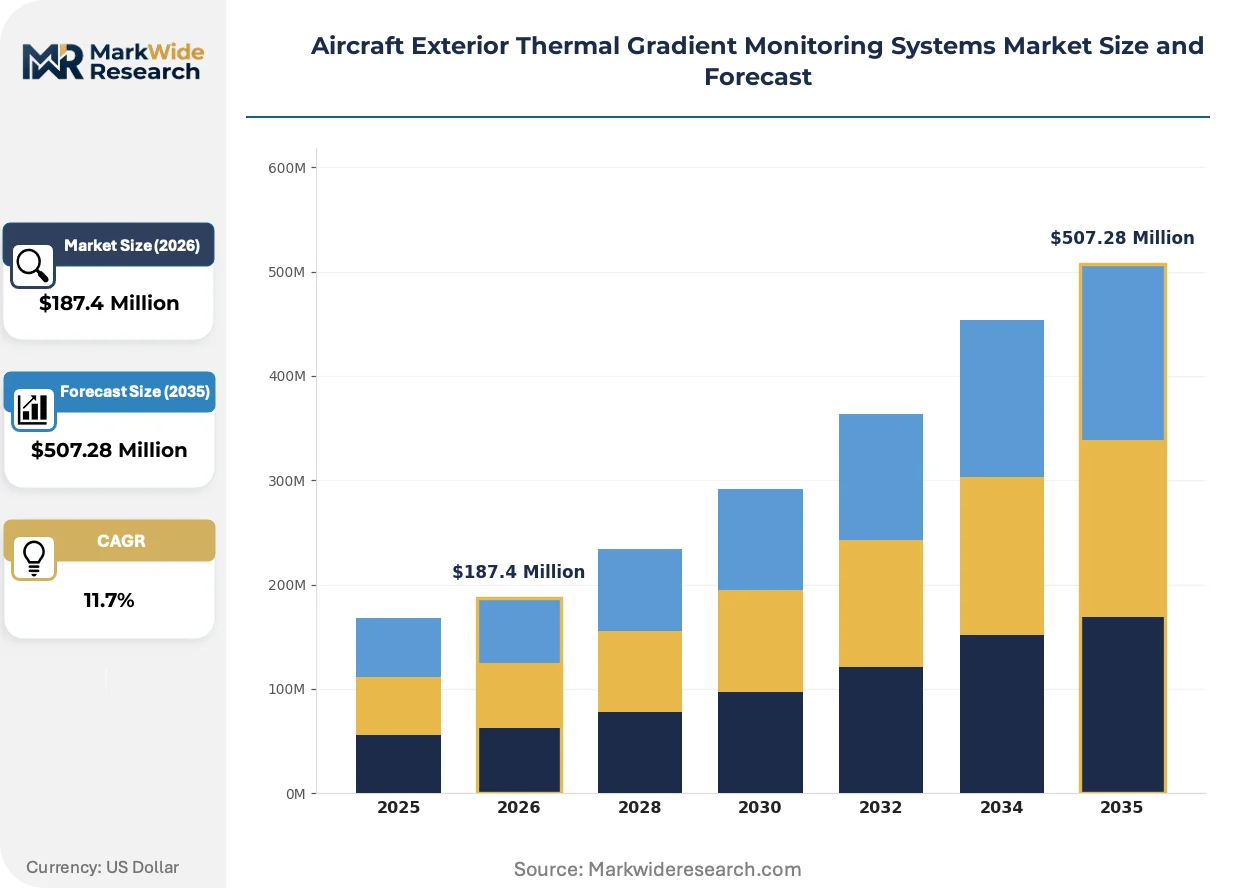
Market Dynamics
Certification requirements for wireless sensor networks in safety-critical exterior applications are compressing product development timelines while elevating validation costs across the installed base upgrade cycle.
Growth Catalysts
- FAA Airworthiness Directives:Mandated ice detection accuracy thresholds for transport category aircraft are forcing sensor performance upgrades across narrow-body and wide-body fleets.
- Fiber Optic Multiplexing:Electromagnetic immunity and distributed sensing capacity are displacing legacy wired architectures in new platform designs.
- Commercial Fleet Expansion:Airlines in the United States are retrofitting thermal monitoring across aging Boeing 737 and Airbus A320 families to reduce unscheduled maintenance events.
Market Restraints
- Specialized Sensor Supply Concentration:European manufacturing footprints in France and Germany control critical fiber optic component supply, creating single-source vulnerability.
- Validation Protocol Costs:EASA CS-25 certification requirements demand extensive flight-test documentation, elevating non-recurring engineering for new entrants.
- Silicon Photonics Substitution:Emerging integrated photonic chips threaten discrete fiber optic sensor assemblies in next-generation monitoring architectures.
Strategic Opportunities
- Unmanned Aerial Systems:Drone operators in the United States are adopting wireless thermal monitoring to meet beyond-visual-line-of-sight operational requirements.
- EU AI Act Algorithmic Transparency:Predictive thermal analytics embedded in monitoring systems gain competitive differentiation through documented decision-pathway compliance.
- Convergence of MEMS and Fiber Sensing:Hybrid architectures combining micro-electromechanical temperature references with distributed optical strain measurement are opening retrofit markets for business aircraft.
Industry Challenges
- Electromagnetic Interference Qualification:Wireless sensor networks must demonstrate coexistence with TCAS, weather radar, and SATCOM systems during certification.
- Legacy Platform Integration:ARINC 429 and MIL-STD-1553 databus architectures in older aircraft constrain data bandwidth for high-resolution thermal gradient telemetry.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Exterior Thermal Gradient Monitoring Systems Market Trends and Innovations
Sensor fusion architectures and edge-computing analytics are redefining how thermal data translates into actionable maintenance decisions across operational environments.
Fiber Bragg grating sensor arrays are decomposing traditional point-sensor installations across wing structures and control surfaces. Regional airlines in North America are piloting multiplexed optical networks to reduce wiring weight and installation labor. This technology is decomposing the installed base of discrete thermocouple harnesses that dominated previous generation monitoring.
EASA's emerging MDR-equivalent framework for aerospace components is introducing algorithmic transparency mandates for predictive thermal analytics. Manufacturers must now document decision pathways in machine-learning-based ice detection systems. Business aircraft operators in Switzerland and Austria are prioritizing suppliers with pre-validated compliance packages to accelerate type certification.
Airlines are unbundling thermal monitoring data from traditional airframe maintenance contracts. Low-cost carriers now procure raw sensor telemetry separately from analytics platforms, enabling multi-vendor interoperability. This pattern is most visible in the United States, where Delta and United have established independent data governance frameworks for fleet-wide thermal gradient repositories.
Aircraft Exterior Thermal Gradient Monitoring Systems Market Segmentation
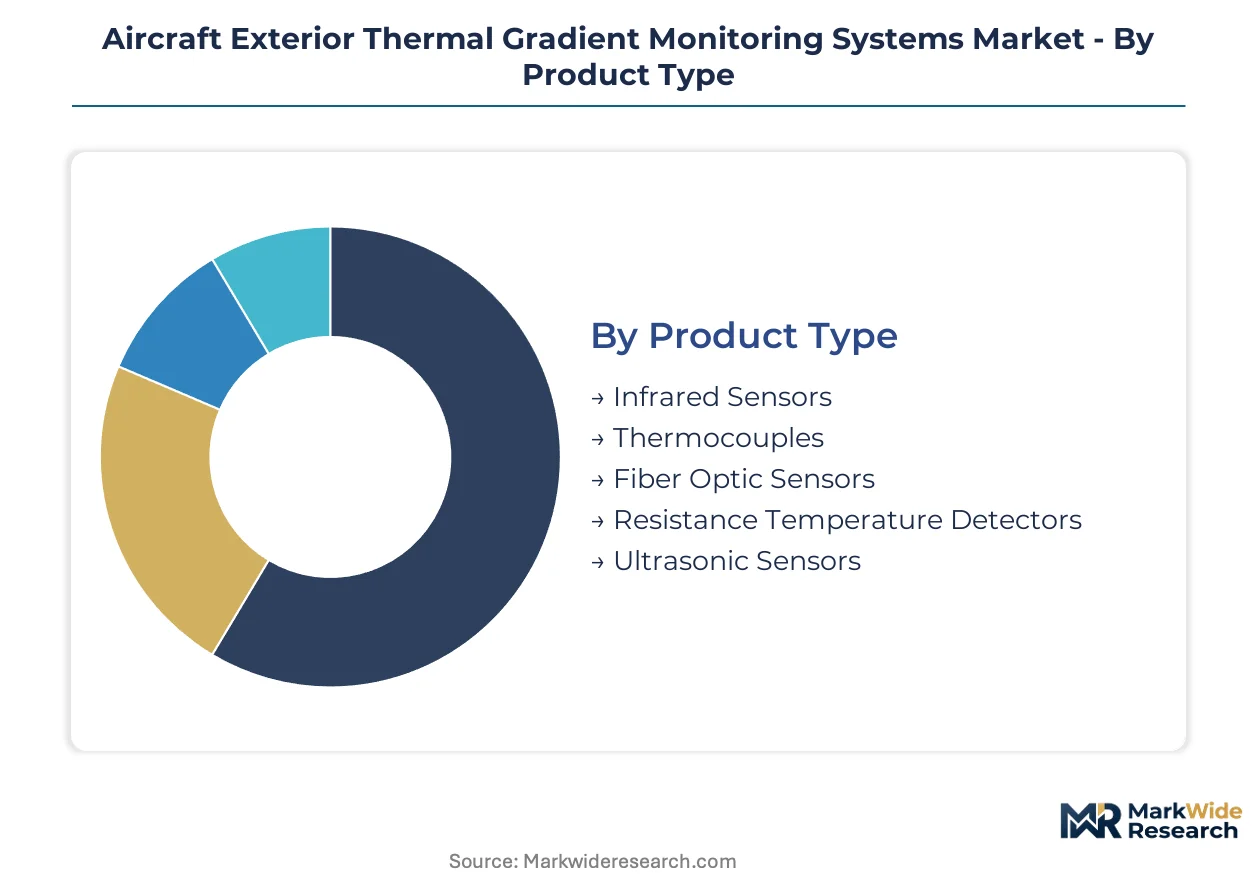
Thermal gradient monitoring architectures fragment across sensor physics, data transmission protocols, and airworthiness certification tiers. Procurement patterns diverge sharply between new platform integrations and retrofit upgrade cycles across commercial and defense end-use segments.
Product Type:
Fiber optic sensors ship predominantly to domestic Boeing and Airbus final assembly lines, while infrared and thermocouple products serve export-led MRO retrofit demand across Middle Eastern and Asian carrier fleets.
- Fiber Optic Sensors:Distributed Bragg grating arrays multiplex temperature and strain measurements across wing structures through single optical fibers. FAA-certified installations concentrate at Boeing 787 and Airbus A350 production facilities in Everett and Toulouse, driven by electromagnetic immunity requirements for composite airframes. The steepest expansion trajectory runs through next-generation narrow-body programs seeking wiring weight reduction.
- Infrared Sensors:Non-contact thermal imaging modules measure surface temperature differentials without physical intrusion into pressure vessels. Demand clusters in United States-based MRO networks retrofitting aging 737NG and A320ceo fleets, constrained by installation labor costs and window aperture modifications.
- Thermocouples:Legacy type-K and type-T junctions dominate the installed base of regional turboprops and cargo conversions.
- Resistance Temperature Detecters:Thin-film platinum elements provide reference-grade calibration for ice detection validation protocols.
- Ultrasonic Sensors:Piezoelectric arrays detect ice accretion thickness through acoustic impedance measurement.
Fiber optic sensors command the established base in new platform design. The steepest expansion runs through infrared retrofit applications.
Technology:
Cost tier stratification separates safety-critical wired architectures from emerging wireless deployments in weight-sensitive segments.
- Wired Monitoring:ARINC 429 and MIL-STD-1553 databus architectures deliver deterministic latency for ice detection alert chains. Commercial OEM procurement concentrates in United States and French supply chains, though validation costs for electromagnetic interference qualification compress margins for new entrants.
- Wireless Monitoring:Low-power mesh networks eliminate harness weight for drone and business aircraft operators. United States-based unmanned system developers drive adoption fastest, navigating FAA special airworthiness certification for beyond-visual-line-of-sight operations.
- Real-Time Data Acquisition:Edge-computing nodes process thermal gradients at the sensor cluster level.
- Remote Sensing:Satellite telemetry links enable ground-based thermal monitoring of long-haul fleets.
- Embedded Systems:FPGA-based processing units integrate ice detection logic with flight control computers.
Wired monitoring retains the revenue base. Wireless architectures are gaining share fastest in emerging air mobility segments.
Application:
Customer type divergence splits volume production for scheduled airlines from specialized engineering for defense and private aviation.
- Commercial Jets:Narrow-body and wide-body platforms require redundant thermal monitoring across leading edges, engine nacelles, and horizontal stabilizers. United States carrier fleet renewal programs and Chinese COMAC C919 production lines anchor demand, shaped by FAA and CAAC ice detection mandates.
- Drones:Small unmanned aerial systems prioritize sensor miniaturization and power efficiency over absolute accuracy. United States commercial drone operators expanding beyond-visual-line-of-sight cargo delivery represent the most dynamic demand concentration.
- Military Fighters:Stealth-compatible fiber optic networks monitor thermal signatures for signature management.
- Helicopters:Main rotor blade ice detection drives specialized sensor packaging for vibration environments.
- Business Aircraft:Owner-operators value discrete retrofit solutions preserving cabin aesthetics.
Commercial jets command the established base. The steepest expansion runs through drone applications.
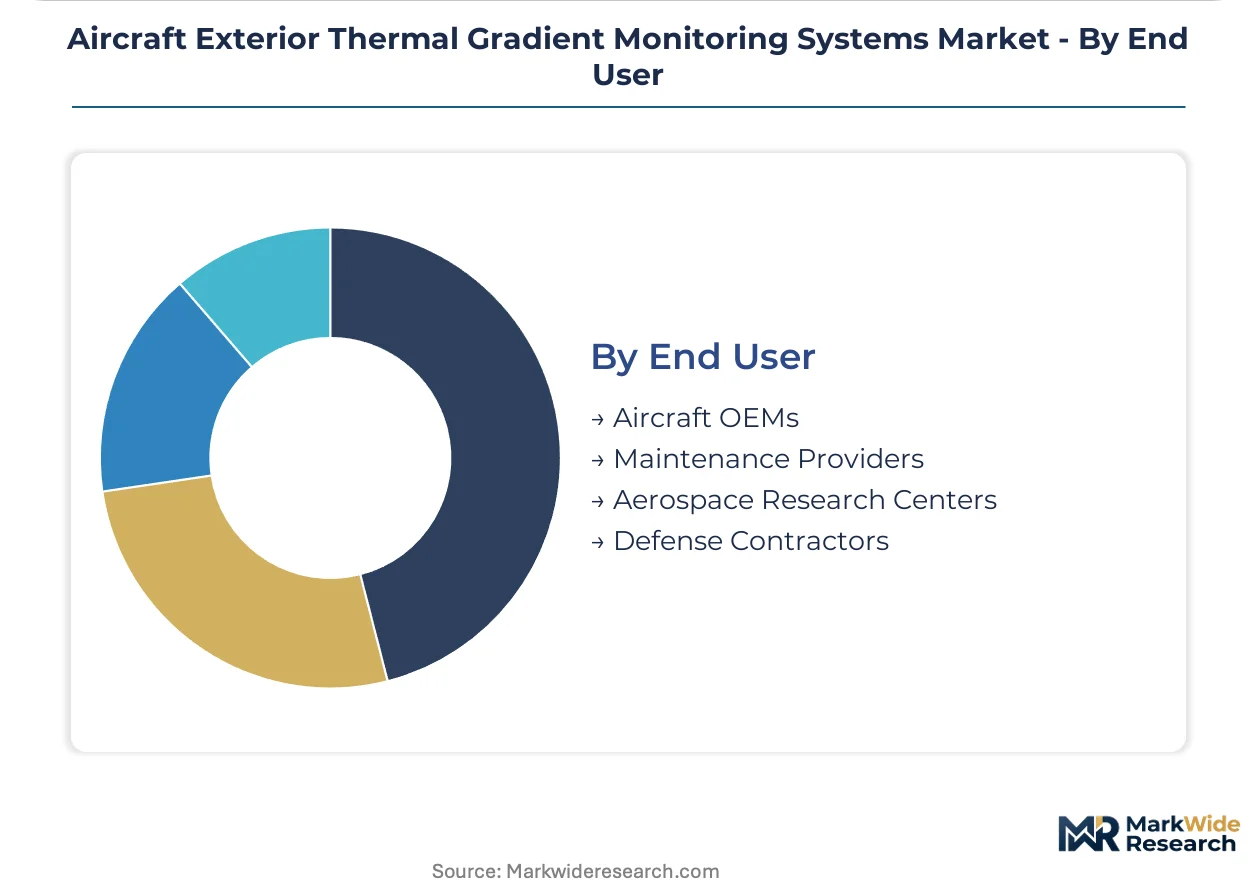
End User:
Supply concentration aligns with manufacturing geography — aircraft OEMs source through domestic tier-one avionics suppliers while defense contractors maintain captive engineering capabilities.
- Aircraft OEMs:Boeing, Airbus, and Embraer integrate thermal monitoring at the electrical systems design phase. Production line demand concentrates in Washington State, Toulouse, and São Paulo industrial corridors, with specification authority residing in airframe engineering centers.
- Defense Contractors:Lockheed Martin and Northrop Grumman classify thermal gradient data within stealth performance parameters. United States Department of Defense procurement channels sustain specialized engineering teams independent of commercial sensor suppliers.
- Maintenance Providers:Delta TechOps and Lufthansa Technik manage fleet-wide thermal data repositories.
- Aerospace Research Centers:NASA Glenn and ONERA validate ice detection algorithms in icing wind tunnels.
Aircraft OEMs command the established base. The steepest expansion runs through maintenance providers unbundling data services from hardware procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Everett final assembly line anchors North American production capacity for thermal gradient monitoring integration. Toulouse and Hamburg factories concentrate European sensor certification workflows. COMAC's Shanghai facilities are expanding domestic supply chain depth for ice detection systems.
United States
Boeing's 787 and 777X programs drive fiber optic sensor procurement at scale. FAA airworthiness directives on ice detection accuracy mandate fleet-wide retrofit schedules for narrow-body carriers. Delta TechOps in Atlanta and United's maintenance hub in San Francisco anchor MRO data repository investments.
France
Airbus final assembly at Toulouse-Blagnac concentrates EASA CS-25 certification activity for new platform designs. The EU AI Act introduces algorithmic transparency requirements for predictive thermal analytics embedded in monitoring systems. Safran's sensor manufacturing footprint in Paris-Saclay anchors European fiber optic component supply.
Germany
Lufthansa Technik in Hamburg manages thermal data repositories for retrofit upgrade cycles across A320ceo and 737NG fleets. EASA flight-test documentation requirements elevate non-recurring engineering costs for sensor validation. Munich's aerospace cluster hosts specialized engineering teams for electromagnetic interference qualification protocols.
China
COMAC's C919 production lines in Shanghai are scaling domestic thermal monitoring integration for CAAC certification compliance. The Civil Aviation Administration of China mandates ice detection accuracy thresholds equivalent to FAA standards. Xi'an's aviation industrial base supports sensor subsystem manufacturing for regional turboprop programs.
United Kingdom
Rolls-Royce engine nacelle programs in Derby drive thermal gradient monitoring specification for propulsion integration. The UK CAA maintains alignment with EASA certification timelines for wireless sensor network approvals. BAE Systems' military aircraft engineering in Lancashire sustains classified thermal signature management capabilities.
Aircraft Exterior Thermal Gradient Monitoring Systems Market Competitive Landscape
Listed leaders compete with private specialists across avionics integration and defense contracting channels. The supplier base concentrates around tier-one system integrators with captive sensor engineering capabilities and specialized component manufacturers serving retrofit demand. Three archetypes dominate: diversified conglomerates bundling thermal sensing with flight management platforms, defense contractors maintaining classified engineering pipelines, and sensor specialists anchoring European supply chains. Competitive moves center on strategic partnerships for data platform interoperability and vertical integration into fiber optic component manufacturing.
Within the diversified conglomerate tier, Honeywell International and RTX exemplify integrated avionics portfolio strategies that bundle thermal gradient monitoring with broader flight management system offerings. Safran occupies a position as the European anchor for specialized sensor manufacturing, with its French industrial footprint controlling critical fiber optic component supply. Thales Group represents the defense-electronics crossover archetype, sustaining dual-use engineering capabilities that serve both military fighter programs and civilian platform retrofits.
| Leading Market Players |
|---|
| Honeywell International |
| RTX |
| Thales Group |
| Safran |
| GE Aerospace |
| Rockwell Collins |
| Meggitt |
| Teledyne Technologies |
| L3Harris Technologies |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with French fiber optic component suppliers lock in both supply access and price visibility for Boeing and Airbus tier-one avionics integrators. These arrangements insulate procurement teams from spot-market volatility in specialized Bragg grating arrays while committing buyers to minimum volume thresholds across platform generations.
Pricing Analysis
Volume-discount tiering structures stratify across FAA-certified, EASA-certified, and non-certified installation grades. Price differentiation centers on electromagnetic immunity qualification level and wiring harness complexity. Cost compression in wireless sensor tiers is intensifying because silicon photonics substitutes threaten discrete fiber optic assemblies. Low-cost carriers exhibit highest price sensitivity, while defense contractors prioritize performance over unit economics.
Supply Chain Analysis
Strategic stockpiling of specialty optical fiber dominates tier-one procurement, with just-in-time delivery reserved for standard thermocouple components. Manufacturing concentrates in France, Germany, and the United States. Production draws from germanium-doped silica preforms, precision lithography equipment, and aerospace-grade connector assemblies. Single-source vulnerability in Paris-Saclay sensor fabrication creates structural risk. Distribution runs through airframe OEM electrical systems divisions and specialized MRO procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet-wide thermal data repository services are expanding faster than hardware shipments as airlines unbundle analytics from sensor procurement. This service-attach dynamic repositions vendor economics toward recurring telemetry licensing and predictive maintenance subscriptions.
For Market Incumbents: Consolidate backward integration into fiber optic component manufacturing to neutralize French supply concentration risk. Lockheed Martin and Northrop Grumman captive engineering capabilities threaten commercial sensor suppliers in classified defense channels. Prioritize EASA algorithmic transparency pre-validation to accelerate OEM design-win cycles.
For New Entrants and Emerging Players: FAA special airworthiness certification fast-tracks offer the most penetrable entry path for wireless thermal monitoring in beyond-visual-line-of-sight drone operations. Target United States commercial unmanned cargo operators with weight-optimized sensor miniaturization. Lead with ground-based thermal telemetry platforms that bypass airframe integration complexity.
For Investors and Strategic Acquirers: Capital is best deployed toward sensor fusion specialists combining MEMS reference architectures with distributed optical strain measurement. Five-to-ten-year viability hinges on regulatory capture in emerging wireless certification pathways. Monitor FAA electromagnetic interference coexistence rulemaking as the critical inflection signal for wireless architecture adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Pre-Validation | EASA AI Act compliance packages accelerate type certification for predictive ice detection systems. |
| Fiber Optic Component Backward Integration | Captive Bragg grating manufacturing neutralizes Paris-Saclay supply concentration vulnerability. |
| Wireless Sensor Certification Fast-Track | FAA special airworthiness pathways unlock beyond-visual-line-of-sight drone thermal monitoring demand. |
| Fleet Data Repository Unbundling | Delta and United independent governance frameworks create multi-vendor interoperability service layers. |
| Silicon Photonics Substitution Investment | Integrated photonic chips threaten discrete sensor economics in next-generation narrow-body programs. |
Research Methodology
The analysis maps fiber optic sensor architectures, infrared retrofit modules, wireless mesh networks, and predictive analytics platforms, each validated through avionics integration engineers, MRO procurement directors, FAA certification specialists, and airline fleet engineering managers. Primary fieldwork combined with secondary validation against EASA CS-25 directive documentation, FAA airworthiness directive filings, customs trade records for aerospace sensor components, and OEM electrical systems specification databases. Bottom-up segment sizing triangulated against top-down fleet installation projections.
Consistency checks validated volume and value outputs against external airframe production schedules and MRO retrofit cycle documentation. The analytical framework models sensor physics, data transmission protocol, airworthiness certification tier, and platform generation segmentation throughout the forecast period. CAGRs derived from installation base growth curves and replacement cycle dynamics, with specific inputs including composite airframe penetration rates and regulatory mandate compliance deadlines.
Decision-makers should treat outputs as directional under assumptions of stable FAA-EASA regulatory alignment and no disruptive silicon photonics substitution; material deviation would warrant model refresh. Revision becomes warranted when electromagnetic interference qualification timelines for wireless architectures cross critical path thresholds for new platform entry-into-service dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.