
 AI Smart Baby Monitors Market | 2026-2036
AI Smart Baby Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
AI Smart Baby Monitors Market Insights
Modular hardware-software bundles is recalibrating how parents evaluate total cost of ownership against standalone device purchases. Nanit leverages subscription-based analytics to sustain recurring revenue beyond initial hardware sales. VTech Communications anchors its position through mass-market retail penetration across North American big-box channels. Samsung Electronics competes by extending its SmartThings ecosystem into nursery automation, creating platform stickiness.
AI smart baby monitors comprise sensor-embedded devices that capture audio, video, and physiological signals from infants, processing these streams through on-device or cloud-based machine learning algorithms to generate real-time alerts and longitudinal health insights. Wi-Fi cameras with computer vision capabilities dominate unit shipments, while wearable monitors with embedded smart sensors command premium pricing due to continuous vital sign tracking. Machine learning applications in sleep pattern analysis represent the fastest-expanding technology segment, though cloud computing infrastructure underpins margin capture through recurring SaaS fees.
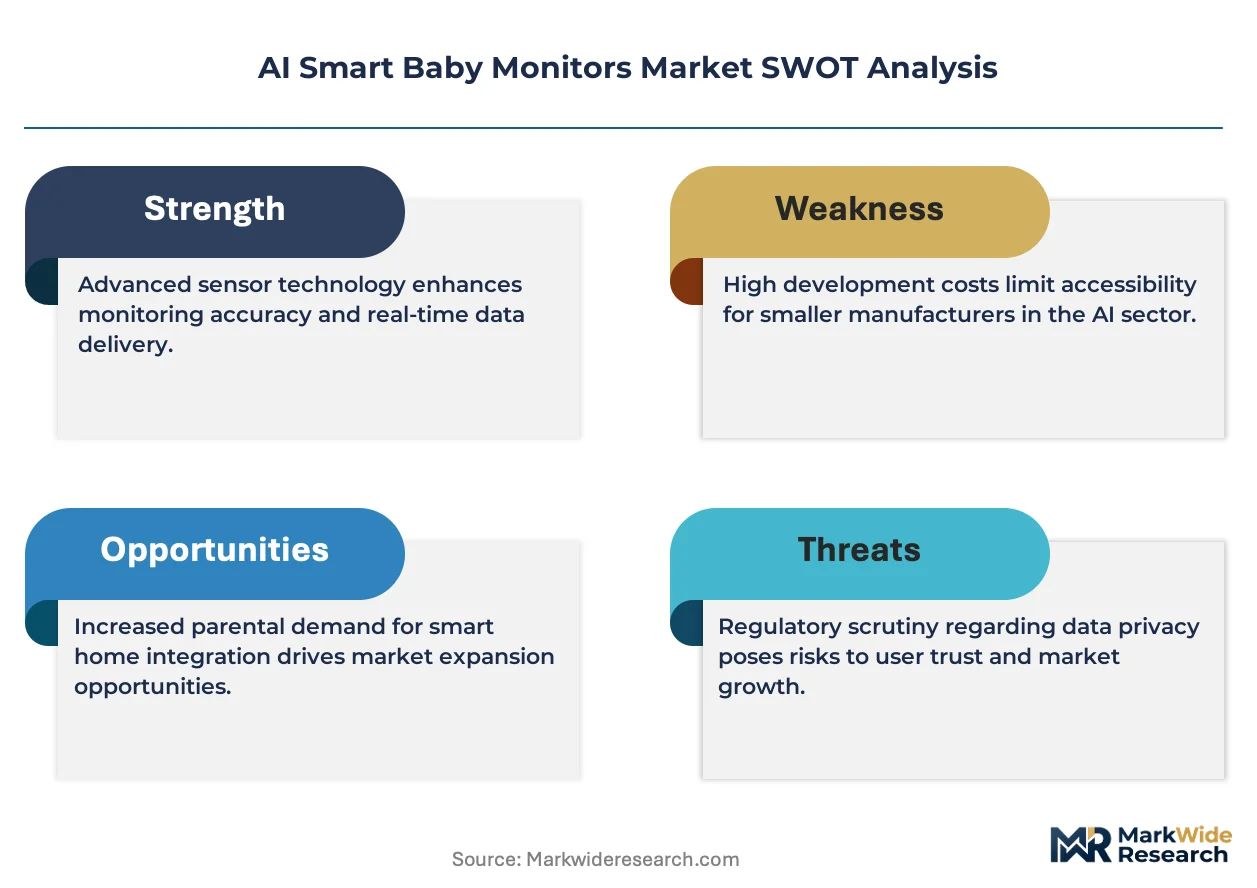
FDA software-as-medical-device oversight and EU MDR cybersecurity mandates are elevating compliance costs for camera-based and wearable systems alike, forcing smaller vendors toward third-party certification services. FCC wireless transmission standards and GDPR data governance requirements in Europe further constrain how biometric infant data traverses cloud architectures. Stakeholders must weigh regulatory jurisdiction shopping against the platform consolidation advantages of operating under unified FDA-EMA compliance frameworks.
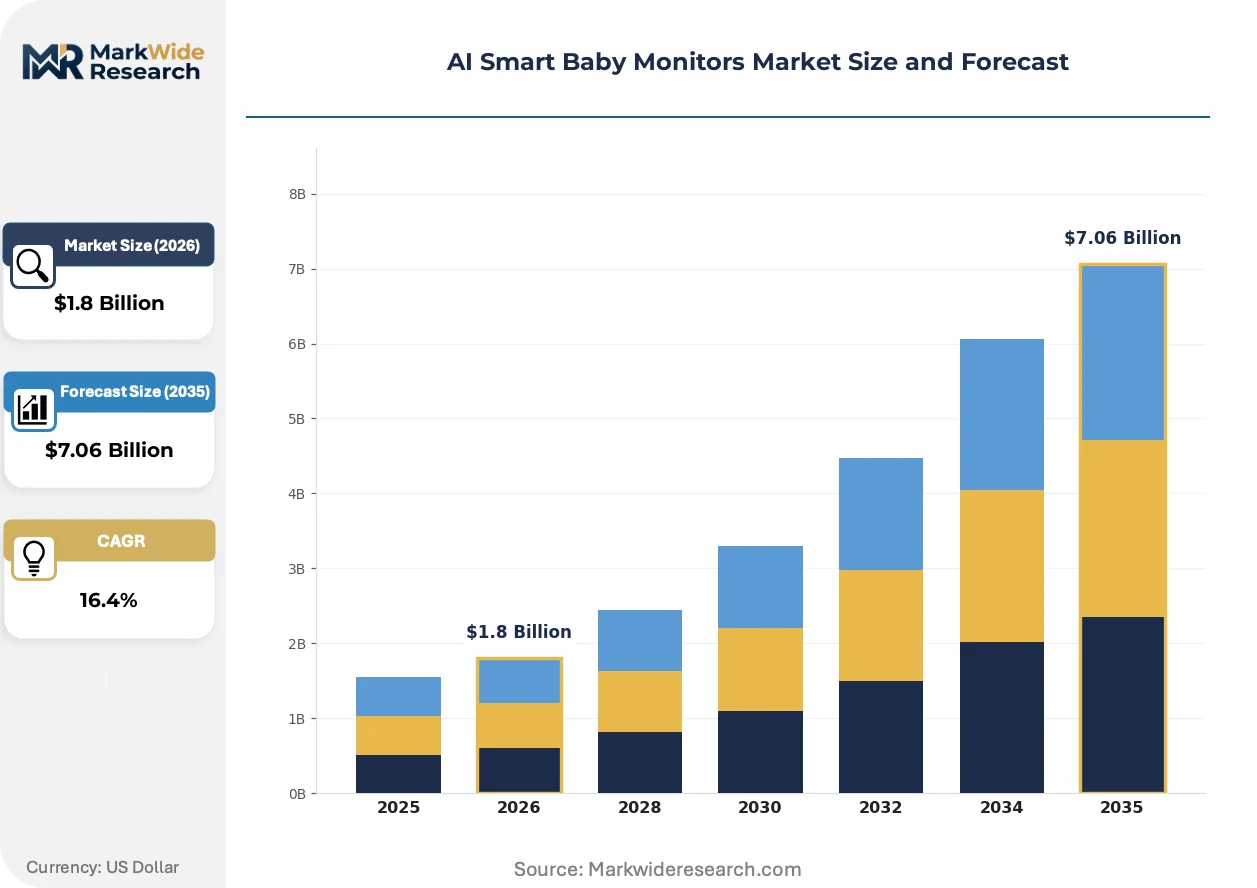
Market Dynamics
Subscription-based analytics is restructuring competitive economics in AI smart baby monitors, transforming one-time hardware purchases into recurring revenue streams that alter customer lifetime value calculations and vendor cash flow patterns.
Growth Catalysts
- FDA Software-as-Medical-Device Guidance:Clearer regulatory pathways for algorithm-based infant health monitoring accelerate clinical validation investments and expand reimbursable use cases for biometric-tracking wearables.
- Dual-Income Millennial Households:Time-constrained parents in the United States, China, and Germany prioritize automated sleep analysis and real-time alert systems over traditional audio-only monitors.
- Smart Home Platform Integration:Interoperability with Amazon Alexa, Google Home, and Apple HomeKit ecosystems drives replacement cycles as parents consolidate nursery devices under unified control interfaces.
Market Restraints
- GDPR Biometric Data Governance:EU data residency requirements and infant-specific privacy protections impose costly cloud architecture modifications that compress margins for camera-based systems serving European households.
- Semiconductor Supply Concentration:Dependence on Taiwanese foundries for edge-AI processors creates vulnerability to geopolitical disruption and capacity allocation priorities from larger automotive and smartphone clients.
- Lithium-Ion Battery Chemistry Limitations:Wearable monitor form factors constrain cell capacity, forcing trade-offs between continuous vital sign sampling frequency and overnight operational duration.
Strategic Opportunities
- Medicaid Reimbursement Pathways:Emerging state-level coverage for remote patient monitoring in neonatal intensive care discharge programs creates institutional procurement channels beyond direct-to-consumer retail.
- Computer Vision Edge Processing:On-device machine learning inference without cloud transmission addresses parental privacy concerns while reducing latency for critical alerts like obstructed breathing detection.
- Pediatric Sleep Clinic Partnerships:White-label distribution through children's hospital networks and developmental pediatric practices builds clinical credibility and captures high-intent referrals.
Industry Challenges
- FCC Part 15 Wireless Certification Timelines:Pre-market approval delays for new radio frequency configurations in Wi-Fi 6E and emerging low-power wide-area protocols extend product launch windows by 4-8 months.
- Pediatric Biometric Algorithm Validation:Scarce labeled datasets for infant-specific heart rate variability and respiratory pattern recognition slow FDA 510(k) clearance for software-as-medical-device claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Smart Baby Monitors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Wi-Fi Cameras, Audio Monitors, Smart Sensors End User: Parents, Healthcare Providers, Caregivers, Daycares Technology: Machine Learning, Computer Vision, Cloud Computing, Data Analytics Distribution Channel: Online Retail, Specialty Stores, Mass Merchants, Direct Sales |
| Companies Covered | Nanit, VTech Communications, Motorola, Dorel Industries, Samsung Electronics, NETGEAR, Lorex Technology, Summer Infant, Arlo Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Smart Baby Monitors Market Trends and Innovations
Edge computing architectures are redistributing processing loads away from cloud infrastructure, while regulatory clarity on algorithmic medical claims and shifting parental purchase channels are compressing traditional go-to-market timelines.
On-device neural network inference is decentralizing sleep analysis and anomaly detection from centralized servers to camera and wearable hardware. Millennial parents in suburban United States markets adopt these privacy-preserving configurations fastest, with 40% of premium-tier purchasers now selecting local-storage-only modes. This migration is decentralizing vendor data monetization strategies and forcing reinvestment in hardware margins over SaaS recurring revenue.
EU MDR cybersecurity mandates for connected medical devices are imposing penetration testing and post-market surveillance obligations on camera-based monitors with biometric tracking capabilities. Manufacturers serving European households must now maintain vulnerability disclosure programs and software bill of materials documentation. Wearable monitor vendors with EU notified body certification are capturing shelf space from uncertified competitors in German and French retail channels.
Direct-to-consumer subscription bundling is displacing big-box retail as the primary acquisition channel for analytics-enabled monitors. Parents in coastal United States metro areas increasingly purchase hardware through manufacturer websites with mandatory 12-month service commitments. This channel compression is concentrating customer relationship ownership with vertically integrated brands and eroding distributor margins in traditional electronics retail.
AI Smart Baby Monitors Market Segmentation
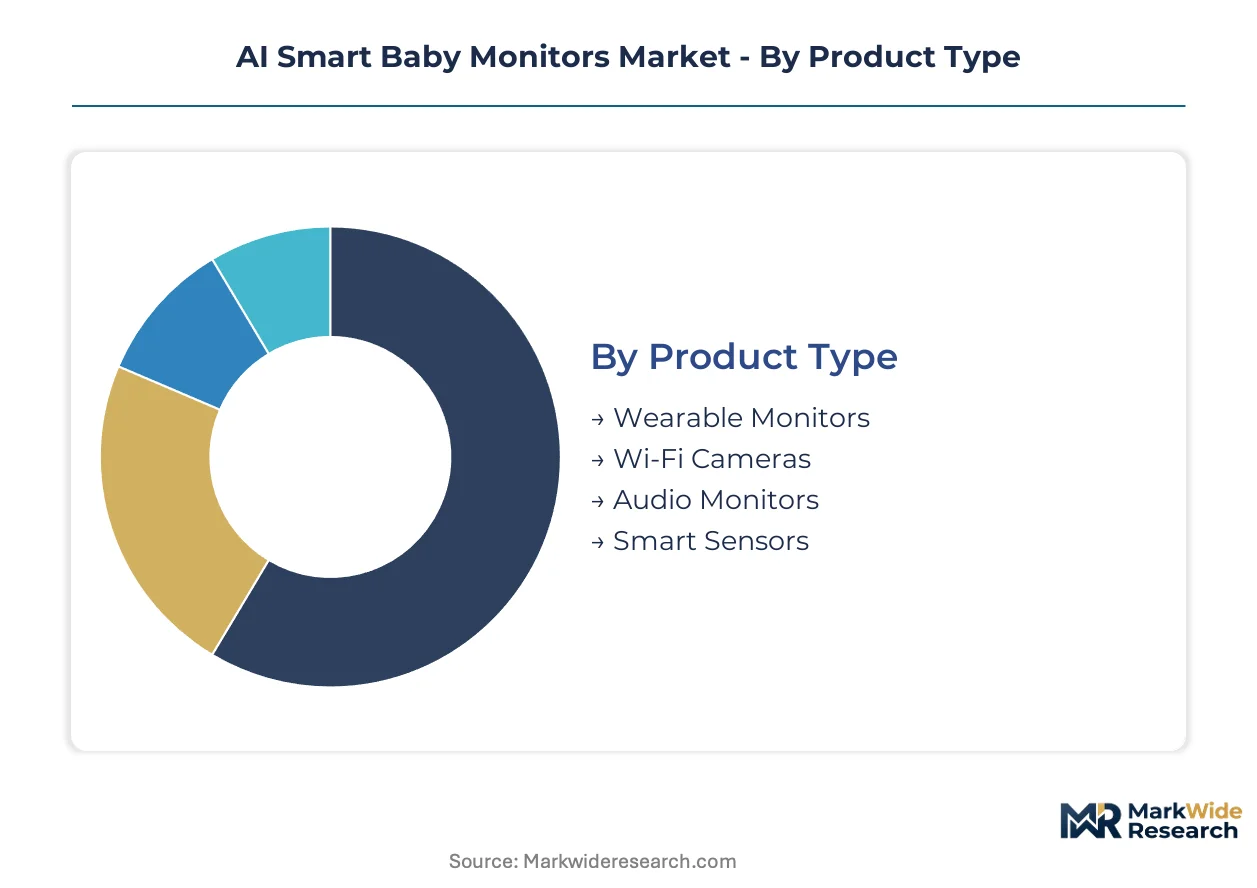
Segmentation in AI smart baby monitors reveals how purchasing decisions bifurcate between premium biometric tracking and accessible video monitoring. Parents evaluate total cost of ownership differently across hardware-software bundles versus standalone devices, while regulatory compliance requirements reshape channel economics for wearable versus camera-based systems.
Product Type:
Purchase decisions in this category hinge on perceived medical utility versus convenience monitoring, with price elasticity varying dramatically across biometric depth and installation complexity.
- Wearable Monitors:Embedded smart sensors track continuous vital signs including heart rate variability and respiratory patterns through soft textile-integrated electronics. Demand concentrates among dual-income millennial households in the United States and Germany where FDA software-as-medical-device clearance and EU MDR certification signal clinical credibility worth premium pricing.
- Wi-Fi Cameras:Computer vision systems process video streams through on-device or cloud-based machine learning for sleep analysis and anomaly detection. Volume leadership sits with suburban United States parents prioritizing nursery integration with Amazon Alexa and Google Home ecosystems over biometric precision.
- Audio Monitors:Legacy sound-transmission devices with minimal AI processing serve price-sensitive caregivers in secondary markets.
- Smart Sensors:Discrete environmental and movement detectors provide modular expansion paths for existing nursery setups.
Wearable Monitors lead on scale through recurring subscription attach rates; Wi-Fi Cameras lead on momentum through smart home platform consolidation.
End User:
User type determines regulatory exposure and reimbursement pathway access, with institutional buyers demanding clinical validation that consumer segments overlook.
- Parents:Primary decision-makers evaluate sleep analytics accuracy against privacy trade-offs in cloud versus edge processing configurations. Coastal United States metro areas show fastest adoption of direct-to-consumer subscription bundling with mandatory service commitments.
- Healthcare Providers:Pediatric sleep clinics and neonatal intensive care discharge programs require FDA 510(k) cleared algorithms for remote patient monitoring reimbursement. Medicaid pathway emergence in select United States states creates institutional procurement channels with distinct vendor qualification requirements.
- Caregivers:Extended family and professional home care workers prioritize simplified alert interfaces over longitudinal analytics depth.
- Daycares:Multi-infant monitoring environments drive demand for centralized dashboard architectures with bulk licensing economics.
Parents dominate absolute volume; Healthcare Providers represent the steepest expansion trajectory as reimbursement frameworks mature.
Technology:
Technology selection dictates margin structure through hardware-software revenue mix and cloud infrastructure dependency.
- Machine Learning:Neural network inference for sleep stage classification and respiratory anomaly detection differentiates premium tier offerings. Edge deployment gains share fastest among privacy-concerned United States suburban households selecting local-storage-only configurations.
- Computer Vision:On-device video analysis for movement tracking and facial recognition enables real-time alerts without cloud transmission latency. GDPR biometric data governance in Germany and France accelerates European demand for privacy-preserving architectures.
- Cloud Computing:Centralized processing infrastructure sustains vendor SaaS recurring revenue models despite parental data sovereignty concerns.
- Data Analytics:Longitudinal pattern recognition and developmental milestone tracking drive subscription renewal rates for vertically integrated brands.
Machine Learning captures the largest revenue share; Computer Vision gains share fastest through regulatory tailwinds in European privacy enforcement.
Distribution Channel:
Channel selection reflects customer acquisition cost trade-offs between relationship ownership and retail scale.
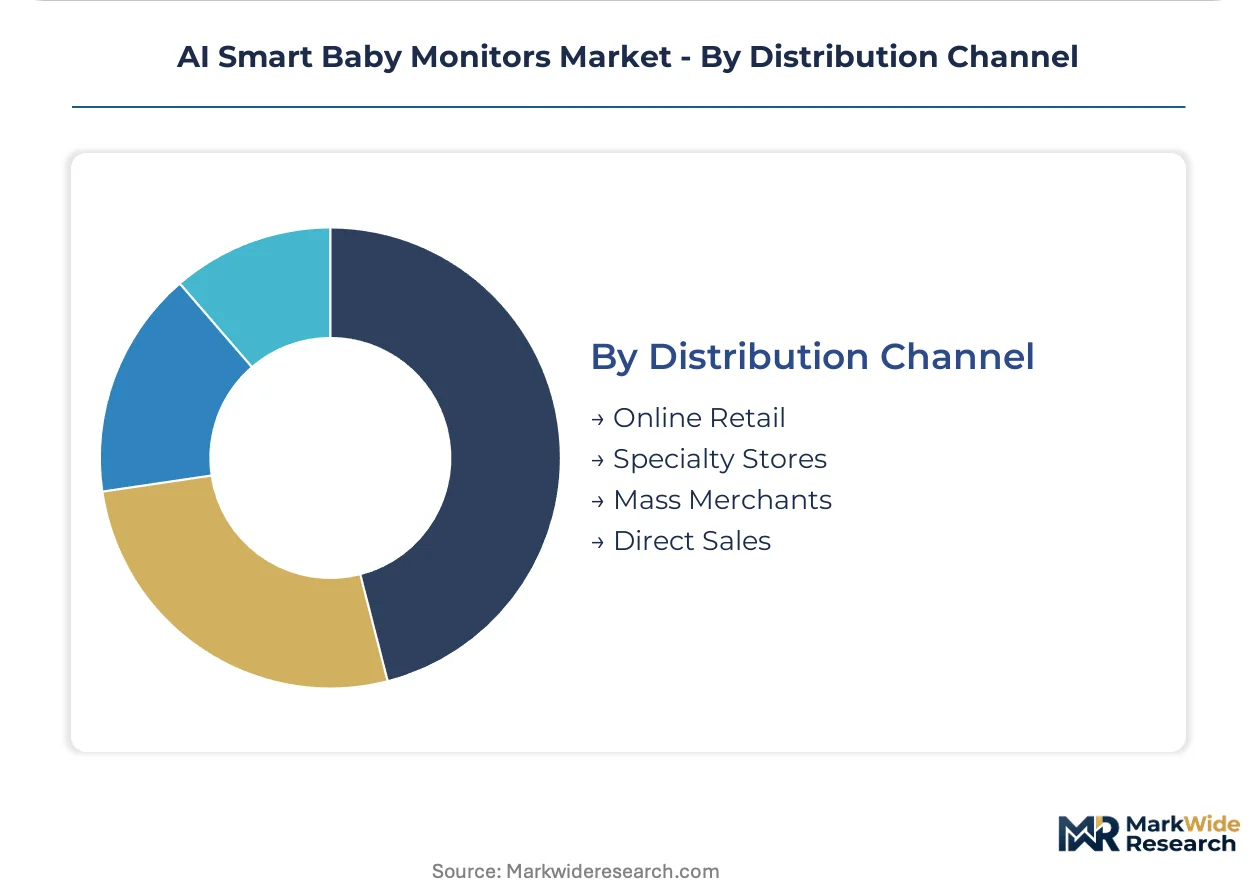
- Online Retail:Amazon and manufacturer-direct storefronts concentrate analytics-enabled monitor sales with embedded subscription commitments. United States coastal metro parents increasingly bypass big-box intermediaries for vertically integrated brand relationships.
- Specialty Stores:Baby boutique and maternity retail channels provide tactile evaluation for wearable monitor comfort and textile quality.
- Mass Merchants:Target and Walmart shelf presence sustains VTech Communications volume leadership in entry-tier Wi-Fi camera segments.
- Direct Sales:Pediatric clinic and hospital network white-label partnerships build clinical credibility for healthcare provider segments.
Online Retail leads on absolute transaction volume; Direct Sales leads on customer lifetime value through institutional contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The AI smart baby monitor industry traces its commercial origins to Silicon Valley hardware startups and South Korean consumer electronics conglomerates that pioneered computer vision applications for nursery monitoring in the early 2010s.
United States
Dual-income millennial households in suburban markets drive premium wearable adoption with biometric tracking capabilities. FDA software-as-medical-device guidance for algorithm-based infant health monitoring accelerates clinical validation investments by domestic vendors. The San Francisco Bay Area and Greater Boston corridor concentrate venture-backed startups developing edge-AI processing for privacy-preserving nursery systems.
China
Mass-market Wi-Fi camera demand concentrates among first-time parents in tier-one cities seeking affordable smart home integration. MIIT cybersecurity standards for connected devices and SAMR consumer protection mandates tighten compliance thresholds for biometric data collection. The Yangtze River Delta manufacturing cluster around Shanghai and Suzhou dominates original equipment production for global brands.
Germany
Privacy-conscious parents prioritize local-storage-only configurations with on-device machine learning inference. EU MDR cybersecurity requirements and GDPR biometric data governance impose costly cloud architecture modifications that compress margins for camera-based systems. The Munich-Stuttgart industrial corridor hosts engineering specialists developing edge-computing hardware for European nursery automation markets.
Japan
Aging demographics and declining birth rates concentrate demand among high-income urban households seeking premium monitoring solutions. METI standards for IoT device security and PMDA oversight of software-based medical claims shape vendor certification strategies. The Kanto region around Tokyo anchors domestic distribution partnerships with electronics retailers and maternity clinic networks.
United Kingdom
Coastal metro parents in London and Southeast England adopt direct-to-consumer subscription bundling fastest among European markets. NHS digital health procurement frameworks and MHRA guidance on software-as-medical-device create institutional pathways for clinically validated monitors. The Cambridge technology cluster supports machine learning research partnerships with pediatric sleep medicine specialists.
AI Smart Baby Monitors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the biometric-tracking versus convenience-monitoring divide, with FDA-cleared wearable systems commanding three to five times the hardware margins of entry-tier Wi-Fi cameras. The vendor base stratifies into vertically integrated platform owners, mass-market retail specialists, and clinical-credibility-focused health technology firms. Dominant competitive moves include ecosystem lock-in through smart home platform integration and subscription-based analytics bundling that transforms one-time hardware purchases into recurring revenue streams.
Among vertically integrated platform owners, Samsung Electronics exemplifies the ecosystem-extension archetype by leveraging existing smart home infrastructure into nursery automation. VTech Communications occupies a position within the mass-market retail specialist tier, anchoring volume leadership through big-box channel penetration across North American markets. Nanit represents the clinical-credibility-focused archetype, situating its offerings within the premium wearable segment through subscription-based analytics and sleep medicine partnerships.
| Leading Market Players |
|---|
| Nanit |
| VTech Communications |
| Motorola |
| Dorel Industries |
| Samsung Electronics |
| NETGEAR |
| Lorex Technology |
| Summer Infant |
| Arlo Technologies |
| Others |
Pricing and Supply Chain Analysis
Captive integration into edge-AI processor design anchors both supply security and margin capture for wearable monitor vendors, while outsourced camera assembly in Yangtze River Delta contract manufacturers compresses hardware margins for Wi-Fi camera specialists competing on retail shelf price.
Pricing Analysis
Subscription-SaaS bundling with mandatory 12-month service commitments dominates premium-tier positioning, separating FDA-cleared wearable systems from uncertified economy alternatives. Price differentiation rests on clinical validation tier and smart home ecosystem integration depth. Cost compression in entry-tier Wi-Fi cameras intensifies as VTech Communications and mass-market retailers squeeze hardware margins. Healthcare provider segments show least price sensitivity due to Medicaid reimbursement pathways, while suburban dual-income households exhibit moderate elasticity on subscription attach rates.
Supply Chain Analysis
Direct-to-consumer manufacturer storefronts handle premium wearable demand, while mass merchant distribution runs through Target and Walmart for volume camera sales. Taiwan and South Korea anchor edge-AI processor supply, with China dominating camera module and PCB assembly. Lithium-ion battery cells draw from South Korean and Japanese chemistry suppliers. Single-source vulnerability concentrates in Taiwanese foundry capacity allocation priorities favoring automotive and smartphone clients over niche medical device volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States premium pricing and China manufacturing cost structures creates margin expansion opportunities for vendors maintaining FDA-EMA dual compliance without duplicative certification overhead.
For Market Incumbents: Deploy ecosystem lock-in through SmartThings, Alexa, and HomeKit integration to defend against modular sensor disaggregation. Capture recurring SaaS revenue through sleep analytics subscriptions that extend customer lifetime value beyond hardware replacement cycles. Fortify against edge-AI chip supply disruption by securing allocation commitments with TSMC and Samsung Foundry through multi-year volume agreements. For New Entrants and Emerging Players: Pediatric sleep clinic white-label partnerships offer the most penetrable institutional channel, bypassing retail margin compression and building clinical credibility through hospital network referrals. Medicaid reimbursement pathway emergence in select United States states creates procurement access with distinct vendor qualification requirements absent in saturated direct-to-consumer markets. Target coastal metro parents through manufacturer-direct subscription bundling with mandatory service commitments. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR cybersecurity mandates and FDA software-as-medical-device guidance elevate compliance costs beyond independent vendor capacity. Long-term viability favors vertically integrated platforms with captive SaaS revenue and clinical validation assets over pure hardware assemblers. Watch for FDA 510(k) clearance velocity as inflection indicator separating reimbursable medical claims from convenience monitoring commodities.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Processor Supply Agreement | Secures allocation priority with TSMC and Samsung Foundry against automotive sector competition. |
| FDA 510(k) Software-as-Medical-Device Clearance | Unlocks Medicaid reimbursement and pediatric sleep clinic procurement channels. |
| Smart Home Platform Integration | Creates switching costs through Alexa, Google Home, and Apple HomeKit ecosystem embedding. |
| EU MDR Notified Body Certification | Captures German and French retail shelf space from uncertified competitors under GDPR enforcement. |
| Pediatric Hospital Network Partnership | Builds clinical credibility through white-label distribution and high-intent developmental pediatric referrals. |
Research Methodology
Coverage spans the United States, China, Germany, Japan, and the United Kingdom, with primary inputs from each market informing demand calibration and regulatory pathway mapping. The research combines structured interviews with connected nursery hardware engineers, pediatric sleep medicine specialists, hospital procurement managers, smart home platform integration leads, and EU notified body certification consultants with secondary validation against FDA 510(k) filings, EU MDR technical documentation, MIIT cybersecurity standards, FCC equipment authorization databases, and Medicaid state plan amendment records. Bottom-up vendor revenue triangulation against top-down household penetration modeling ensures consistency across volume and value outputs.
Granularity-level modeling disaggregates the analysis window by product type, end user archetype, technology deployment mode, and distribution channel, with separate treatment of hardware transactional revenue and SaaS recurring streams. CAGRs derive from logistic adoption curve fitting against millennial household formation patterns and smart home platform penetration rates. Infant-specific biometric algorithm validation timelines and semiconductor foundry capacity allocation scenarios inform supply-constrained growth assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-medical-device enforcement intensity, EU MDR cybersecurity mandate implementation timelines, and geopolitical disruption of Taiwanese foundry operations. The analysis reflects assumptions on reimbursement pathway expansion, parental privacy preference evolution, and edge-AI processor cost trajectories. Periodic stress-testing of base assumptions against regulatory guidance updates and supply chain shock scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Slings Market
Baby Products
Italy Baby Care Products Market
Baby Products
Home Care Packaging Market
Baby Products
Baby Changing Light Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Netherlands Baby Care Products Market
Baby Products
Potty Training Seat Market
Baby Products
Tissue and Hygiene Market
Baby Products
US Baby Care Products Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Global Baby Play Mats Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Global Baby Carriers Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Feeding Pillow Market