
 Italy Baby Care Products Market | 2026-2036
Italy Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Baby Care Products Market Insights
Pharmacy channel purchasing among first-time parents is expanding as Italian consumers prioritize dermatologically tested infant formulations. Artsana Group leverages its pediatric heritage and Lombardy manufacturing base to anchor domestic production. Procter & Gamble competes through scale advantages in diaper and wipe categories across Tier-1 Italian cities. Beiersdorf AG differentiates with NIVEA Baby's hypoallergenic positioning and pharmacy shelf dominance.
Italy Baby Care Products encompass topical formulations, absorbent hygiene articles, and cleansing systems engineered for infant skin pH tolerance, typically ranging from 4.5 to 5.5, with tear-free surfactants and preservative-free claims driving premium positioning. Baby lotion and baby shampoo categories sustain above-average margins as parents trade up to organic-certified and allergen-tested variants. Diapers and baby wipes dominate volume throughput through supermarket and online retail channels, though eco-friendly packaging formats are capturing disproportionate growth in urban centers.
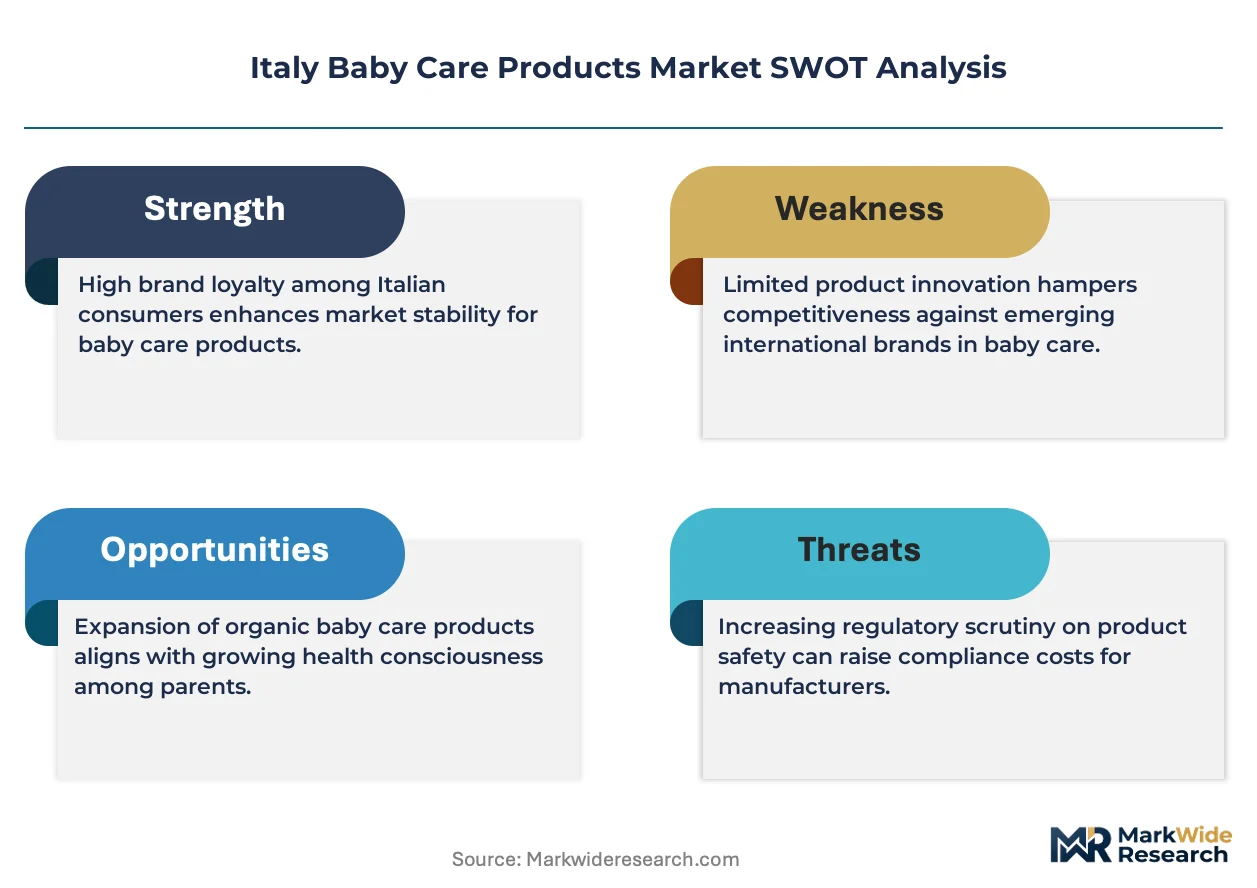
EU REACH restrictions on formaldehyde-releasing preservatives and Italy's Ministry of Health cosmetic vigilance system shape product reformulation cycles and import compliance costs for non-EU suppliers. ECHA substance evaluations and CE marking requirements for certain infant devices create layered regulatory barriers that favor established European manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor evolving EU Green Deal packaging mandates and potential national extended producer responsibility schemes that could reshape cost structures for single-use formats.
Market Dynamics
EU REACH chemical safety standards are forcing systematic reformulation cycles across Italian baby care manufacturing, compressing R&D timelines while elevating compliance costs for preservative-free and hypoallergenic product lines.
Growth Catalysts
- EU Green Deal packaging mandates:Italy's national extended producer responsibility schemes are accelerating demand for biodegradable diaper cores and recyclable wipe substrates among Lombardy-based manufacturers.
- Pharmacy channel expansion:First-time parents in Milan and Rome are prioritizing dermatologically tested infant formulations, driving shelf-space allocation toward allergen-certified SKUs.
- Biomaterial innovation:Organic cotton and bamboo fiber processing technologies are enabling premium positioning for absorbent hygiene articles with certified supply chain traceability.
Market Restraints
- Input cost volatility:Fluctuating prices for superabsorbent polymers and plant-based surfactants are compressing margins on mid-tier diaper and wipe categories.
- Regulatory friction:ECHA substance evaluations for formaldehyde-releasing preservatives are extending reformulation approval timelines by 12-18 months for non-EU ingredient suppliers.
- Supply concentration risk:Northern Italian industrial clusters around Lombardy dominate domestic manufacturing, creating geographic vulnerability to regional logistics disruptions.
Strategic Opportunities
- Underpenetrated southern regions:Campania and Sicily exhibit lower pharmacy-channel density for premium baby care, presenting whitespace for hypoallergenic product distribution expansion.
- Subscription commerce models:Direct-to-consumer replenishment platforms are capturing urban millennial parents seeking automated diaper and wipe delivery with eco-friendly packaging options.
- CE marking convergence:Infant care devices with dual cosmetic-medical classification can leverage streamlined regulatory pathways under EU MDR for premium pricing capture.
Industry Challenges
- Formulation chemistry expertise gap:Shortage of cosmetic toxicologists familiar with EU REACH dossier preparation is delaying product launch timelines for SME manufacturers.
- Legacy ERP integration:Batch-level traceability requirements for EU Green Deal compliance are forcing costly upgrades to manufacturing execution systems across family-owned production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Baby Care Products Market |
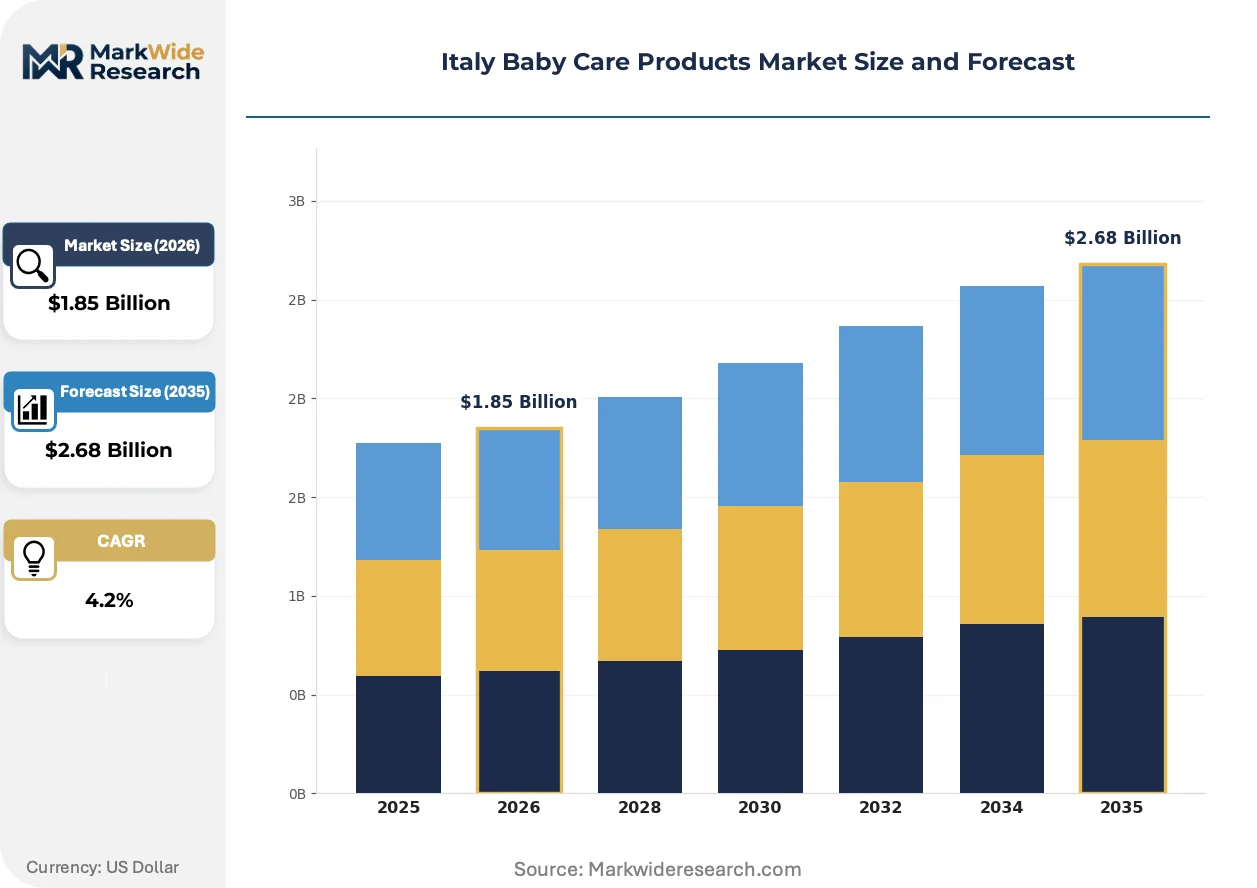
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Baby Wipes, Baby Lotion, Baby Shampoo Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Pharmacies Customer Type: Parents, Caregivers, Hospitals, Clinics Packaging Type: Single-use Packs, Bulk Packs, Eco-friendly Packaging, Refillable Containers |
| Companies Covered | Beiersdorf AG, Henkel AG & Co. KGaA, Procter & Gamble, Pigeon Corporation, Artsana Group, Johnson & Johnson, Unilever, Chicco, Kimberly-Clark Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Baby Care Products Market Trends and Innovations
Bio-based material science and regulatory chemistry are converging to reshape competitive positioning in Italian baby care, with formulation transparency and packaging circularity emerging as primary differentiation vectors.
Plant-derived superabsorbent polymers derived from corn starch and sugarcane bagasse are absorbing moisture-retention performance gaps versus petroleum-based alternatives. Premium diaper manufacturers in Lombardy are adopting these materials at accelerated pilot scales. This absorption of technical limitation is compressing the price premium between eco-certified and conventional absorbent hygiene articles.
Italy's Ministry of Health cosmetic vigilance system is tightening post-market surveillance requirements for infant topical products. Manufacturers must now maintain dedicated pharmacovigilance teams for adverse event reporting. Small and mid-sized brands lacking regulatory affairs infrastructure are outsourcing compliance to specialized consultancies or exiting the pharmacy channel entirely.
Millennial parents are conducting pre-purchase ingredient verification through mobile scanning applications before pharmacy or supermarket transactions. This behavior is elevating the importance of clean-label certification and EWG-verified ratings over traditional brand loyalty. Urban centers including Milan, Rome, and Turin exhibit the highest penetration of this verification-driven purchasing pattern.
Italy Baby Care Products Market Segmentation
Product architecture and channel configuration in Italian baby care are diverging as millennial parents trade up to premium formulations while EU Green Deal mandates force packaging reinvention. Segmentation strategy must reconcile these dual pressures to capture value across the forecast window.
Product Type:
Replacement cycles and upgrade intensity vary sharply across infant hygiene categories, with absorbent articles demanding frequent replenishment while topical formulations reward premium positioning through extended use intervals.
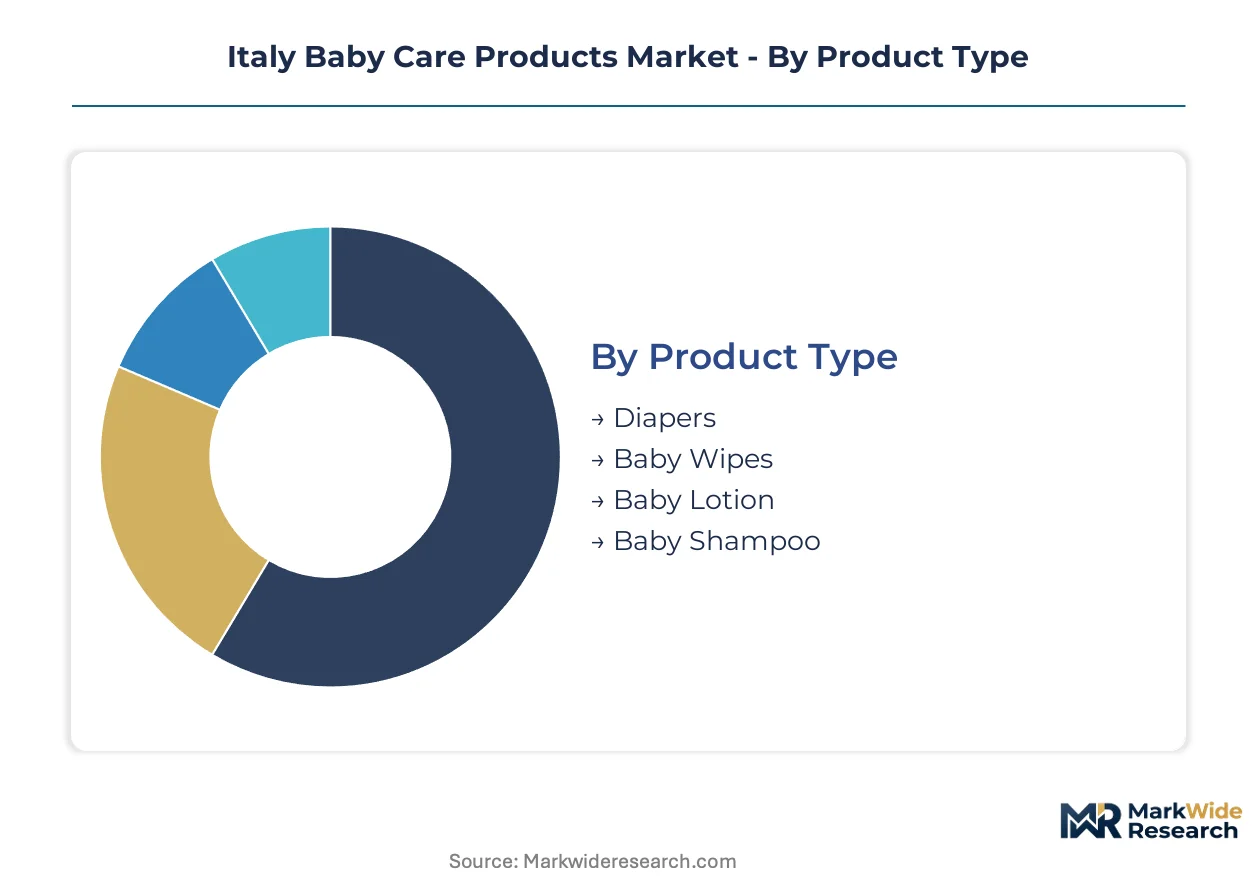
- Diapers:Superabsorbent polymer cores engineered for 12-hour moisture retention dominate manufacturing throughput in Lombardy industrial clusters. Demand concentrates among first-time parents in Milan and Rome seeking dermatologically certified variants, though margin pressure from bio-based material transitions is compressing mid-tier pricing power.
- Baby Wipes:Non-woven substrates with pH-balanced cleansing solutions sustain above-average purchase frequency through supermarket and online channels. Parents in northern Italian cities are trading toward preservative-free and fragrance-free formulations as ECHA substance evaluations tighten compliance requirements for formaldehyde-releasing compounds.
- Baby Lotion:Emollient formulations with ceramide and shea butter compositions target infant skin barrier repair.
- Baby Shampoo:Tear-free surfactant systems with neutral pH positioning capture pharmacy channel preference.
Volume placements concentrate in Diapers; the faster expansion belongs to Baby Wipes.
Distribution Channel:
Channel economics in Italian baby care split between high-frequency supermarket transactions and trust-intensive pharmacy consultations, with digital platforms capturing replenishment automation.
- Supermarkets:Mass-market diaper and wipe SKUs move through hypermarket chains with promotional pricing cycles. Shelf-space allocation in Lombardy and Veneto retail networks favors established brands with scale logistics, though private-label penetration is climbing in economy-tier absorbent hygiene.
- Online Retailers:Subscription commerce models with automated replenishment algorithms are capturing urban millennial parents in Turin and Bologna. Direct-to-consumer platforms emphasize eco-friendly packaging bundles and ingredient transparency portals that bypass traditional retail markups.
- Specialty Stores:Boutique maternity retailers in affluent Milan districts curate premium organic-certified assortments.
- Pharmacies:Hypoallergenic and allergen-tested formulations sustain shelf dominance through dermatologist recommendation networks.
Transaction density peaks in Supermarkets; the steepest expansion trajectory is occurring in Online Retailers.
Customer Type:
Procurement authority and volume scale diverge between household decision-makers and institutional purchasers, with reimbursement pathways shaping product specification in clinical settings.
- Parents:Millennial first-time buyers in northern Italian cities conduct pre-purchase ingredient verification through mobile applications. Their preference for organic-certified and EWG-rated formulations is elevating clean-label importance over legacy brand loyalty in pharmacy and specialty store environments.
- Caregivers:Professional childcare providers and grandparents represent secondary purchase influencers with distinct price sensitivity profiles.
- Hospitals:Neonatal units in Lombardy and Emilia-Romagna medical centers specify pH-neutral cleansing systems for infant hygiene protocols.
- Clinics:Pediatric dermatology practices drive prescription-adjacent recommendation patterns for therapeutic baby care formulations.
Household purchasing dominates absolute volume; institutional procurement is gaining share fastest through standardized tender processes.
Packaging Type:
Material circularity mandates under Italy's extended producer responsibility schemes are forcing rapid format transition, with biodegradability certifications becoming table stakes for premium positioning.
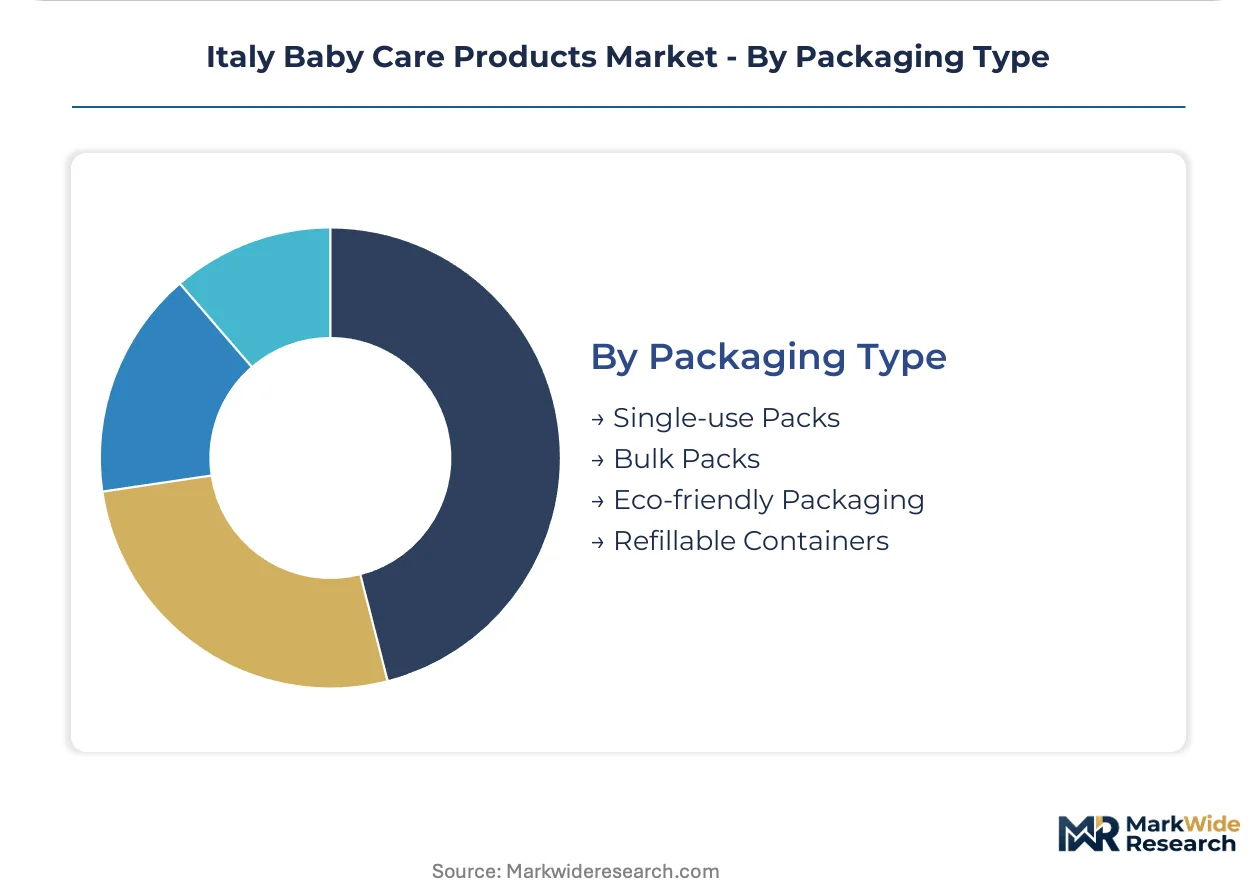
- Single-use Packs:Travel-sized sachets and individual wipe packets sustain convenience-driven demand in airport retail and hospitality channels. Regulatory pressure from EU Green Deal packaging reduction targets is compressing growth prospects for non-recyclable flexible film formats.
- Eco-friendly Packaging:Compostable diaper cores and recyclable wipe substrates derived from corn starch and sugarcane bagasse are absorbing technical performance gaps versus petroleum-based alternatives. Lombardy-based manufacturers are piloting these materials at accelerated scale to capture green premium pricing.
- Bulk Packs:Economy-scale diaper cartons target value-conscious multi-child households.
- Refillable Containers:Concentrate-and-dispense systems for baby lotion and shampoo reduce per-use plastic intensity.
Conventional formats still dominate volume throughput; Eco-friendly Packaging is climbing the fastest as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian baby care production concentrates in Lombardy's industrial belt, while consumption spreads unevenly across northern cities and underpenetrated southern regions. Regional disparities in pharmacy density and organic certification awareness create distinct market development profiles.
Lombardy
Milan anchors premium demand for hypoallergenic formulations and dermatologically tested infant care. The Ministry of Health's cosmetic vigilance system tightens post-market surveillance requirements for manufacturers headquartered here. Artsana Group leverages its pediatric heritage from Lombardy manufacturing bases to serve pharmacy channels across northern Italy.
Lazio
Rome's first-time parents drive pharmacy-channel expansion for allergen-certified baby lotions and tear-free shampoos. EU REACH chemical safety standards force systematic reformulation cycles among importers serving this metropolitan market. Urban retail networks here exhibit the highest penetration of mobile ingredient-scanning behavior among millennial buyers.
Veneto
Padua and Verona sustain above-average consumption of biodegradable diaper cores through supermarket and online retail channels. Italy's extended producer responsibility schemes under the EU Green Deal accelerate packaging transitions for manufacturers distributing through Veneto logistics hubs. Regional retail chains allocate expanding shelf space to eco-certified absorbent hygiene articles.
Campania
Naples and surrounding provinces present whitespace for premium baby care distribution expansion, with lower pharmacy-channel density than northern counterparts. ECHA substance evaluations for formaldehyde-releasing preservatives create compliance barriers for non-EU suppliers attempting entry. Local retail infrastructure favors mass-market diaper and wipe categories over specialized dermatological formulations.
Sicily
Palermo and Catania exhibit lagging adoption of organic-certified infant care relative to mainland cities. The national push for sustainable packaging under EU Green Deal mandates reaches this island region through delayed supply chain adjustments. Southern logistics constraints elevate landed costs for Lombardy-manufactured premium lines.
Italy Baby Care Products Market Competitive Landscape
Top-tier vendors anchor pharmacy and mass retail channels, while mid-tier specialists compete on organic certification and regional distribution reach. The vendor base splits between multinational consumer goods conglomerates with scale logistics and family-owned Italian manufacturers with pediatric heritage credentials. Strategic archetypes include EU regulatory compliance specialists, bio-based material innovators, and subscription commerce platform operators. Competitive moves center on M&A for regional distribution assets and backward integration into sustainable raw material sourcing.
Among Germany-based personal care conglomerates, Beiersdorf AG and Henkel AG & Co. KGaA occupy positions emphasizing dermatological credibility and pharmacy-channel penetration. Procter & Gamble represents the scale-driven multinational archetype with mass retail dominance across Tier-1 Italian cities. Artsana Group exemplifies the domestic heritage manufacturer leveraging Lombardy production infrastructure for pediatric-specialized positioning. These three anchors illustrate how regulatory compliance capability, manufacturing geography, and channel access stratify competitive positioning in this market.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Henkel AG & Co. KGaA |
| Procter & Gamble |
| Pigeon Corporation |
| Artsana Group |
| Johnson & Johnson |
| Unilever |
| Chicco |
| Kimberly-Clark Corporation |
| Others |
Pricing and Supply Chain Analysis
Millennial first-time parents in Milan and Rome concentrate purchasing authority for premium baby care, anchoring a pharmacy-led pricing model that rewards dermatological certification and organic formulation claims over volume discounts.
Pricing Analysis
Margin tightening in mid-tier diapers reflects bio-based material transitions and superabsorbent polymer cost volatility. Three-tier pricing structure across premium, standard, and economy levels separates EU REACH-compliant pharmacy formulations from mass-market supermarket SKUs and private-label alternatives. Price differentiation traces to certification grade and geographic delivery cost, with northern Italian urban buyers least sensitive to premium positioning while southern regions exhibit sharper economy-tier preference.
Supply Chain Analysis
Regional distribution centers in Lombardy operate hub-and-spoke patterns feeding pharmacy networks across northern Italy. Manufacturing concentrates in Italy, Germany, and France for finished formulations, while raw material dependencies include superabsorbent polymers, plant-based surfactants, and organic cotton fiber. Single-source vulnerability in bio-based polymer pilot production creates supply chain risk. Distribution runs through pharmacy wholesalers and supermarket chains with e-commerce platforms capturing replenishment automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's baby care sector sits at a materials-transition inflection, with corn starch and sugarcane bagasse superabsorbent polymers displacing petroleum-based cores in premium diaper manufacturing.
For Market Incumbents: Lock in pharmacy channel shelf dominance through accelerated EU REACH compliance certification and backward integration into Lombardy-based organic cotton processing. Artsana Group's pediatric heritage model demonstrates how regional manufacturing control neutralizes margin pressure from bio-material cost volatility. For New Entrants and Emerging Players: Southern Italian caregivers in Campania and Sicily represent an underserved buyer archetype with limited access to hypoallergenic pharmacy formulations. Direct-to-consumer subscription platforms with automated replenishment algorithms offer the most penetrable go-to-market angle for bypassing established retail gatekeepers. For Investors and Strategic Acquirers: The window for entry favors EU regulatory compliance specialists with dedicated pharmacovigilance infrastructure. Long-term viability hinges on acquisition targets possessing CE marking convergence capability for dual cosmetic-medical infant devices. Watch ECHA substance evaluation timelines for formaldehyde-releasing preservatives as the inflection signal for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU REACH Compliance Certification | Pharmacy channel access for Artsana Group and Beiersdorf AG depends on preservative-free dossier approval. |
| Bio-based Material Pilot Scale-Up | Lombardy manufacturers compress price premiums between eco-certified and conventional absorbent hygiene articles. |
| Subscription Commerce Platform Launch | Urban millennial parents in Turin and Bologna automate diaper replenishment through direct-to-consumer portals. |
| Southern Distribution Expansion | Campania and Sicily whitespace capture requires localized logistics partnerships beyond northern hub concentration. |
| CE Marking Convergence Investment | Dual cosmetic-medical classification unlocks premium pricing in neonatal unit procurement tenders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, combined with primary interviews across brand managers at consumer goods conglomerates, pharmacy category buyers, supply planners at Lombardy manufacturing facilities, and channel sales heads at supermarket chains. ECHA substance evaluation databases, Italy's Ministry of Health cosmetic vigilance reports, and EU Green Deal packaging mandate documentation provided regulatory boundary conditions. Bottom-up SKU-level volume estimates triangulated against top-down category spend analysis.
Granularity-level modeling operated at product type, distribution channel, customer segment, and packaging format dimensions, with regional consumption patterns calibrated to pharmacy density and organic certification awareness indices. CAGRs derived from trend extrapolation of millennial parent purchasing behavior and bio-based material adoption curves across the projection horizon. Superabsorbent polymer price trajectories and EU REACH reformulation cycle timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance evaluation delays and EU Green Deal packaging mandate enforcement intensity. Outputs reflect documented assumptions around bio-based material performance convergence and pharmacy channel expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Smart Baby Monitor Market
Baby Products
Baby Portable Co-Sleeper Market
Baby Products
Baby Pacifier Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
Baby Products Detergents Market
Baby Products
India Baby Care Products Market
Baby Products
Smart Bottle Warmers Market
Baby Products
Diaper Pails Market
Baby Products
Baby Prams and Strollers Market
Baby Products
Smart Pacifier Market
Baby Products
Baby Sleeping Bag Market
Baby Products
South Africa Baby Care Products Market
Baby Products
Baby Digital Monitor Market
Baby Products
Children Products Market
Baby Products
France Baby Care Products Market
Baby Products
Baby Changing Light Market