
 Baby Changing Light Market | 2026-2036
Baby Changing Light Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Changing Light Market Outlook
Specialty baby retail and direct-to-parent e-commerce channels are reshaping how manufacturers reach end buyers. Koninklijke Philips leverages its lighting technology heritage to dominate premium positioning in the LED segment. Graco anchors its presence through bundling with broader nursery furniture portfolios. Chicco competes on European design credentials and pediatric safety certifications.
A baby changing light is a purpose-built luminaire installed near diaper-changing stations, typically delivering warm color temperature output below 3000K with shielded housings to prevent direct infant eye exposure. Its primary commercial purpose is to provide adequate visibility for caregivers during nighttime or low-ambient changing routines without disrupting infant sleep cycles. LED units now lead product type segmentation due to energy efficiency mandates and declining component costs, while smart-enabled variants with motion detection and timer integration represent the fastest-growing margin pool. Wall-mounted installation types sustain the largest volume share in healthcare and daycare settings where permanent fixture standards apply.
FDA guidelines on infant sleep environment safety and CPSC nursery product standards shape material selection and electrical housing requirements for US-market units. Ecodesign and RoHS directives in Europe restrict hazardous substance content and mandate recyclability disclosures, tightening market access for non-compliant suppliers. Stakeholders must monitor evolving smart-home interoperability protocols and regional efficiency benchmarks to determine whether platform partnerships or proprietary control systems offer stronger defensible positioning.
Market Dynamics
LED efficacy gains and motion-sensing integration are collapsing the traditional premium-mid-economy tier boundaries, forcing suppliers to recalibrate hardware margins against software-enabled recurring revenue streams.
Growth Catalysts
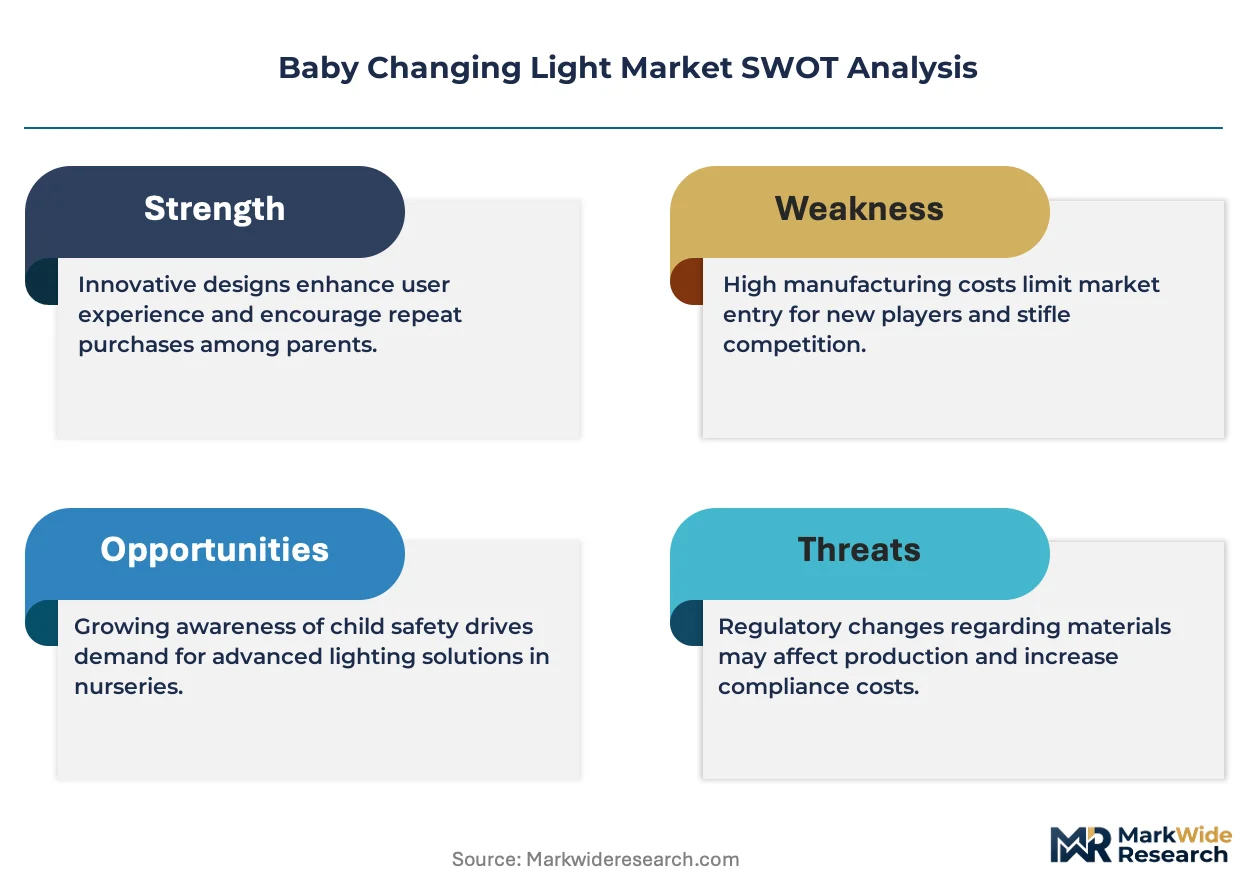
- Updated nursery safety codes:Municipal childcare licensing boards in the United States are mandating shielded luminaires with color temperature below 3000K, accelerating replacement cycles in legacy facilities.
- Daycare procurement standardization:Institutional buyers across Canada are consolidating vendor lists around pediatric safety certifications, concentrating volume with qualified suppliers.
- Smart-home interoperability protocols:Matter and Zigbee integration is enabling voice-activated dimming and sleep-cycle synchronization, expanding addressable demand among tech-forward parents.
Market Restraints
- LED driver component concentration:Sourcing vulnerability concentrates in Taiwanese semiconductor foundries, exposing finished goods to lead-time volatility.
- RoHS compliance friction:Ecodesign directive substance restrictions on cadmium and lead solder raise rework costs for legacy product lines targeting European markets.
- Substitute illumination methods:Smartphone flashlight apps and plug-in nightlights satisfy price-sensitive residential buyers, capping mass-market pricing power.
Strategic Opportunities
- Underpenetrated German childcare infrastructure:Federal Kita expansion funding is creating first-time fixture demand in newly constructed municipal daycare centers.
- Convergence of circadian lighting and infant monitoring:Integration with camera-based breathing detection systems opens premium bundling opportunities in private nursery renovations.
- Direct-to-parent subscription channels:Recurring revenue models for bulb replacement and firmware updates bypass traditional retail margin stacking.
Industry Challenges
- Firmware security certification timelines:FCC Part 15 testing for wireless-enabled units extends product launch schedules by four to six months.
- Optical engineer talent scarcity:Specialized expertise in infant-safe glare control and melanopic lux calculation concentrates in aging workforce cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Changing Light Market |
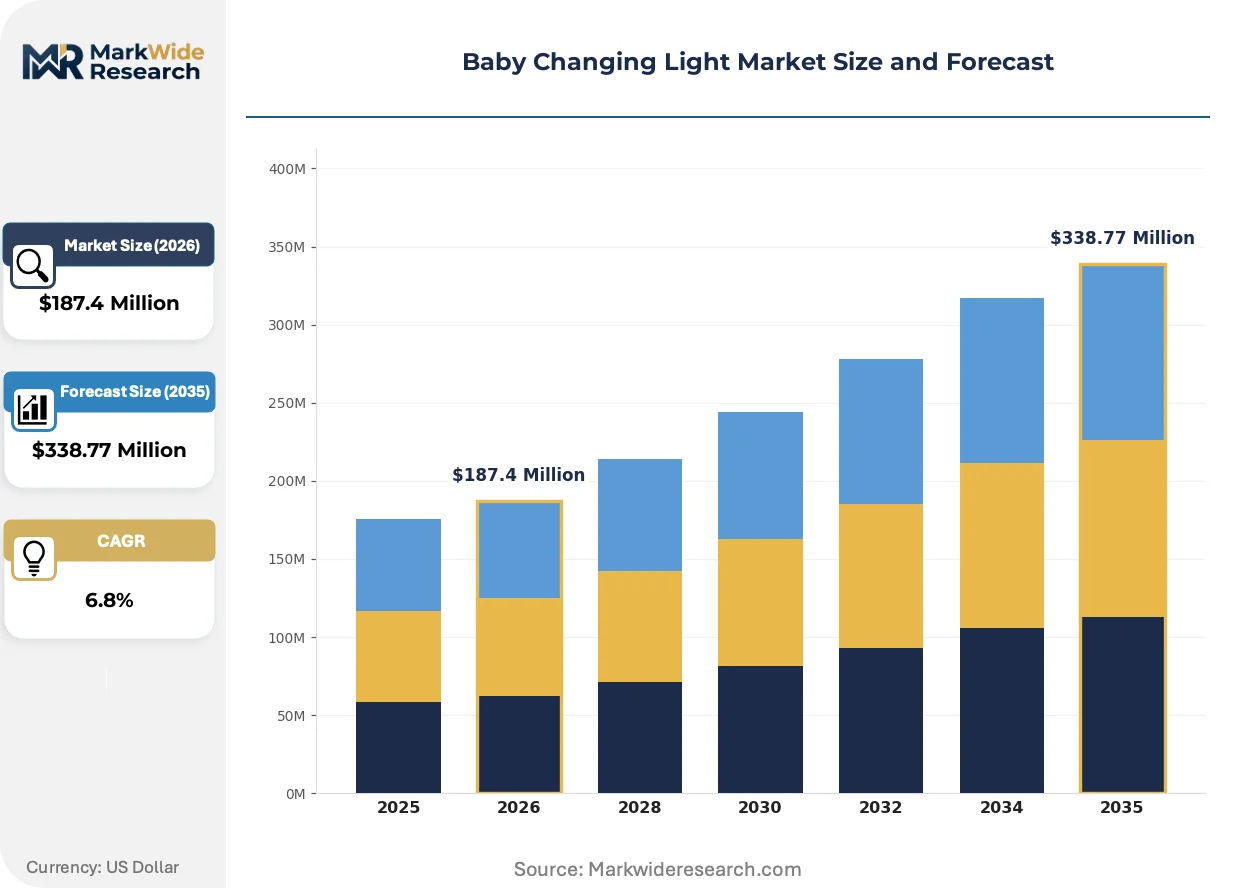
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Incandescent, Smart End User: Parents, Caregivers, Healthcare Facilities, Daycares Installation Type: Wall-mounted, Ceiling-mounted, Portable, Tabletop Safety Features: Motion Detection, Timer, Dimmer, Water-resistant |
| Companies Covered | Koninklijke Philips, Graco, Chicco, Evenflo, Skip Hop, Munchkin, Summer Infant, Angelcare, Koala Kare Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Changing Light Market Strategic Shifts
Product development trajectories center on sensor fusion, regulatory pre-certification, and channel disintermediation. Each trend compresses legacy competitive advantages while opening new margin pools.
Chip-on-board LED arrays with integrated driver electronics are collapsing the cost delta between basic and tunable white units. Daycare procurement departments in Texas and California are specifying these modules for new construction, eliminating the separate driver housing that previously distinguished premium from standard tiers. The structural consequence is margin compression for assemblers lacking in-house semiconductor packaging capabilities.
REACH substance restrictions on halogenated flame retardants are forcing housing material transitions to mineral-filled thermoplastics. European importers must now submit full material disclosure documentation to ECHA, adding compliance overhead that disadvantages small-batch suppliers. German and Dutch distributors are consolidating sourcing around manufacturers with pre-certified polymer supply chains.
Hospital gift shop and postpartum retail channels are losing ground to telehealth-integrated e-commerce platforms where pediatricians prescribe specific fixture models. New parent cohorts in Massachusetts and Washington State receive curated product links through patient portal apps, bypassing traditional brick-and-mortar discovery. This behavioral shift rewards suppliers with clinical endorsement relationships and punishes pure retail brands.
Baby Changing Light Market Segmentation
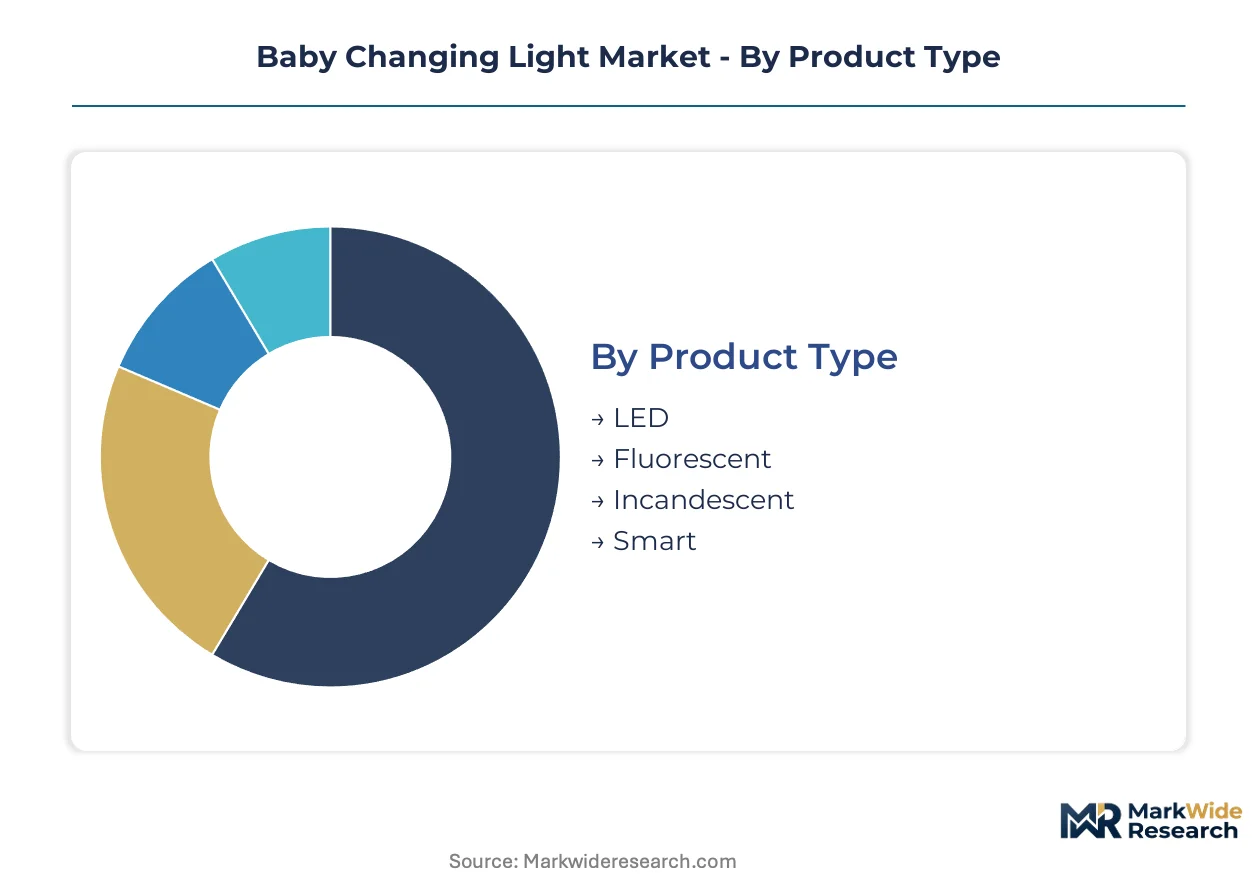
Segmentation in the baby changing light market reveals divergent replacement cycles and margin structures across hardware categories. Understanding which segments turn over fastest versus which sustain longest installed-base lifespans shapes inventory planning and R&D prioritization for manufacturers serving institutional and residential buyers simultaneously.
Product Type:
Replacement cycles vary dramatically across illumination technologies, with semiconductor-dependent segments refreshing fastest and legacy filament technologies lingering longest in residual installations.
- LED:Chip-on-board arrays with integrated drivers dominate new construction specifications in Texas and California daycare facilities. Efficacy improvements above 150 lumens per watt and collapsing component costs are compressing premium-mid-economy tier boundaries, forcing suppliers to recalibrate hardware margins.
- Smart:Motion-sensing units with Matter and Zigbee interoperability represent the steepest expansion trajectory, though FCC Part 15 testing extends launch schedules by four to six months. Firmware-enabled recurring revenue streams offset compressed hardware margins.
- Fluorescent:Legacy T5 and compact fluorescent installations persist in older healthcare facilities with deferred capital budgets; mercury content restrictions under EPA universal waste rules accelerate phase-out timelines.
- Incandescent:Residual demand concentrates in price-sensitive residential replacement purchases where warm color rendering remains the sole selection criterion; Ecodesign directive bans in Europe eliminate this segment entirely for EU-bound suppliers.
LED dominates installed base. Smart is where expansion concentrates.
End User:
Customer type determines purchasing authority structure, with institutional procurement departments imposing certification requirements that residential buyers ignore entirely.
- Healthcare Facilities:Hospital maternity wards and pediatric clinics specify shielded housings below 3000K color temperature under Joint Commission environment-of-care standards; bulk purchasing through group purchasing organizations concentrates volume with qualified vendors.
- Daycares:Municipal licensing boards in Massachusetts and Washington State mandate pediatric safety certifications, consolidating vendor lists around pre-qualified suppliers; federal Kita expansion funding in Germany creates first-time fixture demand in newly constructed municipal centers.
- Parents:Direct-to-consumer e-commerce channels bypass traditional retail margin stacking; telehealth-integrated platforms where pediatricians prescribe specific models reshape discovery patterns.
- Caregivers:Nanny-employed households and informal childcare arrangements prioritize portable and tabletop installation types over permanent fixtures; price sensitivity caps willingness-to-pay below institutional thresholds.
Healthcare Facilities anchor procurement standardization. Daycares are climbing the fastest as regulatory mandates tighten.
Installation Type:
Mounting configuration dictates supply chain requirements, with permanent fixtures demanding electrical contractor relationships and portable units flowing through consumer retail channels.
- Wall-mounted:Permanent fixture standards in healthcare and daycare settings sustain the largest volume share; hardwired installations require NEC Article 410 compliance and licensed electrician labor, creating switching costs that extend replacement cycles.
- Portable:Battery-powered and plug-in units serve traveling parents and multi-room residential use; smartphone flashlight substitution limits pricing power in this segment.
- Ceiling-mounted:Recessed and surface-mounted variants integrate with HVAC and fire suppression systems in new commercial construction; coordination with MEP trades extends project timelines.
- Tabletop:Clip-on and freestanding units compete with general-purpose nightlights; minimal differentiation drives commodity pricing dynamics.
Wall-mounted dominates installed base. Portable is gaining share fastest as residential mobility preferences shift.
Safety Features:
Feature integration separates certified institutional-grade products from basic residential offerings, with sensor fusion commanding premium positioning.
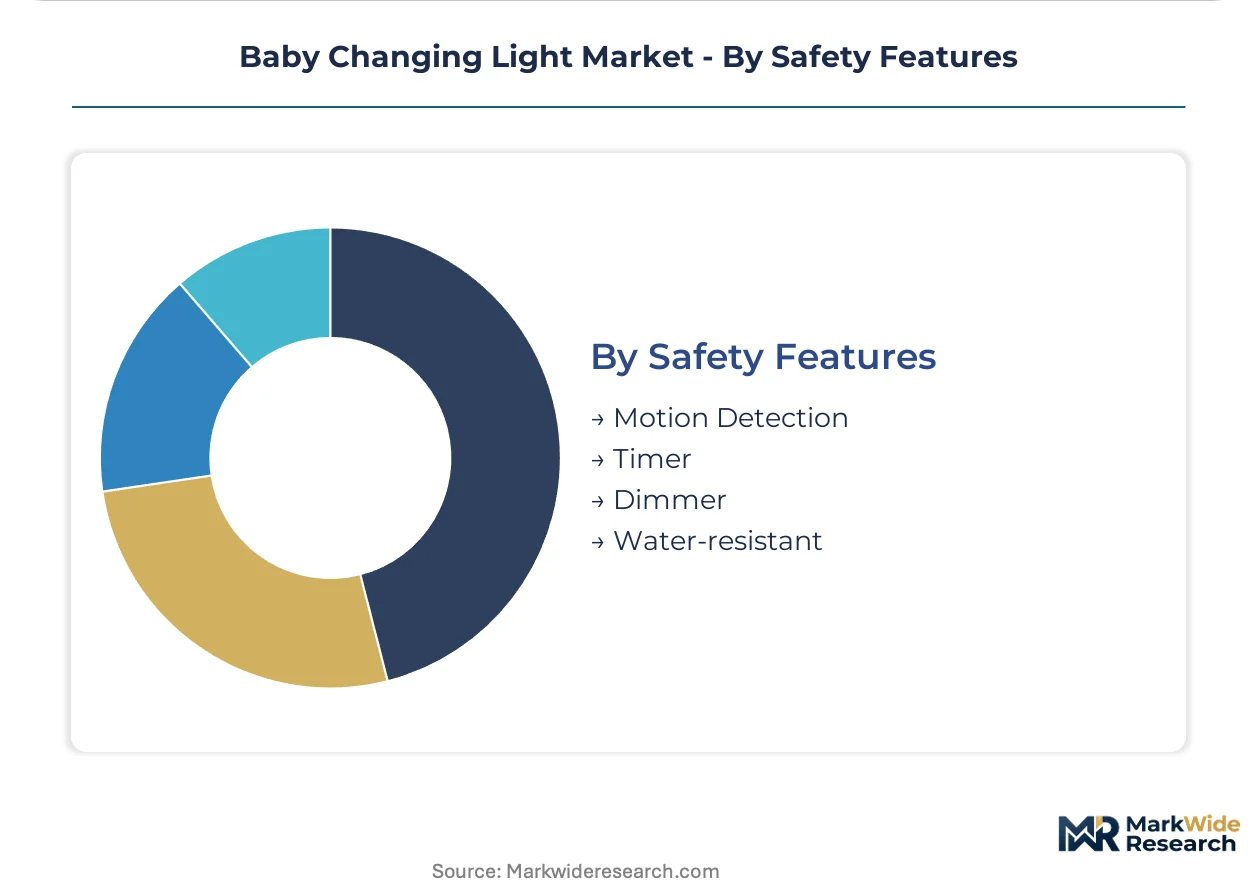
- Motion Detection:Passive infrared and microwave sensors enable hands-free activation for caregivers holding infants; integration with camera-based breathing detection systems opens premium bundling opportunities in private nursery renovations.
- Timer:Programmable auto-shutoff prevents overnight illumination exposure; sleep-cycle synchronization features appeal to tech-forward parent cohorts in Massachusetts and Washington State.
- Dimmer:Analog and digital dimming circuits accommodate circadian lighting protocols; melanopic lux calculation expertise concentrates in aging workforce cohorts, creating capability scarcity.
- Water-resistant:IP44 and higher ingress protection ratings satisfy CPSC nursery product standards for proximity to changing surfaces; housing material transitions to mineral-filled thermoplastics respond to REACH flame retardant restrictions.
Motion Detection dominates feature prioritization. Timer integration is expanding most quickly as sleep hygiene awareness spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidelines on infant sleep environment safety anchor regulatory frameworks in the United States, while ECHA and RoHS directives govern European market access. Municipal childcare licensing boards and federal infrastructure programs are accelerating fixture replacement cycles across distinct national contexts.
United States
Daycare procurement standardization concentrates volume with qualified suppliers as municipal licensing boards mandate shielded luminaires below 3000K color temperature. Joint Commission environment-of-care standards govern hospital maternity ward specifications. Texas and California daycare facilities specify chip-on-board LED arrays for new construction, eliminating separate driver housings.
Germany
Federal Kita expansion funding creates first-time fixture demand in newly constructed municipal daycare centers. REACH substance restrictions on halogenated flame retardants force housing material transitions to mineral-filled thermoplastics. German and Dutch distributors consolidate sourcing around manufacturers with pre-certified polymer supply chains.
Canada
Institutional buyers consolidate vendor lists around pediatric safety certifications, concentrating volume with qualified suppliers. Health Canada and PMRA nursery product standards shape material selection requirements. Provincial childcare infrastructure investment accelerates replacement cycles in legacy facilities.
United Kingdom
Ecodesign directive substance restrictions on cadmium and lead solder raise rework costs for legacy product lines. Telehealth-integrated e-commerce platforms reshape discovery patterns as pediatricians prescribe specific fixture models. Greater London procurement departments specify permanent wall-mounted installations for new childcare infrastructure.
Japan
METI efficiency benchmarks and JIS standards drive LED efficacy improvements above 150 lumens per watt. Smart-home interoperability protocols enable voice-activated dimming among tech-forward parent cohorts. Tokyo and Osaka metropolitan nurseries specify motion-sensing units with sleep-cycle synchronization features.
Baby Changing Light Market Competitive Environment
Lighting technology heritage and nursery furniture portfolios split the market between component specialists and integrated solution providers. The vendor base concentrates around three strategic archetypes: semiconductor-integrated lighting manufacturers, diversified juvenile product conglomerates, and childcare facility fixture specialists. Dominant competitive moves include strategic partnerships for smart-home interoperability certification and portfolio diversification into circadian lighting systems.
Within the heritage lighting tier, Koninklijke Philips occupies a position exemplifying semiconductor-integrated manufacturing capabilities. Graco and Chicco represent diversified juvenile product portfolios that bundle fixtures with broader nursery furniture offerings. These three anchors demonstrate how European design credentials and pediatric safety certifications create defensible positioning against pure retail brands.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Graco |
| Chicco |
| Evenflo |
| Skip Hop |
| Munchkin |
| Summer Infant |
| Angelcare |
| Koala Kare Products |
| Others |
Value Chain & Pricing Dynamics
Taiwanese semiconductor foundry capacity for LED driver ICs constrains finished-goods pricing power, as lead-time volatility ripples through to tiered fixture pricing across North American and European distribution channels.
Pricing Analysis
Price spreads between German-engineered premium units and mass-market Asian imports reach three-to-one multiples in retail channels. Three-tier pricing structure across premium, standard, and economy levels separates Matter-certified smart fixtures from basic LED arrays and residual incandescent replacements. Cost compression in the mid-tier is intensifying because chip-on-board integration collapses component differentiation. Residential caregivers exhibit highest price sensitivity, while Joint Commission-compliant healthcare procurement shows lowest elasticity due to bundled service contracts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for housing plastics and driver electronics. Manufacturing concentrates in China, Taiwan, and Vietnam for LED chip packaging, PCB assembly, and thermoplastic molding. Raw material dependencies span gallium nitride substrates, copper-clad laminates, and mineral-filled polymer resins. Single-source vulnerability in Taiwanese semiconductor foundries threatens production continuity. Distribution runs through group purchasing organizations for institutional buyers and direct-to-parent e-commerce for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart-home platform economics are reconfiguring competitive boundaries as Matter interoperability transforms hardware margins into software-enabled recurring revenue streams.
For Market Incumbents: Insulate premium positioning through captive semiconductor packaging capabilities that neutralize chip-on-board cost compression. Secure pediatric safety certification moats against direct-to-consumer entrants lacking clinical endorsement relationships. Defensive consolidation around firmware update infrastructure preserves recurring revenue against pure retail brands. For New Entrants and Emerging Players: Establish a beachhead in German Kita expansion procurement, where federal infrastructure funding creates first-time fixture demand without entrenched vendor relationships. Target portable and tabletop segments where smartphone flashlight substitution has suppressed incumbent R&D investment. Pursue telehealth-integrated prescription channels as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a circadian lighting platform play because infant sleep-cycle synchronization represents extensible IP into broader pediatric wellness ecosystems. Acquisition targets should display optical engineering talent depth and pre-certified polymer supply chains. Watch firmware security certification timelines as the signal indicating which suppliers can sustain premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Interoperability Certification | Voice-activated dimming through Alexa and Google Home expands addressable demand among tech-forward parent cohorts. |
| Backward Integration into LED Packaging | In-house chip-on-board capabilities collapse cost deltas between tunable white and basic fixture tiers. |
| Pediatric Safety Certification Investment | CPSC and Joint Commission pre-qualification consolidates vendor lists for institutional procurement departments. |
| Telehealth Platform Partnership | Prescription through patient portal apps in Massachusetts and Washington State bypasses traditional retail discovery. |
| Circadian Lighting R&D Expansion | Melanopic lux calculation expertise addresses capability scarcity in aging optical engineering workforce cohorts. |
Study Parameters
Initial hypotheses were tested against primary input from nursery furniture procurement managers, pediatric clinic facilities directors, daycare licensing board inspectors, and LED component sourcing leads, and refined through secondary validation against SEC filings of diversified juvenile product conglomerates, CPSC recall databases, ECHA substance restriction updates, and customs trade records for lighting fixture imports. Bottom-up segment sizing triangulated with top-down market reconstruction.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by illumination technology, end-user category by purchasing authority structure, installation type by supply chain requirements, and safety feature integration by certification tier. CAGRs derived from replacement cycle analysis and new construction fixture specifications. Forecast inputs included municipal childcare infrastructure investment flows and smart-home protocol adoption curves.
Sensitivities concentrate around Taiwanese semiconductor foundry utilization rates and REACH substance restriction expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Global Pregnancy Pillow Market
Baby Products
Baby Shoes Market
Baby Products
Baby Seat Liners Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Kids Activity Box Market
Baby Products
Baby Portable Co-Sleeper Market
Baby Products
Portable Cribs Market
Baby Products
Baby Bottle Warmer and Sterilizer Market
Baby Products
LAMEA Baby Care Products Market
Baby Products
Smart Crib Market
Baby Products
Baby Bottle Holder Market
Baby Products
Global Baby Mattresses Market
Baby Products
Baby Care Products Market
Baby Products
Baby Stroller Market