
 Global Baby Carriers Market | 2026-2036
Global Baby Carriers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baby Carriers Market Analysis
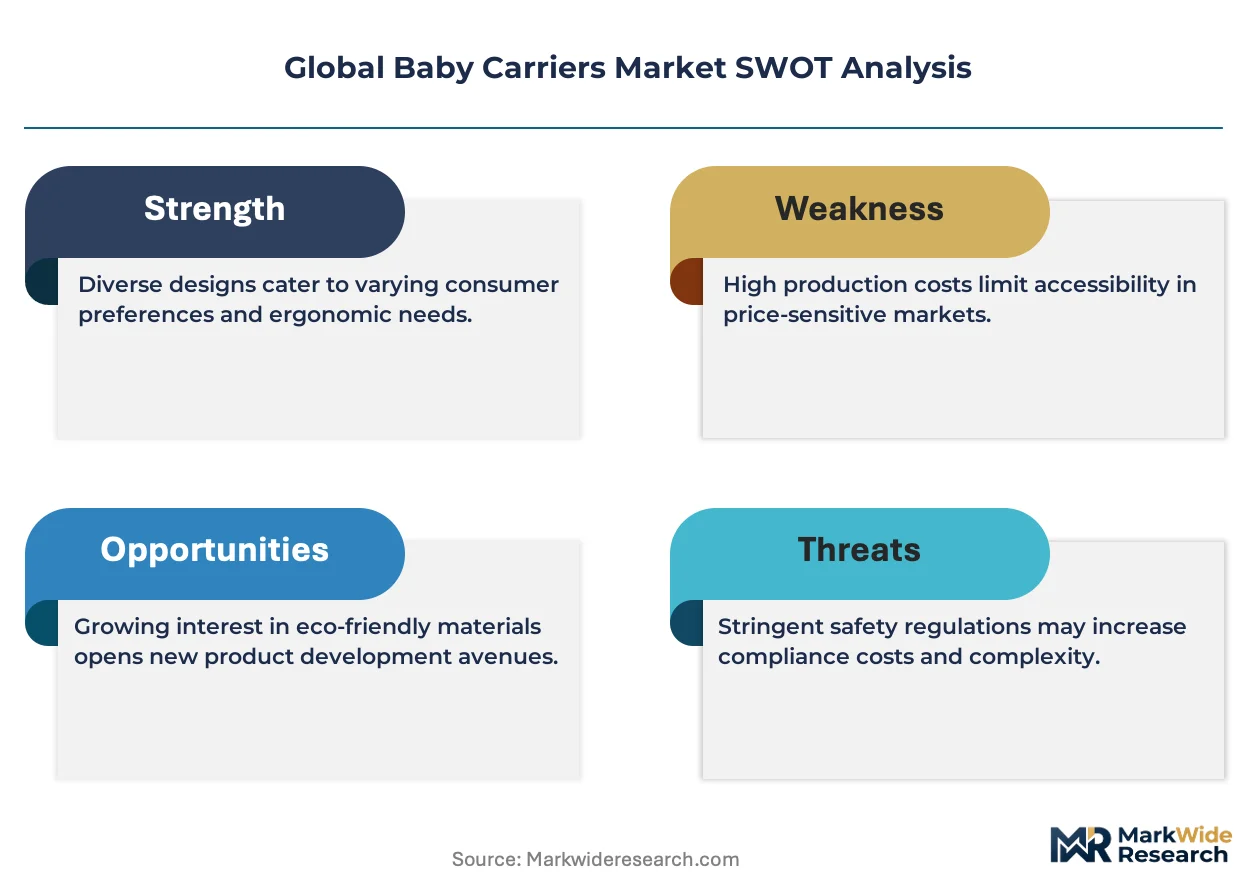
Organic cotton is decoupling from conventional textile economics as certification premiums narrow and supply chains stabilize. ERGObaby Carrier Inc. leverages its vertically controlled manufacturing in Vietnam to secure GOTS-certified fabric volumes. BabyBjorn AB anchors its Nordic design heritage through pediatric-orthopedist collaborations that validate hip-safe positioning. Goodbaby International Holdings Limited dominates Asian mass retail through distributor networks spanning tier-one and tier-two Chinese cities.
A baby carrier is a wearable infant-transport device constructed from woven or knit textiles, structured foam padding, and adjustable buckle or strap systems, engineered to distribute infant weight across the caregiver's torso, hips, and shoulders for extended carrying without musculoskeletal strain. Soft structured carriers command the largest revenue pool due to their balance of ergonomic support and ease of use, while wrap-style products sustain niche premium positioning among attachment-parenting communities. Mesh-material variants represent the fastest-growing material segment as breathability becomes a non-negotiable specification in humid climates and active-use scenarios.
The US Consumer Product Safety Commission enforces mandatory sling carrier standards under ASTM F2907, while the EU's General Product Safety Directive and CE marking requirements shape product-access protocols for European imports. Japan's Ministry of Economy, Trade and Industry (METI) administers consumer product safety surveys that influence retailer stocking decisions for imported babywearing goods. Stakeholders must monitor evolving chemical-restriction lists under REACH and state-level flame-retardant bans in the US, as material-compliance costs will determine which suppliers retain shelf space in regulated channels.
Market Dynamics
Ergonomic certification requirements under the EU's General Product Safety Directive are compressing product development timelines while simultaneously elevating material specifications across all price tiers, forcing manufacturers to reconfigure supplier relationships.
Growth Catalysts
- Dual-income household expansion:China's urban centers generate concentrated demand for premium babywearing solutions as professional parents prioritize mobility without sacrificing infant proximity.
- ASTM F2907 enforcement:The US Consumer Product Safety Commission's mandatory sling carrier standards professionalize product safety claims and filter substandard imports from mass retail channels.
- Mesh textile innovation:Breathable synthetic weaves address humidity-driven comfort requirements in Southeast Asian and Gulf state markets, opening previously constrained seasonal sales windows.
Market Restraints
- GOTS cotton premium volatility:Organic fiber certification costs fluctuate with weather-impacted harvests in India and Turkey, compressing margin predictability for certified product lines.
- Single-source foam dependency:High-density polyethylene padding production concentrates in Guangdong province, creating vulnerability to regional logistics disruptions or energy rationing.
- REACH chemical restriction cascade:The European Chemicals Agency's evolving substance restrictions force iterative material reformulation, extending qualification cycles by 8-14 months.
Strategic Opportunities
- Brazilian mass-market penetration:ANVISA regulatory harmonization with ISO standards reduces import friction, enabling distributor network establishment ahead of local manufacturing capacity.
- Rental-subscription channel emergence:Nordic urban parents demonstrate willingness to lease carriers across infant growth stages, creating recurring revenue models distinct from unit sales.
- Telehealth integration:Pediatric orthopedist-validated positioning data streams into postpartum digital care platforms, embedding product selection within medical guidance workflows.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized expertise in infant spine-load distribution remains concentrated in academic research centers, constraining in-house R&D scaling.
- Multi-jurisdiction certification backlog:Simultaneous CE marking, ASTM compliance, and Japan METI survey preparation creates parallel testing costs that strain mid-tier manufacturer cash reserves.
- Legacy distributor contract renegotiation:Established Asian retail partnerships lock in margin structures incompatible with direct-to-consumer pricing transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baby Carriers Market |
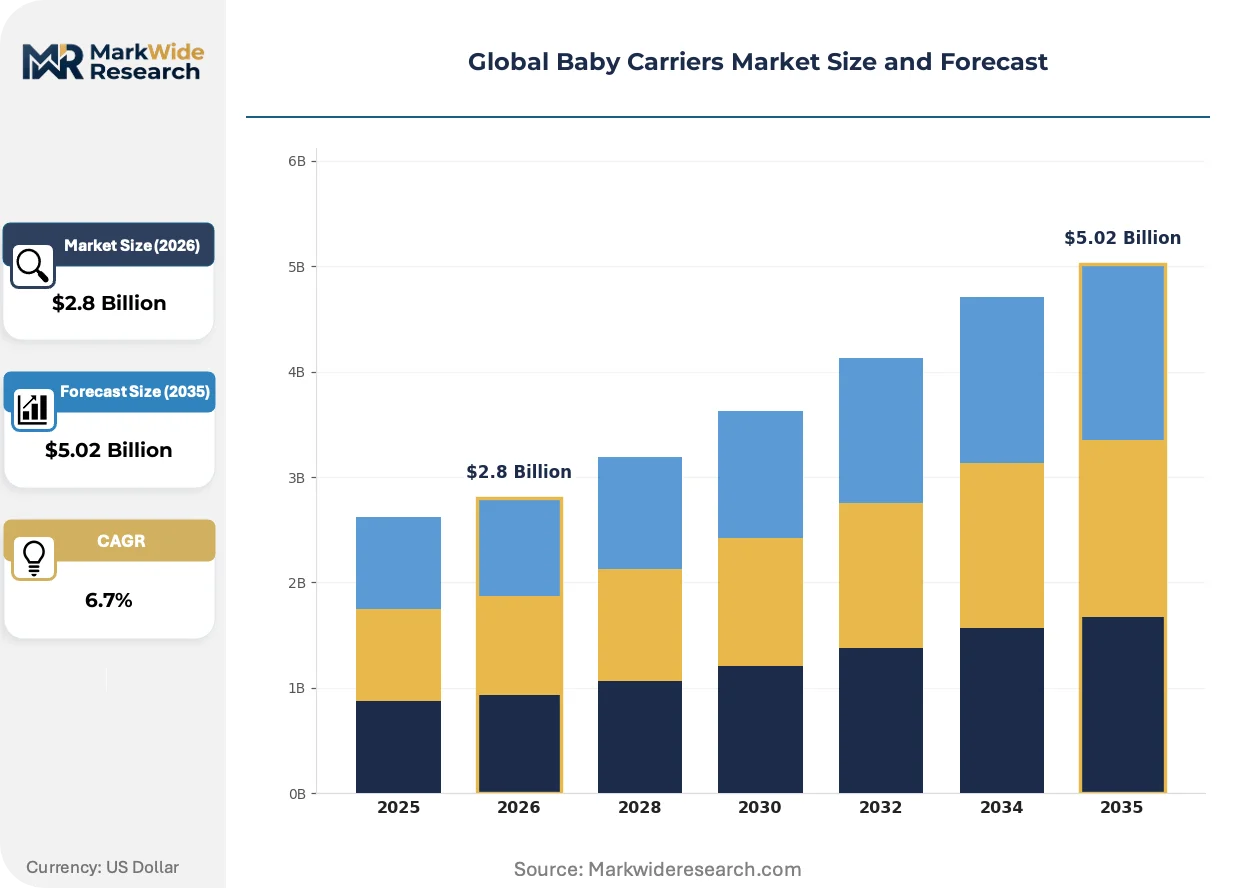
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Structured Carriers, Wraps, Sling Carriers, Frame Carriers End User: Parents, Caregivers, Childcare Providers, Retailers Material: Cotton, Polyester, Nylon, Mesh Weight Capacity: 0-15 lbs, 15-30 lbs, 30-45 lbs, 45 lbs & above |
| Companies Covered | ERGObaby Carrier Inc., BabyBjorn AB, Infantino LLC, Combi Corp, Artsana Spa, Boba Inc., Baby K'tan LLC, Lillebaby LLC, Goodbaby International Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baby Carriers Market Emerging Trajectories
Material science convergence with digital health validation protocols is redefining product differentiation beyond aesthetic positioning, creating new competitive moats around clinical credibility and supply chain traceability.
Adaptive tension-distribution mesh is absorbing sweat-management functionality from separate accessory products into primary carrier construction. Active parents in Singapore and Sydney reject detachable cooling inserts in favor of integrated ventilation channels. This consolidation is absorbing aftermarket accessory revenue into upfront product pricing, compressing the addressable market for complementary goods.
REACH substance restriction lists now explicitly target flame retardants and phthalates in infant textile applications. European importers face batch-testing mandates at port of entry, diverting non-compliant shipments to secondary markets. Soft-structured carrier segments with foam padding components absorb the highest compliance costs, accelerating material substitution toward natural fiber alternatives.
Certification-driven preference formation now precedes brand consideration for first-time parents. Hospital discharge bag partnerships and midwife recommendation networks displace traditional retail discovery in Germany and the Netherlands. This channel migration concentrates volume with suppliers possessing institutional procurement credentials, marginalizing pure-play e-commerce entrants lacking clinical validation relationships.
Global Baby Carriers Market Segmentation
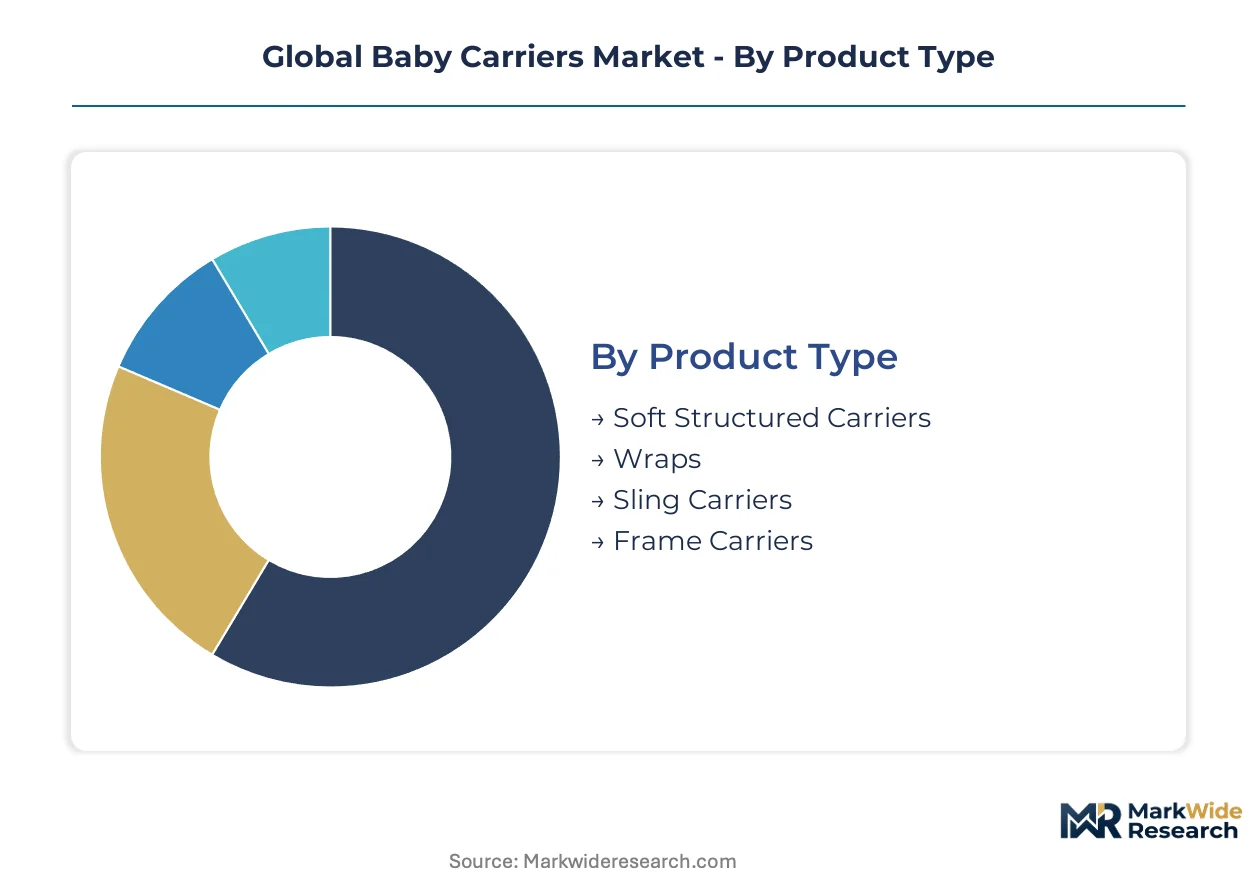
Segmentation in the baby carriers market determines which certification pathways manufacturers must navigate and which distribution channels prove viable. Product type and material composition dictate regulatory burden intensity, while end-user classification shapes pricing architecture and marketing investment.
Product Type:
ASTM F2907 compliance requirements vary sharply across construction methodologies, with sling-style products facing the most stringent sling carrier standards while frame carriers trigger additional mechanical safety protocols.
- Soft Structured Carriers:These products combine structured foam padding with adjustable buckle systems for ergonomic weight distribution across caregiver hips and shoulders. Dual-income households in Chinese tier-one cities concentrate demand here, prioritizing premium solutions that enable professional mobility without sacrificing infant proximity.
- Wraps:Long woven or knit fabric lengths require manual tying techniques and appeal to attachment-parenting communities seeking customizable positioning. Nordic urban parents in Stockholm and Copenhagen demonstrate willingness to lease wrap carriers across infant growth stages, creating recurring revenue models distinct from unit sales.
- Sling Carriers:Single-shoulder designs with ring or pouch construction face mandatory ASTM F2907 enforcement in US retail channels.
- Frame Carriers:External backpack-style aluminum or polymer frames support extended hiking and outdoor use with enhanced load-bearing capacity.
Soft Structured Carriers sits at the top of the volume ranking, with Mesh-material variants climbing the fastest through integration into breathable carrier construction.
End User:
Customer type determines channel economics, with institutional procurement credentials becoming prerequisites for volume concentration as hospital discharge bag partnerships displace traditional retail discovery.
- Parents:First-time buyers in Germany and the Netherlands now form preferences through midwife recommendation networks and clinical validation relationships before considering brand attributes. This certification-driven preference formation concentrates volume with suppliers possessing institutional procurement credentials.
- Caregivers:Grandparents and extended family members purchasing secondary carriers prioritize simplicity and intuitive adjustment mechanisms over advanced ergonomic features.
- Childcare Providers:Daycare centers and nursery facilities require multi-user durability and standardized sizing to accommodate varying staff physiques.
- Retailers:Buyers for mass-market chains and specialty boutiques face margin compression from legacy distributor contracts incompatible with direct-to-consumer pricing transparency.
Parents command the dominant revenue share, with Childcare Providers expanding most quickly as professional early childhood services proliferate in urban markets.
Material:
REACH chemical restriction lists explicitly target flame retardants and phthalates in infant textile applications, diverting batch-testing costs unevenly across fiber categories.
- Cotton:Natural fiber alternatives absorb the highest compliance cost acceleration as foam-padded segments face REACH substance restrictions. GOTS-certified organic cotton volumes from India and Turkey supply ERGObaby's vertically controlled Vietnamese manufacturing.
- Polyester:Synthetic durability supports machine-washable construction for high-frequency use scenarios in commercial childcare settings.
- Nylon:High tensile strength enables lightweight webbing and strap systems with abrasion resistance.
- Mesh:Breathable synthetic weaves address humidity-driven comfort requirements in Singapore, Sydney, and Gulf state markets, opening previously constrained seasonal sales windows through integrated ventilation channels.
Cotton retains volume leadership, with Mesh gaining share fastest as breathability becomes non-negotiable in humid climates and active-use scenarios.
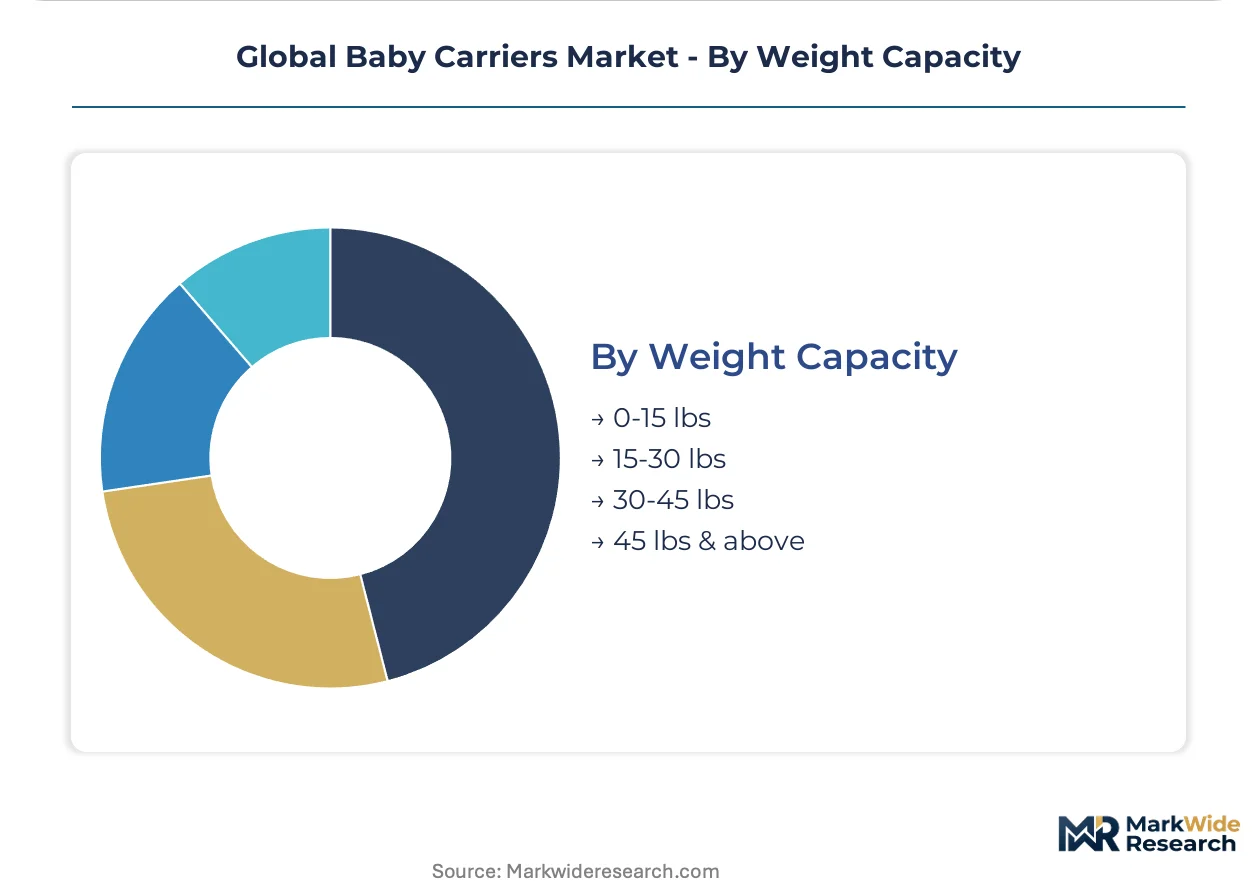
Weight Capacity:
Load rating segmentation aligns with infant developmental stages and corresponding hip-safe positioning requirements validated through pediatric-orthopedist collaborations.
- 0-15 lbs:Newborn-specific designs emphasize head support and fetal-position accommodation for the earliest weeks.
- 15-30 lbs:The broadest addressable window captures seated carrying from approximately four months through toddlerhood.
- 30-45 lbs:Extended-use construction serves preschool-age children in back-carry configurations.
- 45 lbs & above:Specialized hiking and special-needs applications require reinforced frame structures and load-bearing hip belts.
15-30 lbs dominates unit volume, with 0-15 lbs showing steepest expansion trajectory as ergonomic newborn positioning gains clinical validation priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors baby carrier manufacturing through vertically controlled production corridors serving export demand. Regulatory divergence across import markets fragments compliance pathways. Urban consumption clusters in Shanghai, Tokyo, and Munich concentrate premium purchasing power.
United States
ASTM F2907 enforcement by the US Consumer Product Safety Commission filters substandard sling carriers from mass retail channels. Dual-income households in Seattle and Austin drive premium ergonomic adoption. California's flame-retardant restrictions under Proposition 65 extend material testing burdens beyond federal minimums.
Germany
Midwife recommendation networks in Berlin and Hamburg displace traditional retail discovery for first-time parents. REACH substance restrictions by the European Chemicals Agency mandate iterative material reformulation. Bavaria's pediatric-orthopedist validation programs embed product selection within medical guidance workflows.
China
Dual-income households in Shanghai and Beijing prioritize premium babywearing solutions enabling professional mobility. SAMR consumer product safety surveys influence retailer stocking decisions for domestic and imported goods. Guangdong's foam padding production concentration creates vulnerability to regional logistics disruptions.
Japan
METI consumer product safety administration shapes import protocols for babywearing goods through pre-market survey requirements. Tokyo's dense urban transit environment sustains demand for compact, lightweight carrier formats. Osaka-based distributor networks lock in margin structures resistant to direct-to-consumer pricing transparency.
Australia
TGA-aligned state-level product safety frameworks govern infant textile imports through harmonized testing protocols. Sydney and Melbourne parents reject detachable cooling inserts in favor of integrated mesh ventilation. Queensland's humidity-driven comfort requirements accelerate breathable synthetic weave adoption.
Global Baby Carriers Market Vendor Landscape
Global majors compete with regional champions across certification pathways and channel access. The vendor base stratifies into three tiers: vertically integrated manufacturers with captive GOTS-certified supply, design-centric Nordic specialists leveraging clinical validation, and Asian mass-market distributors spanning tier-one and tier-two cities. Dominant competitive moves include backward integration into Vietnamese textile production and strategic partnerships with pediatric-orthopedist research centers.
Within the vertically integrated tier, ERGObaby Carrier Inc. and Goodbaby International Holdings Limited exemplify divergent geographic anchoring strategies. BabyBjorn AB occupies a position representing Nordic design heritage and clinical credibility archetypes. These three entities collectively illustrate how certification-driven preference formation concentrates volume with suppliers possessing institutional procurement credentials rather than pure-play e-commerce positioning.
| Leading Market Players |
|---|
| ERGObaby Carrier Inc. |
| BabyBjorn AB |
| Infantino LLC |
| Combi Corp |
| Artsana Spa |
| Boba Inc. |
| Baby K'tan LLC |
| Lillebaby LLC |
| Goodbaby International Holdings Limited |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between GOTS-certified organic carriers and uncertified commodity alternatives manifests in both margin structures and sourcing configurations, with premium tiers commanding captive Vietnamese textile flows while economy segments depend on spot-market Guangdong foam padding.
Pricing Analysis
Input-cost pass-through from organic cotton certification premiums and REACH-mandated material reformulation compresses margins differentially across tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and pediatric-orthopedist validation intensity. Cost compression in the economy tier intensifies because single-source foam dependency limits supplier negotiation leverage. First-time parents in Germany and the Netherlands exhibit lowest price sensitivity due to midwife-guided preference formation, while grandparents purchasing secondary carriers demonstrate highest sensitivity to intuitive-adjustment premiums.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong province for high-density polyethylene foam padding and with Vietnamese vertically controlled corridors for GOTS-certified organic cotton. Raw material dependencies center on Indian and Turkish organic fiber harvests, Guangdong synthetic foam production, and breathable synthetic mesh weaves. Tariff exposure looms for US-bound shipments facing California Proposition 65 flame-retardant testing beyond federal ASTM F2907 minimums. Distribution runs through hospital discharge bag partnerships and midwife recommendation networks in Germany, mass retail distributor networks in Chinese tier-one cities, and specialty boutique channels in Nordic urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in certification-driven premium tier capture, justified by narrowing GOTS cotton premium volatility as Indian and Turkish supply chains stabilize procurement predictability.
For Market Incumbents: Anchor clinical credibility through pediatric-orthopedist research center partnerships that embed product selection within Bavaria's medical guidance workflows and German hospital discharge protocols. Defend against pure-play e-commerce entrants lacking institutional procurement credentials by locking multi-year midwife recommendation network exclusives. Prioritize backward integration into Vietnamese GOTS-certified textile production to decouple from spot-market organic fiber volatility. For New Entrants and Emerging Players: Grandparents and extended family members purchasing secondary carriers represent an underserved buyer archetype with minimal incumbent attention to intuitive-adjustment simplicity. Brazilian mass-market penetration offers lowest regulatory friction following ANVISA harmonization with ISO standards, enabling distributor network establishment ahead of local manufacturing capacity. Telehealth-integrated positioning validation provides a go-to-market angle distinct from traditional retail discovery channels. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers face parallel CE marking, ASTM compliance, and Japan METI survey preparation costs that strain cash reserves. Long-term viability favors vertically integrated specialists with captive GOTS-certified supply and clinical validation relationships over pure-play e-commerce positioning. Watch for REACH chemical restriction cascade acceleration as the inflection indicator triggering material reformulation cost spikes and supplier attrition.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric-Orthopedist Research Partnership | Bavaria's validation programs embed product selection within medical guidance workflows, displacing retail discovery. |
| Backward Integration into Vietnamese Textile Production | Captive GOTS-certified organic cotton volumes decouple ERGObaby from spot-market certification premium volatility. |
| Rental-Subscription Channel Launch | Nordic urban parents in Stockholm demonstrate willingness to lease across infant growth stages, creating recurring revenue. |
| ANVISA-Aligned Distributor Network Establishment | Brazilian regulatory harmonization with ISO standards reduces import friction ahead of local manufacturing capacity. |
| Integrated Mesh Ventilation Product Line | Singapore and Sydney parents reject detachable cooling inserts, absorbing aftermarket accessory revenue into upfront pricing. |
Methodological Framework
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with brand managers, category buyers at mass retail chains, supply planners, and pediatric-orthopedist consultants with secondary validation from customs records, Nielsen retail audit data, SEC 10-K filings, and SAMR consumer product safety survey disclosures. Triangulation across these sources calibrates volume estimates against production capacity declarations and import-export flow tracking.
Historical trendline analysis of soft structured carrier, wrap, sling, and frame carrier segments across cotton, polyester, nylon, and mesh material categories informs projection framework construction throughout the forecast period. Modeled dimensions include product type, material composition, end-user classification, and weight capacity tier, with CAGRs derived from regression against dual-income household expansion rates, certification adoption curves, and regional regulatory enforcement intensity. Forecast inputs incorporate REACH substance restriction evolution pacing and ASTM F2907 compliance cost trajectories.
Underlying measurement precision varies by segment; soft structured carriers and 15-30 lbs weight capacity tiers carry tighter precision than wrap-style niche premiums due to higher volume concentration and standardized reporting. Forecasts reflect assumptions around regulatory enforcement continuity, organic fiber harvest stability, and distributor contract renegotiation dynamics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Bottle Warmer and Sterilizer Market
Baby Products
South Africa Baby Care Products Market
Baby Products
Electric Baby Nail Trimmer Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Silicone Baby Product Market
Baby Products
Baby Bouncers Market
Baby Products
Baby Powder Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
Baby Prams and Strollers Market
Baby Products
Baby High Chair Market
Baby Products
Baby Gift Basket Market
Baby Products
Baby Tableware Market
Baby Products
Sippy Cups Market
Baby Products
Puppy Teething Toys Market
Baby Products
South Korea Baby Care Products Market