
 Baby Slings Market | 2026-2036
Baby Slings Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Slings Market Outlook
Turkish textile mills is realigning woven-fabric output toward certified baby-wearable substrates, tightening feedstock availability for European and North American sling brands. Ergobaby leverages vertical manufacturing partnerships across Southeast Asian loom houses to secure ring-sling webbing capacity. Didymos anchors its market position through decades-old jacquard-weave expertise in organic cotton blends.
A baby sling is a torso-mounted infant carrier constructed from continuous fabric panels, typically spanning 2.5 to 6 metres in length, designed to distribute a child's weight across the wearer's shoulders, back, and hips through tension-based wrapping or fixed-point suspension. The primary commercial purpose is hands-free mobility for caregivers while maintaining physical proximity that supports infant thermoregulation and vestibular development. Wrap configurations occupy the premium tier due to custom-weave artisanal production and extended usable lifespan from newborn through toddler stages. Mesh materials gain fastest traction in equatorial and humid subtropical markets where breathability determines purchase decisions. Cotton sustains volume leadership across mass-market ring and pouch formats where cost transparency and laundering durability dominate buyer calculus.
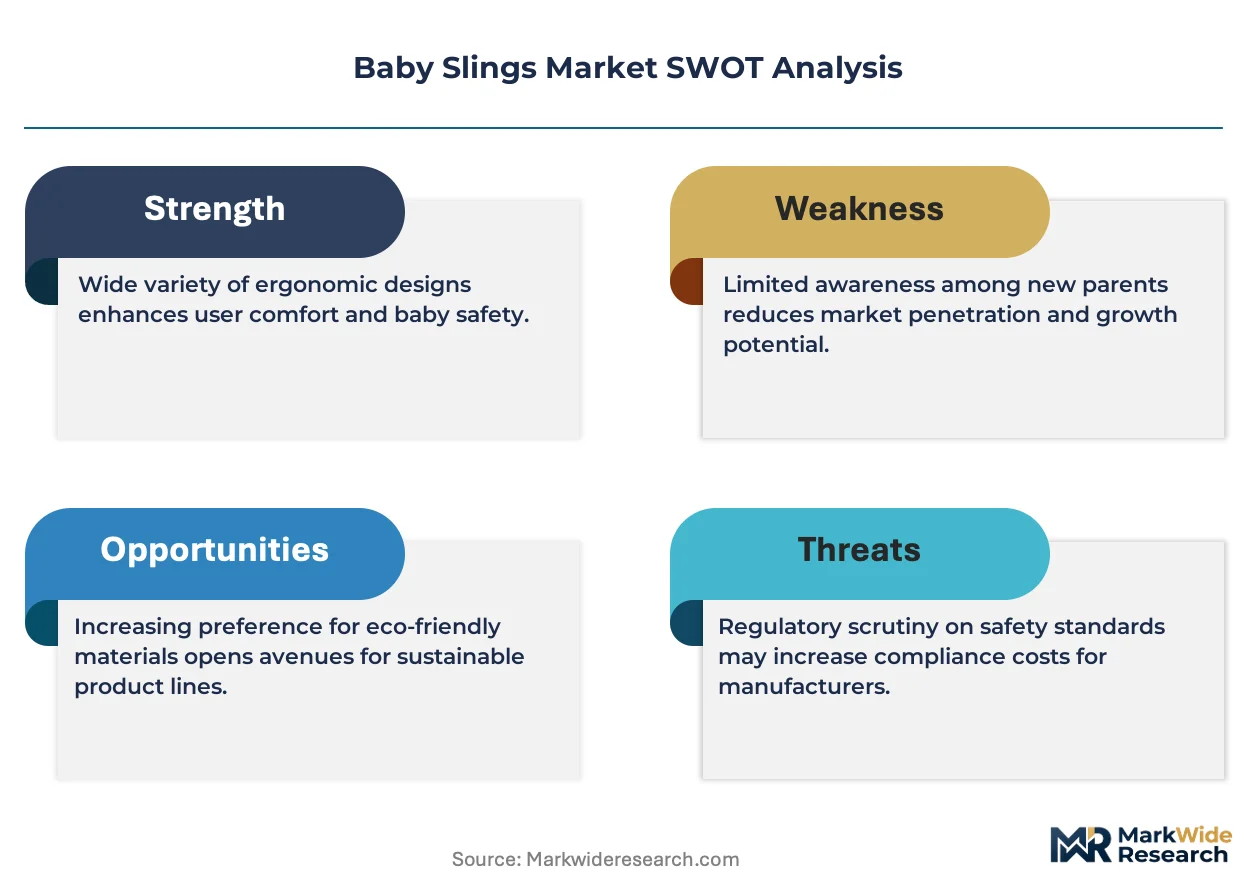
The US Consumer Product Safety Commission mandates ASTM F2907 compliance for all sling carriers sold domestically, forcing design modifications to head-support panels and warning-label placement. The EU's General Product Safety Regulation and REACH chemical restrictions govern import thresholds for dyes and fabric treatments entering European distribution channels. ASTM testing protocols for dynamic load and structural integrity continue elevating compliance costs for smaller weave-house brands. Stakeholders must monitor evolving mechanical-testing standards across jurisdictions to anticipate redesign cycles and inventory obsolescence risks.
Market Dynamics
The Baby Slings Market faces a structural squeeze between Turkish textile mill reallocation toward certified baby-wearable substrates and the US Consumer Product Safety Commission's ASTM F2907 enforcement wave, which is compressing certification timelines and feedstock availability simultaneously.
Growth Catalysts
- ASTM F2907 Compliance Mandate:The US Consumer Product Safety Commission's updated sling carrier standards force domestic design modifications that elevate safety premiums and accelerate replacement cycles among legacy inventory holders.
- Attachment Parenting Philosophy:Millennial and Gen Z parents across urban United States, Germany, and South Korea clusters prioritize torso-mounted infant proximity, driving sustained demand for wrap and ring-sling configurations.
- Mesh Material Innovation:Breathable woven substrates gain fastest traction in equatorial and humid subtropical markets where thermoregulation determines purchase decisions over cotton alternatives.
Market Restraints
- Turkish Feedstock Concentration:Realignment of Anatolian loom houses toward certified baby-wearable output tightens ring-sling webbing availability for European and North American brands without vertical manufacturing partnerships.
- REACH Chemical Friction:The EU's dye and fabric treatment restrictions under REACH compliance elevate import thresholds, disproportionately burdening smaller weave-house brands lacking dedicated regulatory affairs capacity.
- Jacquard-Weave Skill Scarcity:Decades-old artisanal expertise in organic cotton blend construction concentrates within limited German manufacturing bases, constraining premium tier expansion.
Strategic Opportunities
- Urban Cluster Penetration:Untapped demand concentrates in secondary metropolitan zones across South Korea and Germany where specialty retail distribution remains underdeveloped relative to primary cities.
- Southeast Asian Loom Partnerships:Vertical manufacturing alliances with Vietnamese and Indonesian textile houses offer pathway to captive ring-sling webbing capacity outside Turkish supply constraints.
- Extended Usable Lifespan Positioning:Wrap configurations spanning newborn through toddler stages command premium pricing through custom-weave artisanal production narratives that resist commoditization.
Industry Challenges
- Dynamic Load Certification Timelines:ASTM testing protocols for structural integrity compress product development windows, forcing redesign cycles that risk inventory obsolescence before market entry.
- Warning-Label Placement Complexity:Jurisdictional variation in head-support panel and label positioning mandates fragments production runs and elevates SKU management costs for multi-market brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Slings Market |
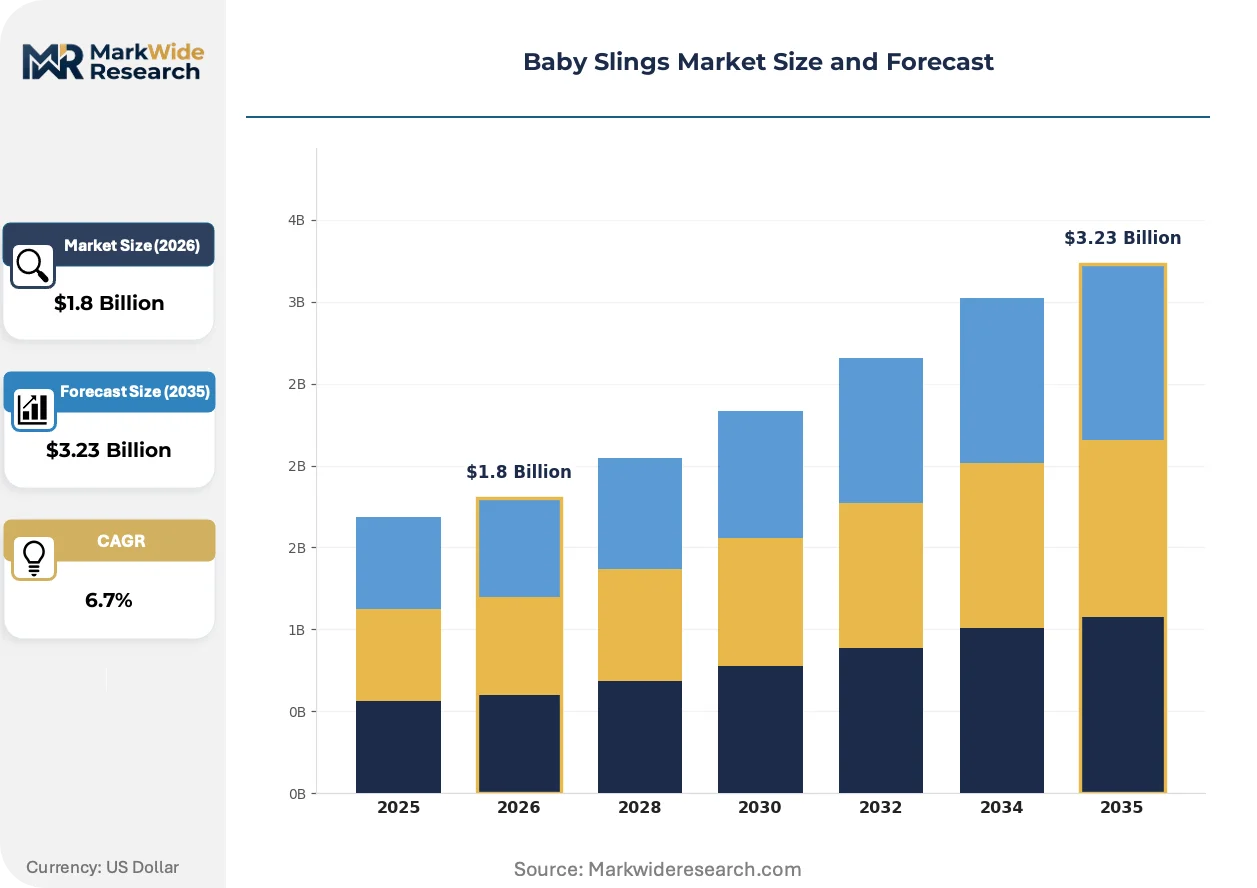
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrap, Ring, Pouch, Mei Tai Material: Cotton, Linen, Mesh, Synthetic Age Group: Infants, Toddlers, Newborns, Preemies Distribution Channel: Online, Retail Stores, Specialty Shops, Marketplaces |
| Companies Covered | BabyBjörn, Ergobaby, Boba, Infantino, Lillebaby, Moby Wrap, Didymos, Chimparoo, Baby K'tan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Slings Market Strategic Shifts
Active reshaping of the Baby Slings Market centers on three vectors: substrate technology fragmentation, regulatory compliance automation, and buyer procurement pattern compression toward certified durability claims.
Adaptive mesh-weave substrates is modularizing across humidity-responsive product lines. These breathable panels incorporate variable-density knit structures that adjust ventilation based on ambient temperature. Premium-tier buyers in Singapore, Houston, and Brisbane metro clusters adopt these configurations at accelerated pace. The technology is modularizing what was previously fixed-fabric inventory into seasonally adjustable carrier systems.
REACH chemical screening protocols now mandate pre-import dye certification for all fabric treatments entering European distribution channels. The European Chemicals Agency's expanded substance restrictions force reformulation of colorfast agents and antimicrobial coatings. Small-batch artisanal weavers in Portugal and Italy face disproportionate compliance cost elevation, consolidating advantage toward scaled manufacturers with in-house testing laboratories.
Certification-driven preference compression now dominates caregiver purchase decisions. ASTM F2907 compliance badges displace brand loyalty as primary selection criterion among first-time parents. Specialty boutiques in Seattle, Munich, and Seoul report inventory turns favoring labeled safety assurance over aesthetic differentiation. This behavioral shift concentrates volume toward vertically integrated manufacturers controlling their own certification pipeline.
Baby Slings Market Segmentation
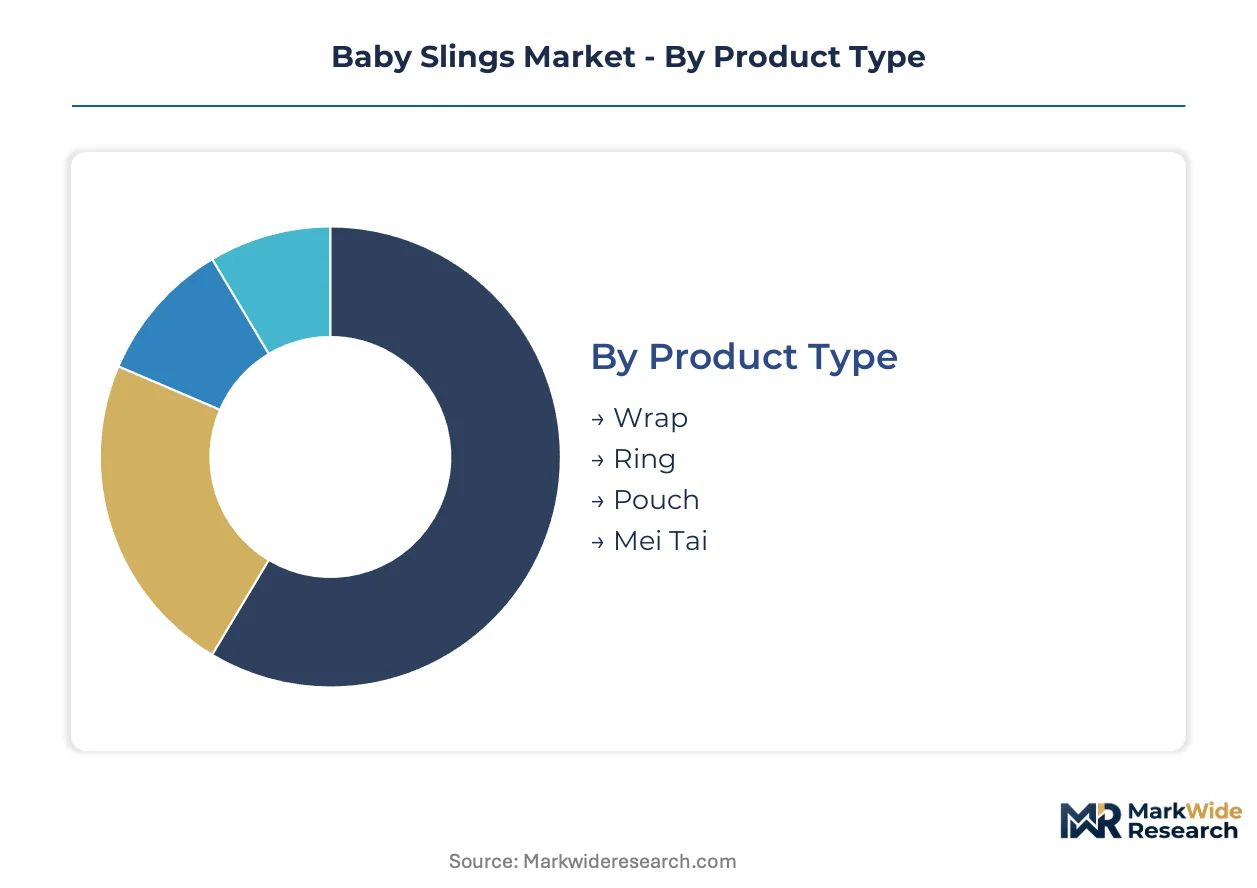
Carrier configuration and substrate selection determine pricing power and replacement frequency in this market. Material sourcing constraints and certification requirements fragment competitive positioning across product tiers.
Product Type:
Volume leadership sits with standardized formats while artisanal constructions command margin premiums.
- Wrap:Continuous fabric panels spanning 2.5 to 6 metres enable tension-based weight distribution across shoulders, hips, and back. Demand concentrates among Millennial and Gen Z parents in Seattle, Munich, and Seoul who prioritize newborn-through-toddler lifespan and attachment parenting compatibility.
- Ring:Fixed-point suspension through aluminum or nylon rings permits rapid adjustment without re-tying. Turkish textile mill reallocation toward certified substrates tightens webbing availability, forcing brands toward Southeast Asian loom partnerships.
- Pouch:Pre-sewn pocket construction offers entry-level price positioning with minimal learning curve. ASTM F2907 head-support panel modifications elevate per-unit compliance costs.
- Mei Tai:Asian-origin square body with waist straps and shoulder ties bridges structured carrier and wrap flexibility. REACH dye restrictions constrain European import volumes for smaller weave-house producers.
Today's leader: Wrap. Tomorrow's challenger: Ring.
Material:
Substrate selection tracks climate exposure and laundering durability expectations.
- Cotton:Volume leadership persists across mass-market formats where cost transparency and washing resilience dominate purchase calculus. Organic cotton blends anchor Didymos positioning through jacquard-weave expertise.
- Mesh:Variable-density knit structures adjust ventilation based on ambient temperature. Singapore, Houston, and Brisbane metro clusters adopt these configurations fastest where thermoregulation determines selection.
- Linen:Stiff initial hand softens with washing while offering superior moisture wicking. Portuguese and Italian small-batch weavers face REACH chemical screening cost elevation.
- Synthetic:Polyester-nylon blends reduce water absorption and drying time. Ergobaby leverages Southeast Asian manufacturing partnerships for ring-sling webbing capacity outside Turkish supply constraints.
Cotton dominates transaction volume. Mesh climbs fastest in equatorial and humid subtropical zones.
Age Group:
Developmental stage dictates carrier geometry and safety certification requirements.
- Newborns:Head and neck support mandates elevate ASTM F2907 design complexity for products targeting 0-4 month users. US Consumer Product Safety Commission warning-label placement rules fragment production runs.
- Infants:Core volume segment spanning supported sitting through independent mobility. Urban clusters across United States, Germany, and South Korea concentrate replacement cycle demand.
- Toddlers:Extended usable lifespan positioning commands premium pricing for wrap configurations accommodating 15-35 pound range. Custom-weave artisanal production resists commoditization.
- Preemies:Specialized kangaroo care positioning requires medical-grade substrate certification. Smaller addressable volume limits brand investment in dedicated product lines.
Infants generate current revenue concentration. Toddlers drive margin expansion through extended-use positioning.
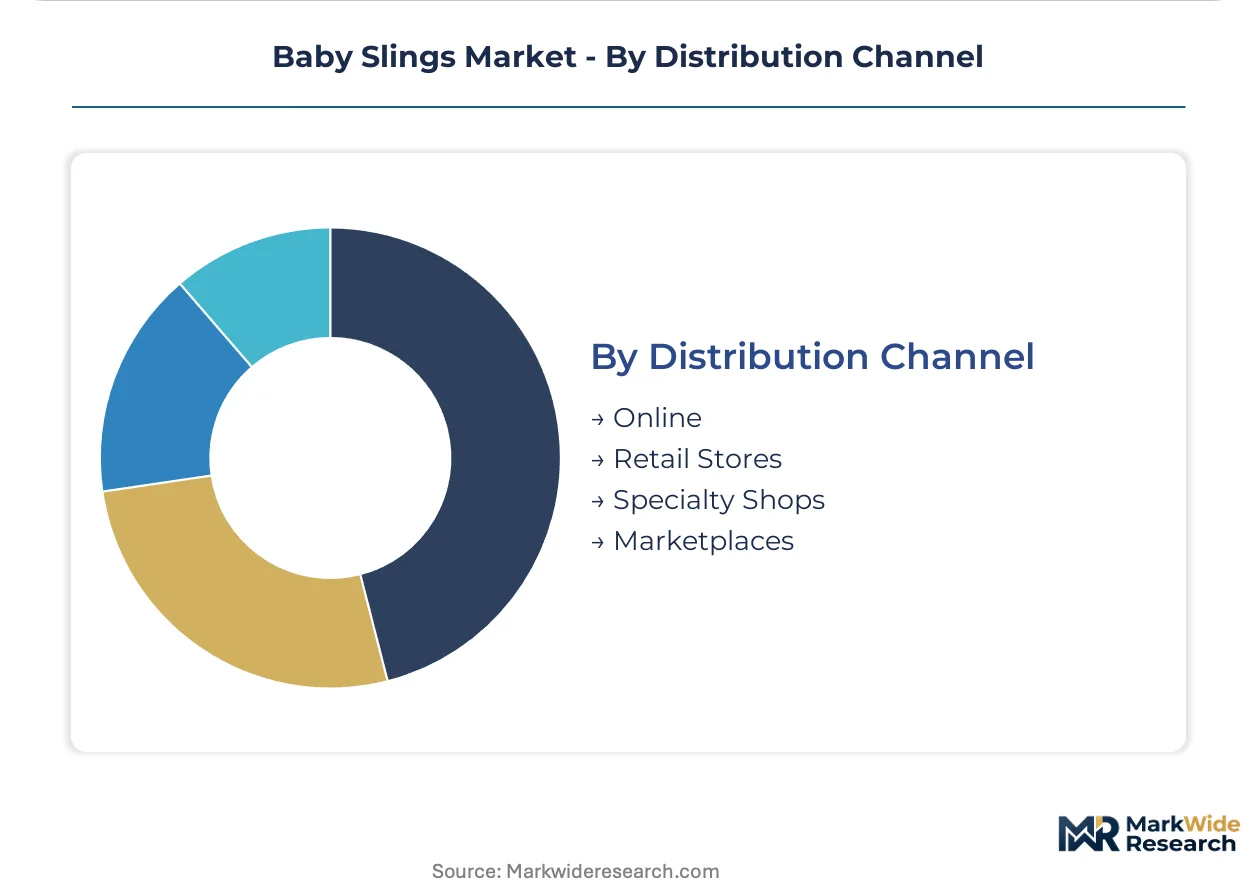
Distribution Channel:
Channel selection determines customer education depth and certification badge visibility.
- Specialty Shops:Hands-on fitting instruction and ASTM F2907 compliance verification dominate purchase support. Seattle, Munich, and Seoul boutiques report inventory turns favoring labeled safety assurance over aesthetic differentiation.
- Online:Direct-to-consumer models compress price transparency and comparison shopping. Certification-driven preference displacement accelerates toward vertically integrated manufacturers controlling their own testing pipeline.
- Retail Stores:Mass-market shelf placement requires SKU management across jurisdictional label variations. Warning-label placement complexity elevates multi-market brand costs.
- Marketplaces:Third-party platform aggregation fragments brand control over compliance messaging. Counterfeit and uncertified product infiltration risks caregiver safety.
Specialty shops anchor premium positioning. Online channels expand fastest through certification-badge-driven selection behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing baby sling manufacturing capacity toward jurisdictions with streamlined certification pathways, while demand clusters concentrate in urban centers where attachment parenting philosophies penetrate deepest.
United States
ASTM F2907 compliance mandates from the US Consumer Product Safety Commission compress product development timelines for domestic brands. Seattle and Austin metro clusters drive premium wrap adoption among Millennial parents prioritizing extended-use configurations. Specialty boutiques in these markets report inventory turnover rates favoring certified safety badges over aesthetic differentiation.
Germany
REACH chemical restrictions and ECHA dye certification requirements elevate import barriers for non-EU suppliers. Munich and Hamburg anchor continental demand for jacquard-weave artisanal production. Didymos leverages decades-old organic cotton blend expertise concentrated in these manufacturing bases to defend premium positioning.
South Korea
MFDS-aligned product safety expectations and dense urban living patterns sustain ring-sling demand in Seoul Capital Area and Busan-Ulsan clusters. Secondary metropolitan zones remain underpenetrated relative to primary cities. Local distributors report fastest growth in humidity-responsive mesh configurations for subtropical summer conditions.
Australia
TGA-recognized safety standards and thermoregulation-driven purchase behavior concentrate demand in Brisbane and Sydney metro areas. Breathable woven substrates gain traction fastest where equatorial humidity patterns dominate caregiver selection criteria. Local specialty retailers emphasize seasonally adjustable carrier systems over fixed-fabric alternatives.
Turkey
Anatolian loom house reallocation toward certified baby-wearable substrates tightens feedstock availability for European and North American brands. Istanbul-based textile mills now prioritize captive ring-sling webbing capacity over commodity fabric output. This supply constraint accelerates Southeast Asian manufacturing partnerships among brands lacking vertical integration.
Baby Slings Market Competitive Environment
German producers anchor the premium artisanal tier; Southeast Asian manufacturing partnerships hold volume scalability. Market structure tilts toward consolidation as ASTM F2907 compliance costs and REACH chemical screening burdens eliminate smaller weave-house competitors. Three archetypes dominate: vertically integrated manufacturers controlling certification pipelines, specialty boutiques emphasizing hands-on fitting instruction, and direct-to-consumer brands leveraging safety-badge visibility. Dominant competitive moves include Southeast Asian loom partnerships bypassing Turkish supply constraints and extended-usable-lifespan positioning resisting commoditization.
Among German-based specialists, Didymos occupies a position exemplifying jacquard-weave artisanal expertise. Within the vertically integrated tier, Ergobaby represents manufacturing partnership strategies across Vietnamese and Indonesian textile houses. On the accessible-premium vector, Moby Wrap sits within the wrap-configuration category where custom-weave narratives command pricing power.
| Leading Market Players |
|---|
| BabyBjörn |
| Ergobaby |
| Boba |
| Infantino |
| Lillebaby |
| Moby Wrap |
| Didymos |
| Chimparoo |
| Baby K'tan |
| Others |
Value Chain & Pricing Dynamics
Jacquard-weave artisan concentration in southwestern Germany widens pricing spreads between custom-woven premium wraps and mass-market ring-sling alternatives. Labor-cost differentials between these specialized German manufacturing bases and Southeast Asian loom houses compress margins at standard tier while sustaining premium pricing power.
Pricing Analysis
Specialty boutique markups absorb ASTM F2907 certification costs and hands-on fitting instruction overhead. Three-tier pricing structure across premium, standard, and economy levels separates Didymos-level artisanal wraps from Ergobaby's accessible-premium positioning and Infantino's entry-level pouches. Price differentiation hinges on certification grade and custom-weave complexity. Pricing pressure stems from REACH chemical screening cost elevation disproportionately burdening smaller Portuguese and Italian weavers. First-time parents in urban United States clusters show lowest price sensitivity when safety badges accompany premium substrates.
Supply Chain Analysis
Direct-to-specialty-retail channels dominate premium wrap distribution through Seattle, Munich, and Seoul boutiques. Raw material flows draw from Turkish organic cotton bases, Vietnamese synthetic-blend houses, and Indonesian mesh-weave specialists. Component dependencies center on aluminum ring forgings, jacquard loom capacity, and humidity-responsive knit structures. Single-source vulnerability concentrates in Anatolian loom house reallocation toward certified baby-wearable substrates. Distribution runs through vertically integrated manufacturers controlling captive Southeast Asian webbing capacity alongside fragmented artisanal weave-house networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Baby Slings Market represents a late-cycle quality story as ASTM F2907 compliance badges displace brand loyalty among Millennial and Gen Z parents prioritizing certified safety assurance over aesthetic differentiation.
For Market Incumbents: Acquire jacquard-weave artisan expertise concentrated in German manufacturing bases to defend premium positioning against Southeast Asian manufacturing partnership strategies. Secure captive ring-sling webbing capacity through Vietnamese and Indonesian loom alliances before Turkish feedstock constraints tighten further. Certification pipeline control remains the critical defensive lever against REACH chemical screening cost elevation. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer lowest-friction entry for humidity-responsive mesh configurations targeting underpenetrated secondary metropolitan zones in South Korea and Australia. White-space concentration sits with subtropical climate-adaptive product lines where thermoregulation determines purchase decisions. Specialty boutique partnerships in Brisbane and Busan-Ulsan clusters provide credible go-to-market validation. For Investors and Strategic Acquirers: Vertically integrated baby-wearable specialists are the most active acquirer in this space, consolidating ASTM F2907 compliance infrastructure and REACH chemical screening laboratories. Five-to-ten year viability favors manufacturers controlling both certification pipelines and Southeast Asian loom partnerships. Acquisition target archetype: mid-scale weave-houses with established jacquard expertise and untapped direct-to-consumer channels. Watch for MFDS-aligned safety standard harmonization across East Asian markets as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Southeast Asian Loom Partnership | Vietnamese and Indonesian textile alliances bypass Turkish supply constraints for ring-sling webbing capacity. |
| ASTM F2907 Certification Investment | In-house testing laboratories accelerate product development timelines against dynamic load protocol compression. |
| Humidity-Responsive Mesh Launch | Singapore, Houston, and Brisbane metro clusters adopt breathable substrates fastest for equatorial conditions. |
| Extended-Use Lifespan Positioning | Wrap configurations spanning newborn-through-toddler stages resist commoditization through artisanal production narratives. |
| Secondary Metropolitan Expansion | Underpenetrated Busan-Ulsan and Hamburg clusters offer distribution growth outside saturated primary cities. |
Study Parameters
Bottom-up caregiver demand modeling reconciled against top-down textile mill capacity tracking forms the analytical core of this study. Primary interviews with brand managers at German artisanal weave-houses, procurement leads at Southeast Asian loom partnerships, category buyers at Seattle and Munich specialty boutiques, and regulatory affairs specialists navigating ASTM F2907 protocols combined with secondary validation from US Consumer Product Safety Commission enforcement records, ECHA REACH substance restriction updates, and customs data on certified baby-wearable substrate flows.
Input-output matrices map carrier configuration demand against jacquard-weave capacity, ring-sling webbing availability, and mesh-weave innovation trajectories across the projection horizon. Segmentation dimensions modeled include product type, substrate material, developmental age group, and distribution channel, with regional regulatory cluster overlays for US, EU, and South Korean compliance pathways. CAGRs derive from elasticity-adjusted replacement cycle analysis and urban cluster penetration saturation curves.
Regulatory enforcement waves, feedstock reallocation shocks, and certification timeline compression are the dominant revision risks to forecast outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Swing Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Baby Changing Light Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Baby Pacifier Thermometer Market
Baby Products
South Korea Baby Care Products Market
Baby Products
Baby Bouncers Market
Baby Products
Diaper Bag Market
Baby Products
Baby Feeding Bottles Market
Baby Products
Baby Changing Station Market
Baby Products
Baby Wipes Market
Baby Products
Stroller Rental Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Automatic Baby Swing Market
Baby Products
Tissue and Hygiene Market
Baby Products
Baby Bottle Market