
 Breastfeeding Accessories Market | 2026-2036
Breastfeeding Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Breastfeeding Accessories Market Analysis
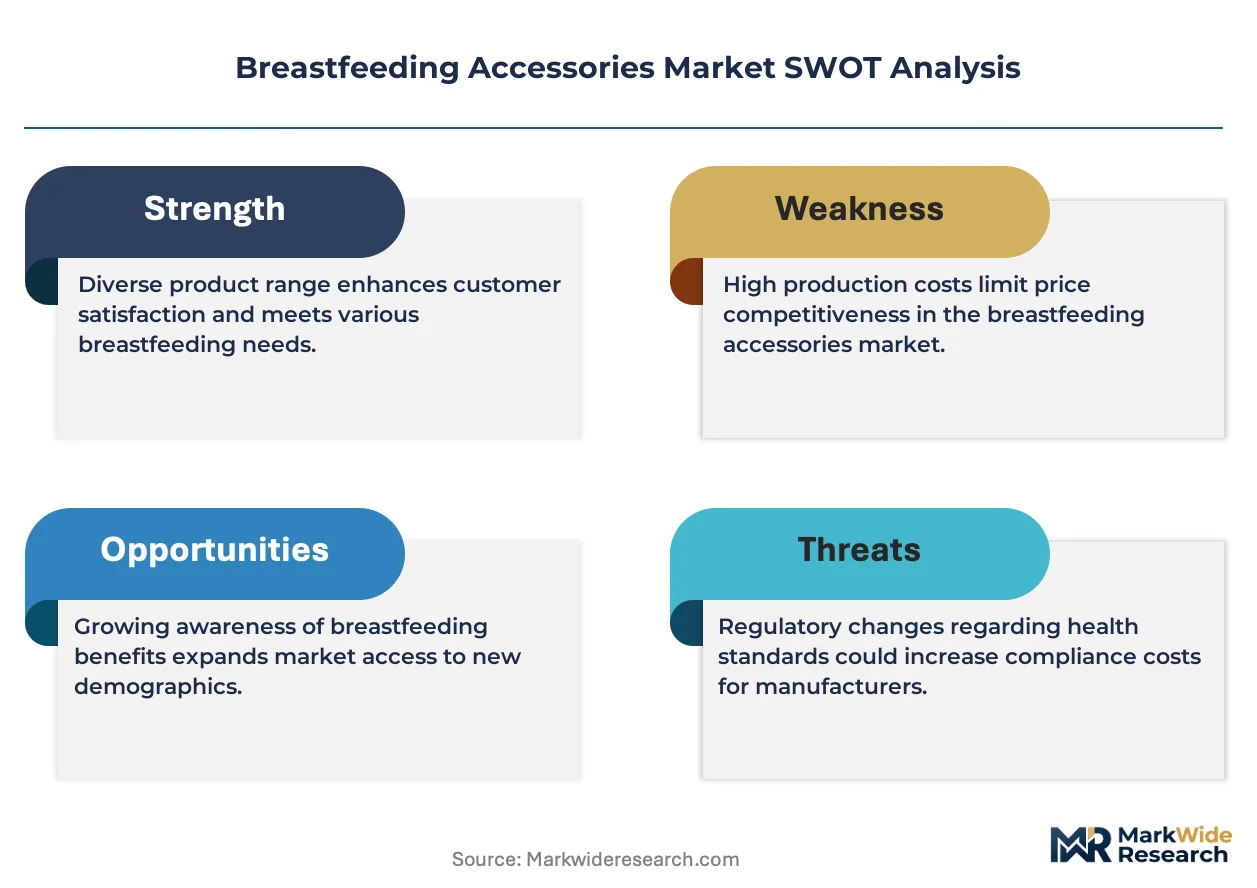
The capital-intensity divergence between established pump manufacturers and emerging wearable specialists is unwinding traditional barriers to entry. Medela AG leverages decades of clinical validation to sustain premium positioning across hospital channels. Willow Innovations Inc. competes through proprietary wearable technology that eliminates tubing and external collection bottles. Koninklijke Philips NV anchors mass-market volume through Avent brand distribution in retail pharmacies across multiple continents.
Breastfeeding accessories comprise mechanical and consumable products designed to support lactation, milk expression, and storage, typically manufactured from medical-grade silicone, BPA-free polymers, or absorbent textiles with specifications including ISO 10993 biocompatibility certification and FDA Class II device classification where motorized pumps are concerned. Their primary commercial purpose centers on enabling milk expression outside direct nursing contexts, supporting maternal workforce participation and infant nutrition continuity. Breast pumps capture the dominant value share within product type segmentation, though milk storage bags generate recurring revenue streams with higher purchase frequency. Online retail channels represent the fastest-growing distribution pathway, driven by subscription replenishment models and discrete purchasing preferences among new mothers.
FDA 510(k) clearance requirements for powered breast pumps shape product development timelines and capital allocation among manufacturers seeking US market access, while the EU MDR and REACH frameworks govern silicone material safety and chemical migration limits in European jurisdictions. The EU AI Act introduces emerging compliance considerations for smart pump connectivity features that collect biometric data. Stakeholders must monitor regulatory divergence between connected device data governance in Europe and clinical efficacy claims permitted in US marketing.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around single-source contracts for pump fleets, compressing supplier margins while elevating clinical validation requirements above consumer marketing claims.
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers accelerating biocompatibility documentation for silicone components are capturing shelf space as non-compliant products exit European distribution channels.
- Wearable pump technology:Elimination of external tubing and collection bottles is expanding addressable demand among mobile professionals requiring discreet expression during work hours.
- Working mother workforce participation:United States employer lactation accommodation mandates under the Fair Labor Standards Act are institutionalizing pump infrastructure in corporate facilities.
Market Restraints
- Medical-grade silicone supply concentration:Three specialty chemical producers in Germany and Japan control high-purity elastomer feedstocks, exposing manufacturers to input cost volatility.
- FDA 510(k) clearance timelines:Powered pump submissions averaging 180-day review cycles delay revenue recognition for new entrants lacking predicate device pathways.
- Manual expression substitutes:Low-cost hand pumps and passive collection shells retain price-sensitive segments in developing economies.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer platforms for milk storage bags and replacement valve kits are capturing recurring revenue with higher purchase frequency than durable hardware.
- EU AI Act biometric data provisions:Smart pumps with app-connected expression tracking can leverage regulatory clarity on health data processing to differentiate against non-connected alternatives.
- Hospital-at-home transition:Postpartum discharge compression is extending rental pump programs into home settings through insurance reimbursement channels.
Industry Challenges
- ISO 10993 biocompatibility certification capacity:Testing laboratory backlogs for cytotoxicity and sensitization assays are extending product development timelines beyond commercial planning horizons.
- Legacy pump fleet interoperability:Proprietary flange and tubing geometries from incumbent manufacturers create switching costs that fragment replacement part markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breastfeeding Accessories Market |
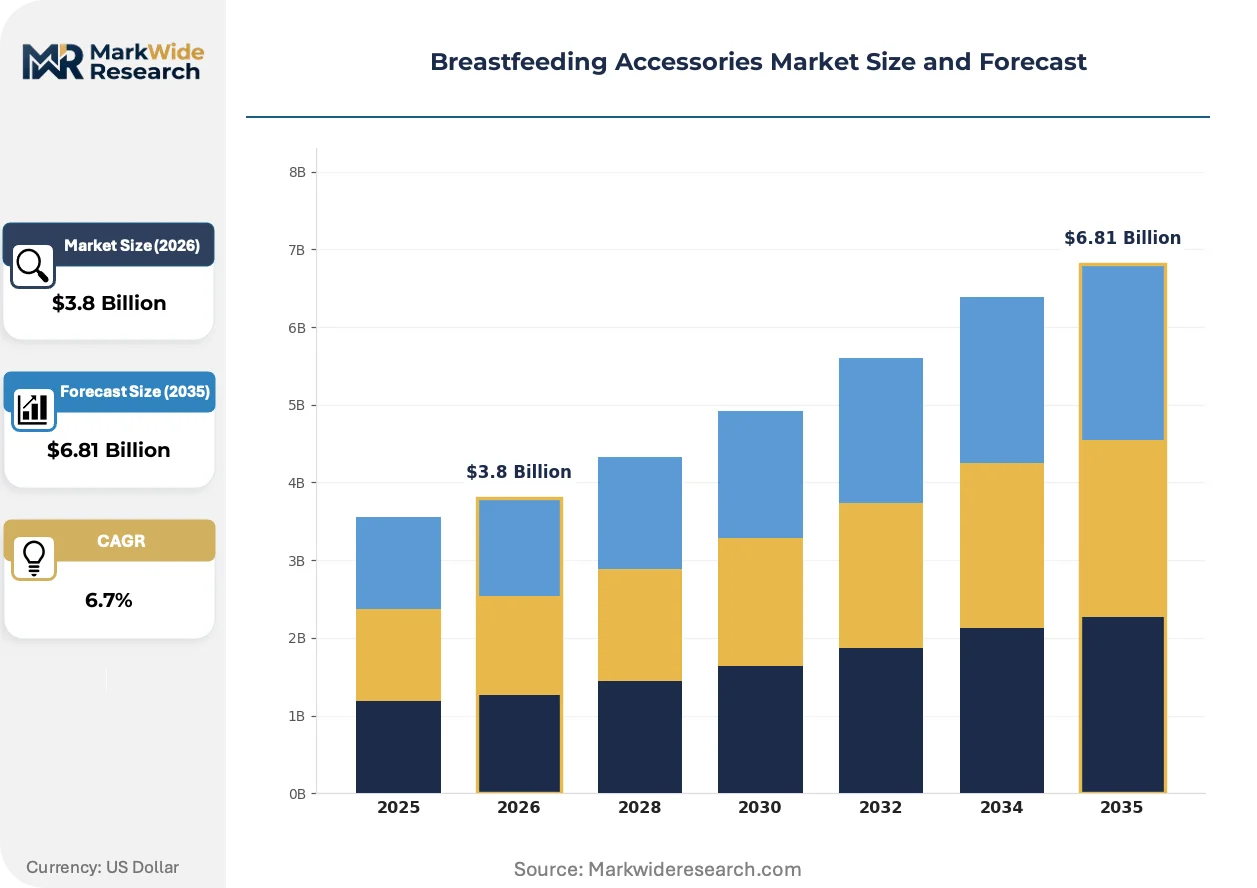
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nursing Pads, Breast Pumps, Milk Storage Bags, Nipple Cream End User: New Mothers, Hospitals, Nursing Homes, Lactation Consultants Material: Silicone, BPA-Free Plastic, Cotton, Gel Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Pigeon Corporation, Willow Innovations Inc., Medela AG, Mayborn Group Limited, Artsana Group, Koninklijke Philips NV, Ameda Inc., Tommee Tippee, Lansinoh Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breastfeeding Accessories Market Emerging Trajectories
Wearable hardware architectures and connected data platforms are compressing the functional gap between clinical-grade hospital pumps and consumer portability, while regulatory frameworks on both sides of the Atlantic are rewriting compliance cost structures for silicone-based devices.
Motor and battery assemblies are miniaturizing through solid-state pump mechanisms that fit within bra-mounted form factors. Working mothers in professional services sectors are adopting these devices at rates exceeding hospital-grade rental alternatives. This compression of hardware footprint is miniaturizing the addressable market for traditional tabletop pumps with external power supplies and collection bottles.
REACH framework amendments on siloxane migration limits are tightening material specifications for European market access. Manufacturers are reformulating liquid silicone rubber compounds to meet D4/D5/D6 cyclosiloxane thresholds. Breast shield and valve component suppliers serving EU distribution channels are absorbing reformulation costs and extending qualification timelines.
Discrete purchasing through pharmacy-integrated telehealth platforms is displacing retail aisle selection for first-time mothers. Lactation consultant referrals now route through digital health apps that embed product recommendations. This channel migration is most visible in United States metropolitan markets where employer-sponsored virtual care benefits include postpartum support programs.
Breastfeeding Accessories Market Segmentation
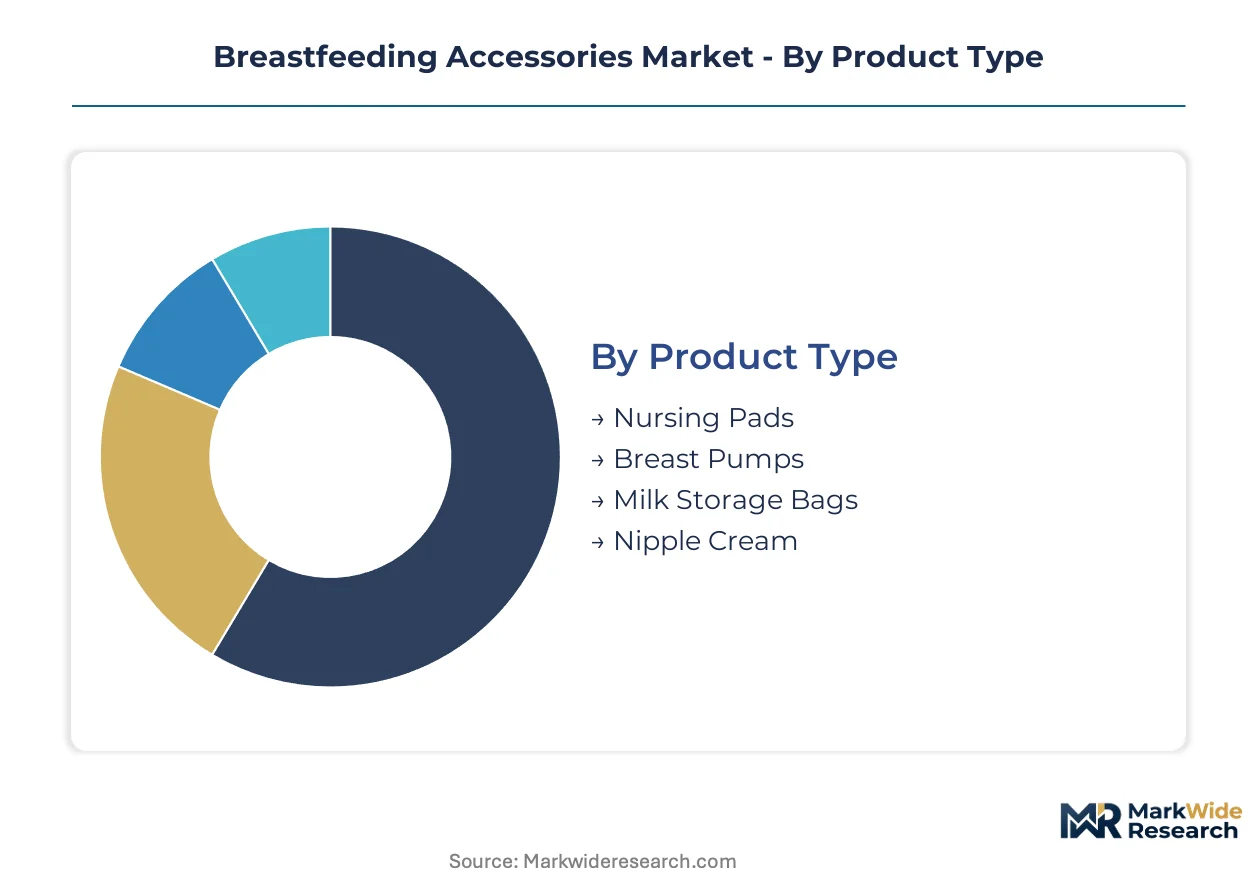
Channel fragmentation in breastfeeding accessories demands precise segment-to-route alignment. Hospital procurement contracts favor durable hardware with clinical validation, while direct-to-consumer platforms capture replenishment purchasing for consumables.
Product Type:
Channel-mix dynamics vary sharply across product categories, with durable hardware flowing through institutional procurement and consumables migrating to subscription platforms.
- Breast Pumps:Motorized and manual devices manufactured from medical-grade silicone and BPA-free polymers with ISO 10993 biocompatibility certification. Demand concentrates among working mothers in the United States seeking portable expression solutions compatible with Fair Labor Standards Act workplace accommodation mandates.
- Milk Storage Bags:Multi-layer polymer pouches with leak-proof sealing mechanisms designed for freezer storage and thermal sterilization compatibility. Recurring purchase frequency drives direct-to-consumer subscription models through pharmacy-integrated telehealth platforms in metropolitan markets.
- Nursing Pads:Absorbent textile or hydrogel inserts managing leakage between feeding sessions.
- Nipple Cream:Lanolin-based or plant-derived topical formulations addressing tissue irritation.
Breast pumps dominate installed base. Milk storage bags are where expansion concentrates.
End User:
Cost-tier stratification separates premium clinical validation from economy accessibility across user categories.
- New Mothers:Primary consumers spanning first-time purchasers and experienced mothers, with discrete purchasing preferences driving online channel migration. United States employer-sponsored virtual care benefits now embed lactation consultant referrals that route product recommendations through digital health apps.
- Hospitals:Institutional procurement departments consolidating vendor relationships around single-source contracts for pump fleets, elevating clinical efficacy documentation above consumer marketing claims and compressing supplier margins.
- Nursing Homes:Long-term care facilities requiring durable equipment for resident lactation support.
- Lactation Consultants:Independent and hospital-affiliated professionals influencing product recommendations through credential-backed endorsement.
New mothers represent the volume anchor. Hospitals are where margin compression is most severe.
Material:
Regulatory geography dictates material formulation, with REACH amendments in Europe and FDA biocompatibility requirements in the United States creating divergent compliance cost structures.
- Silicone:Medical-grade liquid silicone rubber compounds meeting EU MDR biocompatibility documentation and D4/D5/D6 cyclosiloxane thresholds under REACH framework amendments. Supply concentrates among three specialty chemical producers in Germany and Japan, exposing manufacturers to input cost volatility.
- BPA-Free Plastic:Polypropylene and polycarbonate alternatives eliminating bisphenol-A migration risks, with FDA food-contact substance notifications required for milk-contact applications.
- Cotton:Absorbent natural fibers for nursing pad textiles requiring moisture-wicking treatment.
- Gel:Hydrogel formulations for therapeutic cooling applications.
Silicone commands premium positioning. BPA-free plastic is where volume manufacturing scales.
Distribution Channel:
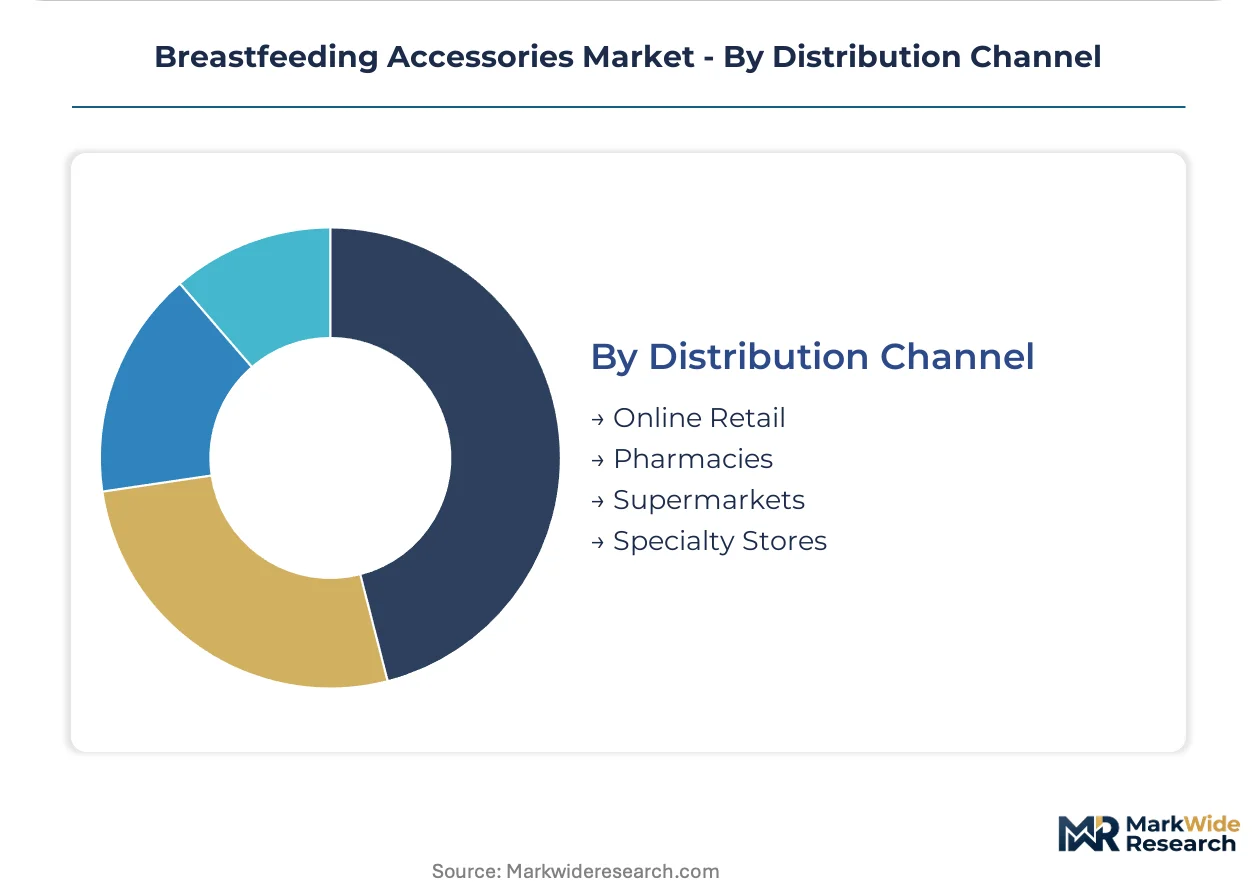
Customer-type migration patterns are reshaping route-to-market priorities, with discrete purchasing preferences accelerating digital channel displacement of retail aisle selection.
- Online Retail:E-commerce platforms and direct-to-consumer sites capturing subscription replenishment models for consumables, driven by discrete purchasing preferences among new mothers and pharmacy-integrated telehealth referrals in United States metropolitan markets.
- Pharmacies:Retail pharmacy chains and hospital outpatient dispensaries anchoring mass-market volume through Avent brand distribution, with lactation consultant referrals increasingly routing through digital health apps that embed product recommendations.
- Supermarkets:Mass-market retail channels for entry-level nursing pads and nipple cream.
- Specialty Stores:Maternity-focused boutiques and baby product retailers.
Pharmacies retain the durable hardware anchor. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity for wearable pump technology, while Indian and Southeast Asian markets remain anchored to manual expression substitutes. This demand-elasticity contrast shapes regional product mix and margin structures.
United States
Employer lactation accommodation mandates under the Fair Labor Standards Act institutionalize pump infrastructure in corporate facilities. FDA 510(k) clearance timelines averaging 180 days delay revenue recognition for new entrants. The Boston-to-Washington corridor concentrates telehealth-integrated pharmacy platforms routing lactation consultant referrals.
Germany
REACH framework amendments on D4/D5/D6 cyclosiloxane migration limits tighten material specifications for silicone-based accessories. EU MDR compliance deadlines accelerate biocompatibility documentation requirements. Specialty chemical producers in the Rhine-Ruhr industrial cluster control high-purity elastomer feedstocks, exposing manufacturers to input cost volatility.
Japan
Working mother workforce participation drives demand for discreet portable expression solutions compatible with extended commuting patterns. METI guidelines on medical device software govern smart pump connectivity features collecting biometric data. The Osaka-Kobe manufacturing belt anchors precision molding capacity for miniaturized motor and battery assemblies.
United Kingdom
NHS procurement frameworks for hospital pump fleets consolidate vendor relationships around single-source contracts, compressing supplier margins. MHRA recognition of FDA 510(k) clearances streamlines market access for US-validated products. The Cambridge-Oxford-London triangle concentrates digital health platforms embedding lactation support into employer-sponsored virtual care benefits.
Australia
TGA medical device classifications align with FDA Class II frameworks, reducing regulatory friction for US-origin manufacturers. Private health insurance reimbursement channels extend rental pump programs into home settings post-discharge. Sydney and Melbourne metropolitan markets concentrate pharmacy-integrated telehealth platforms capturing discrete purchasing preferences.
Breastfeeding Accessories Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with hospital procurement consolidation favoring scale and clinical validation over consumer marketing. The market structure compresses margins for fleet suppliers while rewarding proprietary miniaturization and connected data platforms. Two strategic archetypes dominate: clinical-grade incumbents leveraging decades of hospital validation, and wearable specialists eliminating external tubing through solid-state mechanisms. Competitive moves center on M&A to capture subscription replenishment platforms and strategic partnerships with telehealth routing systems.
Within the clinical validation tier, Medela AG and Koninklijke Philips NV exemplify scale-driven positioning, while Willow Innovations Inc. occupies the wearable specialist vector. Medela AG leverages hospital channel relationships, Philips anchors mass-market pharmacy distribution, and Willow Innovations represents proprietary technology eliminating external collection apparatus. These three companies illustrate the competitive tension between institutional procurement consolidation and consumer-directed portability.
| Leading Market Players |
|---|
| Pigeon Corporation |
| Willow Innovations Inc. |
| Medela AG |
| Mayborn Group Limited |
| Artsana Group |
| Koninklijke Philips NV |
| Ameda Inc. |
| Tommee Tippee |
| Lansinoh Laboratories Inc. |
| Others |
Supply Flow & Price Mechanics
EU MDR biocompatibility documentation gates both silicone supplier qualification and tiered hardware pricing simultaneously. Manufacturers absorbing extended ISO 10993 cytotoxicity testing timelines pass qualification costs into premium pump tiers, while non-compliant products forfeit European shelf access entirely.
Pricing Analysis
Replacement valve kits and milk storage bags drive lifetime customer value through subscription replenishment models. Three-tier pricing structure across hospital-grade, wearable portable, and manual economy levels separates clinical validation tiers. Pricing pressure stems from hospital procurement consolidation around single-source fleet contracts. Working mothers in professional services demonstrate lowest price sensitivity for discreet wearable form factors.
Supply Chain Analysis
Germany and Japan anchor medical-grade liquid silicone rubber production for breast shield and valve components. High-purity elastomer feedstocks draw from three specialty chemical producers, exposing manufacturers to input cost volatility. Single-source vulnerability concentrates in cyclosiloxane-compliant formulations meeting REACH D4/D5/D6 thresholds. Distribution runs through pharmacy-integrated telehealth platforms and hospital procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Breastfeeding accessories are recovering through working mother workforce participation cycles. Employer lactation accommodation mandates under the Fair Labor Standards Act institutionalize pump infrastructure demand.
For Market Incumbents: Compound hospital channel relationships through extended validation documentation and fleet service contracts. Deepen backward integration into medical-grade silicone compounding to offset feedstock concentration risk. Capture subscription replenishment platforms for consumables to defend against wearable specialists eroding hardware margins. For New Entrants and Emerging Players: Anchor in direct-to-consumer telehealth routing systems where lactation consultant referrals embed product recommendations. Target discrete purchasing preferences among first-time mothers in United States metropolitan markets. Pursue FDA 510(k) clearance through predicate device pathways to compress revenue recognition delays. For Investors and Strategic Acquirers: EU AI Act biometric data provisions reshape the acquisition landscape for connected pump platforms with app-integrated expression tracking. Five-to-ten year viability favors targets with regulatory clearance across both FDA and EU MDR jurisdictions. Monitor hospital-at-home reimbursement channel expansion as inflection signal for rental pump program extension.| Strategic Initiative | Industry Significance |
|---|---|
| Wearable Hardware Miniaturization | Solid-state pump mechanisms fitting bra-mounted form factors capture mobile professional demand. |
| Subscription Platform Acquisition | Recurring revenue from milk storage bags and valve kits exceeds durable hardware purchase frequency. |
| EU MDR Compliance Investment | Biocompatibility documentation acceleration captures shelf space as non-compliant products exit. |
| Telehealth Routing Partnership | Digital health app integration embeds product recommendations through lactation consultant referrals. |
| Hospital-at-Home Reimbursement Strategy | Insurance channels extending rental pump programs into post-discharge home settings. |
Methodological Framework
Operator-level perspectives from hospital procurement managers, lactation consultants, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement contracts, and CMS Medicare reimbursement data. Bottom-up unit economics triangulated against top-down market sizing across product categories.
Sensitivity analysis tested forecast robustness across alternative working mother participation scenarios and regulatory timeline assumptions. Segmentation dimensions modeled include product type, end user category, material formulation, and distribution channel across the projection horizon. CAGRs derived from installed base growth, replacement cycle compression, and subscription attach rate trajectories.
Underlying assumptions cover employer accommodation mandate enforcement, silicone feedstock supply continuity, and FDA review cycle stability, with deviation risk concentrated in REACH amendment implementation timing and hospital procurement consolidation velocity. Recalibration cycles align with material shifts in regulatory clearance timelines and reimbursement channel expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Nipple/Teat Market
Baby Products
Smart Crib Market
Baby Products
Electric Baby Nail Trimmer Market
Baby Products
Silicone Baby Product Market
Baby Products
Baby Wet Wipes Market
Baby Products
Global Baby Car Seats Market
Baby Products
Children Products Market
Baby Products
Smart Pacifier Market
Baby Products
Baby Stroller Market
Baby Products
Puppy Teething Toys Market
Baby Products
Maternity Products Market
Baby Products
Baby Gift Basket Market
Baby Products
Baby Seat Liners Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
Durable Juvenile Products Market
Baby Products
US Baby Care Products Market