
 AI in Accounting Market | 2026-2036
AI in Accounting Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Accounting Market Analysis
Cloud-native infrastructure is rebalancing legacy on-premise deployment economics across the AI in accounting sector. Intuit Inc. leverages its consumer-to-business ecosystem to anchor small-enterprise adoption. SAP SE sustains deep ERP integration that dominates large-corporation procurement cycles. Deloitte Touche Tohmatsu Limited positions its audit technology practice to compete on regulatory complexity.
AI in accounting encompasses software systems that apply machine learning algorithms, natural language processing, and robotic process automation to classify transactions, extract data from unstructured documents, and generate predictive financial forecasts with minimal human intervention. Invoice Processing leads application adoption due to its high volume and rule-based structure, while Predictive Analytics captures expanding margin pools as CFOs prioritize forward-looking intelligence. Natural Language Processing is the fastest-growing technology segment as vendors embed conversational interfaces into compliance workflows.
The US SEC, the EU's CSRD framework, and the UK's Financial Conduct Authority shape demand by mandating algorithmic transparency and audit trail integrity in automated financial systems. GDPR and state-level privacy statutes in California and New York constrain cross-border data flows, forcing localization of AI model training. Stakeholders must monitor evolving jurisdictional requirements before committing to multi-tenant platform architectures.
Market Dynamics
The US SEC's disclosure rules on AI governance are forcing accounting firms to restructure compliance workflows and redirect capital toward algorithmic transparency infrastructure.
Growth Catalysts
- Invoice Processing Automation:High-volume transaction classification drives immediate ROI for mid-market enterprises deploying robotic process automation tools.
- EU CSRD Framework:Mandatory sustainability reporting requirements expand demand for predictive analytics that forecast carbon-adjusted financial performance.
- Natural Language Processing:Conversational interfaces embedded in audit workflows compress query resolution cycles for compliance teams.
Market Restraints
- GDPR Data Localization:Cross-border restrictions on model training data force redundant infrastructure investments in Germany, France, and Ireland.
- Legacy ERP Integration Costs:SAP and Oracle system customizations consume 40-60% of implementation budgets for large enterprises.
- Audit Trail Integrity Standards:The UK's Financial Conduct Authority mandates immutable logging that increases storage and verification overhead.
Strategic Opportunities
- Small-Enterprise Segment:Cloud-native platforms priced under $500 monthly remain underpenetrated across the United States Midwest and Southeast.
- Real-Time Forecasting Convergence:Machine learning algorithms fused with external economic indicators enable dynamic scenario modeling for CFOs.
- State-Level Privacy Statutes:California's CPRA and New York's SHIELD Act create compliance service bundling opportunities for regional accounting networks.
Industry Challenges
- Algorithmic Bias Auditing:Firms lack sufficient data scientists trained in fairness testing for credit-scoring and loan-provision models.
- Multi-Jurisdictional Certification:ISO 27001, SOC 2 Type II, and EU AI Act conformity assessments extend sales cycles by 6-12 months.
- API Fragmentation:Inconsistent data formats between banking, tax, and ERP systems require expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Accounting Market |
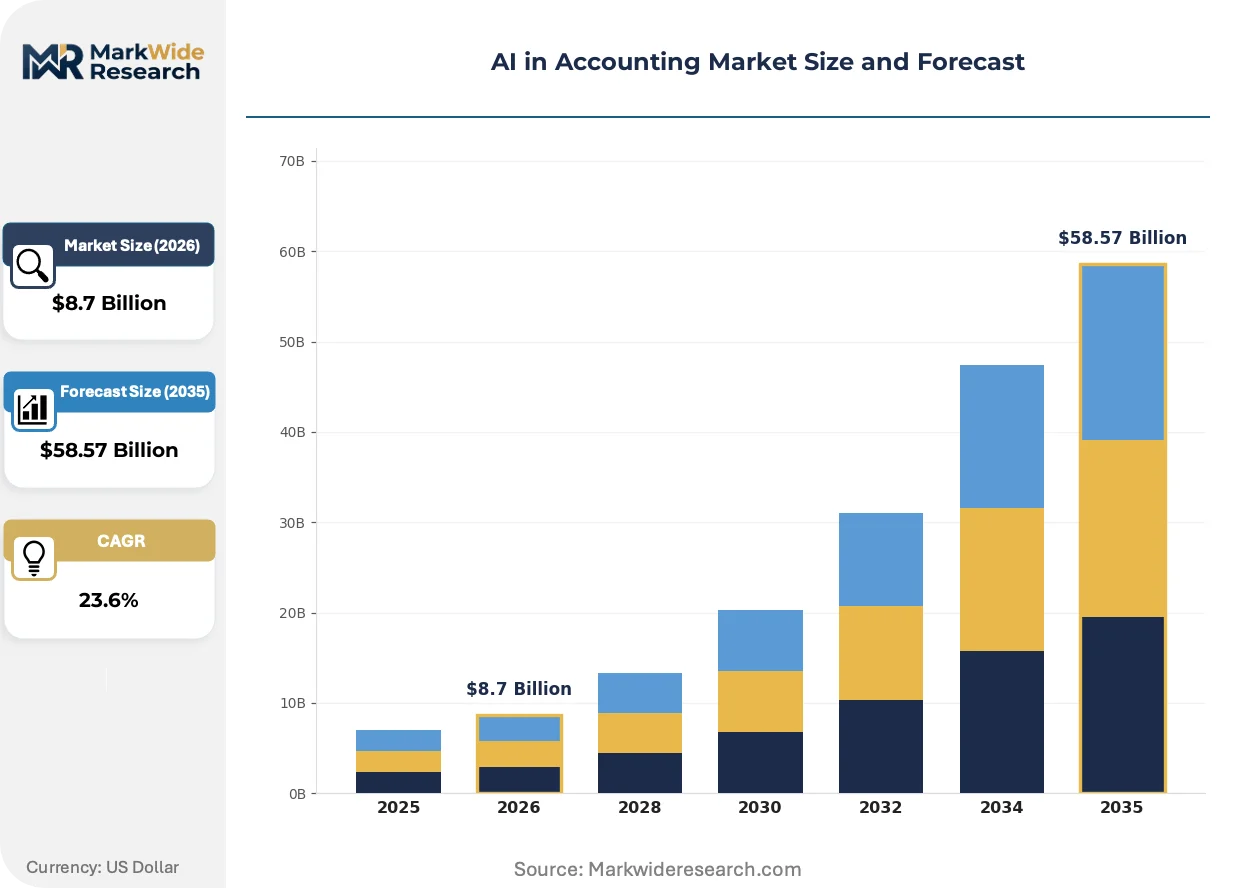
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Invoice Processing, Audit Assistance, Expense Management, Financial Reporting End User: Small Enterprises, Medium Enterprises, Large Corporations, Accounting Firms Solution: Tax Automation, Fraud Detection, Predictive Analytics, Data Visualization Technology: Machine Learning, Natural Language Processing, Robotic Process Automation, Optical Character Recognition |
| Companies Covered | Intuit Inc., Xero Limited, Sage Group plc, SAP SE, Oracle Corporation, Microsoft Corporation, Deloitte Touche Tohmatsu Limited, Ernst & Young Global Limited, Zoho Corporation Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Accounting Market Emerging Trajectories
Generative AI is compressing document analysis timelines while regulators race to establish governance frameworks for autonomous financial decision systems.
Large language models trained on regulatory filings and contract corpora are electrifying due diligence processes. Private equity firms and commercial lenders now deploy these systems to extract covenant terms and risk flags from unstructured credit agreements in minutes rather than days. This capability is compressing analyst headcount ratios and reshaping talent models at bulge-bracket advisory practices.
The EU AI Act's risk-based classification system imposes conformity obligations on high-stakes financial applications. Automated credit decisions and fraud detection algorithms face mandatory human oversight and ex-ante auditing requirements. German and French accounting software vendors are pre-emptively embedding explainability modules to secure CE marking ahead of enforcement deadlines.
Subscription pricing for AI-enhanced audit tools is displacing traditional hourly billing arrangements. Mid-tier firms in Texas and Illinois now package predictive analytics and automated reconciliation into fixed-fee engagements. This shift transfers outcome risk to technology providers while locking in multi-year client relationships through integrated platform dependencies.
AI in Accounting Market Segmentation
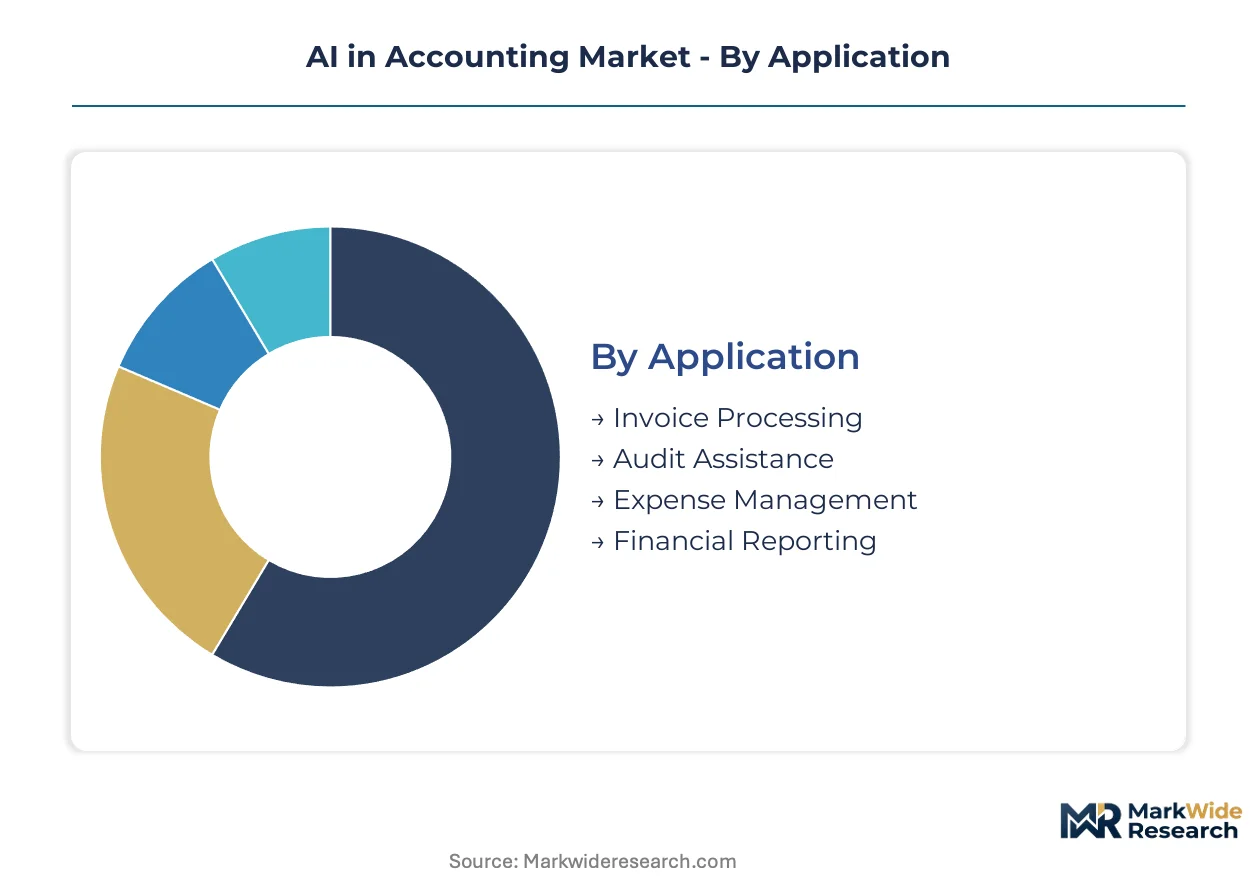
Segmentation in AI accounting software reveals how procurement criteria diverge sharply between transaction-heavy mid-market buyers and compliance-driven enterprise purchasers. Understanding these fault lines enables vendors to align R&D investment with margin concentration rather than revenue volume alone.
Application:
Procurement teams prioritize immediate labor cost reduction over predictive capabilities when evaluating application modules.
- Invoice Processing:Robotic process automation extracts line-item data from scanned documents and PDFs, routing approvals through configurable workflows. Mid-market enterprises in the United States Midwest deploy this module first due to quantifiable headcount reductions in accounts payable departments.
- Predictive Analytics:Machine learning models forecast cash flow trajectories and revenue volatility using historical ledger data combined with external economic indicators. CFOs at publicly traded firms facing SEC disclosure mandates drive adoption here, seeking algorithmic transparency for audit defense.
- Audit Assistance:Automated sampling and anomaly detection compress fieldwork timelines for external auditors.
- Expense Management:Real-time policy enforcement and receipt matching reduce reimbursement cycle times.
- Financial Reporting:Natural language generation drafts narrative disclosures from structured data inputs.
Invoice Processing leads on scale; Predictive Analytics leads on momentum.
End User:
Deployment complexity and integration requirements stratify the buyer base into distinct service tiers.
- Accounting Firms:Multi-client architectures demand tenant isolation and role-based access controls across hundreds of simultaneous engagements. The Big Four and mid-tier networks in Illinois and Texas purchase these platforms to standardize methodology across dispersed practice offices.
- Large Corporations:ERP integration mandates dominate procurement, with SAP and Oracle connectivity consuming implementation budgets. German and French manufacturing conglomerates under EU CSRD reporting obligations prioritize carbon-adjusted forecasting modules.
- Small Enterprises:Cloud-native solutions priced below $500 monthly target underpenetrated segments in the United States Southeast.
- Medium Enterprises:Hybrid deployment models balance customization needs against IT resource constraints.
Accounting Firms concentrate purchasing power; Small Enterprises offer the steepest expansion trajectory.
Solution:
Regulatory enforcement intensity determines which solution modules command premium pricing versus commodity positioning.
- Fraud Detection:Anomaly scoring algorithms flag journal entry irregularities and vendor master file changes for investigation. Banking regulators in the United Kingdom and United States mandate these capabilities for institutions above asset thresholds, creating compliance-driven demand.
- Tax Automation:Jurisdiction-specific rule engines calculate liabilities across multi-state and international filings. California's franchise tax complexity and New York's combined reporting requirements generate concentrated demand from regional enterprise clusters.
- Predictive Analytics:Scenario modeling tools support CFO decision-making under uncertainty.
- Data Visualization:Dashboard interfaces translate ledger outputs into executive-facing performance metrics.
Fraud Detection commands regulatory premiums; Tax Automation scales with jurisdictional fragmentation.
Technology:
Infrastructure maturity and talent availability shape which technology layers vendors build versus buy.
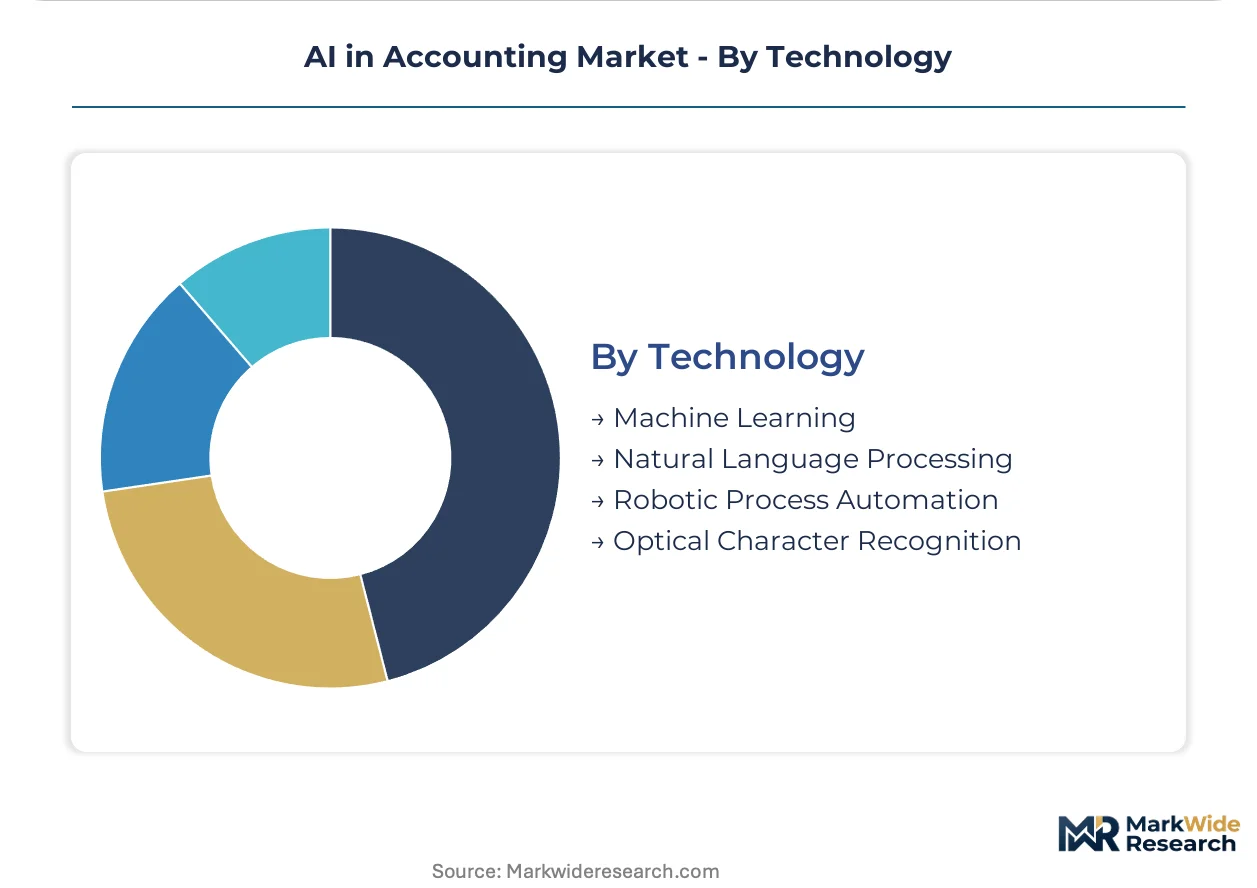
- Natural Language Processing:Transformer architectures extract entities from unstructured contracts and regulatory filings, enabling conversational query interfaces. Private equity due diligence teams and commercial credit analysts deploy these systems to compress document review cycles from days to minutes.
- Machine Learning:Supervised classification models trained on labeled transaction data automate account coding and anomaly flagging. German software vendors embed explainability modules to satisfy EU AI Act conformity requirements for high-risk financial applications.
- Robotic Process Automation:Script-based automation handles repetitive data entry and reconciliation tasks.
- Optical Character Recognition:Image-to-text conversion enables digitization of paper-based source documents.
Machine Learning anchors current deployment volume; Natural Language Processing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's enterprise software corridor anchors AI accounting innovation, though regulatory divergence across jurisdictions fragments deployment patterns. The United States, Germany, United Kingdom, China, and India concentrate distinct demand drivers shaped by local compliance architectures and industrial digitization timelines.
United States
Mid-market enterprises in Texas and Illinois drive cloud-native adoption for invoice automation, while SEC disclosure mandates on algorithmic governance redirect compliance spending. The CPRA in California and SHIELD Act in New York impose state-level data localization requirements that complicate multi-tenant platform architectures. Chicago's financial services corridor hosts concentrated procurement from regional accounting networks bundling predictive analytics into fixed-fee engagements.
Germany
Manufacturing conglomerates under EU CSRD reporting obligations prioritize carbon-adjusted forecasting modules integrated with SAP ERP systems. The EU AI Act's risk-based classification imposes conformity obligations on automated credit decisions, prompting German vendors to embed explainability modules ahead of enforcement deadlines. Munich and Frankfurt clusters concentrate procurement from Mittelstand firms modernizing financial operations under dual regulatory pressure from Brussels and Berlin.
United Kingdom
The Financial Conduct Authority mandates immutable audit trail logging for automated financial systems, increasing storage overhead for London-based accounting firms. Private equity due diligence teams deploy natural language processing to compress document review cycles from credit agreements. The City's advisory practices reshape talent models as large language models trained on regulatory filings displace traditional analyst ratios.
China
Dual carbon goals and GB standards compliance accelerate demand for predictive analytics forecasting carbon-adjusted financial performance in state-owned enterprises. SAMR oversight of algorithmic transparency constrains autonomous decision systems in banking and insurance applications. Yangtze River Delta manufacturing hubs concentrate procurement of robotic process automation for high-volume transaction classification.
India
SEBI's evolving disclosure framework and RBI's digital lending guidelines shape compliance investments from Mumbai's financial services sector. The PLI scheme for IT hardware indirectly supports cloud infrastructure expansion for SaaS accounting platforms. Bangalore's technology corridor hosts development centers for natural language processing tools targeting conversational audit interfaces.
AI in Accounting Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors bridge ERP integration gaps and secure regulatory certification pathways. The vendor base stratifies across three tiers: global ERP-integrated suites, cloud-native mid-market specialists, and Big Four audit technology practices. Two archetypes command premium positioning: ecosystem-anchored platforms leveraging consumer-to-business data flows, and compliance-heavy practices competing on regulatory complexity. M&A activity concentrates on natural language processing capabilities and regional accounting network acquisitions.
Within the ecosystem-anchored tier, Intuit Inc. and Xero Limited exemplify cloud-native architectures priced for small-enterprise penetration. SAP SE and Oracle Corporation occupy positions at the ERP-integrated extreme, where implementation budgets concentrate on legacy system customization. Deloitte Touche Tohmatsu Limited represents the audit-technology archetype, competing on multi-jurisdictional compliance automation rather than pure software margins.
| Leading Market Players |
|---|
| Intuit Inc. |
| Xero Limited |
| Sage Group plc |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Deloitte Touche Tohmatsu Limited |
| Ernst & Young Global Limited |
| Zoho Corporation Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Mid-market enterprises in the United States Midwest demanding sub-$500 monthly SaaS subscriptions are compressing vendor margins and forcing cloud-native providers to localize training infrastructure in Germany, France, and Ireland rather than centralizing in lower-cost jurisdictions.
Pricing Analysis
Input-cost pass-through from redundant EU data localization investments feeds into subscription tiers across cloud-native platforms. Three-tier pricing structure across premium, standard, and economy levels separates SOC 2 Type II certified enterprise suites from mid-market offerings and basic automation tools. Price differentiation hinges on audit trail granularity and ERP integration depth. Cost compression in the small-enterprise tier is intensifying because Intuit and Xero are bundling predictive analytics into base packages. Regional accounting networks in Texas and Illinois show highest price sensitivity; SAP-integrated manufacturing conglomerates in Germany absorb premium positioning.
Supply Chain Analysis
Certification gating through ISO 27001, SOC 2 Type II, and EU AI Act conformity assessments restricts qualified vendor pools to established players with compliance infrastructure. Software development concentrates in the United States, India, and Germany, with Bangalore and Silicon Valley hosting natural language processing R&D centers. Cloud compute and specialized AI chipsets from NVIDIA and AMD constitute critical input dependencies. Single-source vulnerability in transformer model architectures trained on proprietary regulatory corpora threatens competitive differentiation. Distribution runs through direct enterprise sales for large corporations and channel partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between California's CPRA-mandated data localization costs and India's PLI-subsidized cloud infrastructure creates margin expansion opportunities for vendors with multi-jurisdictional deployment capabilities.
For Market Incumbents: Lock in multi-year client relationships through integrated platform dependencies before subscription pricing fully displaces hourly billing. Defend against cloud-native entrants by embedding explainability modules that preempt EU AI Act enforcement. Prioritize certification investment in ISO 27001 and SOC 2 Type II to extend sales cycle advantages over unqualified competitors. For New Entrants and Emerging Players: Small enterprises in the United States Southeast remain underserved by incumbent pricing models. White-space exists in carbon-adjusted forecasting modules for Mittelstand firms under dual EU CSRD and German regulatory pressure. A channel partnership strategy with regional accounting networks in Texas and Illinois accelerates penetration without direct enterprise sales overhead. For Investors and Strategic Acquirers: Asymmetric upside sits with natural language processing specialists possessing regulatory filing training data and conversational audit interfaces. Long-term viability favors vendors with explainability architecture compatible with EU AI Act high-risk application requirements. Watch for SEBI disclosure framework evolution in India as an inflection indicator for emerging market compliance automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | SAP and Oracle ERP connectivity consumes 40-60% of implementation budgets, locking in multi-year relationships. |
| Acquisition of Specialist Firm | Natural language processing capabilities trained on regulatory filings compress due diligence cycles for private equity clients. |
| Strategic Partnership | Regional accounting networks in Chicago bundle predictive analytics into fixed-fee engagements, transferring outcome risk. |
| Geographic Expansion | Cloud infrastructure localization in Germany and France satisfies GDPR cross-border restrictions on model training data. |
| Product Launch | Explainability modules embedded ahead of EU AI Act enforcement deadlines secure CE marking for high-risk financial applications. |
Methodological Framework
Coverage spans the United States, Germany, United Kingdom, China, and India, with primary inputs from each market. Primary interviews with CFOs at publicly traded firms, compliance officers at Big Four practices, procurement leads at Mittelstand manufacturers, and platform engineers at cloud-native vendors combined with secondary validation from SEC filings, EU regulatory databases, SEBI disclosure records, and hyperscaler capex disclosures. Bottom-up and top-down triangulation reconciled segment-level adoption rates with aggregate market sizing.
Rate-of-change decomposition across the analysis window separated baseline automation adoption from generative AI acceleration effects. Segmentation dimensions modeled include application type, end-user archetype, solution module, and technology layer alongside deployment complexity and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating invoice processing automation penetration rates, predictive analytics procurement cycles, and natural language processing capability diffusion timelines. External economic indicator integration and algorithmic transparency mandate compliance costs informed forecast trajectories.
Underlying measurement precision varies by segment; invoice processing automation carries tighter precision than emerging predictive analytics modules due to established deployment patterns. Forecasts reflect assumptions about SEC disclosure rule evolution, EU AI Act enforcement timing, and state-level privacy statute proliferation. A model refresh is warranted upon material change in cross-border data flow restrictions or generative AI regulatory classification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
South Africa Forensic Accounting Market
Accounting and Taxation Services
Canada Forensic Accounting Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
Australia Accounting Software Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
Tax Compliance Services Market
Accounting and Taxation Services
Global Sales Tax Compliance Software Market
Accounting and Taxation Services
Global Financial Accounting Advisory Services Market
Accounting and Taxation Services
Canada Accounting Software Market
Accounting and Taxation Services
Japan Forensic Accounting Market
Accounting and Taxation Services
China Forensic Accounting Market
Accounting and Taxation Services
South Korea Forensic Accounting Market